
 Automotive Personal Assistance System Market | 2026-2036
Automotive Personal Assistance System Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Personal Assistance System Market Outlook
European component suppliers is repositioning around software-defined cockpit architectures as automakers decouple hardware from interface layers. Bosch leverages its Tier 1 supplier relationships to embed voice-processing modules directly into instrument clusters. Continental AG anchors its competitive stance through sensor-fusion capabilities that merge gesture recognition with cabin monitoring. BMW competes by controlling the full stack from cloud-based natural language models to edge-computing head units.
An automotive personal assistance system constitutes an integrated human-machine interface that processes multimodal inputs—voice commands, touch gestures, and biometric signals—to execute vehicle functions, infotainment operations, and connected services through embedded software and vehicle-bus integration. These systems rely on natural language processing engines capable of sub-200-millisecond response latency and continuous-learning algorithms that adapt to driver behavior patterns without cloud dependency. The technology dimension shows artificial intelligence and sensor fusion capturing the steepest development investment as automakers chase hands-free cabin control. The end-user dimension reveals OEMs dominating procurement volumes while fleet operators represent the fastest-expanding buyer category due to telematics integration and driver-safety mandates. The feature dimension places navigation assistance and vehicle diagnostics as the highest-margin modules because they generate recurring data-service revenue streams.
NHTSA guidelines on driver distraction limit visual-manual task duration to two seconds, directly shaping touchscreen and gesture-control interface designs for US-bound vehicles. The EU AI Act classifies certain in-vehicle biometric identification systems as high-risk, imposing conformity assessment obligations that extend market-access timelines for European deployments. China's MIIT mandates data-localization requirements for connected-vehicle systems, creating architecture constraints for foreign suppliers serving domestic OEMs. Stakeholders must weigh regulatory fragmentation against platform standardization when selecting which multimodal input technologies to prioritize for cross-border vehicle programs.
Market Dynamics
The automotive personal assistance system market is restructuring around software-defined vehicle architectures, where automakers decouple hardware layers from interface software to enable over-the-air feature updates and subscription monetization.
Growth Catalysts
- NHTSA distracted-driving enforcement:The US regulator's two-second visual-manual task limit compels automakers to deploy voice-first interfaces, accelerating procurement of natural language processing modules.
- AI-driven cabin monitoring:Sensor fusion combining biometric identification with occupant detection is expanding addressable functionality beyond the driver to all vehicle occupants.
- German automotive software clusters:Concentrated engineering talent in Stuttgart and Munich enables rapid prototyping of multimodal HMI systems for premium vehicle programs.
Market Restraints
- Semiconductor supply concentration:Voice-processing ASICs depend on Taiwanese foundry capacity, exposing lead-time volatility for system integrators.
- EU AI Act conformity assessment:High-risk classification for biometric identification systems extends European market-access timelines by 12-18 months.
- Edge-computing cost structure:On-vehicle inference engines require automotive-grade GPUs that carry 3-4x cost premiums versus consumer silicon alternatives.
Strategic Opportunities
- Chinese data-localization architecture:MIIT mandates for in-vehicle data processing create demand for domestically hosted natural language models and edge-computing stacks.
- Fleet telematics integration:Commercial vehicle operators seek unified driver-assistance and dispatch-management interfaces, opening B2B procurement channels.
- Gesture-voice convergence:Combining computer vision with speech recognition enables hands-free control for logistics and construction vehicle segments.
Industry Challenges
- Automotive NLP engineering scarcity:Sub-200-millisecond latency requirements demand specialized expertise in embedded speech processing that outpaces university pipeline output.
- Legacy vehicle-bus integration:Controller area network protocols in existing fleets constrain feature deployment without hardware retrofits that erode margin structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Personal Assistance System Market |
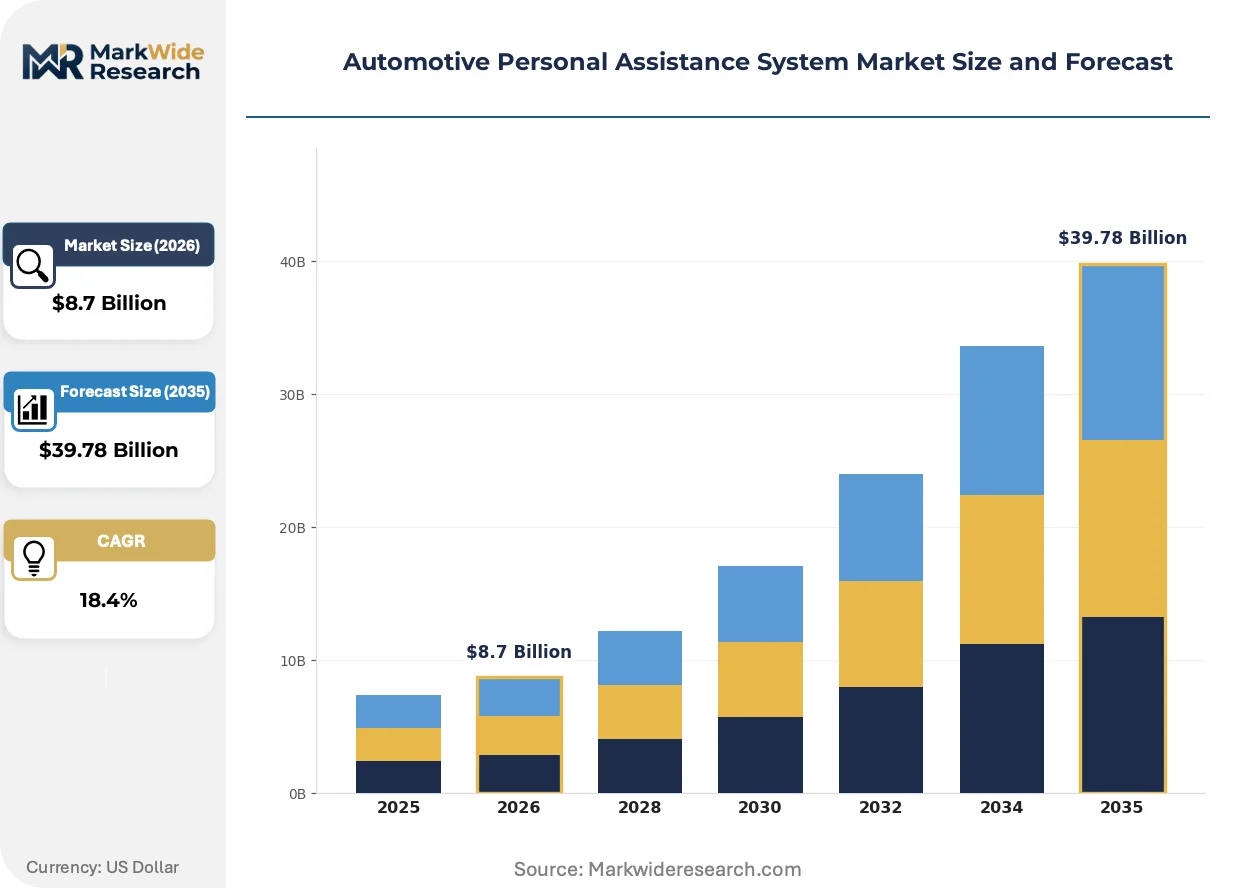
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Voice-Activated, Touchscreen, Gesture Control, Mobile App Technology: Artificial Intelligence, Machine Learning, Natural Language Processing, Sensor Fusion End User: OEMs, Fleet Operators, Tech Developers, Individual Consumers Feature: Navigation Assistance, Vehicle Diagnostics, Entertainment Control, Communication |
| Companies Covered | Nuance Communications, Bosch, BMW, Continental AG, Audi, Alpine Electronics, Mobileye (Intel), Tata Motors, Wipro, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Personal Assistance System Market Strategic Shifts
Development priorities are compressing around three vectors: on-device intelligence eliminating cloud dependency, regulatory alignment across fragmented jurisdictions, and fleet-operator procurement models displacing traditional retail channels.
Edge-based natural language inference is integrating dedicated neural processing units directly into instrument clusters and head units. Tier 1 suppliers are embedding these modules at volume scale for 2027-2028 vehicle programs. This architecture is integrating real-time response capabilities without connectivity dependencies, enabling consistent performance in tunnel and rural coverage gaps.
The EU AI Act's risk-classification framework is mandating conformity assessments for biometric identification systems deployed in European vehicles. Automakers must document algorithmic transparency and human oversight protocols before type approval. German and French regulators are conducting parallel technical reviews, creating compliance duplication for multi-country vehicle launches.
Fleet operators are consolidating procurement decisions at the holding-company level rather than through individual dealership networks. Logistics and ride-hailing platforms specify unified HMI standards across mixed-vehicle fleets, pressuring OEMs to support third-party application programming interfaces. This concentration is most visible in the United States, where national leasing companies negotiate enterprise-wide telematics and assistance system packages.
Automotive Personal Assistance System Market Segmentation
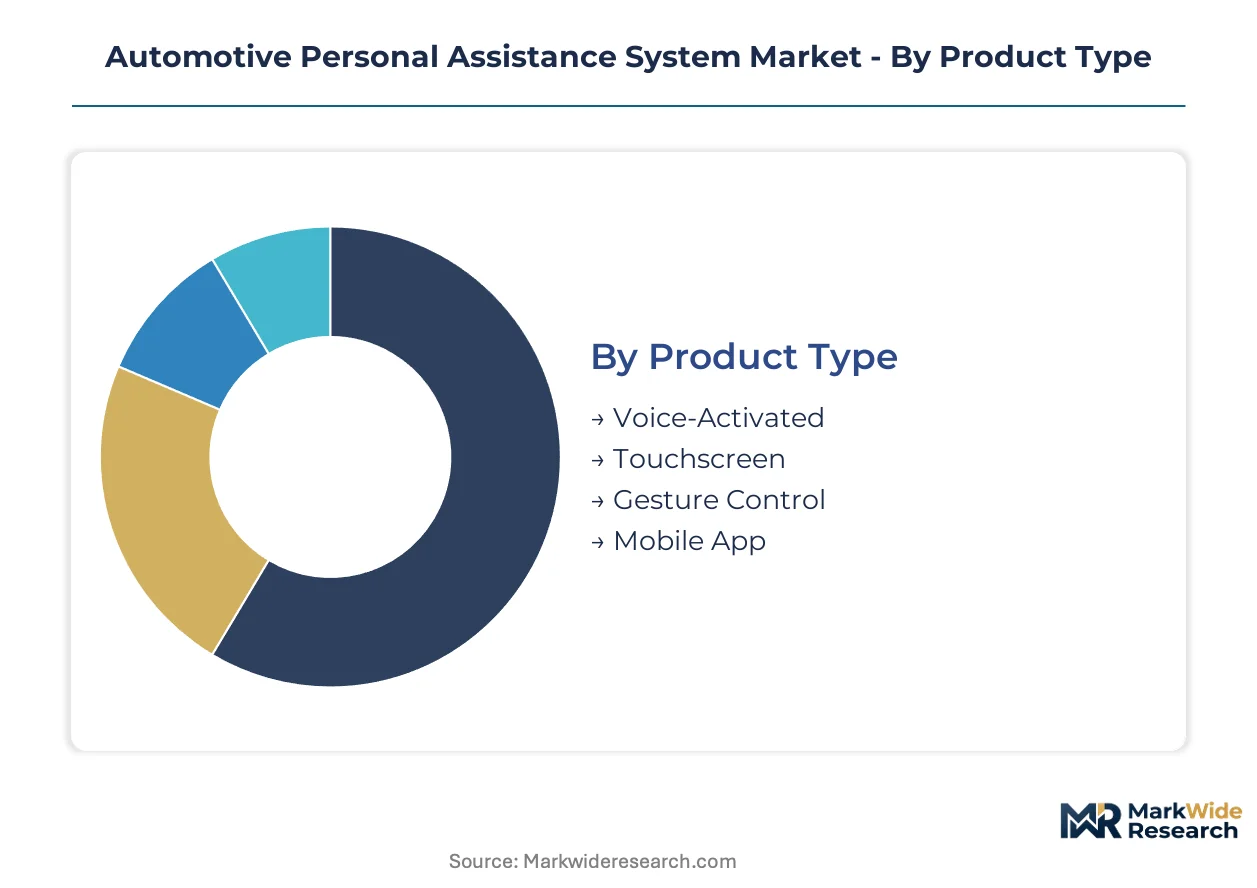
Automotive personal assistance systems fragment across four dimensions that determine procurement patterns and margin structures. Product type dictates hardware cost and interface complexity, while technology selection locks in development timelines and regulatory exposure.
Product Type:
Buyer decisions hinge on distraction-compliance requirements and cabin ergonomics rather than technology novelty alone.
- Voice-Activated:Systems process natural language through embedded ASICs achieving sub-200-millisecond latency without cloud dependency. NHTSA's two-second visual-manual task limit compels US automakers to prioritize voice-first architectures for new vehicle programs.
- Touchscreen:Capacitive multi-touch displays integrate haptic feedback layers and proximity sensing for gesture anticipation. Germany's premium OEMs specify 12-inch-plus diagonal formats with OLED backlighting, driving display panel procurement volumes.
- Gesture Control:Time-of-flight cameras and radar sensors capture three-dimensional hand movements for non-contact interface operation. Continental AG and Bosch embed these modules in instrument clusters for hands-free cabin control.
- Mobile App:Smartphone-based interfaces extend vehicle functionality through Bluetooth Low Energy and ultra-wideband digital keys. Fleet operators in the United States consolidate procurement through enterprise mobility platforms rather than OEM-native applications.
Volume sits with touchscreen interfaces; growth tilts toward voice-activated systems as distraction regulations tighten across jurisdictions.
Technology:
Development investment concentrates where inference latency and automotive-grade reliability intersect.
- Artificial Intelligence:Deep learning models execute intent classification and context retention on neural processing units. China's MIIT data-localization mandates require domestic hosting of AI inference engines, constraining cloud-dependent architectures.
- Machine Learning:Continuous-learning algorithms adapt to driver behavior patterns using on-vehicle training without transmitting biometric data. The EU AI Act's high-risk classification for biometric identification extends conformity assessment timelines for European deployments.
- Natural Language Processing:Embedded speech recognition engines parse multilingual commands with speaker diarization for occupant-specific responses. Stuttgart and Munich engineering clusters supply specialized talent for sub-200-millisecond latency requirements.
- Sensor Fusion:Algorithms merge camera, radar, and capacitive inputs for multimodal intent disambiguation. BMW integrates sensor-fusion stacks from cloud-based models to edge-computing head units across its full vehicle lineup.
Artificial intelligence commands the largest development budgets; natural language processing is expanding most quickly as voice interfaces displace touch-dominant cabin controls.
End User:
Procurement authority is shifting from retail channels toward centralized fleet decision-making.
- OEMs:Vehicle manufacturers specify integrated HMI stacks through Tier 1 supplier relationships, embedding assistance modules at the platform architecture stage. German and US automakers decouple hardware from software layers to enable over-the-air feature monetization.
- Fleet Operators:Commercial vehicle holding companies negotiate enterprise-wide telematics and assistance system packages across mixed-vehicle fleets. National leasing companies in the United States drive standardization through API requirements for third-party dispatch integration.
- Tech Developers:Software firms supply natural language models and computer vision algorithms through licensing arrangements with automotive suppliers. These entities face margin pressure as OEMs bring core AI capabilities in-house.
- Individual Consumers:Aftermarket installation of personal assistance modules represents a marginal revenue stream constrained by vehicle-bus integration complexity and warranty voiding concerns.
OEMs retain volume dominance; fleet operators are gaining share fastest as telematics mandates and driver-safety regulations consolidate procurement authority.
Feature:
Recurring revenue potential determines feature prioritization in product roadmaps.
- Navigation Assistance:Real-time routing engines integrate predictive traffic models and point-of-interest databases through subscription data services. This module generates recurring revenue streams that offset hardware margin compression.
- Vehicle Diagnostics:Prognostic algorithms monitor powertrain and chassis systems to predict maintenance intervals and component failures. Fleet operators in China and the United States mandate diagnostic integration for warranty compliance and uptime optimization.
- Entertainment Control:Media streaming and gaming interfaces extend occupant engagement through third-party application ecosystems. Content licensing arrangements with streaming platforms create additional monetization layers.
- Communication:Hands-free calling and messaging integration leverages smartphone mirroring protocols and embedded cellular modems. Regulatory distraction limits in the United States and Europe constrain feature complexity to voice-only operation during vehicle motion.
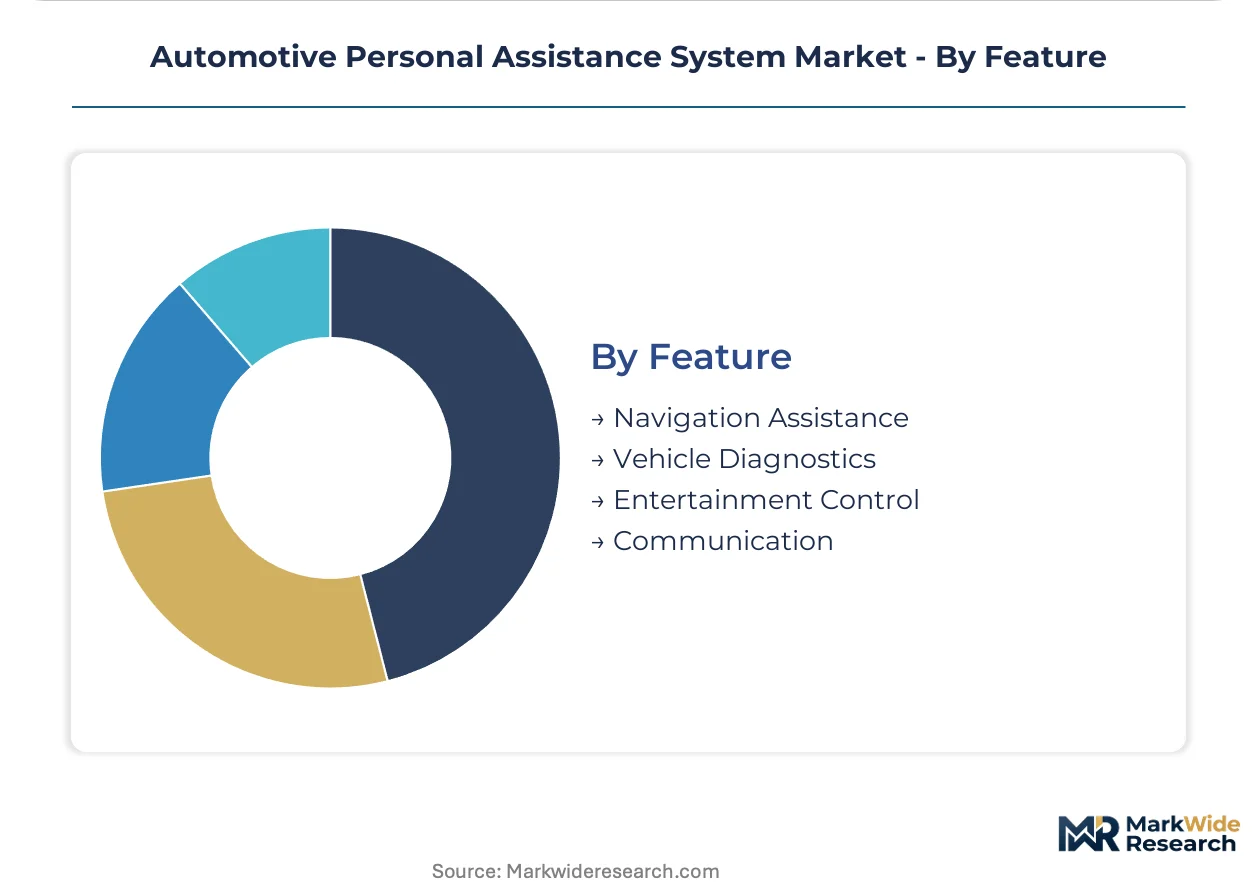
Navigation assistance captures the steepest margin expansion; vehicle diagnostics shows the fastest climb as predictive maintenance contracts proliferate in commercial fleets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive software engineering clusters anchor the geographic distribution of development talent, with Stuttgart and Munich hosting dense concentrations of natural language processing specialists and embedded systems architects.
United States
NHTSA's two-second visual-manual task limit compels automakers to prioritize voice-first interface architectures. The regulator's distracted-driving enforcement creates procurement pressure for sub-200-millisecond latency speech recognition modules. Silicon Valley and Detroit engineering centers prototype multimodal HMI systems for 2027-2028 vehicle programs.
Germany
Premium OEM platform architectures drive demand for software-defined cockpit systems with over-the-air update capabilities. The EU AI Act's high-risk classification for biometric identification extends conformity assessment timelines for European deployments. Stuttgart and Munich clusters supply specialized talent for embedded neural processing unit integration.
China
Domestic OEM procurement concentrates on data-localized natural language models for connected-vehicle systems. MIIT mandates require in-vehicle data processing architectures that constrain cloud-dependent foreign supplier designs. Yangtze River Delta engineering centers develop edge-computing stacks for domestic hosting compliance.
Japan
Automotive semiconductor supply relationships shape voice-processing ASIC procurement decisions. METI industrial policy supports domestic foundry capacity for automotive-grade neural processing units. Nagoya and Tokyo engineering clusters specialize in sensor-fusion algorithms for gesture-voice convergence.
South Korea
Electronics conglomerates leverage display panel manufacturing scale for integrated cockpit module supply. National R&D programs fund embedded AI inference engines for hands-free cabin control. Seoul Capital Area engineering centers develop continuous-learning algorithms for driver behavior adaptation.
Automotive Personal Assistance System Market Competitive Environment
Global majors compete with regional champions across software stack integration depth, with Tier 1 suppliers embedding voice-processing modules directly into instrument clusters while automakers build in-house natural language capabilities. The structure fragments across three strategic tiers: full-stack OEMs controlling cloud-to-edge architectures, modular Tier 1 suppliers providing sensor-fusion subsystems, and specialist software firms licensing computer vision algorithms. Dominant competitive moves include strategic partnerships for semiconductor supply security and backward integration into neural processing unit design.
Within the full-stack OEM tier, BMW exemplifies vertical control from cloud-based models to edge-computing head units. Among Tier 1 modular suppliers, Bosch and Continental AG occupy positions anchoring voice-processing and sensor-fusion subsystems respectively. Nuance Communications represents the specialist licensing archetype for embedded speech recognition engines.
| Leading Market Players |
|---|
| Nuance Communications |
| Bosch |
| BMW |
| Continental AG |
| Audi |
| Alpine Electronics |
| Mobileye (Intel) |
| Tata Motors |
| Wipro |
| Others |
Value Chain & Pricing Dynamics
Fleet operator procurement consolidation in the United States and Germany anchors contract-based pricing for automotive personal assistance systems, with enterprise telematics packages commanding volume discounts that OEMs offset through subscription service bundling.
Pricing Analysis
Warranty and predictive maintenance service bundling separates premium-tier assistance systems from standard hardware-only configurations, with BMW and Continental AG embedding extended diagnostic coverage into multi-year contracts. Three-tier pricing structure across premium, standard, and economy levels reflects neural processing unit performance grades and ISO 26262 functional safety certification tiers. Cost compression in mass-market voice-processing modules is intensifying because Taiwanese foundry capacity constraints limit ASIC supply elasticity. Fleet operators exhibit highest price sensitivity due to multi-thousand-unit procurement scales, while premium OEM captive programs show lowest sensitivity where brand differentiation overrides unit cost.
Supply Chain Analysis
Specialized embedded NLP engineering talent scarcity in Stuttgart, Munich, and Silicon Valley constrains module production scaling for sub-200-millisecond latency systems. Voice-processing ASICs draw from Taiwan and South Korea foundry capacity, while sensor-fusion camera modules source from Japanese and German optics clusters. Single-source vulnerability in neural processing unit intellectual property creates supply chain risk as ARM and proprietary RISC-V architectures compete for automotive design wins. Distribution runs through Tier 1 supplier-direct OEM relationships, with Bosch and Continental AG anchoring procurement channels for integrated cockpit modules.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive-grade GPU and neural processing unit foundry capacity bottlenecks prop pricing power for incumbent semiconductor suppliers serving voice-first cabin architectures.
For Market Incumbents: Deploy backward integration into dedicated neural processing unit design to secure inference engine supply against fabless competitor encroachment. Fortify sensor-fusion algorithm portfolios through certification investment for EU AI Act high-risk biometric system compliance. Lock in fleet operator procurement via API standardization that raises switching costs for rival telematics platforms. For New Entrants and Emerging Players: Capture Chinese domestic OEM procurement for data-localized natural language models under MIIT compliance mandates. Target aftermarket retrofit opportunities in commercial vehicle segments where legacy CAN bus integration barriers are lower than passenger car programs. Pursue licensing arrangements with Yangtze River Delta engineering clusters for edge-computing stack co-development. For Investors and Strategic Acquirers: The window for entry favors specialist embedded speech recognition firms with sub-200-millisecond latency proven deployments and Tier 1 supplier validation. Long-term viability hinges on regulatory compliance architecture depth across NHTSA, EU AI Act, and MIIT jurisdictions. Monitor EU AI Act conformity assessment timeline compression as inflection indicator for European market access cost normalization.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Vehicle Investment | BMW's full-stack control from cloud models to edge head units demonstrates vertical integration returns. |
| Battery Supply Agreement | Edge-computing module power requirements drive automotive-grade GPU procurement partnerships with foundries. |
| Platform Standardization | Fleet operator API mandates force OEM convergence on unified HMI architectures across mixed-vehicle deployments. |
| Geographic Manufacturing Footprint | MIIT data-localization requirements compel domestic hosting infrastructure for China-bound natural language models. |
| Charging Infrastructure Partnership | Voice-first cabin control integration with charging station networks extends assistance system utility beyond vehicle boundaries. |
Study Parameters
Document review covered SEC automotive supplier filings, NHTSA regulatory dockets, and EU AI Act technical documentation, complemented by interviews with OEM platform engineers, Tier 1 supplier procurement leads, fleet telematics operators, and embedded NLP engineering directors. Secondary validation drew from vehicle production databases, IHS Markit registration data, and semiconductor trade flow records. Bottom-up module shipment estimates triangulated against top-down OEM platform content analysis.
Cross-referencing historical adoption curves with expert panel input on 2027-2028 vehicle program timelines anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, technology stack, end-user procurement authority, and feature module recurring revenue potential. CAGRs derived from unit volume trajectory analysis adjusted for semiconductor supply elasticity constraints and regulatory approval timeline risk.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU AI Act enforcement consistency and Taiwanese foundry capacity allocation shifts. Forecasts reflect assumptions on NHTSA distracted-driving guideline permanence and MIIT data-localization mandate scope stability. Material deviation in neural processing unit supply availability or biometric system risk-classification reinterpretation warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Forklift Camera Systems Market
Automotive Safety and Security Systems
Safety Restraint Systems Market
Automotive Safety and Security Systems
Global Emergency Locking Retractor Seatbelt Market
Automotive Safety and Security Systems
Automotive Speed Limiter Market
Automotive Safety and Security Systems
North America Airbag Systems Market
Automotive Safety and Security Systems
Automotive Inertial Systems Market
Automotive Safety and Security Systems
Wearable Motorcycle Airbags Market
Automotive Safety and Security Systems
Crane Collision Avoidance Devices Market
Automotive Safety and Security Systems
Motorcycle Anti-Lock Braking System Market
Automotive Safety and Security Systems
Asia Pacific Airbag Systems Market
Automotive Safety and Security Systems
Automotive Immobilizer Market
Automotive Safety and Security Systems
In-Cabin Monitoring System (ICMS) Market
Automotive Safety and Security Systems
Road Speed Limiter Market
Automotive Safety and Security Systems
Forward Collision Warning System for Automotive Market
Automotive Safety and Security Systems
North America Automotive Adaptive Lighting System Market
Automotive Safety and Security Systems
Global Automotive Lidar Sensor Market