
 Smart Electric Bikes Market | 2026-2036
Smart Electric Bikes Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Electric Bikes Market Insights
The EU Green Deal is broadening the addressable market for connected pedal-assist vehicles as member states tighten urban mobility emissions budgets. Bosch eBike Systems leverages its Stuttgart engineering base to dominate mid-motor integration for premium urban fleets. Yamaha Motor Co. Ltd. sustains competitive positioning through in-house production of compact drive units. Rad Power Bikes anchors North American direct-to-consumer channels with simplified hub-motor configurations.
Smart electric bikes integrate battery-electric propulsion with IoT connectivity, GPS tracking, and regenerative braking systems rated typically between 250W and 750W motor output, serving last-mile logistics and personal mobility reduction of urban congestion. City E-Bikes occupy the largest installed base as municipal infrastructure expands dedicated lane networks across European capitals. Mountain E-Bikes represent the fastest-growing product category as trail access policies liberalize in alpine jurisdictions. Lithium-Ion batteries command the dominant technology position due to energy density thresholds that define frame-integrated design feasibility.
FCC certification governs wireless telemetry modules in the United States, while ECHA REACH compliance constrains battery material sourcing for European assemblers. The EU AI Act introduces algorithmic transparency requirements for predictive maintenance platforms that optimize fleet uptime. Stakeholders must monitor evolving battery passport mandates and cross-border data governance frameworks that will determine service-layer monetization potential.
Market Dynamics
The EU Green Deal's transport decarbonization mandates are compressing fleet procurement timelines and forcing assemblers to reconfigure supply chains around battery passport traceability requirements. This regulatory pressure is concentrating demand in markets with mature charging infrastructure and established subsidy frameworks.
Growth Catalysts
- Urban Delivery Electrification:Last-mile logistics operators across Germany, the Netherlands, and Denmark are replacing combustion vans with cargo e-bikes to comply with municipal low-emission zones. Fleet procurement volumes are accelerating as diesel access restrictions tighten in Amsterdam, Copenhagen, and Berlin.
- EU Green Deal Mandates:The European Commission's binding emissions budgets for urban mobility are redirecting municipal procurement toward connected pedal-assist vehicles. Member states must demonstrate transport sector decarbonization progress through verified fleet data.
- Lithium-Ion Energy Density Thresholds:Advances in cell chemistry are enabling frame-integrated battery designs that reduce weight and improve handling. These technical gains are expanding the addressable market for premium urban mobility solutions.
Market Restraints
- Battery Material Concentration:ECHA REACH compliance constraints on cobalt and nickel sourcing are limiting European assemblers' supplier options. Raw material processing capacity concentrates in a narrow geography, creating input cost volatility.
- Motor Supplier Concentration:Mid-motor integration expertise clusters around Stuttgart engineering bases, creating dependency on German component suppliers for premium fleet specifications.
- Technical Limitation:Regenerative braking efficiency remains constrained by urban stop-start duty cycles that limit energy recovery rates below theoretical maximums.
Strategic Opportunities
- Underpenetrated Alpine Markets:Trail access policy liberalization in Swiss and Austrian jurisdictions is opening new terrain for Mountain E-Bike deployment. These markets currently lack dedicated service networks.
- EU AI Act Compliance:Algorithmic transparency requirements for predictive maintenance platforms create first-mover advantages for assemblers with embedded telemetry capabilities. Fleet operators will prioritize uptime optimization tools.
- Direct-to-Consumer Channel Expansion:Simplified hub-motor configurations are enabling bypass of traditional bike retail networks. North American demand is migrating toward online configuration tools with home delivery assembly.
Industry Challenges
- FCC Certification Timeline:Wireless telemetry modules for US market entry face extended testing protocols that delay product launches by 4-6 months relative to CE-marked equivalents.
- Cross-Border Data Governance:Fleet operators deploying across Germany, France, and Belgium must reconcile divergent data localization requirements for GPS tracking and rider analytics.
- Skill Gap in Battery Diagnostics:Independent repair networks lack training for lithium-ion pack servicing, forcing reliance on manufacturer-authorized channels that extend downtime.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Electric Bikes Market |
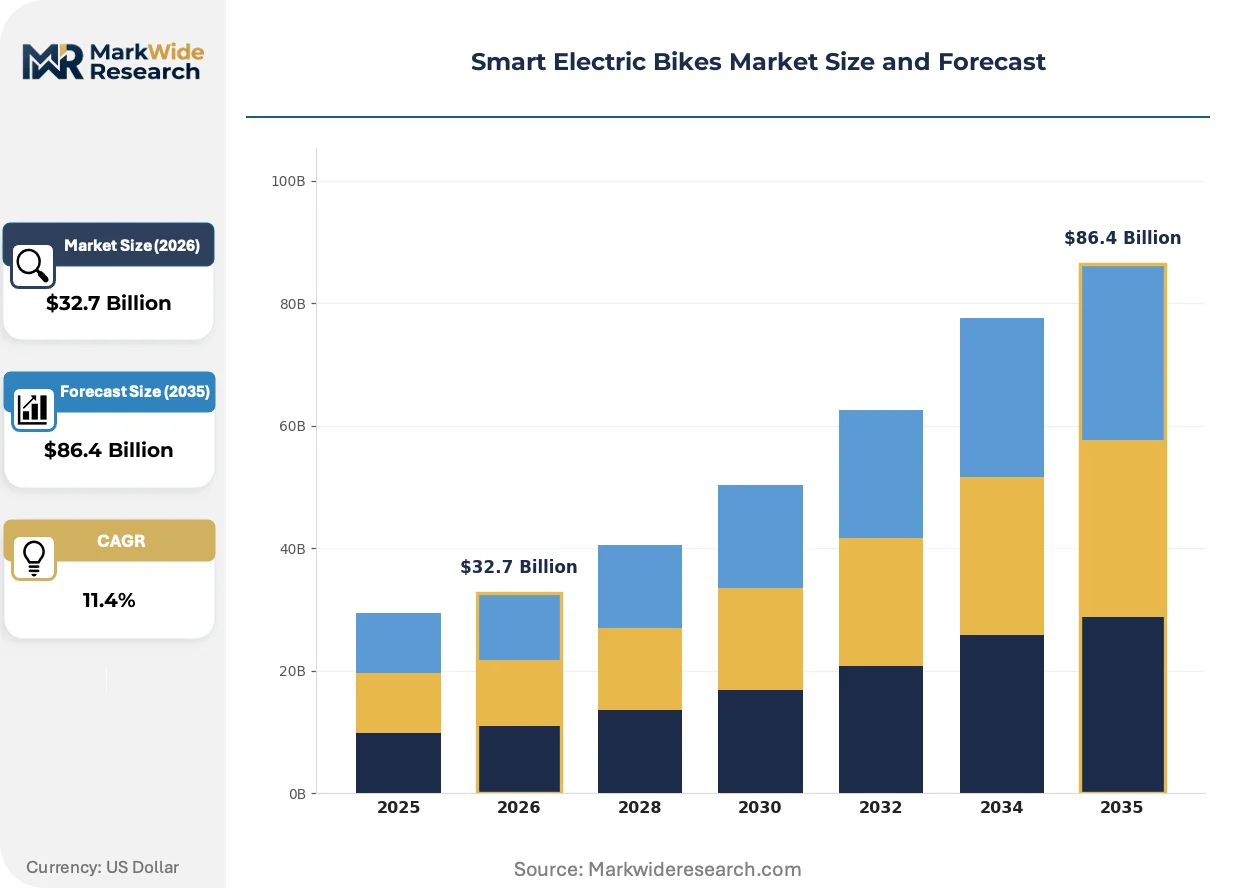
| Market Size in 2026 | $32.7 Billion |
| Market Size in 2035 | $86.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: City E-Bikes, Mountain E-Bikes, Folding E-Bikes, Cruiser E-Bikes Battery Type: Lithium-Ion, Lead Acid, Nickel-Metal Hydride, Others Motor Position: Hub Motor, Mid Motor, Rear Motor, Front Motor End User: Commuters, Recreational Users, Delivery Services, Fleet Operators |
| Companies Covered | Bosch eBike Systems, Yamaha Motor Co. Ltd., Giant Manufacturing Co. Ltd., Trek Bicycle Corporation, Rad Power Bikes, Specialized Bicycle Components, Yadea Group Holdings Ltd, Merida Industry Co. Ltd., Aventon Bikes, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Electric Bikes Market Trends and Innovations
Connected vehicle architectures are converging with predictive analytics to transform asset utilization models in commercial fleet deployments. This integration is compressing maintenance cycles and enabling new service-layer revenue streams.
Regenerative braking systems rated between 250W and 750W motor output are expanding into municipal bike-sharing fleets as operators seek to reduce charging infrastructure dependency. Copenhagen's procurement specifications now require energy recovery capability as a baseline feature. This technology is expanding into adjacent segments previously served by passive hub-motor designs.
The EU AI Act introduces mandatory algorithmic transparency for predictive maintenance platforms that optimize fleet uptime. European assemblers must document decision logic for battery health algorithms and diagnostic recommendation engines. City E-Bike fleet operators in Germany and the Netherlands face the steepest compliance burden as they deploy the largest connected vehicle populations.
Subscription-based fleet access models are displacing outright purchase arrangements among urban delivery services. Logistics operators in Paris and Milan now prioritize per-kilometer pricing over capital expenditure. This shift is most visible in last-mile verticals where route volatility makes asset ownership risk-prohibitive.
Smart Electric Bikes Market Segmentation
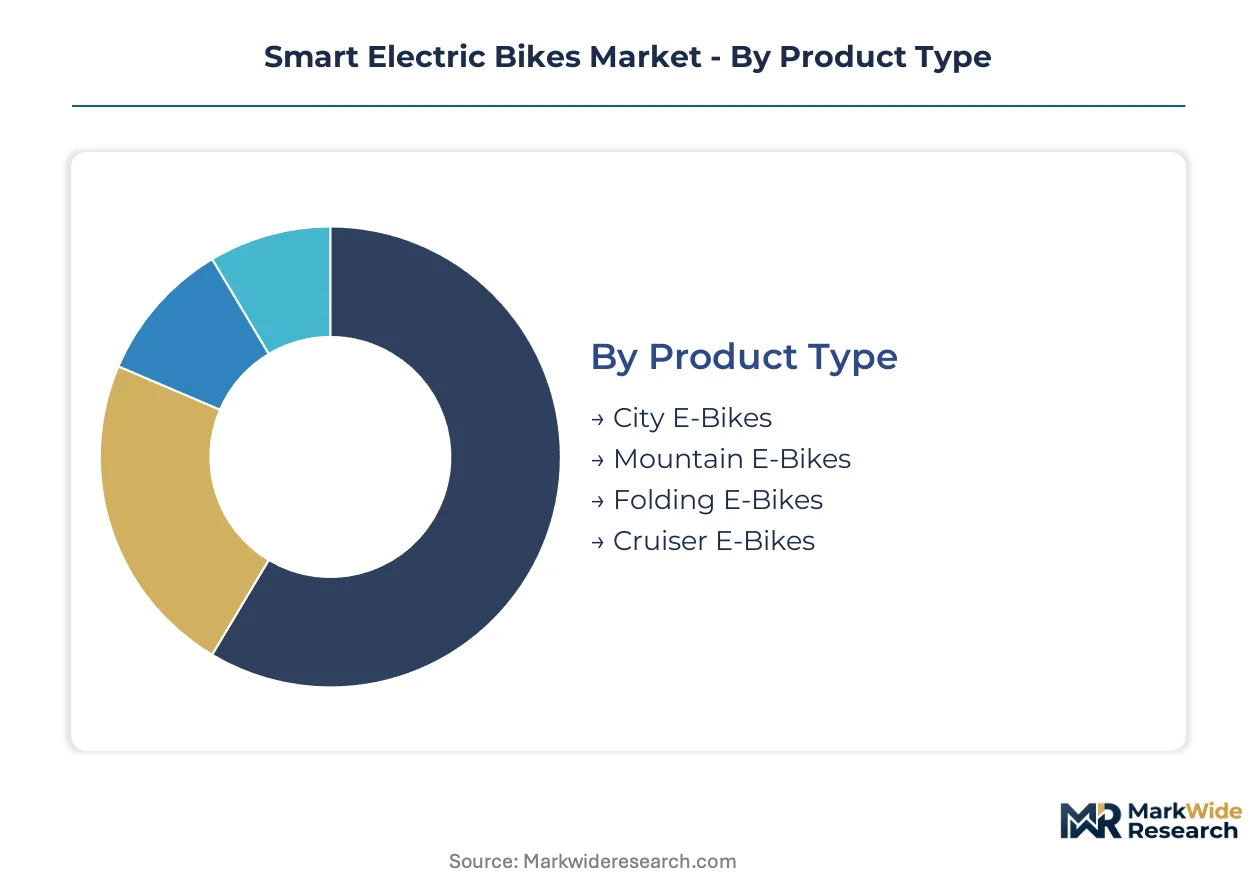
Segmentation in the Smart Electric Bikes Market reveals how technical specifications align with distinct use cases and procurement patterns. Battery chemistry, motor placement, and frame architecture determine pricing tiers, regulatory compliance pathways, and service network requirements across urban mobility and commercial fleet deployments.
Product Type:
Frame geometry and suspension architecture define the primary product categories, with each configuration optimized for distinct terrain and duty cycles.
- City E-Bikes:Step-through frames with integrated lighting and rack systems dominate municipal procurement in Amsterdam and Copenhagen. Fleet operators prioritize these configurations for last-mile logistics where frequent mounting and dismounting reduce delivery times. Dedicated lane expansion across Berlin and Vienna accelerates replacement cycles for aging bike-sharing assets.
- Mountain E-Bikes:Full-suspension designs with high-torque mid-motors serve alpine terrain access in Swiss and Austrian jurisdictions. Trail policy liberalization in Graubünden and Tyrol creates demand for ruggedized battery enclosures and enhanced water-ingress protection. These specifications command premium positioning where terrain capability justifies acquisition cost.
- Folding E-Bikes:Hinge-frame designs with reduced wheelbases address multi-modal commuters in dense urban cores. Paris and London operators deploy these for riders combining rail transit with final-mile segments.
- Cruiser E-Bikes:Upright seating positions with balloon tires serve recreational coastal corridors in Portugal and southern Spain. Leisure-oriented specifications emphasize comfort over technical performance metrics.
Mature deployment sits with City E-Bikes. Newer deployment is concentrated in Mountain E-Bikes.
Battery Type:
Cell chemistry selection determines energy density, thermal management requirements, and end-of-life handling protocols across regulatory jurisdictions.
- Lithium-Ion:NMC and LFP cell architectures enable frame-integrated designs that reduce center-of-gravity height and improve handling dynamics. ECHA REACH compliance constraints on cobalt sourcing concentrate procurement among European assemblers with verified supply chain documentation. These packs dominate premium urban fleet specifications where weight reduction justifies cell cost premiums.
- Lead Acid:Flooded and AGM configurations persist in price-sensitive emerging markets with limited recycling infrastructure. Lower energy density forces external rack mounting that compromises vehicle dynamics and theft vulnerability.
- Nickel-Metal Hydride:Moderate energy density with reduced thermal runaway risk serves niche applications in temperature-extreme climates where lithium-ion management systems add cost complexity.
- Others:Solid-state prototypes and sodium-ion alternatives remain pre-commercial for two-wheel applications, with pilot deployments limited to research partnerships in German technical universities.
Volume concentration favors Lithium-Ion. Regulatory pressure is shifting procurement toward chemistry-neutral performance specifications.
Motor Position:
Drive unit placement determines torque delivery characteristics, maintenance accessibility, and frame design constraints across manufacturer engineering bases.
- Hub Motor:Direct-drive and geared variants integrated into wheel assemblies simplify manufacturing and enable belt-drive compatibility. Rad Power Bikes leverages these configurations for direct-to-consumer assembly simplicity in North American markets. Reduced unsprung weight concerns limit adoption in full-suspension mountain applications.
- Mid Motor:Bottom-bracket integration preserves wheel interchangeability and optimizes center-of-mass distribution for technical terrain. Bosch eBike Systems dominates this segment through Stuttgart-based engineering expertise and OEM partnership density. Premium fleet operators in Germany and the Netherlands specify mid-motor architectures for loaded cargo applications.
- Rear Motor:Dropout-integrated designs balance traction optimization with frame compatibility across retrofit conversion markets. These configurations serve aftermarket electrification of conventional bicycle frames.
- Front Motor:Fork-mounted drive units introduce steering inertia and traction limitations that restrict deployment to flat-terrain applications with minimal load variability.
Technology leadership resides with Mid Motor. Cost-driven volume expansion favors Hub Motor.
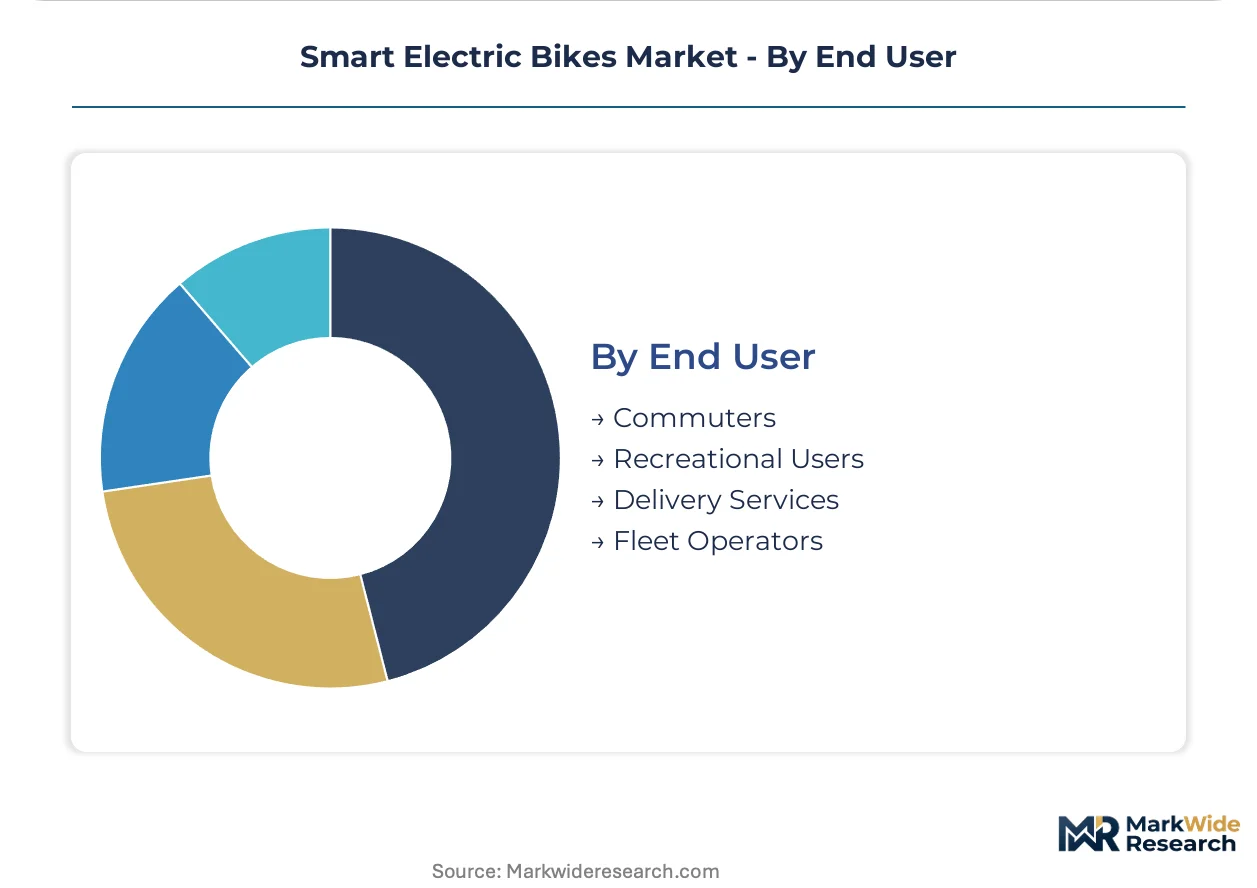
End User:
Procurement authority and utilization intensity create distinct requirements for durability, connectivity, and service response across customer categories.
- Commuters:Daily utilization patterns between 10-30 kilometers prioritize reliability and weather protection over performance specifications. Subscription access models in Paris and Milan displace outright purchase for this segment.
- Recreational Users:Weekend-centric duty cycles with seasonal storage requirements emphasize battery management systems that mitigate degradation during idle periods.
- Delivery Services:High-frequency stop-start operations with loaded cargo demand predictive maintenance platforms and rapid battery swap infrastructure. Urban low-emission zone compliance in Amsterdam and Berlin forces fleet conversion timelines.
- Fleet Operators:Centralized procurement with standardized specifications enables volume pricing and unified telematics integration. Municipal bike-sharing tenders in Copenhagen now mandate regenerative braking and GPS tracking as baseline features.
Procurement scale concentrates with Fleet Operators. Margin expansion opportunity sits with Delivery Services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors European smart electric bike engineering, with Bosch eBike Systems driving mid-motor integration from its Baden-Württemberg base. Battery demand clusters across Germany, the Netherlands, and Denmark as municipal procurement accelerates fleet electrification.
Germany
Berlin and Hamburg drive cargo e-bike fleet conversions as diesel van restrictions tighten in low-emission zones. The EU Green Deal mandates verified transport decarbonization progress through connected vehicle data. Stuttgart engineering bases concentrate mid-motor expertise for premium urban mobility specifications.
Netherlands
Amsterdam's municipal procurement now requires regenerative braking capability in bike-sharing tenders. ECHA REACH compliance constraints on cobalt sourcing limit European assemblers' supplier documentation options. Randstad logistics operators prioritize subscription-based fleet access over capital expenditure for last-mile delivery.
Denmark
Copenhagen mandates GPS tracking and energy recovery systems as baseline features in municipal tenders. The EU AI Act introduces algorithmic transparency requirements for predictive maintenance platforms optimizing fleet uptime. Danish fleet operators deploy standardized telematics across Germany and Belgium despite divergent data localization requirements.
United States
Seattle and Portland accelerate direct-to-consumer channel migration for simplified hub-motor configurations. FCC certification timelines for wireless telemetry modules extend product launches by 4-6 months relative to CE-marked equivalents. Rad Power Bikes anchors North American online configuration tools with home delivery assembly models.
Switzerland
Graubünden and Tyrol trail access policies liberalize demand for Mountain E-Bike deployment with ruggedized battery enclosures. Swissmedic-equivalent technical standards govern predictive maintenance algorithm deployments in cross-border fleet operations. Alpine jurisdictions currently lack dedicated service networks for premium terrain-capable specifications.
Smart Electric Bikes Market Competitive Landscape
The competitive structure tilts toward engineering-intensive component suppliers controlling premium fleet specifications. Mid-motor integration expertise clusters around Stuttgart-based engineering bases, creating dependency concentration for loaded cargo applications. Two strategic archetypes dominate: vertically integrated drive unit manufacturers and direct-to-consumer hub-motor assemblers. Competitive moves concentrate on strategic OEM partnerships and geographic channel expansion.
Among German engineering-intensive suppliers, Bosch eBike Systems and Yamaha Motor Co. Ltd. exemplify the drive unit manufacturer archetype through Stuttgart-based and in-house production positioning respectively. Rad Power Bikes occupies the direct-to-consumer vector with simplified hub-motor configurations. These three anchors illustrate how technical specialization and channel strategy bifurcate competitive positioning across premium fleet and mass-market segments.
| Leading Market Players |
|---|
| Bosch eBike Systems |
| Yamaha Motor Co. Ltd. |
| Giant Manufacturing Co. Ltd. |
| Trek Bicycle Corporation |
| Rad Power Bikes |
| Specialized Bicycle Components |
| Yadea Group Holdings Ltd |
| Merida Industry Co. Ltd. |
| Aventon Bikes |
| Others |
Pricing and Supply Chain Analysis
Frame-integrated battery designs enabled by advancing cell chemistry are simultaneously compressing production costs and concentrating procurement power among European assemblers with verified ECHA REACH documentation. This technical transition tightens supplier qualification thresholds while expanding premium positioning for fleet operators seeking weight-optimized urban mobility solutions.
Pricing Analysis
Value-based pricing anchored to fleet uptime outcomes dominates municipal procurement in Copenhagen and Amsterdam. Three-tier pricing structure across premium mid-motor, standard hub-motor, and economy conversion-kit levels reflects certification grade and after-sales bundling intensity. Pricing pressure stems from raw material volatility in cobalt and nickel sourcing. Delivery services exhibit highest price sensitivity due to route volatility, while alpine recreational buyers tolerate premium positioning for terrain capability.
Supply Chain Analysis
EU Green Deal domestic-content mandates are forcing battery passport traceability investments that reshape sourcing patterns across European assembly operations. Mid-motor expertise clusters in Germany, Netherlands, and Denmark while lithium-ion cell production draws from South Korea and Japan. Cobalt and nickel dependencies create single-source vulnerability in cathode material supply. Distribution runs through OEM partnership networks for premium fleet specifications and direct-to-consumer channels for simplified hub-motor configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
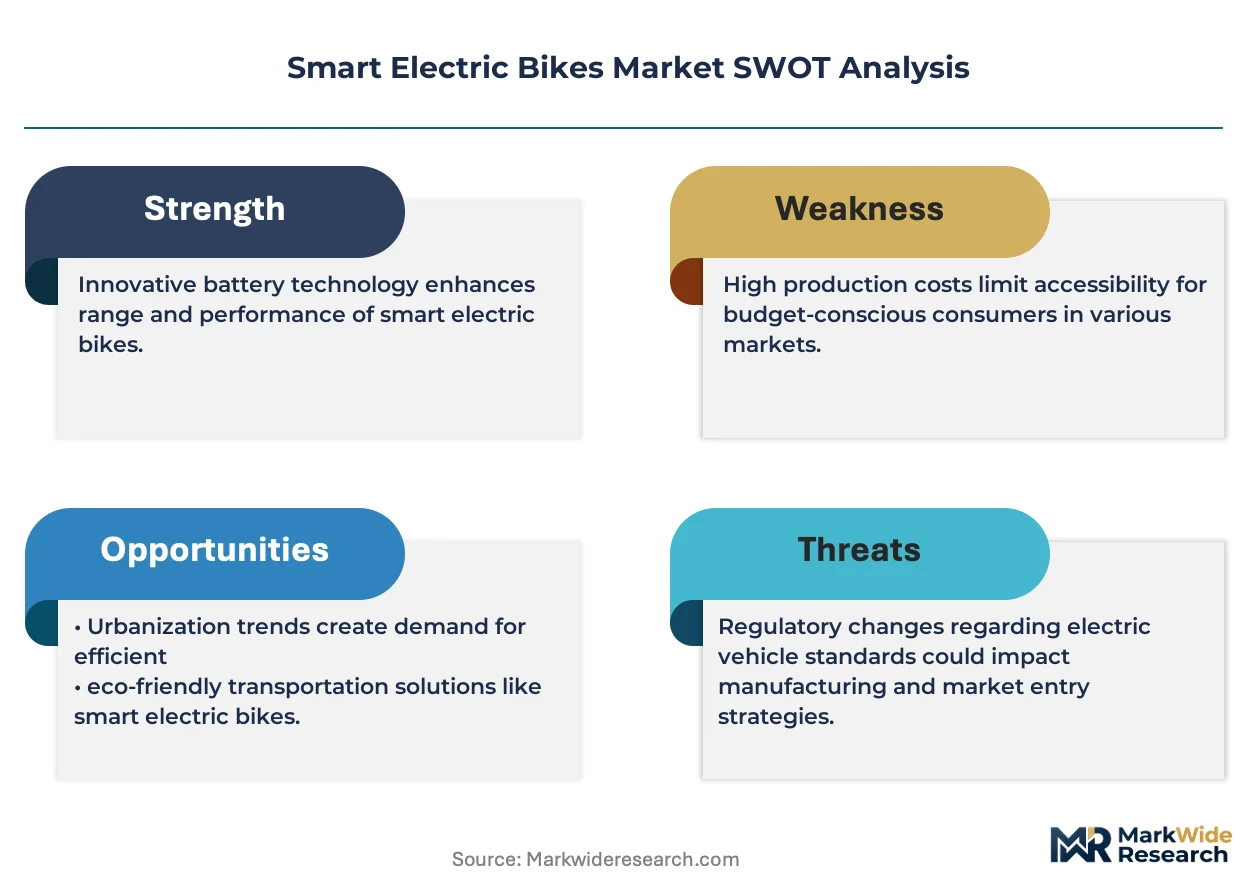
The EU AI Act's algorithmic transparency requirements create a cost-of-compliance moat that favors incumbents with embedded telemetry capabilities and documented decision logic for predictive maintenance platforms.
For Market Incumbents: Acquire predictive maintenance software assets to consolidate fleet uptime optimization capabilities. Bosch eBike Systems should deepen Stuttgart engineering density for mid-motor integration while expanding battery passport documentation systems to defend against emerging hub-motor assemblers exploiting direct-to-consumer channel expansion. Certification investment in ECHA REACH compliance creates switching costs that protect municipal procurement relationships. For New Entrants and Emerging Players: Begin with underpenetrated Mountain E-Bike service networks in Swiss and Austrian alpine jurisdictions where trail access liberalization outpaces dedicated maintenance infrastructure. Target subscription-based fleet access models in Paris and Milan logistics verticals where route volatility makes asset ownership risk-prohibitive. Deploy simplified hub-motor configurations with online configuration tools to bypass traditional retail networks. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by automotive Tier 1 suppliers seeking electrification capabilities. Long-term viability hinges on differentiation through software-defined service layers rather than hardware commoditization. Monitor EU battery passport mandate implementation timelines as inflection indicator for compliance-cost barriers affecting acquisition target valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Passport Traceability Investment | ECHA REACH compliance documentation creates procurement eligibility for German municipal tenders. |
| Predictive Maintenance Platform Development | EU AI Act algorithmic transparency requirements favor first-movers with embedded telemetry architectures. |
| Direct-to-Consumer Channel Expansion | Rad Power Bikes demonstrates simplified hub-motor configurations bypass traditional retail networks effectively. |
| Alpine Service Network Buildout | Graubünden and Tyrol trail access policies create whitespace for Mountain E-Bike maintenance infrastructure. |
| Subscription Fleet Access Model Launch | Paris and Milan logistics operators prioritize per-kilometer pricing over capital expenditure commitments. |
Research Methodology
Trade databases, EU regulatory filings, and automotive component supplier disclosures formed the secondary backbone for this analysis. Primary interviews with fleet procurement managers, municipal tender officials, battery supply chain directors, and predictive maintenance platform engineers validated segment assumptions. Bottom-up and top-down triangulation reconciled production volume estimates with end-user deployment data across German, Dutch, and Danish urban mobility operators.
Bottom-up modeling aggregated individual country-level fleet conversion timelines while top-down analysis cross-checked against EU Green Deal transport decarbonization budget allocations. Segmentation dimensions included product type, battery chemistry, motor position, and end-user category across the analysis window. CAGRs derived from logistic curve fitting to municipal procurement acceleration patterns and lithium-ion energy density improvement trajectories. Forecast inputs incorporated diesel van restriction tightening schedules and charging infrastructure deployment curves.
Underlying measurement precision varies by segment; City E-Bike fleet data carries tighter precision than emerging Mountain E-Bike alpine deployments. Forecasts reflect documented assumptions regarding EU battery passport implementation timelines and ECHA REACH enforcement intensity. Raw material price volatility and cross-border data governance divergence present specific revision risks. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
Global Motorcycle Supercharger Market
Bikes and Motorcycles
Two-Wheeler Lighting Market
Bikes and Motorcycles
Sweden Electric Bike Market
Bikes and Motorcycles
US Fuel Cell Bikes Market
Bikes and Motorcycles
Global Two Wheeler Accessories Market
Bikes and Motorcycles
Netherlands E-Bike Market
Bikes and Motorcycles
On-Road Motorcycles Market
Bikes and Motorcycles
Bicycle Trip Market
Bikes and Motorcycles
Europe Two-Wheeler Market
Bikes and Motorcycles
Latin America Bike Sharing Market
Bikes and Motorcycles
Europe Motorcycle Airbag Market
Bikes and Motorcycles
Motorcycle Wheels Market
Bikes and Motorcycles
Motorcycle Drive Chain Market
Bikes and Motorcycles
Two-Wheeler Brake Pads Market
Bikes and Motorcycles
United Arab Emirates E-Bike Market
Bikes and Motorcycles
Flying Bikes Market