
 Maxi Scooter Market | 2026-2036
Maxi Scooter Market Size, Share, and Industry Trends Forecast 2026-2036
Maxi Scooter Market Foresight
Multi-sourcing of battery packs and powertrain subsystems is broadening as OEMs hedge against semiconductor and raw material volatility. Honda anchors its competitive stance through in-house engine manufacturing and scale advantages across Asian supply corridors. Yamaha differentiates via performance-oriented 300cc-500cc platforms targeting touring-oriented riders in mature European markets. Kymco specializes in electric maxi scooter architectures, leveraging Taiwan's electronics supplier density to compress development cycles.
A maxi scooter denotes a large-frame motorized two-wheeler with an enclosed step-through chassis, typically housing engines from 125cc to 500cc and offering under-seat storage exceeding 40 liters. These vehicles serve primarily urban and suburban commuters requiring weather protection, cargo capacity, and highway-capable speeds without motorcycle licensing complexity in many jurisdictions. Gasoline configurations retain volume leadership across European and Southeast Asian markets, while electric variants capture disproportionate R&D allocation amid fleet electrification mandates. The 300cc engine capacity band occupies the margin-rich center of the product spectrum, balancing regulatory compliance with premium pricing power. Customer type segmentation reveals fleet operators and delivery services as the fastest-expanding demand pool, driven by last-mile logistics densification.
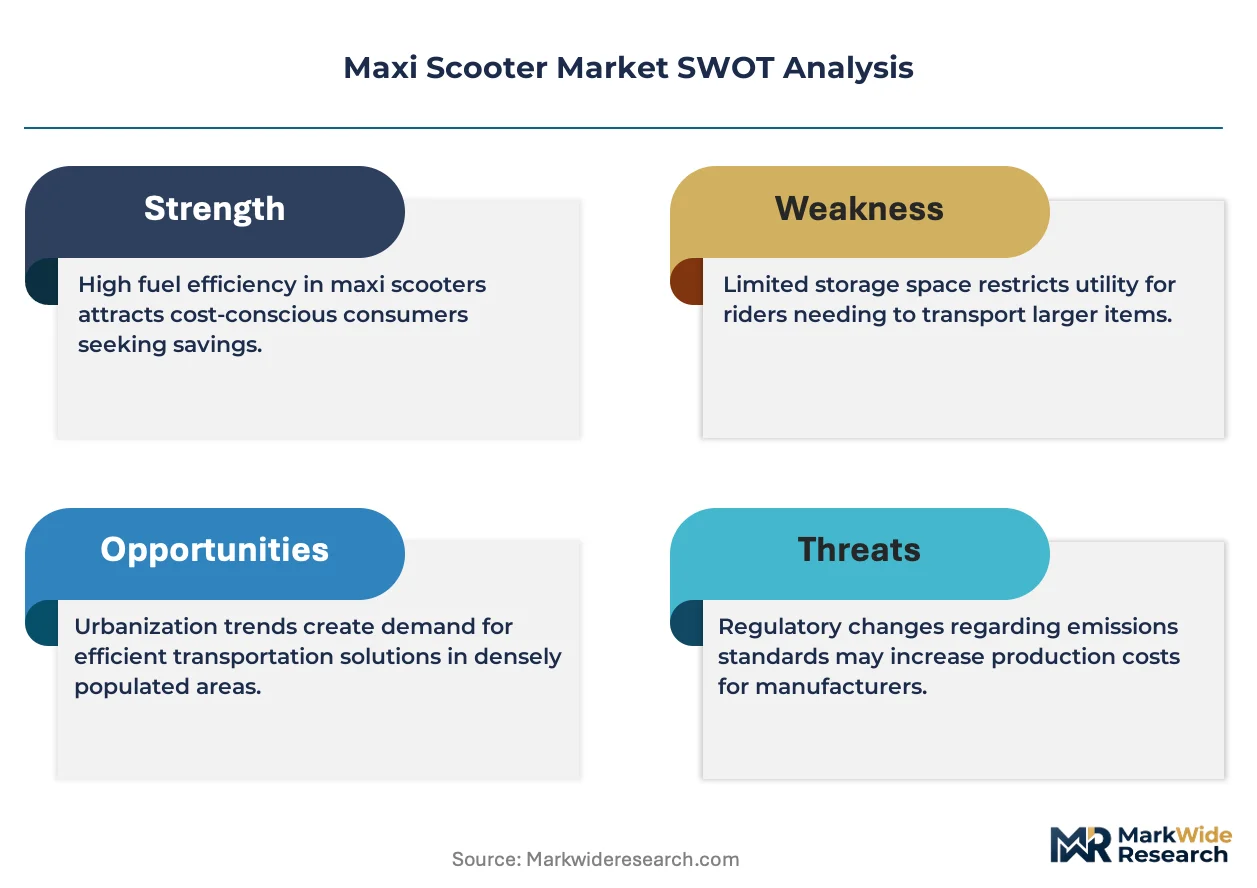
Europe's EMA and F-Gas Regulation constrain refrigerant choices in thermal management systems, indirectly shaping electric maxi scooter battery cooling architectures. The EPA in the United States enforces Tier 3 emission thresholds that gasoline-powered imports must satisfy for federal compliance, filtering the addressable product set. Japan's METI subsidizes domestic battery supply chain localization, influencing where OEMs situate electric platform engineering centers. Stakeholders must track how divergent carbon-accounting rules across the EU, US, and Japan reshape sourcing economics for lithium-ion cell packs and rare-earth motor materials.
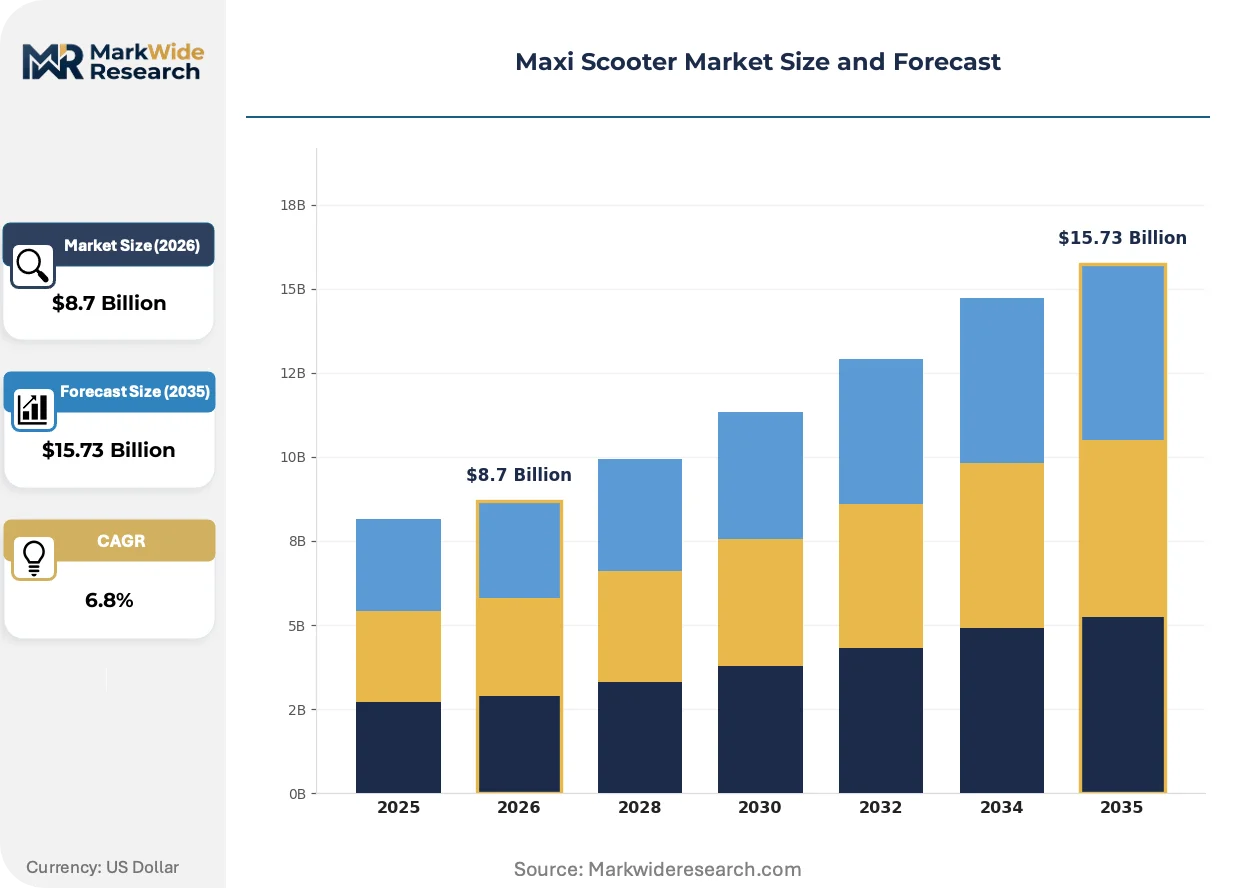
Market Dynamics
Fleet electrification mandates across European cities are compressing replacement cycles and forcing powertrain portfolio redesigns, while raw material volatility pushes OEMs toward multi-sourcing strategies for battery cells and semiconductor components.
Growth Catalysts
- Urban logistics densification:Last-mile delivery operators in Milan, Paris, and Barcelona are tripling fleet orders for 300cc-class vehicles to navigate congestion-charged city centers while maintaining cargo capacity.
- Euro 6 emission protocols:The impending regulatory tightening is accelerating gasoline engine R&D spend toward lean-burn combustion and hybrid architectures ahead of enforcement deadlines.
- Taiwan electronics corridor:Dense supplier clustering around Taichung and Tainan compresses electric powertrain development cycles by enabling same-day prototyping iterations for motor controllers and battery management systems.
Market Restraints
- Lithium carbonate price volatility:Cell pack input costs swing unpredictably, eroding margin visibility for electric platform investments and forcing hedging strategies that consume working capital.
- Semiconductor foundry concentration:Taiwan and South Korea dominate automotive-grade chip fabrication, creating single-source vulnerability for throttle controllers and instrument cluster processors.
- High-voltage technician scarcity:Electric drivetrain servicing requires certified specialists that independent repair networks struggle to recruit and retain at viable wage structures.
Strategic Opportunities
- Battery-as-a-service models:Swappable pack architectures decouple vehicle purchase from energy storage ownership, lowering entry barriers for fleet operators in Barcelona and Rome.
- India two-wheeler electrification:FAME-II subsidy extensions and state-level purchase incentives create addressable demand for 125cc-equivalent electric platforms in Bengaluru and Delhi NCR.
- Connected fleet telematics:Integrated route optimization and predictive maintenance APIs differentiate vendor offerings for logistics aggregators managing multi-brand scooter pools.
Industry Challenges
- Homologation timeline compression:Euro 5 to Euro 6 transition windows force parallel certification tracks that strain engineering bandwidth and delay regional product launches.
- Legacy dealer service adaptation:Traditional retail networks lack diagnostic equipment and training curricula for high-voltage systems, creating warranty execution gaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Maxi Scooter Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric, Gasoline, Hybrid, Off-Road Customer Type: Individual Users, Fleet Operators, Delivery Services, Rental Companies Engine Capacity: 125cc, 200cc, 300cc, 500cc Distribution Channel: Showrooms, Online Retail, Dealers, Trade Shows |
| Companies Covered | Kymco, BMW, Honda, Aprilia, SYM, Yamaha, Suzuki, Vespa, Piaggio, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Maxi Scooter Market Shifts & Advancements
Powertrain electrification and thermal management advances are converging with procurement model experimentation, reshaping how vehicles are specified, financed, and maintained across urban delivery and private mobility segments.
Cell-to-pack battery architectures are automating thermal propagation containment and structural integration previously handled by modular enclosures. Fleet operators in Amsterdam and Copenhagen are specifying these designs to maximize volumetric energy density and minimize pack replacement downtime. The technology is automating vendor selection criteria toward integrated cell manufacturers with in-house thermal engineering capabilities.
Europe's F-Gas Regulation constrains refrigerant choices for battery cooling circuits, forcing redesigns toward CO2-based systems or dielectric fluid immersion. Tier-1 suppliers are consolidating thermal management competencies to serve multiple OEM programs simultaneously. Electric maxi scooter platforms with highway-speed thermal loads face the steepest compliance cost escalation.
Subscription-based access models are displacing traditional ownership in dense European urban cores. Young professionals in Berlin and Vienna increasingly favor all-inclusive monthly fees covering vehicle, insurance, maintenance, and battery swapping over depreciation risk. This shift concentrates demand toward OEMs with captive financing arms and swap-station network partnerships.
Maxi Scooter Market Segmentation
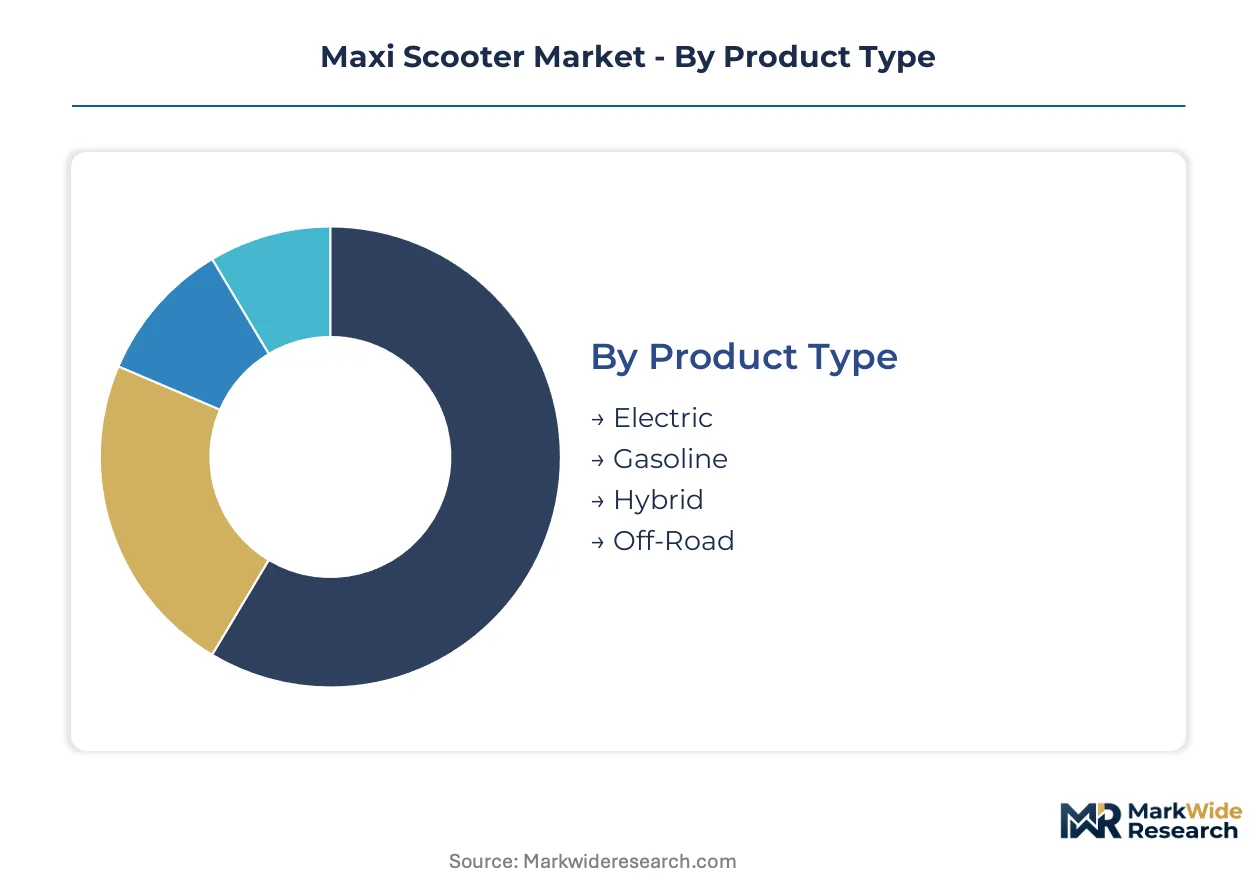
Segmentation in the maxi scooter market reveals how powertrain choices, procurement patterns, and displacement preferences diverge across private mobility and commercial logistics applications. Understanding these splits enables OEMs to allocate R&D budgets and configure distribution networks against distinct buyer economics.
Product Type:
Buyers weigh total cost of ownership against regulatory compliance timelines when selecting propulsion architecture.
- Electric:Battery-electric platforms with lithium-ion cell packs and integrated thermal management systems. Fleet operators in Milan and Barcelona prioritize these for congestion-zone access and fuel cost predictability, though charging infrastructure gaps constrain private adoption.
- Gasoline:Internal combustion engines from 125cc to 500cc, predominantly single-cylinder or parallel-twin configurations. Individual commuters across Italy and France favor gasoline for refueling speed and established service networks, even as Euro 6 deadlines force powertrain redesigns.
- Hybrid:Mild-hybrid architectures combining small-displacement engines with electric assist motors. Brief treatment: Limited commercial traction due to cost complexity, though some European OEMs explore 48V systems for emissions compliance bridging.
- Off-Road:Reinforced chassis and suspension travel for unpaved terrain navigation. Brief treatment: Niche demand concentrated in Mediterranean recreational markets with limited volume scaling potential.
Volume sits with gasoline configurations; growth tilts toward electric platforms.
Customer Type:
Procurement scale and utilization intensity separate buyer groups more sharply than price sensitivity alone.
- Individual Users:Private commuters seeking weather protection and cargo capacity without motorcycle licensing complexity. These buyers dominate Italian and Spanish retail channels, prioritizing brand heritage and under-seat storage dimensions over connected features.
- Delivery Services:Last-mile logistics operators running high-utilization fleets across dense urban cores. Demand concentrates in Paris and Rome where traffic restrictions and delivery volume surges compress replacement cycles toward 300cc-class vehicles.
- Fleet Operators:Multi-vehicle managers serving corporate mobility or rental pools. Brief treatment: Standardized maintenance protocols and telematics integration drive vendor selection over individual model specifications.
- Rental Companies:Short-term mobility providers targeting tourists and temporary residents. Brief treatment: Seasonal demand fluctuations in coastal Mediterranean cities create inventory management complexity.
Individual users generate the highest unit volumes; delivery services are expanding most quickly.
Engine Capacity:
Displacement bands align with licensing regimes, highway capability requirements, and margin structures.
- 300cc:Single-cylinder or parallel-twin engines balancing urban maneuverability with sustained highway speeds. This band captures disproportionate R&D investment and pricing power across European markets, serving commuters who traverse city peripheries regularly.
- 125cc:Entry-level displacement restricted to urban speeds in many licensing jurisdictions. Novice riders in Italy and France favor these for reduced insurance costs and accessible operating permits, though limited power constrains suburban utility.
- 200cc:Mid-displacement stepping stone between urban-only and highway-capable platforms. Brief treatment: Squeezed positioning as 300cc pricing compression erodes its value proposition.
- 500cc:Premium touring-oriented displacement with twin-cylinder configurations. Brief treatment: Enthusiast segment with highest per-unit margins but constrained volume due to licensing tier jumps in key markets.
300cc configurations anchor manufacturer profitability; 125cc variants gain share fastest among electrification-adjacent entry buyers.
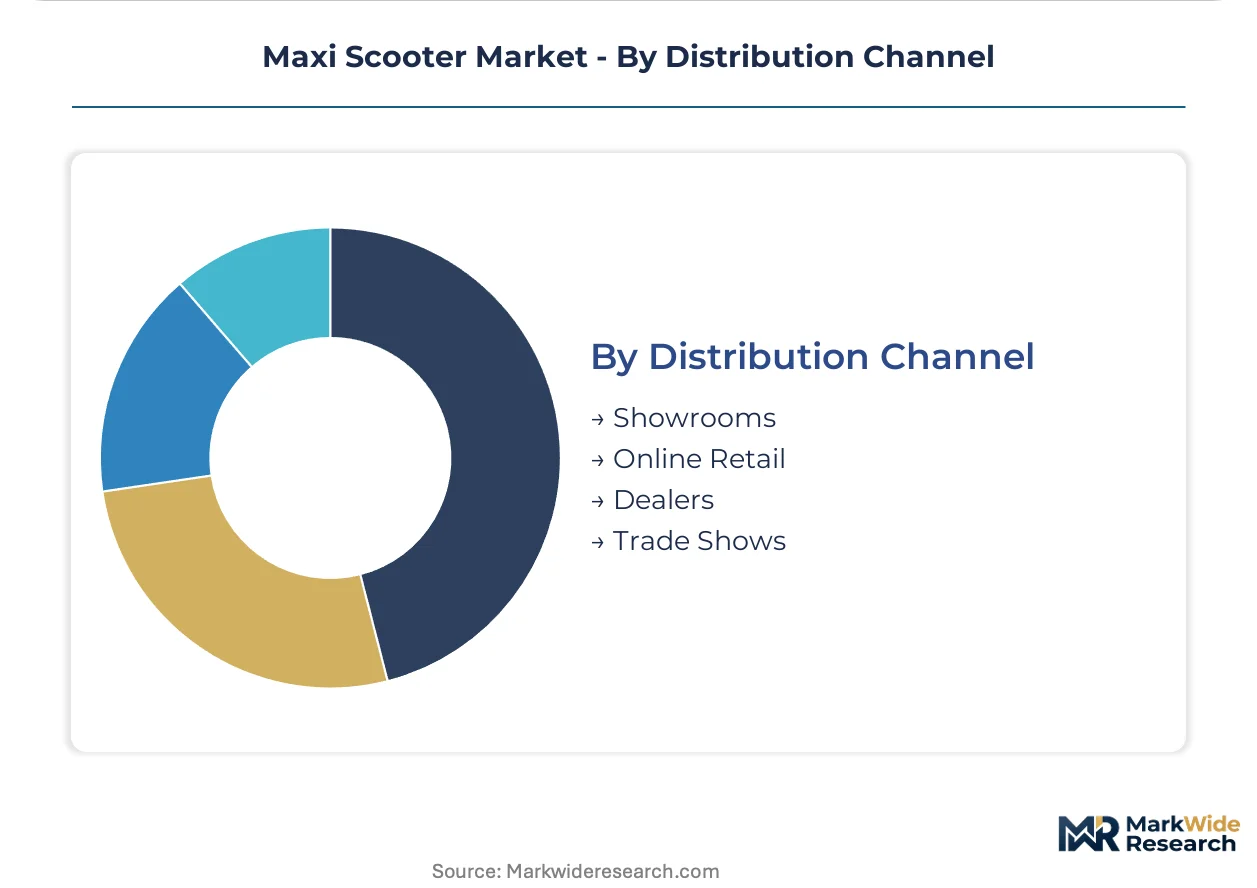
Distribution Channel:
Channel selection reflects purchase frequency, technical complexity, and financing integration requirements.
- Dealers:Authorized retail networks providing test rides, warranty execution, and service bay access. Established dealer density in Northern Italy and Germany sustains gasoline platform sales despite electric direct-to-consumer experiments.
- Online Retail:Digital-first purchase journeys with home delivery or pickup point fulfillment. Young professionals in Berlin and Vienna increasingly favor this channel for subscription-based access models with bundled insurance.
- Showrooms:Manufacturer-owned flagship locations in premium urban positioning. Brief treatment: Brand experience investments concentrate in Milan and Paris with limited transaction conversion.
- Trade Shows:Periodic exhibition-based ordering for fleet procurement managers. Brief treatment: EICMA in Milan anchors annual B2B volume commitments for rental and delivery operators.
Dealer networks handle the greatest transaction volume; online retail is climbing the fastest among urban subscription adopters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lithium carbonate processing in Chile's Atacama salt flats supplies cathode precursors for battery packs assembled in Taichung and Shenzhen. This raw-material corridor shapes where electric maxi scooter engineering centers concentrate and how OEMs route procurement spend.
Italy
Individual commuters in Milan and Rome sustain gasoline platform demand through entrenched dealer networks and brand heritage preferences. Euro 5 and impending Euro 6 protocols force powertrain redesigns across single-cylinder and parallel-twin portfolios. Piaggio maintains manufacturing clusters in Tuscany and Veneto, anchoring domestic supply chains for 300cc-class vehicles.
Taiwan
Electronics supplier density around Taichung and Tainan compresses electric powertrain development cycles for motor controllers and battery management systems. METI-influenced Japanese OEMs source from this corridor to localize engineering for Asian electric platforms. Kymco leverages this clustering to prototype swappable pack architectures ahead of European fleet mandates.
Germany
Fleet operators in Berlin and Munich pilot subscription-based access models with bundled insurance and maintenance. The KBA enforces type-approval standards that filter gasoline import compliance and shape electric homologation timelines. BMW anchors engineering in Bavaria, developing thermal management systems constrained by Europe's F-Gas Regulation.
France
Delivery services in Paris tripled fleet orders for 300cc-class vehicles to navigate congestion-charged city centers while maintaining cargo capacity. The country's national environmental regulator enforces low-emission zone protocols that accelerate gasoline replacement cycles. Industrial clustering around Lyon supports precision casting for engine blocks and dielectric fluid cooling components.
Japan
Touring-oriented riders in Tokyo and Osaka sustain demand for 400cc-500cc platforms with premium pricing power. METI subsidizes domestic battery supply chain localization, influencing where OEMs situate electric platform engineering centers. Yamaha and Honda maintain captive engine manufacturing in Shizuoka and Kumamoto, preserving scale advantages across Asian supply corridors.
Maxi Scooter Market Competitive Landscape
Capacity expansion dominates the current landscape as OEMs add assembly lines for electric platforms ahead of European fleet mandates. The vendor base organizes around three tiers: integrated automotive conglomerates with captive powertrain manufacturing, specialized two-wheeler houses with entrenched dealer density, and emerging electric-native entrants leveraging contract manufacturing. Strategic archetypes include scale-driven gasoline specialists, electronics-integrated electric pioneers, and premium touring-positioned performance brands. M&A activity and strategic partnerships concentrate around battery pack sourcing and swap-station network access.
Among Asian-based manufacturers, Honda, Yamaha, and Kymco occupy distinct competitive positions. Honda exemplifies the vertically integrated archetype through in-house engine manufacturing and control over Asian supply corridors. Yamaha represents performance-oriented positioning across 300cc-500cc touring platforms targeting mature European markets. Kymco sits within the electric-native tier, leveraging Taiwan's electronics supplier density to compress development cycles for swappable battery architectures.
| Leading Market Players |
|---|
| Kymco |
| BMW |
| Honda |
| Aprilia |
| SYM |
| Yamaha |
| Suzuki |
| Vespa |
| Piaggio |
| Others |
Supply & Pricing Matrix
Lithium carbonate spot volatility cascades through cell pack procurement into three-tier pricing structure across premium, standard, and economy levels, with fleet buyers absorbing cost compression through battery-as-a-service unbundling while individual commuters face sticker shock on outright purchases.
Pricing Analysis
Warranty and service bundling separates fleet procurement from retail transactions, with delivery operators negotiating all-inclusive maintenance contracts that inflate upfront unit economics but flatten total cost visibility. Price differentiation hinges on thermal management certification grade and swap-station network access. Pricing pressure stems from raw material input swings eroding margin visibility for electric platform investments. Fleet operators exhibit lowest price sensitivity due to utilization intensity, while novice 125cc buyers in Italy and France drive hardest bargain negotiations.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale fleet demand from Paris and Milan delivery aggregators, while dealer networks manage fragmented individual buyer transactions. Manufacturing concentrates in Italy, Taiwan, and Japan, drawing from Chilean lithium processing and Chinese cathode precursor refining. Semiconductor foundry concentration in Taiwan and South Korea creates single-source vulnerability for throttle controllers and battery management systems. Distribution runs through authorized retail networks with captive financing arms in Northern Italy and Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into battery cell manufacturing and swap-station infrastructure represents the decisive competitive lever, with OEMs racing to secure cathode precursor supply and captive energy storage networks before European fleet mandates harden procurement requirements.
For Market Incumbents: Anchor profitability through backward integration into lithium-ion cell production and thermal management subsystem manufacturing, neutralizing raw material volatility exposure. Defend dealer network density against direct-to-consumer experiments by embedding high-voltage diagnostic equipment and certified technician training curricula, closing warranty execution gaps that electric-native entrants exploit.
For New Entrants and Emerging Players: Swappable pack architecture patents offer entry wedge into Barcelona and Rome fleet markets where battery-as-a-service models lower capital barriers. Target India two-wheeler electrification under FAME-II subsidy extensions, exploiting state-level purchase incentives in Bengaluru and Delhi NCR with 125cc-equivalent electric platforms priced below gasoline alternatives.
For Investors and Strategic Acquirers: Distressed-cycle entries favor Taiwan-based electronics-integrated powertrain specialists with METI-influenced Japanese OEM relationships, capturing engineering center localization trends. Long-term viability hinges on swap-station network density achieving critical mass in congestion-charged European urban cores. Watch lithium carbonate futures backwardation as inflection signal for electric platform margin recovery.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Cell pack procurement contracts with Chilean lithium processors stabilize input cost visibility for European fleet mandates. |
| Swap-Station Network Partnership | Barcelona and Rome infrastructure density accelerates battery-as-a-service adoption among delivery service operators. |
| Thermal Management Investment | CO2-based cooling system development satisfies Europe's F-Gas Regulation constraints on electric highway-speed platforms. |
| Platform Standardization | 300cc-class architecture commonality across gasoline and hybrid variants compresses Euro 6 homologation timelines. |
| Geographic Manufacturing Footprint | Taichung electronics corridor proximity compresses motor controller prototyping cycles for Asian electric platforms. |
Research Methodology
Document review covered customs trade databases, vehicle registration filings, and OEM annual disclosures, complemented by interviews with fleet procurement managers at Milan and Paris delivery operators, dealer network principals in Northern Italy and Germany, and thermal management engineering leads at Tier-1 suppliers. Secondary validation drew from KBA type-approval records, EICMA exhibition order data, and METI subsidy program documentation. Bottom-up triangulation across production volume estimates and top-down reconciliation against replacement cycle assumptions anchored forecast integrity.
Segment-level projections across powertrain architecture, engine displacement band, and customer type were generated across the analysis window, with CAGRs derived from logistic diffusion curves fitted to fleet electrification mandate enforcement schedules and urban logistics densification trajectories. Model inputs incorporated Euro 6 compliance cost escalation curves, lithium carbonate price volatility bands, and semiconductor foundry capacity utilization assumptions specific to automotive-grade chip fabrication.
Several conditions sit outside the modeled scope, including abrupt regulatory timeline shifts, trade policy disruptions affecting Chile-Taiwan battery material corridors, and unforeseen breakthroughs in solid-state cell chemistry. Forecasts reflect documented assumptions regarding fleet operator procurement elasticity and individual buyer gasoline preference persistence. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
United Arab Emirates E-Bike Market
Bikes and Motorcycles
Brazil E-Bike Market
Bikes and Motorcycles
Emission Control Catalyst for Motorcycle Market
Bikes and Motorcycles
LAMEA Motorcycle ADAS Market
Bikes and Motorcycles
Electric Cargo Bikes Market
Bikes and Motorcycles
Denmark E-Bike Market
Bikes and Motorcycles
Bike Computer Market
Bikes and Motorcycles
Europe Motorcycle Market
Bikes and Motorcycles
Hydrobike Market
Bikes and Motorcycles
Bike Kickstand Market
Bikes and Motorcycles
Two-Wheeler Lighting Market
Bikes and Motorcycles
North America Bicycle Market
Bikes and Motorcycles
Connected Motorcycle Market
Bikes and Motorcycles
Automotive Bicycle Rack Market
Bikes and Motorcycles
Asia-Pacific Two-Wheeler Taxi Market
Bikes and Motorcycles
Ride on Bikes Market