
 Cruiser Bikes Market | 2026-2036
Cruiser Bikes Market Size, Share, and Industry Trends Forecast 2026-2036
Cruiser Bikes Market Intelligence
A widening capital-intensity gap between premium heritage builders and volume-focused assemblers is reorganizing competitive dynamics in the cruiser motorcycle space. Harley-Davidson leverages its vertically integrated domestic manufacturing footprint to sustain margin control across the mid-displacement and heavy-touring ranges. Indian Motorcycle anchors its position through heritage branding and dealer network density in North American markets. Yamaha competes aggressively in the entry-level cruiser segment with liquid-cooled V-twin platforms that undercut traditional air-cooled rivals on maintenance cost.
Cruiser bikes are heavyweight motorcycles engineered for relaxed ergonomics, low seat heights, and substantial torque delivery at low RPM, typically constructed around V-twin or parallel-twin engines with steel tube frames and belt or shaft final drive. The category serves recreational road riders, long-distance tourers, and style-conscious urban commuters who prioritize comfort and aesthetic presence over cornering performance. Standard Cruiser and Touring Cruiser variants dominate unit volume, while the Custom Cruiser segment commands disproportionate margin contribution through aftermarket parts integration and personalization services. Steel frame construction retains cost leadership in mass-market offerings, though aluminum and carbon fiber adoption accelerates in premium displacement tiers where weight reduction justifies material substitution economics.
EPA emission certification in the United States, Euro 5 standards administered by the European Commission, and type-approval requirements from Japan's Ministry of Land, Infrastructure, Transport and Tourism collectively dictate engine architecture choices and exhaust after-treatment investments. Compliance timelines force manufacturers to retire carbureted legacy platforms and accelerate fuel-injection and catalytic converter deployment across model lines. Stakeholders must monitor regulatory divergence between California's Air Resources Board and federal EPA thresholds, as stricter state-level rules could fragment product planning and certification costs for multi-market portfolios.
Market Dynamics
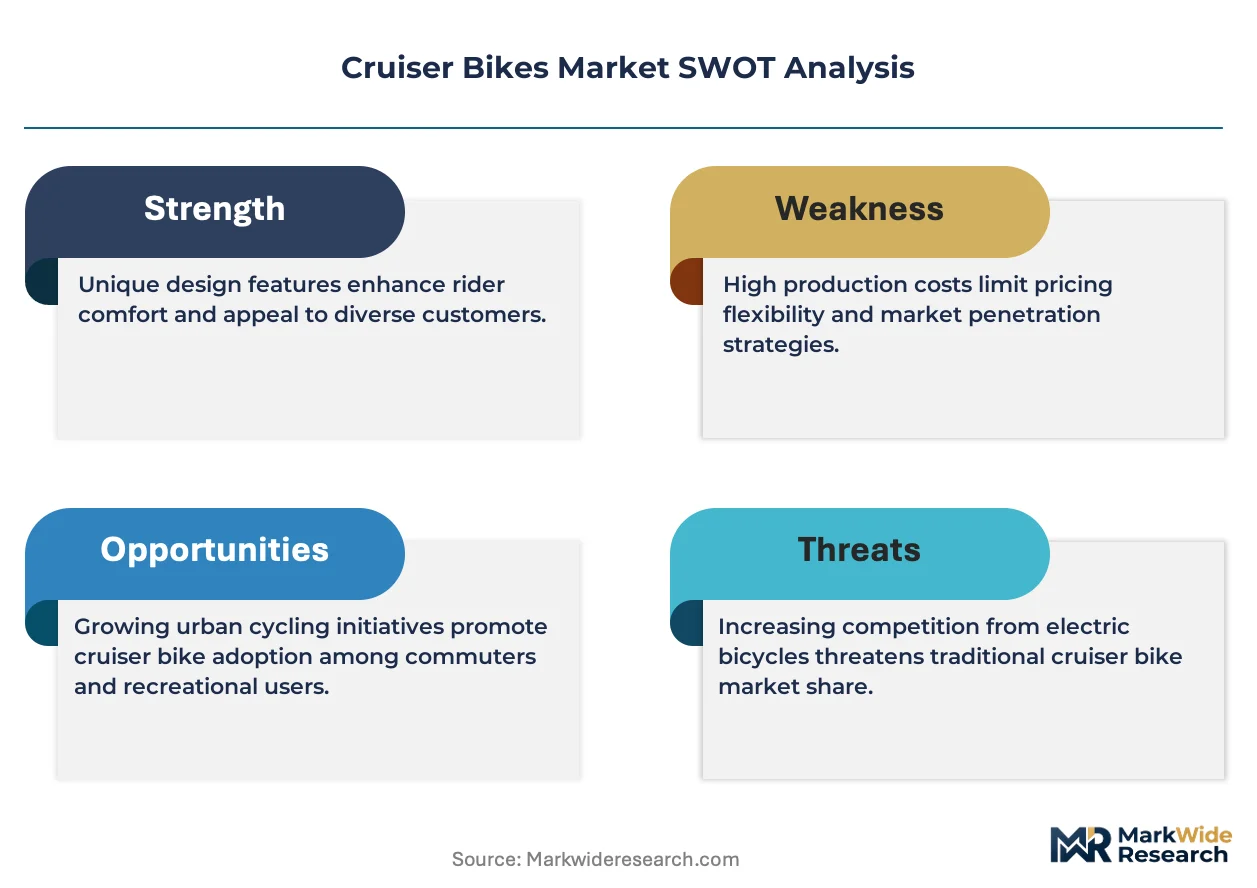
EPA emission certification and Euro 5 compliance deadlines are forcing cruiser manufacturers to retire carbureted architectures and absorb substantial exhaust after-treatment costs, compressing margins on entry-displacement models while accelerating consolidation around fuel-injected platforms.
Growth Catalysts
- Leisure rider expansion:Wisconsin and California anchor a demographic shift toward recreational touring, with empty-nest buyers prioritizing comfort and aesthetic presence over sport performance.
- Euro 5 engine architecture:The European Commission's stricter type-approval standards are compelling cleaner combustion designs that extend platform lifecycles through modular scalability.
- Shaft final drive adoption:Liquid-cooled V-twin configurations with maintenance-reducing shaft drives are capturing riders seeking lower total cost of ownership.
Market Restraints
- Steel tube frame cost volatility:Input material price swings compress assembler margins on mass-market Standard Cruiser variants where substitution economics fail.
- California Air Resources Board fragmentation:Stricter state-level emission thresholds versus federal EPA baselines force redundant certification investments for multi-market portfolios.
- Electric powertrain substitution:Battery-electric two-wheelers from adjacent categories threaten urban commuter segments where cruiser styling competes with zero-emission alternatives.
Strategic Opportunities
- Custom Cruiser aftermarket integration:Personalization services and parts bundling command disproportionate margin contribution beyond base vehicle sales.
- Japan type-approval alignment:The Ministry of Land, Infrastructure, Transport and Tourism's harmonized standards open pathway for unified platform certification across Pacific Rim markets.
- Direct-to-rider digital channels:Manufacturer-owned configuration tools and subscription maintenance packages bypass traditional dealer density constraints.
Industry Challenges
- Catalytic converter integration complexity:Packaging exhaust after-treatment within heritage frame geometries demands retooling investments that strain mid-tier assemblers.
- Carbureted legacy technician scarcity:Diagnostic expertise for aging air-cooled fleets is concentrating at specialized independent shops, fragmenting service network coverage.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cruiser Bikes Market |
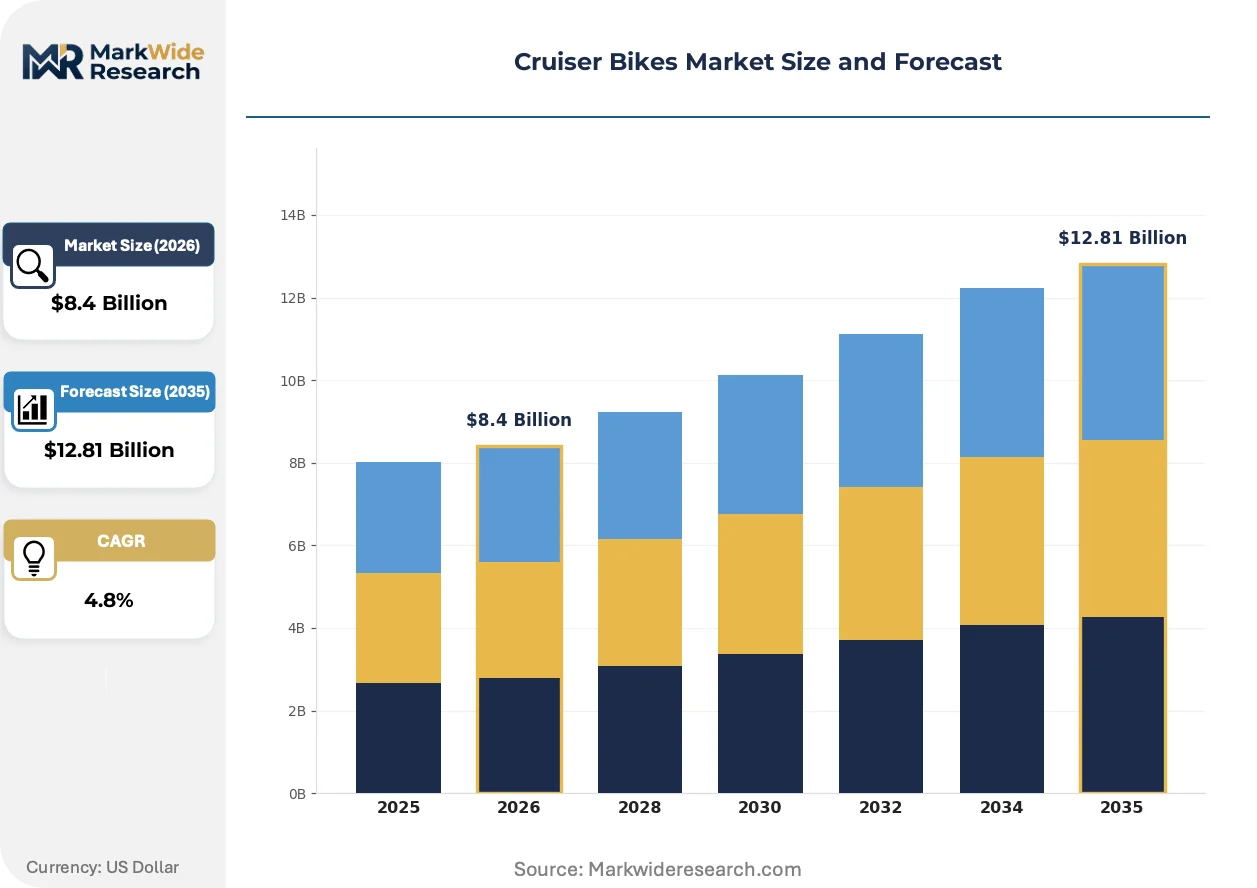
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $12.81 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Bike Type: Standard Cruiser, Chopper, Custom Cruiser, Touring Cruiser Frame Material: Steel, Aluminum, Carbon Fiber, Titanium Engine Capacity: 250cc-500cc, 501cc-1000cc, 1001cc-1500cc, Above 1500cc Design Style: Classic, Modern, Retro, Sporty |
| Companies Covered | Triumph, Kawasaki, Harley-Davidson, Yamaha, Honda, Ducati, BMW Motorrad, Buell, Indian Motorcycle, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cruiser Bikes Market Strategic Shifts & Innovations
Powertrain electrification, regulatory harmonization pressures, and direct-channel commerce are restructuring how cruiser motorcycles reach riders and comply with emission mandates.
Liquid-cooled V-twin architectures with dual overhead camshafts are displacing traditional pushrod air-cooled designs across the mid-displacement range. Entry-level buyers from touring and urban commuter segments are adopting these platforms for reduced valve-adjustment intervals and thermal stability. This displacement is compressing the aftermarket service revenue pool that legacy air-cooled architectures sustained.
EPA emission certification timelines now require onboard diagnostic systems and evaporative emission controls that carbureted platforms cannot accommodate. Manufacturers must retire entire model families or invest in fuel-injection retrofit engineering. Heavy-touring displacement tiers absorb these costs most readily, while sub-500cc entry segments face platform abandonment or supplier consolidation.
Configuration-based purchasing through manufacturer digital platforms is replacing traditional dealer lot inventory selection. Riders in Wisconsin and California now specify paint, seating, and audio packages before production, reducing finished goods carrying costs. This shift is most visible among Custom Cruiser buyers prioritizing aesthetic differentiation over immediate availability.
Cruiser Bikes Market Segmentation
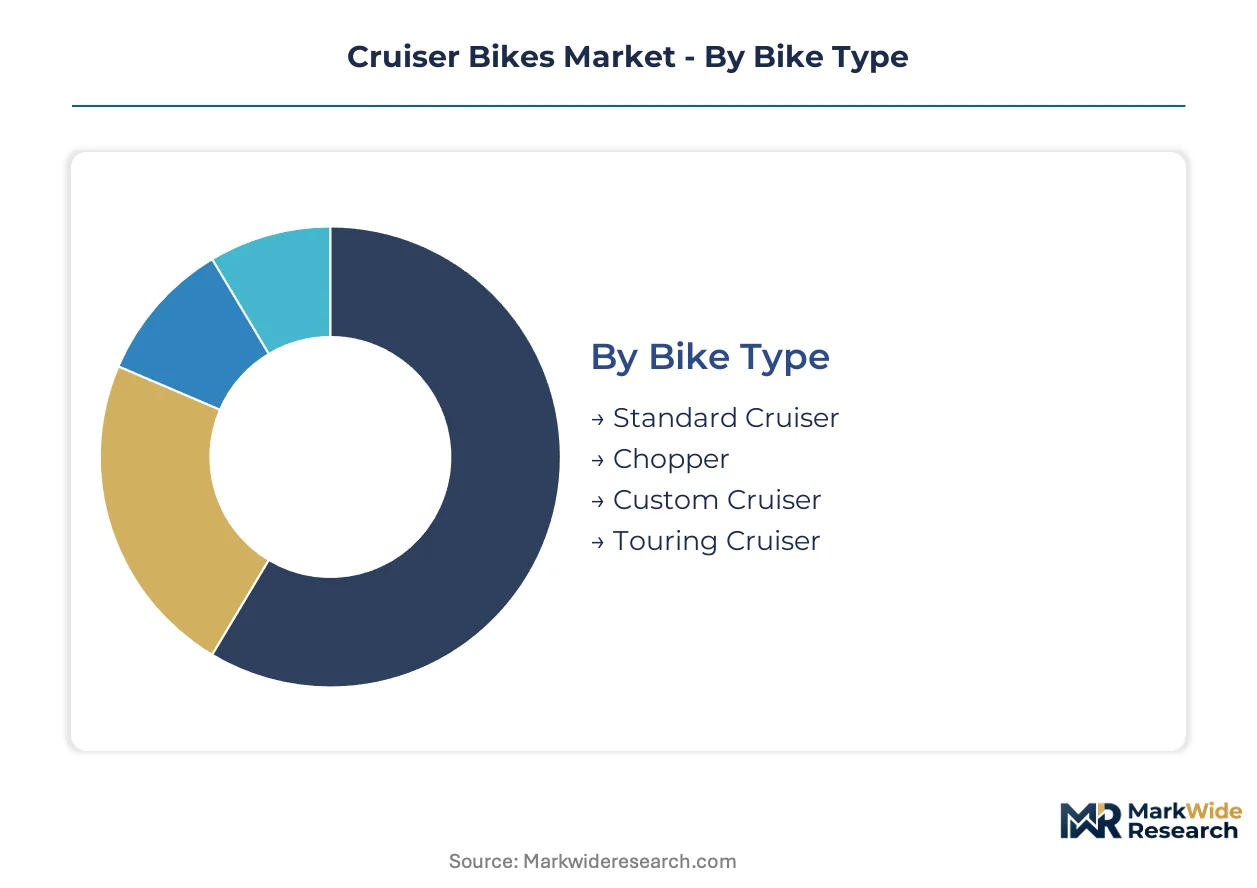
Cruiser bike segmentation reveals how substitution pressures from electric two-wheelers and shifting rider demographics are fragmenting traditional category boundaries. Manufacturers must align platform architecture with specific displacement tiers and frame material economics to defend margin positions.
Bike Type:
Electric powertrain substitution threatens urban-commuter-oriented segments most severely, while long-distance touring variants retain insulation through range and charging infrastructure limitations.
- Standard Cruiser:Entry-displacement V-twin or parallel-twin configurations with steel tube frames and belt final drive dominate unit volume. Wisconsin and California recreational riders anchor demand for accessible seat heights and minimal maintenance intervals.
- Touring Cruiser:Heavy-displacement platforms integrate hard-shell luggage, audio systems, and wind protection for multi-day highway travel. Empty-nest buyers in the United States prioritize these variants for cross-country route completion capability.
- Chopper:Extended fork geometries and stretched wheelbases emphasize aesthetic extremity over practical ergonomics.
- Custom Cruiser:Factory-personalization programs and aftermarket parts bundling command premium pricing through exclusive paint and accessory configurations.
Standard Cruiser anchors the volume base while Touring Cruiser gains share at the steepest rate.
Frame Material:
Cost tier stratification separates mass-market steel construction from premium aluminum and exotic material adoption where weight reduction justifies unit economics.
- Steel:Tubular steel fabrication retains cost leadership in entry and mid-displacement segments. EPA emission compliance investments compress assembler margins when steel input prices fluctuate.
- Aluminum:Cast and extruded aluminum frames reduce unsprung weight for improved handling response. Premium displacement tiers absorb the material substitution premium most readily.
- Carbon Fiber:Limited production runs for ultra-premium custom builds where aesthetic differentiation outweighs cost sensitivity.
- Titanium:Niche applications in exhaust systems and select frame components for weight-critical touring configurations.
Steel construction retains the dominant production share while aluminum adoption climbs fastest among new platform introductions.
Engine Capacity:
Application-based demand concentration separates urban commuter requirements from interstate touring torque demands across the displacement spectrum.
- 501cc-1000cc:Liquid-cooled V-twin architectures with fuel injection and catalytic after-treatment dominate this mid-range. Euro 5 compliance deadlines force platform consolidation here as manufacturers retire carbureted legacy designs.
- 1001cc-1500cc:Heavy-touring displacement tiers integrate shaft final drive and advanced thermal management for sustained highway operation. United States long-distance riders concentrate demand for low-RPM torque delivery and reduced vibration.
- 250cc-500cc:Entry segments face platform abandonment as exhaust after-treatment costs disproportionately burden price-sensitive configurations.
- Above 1500cc:Flagship displacement for heritage-brand flagship models with maximum torque output and premium pricing.
The 501cc-1000cc range carries the highest unit volume while 1001cc-1500cc platforms show the steepest value expansion trajectory.
Design Style:
Customer type differentiation separates heritage-purist preferences from contemporary aesthetic demands in configuration and trim selection.
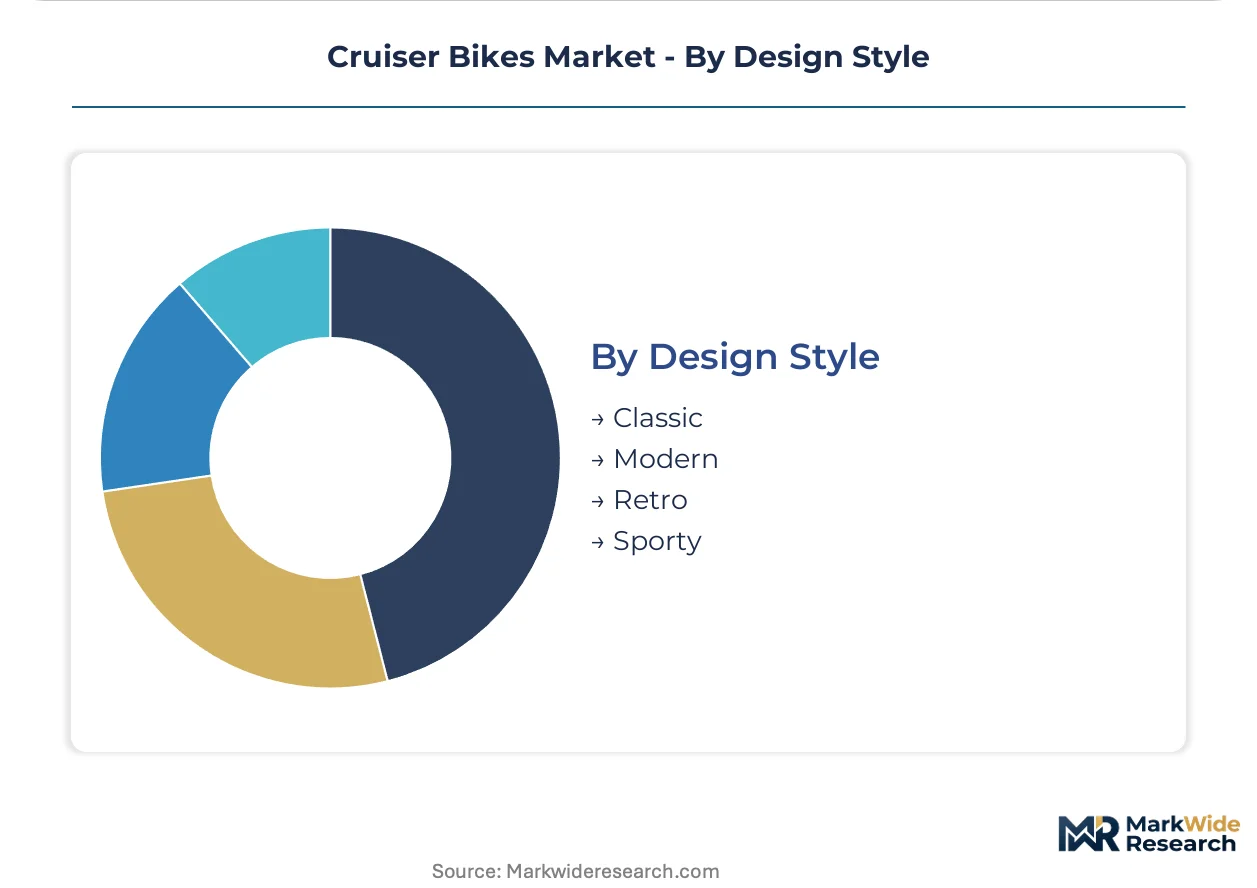
- Classic:Chrome-intensive finishes, spoked wheels, and heritage color palettes target traditional cruiser culture adherents. United States buyers in Wisconsin and California sustain demand for factory-original styling fidelity.
- Modern:LED lighting, blacked-out finishes, and minimal chrome appeal to younger urban commuters. This segment faces the strongest substitution pressure from battery-electric alternatives in metropolitan areas.
- Retro:Period-correct detailing with modern mechanical underpinnings captures nostalgia-driven purchasing.
- Sporty:Aggressive stance, higher foot pegs, and enhanced cornering clearance for riders prioritizing dynamic capability.
Classic styling commands the largest installed base while Modern design configurations expand most quickly among new rider acquisition.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in cruiser motorcycles favor manufacturing-origin markets with established heritage brands, while consumption concentrates in high-disposable-income economies with strong recreational riding cultures. The United States maintains substantial trade surplus in heavy-displacement premium segments, whereas Asia-Pacific markets absorb growing import volumes for mid-range touring configurations.
United States
Wisconsin and California anchor domestic demand through entrenched cruiser culture and empty-nest recreational purchasing. EPA emission certification timelines force manufacturers to retire carbureted platforms ahead of federal compliance deadlines. Milwaukee retains its position as the dominant heritage-brand manufacturing cluster, with vertically integrated production sustaining domestic export capacity.
Germany
Precision-engineered touring configurations from Stuttgart and Munich-based assemblers capture premium displacement demand across European markets. Euro 5 type-approval standards administered by the European Commission accelerate fuel-injection platform consolidation. The Baden-Württemberg industrial corridor concentrates R&D investment for cleaner combustion architectures.
Japan
Domestic absorption of liquid-cooled V-twin platforms from Tokyo and Osaka manufacturers stabilizes amid aging rider demographics. Ministry of Land, Infrastructure, Transport and Tourism type-approval requirements drive harmonization with Pacific Rim certification standards. The Hamamatsu manufacturing basin sustains export-oriented production for Southeast Asian touring markets.
India
Mid-displacement cruiser demand accelerates in Maharashtra and Gujarat as urban commuters seek style differentiation from standard commuters. Central Pollution Control Board emission norms phase in alongside state-level vehicle registration incentives for cleaner engines. The Pune-Chakan industrial belt hosts expanding assembly capacity for domestic consumption and regional export.
Brazil
São Paulo and Rio Grande do Sul sustain import demand for entry-level V-twin configurations despite currency volatility affecting landed costs. ANVISA alignment with international emission benchmarks proceeds alongside PROCONVE regulatory updates for motorcycle categories. The Manaus free trade zone attracts regional assembly investment for Andean market distribution.
Cruiser Bikes Market Key Industry Players
Concentration sits with heritage-brand manufacturers commanding premium pricing through vertically integrated domestic production and dealer network density. The vendor base stratifies across three tiers: integrated heritage builders with century-old brand equity, mid-scale specialists leveraging liquid-cooled architectures for maintenance-cost advantage, and emerging electric entrants threatening urban-commuter positioning. Dominant competitive moves include portfolio diversification into electric powertrains and strategic partnerships for battery technology access.
Among heritage-brand manufacturers, Harley-Davidson exemplifies the integrated premium archetype through its Milwaukee-based production footprint. Indian Motorcycle occupies a parallel position within the same tier, leveraging comparable heritage positioning. Yamaha represents the technology-forward specialist archetype, competing through liquid-cooled platform architectures that reduce total cost of ownership for entry-displacement buyers.
| Leading Market Players |
|---|
| Triumph |
| Kawasaki |
| Harley-Davidson |
| Yamaha |
| Honda |
| Ducati |
| BMW Motorrad |
| Buell |
| Indian Motorcycle |
| Others |
Cost & Logistics Intelligence
Long-term offtake agreements between Milwaukee-based heritage manufacturers and domestic steel suppliers lock in frame material access while insulating production costs from spot market volatility. These arrangements extend platform lifecycle planning visibility across EPA compliance windows, though California Air Resources Board divergence introduces fragmented certification cost exposure for multi-state portfolios.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels. Brand heritage and dealer network density command premium positioning for heavy-touring displacement tiers, while liquid-cooled V-twin architectures from Japanese specialists undercut on total cost of ownership. Pricing pressure stems from exhaust after-treatment cost absorption on entry-displacement models, compressing assembler margins where steel input volatility intersects with Euro 5 compliance investments. Empty-nest recreational riders in Wisconsin and California show lowest price sensitivity, while urban commuters face strongest substitution pressure from battery-electric alternatives.
Supply Chain Analysis
Container availability fluctuations on Pacific trade lanes strain inbound logistics for Japanese and Indian component suppliers serving North American assembly. Steel tube fabrication concentrates in China, India, and domestic Midwestern foundries, while aluminum casting and precision machining draw from Japanese and German specialist tiers. Single-source vulnerability sits with catalytic converter substrate suppliers facing rare earth element constraints. Distribution runs through manufacturer-captive dealer networks with configuration-to-order digital channels gaining share in Custom Cruiser segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics inflection centers on direct-to-rider digital configuration tools that bypass traditional dealer density constraints while capturing aftermarket parts bundling revenue. Interoperability between manufacturer-owned subscription maintenance packages and independent service networks will determine ecosystem lock-in effectiveness.
For Market Incumbents: Shield heavy-touring margin positions by accelerating backward integration into exhaust after-treatment component manufacturing, reducing catalytic converter supply vulnerability. Consolidate dealer network coverage in Wisconsin and California recreational corridors while retiring carbureted legacy platforms ahead of EPA compliance deadlines to free engineering capacity for liquid-cooled architecture development. For New Entrants and Emerging Players: Anchor in the 501cc-1000cc mid-displacement white space where heritage-brand compliance costs create pricing headroom. Target urban commuter segments in Indian and Brazilian metropolitan markets with liquid-cooled parallel-twin platforms emphasizing maintenance-cost advantage. Deploy direct-channel configuration tools with subscription maintenance bundling to circumvent incumbent dealer density moats. For Investors and Strategic Acquirers: Heritage-brand manufacturing assets with vertically integrated domestic footprints and established EPA certification pathways represent the most defensible acquisition archetype. Long-term viability hinges on electric powertrain transition readiness and Pacific Rim type-approval harmonization progress. Monitor Japan Ministry of Land, Infrastructure, Transport and Tourism alignment with EPA thresholds as inflection signal for unified platform certification economics.| Strategic Initiative | Industry Significance |
|---|---|
| Liquid-Cooled Platform Migration | Dual overhead camshaft architectures reduce valve-adjustment intervals for touring riders in Wisconsin and California. |
| Exhaust After-Treatment Integration | Catalytic converter packaging within heritage frame geometries demands retooling investment for Euro 5 compliance. |
| Direct-to-Rider Digital Channel | Manufacturer-owned configuration tools bypass dealer density constraints in Custom Cruiser personalization. |
| Shaft Final Drive Adoption | Maintenance-reducing drivetrains capture empty-nest buyers prioritizing total cost of ownership. |
| Pacific Rim Certification Harmonization | Japan type-approval alignment opens unified platform pathways for Southeast Asian touring markets. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with motorcycle product planning directors, dealer network operations managers, aftermarket parts distributors, and EPA certification engineering leads. Secondary validation drew from EPA emission certification filings, Euro 5 type-approval documentation, Japan Ministry of Land, Infrastructure, Transport and Tourism regulatory updates, and steel commodity trade flow data. Bottom-up platform shipment analysis triangulated against top-down recreational vehicle spending surveys to anchor volume estimates.
Across the analysis window, the forecasting framework modeled displacement tier segmentation, frame material economics, engine architecture evolution, and regional regulatory cluster divergence to derive value expansion trajectories. CAGRs were computed from annualized platform shipment projections cross-referenced with average selling price movements by configuration tier. Industry-specific inputs included EPA compliance timeline acceleration scenarios and electric powertrain substitution elasticity in urban commuter segments.
Decision-makers should treat outputs as directional under stable emission regulatory trajectory assumptions; material deviation would warrant model refresh. Specific risks include California Air Resources Board threshold divergence from federal EPA baselines, rare earth element supply disruption for catalytic converter substrates, and faster-than-anticipated battery-electric two-wheeler penetration in metropolitan areas. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
Sweden E-Bike Market
Bikes and Motorcycles
United Arab Emirates E-Bike Market
Bikes and Motorcycles
UAE Electric Bike Market
Bikes and Motorcycles
Ride on Bikes Market
Bikes and Motorcycles
Motorcycle Shock Absorbers Market
Bikes and Motorcycles
E-Mountain Bike Market
Bikes and Motorcycles
Two-Wheeler Motorcycle Market
Bikes and Motorcycles
Child Bike Seats Market
Bikes and Motorcycles
Bicycle Brake Lever Market
Bikes and Motorcycles
Connected Motorcycle Market
Bikes and Motorcycles
Global Two Wheeler Accessories Market
Bikes and Motorcycles
Two Wheeler Kick Lever Market
Bikes and Motorcycles
Global Hybrid Bicycles Market
Bikes and Motorcycles
Denmark E-Bike Market
Bikes and Motorcycles
Global Motorcycle Supercharger Market
Bikes and Motorcycles
Motorcycle Rider Assistance System Market