
 Connected Drug Delivery Devices Market | 2026-2036
Connected Drug Delivery Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Connected Drug Delivery Devices Market Analysis
The connected drug delivery landscape is pivoting around a sharp divergence between premium integrated platforms and commodity hardware. Medtronic leverages its pump ecosystem to sustain high-margin recurring revenue streams. Insulet Corporation differentiates through tubeless wearable designs that anchor its position in insulin delivery. Ypsomed specializes in pen-based connectivity while competing on manufacturing scale across European markets.
Connected drug delivery devices integrate sensors, wireless modules, and software to track dosing events, adherence patterns, and device performance in real time, typically operating through Bluetooth Low Energy or cellular protocols with battery lifespans spanning weeks to months. These systems serve pharmaceutical companies, healthcare providers, and patients by closing the loop between prescription and consumption data. Wearable injectors lead in revenue contribution due to biologics volume and chronic therapy duration, while smart inhalers represent the fastest-expanding category as respiratory digital therapeutics gain payer acceptance. Bluetooth dominates technology adoption for its low power profile, though cellular connectivity is gaining traction in regions with mature telehealth infrastructure.
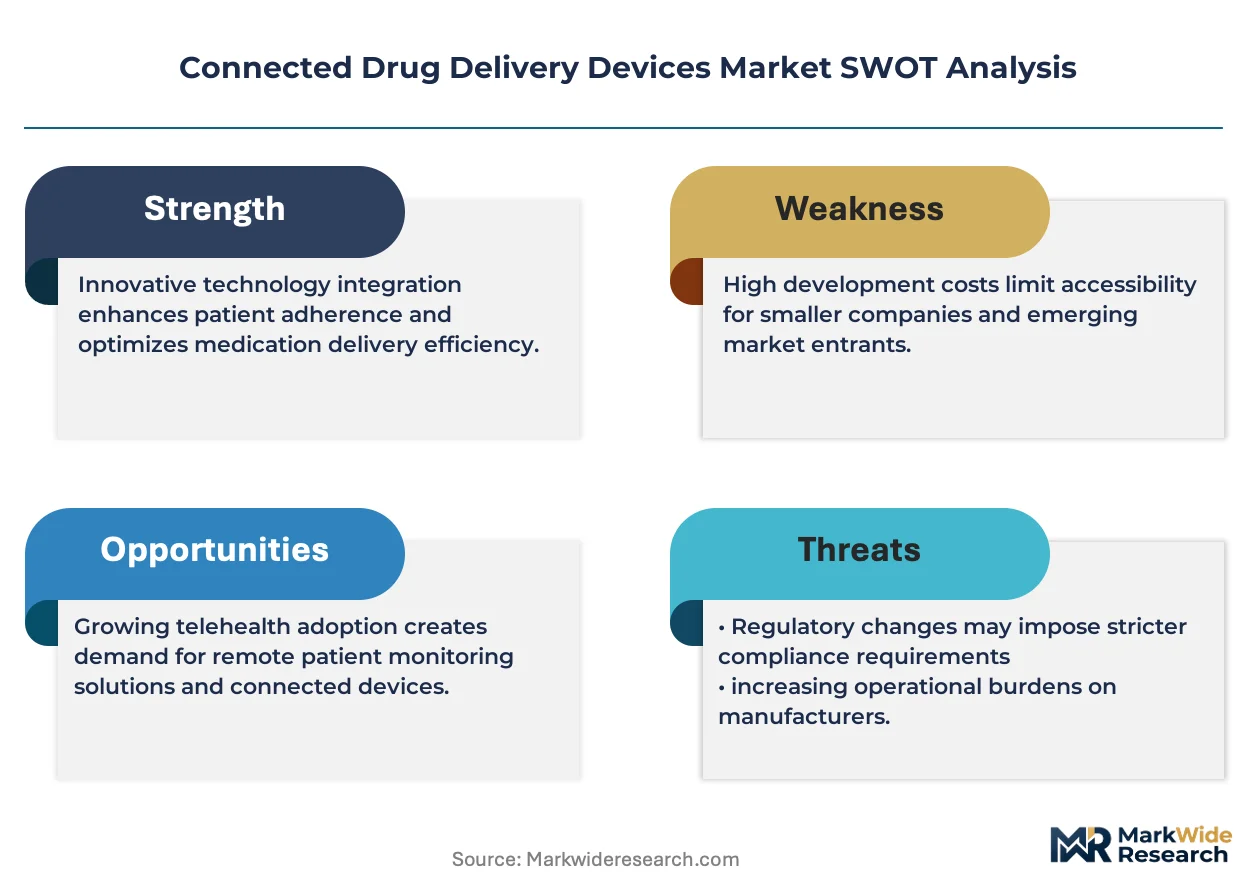
FDA digital health pre-certification, EU MDR cybersecurity annexes, and HIPAA data governance requirements collectively elevate compliance costs while creating barriers for non-validated entrants. The FDA's evolving software-as-medical-device framework pushes manufacturers toward continuous validation cycles rather than discrete product approvals. Stakeholders must weigh platform interoperability investments against the risk of stranded device fleets as regulatory technical standards continue tightening across major markets.
Market Dynamics
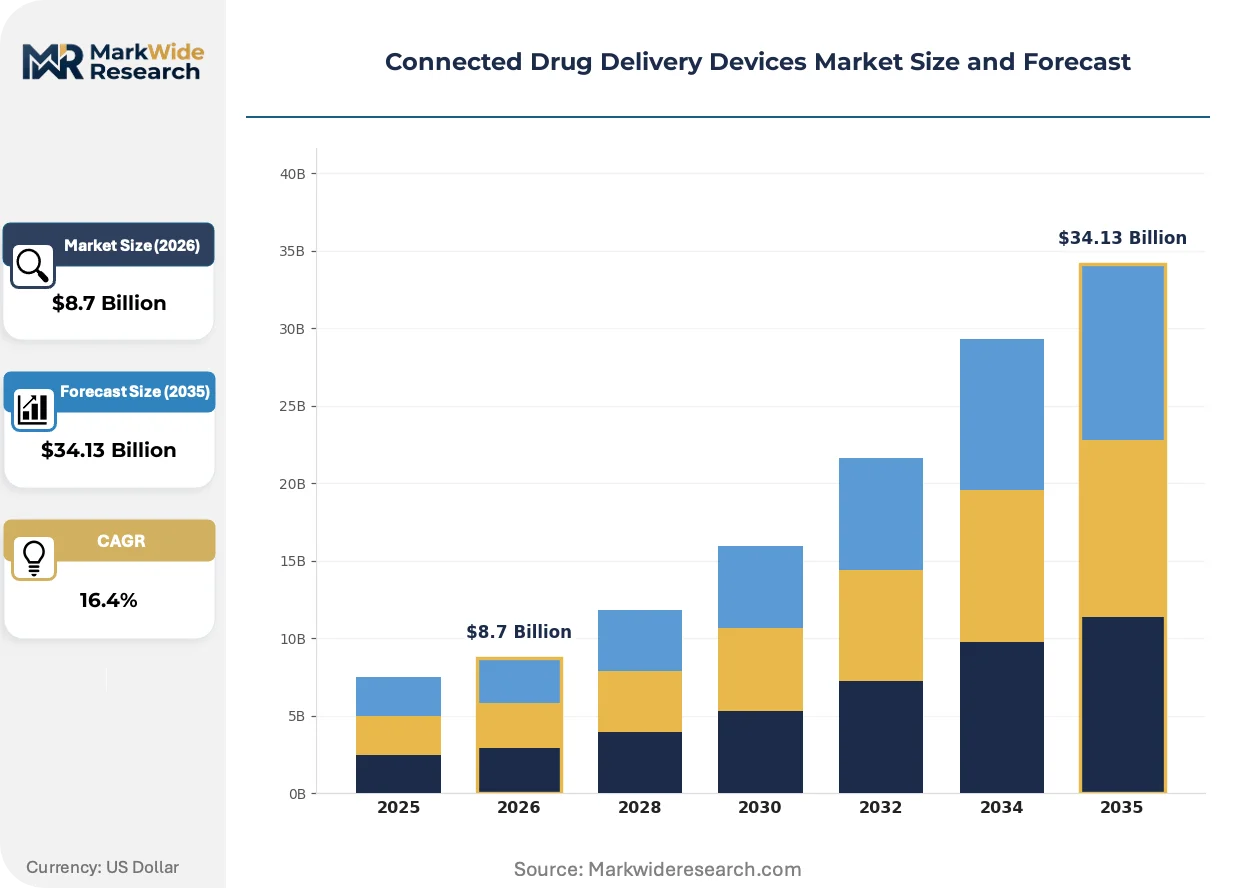
The connected drug delivery market pivots on a fundamental tension between pharmaceutical manufacturers demanding real-world evidence generation and healthcare systems struggling to reimburse data infrastructure costs. FDA software-as-medical-device frameworks and EU MDR cybersecurity annexes now mandate continuous validation cycles rather than discrete approvals, forcing device makers to choose between platform consolidation and fragmented compliance investments.
Growth Catalysts
- Biologics Volume Surge:Chronic therapy expansion in oncology and immunology is pulling wearable injector demand. Home care agencies now specify Bluetooth-enabled adherence tracking as a procurement requirement for high-value biologic therapies.
- EU MDR Cybersecurity Mandates:The regulation's Annex I technical documentation requirements for connected devices are accelerating replacement of legacy pen injectors with validated smart alternatives across German and French hospital networks.
- Remote Patient Monitoring Reimbursement:United States CMS codes for digital therapeutic integration now cover connected inhaler data transmission, creating direct revenue pathways for respiratory device manufacturers.
Market Restraints
- Cellular Module Supply Concentration:Narrow supplier bases for low-power wide-area network chipsets in Taiwan and South Korea create input volatility for manufacturers targeting rural telehealth deployments.
- FDA Pre-Certification Cost Burden:The pilot program's continuous validation requirements demand dedicated software quality systems that mid-tier device makers cannot resource without partnership structures.
- Disposable Component Economics:Single-use sensor assemblies and proprietary cartridge interfaces lock pharmaceutical partners into long-term supply agreements with limited second-source alternatives.
Strategic Opportunities
- Japanese Elderly Care Infrastructure:METI's Society 5.0 initiative funds connected device pilots in rural prefectures where physician density cannot support traditional injection training programs.
- Digital Therapeutic Convergence:Integration of connected inhalers with prescription digital therapeutics for asthma management creates bundled reimbursement pathways previously unavailable to hardware-only vendors.
- Pharmacy Channel Direct Distribution:CVS Health and Walgreens Boots Alliance are building direct-to-patient logistics for connected device onboarding, bypassing traditional durable medical equipment intermediaries.
Industry Challenges
- Embedded Firmware Talent Scarcity:Medical device manufacturers compete with consumer electronics and automotive sectors for engineers skilled in IEC 62304-compliant software lifecycle management.
- Legacy EHR Integration Complexity:Hospital IT departments resist API connections to cloud-based device platforms without on-premise data routing, fragmenting deployment architectures.
- Patent Thicket Navigation:Dense intellectual property holdings around pen-based connectivity mechanics and dose-detection algorithms complicate freedom-to-operate analyses for new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Connected Drug Delivery Devices Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Smart Inhalers, Wearable Injectors, Smart Pens, Connected Pumps End User: Patients, Healthcare Providers, Pharmacies, Home Care Agencies Technology: Bluetooth, RFID, NFC, Cellular Form Factor: Handheld, Implantable, Wearable, Modular |
| Companies Covered | Medtronic, Insulet Corporation, Becton Dickinson, Ypsomed, Aptar Pharma, West Pharmaceutical Services, Adherium Limited, Propeller Health, Phillips-Medisize, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Connected Drug Delivery Devices Market Emerging Trajectories
Sensor miniaturization and edge computing capabilities are collapsing the cost floor for connected functionality, enabling connectivity as a standard feature rather than premium tier. This shift is compressing hardware margins while expanding addressable markets for data services.
Ultra-low-power accelerometers combined with machine learning inference at the device level are rewriting adherence detection accuracy. Pharmaceutical sponsors now specify sub-5% false-positive rates for dosing event recognition in Phase IV trial protocols. Contract research organizations are building device-agnostic data lakes to aggregate signals across multiple connected platforms, compressing trial timelines by eliminating manual diary entries.
EU MDR Annex I Chapter III cybersecurity requirements are forcing manufacturers to implement secure boot architectures and signed firmware updates across entire device fleets. German notified bodies are rejecting submissions lacking SBOM documentation and vulnerability disclosure policies. Companies with legacy Bluetooth Classic implementations face stranded inventory risks as European hospital procurement committees mandate BLE 5.0 or higher for new installations.
Pharmaceutical procurement teams are unbundling device hardware from data analytics subscriptions, treating connectivity infrastructure as a commodity while negotiating separately for adherence algorithm licenses and regulatory-grade evidence packages. This bifurcation is most visible in United States diabetes care, where payers now reimburse connected pen data transmission under remote monitoring codes while excluding manufacturer-branded coaching services from formulary coverage.
Connected Drug Delivery Devices Market Segmentation
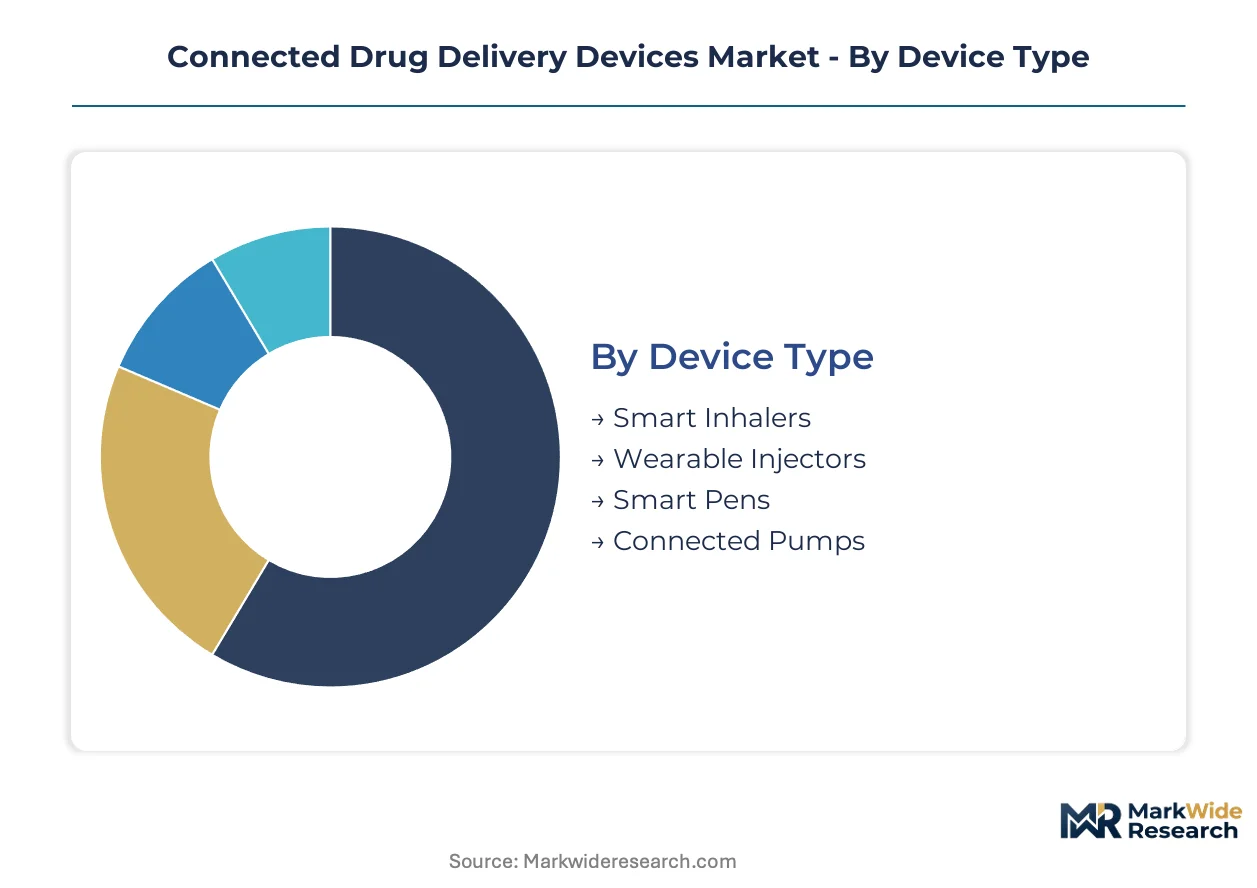
Segmentation in connected drug delivery reveals divergent commercial models across hardware integration depth and data monetization pathways. Device type and technology choices determine whether manufacturers capture one-time sales or recurring platform revenue.
Device Type:
Wearable injectors and connected pumps embed sensors directly into therapeutic delivery mechanisms, while smart inhalers and pens retrofit connectivity onto existing form factors.
- Wearable Injectors:These systems integrate subcutaneous delivery mechanisms with continuous biometric monitoring for biologic therapies. Demand clusters in United States oncology home care networks where CMS reimbursement covers remote therapeutic monitoring for infused therapies.
- Connected Pumps:Closed-loop insulin delivery systems with predictive glucose algorithms anchor diabetes management platforms. German hospital procurement committees now mandate EU MDR Annex I cybersecurity documentation for new pump installations, accelerating replacement cycles.
- Smart Inhalers:Respiratory devices with dose-counters and geolocation tracking for asthma and COPD management.
- Smart Pens:Bluetooth-enabled insulin and GLP-1 injection trackers capturing dose timing and quantity data.
Volume placements concentrate in connected pumps; the faster expansion belongs to wearable injectors.
End User:
Revenue capture varies sharply across customer types, with institutional procurement favoring validated enterprise platforms while direct-to-patient channels prioritize usability and onboarding speed.
- Healthcare Providers:Hospital systems and specialty clinics demand EHR-integrated devices with HL7 FHIR-compliant data export. United States health systems now specify SOC 2 Type II certification for cloud-connected device vendors, filtering out smaller hardware-only suppliers.
- Home Care Agencies:Medicare-certified agencies drive bulk purchasing for chronic therapy populations. Japanese METI-funded Society 5.0 pilots in rural prefectures prioritize agency-managed device distribution where physician density cannot support direct patient training.
- Patients:Direct consumers purchasing through pharmacy or retail channels for self-managed conditions.
- Pharmacies:CVS Health and Walgreens Boots Alliance building logistics infrastructure for device onboarding and adherence coaching.
Procurement volumes cluster with healthcare providers; home care agencies are climbing the fastest as reimbursement frameworks mature.
Technology:
Connectivity protocol selection trades power consumption against data throughput and infrastructure dependency, with implications for device form factor and geographic deployability.
- Bluetooth:BLE 5.0 dominates ambulatory devices for its sub-milliwatt standby power and smartphone gateway compatibility. EU MDR notified bodies in Germany now reject submissions lacking BLE 5.0 or higher, stranding legacy Bluetooth Classic inventory.
- Cellular:Low-power wide-area network modules enable standalone operation without smartphone pairing. Taiwan and South Korea chipset supply concentration creates input volatility for manufacturers targeting rural United States telehealth deployments.
- RFID:Passive identification for hospital inventory management and dose verification workflows.
- NFC:Near-field protocols for pharmacy authentication and patient onboarding tap-to-pair functionality.
Bluetooth anchors current volume; cellular protocols are gaining share fastest where smartphone penetration lags.
Form Factor:
Physical integration depth determines regulatory pathway complexity and patient adherence mechanics, with implications for manufacturing scale and service attach rates.
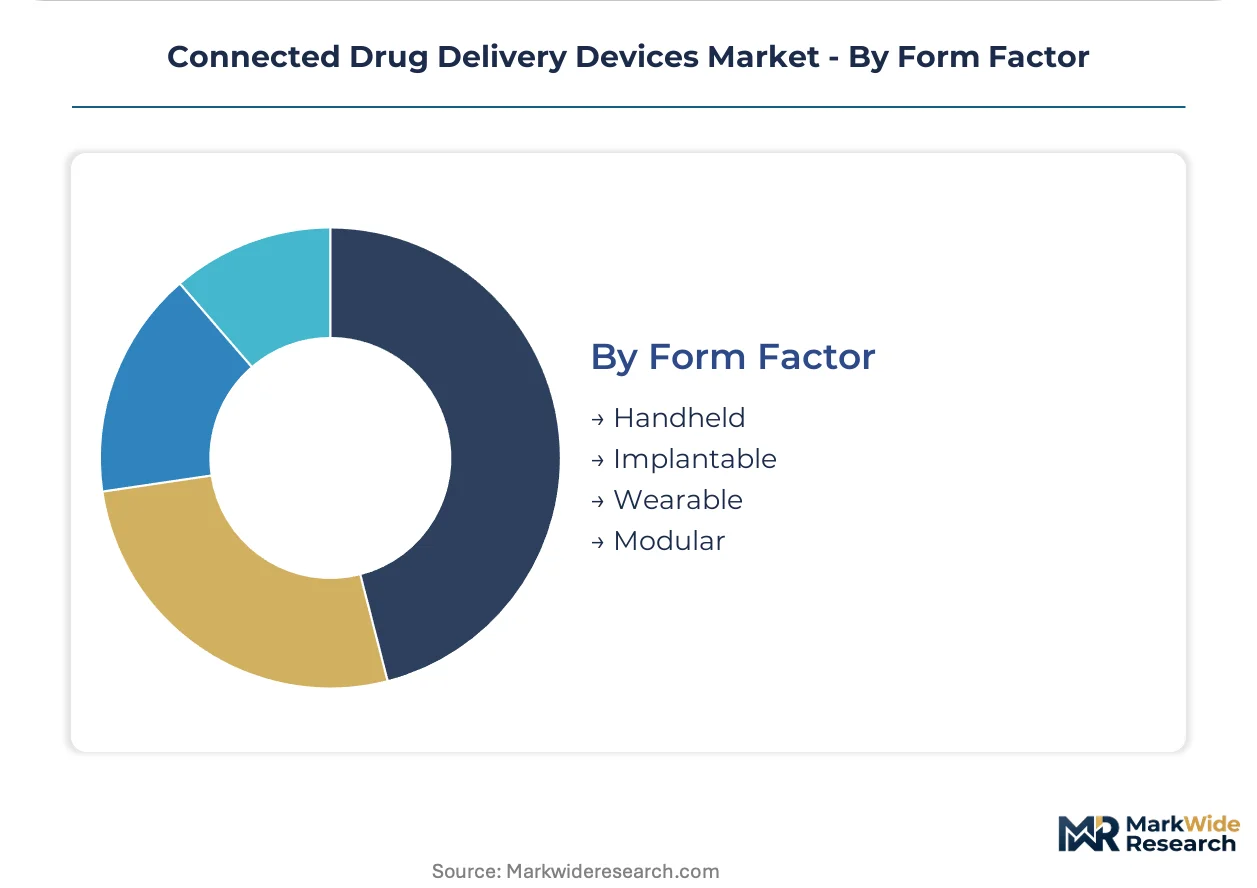
- Wearable:Adhesive patch pumps and continuous infusion systems designed for multi-day body-worn operation. Oncology biologics expansion in United States and Japan pulls demand for tubeless designs that eliminate tubing snagging risks during daily activity.
- Handheld:Inhalers and pen injectors retained in patient control for discrete dosing events. German and French hospital networks replacing legacy pen injectors with validated smart alternatives under EU MDR cybersecurity mandates.
- Implantable:Long-acting drug reservoirs with wireless refill monitoring and dose telemetry.
- Modular:Cartridge-based systems allowing connectivity module reuse across multiple disposable drug containers.
Wearable devices command the steepest expansion trajectory; handheld units retain the volume base through respiratory and diabetes prevalence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Minneapolis anchors North American connected pump development, while Basel and Tokyo corridor facilities drive European and Asian regulatory submissions for wireless-enabled drug delivery systems.
United States
CMS reimbursement codes for remote therapeutic monitoring now cover connected inhaler data transmission, pulling device adoption through Medicare Advantage networks. FDA software-as-medical-device pre-certification demands continuous validation cycles that filter mid-tier hardware vendors from hospital procurement lists. The Route 128 corridor outside Boston clusters digital health infrastructure where contract research organizations aggregate device-agnostic adherence data lakes.
Germany
EU MDR Annex I Chapter III cybersecurity mandates are accelerating replacement of legacy pen injectors across Bavarian and North Rhine-Westphalian hospital networks. German notified bodies now reject submissions lacking software bill of materials documentation and signed firmware update architectures. The Mannheim-Heidelberg medical technology corridor hosts validation laboratories where BLE 5.0 compliance testing occurs for pan-European device certifications.
Japan
METI's Society 5.0 initiative funds connected device pilots in rural prefectures where physician density cannot support traditional injection training programs. PMDA streamlined review pathways for software-enabled devices are compressing time-to-market for manufacturers with prior FDA approvals. The Kobe biomedical innovation cluster concentrates adherence algorithm development for elderly diabetes populations.
United Kingdom
NHS England's digital-first chronic disease management frameworks specify Bluetooth-enabled adherence tracking for biologic therapies in community care settings. MHRA post-Brexit recognition agreements with FDA and PMDA are simplifying multi-market registration strategies for London-headquartered device developers. The Oxford-Cambridge arc hosts pharmaceutical partnerships where real-world evidence generation contracts bundle hardware with data analytics subscriptions.
Switzerland
Swissmedic's alignment with EU MDR technical documentation requirements is positioning Basel-region manufacturers as regulatory bridges into European hospital procurement channels. The country's precision manufacturing base supplies sensor miniaturization components for wearable injector platforms targeting oncology home care. Geneva-based health data governance consultancies are structuring HIPAA-Swiss Data Protection Act compliant cloud architectures for cross-border device deployments.
Connected Drug Delivery Devices Market Vendor Landscape
Premium-margin players sit above commodity-margin players across regulatory validation depth and platform ecosystem integration. The vendor base stratifies between integrated pump manufacturers with recurring software revenue and hardware specialists competing on manufacturing scale. Three archetypes dominate: diversified medical technology conglomerates with closed-loop diabetes platforms; contract manufacturing organizations offering connectivity-as-a-service to pharmaceutical sponsors; and digital health pure-plays monetizing adherence algorithms separately from device sales. Consolidation is concentrating around pump ecosystem acquisitions and strategic partnerships between inhaler manufacturers and prescription digital therapeutic developers.
Within the diversified medical technology tier, Medtronic and Insulet Corporation exemplify platform-centric positioning where device hardware anchors recurring data service revenue. Ypsomed occupies a manufacturing-scale specialist position across European pen-based connectivity markets. These three entities represent divergent strategic bets on whether pharmaceutical partners will continue bundling devices with drug supply or unbundle connectivity infrastructure as a commodity procurement category.
| Leading Market Players |
|---|
| Medtronic |
| Insulet Corporation |
| Becton Dickinson |
| Ypsomed |
| Aptar Pharma |
| West Pharmaceutical Services |
| Adherium Limited |
| Propeller Health |
| Phillips-Medisize |
| Others |
Supply Flow & Price Mechanics
EU MDR Annex I Chapter III cybersecurity mandates now gate qualified supply access for connected drug delivery manufacturers, with SBOM documentation and signed firmware architectures separating premium-tier vendors from commodity hardware suppliers locked out of German hospital procurement channels.
Pricing Analysis
Value-based pricing anchored to adherence outcome metrics now dominates pharmaceutical procurement negotiations, with device hardware unbundled from data analytics subscriptions. Pricing stratifies across FDA pre-certified platforms, CE-marked validated systems, and uncertified commodity alternatives. Cost compression in the mid-tier intensifies because pharmaceutical sponsors now treat connectivity infrastructure as interchangeable procurement categories. Home care agencies exhibit highest price sensitivity due to Medicare reimbursement caps, while integrated pump manufacturers face lowest sensitivity through recurring software revenue lock-in.
Supply Chain Analysis
Low-power wide-area network chipset supply rests on Taiwanese and South Korean specialty semiconductor producers, with Nordic Semiconductor and Quectel modules feeding wearable injector assembly lines. Sensor miniaturization components draw from Swiss precision manufacturing clusters, while disposable cartridge assemblies source from German and French medical plastics molders. Single-source vulnerability concentrates in BLE 5.0 system-on-chip supply where foundry capacity allocation prioritizes consumer electronics. Distribution runs through pharmaceutical company direct procurement channels, bypassing traditional durable medical equipment intermediaries as CVS Health and Walgreens Boots Alliance build captive logistics infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market has become a vertical-integration race where control over adherence algorithm development and regulatory-grade evidence generation determines margin capture, with pharmaceutical partners increasingly unbundling hardware from data services.
For Market Incumbents: Lock in pharmaceutical sponsor relationships through exclusive real-world evidence generation contracts that embed devices into Phase IV trial protocols. Secure FDA pre-certification status to filter mid-tier competitors from hospital procurement lists, while acquiring embedded firmware engineering capabilities to address talent scarcity competing with automotive and consumer electronics sectors. For New Entrants and Emerging Players: Rural Japanese prefectures under METI's Society 5.0 initiative represent an underserved buyer archetype where physician density gaps create demand for agency-managed connected device distribution. Target pharmacy channel direct onboarding partnerships with CVS Health or Walgreens Boots Alliance to bypass traditional DME intermediaries, leveraging cellular-enabled standalone devices where smartphone penetration lags. For Investors and Strategic Acquirers: FDA software-as-medical-device pre-certification pilot expansion is the leading indicator that regulatory-grade validation capabilities will concentrate market power among continuous-validation-compliant vendors. Position for five-to-ten year viability around contract manufacturing organizations offering connectivity-as-a-service, with embedded firmware engineering talent acquisition serving as the primary inflection signal for platform scalability.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Pre-Certification Pathway | Continuous validation compliance filters mid-tier hardware vendors from United States hospital procurement lists. |
| EU MDR Annex I Cybersecurity Documentation | SBOM and signed firmware requirements accelerate replacement cycles across German hospital networks. |
| Pharmaceutical Real-World Evidence Partnership | Phase IV trial protocol embedding creates recurring revenue through adherence data licensing. |
| Pharmacy Channel Direct Distribution | CVS Health and Walgreens captive logistics bypass traditional durable medical equipment intermediaries. |
| Cellular Module Supply Agreement | Taiwanese and South Korean chipset sourcing secures rural telehealth deployment capability. |
Methodological Framework
FDA 510(k) filings, EU MDR notified body submission databases, and CMS reimbursement code announcements formed the secondary backbone, cross-referenced with primary interviews involving connected device product managers, hospital biomedical engineers, pharmaceutical clinical operations executives, and GPO contracts managers. Bottom-up unit economics modeling triangulated against top-down pharmaceutical procurement spend analysis validated market sizing across the projection horizon.
Historical trendline analysis of Bluetooth and cellular protocol adoption rates informed technology penetration assumptions, with segmentation modeling across device type, connectivity protocol, end-user procurement channel, and regional regulatory cluster. CAGR derivation incorporated pharmaceutical biologics pipeline expansion, EU MDR enforcement timelines, and remote patient monitoring reimbursement pathway maturation as industry-specific forecast inputs throughout the modeling period.
Revisions become necessary when FDA software-as-medical-device framework modifications, EU MDR notified body interpretation shifts, or cellular chipset supply disruptions materialize beyond baseline assumptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Contact Lenses Market
Medical Devices
Allografts Market
Medical Devices
Global Image Guided Surgery Devices Market
Medical Devices
Hearing Aid Dehumidifier Market
Medical Devices
Table-Top Autorefractor Market
Medical Devices
Metered Dose Squeeze Dispenser Market
Medical Devices
Atrial Appendage Occluder Market
Medical Devices
Cast Removal Devices Market
Medical Devices
Cervical Retractors Market
Medical Devices
Genitourinary Prosthetics Market
Medical Devices
Asia-Pacific Ambulatory Infusion Pumps Market
Medical Devices
Global Electrotherapy Devices Market
Medical Devices
Endoluminal Device Systems Market
Medical Devices
Oxygen Conserving Devices Market
Medical Devices
Meniscal Rasps Market
Medical Devices
Global Digital Dentistry Devices Market