
 Subcutaneous Injection Ports Market | 2026-2036
Subcutaneous Injection Ports Market Size, Share, and Industry Trends Forecast 2026-2036
Subcutaneous Injection Ports Market Analytics
Buyer concentration across hospital procurement networks is rebalancing toward home care and specialty clinic channels. Medtronic MiniMed leverages its insulin delivery ecosystem to anchor recurring port demand. Becton Dickinson and Company sustains institutional contracts through integrated vascular access portfolios. Smiths Medical differentiates via regional distribution density in European ambulatory markets.
Subcutaneous injection ports are implantable or percutaneous access devices constructed from biocompatible silicone or polyurethane, designed to deliver medication into subcutaneous tissue through a septum that accommodates hundreds of needle punctures without leakage. The device eliminates repeated venipuncture for patients requiring chronic infusion therapy such as chemotherapy or insulin administration. Safety ports command premium positioning due to needlestick prevention engineering and liability risk reduction. Home care end users represent the fastest-expanding channel as reimbursement shifts favor outpatient administration. Dual ports capture margin pools by enabling concurrent delivery of incompatible therapies without separate access sites.
FDA 510(k) clearance requirements and ISO 10993 biocompatibility standards govern material selection and sterilization validation for all commercially distributed ports. The European Medical Device Regulation (MDR) imposes enhanced clinical evidence obligations that extend market access timelines for non-EU manufacturers. Japan's PMDA maintains distinct pharmaceutical affairs consultation pathways for combination products incorporating drug-eluting port designs. Stakeholders must monitor evolving reimbursement codes for home infusion services and anticipate how updated FDA guidance on reusable device reprocessing may reshape product design specifications and competitive positioning.
Market Dynamics
Hospital discharge acceleration is compressing patient dwell times and forcing device manufacturers to engineer ambulatory-ready port systems that tolerate home environment sterilization protocols without clinical supervision.
Growth Catalysts
- Home Infusion Reimbursement Expansion:Medicare's updated home health prospective payment system in the United States now covers subcutaneous port maintenance and supply costs, removing financial barriers to outpatient therapy adoption.
- ISO 10993-5 Cytotoxicity Standards:Harmonized biocompatibility testing protocols accelerate regulatory clearance reciprocity between FDA 510(k) and Japan PMDA pathways, compressing multi-market launch timelines.
- Silicone Elastomer Advances:High-tear-strength platinum-cured formulations extend septum puncture tolerance beyond 2000 accesses, reducing replacement frequency and total cost of ownership for chemotherapy patients.
Market Restraints
- Medical-Grade Silicone Supply Concentration:Specialty silicone feedstock production clusters in Germany and the United States, exposing manufacturers to single-source risk and price volatility during pharmaceutical-grade polymer allocation shortages.
- EU MDR Clinical Evidence Burden:Enhanced post-market surveillance and notified body recertification requirements extend market access timelines by 18-24 months for non-EU manufacturers lacking European clinical trial infrastructure.
- Peripheral Intravenous Catheter Substitution:Short-term PIVC devices capture acute-care medication delivery where dwell time falls below 72 hours, limiting port addressable market to chronic therapy indications.
Strategic Opportunities
- Pediatric Hemophilia Home Care:Underpenetrated patient populations in India and Brazil present white space for low-profile port designs scaled to pediatric anatomy and family-administered factor replacement therapy.
- Drug-Device Combination Pathways:FDA's emerging guidance on integrated delivery systems creates regulatory tailwind for ports pre-loaded with biologic formulations, capturing margin pools from pharmaceutical partners.
- Remote Patient Monitoring Convergence:Bluetooth-enabled port cap sensors that track access frequency and dwell time are absorbing venture capital, enabling subscription revenue models beyond device sale economics.
Industry Challenges
- Biomedical Engineer Talent Scarcity:Specialized expertise in implantable polymer fatigue modeling and sterilization validation remains concentrated at top-tier universities in Massachusetts and Switzerland, constraining R&D scaling.
- Gamma Sterilization Facility Bottlenecks:Contract sterilization providers face cobalt-60 source replenishment delays, extending finished goods release timelines and compressing working capital efficiency.
- Legacy Hospital IT Integration:Home care ports must interface with diverse electronic health record systems, requiring costly middleware development for seamless infusion documentation and adverse event reporting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Subcutaneous Injection Ports Market |
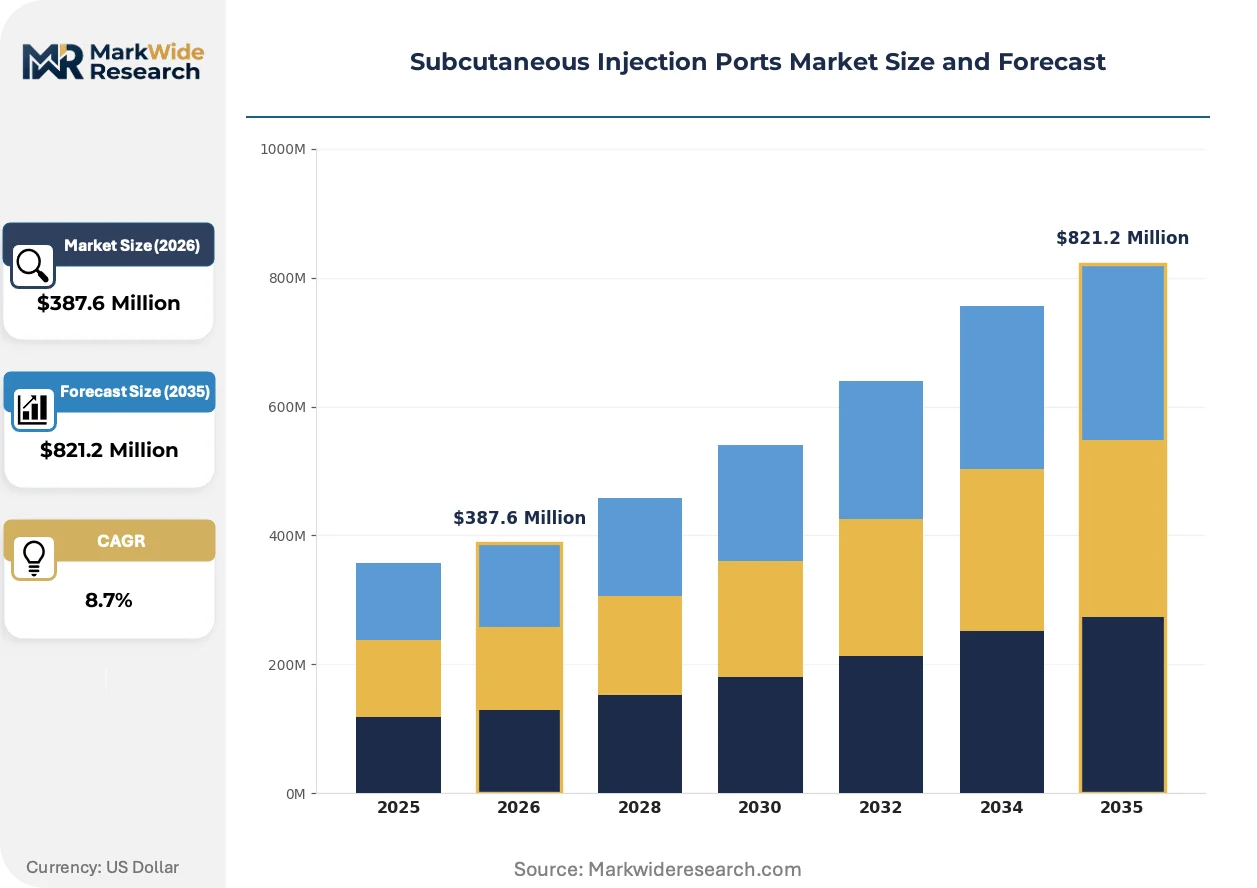
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Ports, Adjustable Ports, Safety Ports, Dual Ports End User: Hospitals, Home Care, Specialty Clinics, Long-Term Care Facilities Application: Chemotherapy, Insulin Delivery, Pain Management, Antibiotic Therapy Material: Polyethylene, Polyurethane, Silicone, Metal |
| Companies Covered | Medtronic MiniMed, Unomedical, Applied Medical Technology, Medtronic, Becton Dickinson and Company, Novo Nordisk, Patheon, Smiths Medical, ICU Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Subcutaneous Injection Ports Market Evolving Landscape
Active materials science and regulatory science convergence are rewriting port design specifications, while channel economics force re-evaluation of how devices reach non-institutional caregivers.
Antimicrobial-impregnated silicone compounds containing silver nanoparticles or triclosan alternatives are absorbing clinical preference as infection prevention becomes the dominant procurement criterion. Oncology outpatient centers in the United States and Germany are standardizing on these formulations despite 15-20% cost premiums. The technology is absorbing market share from conventional uncoated ports by reducing catheter-related bloodstream infection rates and associated liability exposure.
Europe's Medical Device Regulation (MDR) Article 117 imposes unique device identifier traceability and economic operator accountability requirements that reshape post-market surveillance obligations. Manufacturers must now maintain European authorized representatives with direct liability for device performance, not merely regulatory paperwork. Class IIa port devices face heightened scrutiny of biological safety evaluation reports, compelling material suppliers to disclose full polymer additive compositions previously protected as trade secrets.
Hospital procurement consortia are consolidating vendor panels and demanding outcome guarantees that bundle device performance with complication rate thresholds. Group purchasing organizations in the United States now specify port-and-service contracts where suppliers assume risk for bloodstream infection costs exceeding benchmark rates. This restructuring is most visible in Medicare Advantage plan networks where capitated reimbursement aligns provider and supplier incentives around total cost of care reduction.
Subcutaneous Injection Ports Market Segmentation
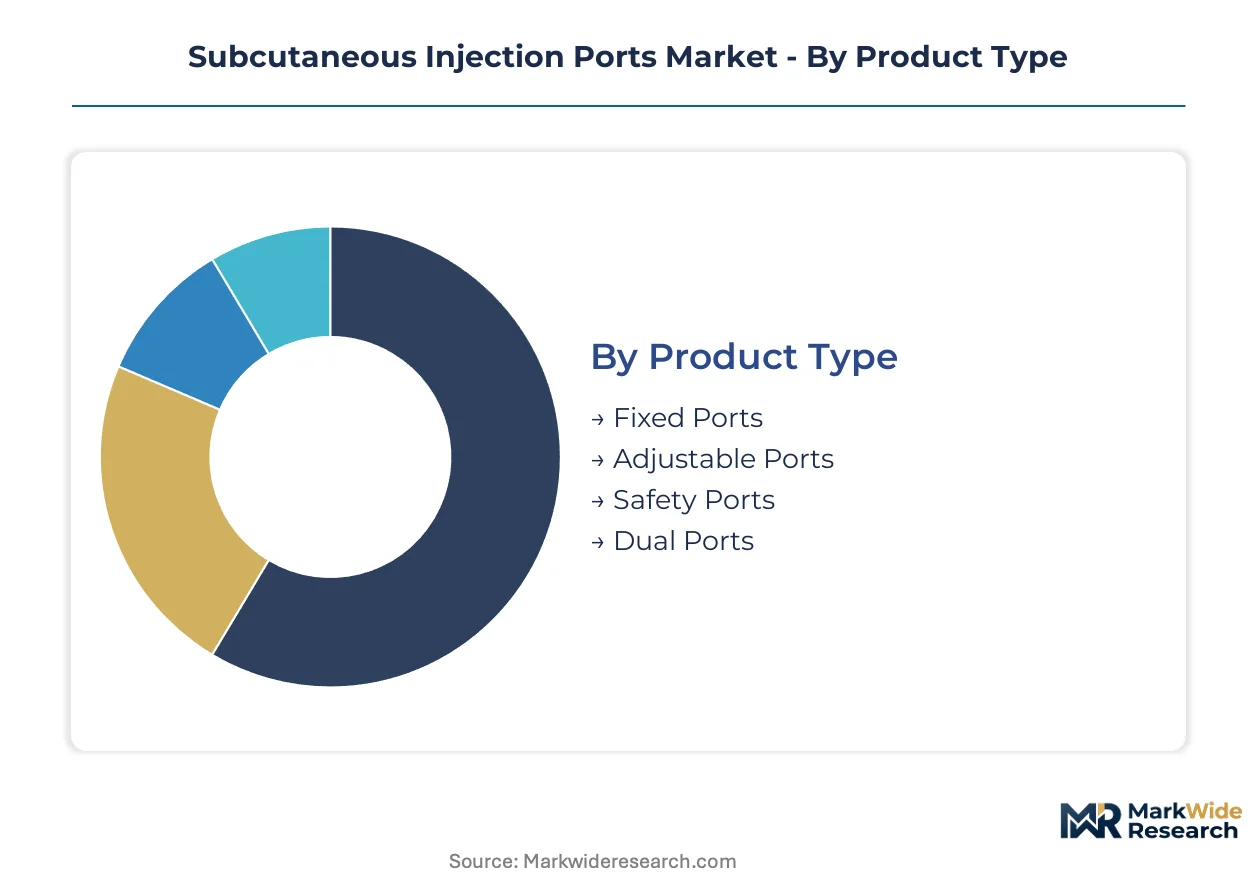
Segmentation in subcutaneous injection ports reveals how technical specifications, clinical settings, and material science converge to determine procurement priorities. Manufacturers engineer distinct port architectures to match dwell time requirements, sterilization protocols, and reimbursement pathways across institutional and ambulatory channels.
Product Type:
Port engineering specifications dictate septum durability, needlestick protection mechanisms, and multi-lumen capabilities that shape total cost of ownership calculations.
- Safety Ports:Integrated passive needlestick prevention systems eliminate exposed sharp post-access, satisfying OSHA bloodborne pathogen compliance for US hospital workers. Oncology infusion centers in the United States and Germany absorb 15-20% cost premiums to reduce liability exposure and worker compensation claims.
- Dual Ports:Independent fluid channels enable concurrent delivery of incompatible therapies—chemotherapy agents and supportive medications—without separate access site creation. Home care agencies in Japan leverage these configurations to reduce nurse visit frequency for complex patients.
- Fixed Ports:Single-septum designs with fixed catheter length dominate high-volume chemotherapy protocols where standardized access simplifies nursing workflows.
- Adjustable Ports:Variable catheter depth mechanisms accommodate adipose tissue thickness variation across patient populations, improving flow rates in bariatric applications.
Safety Ports lead on scale; Dual Ports lead on momentum.
End User:
Channel economics and reimbursement architecture determine procurement volume concentration and margin structure across care settings.
- Home Care:Medicare's home health prospective payment system expansion in the United States now covers port maintenance and supply costs, eliminating financial barriers to outpatient therapy adoption. Family-administered factor replacement for hemophilia patients drives demand for low-profile designs with simplified access protocols.
- Specialty Clinics:Outpatient oncology and infusion centers in Germany standardize on antimicrobial-impregnated port formulations despite cost premiums, prioritizing infection rate guarantees in vendor contracts.
- Hospitals:Accelerated discharge protocols compress patient dwell times, forcing procurement of ambulatory-ready port systems that tolerate home sterilization without clinical supervision.
- Long-Term Care Facilities:Skilled nursing facilities absorb ports for extended antibiotic therapy and pain management where IV access preservation proves clinically advantageous.
Home Care expands most quickly; Hospitals retain volume concentration.
Application:
Therapeutic indication determines port dwell time requirements, access frequency, and compatibility with concurrent medication delivery.
- Chemotherapy:Platinum-cured silicone septum formulations tolerate beyond 2000 puncture cycles, reducing replacement frequency for oncology patients on multi-year treatment protocols. US and German outpatient centers drive specification standards.
- Insulin Delivery:Miniaturized port profiles accommodate pediatric anatomy and family-administered therapy, with Bluetooth-enabled cap sensors emerging for access frequency tracking.
- Pain Management:High-flow port configurations support continuous opioid and local anesthetic infusion for palliative care and chronic pain patients.
- Antibiotic Therapy:Extended dwell applications for osteomyelitis and endocarditis require ports compatible with vesicant and irritant medication properties.
Chemotherapy anchors revenue scale; Insulin Delivery climbs the fastest.
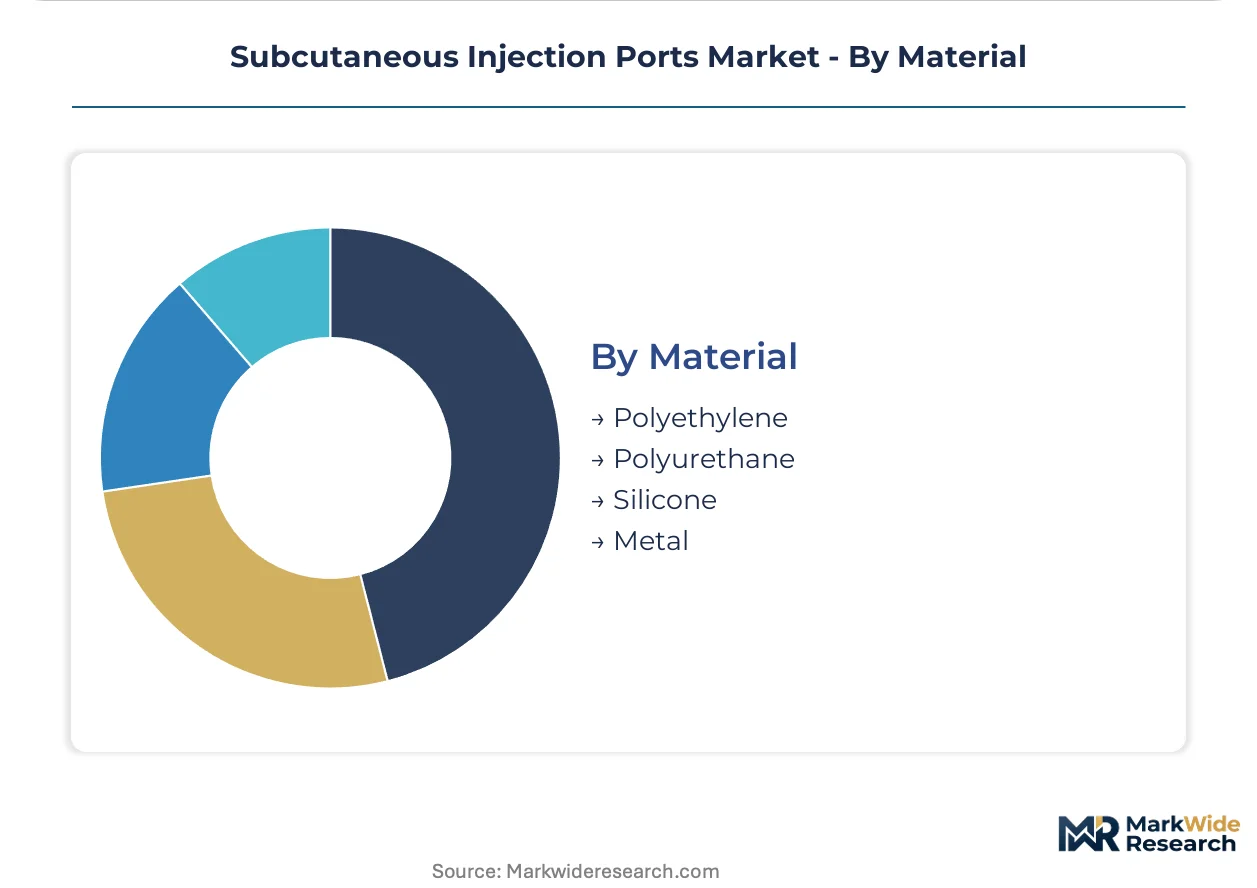
Material:
Polymer selection governs biocompatibility certification, sterilization validation, and septum fatigue performance across regulatory jurisdictions.
- Silicone:Medical-grade platinum-cured elastomers dominate septum construction for high-puncture-cycle applications, with specialty feedstock production concentrated in Germany and the United States exposing supply chain vulnerability.
- Polyurethane:Catheter shaft material selected for kink resistance and tensile strength in ambulatory patient movement conditions.
- Polyethylene:Port body construction material offering cost efficiency in single-use and limited-dwell applications.
- Metal:Titanium and stainless steel components provide radiopacity for imaging verification and structural integrity in implantable port chambers.
Silicone commands specification authority; Polyurethane gains share in ambulatory designs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's outpatient oncology infrastructure absorbs antimicrobial-impregnated ports at 15-20% cost premiums, while Japan's aging demographic concentrates demand in home care channels where PMDA combination product pathways govern drug-device integration timelines.
United States
Medicare's home health prospective payment system expansion eliminates financial barriers to outpatient port adoption for chemotherapy and insulin delivery. FDA 510(k) clearance pathways and OSHA bloodborne pathogen compliance requirements shape safety port specifications. The Greater Boston biomedical corridor anchors platinum-cured silicone septum R&D for high-puncture-cycle applications.
Germany
Outpatient infusion centers standardize on antimicrobial-impregnated formulations despite cost premiums, prioritizing infection rate guarantees in vendor contracts. EU MDR Article 117 imposes unique device identifier traceability and economic operator accountability obligations. The Rhine-Main industrial cluster concentrates specialty silicone feedstock production for medical-grade polymer supply.
Japan
Home care agencies leverage dual port configurations to reduce nurse visit frequency for complex patients requiring concurrent incompatible therapies. PMDA maintains distinct pharmaceutical affairs consultation pathways for combination products incorporating drug-eluting designs. The Kanto region around Tokyo anchors distribution networks serving the country's aging population.
India
Pediatric hemophilia home care presents underpenetrated white space for low-profile port designs scaled to family-administered factor replacement therapy. CDSCO medical device regulations govern import and distribution of implantable access devices. Maharashtra's Mumbai-Pune pharmaceutical corridor absorbs venture attention for ambulatory-ready port system localization.
Brazil
Extended antibiotic therapy for osteomyelitis drives port demand in outpatient settings where IV access preservation proves clinically advantageous. ANVISA regulatory pathways shape biocompatibility certification requirements for imported silicone and polyurethane components. São Paulo's healthcare infrastructure anchors specialty clinic procurement networks for chronic disease management devices.
Subcutaneous Injection Ports Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across institutional and ambulatory channels. The vendor base clusters around three strategic archetypes: integrated vascular access portfolio holders, insulin delivery ecosystem anchors, and regional distribution density specialists. Consolidation pressure intensifies as hospital procurement consortia demand outcome guarantees bundling device performance with complication rate thresholds. M&A activity targets antimicrobial material science capabilities, while strategic partnerships absorb Bluetooth-enabled remote monitoring sensor development.
Within the diversified medical technology tier, Medtronic and Becton Dickinson and Company exemplify integrated portfolio strategies spanning institutional contracting and home care channels. Medtronic MiniMed occupies a position anchoring recurring port demand through insulin delivery ecosystem lock-in. Smiths Medical represents the regional specialization archetype, with European ambulatory market density distinguishing its competitive position against scale-driven conglomerates.
| Leading Market Players |
|---|
| Medtronic MiniMed |
| Unomedical |
| Applied Medical Technology |
| Medtronic |
| Becton Dickinson and Company |
| Novo Nordisk |
| Patheon |
| Smiths Medical |
| ICU Medical |
| Others |
Value Network & Pricing Analysis
ISO 10993-5 cytotoxicity testing harmonization gates qualified silicone feedstock access and separates premium-tier antimicrobial-impregnated ports from standard formulations. Manufacturers lacking validated platinum-cured elastomer supply chains face exclusion from oncology procurement contracts in Germany and the United States.
Pricing Analysis
Capacity additions in Germany and the United States are reshaping price floors for medical-grade silicone feedstock. Three-tier pricing structure across premium antimicrobial, standard silicone, and economy polyethylene tiers reflects certification grade and septum puncture tolerance. Price differentiation stems from ISO 13485 quality mandates and after-sales service bundling. Cost compression in economy polyethylene segments is intensifying because of peripheral intravenous catheter substitution in short-dwell applications. Home care agencies exhibit highest price sensitivity; outpatient oncology centers absorb antimicrobial premiums.
Supply Chain Analysis
Regional distribution centers in the Rhine-Main cluster and Greater Boston corridor anchor hub-and-spoke patterns for specialty silicone feedstock. Supply concentrates in Germany, the United States, and Japan for platinum-cured elastomer production. Raw material dependencies include pharmaceutical-grade silicone, cobalt-60 for gamma sterilization, and titanium for radiopaque port chambers. Single-source vulnerability in medical-grade silicone polymer allocation exposes manufacturers to price volatility during pharmaceutical production surges. Distribution runs through hospital procurement consortia and home care agency networks with direct-to-patient last-mile delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory divergence between FDA 510(k) clearance timelines and EU MDR clinical evidence burdens creates geographic-arbitrage opportunities for manufacturers with dual-certification capabilities. The cost differential in notified body recertification expenses favors US-based firms accessing European markets through authorized representative structures.
For Market Incumbents: Cement institutional contracting advantages through backward integration into platinum-cured silicone septum production. Deepen GPO relationships by assuming bloodstream infection cost risk in outcome-guarantee contracts. Counter peripheral intravenous catheter substitution by emphasizing total cost-of-ownership for multi-year chemotherapy protocols. Invest in Bluetooth-enabled cap sensor R&D to capture subscription revenue models beyond device sales.
For New Entrants and Emerging Players: Capture pediatric hemophilia home care white space in India and Brazil with low-profile port designs scaled to family-administered factor replacement. Target antimicrobial-impregnated formulations for outpatient oncology centers in Germany where infection rate guarantees command procurement preference. Deploy direct-to-home-care-agency distribution to bypass consolidated hospital procurement panels.
For Investors and Strategic Acquirers: Roll-up economics work for regional ambulatory specialists because EU MDR compliance costs are displacing sub-scale European manufacturers. Five-to-ten year viability hinges on drug-device combination product capabilities and remote monitoring sensor integration. Target acquisition archetype: antimicrobial material science specialists with validated biocompatibility testing infrastructure. Monitor FDA guidance evolution on reusable device reprocessing as inflection indicator for design specification shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Accelerates US market access for silicone septum formulations with enhanced puncture tolerance. |
| CE Marking Pathway | EU MDR Article 117 compliance enables antimicrobial-impregnated port distribution to German oncology centers. |
| Hospital System Partnership | Medicare Advantage capitated contracts align supplier incentives with total cost-of-care reduction. |
| Software Companion Development | Bluetooth-enabled cap sensors enable subscription revenue models for access frequency tracking. |
| Reimbursement Strategy | Home health prospective payment system coverage eliminates patient financial barriers to outpatient adoption. |
Research Methodology
Multiple input streams — primary interviews with biomedical engineers and GPO contracts managers, secondary validation through FDA 510(k) filings and CMS Medicare data, and trade data reconciliation — were synthesized to construct market estimates. Conversations with hospital purchasing committees, home care agency procurement leads, and regulatory affairs specialists informed demand-side assumptions. Bottom-up port shipment analysis and top-down chronic disease prevalence modeling were cross-referenced for triangulation.
Data-stream reconciliation across product type, end user channel, therapeutic application, and material composition dimensions anchored the analytical framework. CAGRs were derived from segmented volume projections calibrated to reimbursement code evolution and regulatory pathway timelines. Forecast inputs incorporated ISO 10993-5 harmonization progress, EU MDR notified body capacity constraints, and home infusion therapy expansion rates.
Regulatory pathway delays, silicone feedstock allocation disruptions, and peripheral intravenous catheter technology advances are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding reimbursement expansion trajectories and sterilization facility capacity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Pectus Bar Market
Medical Devices
India Enteral Feeding Devices Market
Medical Devices
South Africa Artificial Organs and Bionic Implants Market
Medical Devices
South Korea Ultrasound Devices Market
Medical Devices
GCC and UAE Diabetes Devices Market
Medical Devices
United States Aesthetic Devices Market
Medical Devices
Snare Devices Market
Medical Devices
Leadless Cardiac Pacemaker Market
Medical Devices
Australia Respiratory Devices Market
Medical Devices
Global Intragastric Balloon Market
Medical Devices
North America Wheelchair Market
Medical Devices
Global Handheld Bladder Scanner Market
Medical Devices
Digital Migraine Treatment Device Market
Medical Devices
Hybrid Grafts Market
Medical Devices
Self-Sampling Blood Collection and Storage Devices Market
Medical Devices
Needle-Free Vaccine Injectors Market