
 Genitourinary Prosthetics Market | 2026-2036
Genitourinary Prosthetics Market Size, Share, and Industry Trends Forecast 2026-2036
Genitourinary Prosthetics Market Foresight
Silicone elastomer is repositioning titanium in select penile implant architectures by improving patient comfort and reducing capsule formation rates. Boston Scientific Corporation leverages its urology-focused manufacturing scale to dominate North American distribution channels for artificial urinary sphincters. Coloplast A/S anchors European market access through deep regulatory relationships with notified bodies under the EU MDR framework. Zephyr Surgical Implants specializes in customizable malleable rod geometries that serve price-sensitive segments without compromising mechanical reliability.
Genitourinary prosthetics comprise implantable medical devices engineered to restore anatomical function or structural integrity following trauma, disease, or congenital conditions affecting the urinary and reproductive systems. These devices typically incorporate biocompatible polymers, metallic alloys, or composite meshes fabricated through injection molding, textile weaving, or precision machining to achieve tensile strength exceeding 15 MPa and fatigue resistance across millions of physiological cycles. Penile implants command the largest revenue pool within product type segmentation due to established reimbursement codes and durable patient satisfaction metrics. Urethral slings represent the fastest-expanding category as outpatient procedural migration accelerates adoption in ambulatory surgery centers. Silicone and titanium material segments divide the market between flexibility-optimized and fixation-optimized clinical applications.
FDA 510(k) clearance pathways and EU MDR technical documentation requirements impose substantial biocompatibility testing burdens that filter smaller manufacturers from commercialization. Japan's PMDA enforces Japan Industrial Standards for implantable polymers that exceed ISO 10993 scope in cytotoxicity evaluation depth. Stakeholders must monitor evolving FDA guidance on antimicrobial device coatings and corresponding EMA harmonization timelines to anticipate competitive qualification gaps.
Market Dynamics
Silicone elastomer architectures are compressing titanium's historical dominance in penile implant fabrication as urology clinics prioritize patient-reported comfort metrics and reduced revision rates over mechanical rigidity.
Growth Catalysts
- EU MDR Conformity Pathways:Harmonized biocompatibility documentation under the Medical Device Regulation is streamlining cross-border commercialization for manufacturers with existing ISO 10993 testing portfolios.
- Ambulatory Surgery Center Migration:Urethral sling procedures are relocating from inpatient facilities to outpatient settings in the United States, compressing reimbursement cycles and expanding addressable procedure volumes.
- Japan Industrial Standards (JIS):PMDA enforcement of elevated cytotoxicity evaluation protocols is filtering non-compliant imports and creating protected market access for qualified polymer suppliers.
Market Restraints
- Medical-Grade Silicone Supply Concentration:Production of implantable elastomer raw materials clusters among three specialty chemical manufacturers, exposing device makers to input cost volatility and allocation constraints.
- FDA 510(k) Predicate Device Requirements:Substantial equivalence demonstrations for novel geometries impose documentation burdens that extend clearance timelines and elevate regulatory consulting expenditures.
- Non-Implant Therapeutic Substitution:Oral pharmacotherapies and vacuum erection devices retain first-line positioning in treatment algorithms, capping penetration rates among mild-to-moderate patient cohorts.
Strategic Opportunities
- Brazil's Expanding Private Insurance Infrastructure:Supplementary health plan enrollment growth in São Paulo and Rio de Janeiro is creating reimbursement pathways for elective implant procedures previously confined to out-of-pocket payment.
- Antimicrobial Coating Technology:FDA draft guidance on device-associated infection prevention is accelerating qualification timelines for silver-ion or antibiotic-eluting surface treatments.
- Telemedicine-Enabled Pre-Surgical Counseling:Virtual consultation platforms are reducing geographic access barriers and compressing patient acquisition costs for specialized urology practices.
Industry Challenges
- Polymer Processing Expertise Scarcity:Injection molding technicians capable of maintaining sub-micron tolerance control for silicone components command premium compensation and exhibit limited labor pool elasticity.
- EU MDR Notified Body Capacity Bottlenecks:Technical documentation review queues at designated conformity assessment organizations are extending time-to-market for legacy product recertifications.
- Legacy Device Inventory Obsolescence:Rigid rod implant architectures face accelerated depreciation as silicone-based alternatives capture preference share, stranding distributor inventory investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Genitourinary Prosthetics Market |
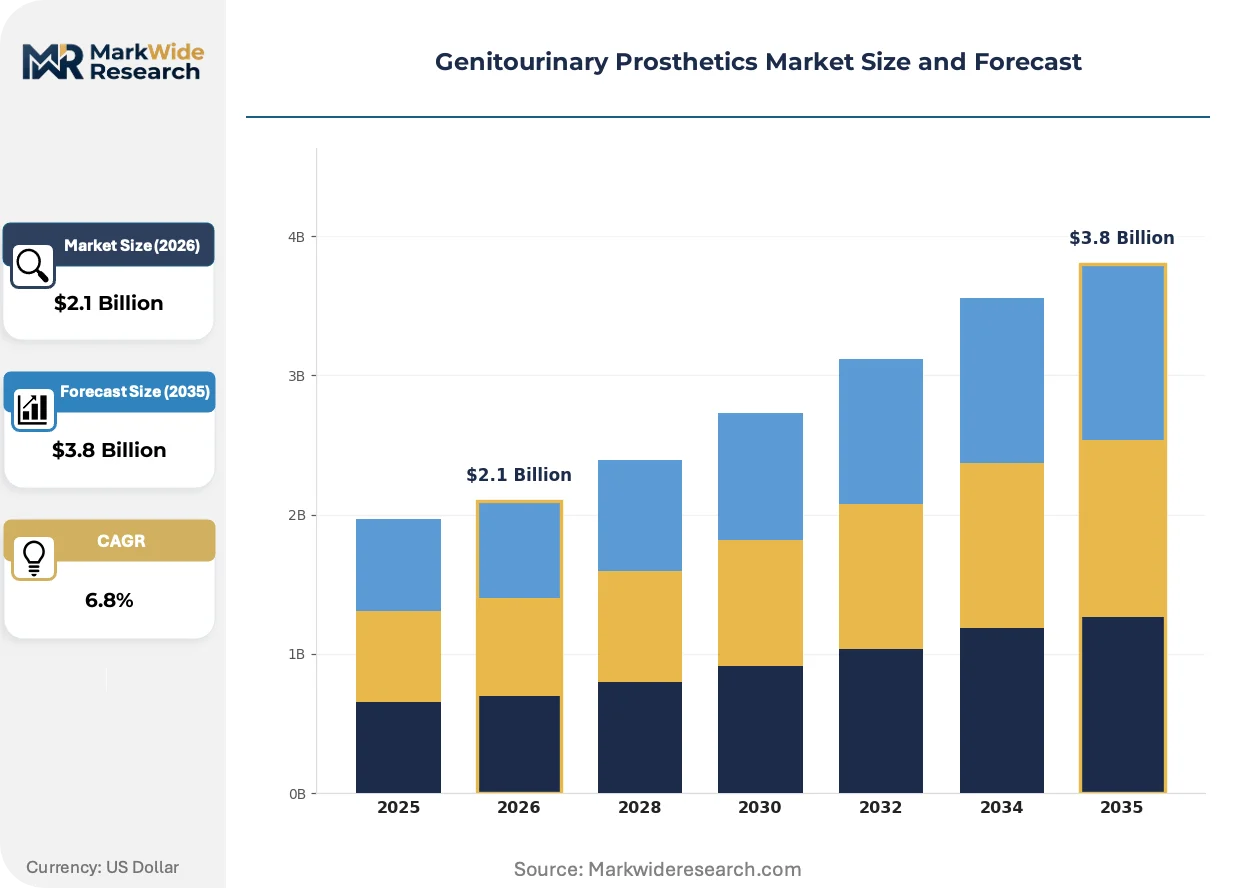
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Penile Implants, Urethral Slings, Artificial Urinary Sphincters, Testicular Prostheses, Female Incontinence Devices Material: Silicone, Titanium, Polyurethane, Polyester Mesh, Hydrogel Application: Urinary Incontinence, Erectile Dysfunction, Genital Reconstruction, Trauma Repair, Cosmetic Enhancement End User: Urology Clinics, Ambulatory Surgery Centers, Specialized Hospitals, Private Practices |
| Companies Covered | Promedon, Rigicon Inc, Boston Scientific Corporation, Qualigen Therapeutics Inc, Advin Healthcare, Coloplast A/S, UroMed, UroMems, Zephyr Surgical Implants, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Genitourinary Prosthetics Market Shifts & Advancements
Material science advances and regulatory harmonization initiatives are compressing product development cycles while elevating performance thresholds for fatigue resistance and biocompatibility documentation.
Silicone elastomer formulations with tuned durometer gradients are overtaking homogeneous titanium rod constructions in three-piece inflatable penile prosthetics. Urology clinics in Germany and the United States are adopting these architectures at accelerating pace as capsule contracture rates decline in longitudinal patient registries. The technology is overtaking legacy mechanical fixation approaches by enabling hydrophilic coating integration that reduces tissue adhesion during explant procedures.
Japan's PMDA has expanded JIS T 0993 cytotoxicity testing requirements beyond ISO 10993 scope for all implantable polymers classified as permanent contact devices. The industrial consequence is a bifurcation between manufacturers with in-house toxicology laboratories and those dependent on third-party testing houses with extended queue times. Penile implant suppliers targeting Japanese market access are responding by front-loading biocompatibility budgets and establishing direct PMDA consultation relationships.
Academic medical centers are consolidating procurement authority for high-value implantable devices into centralized value analysis committees. Independent urology practices and smaller hospital systems are losing direct vendor negotiation leverage as purchasing decisions migrate to multi-stakeholder review boards with standardized clinical evidence requirements. This concentration is most visible in the United States, where integrated delivery networks in Texas and Florida are capturing regional implant procedure volumes through employed physician models.
Genitourinary Prosthetics Market Segmentation
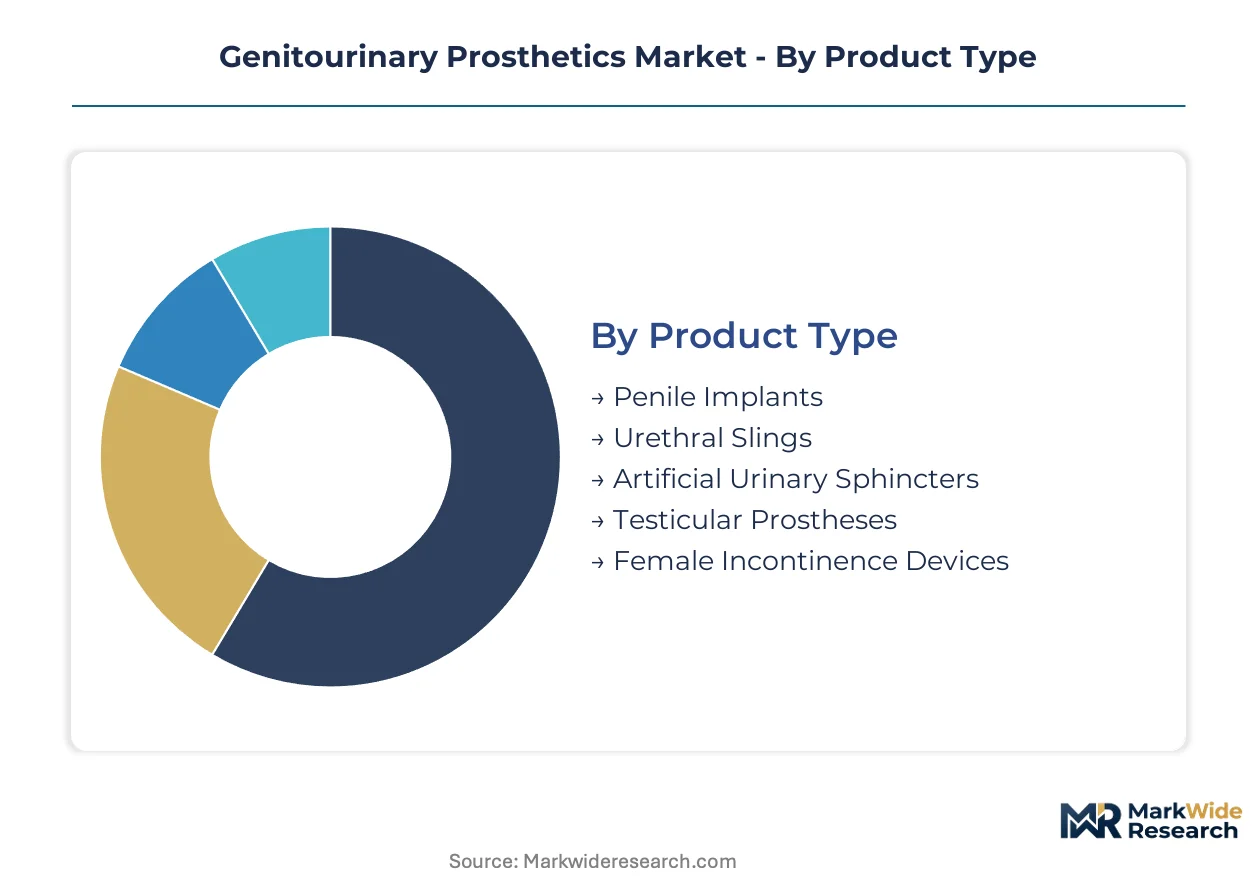
Genitourinary prosthetics segmentation reflects divergent regulatory pathways and reimbursement architectures across clinical applications. Each dimension carries distinct FDA 510(k) or EU MDR documentation burdens that shape manufacturer competitive positioning.
Product Type:
Certification requirements cluster around implant permanence and infection risk profiles, with inflatable devices demanding more extensive biocompatibility dossiers than malleable alternatives.
- Penile Implants:Three-piece inflatable systems incorporate silicone elastomer reservoirs and cylinders with titanium pump mechanisms. Demand concentrates in urology clinics across the United States and Germany where private reimbursement infrastructure supports elective procedural volumes.
- Urethral Slings:Synthetic mesh or autologous fascia configurations address stress urinary incontinence through minimally invasive placement. Ambulatory surgery centers in Texas and Florida are expanding sling procedure volumes as outpatient migration accelerates.
- Artificial Urinary Sphincters:Hydraulic cuff systems require precise pressure calibration for male incontinence management.
- Testicular Prostheses:Solid silicone implants restore cosmetic anatomy following orchiectomy or congenital absence.
- Female Incontinence Devices:Adjustable sling and bulking agent systems target pelvic floor dysfunction in distinct patient demographics.
Leading the category by volume: Penile Implants. Growing fastest: Urethral Slings.
Material:
Raw material selection determines JIS T 0993 cytotoxicity testing depth for Japanese market access and FDA biocompatibility documentation scope.
- Silicone:Medical-grade elastomers dominate inflatable prosthetic architectures due to fatigue resistance and hydrophilic coating compatibility. PMDA enforcement of expanded cytotoxicity protocols is filtering non-compliant imports from Japanese procurement channels.
- Titanium:Alloy rods and fixation components provide structural rigidity for malleable penile implants and sphincter pressure mechanisms. German urology clinics retain preference for titanium-backed devices in specific anatomical configurations.
- Polyurethane:Alternative elastomer with distinct degradation profiles for select sling applications.
- Polyester Mesh:Woven synthetic for mid-urethral sling tension support.
- Hydrogel:Bulking agent formulations for minimally invasive incontinence intervention.
Silicone commands the largest revenue share. Hydrogel applications are expanding most quickly in outpatient settings.
Application:
Clinical indication drives procedural site selection and reimbursement code availability, with erectile dysfunction and urinary incontinence representing divergent patient acquisition economics.
- Urinary Incontinence:Sling and sphincter interventions address stress and urge variants through anatomical support or functional occlusion. Ambulatory surgery centers in São Paulo are capturing volume as Brazilian private insurance expansion creates reimbursement pathways.
- Erectile Dysfunction:Penile implantation serves patients refractory to oral pharmacotherapy. United States urology clinics report highest procedural penetration where aging demographics intersect with established private payer infrastructure.
- Genital Reconstruction:Gender-affirming and congenital anomaly correction procedures.
- Trauma Repair:Post-injury anatomical restoration following pelvic fracture or iatrogenic damage.
- Cosmetic Enhancement:Elective procedures outside medically necessary indications.
Erectile Dysfunction generates the highest average revenue per procedure. Urinary Incontinence shows the steepest expansion trajectory as outpatient capabilities mature.
End User:
Procurement authority concentration into integrated delivery networks is reshaping vendor negotiation leverage across facility types.
- Urology Clinics:Specialized physician practices dominate penile implant volume through direct patient relationships and procedural expertise. Texas and Florida regional networks are consolidating purchasing decisions into value analysis committees with standardized evidence requirements.
- Ambulatory Surgery Centers:Outpatient facilities capture urethral sling migration with compressed reimbursement cycles. United States ASCs are expanding addressable volumes as payers incentivize site-of-care shifts.
- Specialized Hospitals:Academic medical centers with complex reconstruction capabilities.
- Private Practices:Independent physician groups losing direct vendor leverage to network consolidation.
Urology Clinics retain the highest implant procedure volume. Ambulatory Surgery Centers are gaining share fastest as site-of-care economics reshape referral patterns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Private reimbursement infrastructure concentrates procedural demand in the United States, Germany, and Japan, while Brazil's expanding supplementary health plans are unlocking previously out-of-pocket segments. Regulatory divergence across FDA, EU MDR, and PMDA jurisdictions shapes manufacturer market entry sequencing and documentation investment.
United States
Aging demographics intersect with established private payer networks to sustain the highest penile implant procedural penetration globally. FDA 510(k) clearance pathways impose substantial equivalence documentation burdens that filter smaller manufacturers from commercialization. Texas and Florida integrated delivery networks are consolidating procurement authority into centralized value analysis committees with standardized clinical evidence requirements.
Germany
Urology clinics across Bavaria and North Rhine-Westphalia are expanding silicone-based penile prosthetic volumes as patient-reported comfort metrics displace legacy rigid designs. EU MDR conformity assessments through German notified bodies require harmonized biocompatibility documentation that streamlines cross-border commercialization. The Munich-Stuttgart corridor anchors European manufacturing scale for artificial urinary sphincter distribution.
Japan
PMDA enforcement of JIS T 0993 cytotoxicity testing beyond ISO 10993 scope filters non-compliant polymer imports and protects qualified suppliers. Kanto and Kansai regional medical centers demonstrate elevated adoption of fatigue-resistant elastomer architectures in longitudinal registries. Tokyo-based urology practices are front-loading biocompatibility budgets to secure direct PMDA consultation relationships.
Brazil
Supplementary health plan enrollment growth in São Paulo and Rio de Janeiro is creating reimbursement pathways for elective implant procedures previously confined to cash payment. ANVISA regulatory alignment with international standards accelerates qualification timelines for manufacturers with existing ISO 10993 portfolios. Southeast regional ambulatory surgery centers are capturing urethral sling volume as site-of-care economics reshape referral patterns.
United Kingdom
NHS England specialized commissioning frameworks concentrate high-value genitourinary reconstruction procedures into designated supraregional centers. MHRA post-Brexit regulatory autonomy maintains EU MDR technical documentation equivalence while streamlining UKCA marking transition timelines. The London-Oxford-Cambridge triangle anchors academic medical center procurement consolidation with multi-stakeholder evidence review boards.
Genitourinary Prosthetics Market Competitive Landscape
Portfolio diversification dominates the current landscape as manufacturers balance urology-focused depth against multi-specialty breadth. The vendor base stratifies across three tiers: integrated medical device conglomerates with urology divisions, mid-cap specialists with regional regulatory depth, and emerging technology developers targeting unmet mechanical or materials performance gaps. M&A activity and strategic technology licensing represent the primary competitive vectors, with acquisition premiums reflecting EU MDR documentation asset value and PMDA consultation relationships.
Among North American and European anchors, Boston Scientific Corporation exemplifies scale-driven manufacturing and distribution infrastructure, while Coloplast A/S occupies a position anchored in European regulatory relationships and notified body collaboration. Zephyr Surgical Implants represents the specialization archetype, with customizable geometries serving price-sensitive segments without mechanical reliability compromise. These three entities collectively illustrate the competitive spectrum from conglomerate breadth through regional regulatory depth to technical specialization.
| Leading Market Players |
|---|
| Promedon |
| Rigicon Inc |
| Boston Scientific Corporation |
| Qualigen Therapeutics Inc |
| Advin Healthcare |
| Coloplast A/S |
| UroMed |
| UroMems |
| Zephyr Surgical Implants |
| Others |
Supply & Pricing Matrix
Silicone elastomer migration from homogeneous titanium rods is simultaneously compressing per-unit manufacturing costs and concentrating procurement leverage among medical-grade polymer compounders with validated biocompatibility dossiers. This materials transition rewards device makers with captive formulation relationships while penalizing those dependent on spot-market elastomer sourcing.
Pricing Analysis
High-volume malleable rod segments trade margin for hospital system contract security, while three-piece inflatable systems capture premium positioning through fatigue-resistance certification tiers. Price differentiation hinges on FDA 510(k) predicate equivalence documentation depth and ISO 10993 testing completeness, with Japanese PMDA JIS T 0993 compliance commanding additional certification premiums. Pricing pressure stems from ambulatory surgery center procurement consolidation in Texas and Florida, where value analysis committees standardize evidence requirements across integrated delivery networks. Independent urology practices exhibit highest price sensitivity due to inventory carrying cost constraints, whereas academic medical centers prioritize device performance metrics over per-unit expenditure.
Supply Chain Analysis
Freight cost volatility for temperature-controlled medical-grade silicone shipments from Germany and Japan is amplifying landed cost differentials between regional compounders and Asian manufacturing hubs. Raw material sourcing concentrates on Dow Corning and Wacker Chemie specialty elastomer production, with titanium alloy rod feedstock anchored in Chinese and Russian sponge titanium refining. Single-source vulnerability permeates medical-grade silicone allocation, where three specialty chemical manufacturers control implantable elastomer supply. Distribution runs through urology-focused distributor networks with consignment inventory arrangements at major hospital systems, compressing working capital cycles for device makers with direct GPO contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The genitourinary prosthetics sector is becoming a vertical-integration race where control over medical-grade silicone formulation and PMDA consultation relationships determines sustainable margin capture.
For Market Incumbents: Anticipate EU MDR notified body capacity bottlenecks by front-loading technical documentation recertification budgets and establishing redundant conformity assessment partnerships. Secure backward integration into medical-grade silicone compounding through exclusive supply agreements with Wacker Chemie or Dow Corning, insulating against allocation constraints that threaten production continuity for Japanese market access. For New Entrants and Emerging Players: Capture Brazilian private insurance expansion in São Paulo and Rio de Janeiro by aligning ANVISA qualification timelines with local distributor consignment partnerships. Target price-sensitive malleable rod segments in secondary German urology clinics where Coloplast and Boston Scientific field presence remains thinner, leveraging customizable geometries as differentiation against standardized conglomerate offerings. For Investors and Strategic Acquirers: Exit pathways concentrate in mid-cap specialists with complete EU MDR technical documentation assets and established PMDA consultation relationships. Long-term viability favors targets with in-house polymer toxicology laboratories rather than third-party testing dependencies. Monitor FDA draft guidance finalization on antimicrobial device coatings as inflection indicator for silver-ion surface treatment qualification premiums.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Recertification | Streamlines cross-border commercialization through German notified body relationships. |
| PMDA JIS T 0993 Compliance Investment | Filters non-compliant imports and protects Japanese market access for qualified suppliers. |
| Medical-Grade Silicone Supply Agreement | Secures allocation priority from Dow Corning or Wacker Chemie specialty elastomer production. |
| Ambulatory Surgery Center Distribution Partnership | Captures urethral sling volume migration in Texas and Florida outpatient settings. |
| Antimicrobial Coating Qualification | Accelerates FDA clearance timelines for silver-ion surface treatments per draft guidance. |
Research Methodology
Multi-period observation of penile implant procedure volumes, urethral sling migration rates, and silicone elastomer adoption curves anchored the trend analysis, supplemented by interviews with urology clinic procurement directors, biomedical engineers at academic medical centers, GPO contracts managers, and regulatory affairs leads at notified bodies. Secondary validation drew from FDA 510(k) clearance databases, EU MDR technical documentation registries, PMDA approval summaries, hospital procurement databases, and CMS Medicare reimbursement data. Bottom-up procedure volume estimates triangulated against top-down manufacturer revenue disclosures.
Segment-weighting approaches modeled product type, material composition, clinical application, and end-user facility category dimensions across the projection horizon. CAGRs derived from regression analysis of historical procedure penetration rates, adjusted for demographic aging trajectories and reimbursement code expansion timelines. Forecast inputs incorporated PMDA JIS T 0993 enforcement stringency indices and EU MDR notified body capacity utilization rates.
The model holds under stable regulatory harmonization and silicone supply allocation continuity; deviation in medical-grade elastomer production constraints or FDA antimicrobial coating guidance finalization would shift manufacturer competitive positioning. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
High Flow Ventilators Market
Medical Devices
Adjustable Speed Vortex Mixer Market
Medical Devices
France Ophthalmic Devices Market
Medical Devices
Global Casting Devices Market
Medical Devices
Sonohysterography Catheters Market
Medical Devices
Asthma Device Market
Medical Devices
3D Printing for Surgical Procedures Market
Medical Devices
Digital Vision Lenses Market
Medical Devices
India Clear Aligners Market
Medical Devices
US Pulse Oximeters Market
Medical Devices
Plastic Surgery Scaffolds Market
Medical Devices
Balloon Catheters for Bile Stone Removal Market
Medical Devices
Global Joint Pain Injections Market
Medical Devices
Radial Head Resection Implant Market
Medical Devices
Australia Drug Delivery Devices Market
Medical Devices
Power Smart Bed Market