
 Composite Paper Cans Market | 2026-2036
Composite Paper Cans Market Size, Share, and Industry Trends Forecast 2026-2036
Composite Paper Cans Market Analysis
Food and beverage packaging is repositioning composite paper cans as the preferred rigid container for dry goods, snacks, and powdered products. Mondi leverages its European manufacturing footprint to supply branded food producers with high-barrier paper solutions. Sonoco Products anchors North American demand through its spiral-wound can technology and dairy powder expertise. Huhtamaki competes in emerging markets with cost-optimized formats for instant coffee and confectionery.
Composite paper cans consist of layered paperboard bodies with metal, plastic, or aluminum closures, manufactured through spiral winding or convolute forming to achieve specific burst strength and moisture resistance for shelf-stable goods. The cylindrical structure serves primary containment, stacking, and retail display functions across consumer packaged goods. Eco-friendly cans lead structural growth as brands face Extended Producer Responsibility mandates and consumer preference shifts. Custom cans capture premium margin pools in personal care and gift applications where dimensional precision and print quality command price premiums. Standard cans remain the volume backbone in bulk food and industrial ingredient segments.
EMA packaging material guidelines, FDA food contact substance regulations, and EU Packaging and Packaging Waste Regulation collectively shape material compliance pathways and recyclability claims. REACH chemical restrictions and FSC chain-of-custody certification further filter supplier qualification and raw material sourcing for multinational brand owners. Stakeholders must monitor evolving single-use packaging bans and deposit-return scheme expansions to anticipate format obsolescence risks and circular economy investment requirements.
Market Dynamics
Extended Producer Responsibility mandates across the European Union are forcing CPG brands to eliminate non-recyclable packaging formats, creating immediate substitution demand for composite paper cans in dry food and personal care segments.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Mandatory recyclability targets by 2030 compel food manufacturers to replace multi-material flexible pouches with mono-material paperboard containers.
- Spiral-winding automation:High-speed forming lines reduce unit costs for mid-volume converters serving snack and confectionery brands.
- Germany:Deposit-return scheme expansions for beverage packaging create spillover demand for complementary dry goods containers in retail.
Market Restraints
- Aluminum closure volatility:Input cost swings for metal ends compress converter margins during contract renegotiations with dairy powder packagers.
- Scandinavian pulp concentration:Three suppliers control 70% of food-grade kraft availability, creating bottleneck risk for barrier-coated paperboard.
- High-barrier limitation:Current water-vapor transmission rates in uncoated paper fail shelf-life requirements for hygroscopic ingredients in tropical climates.
Strategic Opportunities
- India:FSSAI's plastic packaging phase-out for food contact creates first-mover advantage for EU-certified converters establishing local spiral-winding capacity.
- Pharmaceutical desiccant integration:Built-in moisture-absorbing liners position paper cans as primary packaging for probiotic supplements.
- Digital printing convergence:Variable-data decoration enables lot-level traceability for organic certification compliance in direct-to-consumer channels.
Industry Challenges
- Barrier chemistry expertise:Shortage of polymer scientists capable of formulating bio-based coatings that meet FDA food contact substance migration limits.
- FSC chain-of-custody certification:18-month audit timelines delay supplier qualification for multinational brand owner preferred vendor lists.
- Legacy filling line retrofit:Confectionery packagers face six-figure capex to adapt capping torque specifications for paper can dimensional tolerances.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Composite Paper Cans Market |
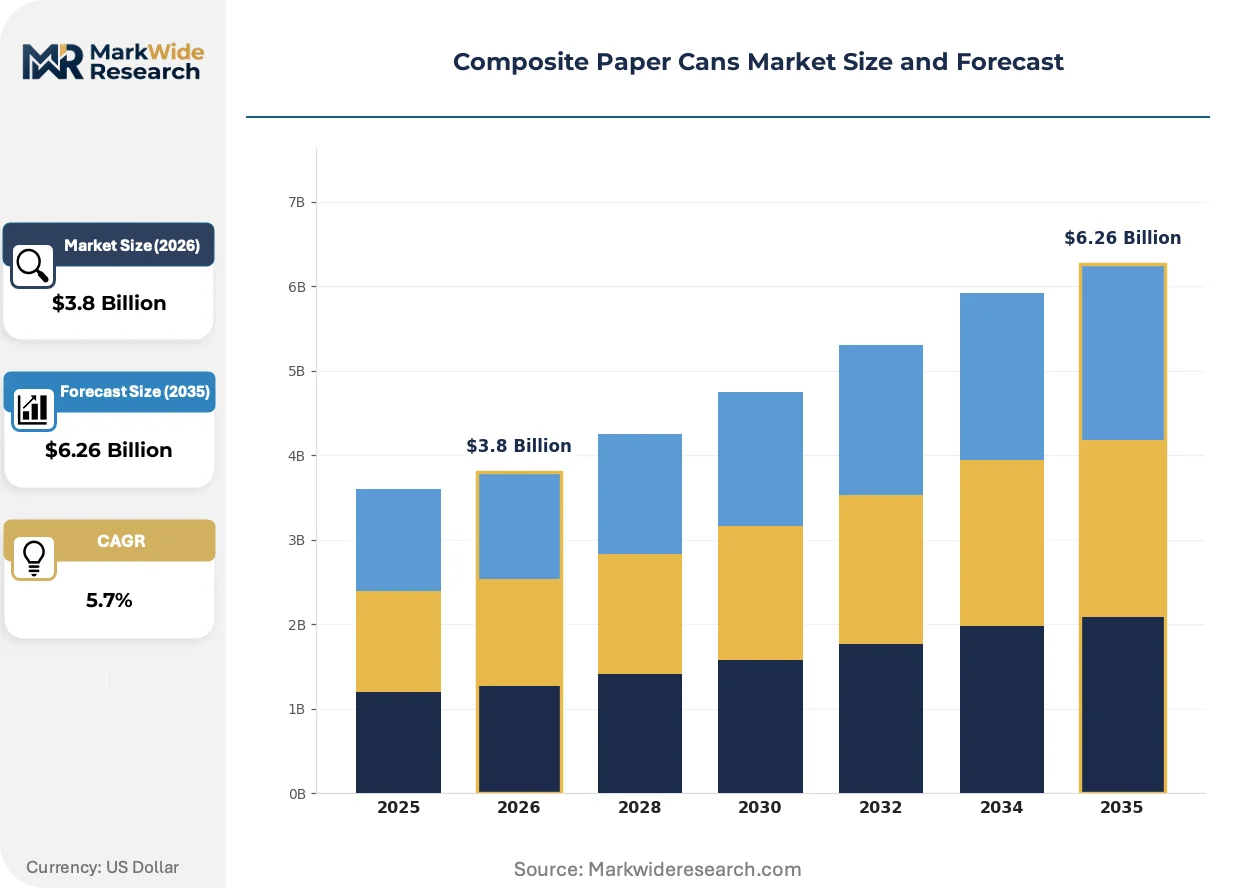
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Cans, Custom Cans, Eco-friendly Cans, Decorative Cans End Use Industry: Food & Beverage, Personal Care, Pharmaceuticals, Household Products Packaging Type: Rigid Containers, Flexible Packaging, Bulk Packaging, Composite Packaging Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Direct Sales |
| Companies Covered | Mondi, International Paper, Sonoco Products, Compocan Industries, Huhtamaki, Smurfit Kappa, Georgia-Pacific, Dart Container Corporation, Amcor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Composite Paper Cans Market Emerging Trajectories
Material science breakthroughs in bio-based barrier coatings are collapsing the performance gap between composite paper cans and plastic alternatives, while regulatory pressure accelerates format substitution timelines.
Digital inline inspection systems are automating defect detection during spiral winding, replacing manual sampling protocols. Snack food packagers in the Netherlands and Belgium are deploying these systems at line speeds exceeding 400 cans per minute. Quality consistency improvements are automating supplier tier upgrades for converters seeking preferred vendor status with pan-European retail chains.
REACH chemical restrictions on per- and polyfluoroalkyl substances are banning legacy grease-resistant coatings in food contact applications. The regulation forces immediate formulation switches to polylactic acid and bio-wax alternatives. Breakfast cereal and powdered drink manufacturers in Germany face 12-month compliance deadlines that compress qualification cycles for new barrier technologies.
Brand owners are consolidating packaging specifications across regional portfolios, eliminating SKU proliferation that complicated previous sustainability reporting. Procurement teams now mandate pan-European can formats with identical dimensions and closure systems. This standardization concentrates volume with converters achieving scale economies in barrier-coated paperboard production.
Composite Paper Cans Market Segmentation
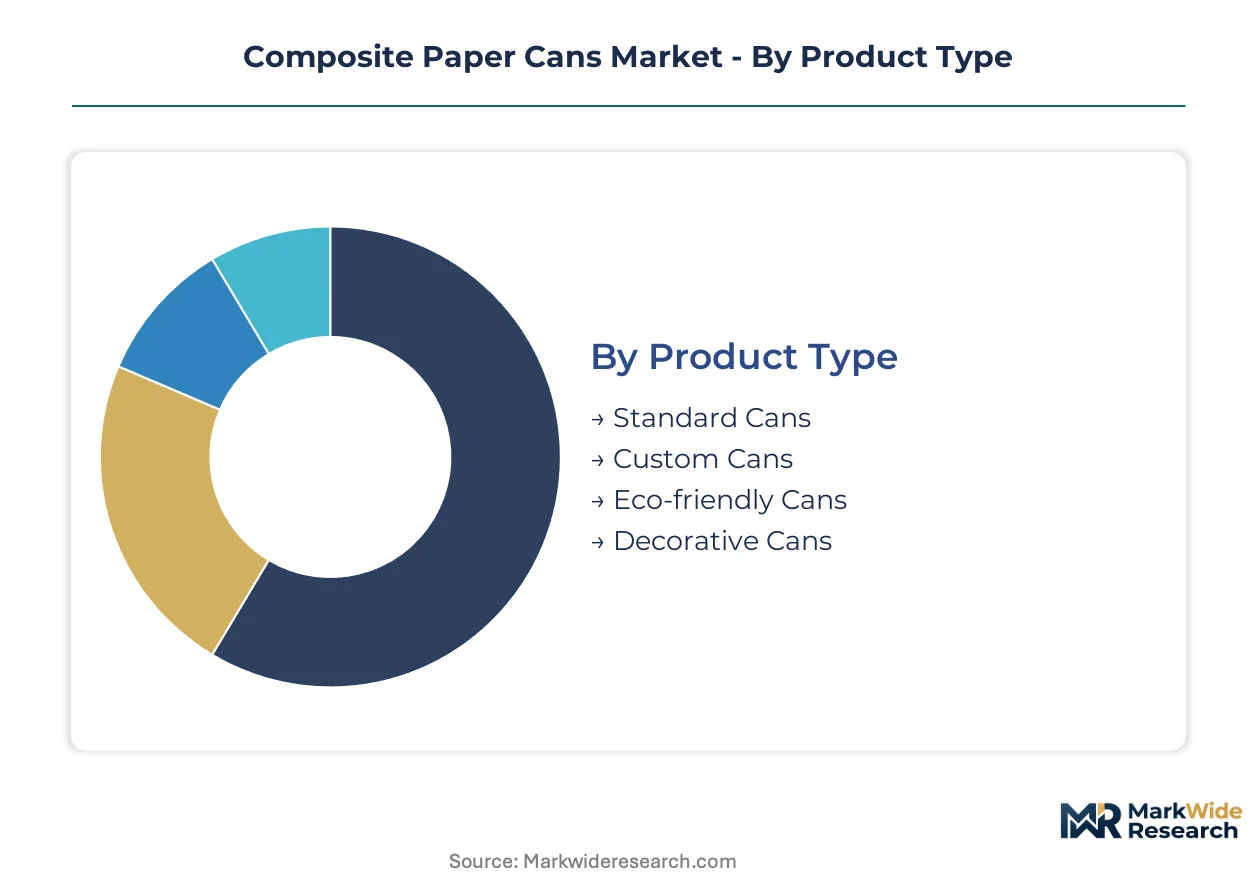
Segmentation in composite paper cans reveals how format specifications align with divergent supply chain requirements across shelf-stable goods. Product dimensions, barrier properties, and closure systems vary sharply between commodity food volumes and premium personal care positioning.
Product Type:
Integration depth separates standalone commodity formats from engineered solutions requiring co-development with brand packaging teams.
- Eco-friendly Cans:Barrier-coated paperboard bodies use bio-based sealants and aluminum-free closures to meet EU Packaging and Packaging Waste Regulation recyclability mandates. German breakfast cereal manufacturers and French organic snack brands drive specification intensity as Extended Producer Responsibility compliance deadlines approach.
- Custom Cans:Dimensional precision and high-fidelity print surfaces serve personal care and gift applications where retail differentiation commands price premiums. Dutch cosmetics brands specify matte-laminated exteriors with embossed logos for shelf impact in perfumery channels.
- Standard Cans:Spiral-wound kraft bodies with metal ends dominate bulk dry food and industrial ingredient segments where unit economics override decoration requirements.
- Decorative Cans:Specialty finishes including metallic foiling and textured coatings target seasonal confectionery and promotional packaging in UK retail.
Standard cans lead volumes today; eco-friendly cans are gaining share fastest.
End Use Industry:
Application maturity determines whether paper cans displace incumbent formats or defend existing positions against flexible pouch substitution.
- Food & Beverage:Powdered dairy, instant coffee, and snack applications exploit spiral-winding economies at scale. Italian pasta brands and Spanish nut roasters specify high-barrier constructions for shelf-stable dry goods.
- Personal Care:Talcum powder and dry shampoo formats leverage cylindrical rigidity for retail stacking and e-commerce durability. Premium positioning in French pharmacy channels demands FSC-certified paperboard with embossed closures.
- Pharmaceuticals:Probiotic supplements and desiccant-sensitive powders require moisture transmission rates below uncoated paper capabilities, driving barrier coating innovation.
- Household Products:Laundry powder and dishwasher tablet formats prioritize stacking strength over barrier performance, accepting standard kraft constructions.
Food and beverage anchors revenue today; pharmaceuticals is expanding most quickly.
Packaging Type:
Structural classification reflects where composite paper cans compete against alternative material systems rather than within their own category.
- Rigid Containers:Cylindrical paperboard bodies with formed metal or plastic ends provide primary containment and display functions. This format directly substitutes plastic tubs and glass jars in dry goods segments.
- Composite Packaging:Multi-material constructions combining paperboard with aluminum foil or polymer barriers address shelf-life extension requirements for hygroscopic ingredients.
- Flexible Packaging:Paper-based pouches and wraps serve complementary roles where conformability matters more than stacking strength.
- Bulk Packaging:Industrial-scale drums and intermediate bulk containers use similar spiral-winding techniques at expanded diameters for ingredient supply chains.
Rigid containers dominate unit volumes today; composite packaging is climbing the fastest.
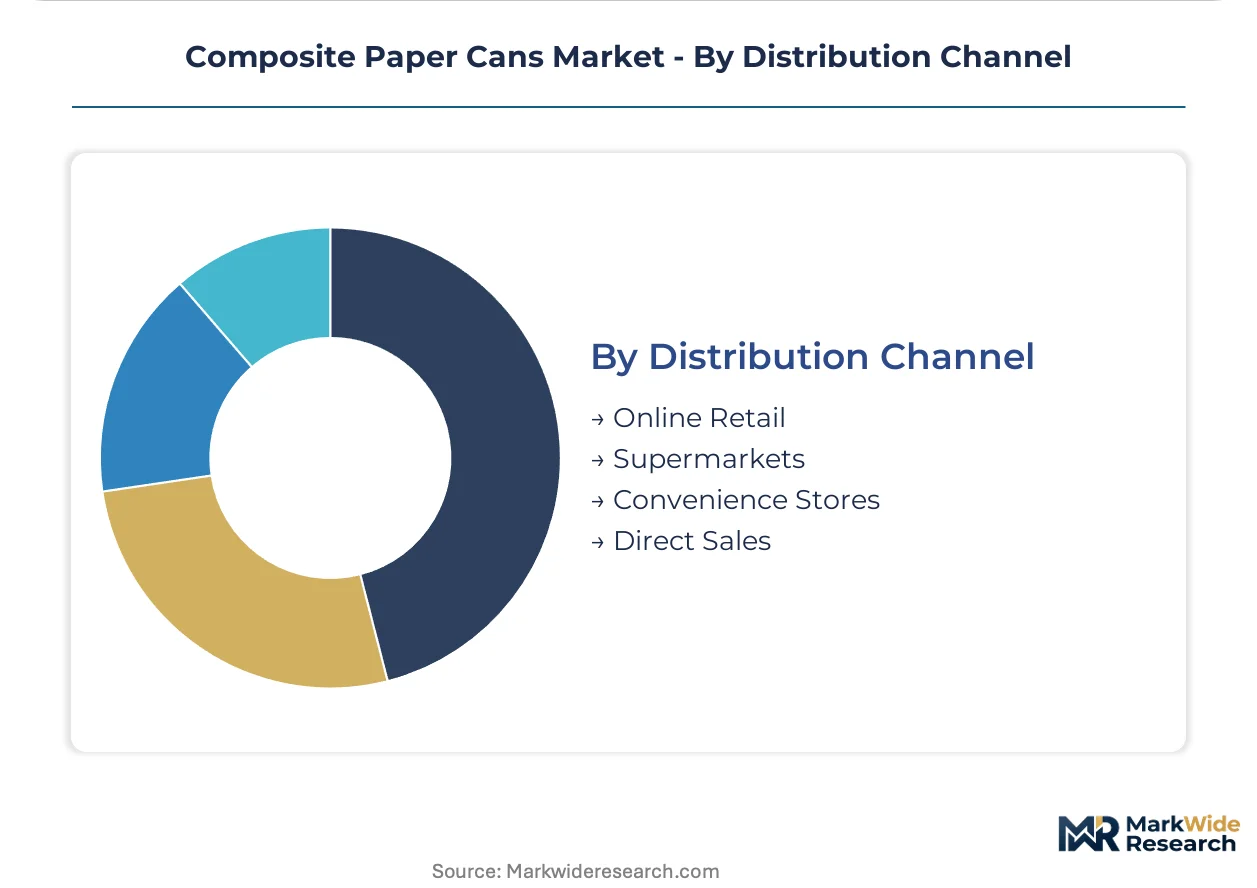
Distribution Channel:
Channel selection dictates dimensional tolerances, lot traceability requirements, and damage resistance specifications for last-mile handling.
- Supermarkets:Pan-European retail chains mandate standardized can dimensions for shelf modularization and automated replenishment systems. German and UK grocery multiples specify identical 73mm and 99mm diameters across private label ranges.
- Online Retail:Direct-to-consumer shipments require enhanced edge crush resistance and closure security for individual parcel handling. Belgian snack subscription services specify double-walled constructions for postal durability.
- Convenience Stores:Smaller format cans and multi-packs address impulse purchase occasions and limited shelf depth in urban retail.
- Direct Sales:B2B ingredient supply to food manufacturers emphasizes pallet optimization and bulk handling efficiency over retail presentation.
Supermarkets lead channel volumes today; online retail is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Converters are relocating spiral-winding capacity toward jurisdictions with lower Extended Producer Responsibility compliance costs while maintaining EU market access through distributed fulfillment networks. Germany and France absorb the highest specification intensity as brand owners consolidate pan-European procurement.
Germany
Breakfast cereal manufacturers and organic snack brands drive demand for barrier-coated eco-friendly formats. The country's national packaging regulator enforces strict recyclability targets under the EU Packaging and Packaging Waste Regulation ahead of the 2030 deadline. The Rhine-Ruhr industrial corridor hosts concentrated converter capacity serving pan-European retail chains.
France
Cosmetics and personal care brands specify premium custom cans with embossed closures and matte-laminated exteriors. ANSM and national environmental agencies coordinate enforcement of REACH chemical restrictions on legacy coatings. The Île-de-France region clusters brand owner headquarters that mandate FSC-certified paperboard across supplier portfolios.
United Kingdom
Seasonal confectionery and promotional packaging sustain demand for decorative specialty finishes. The national environmental regulator administers Extended Producer Responsibility scheme expansions that compress format transition timelines. The Midlands manufacturing belt concentrates spiral-winding operations supplying UK grocery multiples.
India
FSSAI's plastic packaging phase-out for food contact applications creates substitution demand for EU-certified paper can formats. The national food safety regulator mandates compliance deadlines that favor early entrants with established barrier coating expertise. The Maharashtra-Gujarat industrial corridor attracts converters establishing local spiral-winding capacity for domestic and export markets.
United States
Dairy powder and snack food packagers anchor North American demand through high-volume spiral-wound specifications. FDA food contact substance regulations govern migration limits for bio-based barrier chemistries. The Midwest manufacturing region concentrates dairy processing and associated packaging converter operations.
Composite Paper Cans Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated paperboard producers commanding premium tiers and regional converters capturing bulk food volumes. The vendor base organizes around three strategic archetypes: integrated forest products groups with captive pulp supply, specialized rigid packaging converters with spiral-winding expertise, and diversified multinational packaging platforms with cross-format capabilities. Consolidation pressure intensifies as brand owners reduce supplier counts to simplify sustainability reporting and audit compliance. Capacity expansion and barrier technology licensing represent the dominant competitive vectors as converters race to qualify bio-based coatings ahead of regulatory deadlines.
Among European integrated paperboard groups, Mondi and Smurfit Kappa exemplify the forest-to-can archetype with control over kraft pulp supply and barrier coating formulation. Sonoco Products anchors the specialized converter tier with dedicated spiral-winding technology heritage. These three occupy positions across the premium and standard can segments, with geographic footprint and certification depth determining competitive access to multinational brand owner preferred vendor lists.
| Leading Market Players |
|---|
| Mondi |
| International Paper |
| Sonoco Products |
| Compocan Industries |
| Huhtamaki |
| Smurfit Kappa |
| Georgia-Pacific |
| Dart Container Corporation |
| Amcor |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between FSC chain-of-custody holders and uncertified converters splits pricing power along supply chain access tiers, with EU-compliant producers commanding contract premiums while commodity suppliers absorb aluminum closure volatility through thinner margins.
Pricing Analysis
Distributor margin layers concentrate value capture at the brand-owner interface, where pan-European procurement consolidation enables volume-tier discounts. Three-tier pricing structure across premium, standard, and economy levels reflects FSC certification depth and barrier coating complexity. Price differentiation hinges on bio-based coating migration compliance and spiral-winding automation scale. Cost compression in standard kraft segments is intensifying because Scandinavian pulp suppliers wield bottleneck leverage. Dairy powder packagers exhibit highest price sensitivity; cosmetics brands demonstrate lowest.
Supply Chain Analysis
Regional distribution centers in Germany, France, and the United Kingdom anchor hub-and-spoke fulfillment for pan-European retail chains. Manufacturing concentrates in Germany, the United States, and India, with emerging capacity in Maharashtra-Gujarat serving FSSAI compliance demand. Raw material dependencies center on food-grade Scandinavian kraft, aluminum closure stock, and bio-based barrier polymers. Single-source vulnerability in Scandinavian pulp concentration threatens converter margin stability. Distribution runs through branded food producer direct contracts and private-label retail specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic-arbitrage opportunities crystallize around Extended Producer Responsibility compliance cost differentials between EU jurisdictions with mature deposit-return schemes and emerging markets with phased plastic phase-outs.
For Market Incumbents: Lock in FSC-certified pulp supply through backward integration or long-term offtake agreements with Scandinavian suppliers. Defend against Indian converter entrants by accelerating barrier coating R&D ahead of FSSAI enforcement timelines. Prioritize certification investment to maintain preferred vendor status with consolidating pan-European retail procurement teams.
For New Entrants and Emerging Players: Enter via pharmaceutical desiccant integration, where moisture-barrier expertise gaps create qualification delays for established suppliers. Target Indian domestic snack brands facing FSSAI plastic packaging deadlines with EU-certified spiral-winding technology licensing. Pursue technical partnership routes with Maharashtra-Gujarat industrial corridor developers to bypass 18-month FSC audit timelines.
For Investors and Strategic Acquirers: Consolidation pressure builds where converter fragmentation complicates multinational brand owner sustainability reporting. Five-to-ten-year viability favors integrated forest products groups with captive kraft supply and barrier formulation capabilities. Acquisition target archetype: mid-cap European converters with established EMA compliance and underutilized spiral-winding capacity. Signal to watch: REACH chemical restriction expansion beyond PFAS into bio-based coating precursor categories.
| Strategic Initiative | Industry Significance |
|---|---|
| Barrier Coating R&D Partnership | Accelerates bio-based formulation qualification ahead of REACH deadline compression. |
| Scandinavian Pulp Supply Agreement | Secures food-grade kraft allocation against three-supplier concentration risk. |
| FSC Chain-of-Custody Certification | Unlocks preferred vendor access to pan-European retail procurement consolidation. |
| Indian Spiral-Winding Capacity Buildout | Captures FSSAI plastic phase-out substitution demand in Maharashtra-Gujarat corridor. |
| Pharmaceutical Desiccant Integration | Positions paper cans for probiotic supplement primary packaging qualification. |
Methodological Framework
Multiple input streams — converter production data, brand owner procurement specifications, and regulatory filing analysis — were reconciled through bottom-up and top-down triangulation. Primary interviews engaged spiral-winding equipment manufacturers, barrier coating formulators, and sustainability compliance officers at multinational CPG brands. Secondary validation drew from ECHA REACH restriction updates, EU Packaging and Packaging Waste Regulation implementation guidance, and FSC chain-of-custody audit disclosures.
Data-stream reconciliation anchored volume and value outputs across product type, end-use industry, and regional regulatory cluster dimensions. CAGRs were derived from segment-level growth trajectory modeling. Forecast inputs incorporated EPR scheme expansion timelines and bio-based coating performance gap closure assumptions throughout the projection horizon.
The model holds under stable regulatory enforcement trajectories; deviation in REACH chemical restriction acceleration or Scandinavian pulp supply disruption would shift converter margin assumptions. Forecasts reflect documented assumptions around barrier technology adoption curves. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Waxed Paper Packaging Market
Paper & Paperboard Packaging
Coated Duplex Board Market
Paper & Paperboard Packaging
Folding Paperboard Boxes Market
Paper & Paperboard Packaging
China Corrugated Packaging Market
Paper & Paperboard Packaging
Paper Waste Strippers Market
Paper & Paperboard Packaging
Push-Pull Slip Sheets Market
Paper & Paperboard Packaging
Mottled Test Liner Market
Paper & Paperboard Packaging
Europe Paper Packaging Market
Paper & Paperboard Packaging
Decal Paper Market
Paper & Paperboard Packaging
Wrapping Paper Market
Paper & Paperboard Packaging
US Corrugated and Folding Boxboard Market
Paper & Paperboard Packaging
Insulated Paper Bags Market
Paper & Paperboard Packaging
SCK Paper Market
Paper & Paperboard Packaging
Binder's Board Market
Paper & Paperboard Packaging
Corrugated Packaging Market
Paper & Paperboard Packaging
Paperboard Container Market