
 China Corrugated Packaging Market | 2026-2036
China Corrugated Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
China Corrugated Packaging Market Outlook
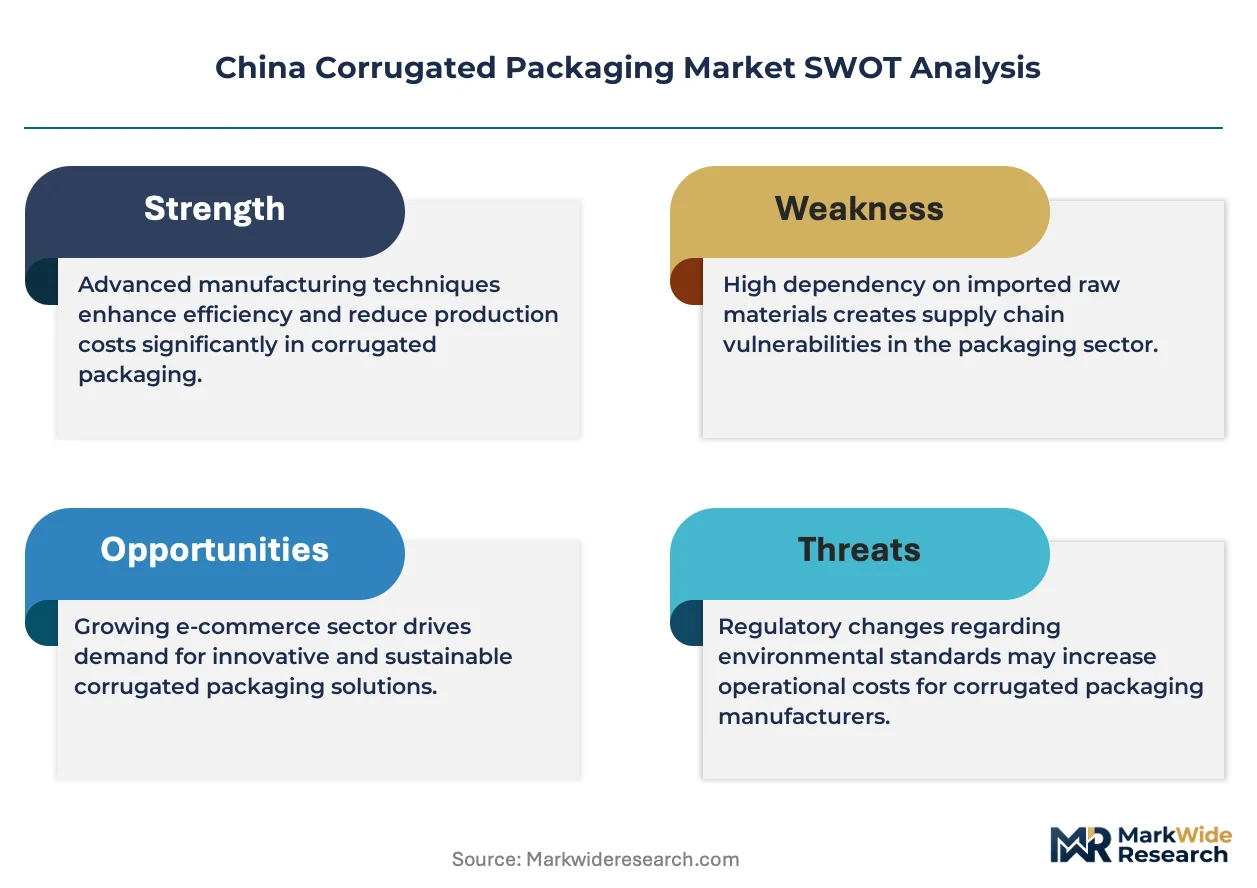
China's dual carbon goals is restructuring corrugated board manufacturing by mandating carbon intensity audits at integrated paper mills. Nine Dragons Paper Holdings Limited leverages captive pulp capacity to insulate feedstock costs across its Guangdong and Jiangsu complexes. Shanying Paper Co Limited anchors recycled linerboard output through proprietary de-inking systems at its Anhui facilities. HengFeng Packaging Materials Co Ltd specializes in moisture-resistant coating formulations for agricultural export trays.
Corrugated packaging consists of fluted paperboard sheets bonded between flat linerboards, typically constructed from kraft or recycled fibers in grammages ranging from 125 to 400 gsm, to provide compressive strength and cushioning during distribution. The product type dimension shows box formats dominating volume while pallet configurations capture premium margins from automotive and heavy machinery clients. Material segmentation reveals fluting grades experiencing fastest uptake as lightweighting protocols reduce board basis weights without sacrificing stackability. Application demand from e-commerce logistics outpaces traditional food and beverage channels, though cold-chain produce containers retain higher per-unit profitability.
SAMR enforces GB/T standards for corrugated board burst strength and edge crush resistance, while MEE implements wastewater discharge limits that elevate capital requirements at smaller mills. The central bank's green credit guidelines steer lending toward mills with certified waste heat recovery systems. Stakeholders must monitor how provincial carbon trading pilots in Guangdong and Hubei reshape mill location economics ahead of national scheme expansion.
Market Dynamics
China's dual carbon goals are compressing mill economics by mandating carbon intensity audits and waste heat recovery certification at integrated paper complexes, forcing asset-heavy producers to reconfigure energy sourcing or exit.
Growth Catalysts
- E-commerce logistics expansion:Tier-two city fulfillment centers are consuming box volumes at rates outpacing traditional retail channels, with JD Logistics and Cainiao Network driving format standardization for automated sortation.
- SAMR packaging standards:Mandatory GB/T certifications for burst strength and edge crush resistance are filtering out subscale converters, consolidating order flow toward certified integrated mills.
- Agricultural export protocols:Moisture-resistant coating specifications for cold-chain produce containers are capturing premium per-unit margins from Southeast Asian and Middle Eastern importers.
Market Restraints
- Recycled fiber cost volatility:Old corrugated container feedstock prices fluctuate with import quota restrictions under China's solid waste management regulations, compressing linerboard margins.
- Guangdong-Jiangsu supply concentration:Integrated capacity clusters in these provinces create geographic vulnerability to regional power rationing during peak demand seasons.
- Plastic substitution threat:Reusable plastic crates retain cost advantages in closed-loop automotive component logistics, limiting corrugated penetration in heavy machinery segments.
Strategic Opportunities
- Central China manufacturing corridor:Anhui and Hubei provinces offer lower carbon credit costs under provincial trading pilots, attracting mill relocation from coastal zones.
- Lightweighting technology convergence:Micro-fluting grades combined with nanocellulose reinforcement are enabling basis weight reductions without stackability loss, opening pharmaceutical and electronics applications.
- Green credit guidelines:The People's Bank of China's preferential lending rates for certified waste heat recovery systems are lowering capital costs for compliant producers.
Industry Challenges
- De-inking technician shortage:Proprietary recycled linerboard operations require skilled operators for contaminant removal systems, with talent concentrated at Shanying Paper and few training pipelines.
- MEE wastewater compliance timelines:Discharge limit upgrades demand 18-24 month capex cycles for biological treatment installations, straining smaller converters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Corrugated Packaging Market |
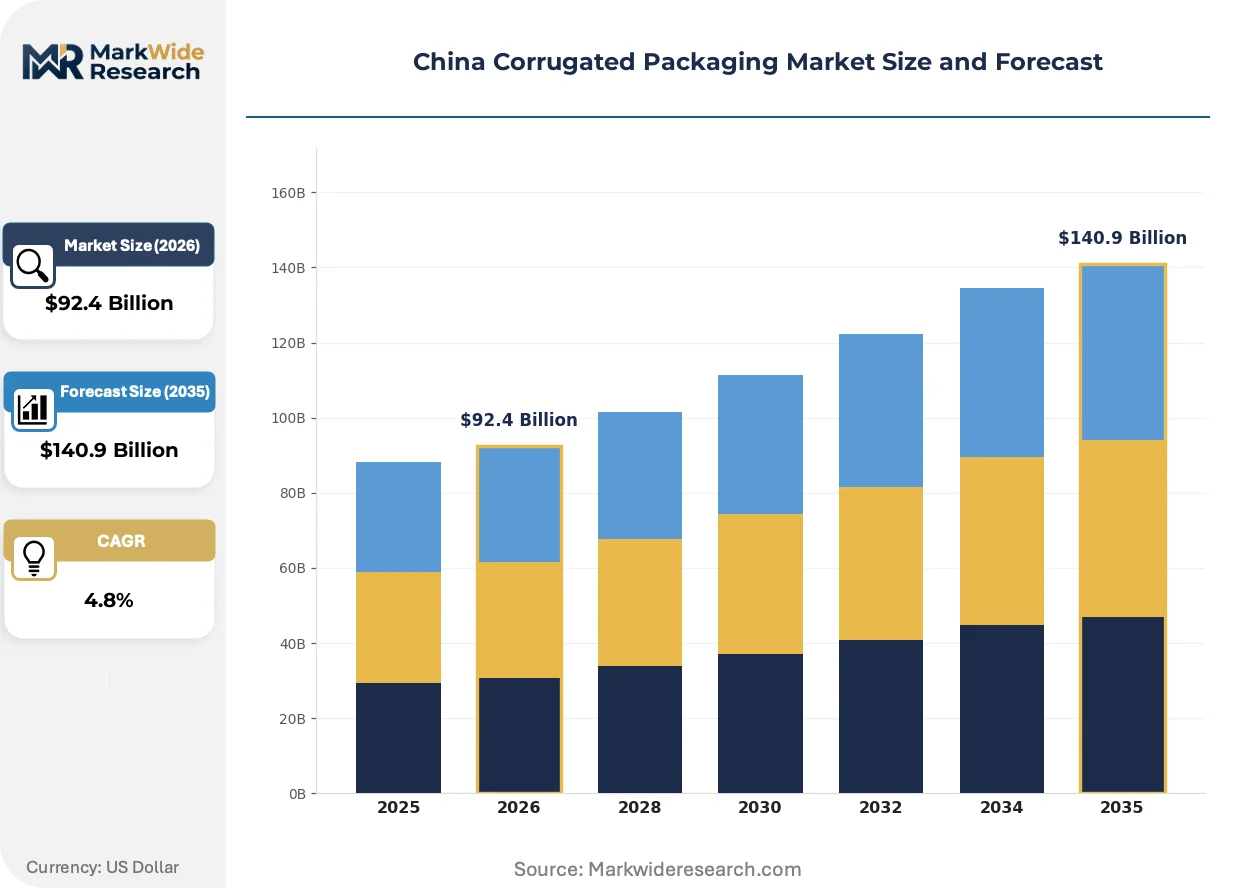
| Market Size in 2026 | $92.4 Billion |
| Market Size in 2035 | $140.9 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Box, Container, Tray, Pallet Material: Fluting, Liner, Coating, Adhesive Application: Food & Beverage, Electronics, Consumer Goods, Healthcare End User: Retail, E-commerce, Manufacturing, Logistics |
| Companies Covered | Shanghai DE Printed Box, Hung Hing Printing Group Limited, Nine Dragons Paper Holdings Limited, Yison Packaging, PackCCP, Shanying Paper Co Limited, HengFeng Packaging Materials Co Ltd, TessPack, Belpax, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Corrugated Packaging Market Strategic Shifts
Digital print integration and automated converting lines are compressing order minimums and lead times, enabling corrugated producers to compete with folding carton specialists in short-run branded packaging.
Micro-fluting technology is rewriting board engineering specifications by substituting E-flute and F-flute profiles for traditional C-flute in e-commerce shipper applications. Electronics and cosmetics brands are specifying these grades for unboxing experience differentiation. The structural consequence is compressing material costs per unit while maintaining protective performance.
MEE wastewater discharge limits are forcing capital deployment toward anaerobic digestion and membrane bioreactor systems at mills below 200,000 tonne annual capacity. Smaller converters in Zhejiang and Fujian are consolidating or exiting rather than absorbing compliance costs. The segment most affected is independent sheet plants without integrated pulping, which are outsourcing to certified regional suppliers.
Brand-direct procurement models are displacing traditional distributor networks in the Yangtze River Delta manufacturing belt. E-commerce platforms and consumer goods multinationals are negotiating annual volume contracts directly with Nine Dragons and Shanying, bypassing regional traders. This pattern is most visible in Shanghai and Suzhou, where logistics operators demand real-time order tracking and 48-hour turnaround guarantees.
China Corrugated Packaging Market Segmentation
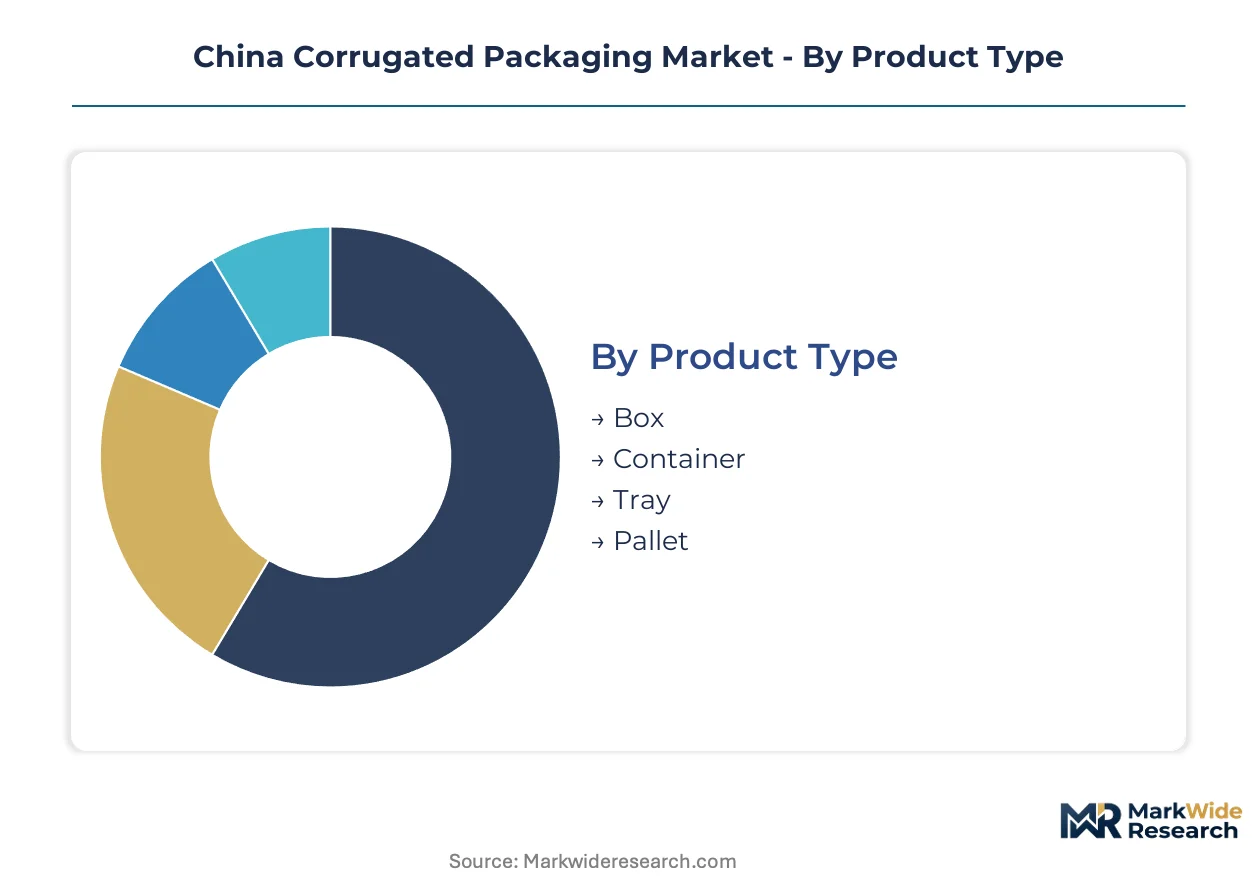
Segmentation in China's corrugated packaging market reveals how supply chain concentration and regulatory pressure concentrate margin capture. Understanding these divisions exposes where capital deployment and certification requirements create competitive moats.
Product Type:
Supply concentration in Guangdong and Jiangsu provinces dictates which formats achieve scale economics first.
- Box:Constructed from fluted paperboard bonded between linerboards in grammages from 125 to 400 gsm. E-commerce logistics operators in tier-two cities are consuming box volumes at rates outpacing traditional retail channels, with JD Logistics and Cainiao Network driving format standardization for automated sortation.
- Container:Heavy-duty corrugated enclosures designed for bulk transport and warehousing applications. Cold-chain produce containers for Southeast Asian and Middle Eastern importers retain higher per-unit profitability due to moisture-resistant coating specifications.
- Tray:Shallow formats for agricultural export and retail display. HengFeng Packaging Materials Co Ltd specializes in moisture-resistant formulations for this segment.
- Pallet:Load-bearing platforms for automotive and heavy machinery clients. Reusable plastic crates retain cost advantages in closed-loop automotive component logistics, limiting corrugated penetration here.
Today's leader: Box. Tomorrow's challenger: Container.
Material:
Cost tier differentiation separates integrated mills with captive pulp from converters dependent on spot fiber markets.
- Fluting:The corrugated middle layer providing compressive strength. Micro-fluting grades combined with nanocellulose reinforcement are enabling basis weight reductions without stackability loss, opening pharmaceutical and electronics applications.
- Liner:Flat outer and inner facing sheets, typically kraft or recycled fiber. Nine Dragons Paper Holdings Limited leverages captive pulp capacity to insulate feedstock costs across its Guangdong and Jiangsu complexes.
- Coating:Surface treatments for moisture resistance and printability. Agricultural export protocols specify these for premium margins from tropical climate destinations.
- Adhesive:Bonding agents for flute-to-liner attachment. Starch-based formulations dominate, with synthetic alternatives capturing niche high-humidity applications.
Volume concentrates in Liner. Margin expansion potential sits with Fluting.
Application:
Customer type stratification shows e-commerce platforms displacing traditional distributor networks in the Yangtze River Delta.
- Food & Beverage:Traditional volume anchor for corrugated consumption. SAMR enforces GB/T standards for burst strength and edge crush resistance that filter out subscale converters.
- Electronics:High-value goods demanding precision-fit protection. Micro-fluting technology is substituting E-flute and F-flute profiles for traditional C-flute in shipper applications, with brands specifying these grades for unboxing experience differentiation.
- Consumer Goods:Mid-tier volume with seasonal fluctuation. Brand-direct procurement models are displacing traditional distributor networks, with multinationals negotiating annual volume contracts directly with integrated mills.
- Healthcare:Regulated applications requiring contamination control. This segment demands certified production environments that smaller converters cannot maintain.
Food & Beverage holds volume dominance. Electronics commands the steepest expansion trajectory.
End User:
Geographic maturity separates coastal logistics hubs from inland manufacturing corridors where provincial carbon trading pilots reshape location economics.
- Retail:Traditional brick-and-mortar distribution. Format standardization here lags e-commerce specifications, compressing margin capture.
- E-commerce:Automated fulfillment driving box innovation. Real-time order tracking and 48-hour turnaround guarantees in Shanghai and Suzhou favor certified integrated suppliers.
- Manufacturing:Industrial component and finished goods packaging. Anhui and Hubei provinces offer lower carbon credit costs under provincial trading pilots, attracting mill relocation from coastal zones.
- Logistics:Third-party operators consolidating multi-client volumes. MEE wastewater discharge limits strain smaller converters without integrated pulping, forcing consolidation toward certified regional suppliers.
E-commerce anchors growth. Manufacturing offers relocation arbitrage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled de-inking technicians cluster at integrated mills in Anhui and Jiangsu provinces, creating geographic bottlenecks that constrain recycled linerboard expansion across interior manufacturing corridors.
Guangdong Province
JD Logistics and Cainiao Network fulfillment centers in Guangzhou and Shenzhen consume box volumes at rates outpacing traditional retail channels. SAMR enforces GB/T standards for burst strength that filter subscale converters from the Pearl River Delta supply base. Nine Dragons Paper Holdings Limited leverages captive pulp capacity across Jiangmen and Dongguan complexes to insulate feedstock costs.
Jiangsu Province
Automated sortation facilities in Suzhou and Wuxi drive format standardization for e-commerce logistics operators. The central bank's green credit guidelines steer lending toward mills with certified waste heat recovery systems in this coastal cluster. Brand-direct procurement models here displace traditional distributor networks, with multinationals negotiating annual volume contracts directly with integrated suppliers.
Anhui Province
Lower carbon credit costs under provincial trading pilots attract mill relocation from coastal zones. Shanying Paper Co Limited anchors recycled linerboard output through proprietary de-inking systems at facilities in Ma'anshan. This interior corridor offers manufacturing cost arbitrage for agricultural export tray producers serving Southeast Asian cold-chain destinations.
Hubei Province
Wuhan logistics operators consolidate multi-client volumes for pharmaceutical and electronics applications requiring precision-fit protection. Provincial carbon trading pilots reshape location economics ahead of national scheme expansion. MEE wastewater discharge limits strain smaller converters without integrated pulping, forcing consolidation toward certified regional suppliers.
Zhejiang Province
Digital print integration and automated converting lines in Hangzhou and Ningbo compress order minimums for short-run branded packaging. MEE wastewater discharge limit upgrades demand capital deployment toward anaerobic digestion systems. Independent sheet plants here are outsourcing to certified regional suppliers rather than absorbing compliance costs.
China Corrugated Packaging Market Competitive Environment
Capital-heavy producers compete with asset-light designers across China's corrugated packaging sector. Integrated paper mills with captive pulp capacity dominate volume supply, while specialized converters capture premium margins in moisture-resistant and micro-fluting applications. The vendor base separates into three archetypes: state-linked giants with backward fiber control, mid-tier regional specialists with proprietary coating formulations, and asset-light digital converters serving short-run branded orders. Dominant competitive moves include geographic relocation toward interior provinces with favorable carbon credit costs and technology licensing partnerships for lightweighting protocols.
Among Hong Kong-listed paper conglomerates, Nine Dragons Paper Holdings Limited and Shanying Paper Co Limited exemplify the integrated mill archetype with captive pulp strategies. HengFeng Packaging Materials Co Ltd occupies a position within the specialized converter tier, representing coating technology differentiation for agricultural export applications. These three entities anchor distinct competitive vectors across the Yangtze River Delta and Pearl River Delta manufacturing belts.
| Leading Market Players |
|---|
| Shanghai DE Printed Box |
| Hung Hing Printing Group Limited |
| Nine Dragons Paper Holdings Limited |
| Yison Packaging |
| PackCCP |
| Shanying Paper Co Limited |
| HengFeng Packaging Materials Co Ltd |
| TessPack |
| Belpax |
| Others |
Value Chain & Pricing Dynamics
Old corrugated container feedstock prices cascade through China's corrugated packaging supply chain, compressing linerboard margins at non-integrated converters while integrated mills with captive pulp capacity maintain pricing power across premium and standard tiers.
Pricing Analysis
Bundled design-to-delivery contracts command premium positioning against unbundled board-only transactions. Pricing stratifies across certified integrated mills, regional converters with SAMR compliance, and spot-market sheet plants. Cost compression in the standard tier is intensifying because recycled fiber import quotas under China's solid waste management regulations constrain feedstock availability. Third-party logistics operators exhibit highest price sensitivity, while pharmaceutical and electronics brands prioritize performance specifications over unit cost.
Supply Chain Analysis
Direct-to-brand procurement channels handle hyperscale e-commerce demand from JD Logistics and Cainiao Network, bypassing traditional distributor networks. Geographic supply concentration centers on Guangdong, Jiangsu, and Anhui provinces where integrated complexes cluster. Raw material dependencies draw from domestic recycled fiber collections, imported OCC quotas, and captive kraft pulp production. Single-source vulnerability exists in proprietary de-inking technician talent concentrated at Shanying Paper's Ma'anshan facilities. Distribution runs through certified regional suppliers consolidating volumes from independent sheet plants exiting due to MEE wastewater compliance costs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's corrugated packaging market functions as a geographic-arbitrage play where Anhui and Hubei provinces offer lower carbon credit costs under provincial trading pilots compared to coastal manufacturing clusters, attracting mill relocation and cost-competitive positioning.
For Market Incumbents: Anticipate plastic substitution threats in closed-loop automotive logistics by deepening moisture-resistant coating R&D for agricultural export applications. Secure backward integration into captive pulp capacity or waste heat recovery certification to defend margin position against MEE wastewater discharge upgrades. Prioritize technician training pipelines to address de-inking operator scarcity constraining recycled linerboard expansion.
For New Entrants and Emerging Players: Begin with micro-fluting technology licensing partnerships targeting electronics and cosmetics brands demanding unboxing experience differentiation. White-space opportunities sit in pharmaceutical cold-chain containers requiring certified production environments. Pursue brand-direct procurement relationships with Yangtze River Delta logistics operators seeking 48-hour turnaround guarantees.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized converters possessing proprietary coating formulations and nanocellulose reinforcement capabilities. Long-term viability over the projection horizon favors asset-light digital converters serving short-run branded orders with automated converting lines. Monitor provincial carbon trading pilot expansion as inflection indicator for mill relocation economics and acquisition timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Mill Relocation to Central China | Anhui and Hubei carbon credit arbitrage lowers operating costs for integrated producers. |
| Waste Heat Recovery Certification | People's Bank of China green credit guidelines reduce capital costs for compliant mills. |
| Micro-Fluting Technology Licensing | Nanocellulose reinforcement enables basis weight reduction for electronics applications. |
| Brand-Direct Procurement Partnerships | Multinationals in Shanghai and Suzhou bypass distributors for volume contract security. |
| Proprietary De-Inking System Investment | Shanying Paper's contaminant removal technology anchors recycled linerboard output expansion. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with paper mill operations directors, e-commerce logistics procurement managers, SAMR regulatory compliance officers, and agricultural export packaging specialists with secondary validation from customs trade data, SEC filings of Hong Kong-listed paper conglomerates, MEE discharge limit documentation, and provincial carbon trading pilot records. Bottom-up capacity assessments and top-down demand modeling triangulated volume estimates.
Segment-weighting approaches distributed value across product type, material grade, application channel, and end-user geography dimensions throughout the forecast period. CAGRs derived from historical trajectory analysis and forward-looking regulatory impact assessment incorporated dual carbon goal compliance timelines, e-commerce fulfillment center expansion pipelines, and lightweighting technology adoption curves.
Several conditions sit outside the modeled scope, including unannounced provincial carbon trading scheme expansions, abrupt OCC import quota adjustments, and breakthrough plastic substitution technologies in closed-loop logistics. Forecasts reflect assumptions about SAMR enforcement consistency and MEE compliance timeline adherence. Periodic stress-testing of base assumptions against wastewater upgrade capital deployment rates and technician training pipeline development is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Freezer Paper Market
Paper & Paperboard Packaging
Europe Mailer Packaging Market
Paper & Paperboard Packaging
Corrugated Packaging Market
Paper & Paperboard Packaging
Kraft Paper Mailer Market
Paper & Paperboard Packaging
Asia Pacific Paper Packaging Market
Paper & Paperboard Packaging
Shredded Paper Filler Market
Paper & Paperboard Packaging
Non-Tacky Transfer Paper Market
Paper & Paperboard Packaging
Paper Cup Lids Market
Paper & Paperboard Packaging
Coated White Board Paper Market
Paper & Paperboard Packaging
Coated Duplex Board Market
Paper & Paperboard Packaging
Paper Packaging Market
Paper & Paperboard Packaging
Industrial Paper Sacks Market
Paper & Paperboard Packaging
Kraft Bubble Mailers Market
Paper & Paperboard Packaging
Paper Cups Market
Paper & Paperboard Packaging
Chipboard Box Market
Paper & Paperboard Packaging
Paperboard Mailer Market