
 Push-Pull Slip Sheets Market | 2026-2036
Push-Pull Slip Sheets Market Size, Share, and Industry Trends Forecast 2026-2036
Push-Pull Slip Sheets Market Analytics
Consolidation among food and beverage distributors is restructuring procurement patterns for unit-load handling equipment. WestRock Company leverages its integrated paperboard supply chain to dominate North American slip sheet production. Smurfit Kappa Group anchors European demand through its corrugated packaging network and specialized logistics solutions. Georgia-Pacific LLC competes on manufacturing scale across multiple substrate grades for push-pull applications.
Push-pull slip sheets are thin, flat platforms—typically manufactured from kraft paperboard, oriented polypropylene, or fiber-reinforced composites—that engage with push-pull forklift attachments to move unitized loads without pallet understructure. Paper-grade slip sheets generally range from 0.5 to 2.0 mm in caliper and incorporate anti-slip coatings or laminated layers to withstand shear forces during loading. The warehousing application commands the largest volume share as e-commerce fulfillment centers adopt slip sheets to maximize cube utilization in containerized shipping. Composite substrates represent the fastest-growing product category, capturing margin pools in pharmaceutical and electronics logistics where moisture resistance and dimensional stability justify premium positioning over standard paper alternatives.
OSHA guidelines in the United States mandate operator training for push-pull attachment systems, directly influencing equipment purchase decisions and aftermarket service contracts. The EU F-Gas Regulation and broader CSRD reporting requirements are pressuring logistics operators to document carbon reductions from pallet elimination programs, creating compliance-driven demand for certified sustainable slip sheet suppliers. Stakeholders must monitor how ISO 18616 pallet-free handling standards evolve across member bodies, as harmonized test methods for slip sheet load capacity would reshape supplier qualification criteria and regional competitive dynamics.
Market Dynamics
Consolidation among food and beverage distributors is compressing procurement cycles for unit-load handling equipment, while the EU Green Deal and REACH regulations mandate pallet elimination programs that favor recyclable paper-based alternatives over wooden infrastructure.
Growth Catalysts
- REACH chemical safety mandates:European chemical exporters face compliance deadlines for sustainable packaging, accelerating substitution of wooden pallets with fiber-reinforced slip sheets in cross-border distribution networks.
- Cold-chain logistics expansion:Food and beverage manufacturers operating frozen storage facilities are standardizing push-pull systems to eliminate moisture-absorbing wooden pallets that degrade in sub-zero environments.
- Composite substrate innovation:Oriented polypropylene formulations with anti-slip laminates are penetrating pharmaceutical logistics where dimensional stability under humidity stress is non-negotiable.
Market Restraints
- Kraft pulp price volatility:Input cost swings for unbleached paperboard compress margins for commodity-grade slip sheet producers serving price-sensitive warehousing segments.
- Attachment equipment concentration:Push-pull forklift system manufacturing clusters in Germany and the United States create supply vulnerability for logistics operators in peripheral markets seeking localized service support.
- Load capacity limitations:Paper-grade calipers below 1.0 mm face structural failure thresholds above 1,500 kg that block adoption in heavy machinery and bulk chemical export applications.
Strategic Opportunities
- India pharmaceutical cold chain:CDSCO temperature-controlled distribution mandates for biologics create first-mover advantage for moisture-resistant composite slip sheet suppliers establishing local converting partnerships.
- CSRD carbon reporting requirements:EU logistics operators must document Scope 3 reductions from pallet elimination, creating certified supplier qualification premiums for sustainable slip sheet producers.
- E-commerce fulfillment automation:Robotic layer-picking systems in automated warehouses favor standardized flat load platforms over variable-height pallet stacks, enabling slip sheet integration with AMR fleets.
Industry Challenges
- OSHA operator certification bottlenecks:Push-pull attachment training mandates in the United States extend equipment commissioning timelines and inflate aftermarket service contract costs for multi-site fleet operators.
- ISO 18616 harmonization delays:Divergent national test methods for slip sheet load capacity across member bodies fragment supplier qualification criteria and complicate cross-border procurement standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Push-Pull Slip Sheets Market |
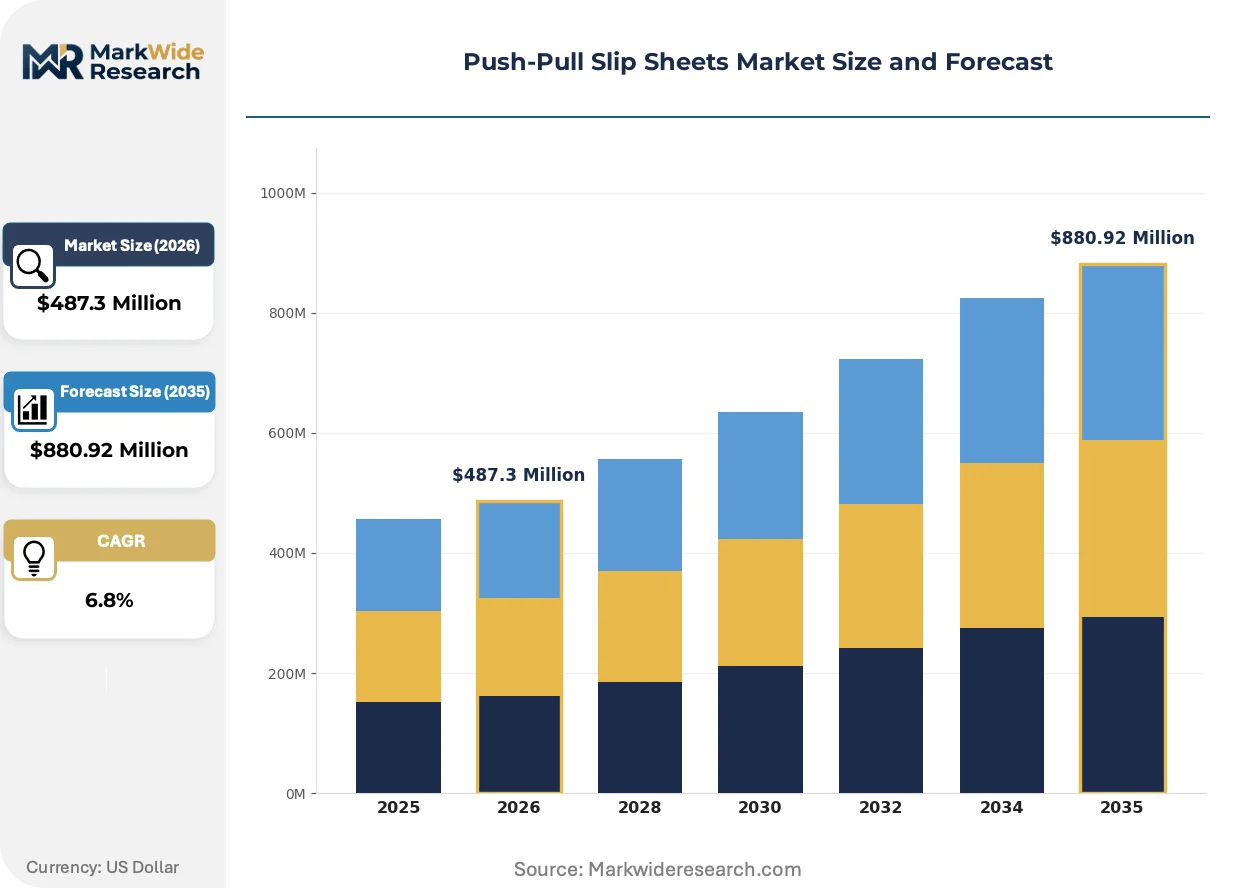
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic, Paper, Composite, Metal End User: Retail, Manufacturing, Food & Beverage, Logistics Application: Warehousing, Shipping, Handling, Storage Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | WestRock Company, Meyer Steel Drum Co., International Paper Company, Elsons International, PAC Global, Smurfit Kappa Group, Greif, Inc., Georgia-Pacific LLC, Sonoco Products Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Push-Pull Slip Sheets Market Evolving Landscape
Material science advances and regulatory carbon accounting are converging to restructure competitive advantage around substrate performance certification rather than unit cost alone.
Fiber-reinforced composite slip sheets incorporating glass or aramid scrim layers are modularizing load platform architecture for pharmaceutical and electronics logistics. Cold-chain operators in Germany and the Netherlands are adopting these substrates fastest, compressing the performance gap between paper-based economy grades and premium plastic alternatives while enabling thinner calipers at equivalent strength ratings.
EU F-Gas Regulation phase-down schedules for hydrofluorocarbon refrigerants are indirectly accelerating slip sheet adoption by forcing cold-store operators to maximize cube density in existing insulated envelopes. Warehouse designers in Belgium and Denmark are specifying push-pull systems to recover pallet storage height, responding to real estate constraints and energy cost pressures simultaneously.
Consolidated food and beverage distributors are unbundling after-sales service contracts from equipment procurement, treating push-pull attachment maintenance as a separate spend category. This behavior shift is most visible in the United States, where third-party logistics providers now negotiate slip sheet supply agreements independent of forklift OEM service networks, fragmenting historical bundled relationships and opening direct supplier channels.
Push-Pull Slip Sheets Market Segmentation
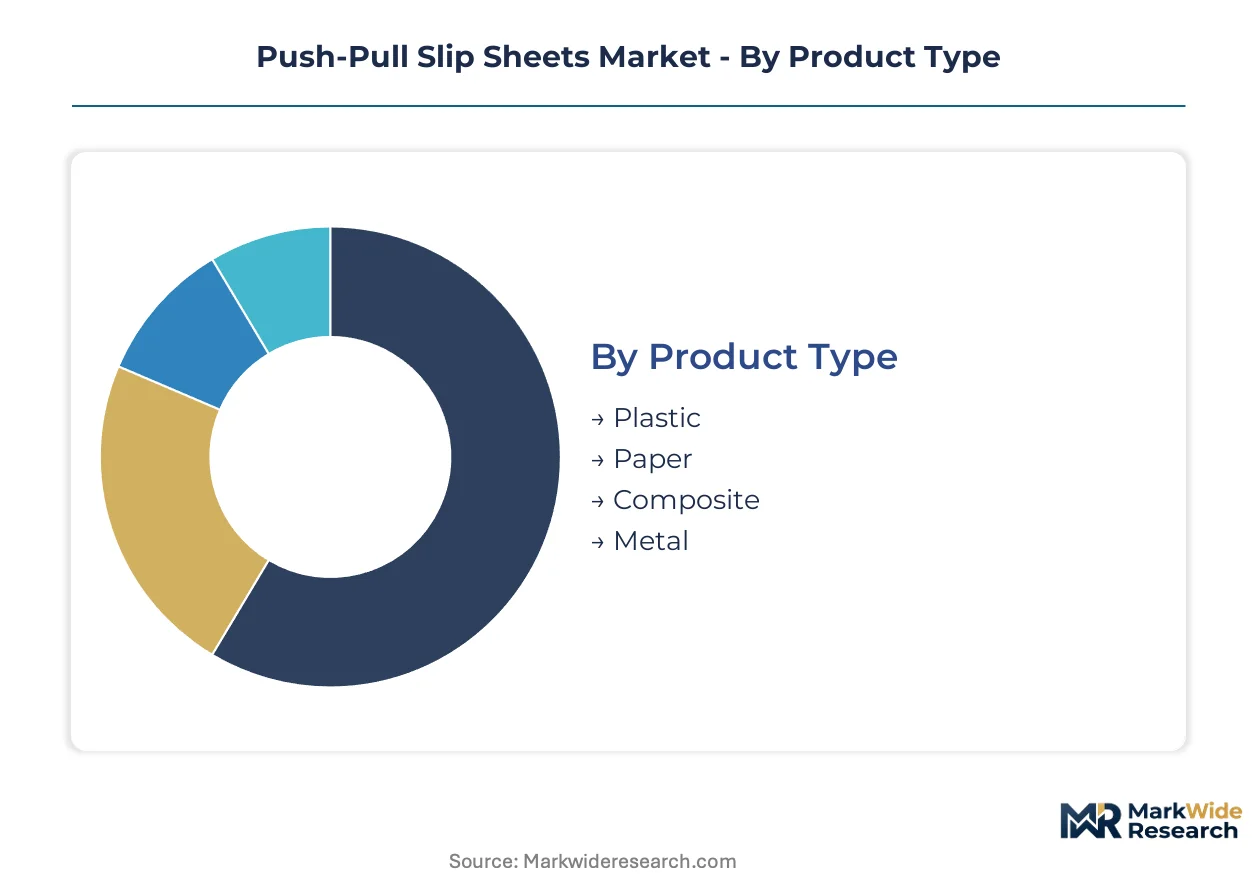
Substrate selection and handling application dictate capital deployment patterns across the push-pull slip sheets market. Procurement teams align material specifications with load requirements, regulatory mandates, and total cost of ownership calculations.
Product Type:
Paper-based platforms demand the heaviest upfront investment in pulping and coating infrastructure, while composite formulations require specialized lamination and fiber-reinforcement equipment.
- Paper:Kraft paperboard calipers from 0.5 to 2.0 mm incorporate anti-slip coatings or laminated layers to withstand shear forces during push-pull loading. Food and beverage manufacturers in Germany are standardizing these for cold-chain logistics to replace moisture-absorbing wooden pallets in sub-zero environments.
- Composite:Fiber-reinforced substrates with glass or aramid scrim layers modularize load platform architecture for pharmaceutical and electronics logistics. Cold-chain operators in the Netherlands are adopting these fastest, compressing the performance gap between paper economy grades and premium plastic alternatives.
- Plastic:Oriented polypropylene formulations with anti-slip laminates penetrate pharmaceutical logistics where dimensional stability under humidity stress is non-negotiable.
- Metal:Aluminum and steel variants serve heavy machinery export applications where paper-grade calipers face structural failure thresholds above 1,500 kg.
Most installed capacity flows through Paper. Expansion is steepest in Composite.
End User:
Volume concentration varies sharply by sector, with food and beverage distributors consolidating procurement cycles fastest while logistics operators fragment across third-party service tiers.
- Food & Beverage:Frozen storage facilities are eliminating wooden pallets that degrade in sub-zero environments. EU Green Deal and REACH regulations mandate pallet elimination programs that favor recyclable paper-based alternatives across German and Belgian distribution networks.
- Logistics:Third-party providers in the United States now negotiate slip sheet supply agreements independent of forklift OEM service networks, fragmenting historical bundled relationships and opening direct supplier channels.
- Manufacturing:Automotive and chemical exporters in Germany are standardizing push-pull handling systems across distribution networks to comply with cross-border sustainable packaging mandates.
- Retail:E-commerce fulfillment centers adopt slip sheets to maximize cube utilization in containerized shipping, with robotic layer-picking systems favoring standardized flat load platforms over variable-height pallet stacks.
Food & Beverage commands the largest procurement volume. Logistics is gaining share fastest through third-party provider expansion.
Application:
Handling intensity and automation compatibility determine substrate durability requirements and attachment system specifications.
- Warehousing:E-commerce fulfillment automation drives adoption as robotic layer-picking systems integrate with AMR fleets using standardized flat load platforms.
- Shipping:Containerized export applications prioritize cube density maximization, with Belgian and Danish warehouse designers specifying push-pull systems to recover pallet storage height.
- Handling:Push-pull forklift attachments require operator certification under OSHA guidelines in the United States, extending equipment commissioning timelines for multi-site fleet operators.
- Storage:Cold-store operators facing EU F-Gas Regulation phase-down schedules maximize cube density in existing insulated envelopes, indirectly accelerating slip sheet adoption.
Warehousing absorbs the highest unit volume. Shipping is climbing the fastest as container optimization pressures intensify.
Distribution Channel:
Channel selection reflects customer scale, technical support requirements, and integration complexity with existing material handling systems.
- Distributors:Integrated corrugated packaging networks anchor European demand through specialized logistics solutions and regional converting partnerships.
- Direct Sales:Large food and beverage distributors unbundle after-sales service contracts from equipment procurement, treating push-pull attachment maintenance as a separate spend category.
- Wholesalers:Price-sensitive warehousing segments in peripheral markets source commodity-grade slip sheets through wholesale channels, exposing margins to kraft pulp price volatility.
- Online Retail:Standardized product configurations with documented load capacity ratings enable digital procurement for smaller logistics operators seeking rapid fulfillment.
Distributors handle the majority of transaction volume. Direct Sales is expanding most quickly among consolidated end users.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany outpaces France in push-pull slip sheet adoption for automotive logistics, while the United States concentrates warehousing demand among third-party fulfillment operators. Belgium and the Netherlands maximize cube density in cold-storage retrofit projects. India's pharmaceutical cold chain emerges as a priority expansion target.
Germany
Automotive and chemical exporters standardize push-pull handling systems across distribution networks to comply with cross-border sustainable packaging mandates. REACH chemical safety deadlines accelerate substitution of wooden pallets with fiber-reinforced slip sheets. The Rhine-Ruhr industrial corridor anchors manufacturing scale for kraft paperboard converting operations serving pan-European logistics networks.
United States
E-commerce fulfillment centers adopt slip sheets to maximize cube utilization in containerized shipping, with robotic layer-picking systems favoring standardized flat load platforms. OSHA guidelines mandate operator training for push-pull attachment systems, directly influencing equipment purchase decisions. The Chicago-Milwaukee corridor concentrates warehousing automation investment among third-party logistics providers.
Belgium
Cold-store operators facing EU F-Gas Regulation phase-down schedules maximize cube density in existing insulated envelopes, indirectly accelerating slip sheet adoption. Warehouse designers specify push-pull systems to recover pallet storage height, responding to real estate constraints and energy cost pressures simultaneously. The Port of Antwerp-Bruges logistics cluster standardizes paper-grade slip sheets for cross-dock operations serving German automotive supply chains.
Netherlands
Cold-chain operators adopt fiber-reinforced composite substrates fastest, compressing the performance gap between paper-based economy grades and premium plastic alternatives. The EU Green Deal mandates pallet elimination programs that favor recyclable paper-based alternatives over wooden infrastructure. The Rotterdam-The Hague logistics corridor concentrates pharmaceutical distribution facilities requiring moisture-resistant load platforms.
India
CDSCO temperature-controlled distribution mandates for biologics create first-mover advantage for moisture-resistant composite slip sheet suppliers establishing local converting partnerships. The country's national pharmaceutical regulator enforces strict cold-chain compliance for vaccine and biologic distribution. The Mumbai-Pune pharmaceutical belt concentrates demand for dimensional stability in high-humidity storage environments.
Push-Pull Slip Sheets Market Competitive Landscape
North American producers anchor one tier; European specialists hold integrated corrugated networks that dominate regional procurement channels. The vendor base splits between paperboard conglomerates with captive pulp supply and independent converters serving price-sensitive warehousing segments. Three archetypes prevail: integrated packaging conglomerates, steel drum fabricators diversifying into flat load platforms, and regional paperboard specialists. Capacity expansion and backward integration into kraft pulping represent the dominant competitive moves.
Within the integrated packaging tier, WestRock Company and International Paper Company exemplify scale-driven producers with captive paperboard supply chains. Georgia-Pacific LLC occupies a position among North American conglomerates competing across multiple substrate grades. Smurfit Kappa Group anchors European demand through its corrugated packaging network and specialized logistics solutions. Meyer Steel Drum Co. represents industrial container fabricators extending product portfolios into load-handling equipment adjacent categories.
| Leading Market Players |
|---|
| WestRock Company |
| Meyer Steel Drum Co. |
| International Paper Company |
| Elsons International |
| PAC Global |
| Smurfit Kappa Group |
| Greif, Inc. |
| Georgia-Pacific LLC |
| Sonoco Products Company |
| Others |
Value Network & Pricing Analysis
Kraft pulp cost volatility cascades through North American and European converting operations, compressing margins for commodity-grade slip sheet producers while reinforcing pricing power among integrated paperboard conglomerates with captive fiber supply.
Pricing Analysis
Capacity additions in Germany and the United States are reshaping price floors for paper-grade slip sheets as regional converters expand kraft paperboard output. Three-tier pricing structure across premium, standard, and economy levels stratifies by substrate certification grade and volume commitment scale. Pricing pressure stems from kraft pulp futures volatility, which squeezes converters serving price-sensitive warehousing segments. Third-party logistics providers exhibit highest price sensitivity due to unbundled procurement of slip sheets from forklift service contracts, while pharmaceutical cold-chain operators tolerate premium positioning for moisture-resistant composite grades.
Supply Chain Analysis
Freight cost differentials between containerized pulp imports and regional converting capacity anchor supply chain configuration decisions across the market. Manufacturing concentrates in Germany, the United States, and the Netherlands, with the Rhine-Ruhr corridor and Chicago-Milwaukee corridor anchoring integrated paperboard production. Raw material dependencies center on unbleached softwood kraft pulp, oriented polypropylene resin, and glass fiber scrim. Single-source vulnerability exists for specialized anti-slip coating chemistries subject to REACH registration requirements. Distribution runs through integrated corrugated packaging networks in Europe and direct sales channels among consolidated North American food and beverage distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH chemical safety mandates in Europe and OSHA certification requirements in the United States create a geographic-arbitrage opportunity for suppliers able to leverage regulatory compliance as a pricing wedge across jurisdictions.
For Market Incumbents: To counter margin compression from kraft pulp volatility, WestRock and Smurfit Kappa should deepen backward integration into regional kraft pulping capacity and lock long-term fiber supply agreements. Certification investment in ISO 18616 load capacity testing protocols defends supplier qualification status against emerging composite substrate specialists. For New Entrants and Emerging Players: CDSCO cold-chain mandates in India open a window for moisture-resistant composite slip sheet suppliers establishing local converting partnerships with Mumbai-Pune pharmaceutical distributors. Target India's biologics distribution infrastructure through joint ventures with existing corrugated packaging converters rather than greenfield manufacturing. For Investors and Strategic Acquirers: Roll-up economics work for regional paperboard specialists with established forklift OEM service relationships because third-party logistics providers are unbundling procurement and fragmenting historical bundled channels. Monitor CSRD carbon reporting adoption rates among EU logistics operators as the inflection signal for sustainable slip sheet supplier premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Kraft Pulping | Captive fiber supply insulates margin compression from commodity pulp futures volatility. |
| ISO 18616 Certification Investment | Harmonized load capacity testing protocols qualify suppliers for cross-border automotive distribution networks. |
| Composite Substrate R&D Partnership | Glass and aramid scrim innovation penetrates pharmaceutical cold-chain applications requiring humidity resistance. |
| Direct Sales Channel Expansion | Unbundled procurement patterns among consolidated food and beverage distributors bypass forklift OEM service networks. |
| India Local Converting Partnership | CDSCO biologics mandates create first-mover positioning in high-humidity pharmaceutical storage environments. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with plant managers at kraft paperboard converters, procurement leads at third-party logistics providers, aftermarket service heads at forklift OEMs, and regulatory affairs specialists at pharmaceutical distributors with secondary validation. Secondary sources included customs and trade data for pulp and paperboard flows, SEC 10-K filings from integrated packaging conglomerates, ECHA REACH registration databases, and OSHA compliance documentation. Bottom-up volume modeling triangulated against top-down macroeconomic indicators across substrate grades and end-use segments.
Segment-weighted projections applied distinct growth assumptions by product type, end user, and application across the analysis window. Modeled dimensions included substrate material, handling intensity, automation compatibility, and regional regulatory cluster. CAGRs derived from historical shipment data, capacity utilization rates at converting facilities, and substitution elasticity estimates for pallet-free handling systems. Forecast inputs incorporated EU F-Gas Regulation phase-down schedules and CDSCO cold-chain enforcement timelines.
Revisions become necessary when REACH chemical safety mandates expand scope, OSHA pushes additional operator certification requirements, or kraft pulp futures experience sustained volatility beyond historical bands. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
MAP Trays Market
Paper & Paperboard Packaging
Coated Recycled Boxboard Market
Paper & Paperboard Packaging
Kraftliner Market
Paper & Paperboard Packaging
Italy Paper Packaging Market
Paper & Paperboard Packaging
Fluting Paper Market
Paper & Paperboard Packaging
North America Paper Cone Market
Paper & Paperboard Packaging
Tracing Paper Market
Paper & Paperboard Packaging
Beverage Filter Paper Market
Paper & Paperboard Packaging
Paper Packaging Market
Paper & Paperboard Packaging
Paper Bottles Market
Paper & Paperboard Packaging
Cold Seal Paper Market
Paper & Paperboard Packaging
Greyboard Market
Paper & Paperboard Packaging
Envelope Market
Paper & Paperboard Packaging
Qatar Paper Packaging Products Market
Paper & Paperboard Packaging
Masking Paper Market
Paper & Paperboard Packaging
Paperboard Clamshell Boxes Market