
 Paper Waste Strippers Market | 2026-2036
Paper Waste Strippers Market Size, Share, and Industry Trends Forecast 2026-2036
Paper Waste Strippers Market Analytics
Buyer concentration among large packaging converters is expanding as regional printers consolidate procurement through centralized equipment budgets. Heidelberg leverages its integrated press-to-finishing workflow to capture multi-unit orders from consolidated buyers. Bobst Group sustains technology leadership through precision stripping modules engineered for high-speed carton lines. Valco Melton competes on adhesive control systems that reduce substrate damage during waste separation.
Paper waste strippers are mechanical devices that remove die-cut blanks, trim, and matrix waste from printed sheets or rolls, typically operating at speeds between 8,000 and 15,000 sheets per hour with vacuum-assisted extraction or pin-based registration systems. Automatic strippers now dominate new installations as labor costs and throughput requirements rise across folding carton operations. Manual and portable strippers retain share in educational institutions and small-format print shops where capital constraints limit automation investment. Semi-automatic units occupy a narrowing mid-market position as buyers polarize between low-cost manual options and fully integrated automatic systems.
EPA standards for municipal recycling contamination directly shape equipment specifications, requiring strippers to achieve cleaner separation of adhesives, films, and coatings from fiber waste streams. OSHA machine guarding regulations mandate interlocked access panels and emergency stop protocols on automatic units sold into US manufacturing plants. Stakeholders must monitor how evolving EPR frameworks in multiple states redefine acceptable recovered fiber quality thresholds and equipment certification requirements.
Market Dynamics
Consolidation among folding carton converters is compressing procurement cycles and favoring suppliers offering integrated press-to-finishing workflows over standalone stripping equipment vendors.
Growth Catalysts
- EPA contamination thresholds:Recycling facilities across the United States are retrofitting lines with advanced vacuum-extraction strippers to meet stricter recovered fiber purity mandates for municipal waste streams.
- Ecodesign for Sustainable Products Regulation:Germany's packaging converters face compliance pressure to source higher-grade recovered material, concentrating equipment demand in Bavaria's industrial corridor.
- High-speed carton automation:Folding carton operations running at 15,000 sheets per hour require pin-based registration systems that manual stripping cannot sustain.
Market Restraints
- Steel and precision-machined component costs:Vacuum pump assemblies and hardened pin registration modules face input price volatility from specialized European suppliers.
- Technical limitation in film-laminated substrates:Adhesive residue from metallized or polyethylene-coated stocks clings to fiber waste, reducing stripper throughput and requiring secondary cleaning stages.
- Substitution by inline die-cutting:Rotary die systems with integrated waste winders bypass stripping entirely for certain roll-fed applications.
Strategic Opportunities
- India's packaging growth corridor:Folding carton capacity expansion in Gujarat and Maharashtra outpaces local stripping equipment supply, creating openings for automatic system vendors.
- Extended Producer Responsibility tailwinds:State-level EPR frameworks in California and New York are mandating cleaner recovered fiber streams, forcing converter upgrades.
- Vision-guided robotics convergence:Machine vision for real-time matrix waste detection is merging with adaptive vacuum control to enable unattended stripping of variable-format jobs.
Industry Challenges
- Mechatronics technician scarcity:Automatic strippers integrating servo-driven registration, vacuum pneumatics, and PLC controls require maintenance staff with cross-disciplinary skills that vocational programs undersupply.
- Legacy press integration friction:Retrofitting vacuum extraction systems onto 1990s-era Heidelberg or Bobst lines demands custom mounting brackets and airflow recalibration that extend commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paper Waste Strippers Market |
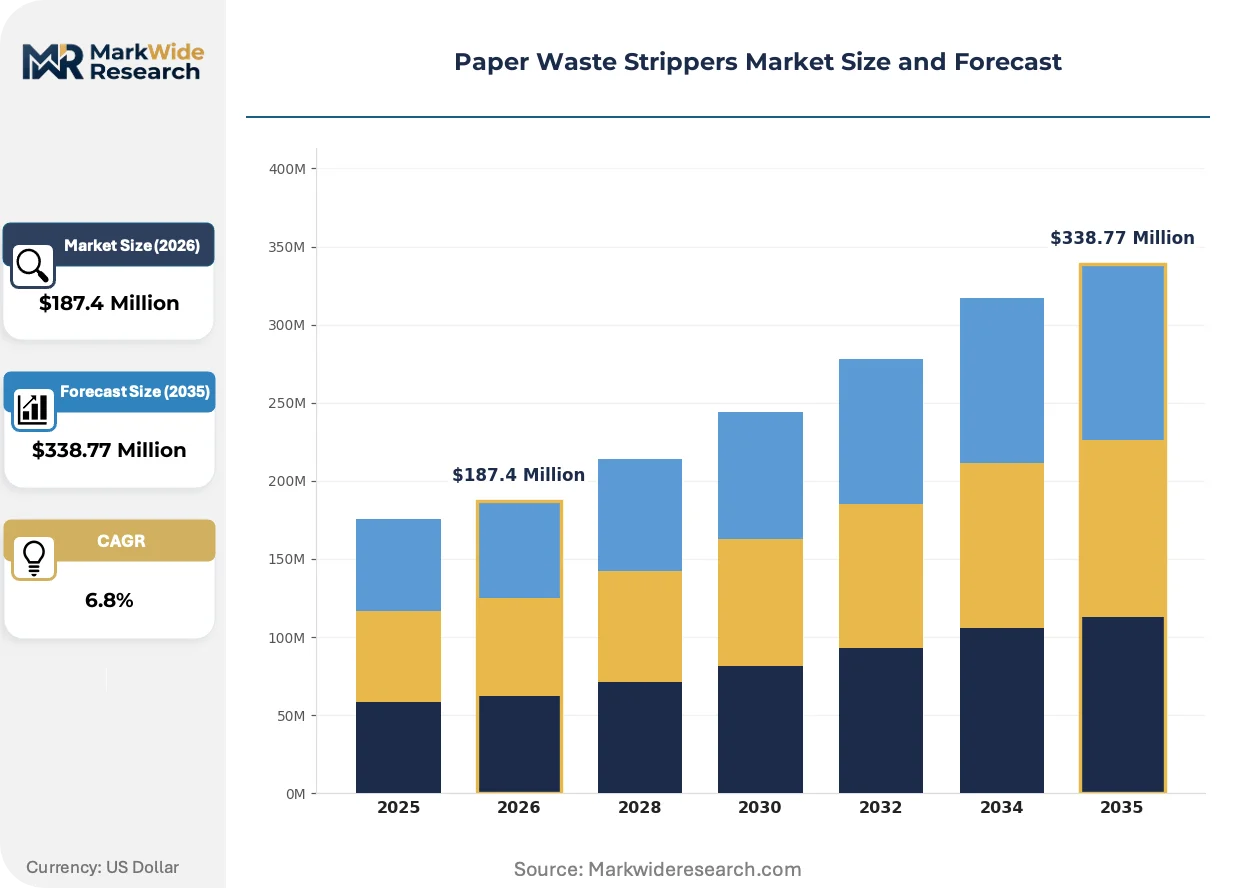
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Strippers, Automatic Strippers, Semi-Automatic Strippers, Portable Strippers End User: Manufacturing Plants, Recycling Facilities, Educational Institutions, Office Buildings Material Type: Cardboard, Newsprint, Coated Paper, Uncoated Paper Distribution Channel: Online Retail, Direct Sales, Distributors, Resellers |
| Companies Covered | Bobst Group, Heidelberg, Valco Melton, Baldwin Technology, Dücker Group, C&T Matrix, Apr Solutions, Kongsberg Precision Cutting, Kompac, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paper Waste Strippers Market Evolving Landscape
Digital workflow integration and sustainability mandates are reshaping how stripping equipment is specified, operated, and serviced across folding carton and commercial print operations.
Machine vision systems for real-time waste matrix detection are converging with adaptive pneumatic controls to enable automatic format changeovers without manual pin-bar adjustment. Mid-size converters in the US Midwest are piloting these retrofits to reduce job-change downtime. The technology is converging with cloud-based performance monitoring to compress maintenance response times and extend mean time between failures.
REACH restrictions on persistent organic pollutants in adhesives and coatings are forcing European packaging converters to reformulate substrate constructions. Strippers must now handle more brittle, low-tack matrices that fracture unpredictably during extraction. German equipment suppliers are responding with segmented vacuum zones and variable suction profiles calibrated to new adhesive chemistries.
Centralized procurement through holding-company equipment budgets is displacing regional plant-level purchasing authority. Large North American packaging groups are consolidating vendor lists and demanding fleet-standardized control interfaces. This concentration is most visible in the Upper Midwest, where private-equity-backed roll-ups are mandating common HMI platforms across acquired plants to reduce training costs and spare parts proliferation.
Paper Waste Strippers Market Segmentation
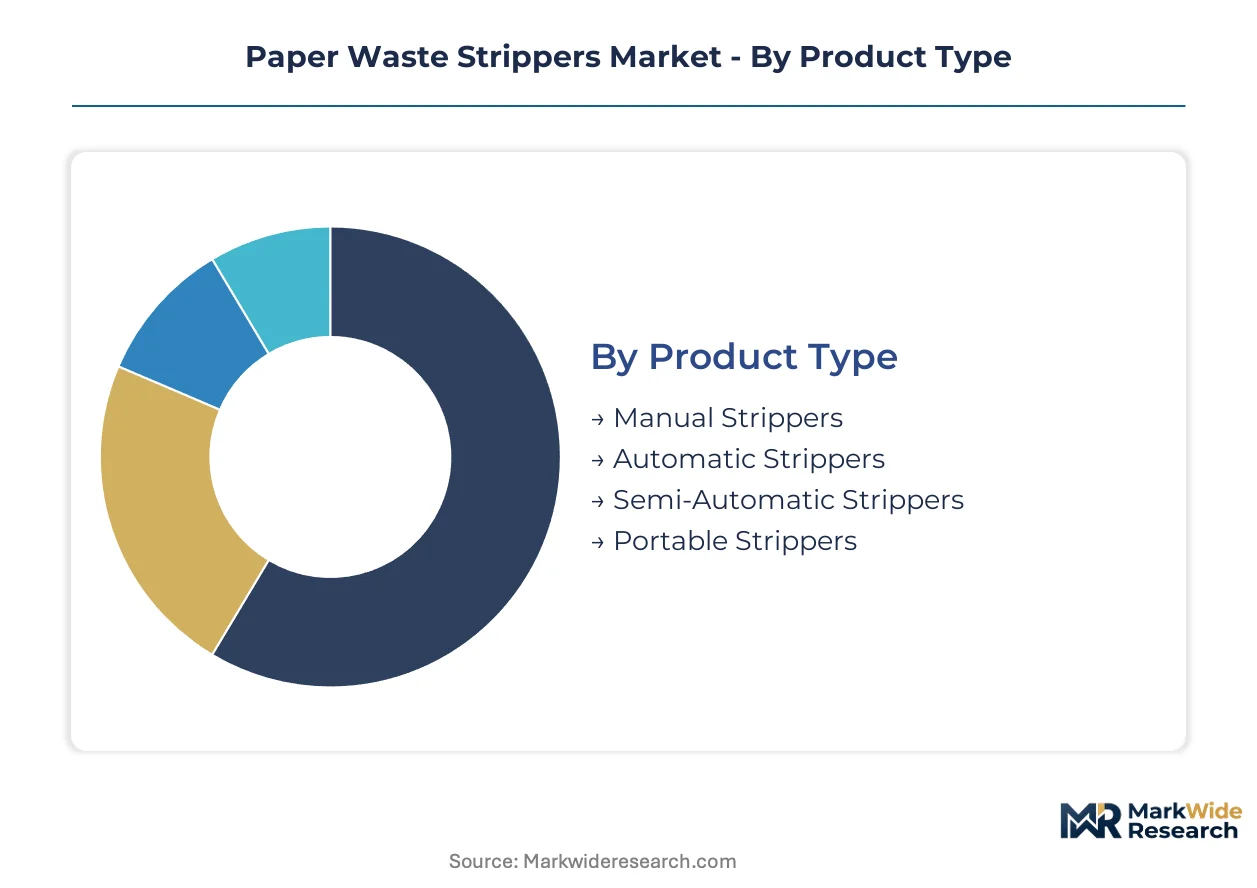
Equipment specification varies sharply across buyer types in the paper waste strippers market. Capital availability, throughput requirements, and regulatory exposure determine which product configurations dominate procurement decisions for each segment cluster.
Product Type:
Automatic strippers command the highest upfront capital outlay, with vacuum-extraction systems and servo-driven registration modules driving installed costs well above manual alternatives. Manual and portable units require minimal infrastructure investment.
- Automatic Strippers:Vacuum-assisted extraction systems with pin-based registration operate at 8,000 to 15,000 sheets per hour. Folding carton converters in Bavaria's industrial corridor are concentrating procurement here as Germany's Ecodesign for Sustainable Products Regulation tightens recovered fiber purity mandates.
- Manual Strippers:Hand-fed units with mechanical pin bars suit low-volume operations where labor costs remain below automation breakeven thresholds. Small-format print shops in Gujarat and Maharashtra retain demand for these units amid capital constraints.
- Semi-Automatic Strippers:Hybrid units requiring operator loading with powered waste extraction occupy narrowing mid-market positioning.
- Portable Strippers:Compact mobile units serve educational institutions and field maintenance applications where fixed installation is impractical.
Most installed capacity flows through automatic strippers. Expansion is steepest in portable strippers.
End User:
Volume concentration and regulatory exposure separate end-user segments, with manufacturing plants and recycling facilities facing the strictest contamination thresholds.
- Manufacturing Plants:Folding carton converters operating high-speed lines demand integrated press-to-finishing workflows with fleet-standardized HMI platforms. EPA-mandated contamination thresholds for recovered fiber streams are forcing equipment upgrades across US Midwest packaging groups.
- Recycling Facilities:Municipal material recovery facilities require advanced vacuum-extraction strippers to meet purity specifications for resale to paper mills. California and New York state-level EPR frameworks are mandating cleaner recovered fiber streams.
- Educational Institutions:Vocational programs and university print shops prioritize low-capital manual units for training purposes.
- Office Buildings:Corporate in-plant operations with intermittent print volumes favor compact semi-automatic configurations.
Manufacturing plants absorb the majority of automatic system shipments. Recycling facilities are expanding most quickly as EPR frameworks proliferate.
Material Type:
Substrate brittleness and adhesive chemistry determine stripping equipment specification, with coated and laminated stocks presenting the most complex extraction challenges.
- Coated Paper:Clay-coated and glossy stocks with metallized or polyethylene layers leave adhesive residue that clings to fiber waste. REACH restrictions on persistent organic pollutants are forcing European converters to reformulate toward more brittle, low-tack matrices that demand segmented vacuum zone calibration.
- Cardboard:Corrugated and folding carton substrates with die-cut blanks and trim waste represent the highest-volume application. German equipment suppliers are adapting variable suction profiles to handle new adhesive chemistries mandated by sustainability regulations.
- Newsprint:Uncoated mechanical pulp stocks with minimal surface treatment strip cleanly with standard vacuum extraction.
- Uncoated Paper:Offset and copy paper substrates require less aggressive extraction parameters, reducing equipment wear rates.
Cardboard processing dominates installed base. Coated paper applications are climbing the fastest as packaging premiumization accelerates.
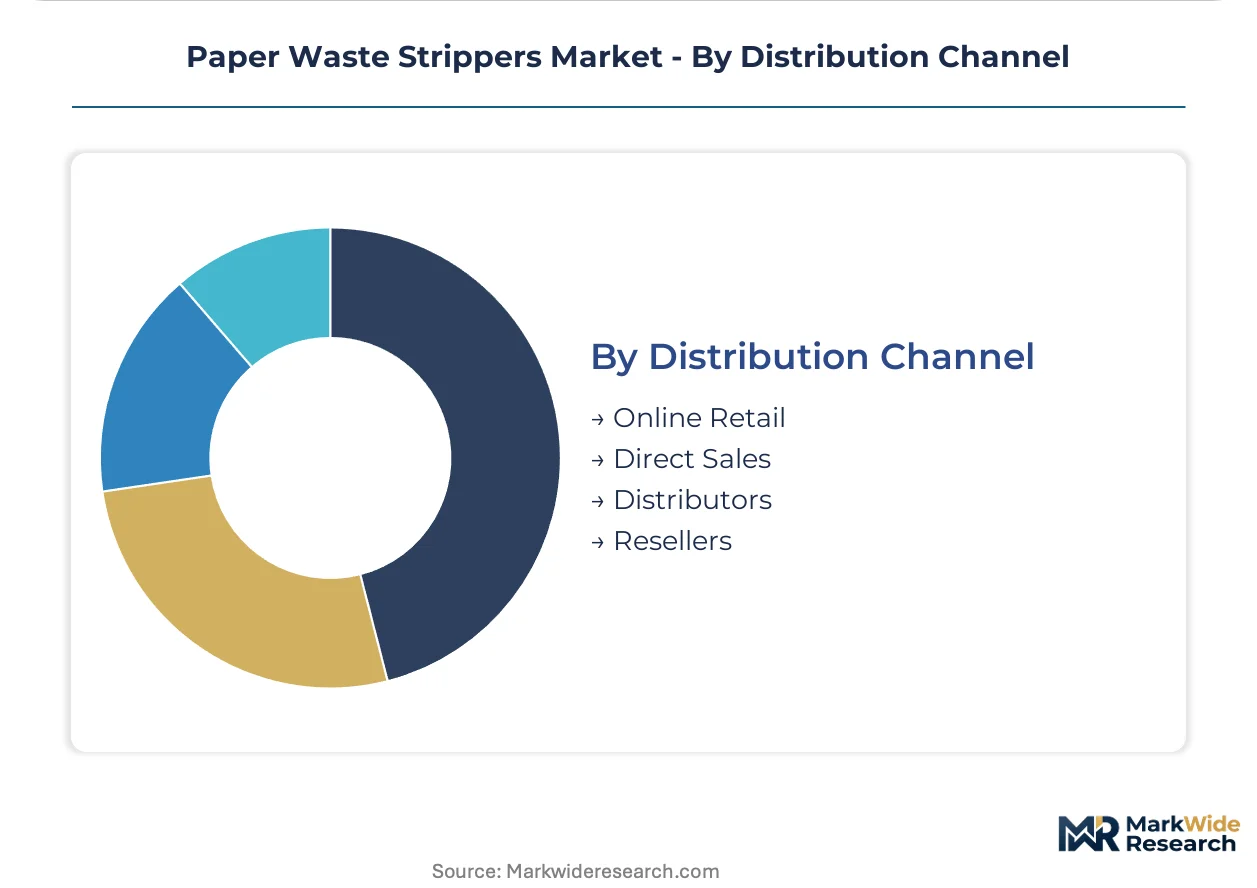
Distribution Channel:
Channel selection tracks buyer scale and technical complexity, with large packaging groups consolidating procurement through direct relationships.
- Direct Sales:Heidelberg and Bobst Group capture multi-unit orders from consolidated buyers through integrated workflow offerings. Private-equity-backed roll-ups in the US Upper Midwest are mandating fleet-standardized control interfaces through direct vendor negotiations.
- Distributors:Regional equipment distributors serve mid-size converters requiring local commissioning support and spare parts availability.
- Online Retail:E-commerce platforms move manual and portable units to educational institutions and small print shops with minimal technical consultation needs.
- Resellers:Secondary market channels handle refurbished automatic systems for cost-constrained buyers entering high-volume segments.
Direct sales channels capture the majority of automatic system revenue. Online retail is gaining share fastest in the portable and manual equipment tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Ecodesign for Sustainable Products Regulation is driving faster equipment replacement cycles than the United States, where EPA contamination thresholds are retrofitting existing lines rather than mandating new capital expenditure.
United States
Recycling facilities across California and New York are retrofitting vacuum-extraction strippers to meet state-level EPR frameworks mandating cleaner recovered fiber streams. OSHA machine guarding regulations require interlocked access panels on automatic units sold into manufacturing plants. The Upper Midwest packaging corridor sees private-equity-backed roll-ups consolidating procurement through centralized equipment budgets.
Germany
Packaging converters in Bavaria's industrial corridor face compliance pressure from the Ecodesign for Sustainable Products Regulation to source higher-purity recovered material. REACH restrictions on persistent organic pollutants in adhesives are forcing substrate reformulation toward more brittle matrices. Equipment suppliers in Baden-Württemberg are responding with segmented vacuum zone calibration for these new chemistries.
India
Folding carton capacity expansion in Gujarat and Maharashtra is outpacing local stripping equipment supply, creating openings for automatic system vendors. The country's national industrial standards body is developing certification frameworks for recovered fiber quality that will shape equipment specifications. Small-format print shops in these states retain demand for manual units amid capital constraints.
China
Packaging premiumization in the Yangtze River Delta is accelerating coated paper applications that demand advanced extraction systems for adhesive-laden waste. The Ministry of Ecology and Environment is tightening contamination standards for municipal recycling streams. Equipment fabricators in the Pearl River Delta are scaling production of vacuum-assisted systems for export markets.
Japan
High-speed carton automation in the Kanto region around Tokyo requires pin-based registration systems operating at 15,000 sheets per hour. METI industrial efficiency guidelines are pressuring converters to reduce manual labor in finishing operations. Equipment vendors in the Chubu region near Nagoya are integrating machine vision for unattended stripping of variable-format jobs.
Paper Waste Strippers Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the paper waste strippers market, creating a tiered structure where scale advantages clash with customization agility. Consolidation among folding carton converters is compressing procurement cycles and favoring suppliers offering integrated press-to-finishing workflows. Three archetypes dominate: diversified printing machinery conglomerates with end-to-end workflow offerings, specialized finishing equipment pure-plays with precision engineering depth, and adhesive control technology crossovers from adjacent bonding applications. Dominant competitive moves include strategic partnerships for digital workflow integration and backward integration into vacuum pneumatics to secure component supply.
Among diversified machinery conglomerates, Heidelberg and Bobst Group exemplify the integrated workflow archetype, leveraging press-to-finishing system bundling to capture multi-unit orders from consolidated buyers. Valco Melton occupies a position within the adhesive control crossover tier, competing on substrate damage reduction during waste separation. These three companies represent the competitive vectors shaping procurement decisions: workflow integration, precision engineering, and process control specialization.
| Leading Market Players |
|---|
| Bobst Group |
| Heidelberg |
| Valco Melton |
| Baldwin Technology |
| Dücker Group |
| C&T Matrix |
| Apr Solutions |
| Kongsberg Precision Cutting |
| Kompac |
| Others |
Value Network & Pricing Analysis
Mechatronics technician scarcity in Baden-Württemberg widens pricing spreads between premium automatic systems and economy manual units as labor-cost differentials compound component sourcing premiums. German equipment suppliers pass specialized workforce premiums through to Bavarian packaging converters while Indian fabricators compete on lower technical labor bases.
Pricing Analysis
Capacity additions in Gujarat and Maharashtra are reshaping price floors for semi-automatic and manual strippers as local fabrication scales. Three-tier pricing structure across premium, standard, and economy levels separates Heidelberg and Bobst Group integrated workflows from regional distributors and online retail channels. Price differentiation hinges on CE certification tier and after-sales service bundling. Cost compression in the manual tier is intensifying because Chinese vacuum pump assemblies flood secondary markets. Small-format print shops in Maharashtra exhibit highest price sensitivity; private-equity-backed packaging groups in the US Upper Midwest show lowest sensitivity due to fleet-standardization mandates.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Chicago, and Shanghai anchor hub-and-spoke patterns for spare parts and commissioning support. Manufacturing concentrates in Germany, China, and India for complete systems; precision-machined pin registration modules and vacuum pump assemblies draw from specialized European suppliers. Steel alloys, servo motors, and PLC control systems constitute critical input dependencies. Single-source vulnerability around hardened vacuum extraction components from Bavarian suppliers threatens lead time stability for non-European OEMs. Distribution runs through direct sales for automatic systems and regional distributors for mid-market units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EPA contamination thresholds and Germany's Ecodesign for Sustainable Products Regulation generate recurring equipment replacement demand across North American and European recycling facilities.
For Market Incumbents: Acquire machine vision and adaptive pneumatic control specialists to counter substitution by inline die-cutting systems with integrated waste winders. Consolidate backward integration into vacuum pump manufacturing to offset input price volatility from European component suppliers. Fleet-standardized HMI platform mandates from private-equity-backed packaging groups create channel control leverage against standalone stripping equipment vendors. For New Entrants and Emerging Players: Begin with portable and manual stripper segments in Gujarat and Maharashtra where folding carton capacity expansion outpaces local supply and capital constraints limit automation penetration. Target educational institutions and small-format print shops through e-commerce channels with minimal technical consultation requirements. Partner with regional equipment distributors for commissioning support rather than building direct sales infrastructure. For Investors and Strategic Acquirers: Packaging machinery conglomerates with end-to-end workflow offerings are the most active acquirer in this space, seeking precision stripping module capabilities to complement press-to-finishing integration. Over a multi-year horizon, vendors with captive vacuum pneumatics supply and machine vision convergence expertise demonstrate superior margin resilience. Watch state-level EPR framework proliferation across the United States as the primary inflection signal for recycling facility retrofit demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Vacuum Pneumatics | Captive supply of vacuum pump assemblies insulates Heidelberg and Bobst Group from European component price volatility. |
| Machine Vision Convergence | Adaptive pneumatic controls with real-time matrix detection reduce job-change downtime for US Midwest converters. |
| Fleet-Standardized HMI Platforms | Common control interfaces across acquired plants reduce training costs for private-equity-backed packaging roll-ups. |
| Regional Distribution Center Expansion | Hub-and-spoke spare parts networks in Stuttgart and Shanghai compress maintenance response times for automatic systems. |
| Segmented Vacuum Zone Calibration | Variable suction profiles address brittle low-tack matrices from REACH-mandated adhesive reformulations in Germany. |
Research Methodology
Multiple input streams — equipment shipment data, regulatory filing analysis, and converter capacity surveys — were reconciled across primary interviews and secondary validation. Plant engineers at folding carton operations, aftermarket service heads at OEMs, and procurement leads at packaging groups provided operational perspective. EPA enforcement records, ECHA REACH restriction updates, and BIS certification frameworks supplied regulatory context. Trade flow databases, customs records, and industrial equipment registries furnished volume benchmarks. Bottom-up unit economics and top-down sectoral sizing were cross-referenced for triangulation.
Historical capacity utilization patterns were cross-referenced against panel input from equipment vendors and end-user procurement committees. Segmentation dimensions modeled include automation level, end-user facility type, substrate material construction, and regional regulatory cluster. CAGRs were derived from slope analysis of installed base expansion against replacement cycle compression. Forecast inputs incorporated EPR framework adoption timelines and machine vision technology maturation curves across the projection horizon.
Several conditions sit outside the modeled scope, including tariff rate modifications on precision-machined components, metallized substrate formulation shifts beyond REACH mandates, and rotary die system substitution acceleration. Forecasts reflect documented assumptions around regulatory enforcement intensity and technology adoption elasticity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Tracing Paper Market
Paper & Paperboard Packaging
Clay Coated Recycled Boxboard Market
Paper & Paperboard Packaging
Machine Glazed Paper Market
Paper & Paperboard Packaging
Micro Flute Paper Market
Paper & Paperboard Packaging
Food Contact Paper and Board Market
Paper & Paperboard Packaging
Desiccant Paper Market
Paper & Paperboard Packaging
Clear Envelopes and Mailing Supplies Market
Paper & Paperboard Packaging
Corrugated Handle Box Market
Paper & Paperboard Packaging
Paper Packaging Market
Paper & Paperboard Packaging
Middle East and Africa Paper Cone Market
Paper & Paperboard Packaging
Paper and Paperboard Trays Market
Paper & Paperboard Packaging
Asia-Pacific Paper Cone Market
Paper & Paperboard Packaging
Latin America Paper Packaging Market
Paper & Paperboard Packaging
Heat Sealable Pulp Board Tray Market
Paper & Paperboard Packaging
GCC Paper Cup Market
Paper & Paperboard Packaging
Kraft Envelopes Market