
 Mottled Test Liner Market | 2026-2036
Mottled Test Liner Market Size, Share, and Industry Trends Forecast 2026-2036
Mottled Test Liner Market Foresight
The capital-intensity divergence between integrated pulp-to-liner producers and merchant converters is collapsing as energy and fiber costs squeeze thin-margin operators. Stora Enso leverages its Nordic wood fiber captive supply to sustain cost leadership across European test liner grades. Smurfit Kappa dominates Iberian and Latin American markets through vertically integrated containerboard networks that anchor regional pricing power.
Mottled test liner is a recycled-paperboard substrate distinguished by its visible fiber speckling, typically manufactured from 100% recovered paper with basis weights ranging from 80 to 200 grams per square meter, serving primarily as the outer printable layer of corrugated shipping containers. The paper segment leads volume shipments due to established recycling infrastructure and lower unit economics, while the composite segment captures expanding margin pools as brand owners specify moisture-resistant barrier performance for chilled food chains. Food packaging applications command the fastest growth trajectory among end-use categories, driven by e-commerce grocery fulfillment and regulatory pressure to eliminate single-use plastics in primary and secondary packaging.
The EU Green Deal and F-Gas Regulation shape fiber sourcing mandates and carbon accounting disclosures for European producers, while India's BIS recycled-content standards and PLI scheme for paperboard manufacturing redirect capacity investments toward compliant domestic supply. The US EPA industrial emissions framework and state-level extended producer responsibility laws in California and Maine impose parallel compliance burdens on North American suppliers. Stakeholders must monitor how diverging carbon border adjustment mechanisms and recycled fiber certification schemes reshape competitive access across the Atlantic and Pacific trade corridors.
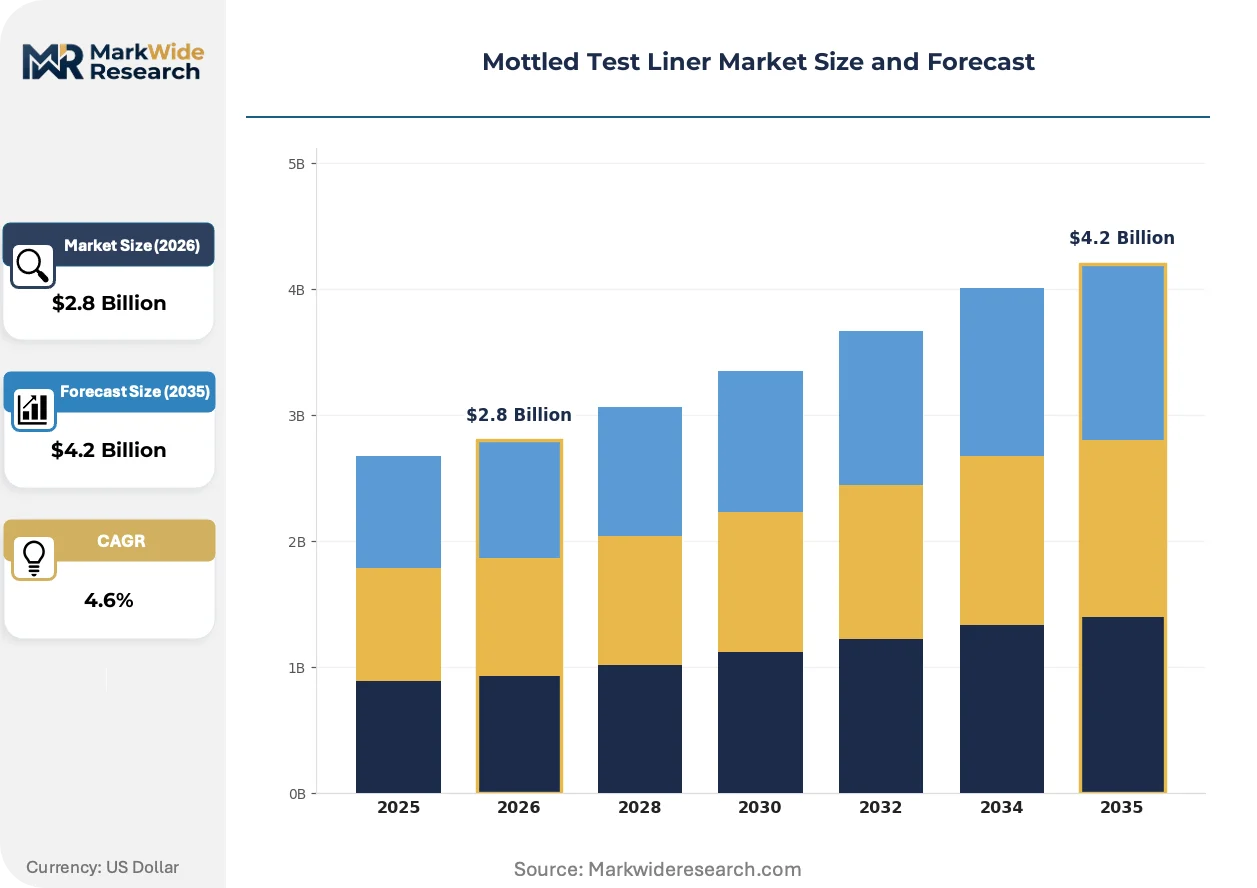
Market Dynamics
The mottled test liner segment is undergoing a structural compression as energy-intensive recycled fiber processing collides with EU carbon border adjustment mechanisms and India's BIS recycled-content mandates, forcing merchant converters to either integrate backward or exit thin-margin grades.
Growth Catalysts
- E-Commerce Grocery Fulfillment:Cold-chain corrugated demand from online food retailers is pulling moisture-resistant mottled grades into secondary packaging specifications previously served by plastic.
- EU Green Deal Packaging Rules:The regulation's recycled-content floors and extended producer responsibility frameworks are locking in fiber-based substitutes across German and French retail supply chains.
- Bangalore Electronics Corridor:Box plants in South India are scaling test liner consumption to serve semiconductor and consumer electronics export packaging.
Market Restraints
- Recovered Fiber Cost Volatility:Old corrugated container price swings in European spot markets compress converter margins unpredictably.
- Nordic Pulp Supply Concentration:Integrated producers with captive wood fiber access control cost leadership positions across premium test liner grades.
- Plastic Barrier Substitution:Polyethylene-coated alternatives retain moisture protection advantages in frozen food logistics.
Strategic Opportunities
- India PLI Scheme for Paperboard:Domestic capacity investments aligned with BIS standards capture import substitution demand from non-compliant foreign suppliers.
- Barrier Coating Convergence:Bio-based moisture treatments combined with fiber speckling aesthetics open chilled ready-meal packaging specifications.
- Direct Converter Relationships:Bypassing merchant distributors to supply Bangalore and Chennai box plants shortens order cycles.
Industry Challenges
- Recycled Fiber Sorting Expertise:Contamination control for food-grade mottled liner requires skilled technicians scarce in emerging manufacturing clusters.
- CSRD Carbon Accounting Integration:Scope 3 disclosure requirements for European buyers demand supply chain data infrastructure most merchant converters lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mottled Test Liner Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Paper, Film, Cardboard, Composite Application: Pharmaceuticals, Cosmetics, Electronics, Food Packaging End User: Manufacturers, Retailers, Distributors, Consumers Technology: Printing, Coating, Laminating, Converting |
| Companies Covered | Stora Enso, Smurfit Kappa, Mondi Group, DS Smith, Svenska Cellulosa, NorPaper, Saica Paper, Asia Pulp and Paper, International Paper Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mottled Test Liner Market Shifts & Advancements
Active developments across fiber processing, regulatory compliance architecture, and buyer procurement systems are compressing legacy competitive advantages while elevating sustainability-verified supply chains.
Advanced screening and cleaning systems for mixed recovered paper are displacing conventional deinking configurations in mottled grade production. German packaging converters are adopting these systems rapidly to meet EU Green Deal contamination thresholds. The technology is displacing merchant converters dependent on purchased pulp from integrated competitors with in-house fiber recovery.
CSRD mandatory sustainability disclosures are restructuring supplier qualification protocols across European corrugated value chains. Large retail and foodservice buyers now require documented recycled-content percentages and carbon intensity data. Fresh produce and chilled dairy segments are responding by consolidating purchases around vertically integrated liner producers with certified fiber traceability.
Consolidated procurement by multinational food brands is compressing supplier bases and extending contract durations. Direct sourcing agreements with integrated liner producers are replacing spot-market purchasing through distributors. This pattern is most visible in Germany and France, where retail consolidation has concentrated packaging specification authority among fewer buying centers.
Mottled Test Liner Market Segmentation
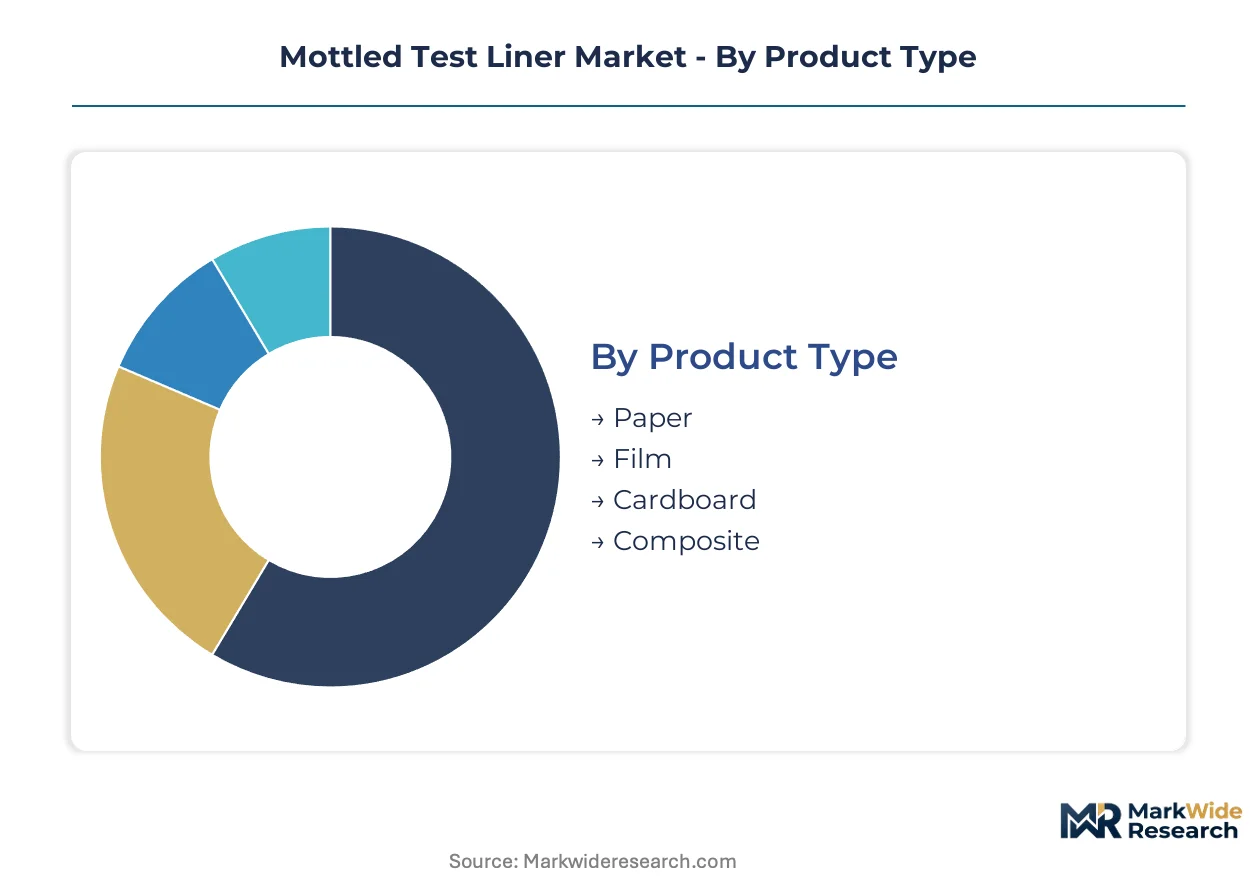
Mottled test liner segmentation reveals divergent margin structures across substrate technologies and end-use specifications. Product type and application splits expose where integrated producers capture value versus where merchant converters fight for share.
Product Type:
Paper dominates domestic consumption across European and Indian corrugated networks, while composite grades serve export-led demand from chilled food logistics hubs.
- Paper:Manufactured from 100% recovered fiber with visible speckling across 80-200 gsm basis weights, this substrate anchors cost-efficient corrugated outer layers. German and French food packaging converters favor paper grades for EU Green Deal compliance, though energy-intensive recycled fiber processing squeezes merchant operator margins.
- Composite:Multi-layer constructions combining fiber substrates with moisture-resistant barriers command premium positioning in cold-chain applications. Bangalore electronics exporters specify composite grades for semiconductor packaging facing tropical humidity exposure during ocean freight.
- Film:Polyethylene-coated alternatives retain frozen food logistics specifications where moisture protection trumps fiber-based sustainability claims.
- Cardboard:Heavier caliper variants serve point-of-sale display packaging with structural rigidity requirements beyond standard shipping container duty.
Paper holds the largest share; momentum sits with composite.
Application:
Food packaging concentrates volume demand through regulatory-driven plastic substitution, while electronics applications scale fastest in South Indian manufacturing corridors.
- Food Packaging:E-commerce grocery fulfillment pulls moisture-resistant mottled grades into secondary specifications previously served by single-use plastics. EU extended producer responsibility frameworks lock in fiber-based substitutes across German retail supply chains.
- Electronics:Semiconductor and consumer electronics export packaging from Bangalore and Chennai drives specification-grade test liner consumption. Box plants in South India scale orders to serve manufacturing corridor expansion.
- Pharmaceuticals:Cold-chain drug distribution requires contamination-controlled fiber grades with documented traceability for EU and US regulatory submissions.
- Cosmetics:Premium unboxing experiences favor mottled aesthetic substrates for direct-to-consumer beauty brand shipments.
Food packaging commands the dominant volume position; electronics claims the steepest expansion trajectory.
End User:
Manufacturer procurement consolidates around direct mill relationships, while distributor channels fragment across spot-market purchasing.
- Manufacturers:Integrated food brands and electronics OEMs negotiate multi-year supply agreements with certified fiber traceability. CSRD disclosure requirements favor vertically integrated liner producers with Scope 3 data infrastructure.
- Retailers:Consolidated buying centers in Germany and France extend contract durations and compress supplier bases around sustainability-verified sources.
- Distributors:Merchant intermediaries serve smaller converters lacking volume scale for direct mill negotiations, exposed to recovered fiber price volatility.
- Consumers:End-user demand manifests indirectly through brand owner sustainability specifications rather than direct purchasing.
Manufacturers represent the highest-value customer tier; retailer procurement consolidation is accelerating fastest.
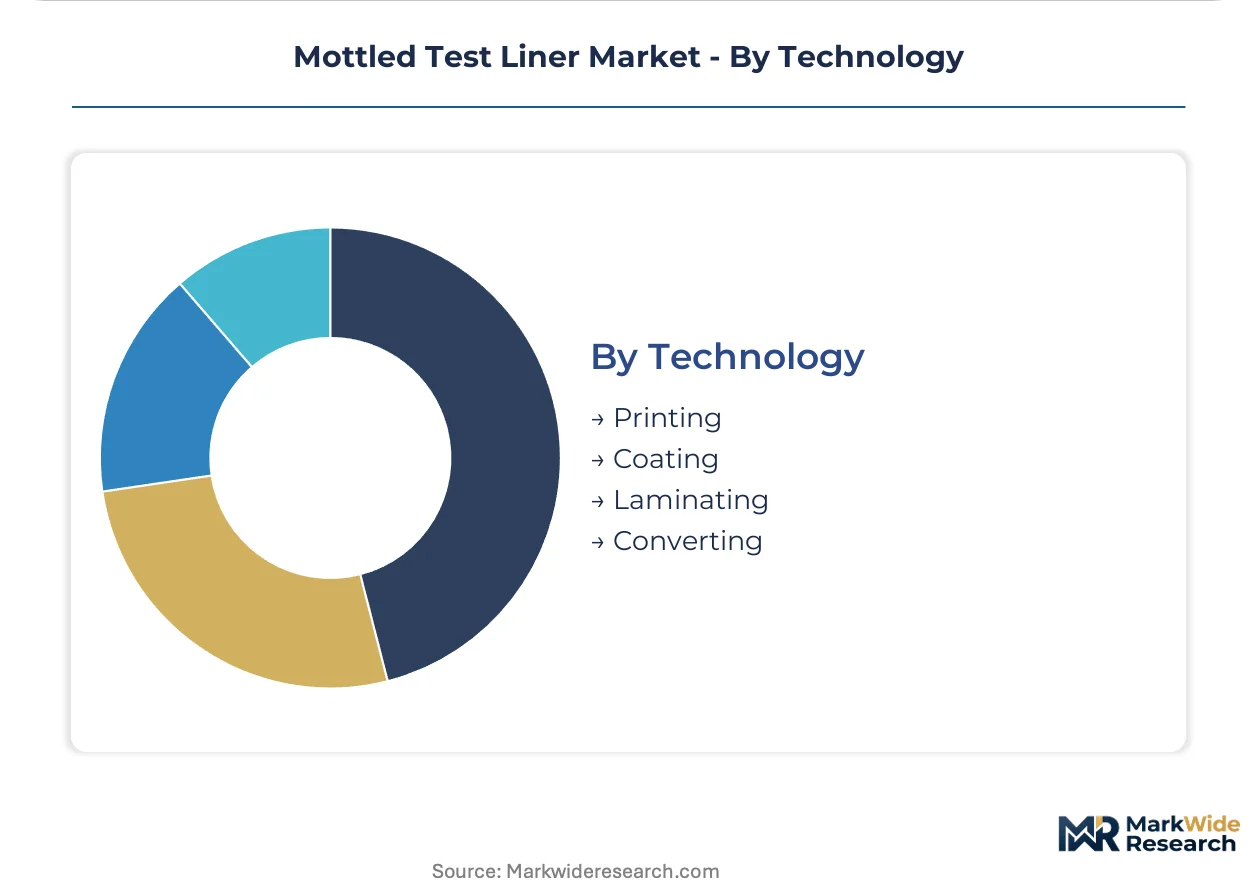
Technology:
Converting capabilities separate integrated producers from merchant competitors, while coating innovation opens barrier performance specifications.
- Converting:Corrugator line integration and box plant proximity determine logistics cost positioning. Direct converter relationships in Bangalore and Chennai shorten order cycles for electronics exporters.
- Coating:Bio-based moisture treatments combined with fiber speckling aesthetics penetrate chilled ready-meal packaging. German converters adopt advanced screening systems to meet EU Green Deal contamination thresholds.
- Printing:Flexographic and digital print compatibility on mottled surfaces enables brand differentiation for cosmetics and food retail applications.
- Laminating:Multi-ply adhesion processes create structural performance for heavy-duty electronics and industrial component packaging.
Converting dominates current capacity deployment; coating technology is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates with Nordic integrated producers holding captive wood fiber, while Indian merchant converters absorb volatility from imported pulp and energy costs. German and French buyers leverage CSRD disclosure requirements to consolidate supplier bases around certified sources. Bangalore's electronics corridor and São Paulo's food packaging hub represent divergent demand poles reshaping trade flows.
Germany
Food packaging converters in Bavaria and North Rhine-Westphalia scale orders for EU Green Deal-compliant recycled-content grades. The country's national packaging regulator enforces extended producer responsibility frameworks that lock fiber-based substitutes into retail supply chains. Box plants around Hamburg and Frankfurt serve e-commerce grocery fulfillment networks demanding moisture-resistant specifications.
India
Corrugated plants in Karnataka and Tamil Nadu expand test liner consumption to serve semiconductor and consumer electronics exporters. BIS recycled-content standards and the PLI scheme for paperboard manufacturing redirect capacity investments toward compliant domestic supply. Bangalore's manufacturing corridor anchors specification-grade demand from box plants shortening order cycles through direct mill relationships.
United States
California and Maine state-level extended producer responsibility laws impose parallel compliance burdens on containerboard suppliers serving West Coast cold-chain logistics. The EPA industrial emissions framework shapes carbon accounting disclosures for buyers qualifying suppliers. Pacific Northwest integrated mills leverage hydroelectric power access to sustain cost positioning across recycled liner grades.
Brazil
São Paulo state food processors specify mottled grades for export meat and produce packaging facing EU carbon border adjustment exposure. The country's national industrial standards body aligns certification schemes with European buyer requirements. Corrugator networks in the Southeast region consolidate procurement around vertically integrated producers with certified fiber traceability.
Mottled Test Liner Market Competitive Landscape
Concentration sits with Nordic and Iberian integrated producers holding captive fiber supply and corrugator network control. Merchant converters without backward integration into pulp recovery face margin compression from energy and recovered fiber cost volatility. Two archetypes dominate: vertically integrated containerboard networks with regional pricing power, and specialized recycled-fiber processors serving sustainability-verified procurement channels. Competitive moves center on capacity expansion aligned with BIS and EU Green Deal compliance standards, plus direct converter relationships bypassing distributor intermediaries.
Within the integrated network tier, Stora Enso and Smurfit Kappa exemplify archetypes leveraging geographic positioning. Stora Enso's Nordic wood fiber captive supply sustains cost leadership across European test liner grades. Smurfit Kappa's Iberian and Latin American containerboard networks anchor regional pricing power through corrugator integration. Mondi Group occupies a position bridging African and European supply corridors with certified fiber traceability infrastructure.
| Leading Market Players |
|---|
| Stora Enso |
| Smurfit Kappa |
| Mondi Group |
| DS Smith |
| Svenska Cellulosa |
| NorPaper |
| Saica Paper |
| Asia Pulp and Paper |
| International Paper Company |
| Others |
Supply & Pricing Matrix
Long-term offtake agreements between German food packaging converters and Nordic integrated producers lock in fiber supply access while muting exposure to Old Corrugated Container spot volatility. These contracts anchor price visibility across the EU Green Deal compliance window, binding buyers to certified recycled-content grades at fixed differentials above energy-indexed production costs.
Pricing Analysis
Configured-to-order pricing for moisture-resistant composite grades commands spreads of 15-25% above standard paper specifications, reflecting barrier coating complexity and food-grade contamination controls. Three-tier pricing structure across premium, standard, and economy levels stratifies by BIS certification status and CSRD traceability documentation. Price differentiation intensifies as merchant converters without captive fiber access absorb OCC cost swings that integrated producers hedge through Nordic wood pulp integration. Small-scale distributors in South India exhibit acute price sensitivity, while German retail buying centers prioritize specification compliance over unit cost.
Supply Chain Analysis
Container availability on Asia-Europe trade lanes shapes inbound logistics costs for Indian merchant converters sourcing European screening equipment and coating chemicals. Supply concentrates in Finland, Sweden, and Germany for advanced fiber recovery systems; recovered fiber sorting expertise draws from German technical training networks. Raw material dependencies span Old Corrugated Containers, bio-based moisture barriers, and specialized deinking chemicals. Single-source vulnerability sits with Nordic pulp supply concentration for premium grades. Distribution runs through vertically integrated containerboard networks in Iberia and Latin America, bypassing merchant intermediaries for large converter accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized technicians capable of operating advanced contamination screening systems represent the critical capability gap constraining capacity expansion in emerging manufacturing clusters. This scarcity reshapes competitive access across compliance-driven procurement channels.
For Market Incumbents: Compound captive fiber advantages by deepening direct converter relationships in Bangalore and Chennai electronics corridors, bypassing distributor intermediaries entirely. Integrate backward into recovered fiber collection networks to secure OCC supply against spot volatility. Defend against merchant converter margin compression by accelerating CSRD-compliant Scope 3 data infrastructure deployment ahead of buyer qualification deadlines. For New Entrants and Emerging Players: Differentiate on BIS-certified domestic supply aligned with India's PLI scheme for paperboard manufacturing, capturing import substitution demand from non-compliant foreign suppliers. Target South Indian electronics packaging specifications where specification-grade composite demand outpaces local supply. Penetrate through direct mill-to-plant relationships with corrugators serving semiconductor exporters, shortening order cycles against established distributor channels. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated mid-cap specialists with certified fiber traceability infrastructure and established CSRD disclosure systems. Long-term viability favors producers with backward integration into pulp recovery and corrugator network control across regional pricing hubs. Watch for EU carbon border adjustment mechanism implementation as the inflection signal reshaping Atlantic trade competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recovered Fiber Collection | Nordic producers secure OCC supply against European spot volatility through captive collection networks. |
| CSRD-Compliant Scope 3 Data Infrastructure | German retail buyers consolidate procurement around suppliers with documented carbon intensity disclosure. |
| Direct Converter Relationships in South India | Bangalore electronics exporters shorten order cycles by bypassing merchant distributor intermediaries. |
| Bio-Based Barrier Coating Development | Chilled ready-meal specifications open to fiber-based substitutes displacing polyethylene-coated alternatives. |
| PLI-Aligned Domestic Capacity Expansion | Indian producers capture import substitution demand under BIS recycled-content standards enforcement. |
Research Methodology
Desk research of trade flow databases, EU regulatory filings, and Indian industrial policy documents preceded structured interviews with corrugator plant managers, packaging procurement leads at German food retailers, fiber recovery equipment engineers, and sustainability compliance officers at integrated producers. Secondary validation drew from customs records, BIS certification registries, and SEC filings of publicly traded containerboard manufacturers. Bottom-up volume estimates from regional corrugator capacity were triangulated against top-down demand projections from end-use consumption patterns.
Variance decomposition across product type, application, and technology segments isolates growth contribution by specification tier over the projection horizon. The analytical framework models CAGRs through fiber cost pass-through elasticity, regulatory compliance adoption curves, and substitution dynamics between paper and composite substrates. Industry-specific inputs include OCC price volatility indices, EU Green Deal implementation timelines, and Bangalore electronics corridor expansion rates.
The analysis sits within stated boundaries; outcomes outside sustained EU Green Deal enforcement or disrupted Asia-Europe container flows would require recalibration. Forecasts reflect assumptions regarding BIS standard adoption rates and PLI scheme disbursement continuity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Kraft Bubble Mailers Market
Paper & Paperboard Packaging
Europe Paper Packaging Market
Paper & Paperboard Packaging
Japan Paper Packaging Market
Paper & Paperboard Packaging
Composite Paper Cans Market
Paper & Paperboard Packaging
Food Contact Paper and Board Market
Paper & Paperboard Packaging
Box Liners Market
Paper & Paperboard Packaging
Paper Release Liners Market
Paper & Paperboard Packaging
Recycled Paper Packaging Market
Paper & Paperboard Packaging
Paper Coaster Market
Paper & Paperboard Packaging
Micro Flute Paper Market
Paper & Paperboard Packaging
Food Wrapping Paper Market
Paper & Paperboard Packaging
Paper Cup Machine Market
Paper & Paperboard Packaging
Bamboo Packaging Market
Paper & Paperboard Packaging
Corrugated Board Market
Paper & Paperboard Packaging
Paper Cone Cup Market
Paper & Paperboard Packaging
Corrugated Handle Box Market