
 SCK Paper Market | 2026-2036
SCK Paper Market Size, Share, and Industry Trends Forecast 2026-2036
SCK Paper Market Outlook
ISO 14001 environmental management certification is bifurcating the competitive landscape into qualified suppliers and excluded challengers. UPM-Kymmene Corporation leverages its integrated pulp-to-paper operations across Nordic mills to sustain cost-advantaged supply to European label converters. Pixelle Specialty Solutions anchors its position through deep specialization in silicone-compatible base papers for pressure-sensitive adhesive applications. Stora Enso competes by extending its renewable materials platform into bio-based coating alternatives that reduce petrochemical dependency.
SCK paper denotes single-coated kraft paper, a one-side silicone-treated substrate engineered with 40–120 gram per square meter basis weight and controlled porosity to enable clean adhesive release in label construction. The coating process applies curable polydimethylsiloxane formulations that crosslink under thermal or UV activation, creating a non-stick surface for removable and permanent label stocks alike. Uncoated paper variants occupy mature volume positions in basic stationery and educational supply chains where price sensitivity dominates procurement criteria. Specialty paper grades command premium positioning within industrial and creative applications requiring customized release profiles, dimensional stability, or print receptivity for digital presses.
FDA food-contact substance notifications govern silicone chemistry selections for SCK papers entering US food labeling streams, while the EU REACH framework restricts certain catalyst residues in coating formulations sold across European member states. Japan's METI administers JIS standards that specify basis weight tolerances and silicone adhesion thresholds for domestic converting operations. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions, as regulatory pressure on fluorinated chemistries redirects coating innovation toward silicone and bio-based release systems.
Market Dynamics
REACH compliance in Europe is tightening chemical disclosure requirements for silicone-coated substrates, forcing converters to requalify suppliers and reshaping procurement specifications across premium label segments.
Growth Catalysts
- Automotive labeling clusters in Germany:Specification-grade procurement from automotive OEMs and tier-one suppliers concentrates demand for high-release SCK papers with tight basis weight tolerances.
- FDA food-contact substance notifications:US food labeling streams require validated silicone chemistries, creating a compliance moat that locks in qualified suppliers against unverified imports.
- UV-activated polydimethylsiloxane curing:Faster line speeds and lower energy consumption versus thermal curing are accelerating adoption among North American packaging converters.
Market Restraints
- Softwood kraft pulp price volatility:Input cost swings from Nordic and Canadian fiber markets compress converter margins and destabilize annual contract pricing.
- Fluorinated chemistry substitution timelines:PFAS restrictions under EU REACH and emerging US state-level bans force costly reformulation of legacy release coatings before silicone alternatives achieve equivalent performance.
- Specialty paper machine concentration:Narrow web widths and precision calendering requirements limit viable production to a handful of European and North American mills.
Strategic Opportunities
- Pharmaceutical serialization mandates:Track-and-trace regulations in the EU and US are expanding demand for tamper-evident labels on SCK backings with verified adhesive compatibility.
- Bio-based coating alternatives:Stora Enso's renewable materials platform demonstrates pathway to reduce petrochemical dependency and capture sustainability premiums.
- Digital press print receptivity:Next-generation SCK grades with optimized surface energy are opening premium short-run label segments previously served by filmic substrates.
Industry Challenges
- ISO 14001 certification timelines:Environmental management system audits create 12-18 month qualification delays for challengers attempting to supply major European converters.
- Silicone adhesion threshold calibration:JIS standard compliance for Japanese converting operations requires specialized testing equipment and trained technicians scarce outside established supply bases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | SCK Paper Market |
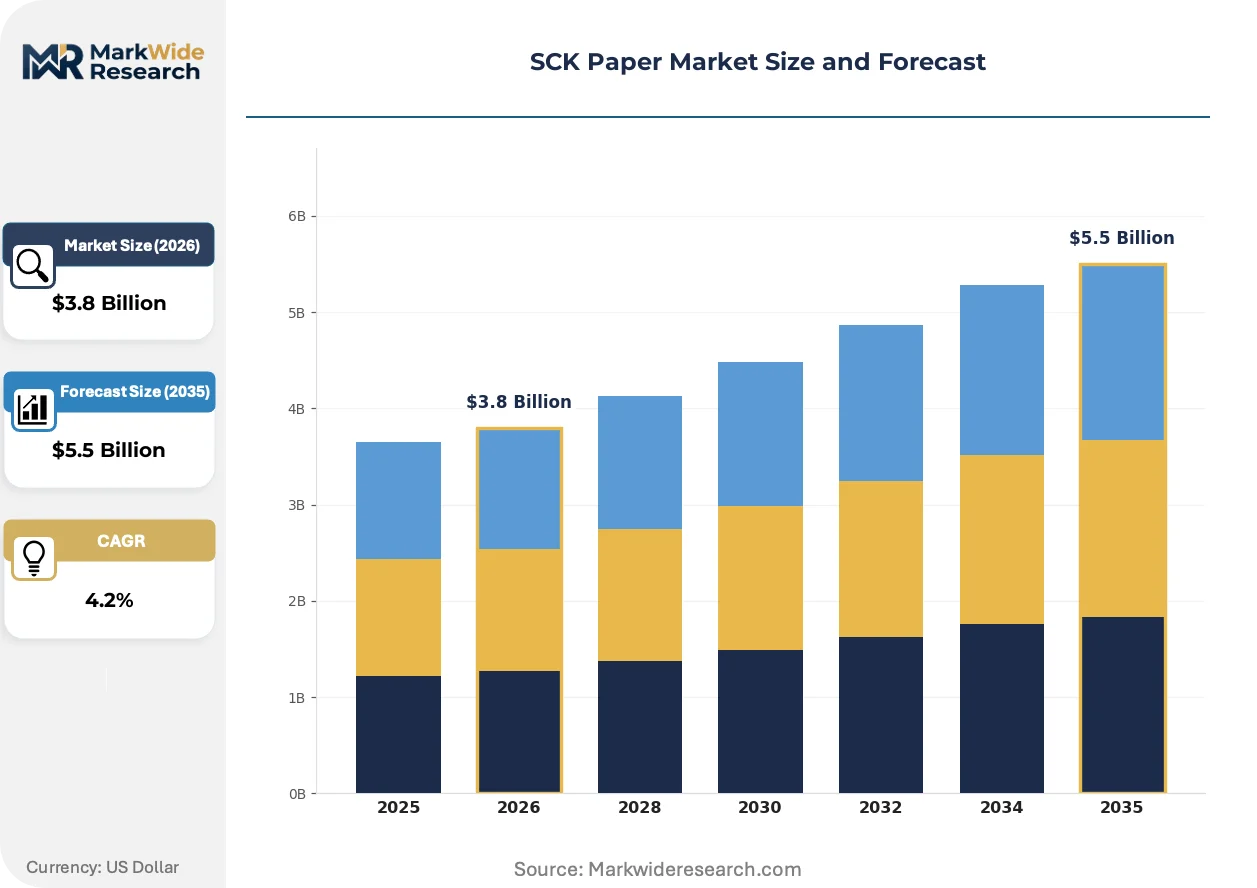
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.5 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coated Paper, Uncoated Paper, Specialty Paper, Kraft Paper End Use: Printing, Packaging, Stationery, Writing Distribution Channel: Direct Sales, Retail, Online, Wholesalers Application: Commercial, Educational, Industrial, Creative |
| Companies Covered | UPM-Kymmene Corporation, Pixelle Specialty Solutions, Kruger Specialty Papers, Cheever Specialty Paper & Film, Ahlstrom-Munksjö, Stora Enso, Taiko Paper MFG. LTD, Cotek Papers, NorCell Paper, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
SCK Paper Market Strategic Shifts
Coating chemistry innovation and regulatory chemistry restrictions are simultaneously compressing legacy formulations and opening substitution pathways across food-contact and industrial label segments.
Electron-beam curable silicone coatings are displacing thermal oven systems in high-volume North American converting lines. Major label stock producers in Ohio and Wisconsin have retrofitted coating towers to enable instant cure at ambient temperature. This technology is displacing natural gas-dependent thermal systems and eliminating silicone migration risks that previously limited basis weight reduction.
EU REACH Annex XVII restrictions on organotin catalyst residues now govern coating formulation approvals for European label converters. ECHA substance evaluation has flagged specific platinum catalyst byproducts, forcing reformulation of standard polydimethylsiloxane systems. German automotive label clusters are responding by mandating full material disclosure from SCK suppliers as a contract precondition.
Specification-grade buyers now require chain-of-custody documentation from pulp source through finished roll. European pharmaceutical and cosmetic label converters in Hamburg and Milan are rejecting spot-market purchases in favor of multi-year supply agreements with verified fiber provenance. This pattern is most visible in Germany, where automotive and pharmaceutical labeling clusters have merged procurement functions to enforce unified supplier qualification standards.
SCK Paper Market Segmentation

SCK paper procurement splits across technical specifications, end-use performance requirements, and channel economics. Converters align purchasing decisions with regulatory compliance tiers, application durability needs, and supply chain reliability metrics rather than commodity pricing alone.
Product Type:
FDA food-contact substance notifications and EU REACH Annex XVII restrictions on organotin catalyst residues create divergent qualification pathways for each substrate grade.
- Coated Paper:One-side silicone-treated substrates engineered with 40–120 gram per square meter basis weight and controlled porosity enable clean adhesive release. Specification-grade procurement from German automotive OEMs and tier-one suppliers concentrates demand for high-release variants with tight basis weight tolerances.
- Specialty Paper:Customized release profiles, dimensional stability, and print receptivity for digital presses command premium positioning. Hamburg and Milan pharmaceutical and cosmetic label converters are rejecting spot-market purchases in favor of multi-year supply agreements with verified fiber provenance for these grades.
- Uncoated Paper:Basic variants occupy mature volume positions in educational supply chains where price sensitivity dominates procurement criteria.
- Kraft Paper:Softwood kraft pulp input from Nordic and Canadian fiber markets supplies foundational stock for downstream silicone coating operations.
Established volume favors uncoated grades; emerging adoption favors specialty paper with digital press compatibility.
End Use:
Channel economics and customer technical requirements reshape procurement patterns across each consumption category.
- Packaging:North American packaging converters are expanding SCK paper adoption for premium label backing applications. UV-activated polydimethylsiloxane curing enables faster line speeds and lower energy consumption versus thermal curing systems.
- Printing:Next-generation SCK grades with optimized surface energy are opening premium short-run label segments previously served by filmic substrates. Ohio and Wisconsin label stock producers have retrofitted coating towers to support this transition.
- Stationery:Mature demand concentrates in basic office supply chains with limited specification requirements.
- Writing:Educational procurement drives volume through institutional purchasing agreements.
Packaging applications are climbing the fastest; stationery maintains baseline volume without premium capture.
Distribution Channel:
Customer scale and qualification complexity determine channel selection and service level agreements.
- Direct Sales:Major converters in Germany have merged automotive and pharmaceutical procurement functions to enforce unified supplier qualification standards through direct relationships.
- Wholesalers:Inventory pooling and logistics consolidation serve mid-tier converters lacking volume for mill-direct arrangements.
- Online:Spot-market availability supports emergency replenishment and small-batch creative applications.
- Retail:Stationery and educational supply chains rely on established distributor networks for predictable fulfillment.
Direct sales capture specification-grade volume; wholesale channels sustain mid-market converter access.
Application:
Performance requirements and regulatory exposure differentiate commercial viability across use cases.
- Industrial:Electron-beam curable silicone coatings are displacing thermal oven systems in high-volume North American converting lines. Instant cure at ambient temperature eliminates silicone migration risks that previously limited basis weight reduction.
- Commercial:Food labeling streams require validated silicone chemistries per FDA notifications, creating compliance moats that lock in qualified suppliers against unverified imports.
- Educational:Price-sensitive procurement through institutional purchasing agreements favors basic uncoated grades.
- Creative:Short-run digital press applications demand specialty grades with customized surface energy profiles.
Industrial applications show steepest expansion trajectory; educational use provides stable baseline demand without margin premium.

Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH compliance in Europe is tightening chemical disclosure requirements for silicone-coated substrates, forcing converters to requalify suppliers and reshaping procurement specifications across premium label segments. FDA food-contact substance notifications govern silicone chemistry selections for SCK papers entering US food labeling streams. Japan's METI administers JIS standards that specify basis weight tolerances and silicone adhesion thresholds for domestic converting operations.
United States
North American packaging converters are expanding SCK paper adoption for premium label backing applications. FDA food-contact substance notifications require validated silicone chemistries, creating a compliance moat that locks in qualified suppliers against unverified imports. Ohio and Wisconsin label stock producers have retrofitted coating towers to enable electron-beam curable silicone coatings.
Germany
Automotive and pharmaceutical labeling clusters in Hamburg and Baden-Württemberg drive specification-grade procurement for high-release SCK papers with tight basis weight tolerances. EU REACH Annex XVII restrictions on organotin catalyst residues now govern coating formulation approvals. German automotive OEMs and tier-one suppliers have merged procurement functions to enforce unified supplier qualification standards.
Japan
Domestic converting operations demand JIS-compliant SCK papers with verified silicone adhesion thresholds. METI standards specify basis weight tolerances that limit viable supply to established Japanese and specialty Asian mills. Tokyo and Osaka pharmaceutical label converters prioritize multi-year supply agreements with verified fiber provenance over spot-market purchases.
Finland
Integrated pulp-to-paper operations across Nordic mills sustain cost-advantaged supply to European label converters. ECHA substance evaluation has flagged specific platinum catalyst byproducts, forcing reformulation of standard polydimethylsiloxane systems. Finnish suppliers leverage ISO 14001 environmental management certification to capture premium positioning in German automotive and pharmaceutical procurement channels.
China
Domestic label stock producers are expanding capacity for food-contact compliant SCK papers serving export markets. SAMR and GB standards increasingly reference EU REACH chemical restrictions for silicone-coated substrates. Yangtze River Delta converting clusters are retrofitting coating lines to accommodate UV-activated polydimethylsiloxane curing systems.
SCK Paper Market Competitive Environment
Listed leaders compete with private specialists across capital intensity and certification depth. The vendor base concentrates around integrated pulp-to-paper operators, specialty coating converters, and regional niche suppliers. Three archetypes dominate: Nordic integrated forest products groups, North American specialty paper independents, and Asian precision converters. Competitive moves center on backward integration into softwood kraft pulp supply and multi-year qualification contracts with pharmaceutical and automotive OEMs.
Within the integrated tier, UPM-Kymmene Corporation and Stora Enso represent Nordic forest products groups with captive pulp supply. Among North American specialists, Pixelle Specialty Solutions exemplifies deep focus on silicone-compatible base papers. Kruger Specialty Papers anchors Canadian supply to North American label converters. These named entities occupy positions that reflect broader structural patterns rather than individual strategic choices.
| Leading Market Players |
|---|
| UPM-Kymmene Corporation |
| Pixelle Specialty Solutions |
| Kruger Specialty Papers |
| Cheever Specialty Paper & Film |
| Ahlstrom-Munksjö |
| Stora Enso |
| Taiko Paper MFG. LTD |
| Cotek Papers |
| NorCell Paper |
| Others |
Value Chain & Pricing Dynamics
Electron-beam curable silicone coatings displacing thermal oven systems simultaneously redraw supply geography toward Ohio and Wisconsin retrofit hubs and compress energy cost differentials that previously favored Nordic pulp integration. This substitution dynamic concentrates pricing power with coating technology licensors while eroding the margin buffers of legacy thermal-dependent converters.
Pricing Analysis
Certification level creates the primary spread, with ISO 14001-qualified supply commanding substantial premiums over uncertified alternatives in German automotive procurement channels. Three-tier pricing structure across REACH-compliant, FDA-notified, and basic industrial grades reflects divergent qualification burdens. Cost compression in standard-grade uncoated paper is intensifying because educational procurement channels prioritize spot-market sourcing. Pharmaceutical and food-label converters exhibit the lowest price sensitivity due to regulatory substitution risks, while stationery distributors face acute margin pressure from commoditized Asian supply.
Supply Chain Analysis
Just-in-time inventory preferences dominate North American packaging converters seeking UV-curing line efficiency, whereas European pharmaceutical clusters maintain strategic stockpiles against REACH-driven supply requalification delays. Geographic concentration centers on Finland, Sweden, and Germany for specification-grade output, with China expanding food-contact compliant capacity for export markets. Softwood kraft pulp from Nordic and Canadian fiber markets, platinum catalyst systems, and specialized calendering equipment constitute critical input dependencies. Single-source vulnerability concentrates around narrow-web precision paper machines limited to a handful of European and North American mills. Distribution runs through direct mill relationships for qualified volume, with wholesale channels serving mid-tier converter access.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
SCK paper procurement is consolidating around platform-standardized qualification systems that reward ecosystem breadth over point-product optimization, as German automotive and pharmaceutical clusters merge supplier validation databases into unified interoperability frameworks.
For Market Incumbents: Secure multi-year fiber provenance contracts with Nordic pulp suppliers before ECHA substance evaluation triggers further coating reformulation cycles. Deepen captive softwood kraft supply through backward integration into Canadian fiber markets to defend margin position against Asian cost competition. Lock in electron-beam curing technology licensing to maintain technology differentiation as UV-activated systems commoditize. For New Entrants and Emerging Players: Lead with bio-based coating alternatives targeting sustainability premiums in Hamburg and Milan pharmaceutical converter channels, where verified fiber provenance commands contract preference over spot-market pricing. Target Chinese domestic label stock producers retrofitting Yangtze River Delta coating lines for UV-curing compatibility, offering technical partnership rather than direct mill competition. Establish JIS calibration capability to access Japanese pharmaceutical serialization demand underserved by European-qualified supply. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated pulp-to-paper operators with captive certification depth over standalone coating converters. Long-term viability over the next decade rests on backward integration into fiber supply and multi-year OEM qualification contracts rather than volume scale alone. Watch for EU REACH Annex XVII expansion into additional platinum catalyst byproducts as the inflection signal that would accelerate supplier attrition and create acquisition opportunities among reformulation-lagged independents.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Softwood Kraft Pulp | Captive Nordic and Canadian fiber supply insulates margin compression from commodity volatility. |
| Electron-Beam Curing Technology Licensing | Ohio and Wisconsin retrofit demand creates first-mover advantage in ambient-temperature coating systems. |
| REACH-Compliant Coating Reformulation | ECHA organotin and platinum catalyst restrictions force supplier requalification that locks out unverified imports. |
| Multi-Year Fiber Provenance Contracts | Hamburg and Milan pharmaceutical converters reject spot-market purchases for verified chain-of-custody documentation. |
| JIS Calibration Capability Investment | Tokyo and Osaka pharmaceutical label demand requires specialized silicone adhesion testing equipment scarce outside established supply bases. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade customs data, and industry association reports to construct validated supply and demand estimates. Primary interviews engaged coating line engineers at North American label stock producers, procurement directors at German automotive tier-one suppliers, technical R&D leads at Nordic pulp integrators, and regulatory affairs specialists at EU-based converters. Secondary validation drew from ECHA substance evaluation databases, FDA food-contact substance notifications, JIS standard documentation, and SEC filings of listed forest products groups. Bottom-up capacity and consumption modeling triangulated against top-down macroeconomic drivers.
Segmentation dimensions modeled include product type tier, end-use application, distribution channel structure, and regional regulatory cluster across the analysis window. Value projections incorporate coating technology substitution curves, certification penetration rates, and fiber input cost trajectories. CAGRs derive from fitted growth curves applied to baseline consumption estimates, with cross-reference to historical volatility patterns in softwood kraft pulp markets and silicone chemistry cost structures.
Forecasts assume regulatory continuity in EU REACH, FDA food-contact notification pathways, and Japanese METI standards; material policy shifts would require re-modeling. Revision becomes warranted when PFAS substitution timelines accelerate beyond silicone alternative performance parity or when Nordic pulp supply disruptions exceed historical volatility bands.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Protective Paperboard Market
Paper & Paperboard Packaging
North America Corrugated Packaging Market
Paper & Paperboard Packaging
Coated Paper Market
Paper & Paperboard Packaging
Paperboard Packaging Market
Paper & Paperboard Packaging
Transfer Paper Market
Paper & Paperboard Packaging
Dunnage Paper Bags Market
Paper & Paperboard Packaging
Middle East Corrugated Packaging Market
Paper & Paperboard Packaging
Paperboard Partition Market
Paper & Paperboard Packaging
Paperboard Bowl Market
Paper & Paperboard Packaging
South East Asia Corrugated Packaging Market
Paper & Paperboard Packaging
Die Cut Box Market
Paper & Paperboard Packaging
Coated White Board Paper Market
Paper & Paperboard Packaging
Push-Pull Slip Sheets Market
Paper & Paperboard Packaging
Waxed Paper Packaging Market
Paper & Paperboard Packaging
Liquid Packaging Board Market
Paper & Paperboard Packaging
Tissue and Hygiene Paper Packaging Market