
 Decal Paper Market | 2026-2036
Decal Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Decal Paper Market Analysis
Aftermarket service revenue is rewriting how decal paper suppliers capture lifetime value. Avery Dennison Corporation leverages its global distribution network to dominate fleet and vehicle graphics segments. Felix Schoeller Group anchors European demand through specialized coated substrates for industrial transfer applications. Mondi plc competes on sustainable fiber sourcing, positioning its product line for tightening packaging regulations.
Decal paper comprises coated or uncoated substrates engineered with release liners, silicone layers, and receptive topcoats to accept inkjet, laser, or screen-printed imagery for subsequent transfer onto glass, metal, plastic, or ceramic surfaces. Vinyl product types sustain premium pricing due to durability requirements in automotive and outdoor commercial installations, while water-soluble backing materials are gaining share in household craft and temporary decorative applications where clean removal matters. Specialty transparent grades lead margin pools for electronics and appliance labeling, whereas pressure-sensitive adhesive configurations occupy the volume core across industrial barcode and safety signage deployments.
EPA volatile organic compound rules and REACH substance restrictions are forcing reformulation of solvent-based adhesives and coatings across North American and European supply chains. FDA indirect food contact standards govern decal paper used in beverage and food packaging applications, creating compliance barriers for uncertified imports. ISO printability and adhesion test protocols shape procurement specifications for multinational brand owners. Stakeholders must monitor how biobased substrate alternatives perform against existing silicone release and thermal transfer benchmarks before committing capital to capacity expansion.
Market Dynamics
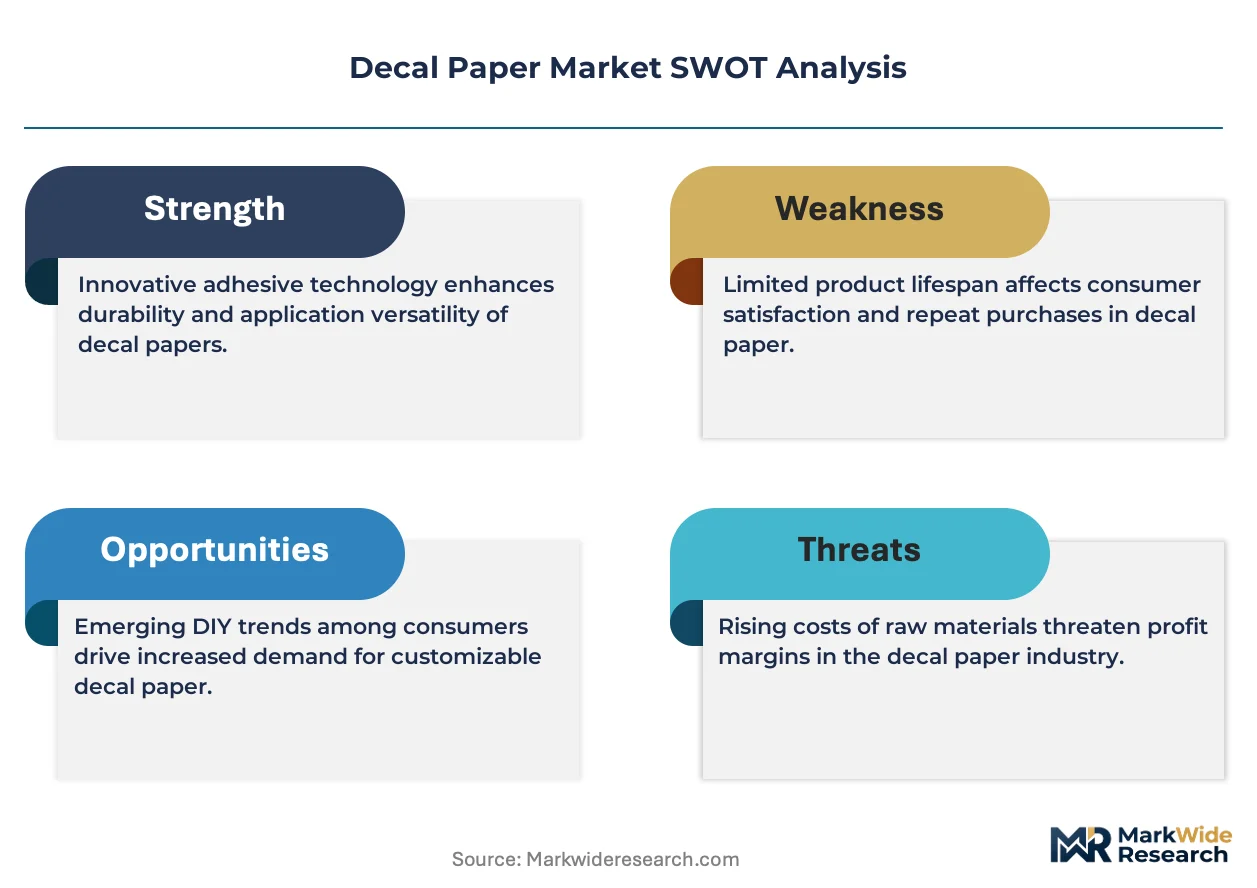
REACH substance restrictions and EPA volatile organic compound rules are forcing simultaneous reformulation of solvent-based adhesives and silicone release coatings across North American and European supply chains, compressing margins for uncertified converters while rewarding pre-compliant substrate suppliers.
Growth Catalysts
- Fleet graphics standardization:Commercial vehicle wrap installers in Germany and Japan are specifying premium vinyl decal substrates with extended outdoor durability warranties, pulling volume through certified distributor networks.
- REACH Article 33 disclosure mandates:ECHA enforcement of Substances of Very High Concern reporting is disqualifying non-compliant Asian imports from European industrial labeling procurement tenders.
- Water-soluble backing innovation:Temporary decorative applications in household craft segments are migrating from permanent adhesive systems to clean-removal substrates, opening new volume pools outside traditional industrial buyers.
Market Restraints
- Petrochemical input volatility:Polyvinyl chloride resin and silicone release coating prices fluctuate with crude oil derivatives, compressing converter margins on fixed-price contract volumes.
- Substrate supply concentration:Specialty coated paper mills in Scandinavia and coated film extruders in South Korea control critical capacity for electronics-grade transparent decal stocks.
- Digital printing substitution:Direct-to-shape inkjet systems on glass and metal containers are bypassing transfer decal steps in premium beverage packaging runs.
Strategic Opportunities
- India industrial corridor expansion:BIS certification requirements for safety signage in Maharashtra and Gujarat manufacturing zones are creating compliant-substrate demand that domestic converters cannot yet satisfy.
- Biobased substrate development:Cellulose nanofiber alternatives to petroleum-based backings align with EU Green Deal procurement preferences in public sector signage contracts.
- E-commerce sample-to-bulk channel:Online craft marketplaces are enabling direct-to-hobbyist distribution of small-format decal paper, bypassing traditional wholesale paper merchant networks.
Industry Challenges
- Adhesion certification timelines:ISO 29862 peel strength and ASTM D3330 protocol validation for new adhesive formulations extends product development cycles by 8-14 months.
- Legacy screen-printing integration:Hybrid production environments must reconcile UV-inkjet color management with solvent-based screen ink curing profiles, complicating workflow standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Decal Paper Market |
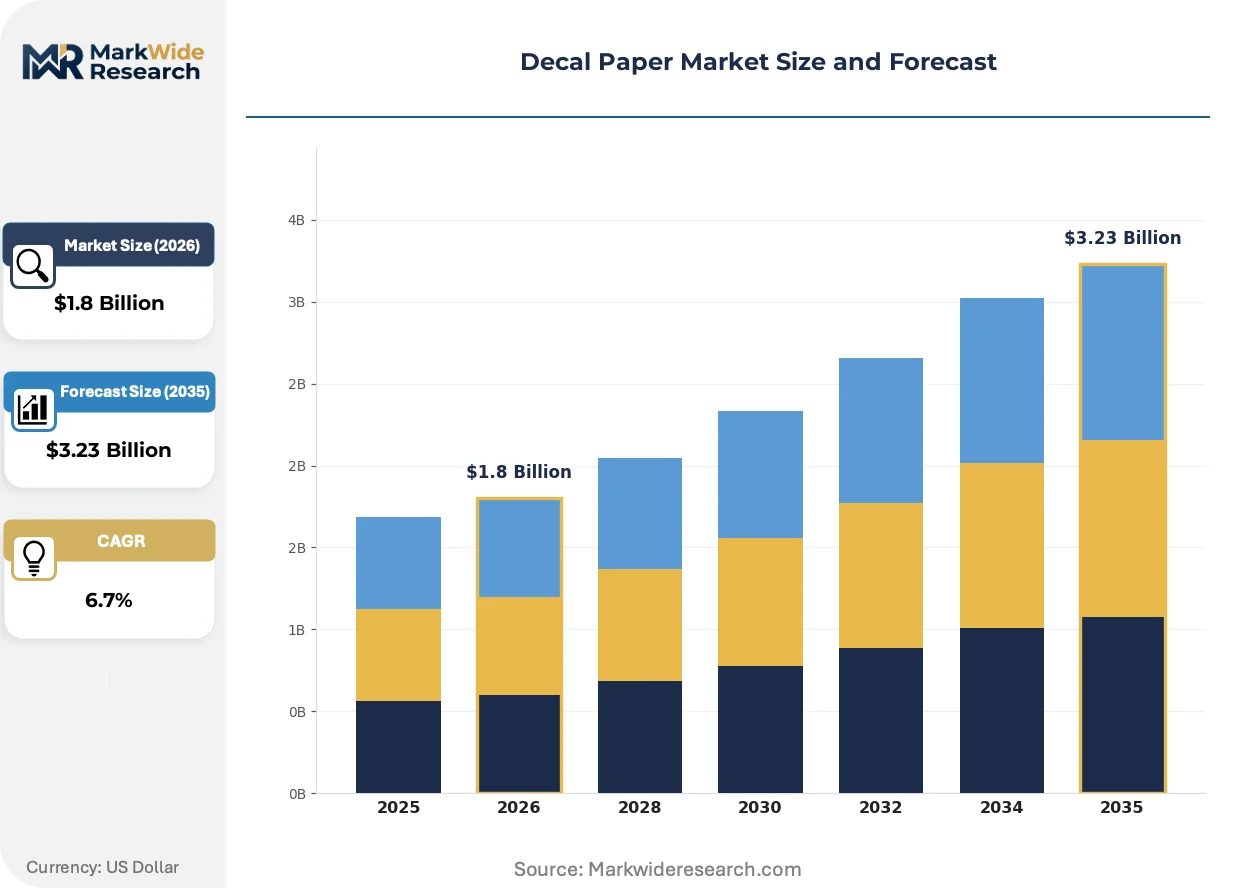
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vinyl, Paper, Transparent, Specialty Application: Automotive, Household, Commercial, Industrial Backing Material: Adhesive, Non-Adhesive, Water-Soluble, Pressure-Sensitive Distribution Channel: Online Retail, Wholesale, Direct Sales, Specialty Stores |
| Companies Covered | Mondi plc, Glatfelter, Avery Dennison Corporation, Lintec Corporation, Felix Schoeller Group, Tullis Russell Group, Fujifilm Holdings Corporation, UPM-Kymmene Corporation, 3M Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Decal Paper Market Emerging Trajectories
Active reformulation of release coatings and adhesive chemistries is compressing product development cycles while opening substitution pathways for petrochemical-dependent substrate systems. Three developments are restructuring competitive positioning.
Laser-compatible topcoat technologies with enhanced toner adhesion and heat resistance are rendering obsolete traditional inkjet-optimized decal papers in office and light production environments. Corporate in-house signage departments and franchise print shops are adopting these substrates at accelerating rates, compressing demand for dual-purpose coated stocks and forcing substrate suppliers to segment their product architectures by output technology rather than attempting universal compatibility.
EPA National Emission Standards for Hazardous Air Pollutants for surface coating operations are tightening volatile organic compound limits on adhesive drying processes. Industrial converters in Ohio, Michigan, and Texas are retrofitting thermal oxidizers or migrating to water-based adhesive systems, with food-contact beverage labeling applications facing the most acute compliance timelines due to overlapping FDA indirect additive migration requirements.
Consolidated procurement by multinational fleet management operators is compressing supplier bases and unbundling aftermarket graphics from vehicle acquisition contracts. Tier-one automotive leasing companies in Germany and commercial truck operators in California are specifying single-source decal substrate approvals spanning wrap films, transfer papers, and protective overlaminates, displacing fragmented purchasing across multiple converter relationships and concentrating volume with vertically integrated material suppliers capable of certificate-of-analysis documentation at batch level.
Decal Paper Market Segmentation
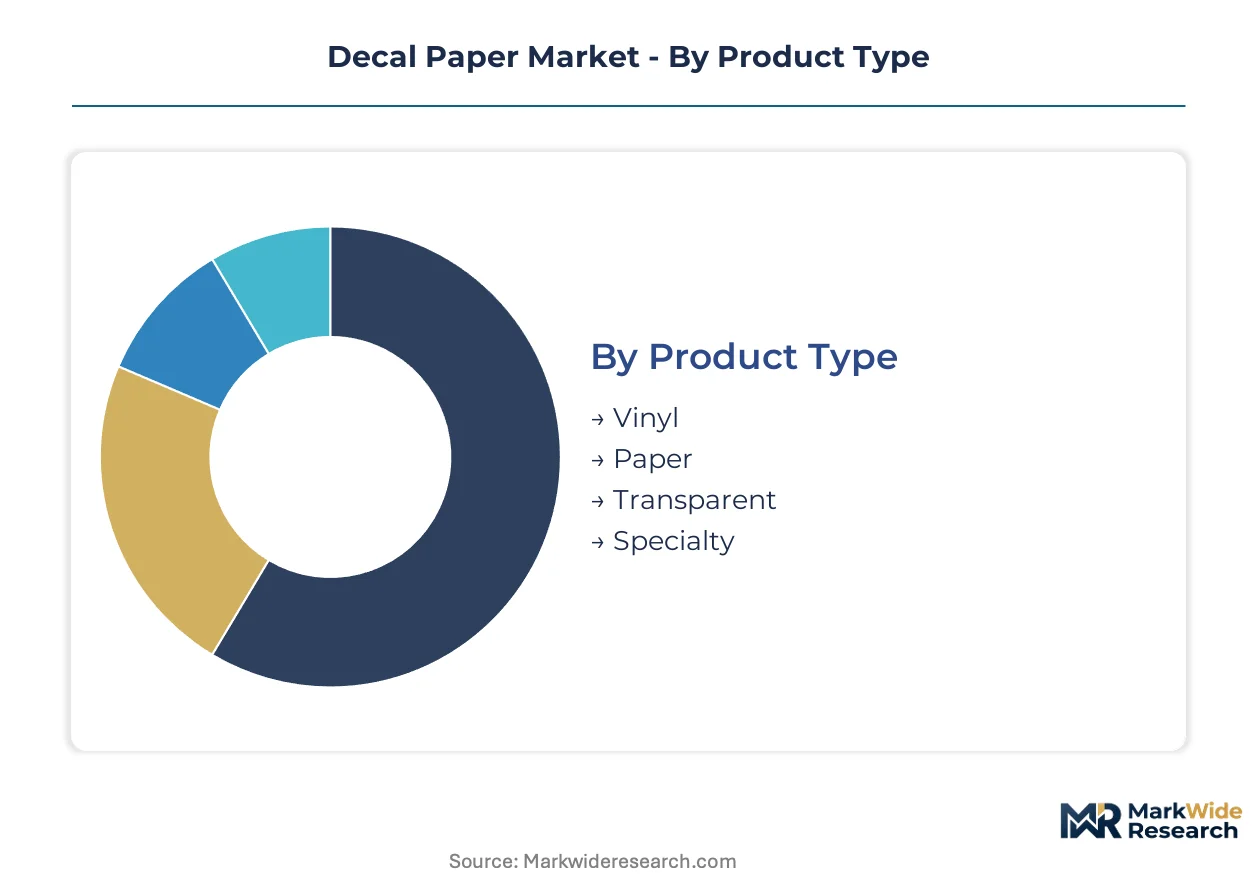
Decal paper segmentation reveals how substrate chemistry, application environment, and procurement channel determine margin structure and compliance burden. Suppliers must align formulation investments with the durability, removability, and regulatory requirements of each vertical.
Product Type:
Cost tier differentiation separates commodity substrates from performance-grade materials with certified outdoor lifespans and specialized optical properties.
- Vinyl:Polyvinyl chloride-based substrates with UV-stabilized face stocks and permanent or removable adhesive systems. Fleet graphics installers in Germany specify these for vehicle wraps requiring 5-7 year outdoor durability warranties under ECHA substance restrictions.
- Transparent:Optically clear polyester or polypropylene films with silicone release liners for electronics and appliance labeling. Japan's precision electronics manufacturers drive specifications for haze-free appearance and laser-print compatibility.
- Paper:Clay-coated or cast-coated stocks with solvent or water-based receptive layers for indoor short-term applications. Craft segments and temporary promotional signage favor these for cost efficiency and ink absorption.
- Specialty:Heat-resistant, chemical-resistant, or metalized substrates for industrial process labeling and aerospace applications. These command premium positioning through ISO-certified performance validation.
Vinyl commands the established base. The steepest expansion runs through transparent grades serving electronics miniaturization trends.
Application:
End-use environment dictates adhesive chemistry, substrate thickness, and surface preparation requirements across diverging performance specifications.
- Automotive:Exterior-grade vinyl decals with pressure-sensitive adhesives formulated for painted metal, glass, and thermoplastic olefin surfaces. California Air Resources Board VOC rules and EPA NESHAP compliance shape converter qualification requirements.
- Industrial:Safety signage, equipment labeling, and barcode applications requiring chemical resistance and aggressive adhesion to powder-coated metals. BIS certification mandates in Maharashtra and Gujarat manufacturing corridors are pulling compliant substrate demand.
- Commercial:Point-of-sale graphics, window signage, and architectural installations balancing visual impact with clean removability. Water-soluble backing innovations are penetrating this segment for temporary campaigns.
- Household:Craft, décor, and personal customization applications prioritizing ease of use and safe handling. E-commerce sample-to-bulk channels are fragmenting traditional wholesale distribution here.
Industrial applications command the established base. The steepest expansion runs through automotive as fleet standardization concentrates procurement.
Backing Material:
Release mechanism and adhesive permanence determine application workflow, end-user skill requirements, and environmental compliance exposure.
- Pressure-Sensitive:Permanent or removable acrylic adhesives on silicone-coated release liners for immediate bond without activation. This configuration dominates industrial barcode and safety signage volume.
- Water-Soluble:PVA or starch-based backings that dissolve for clean removal without residue. Household craft segments and temporary commercial graphics are migrating to these substrates.
- Adhesive:Heat-activated or solvent-activated systems requiring external energy or chemical preparation for bond formation. Specialty industrial applications retain these for extreme environment performance.
- Non-Adhesive:Static-cling or vacuum-form substrates relying on mechanical rather than chemical attachment. Window graphics and reusable signage favor these for repositionability.
Pressure-sensitive configurations command the established base. The steepest expansion runs through water-soluble backings serving clean-removal demand.
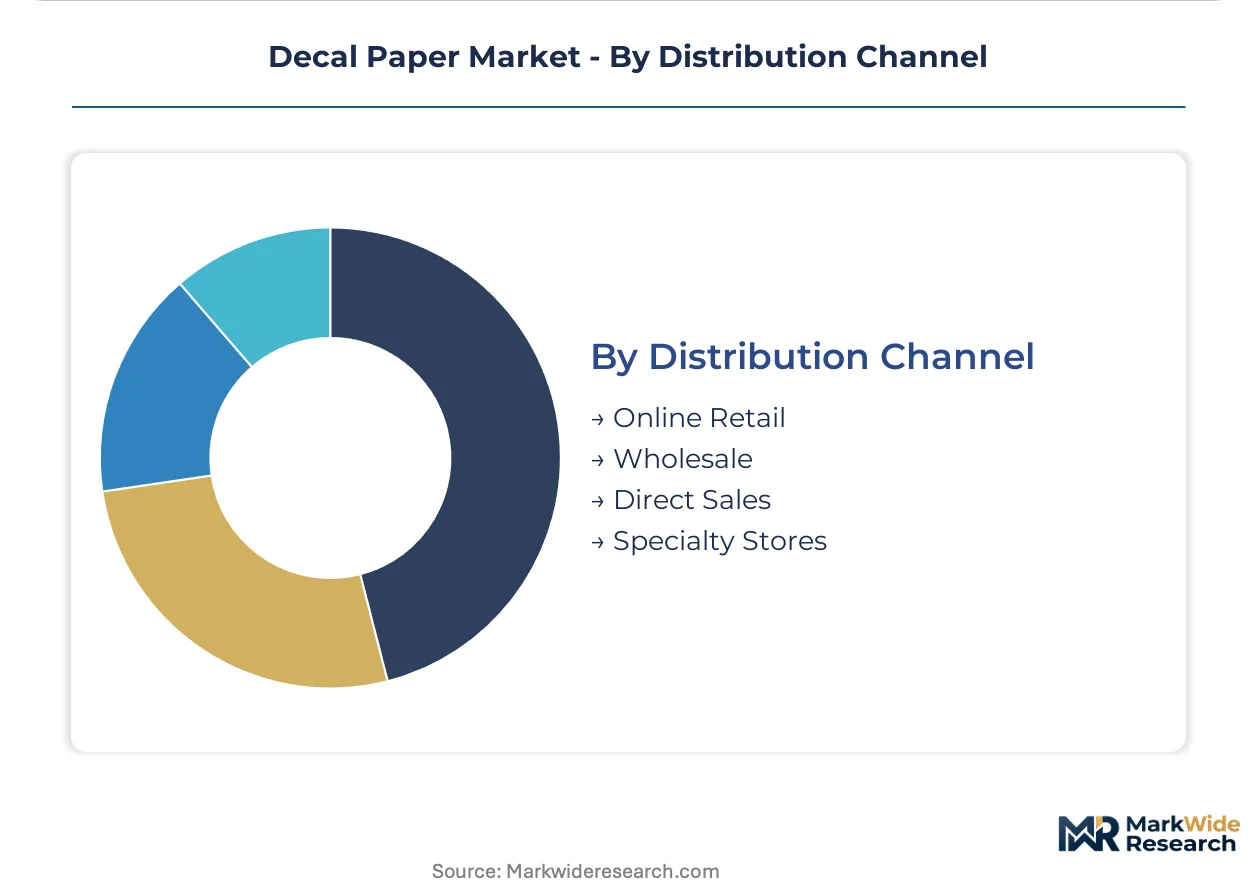
Distribution Channel:
Customer scale and technical support requirements segment procurement pathways from self-service hobbyist purchases to engineered specification programs.
- Wholesale:Volume supply through paper merchants and industrial distributors to commercial printers and sign shops. Fleet graphics standardization is consolidating purchasing through certified distributor networks.
- Direct Sales:Manufacturer-to-converter relationships for custom-coated substrates with certificate-of-analysis documentation. Tier-one automotive leasing companies in Germany specify these channels for batch-level traceability.
- Online Retail:Small-format, pre-cut, or sample-sized products targeting hobbyists and small businesses. Craft marketplaces are enabling direct-to-consumer bypass of traditional merchant networks.
- Specialty Stores:Art supply and hobby retailers with staff expertise for customer education. These outlets retain relevance where substrate selection requires hands-on evaluation.
Wholesale channels command the established base. The steepest expansion runs through online retail capturing fragmented craft and small-business demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity in decal paper procurement diverges sharply by end-use sophistication. Fleet graphics installers in Germany absorb premium vinyl substrate costs for warranty-backed durability, while Indian safety signage buyers face acute pressure to source BIS-certified materials without compliant domestic supply.
Germany
Fleet graphics standardization by automotive leasing companies drives premium vinyl substrate demand. ECHA enforcement of REACH Article 33 SVHC disclosure mandates disqualifies non-compliant imports from industrial tenders. The North Rhine-Westphalia industrial corridor concentrates converter capacity serving vehicle wrap installers with certificate-of-analysis documentation.
United States
Commercial truck operators in California and fleet management companies across the Midwest specify single-source substrate approvals. EPA National Emission Standards for Hazardous Air Pollutants tighten VOC limits on adhesive drying processes, forcing Ohio and Michigan converters to retrofit thermal oxidizers. The Ohio-Michigan-Texas manufacturing triangle hosts the majority of industrial labeling production.
Japan
Precision electronics manufacturers drive specifications for haze-free transparent films with laser-print compatibility. METI standards on chemical substance management in manufacturing supply chains shape procurement protocols. The Kanto region around Tokyo anchors demand for optically clear polyester substrates in appliance and electronics labeling.
India
BIS certification requirements for safety signage in Maharashtra and Gujarat manufacturing zones outpace domestic converter capability. The country's national standards body mandates compliance for industrial barcode and equipment labeling applications. The Maharashtra-Gujarat industrial corridor generates pull for imported compliant substrates that local mills cannot yet satisfy.
South Korea
Coated film extruders control critical capacity for electronics-grade transparent decal stocks serving regional OEM demand. The country's Ministry of Environment enforces chemical registration requirements on adhesive formulations. The Gyeonggi-Seoul manufacturing cluster specializes in high-clarity films for consumer electronics and automotive display applications.
Decal Paper Market Vendor Landscape
Capability concentration sits with specialized coated substrate engineers; scale advantage sits with diversified materials conglomerates. The vendor base stratifies between vertically integrated film extruders, regional paper merchants with coating partnerships, and niche transparent film specialists. Three archetypes dominate: industrial-grade substrate engineers with ISO-certified validation protocols, sustainable fiber sourcing platforms aligned with EU Green Deal procurement, and precision coating specialists serving electronics miniaturization trends. Competitive moves center on batch-level traceability documentation for fleet procurement and biobased substrate development for public sector contracts.
Within the diversified materials tier, Mondi plc and Avery Dennison Corporation exemplify divergent scale strategies. Mondi anchors European positioning through sustainable fiber sourcing credentials that align with tightening packaging regulations. Avery Dennison leverages global distribution infrastructure to concentrate fleet and vehicle graphics volume through certified channel networks. Felix Schoeller Group occupies a specialized position among coated substrate engineers, serving industrial transfer applications with release liner and receptive topcoat expertise. These three represent the capability-scale spectrum: fiber-sourced sustainability, distribution-integrated scale, and precision coating specialization.
| Leading Market Players |
|---|
| Mondi plc |
| Glatfelter |
| Avery Dennison Corporation |
| Lintec Corporation |
| Felix Schoeller Group |
| Tullis Russell Group |
| Fujifilm Holdings Corporation |
| UPM-Kymmene Corporation |
| 3M Company |
| Others |
Supply Flow & Price Mechanics
Rotterdam-Antwerp freight corridors shape cost dynamics for specialty coated substrates moving from Scandinavian mills to German fleet graphics installers, compressing margins for uncertified converters while rewarding pre-compliant suppliers with certificate-of-analysis documentation and tiered pricing power.
Pricing Analysis
Aftermarket service revenue from extended durability warranties and fleet maintenance contracts drives lifetime value capture. Three-tier pricing structure across premium vinyl with REACH certification, standard industrial grades, and economy paper stocks reflects divergence in warranty backing and regulatory documentation. Pricing pressure stems from petrochemical input volatility in silicone release coatings and polyvinyl chloride resins. Fleet graphics installers in Germany absorb premium tiers for warranty-backed outdoor durability, while Indian safety signage buyers face acute price sensitivity due to limited BIS-certified domestic supply.
Supply Chain Analysis
Tariff exposure between South Korea and Japan dominates supply chain risk for electronics-grade transparent decal stocks. Specialty coated paper mills in Scandinavia and coated film extruders in South Korea control critical capacity, drawing from petrochemical feedstocks, silicone release formulations, and cellulose pulp grades. Single-source vulnerability concentrates in transparent polyester films for precision electronics labeling. Distribution runs through certified industrial distributors and direct manufacturer-to-converter channels with batch-level traceability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Water-soluble backing innovation and biobased substrate development are disrupting traditional petrochemical-dependent supply chains, with EPA NESHAP compliance timelines and EU Green Deal procurement preferences accelerating the inflection.
For Market Incumbents: Entrench certification advantage by accelerating REACH Article 33 documentation and ISO 29862 peel strength validation for adhesive formulations. Deepen backward integration into silicone release coating production to defend margin position against petrochemical price volatility. Capture fleet graphics standardization volume through exclusive distributor network lock-ups with tier-one automotive leasing companies.
For New Entrants and Emerging Players: Pursue Maharashtra and Gujarat industrial corridor demand for BIS-certified safety signage substrates where domestic converter capability lags. Target online craft marketplace distribution for water-soluble backing products to bypass entrenched wholesale paper merchant networks. Lead with e-commerce sample-to-bulk channel strategies for household craft segments.
For Investors and Strategic Acquirers: Precision coating specialists with laser-compatible topcoat technologies and electronics-grade transparent film capabilities offer the strongest acquisition profile. Long-term viability hinges on biobased substrate performance validation against existing silicone release benchmarks. Watch for EPA enforcement actions on volatile organic compound limits as the signal for accelerated water-based adhesive system adoption.
| Strategic Initiative | Industry Significance |
|---|---|
| Biobased Substrate Development | Cellulose nanofiber alternatives align with EU Green Deal public sector procurement preferences. |
| REACH Certification Investment | ECHA Article 33 SVHC documentation disqualifies non-compliant Asian imports from European tenders. |
| Fleet Graphics Standardization | Single-source approvals with German automotive leasing companies concentrate volume with integrated suppliers. |
| Water-Soluble Backing Scale-Up | Clean-removal substrates capture household craft migration from permanent adhesive systems. |
| Laser-Compatible Topcoat Launch | Enhanced toner adhesion renders inkjet-optimized stocks obsolete in corporate signage departments. |
Methodological Framework
Desk research of customs trade data, SEC filings from diversified materials conglomerates, and ECHA substance restriction databases preceded structured interviews with coated substrate plant managers, fleet graphics procurement leads at automotive leasing companies, industrial distributor channel partners, and technical R&D directors at release liner specialists. Primary fieldwork with vehicle wrap installers in Germany and electronics manufacturers in Japan validated secondary estimates. Bottom-up volume triangulation across product type, application, and backing material segments was cross-checked against top-down market sizing.
Assumptions around REACH enforcement intensity, EPA NESHAP compliance timelines, and biobased substrate performance maturation were held fixed while petrochemical input cost trajectories and fleet standardization adoption rates were stress-tested. Segmentation modeling spanned substrate chemistry, end-use environment, procurement channel, and regional regulatory cluster. CAGRs were derived from installed base growth, replacement cycle analysis, and technology substitution curves. Forecast inputs incorporated BIS certification rollout pace in Indian manufacturing corridors and METI chemical substance management protocol adoption.
Sensitivities concentrate around ECHA enforcement actions on Substances of Very High Concern, EPA volatile organic compound rulemaking on adhesive drying processes, and breakthrough performance validation for cellulose nanofiber alternatives. Forecasts reflect these assumptions with explicit acknowledgment that regulatory acceleration or biobased substrate failure against silicone release benchmarks would necessitate material revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Ultraflute Paper Market
Paper & Paperboard Packaging
Push-Up Paperboard Tube Market
Paper & Paperboard Packaging
Composite Paper Cans Market
Paper & Paperboard Packaging
Countertop Paper Napkin Dispenser Market
Paper & Paperboard Packaging
Retail Paper Bags Market
Paper & Paperboard Packaging
Latin America Paper Packaging Market
Paper & Paperboard Packaging
Asia Pacific Paper Packaging Market
Paper & Paperboard Packaging
Paper Canisters Market
Paper & Paperboard Packaging
Machine Glazed Kraft Paper Market
Paper & Paperboard Packaging
Cellular Paper Cardboard Market
Paper & Paperboard Packaging
Paper Band Market
Paper & Paperboard Packaging
Global Window Cake Box Market
Paper & Paperboard Packaging
US Paper Cups and Paper Plates Market
Paper & Paperboard Packaging
Kraft Bubble Mailers Market
Paper & Paperboard Packaging
Chipboard Box Market
Paper & Paperboard Packaging
Masking Paper Market