
 Waxed Paper Packaging Market | 2026-2036
Waxed Paper Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Waxed Paper Packaging Market Analytics
Multi-source procurement among large food-service buyers is consolidating toward a smaller set of qualified suppliers with integrated coating capabilities. International Paper leverages its North American pulp network to secure feedstock cost advantages for waxed paper grades. WestRock anchors its position through containerboard integration that extends into specialty coated papers for food contact. Novolex differentiates via direct relationships with quick-service chains that demand consistent lot-to-lot barrier performance.
Waxed paper packaging denotes kraft or sulfite paper substrates impregnated or surface-coated with paraffin, microcrystalline wax, or vegetable-based waxes to impart moisture resistance and grease barrier properties, typically achieving oil-kit values of 4-12 and moisture vapor transmission rates below 10 g/m²/day. The material serves primarily as a disposable food-contact wrapper, liner, and interleaving medium across commercial kitchens, bakeries, and retail deli counters. Food wrap occupies the largest volume share within product type segmentation, while compostable certification grades are expanding fastest as buyers face procurement mandates from corporate sustainability programs. Cupstock applications sustain premium pricing due to the technical precision required for roll-fed hot-drink sleeve forming and leak resistance under thermal stress.
FDA food-contact regulations under 21 CFR 176.170 govern wax and wax-polymer coatings in the United States, while the EU Framework Regulation EC 1935/2004 sets migration limits that directly determine which wax formulations gain market access across member states. FSC chain-of-custody certification has become a de facto tender requirement for supply contracts with multinational food retailers, effectively filtering out uncertified mills from qualified vendor lists. Stakeholders must monitor the pace at which regional compostability standards diverge, since conflicting test protocols between ASTM D6400 and EN 13432 create formulation complexity for suppliers serving multiple jurisdictions.
Market Dynamics
Quick-service restaurant chains are consolidating supplier relationships around certified compostable waxed paper grades as single-use plastic bans harden procurement mandates across North America and Western Europe. This buyer concentration is compressing vendor margins while elevating technical qualification barriers for new market entrants.
Growth Catalysts
- EU Single-Use Plastics Directive:Article 5 restrictions on plastic food containers and wrappers are mandating paper-based alternatives across member states, with enforcement tightening in France, Germany, and Italy through 2025-2026 implementation deadlines.
- Quick-service restaurant sustainability mandates:Corporate procurement programs at major burger and bakery chains now require compostable certification as a tender precondition, pulling volume toward qualified coated-paper suppliers.
- Vegetable-based wax formulations:Soy and carnauba wax coatings are achieving grease-barrier parity with paraffin while satisfying ASTM D6400 and EN 13432 compostability protocols.
Market Restraints
- Crude oil price volatility:Paraffin wax remains the dominant coating feedstock, tying production costs to petroleum markets that have swung 40% annually since 2022.
- Integrated pulp-to-paper concentration:North American virgin kraft supply is controlled by a handful of mill complexes, limiting negotiating leverage for independent converters.
- Silicone-coated parchment substitution:High-temperature bakery applications above 200°C are migrating to silicone release liners that withstand thermal stress beyond waxed paper limits.
Strategic Opportunities
- India food-service expansion:Quick-service pizza and burger chains in Mumbai, Delhi, and Bangalore are adopting waxed paper liners as FSSAI tightens plastic-contact restrictions for hot foods.
- Home meal-kit delivery channels:Subscription food boxes require moisture-resistant interleaving for pre-portioned proteins, opening specification work with cold-chain logistics providers.
- Extended Producer Responsibility schemes:France's Citeo packaging fee modulation rewards compostable materials with lower eco-modulation rates, creating cost advantages over conventional plastic laminates.
Industry Challenges
- Composting infrastructure mismatch:Industrial composting facility coverage remains sparse in the US Midwest and Southern states, undermining the end-of-life value proposition for certified grades.
- Lot-to-lot barrier consistency:Quick-service chains are rejecting shipments that fail oil-kit testing, forcing converters to invest in inline coating weight monitoring and statistical process control systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Waxed Paper Packaging Market |
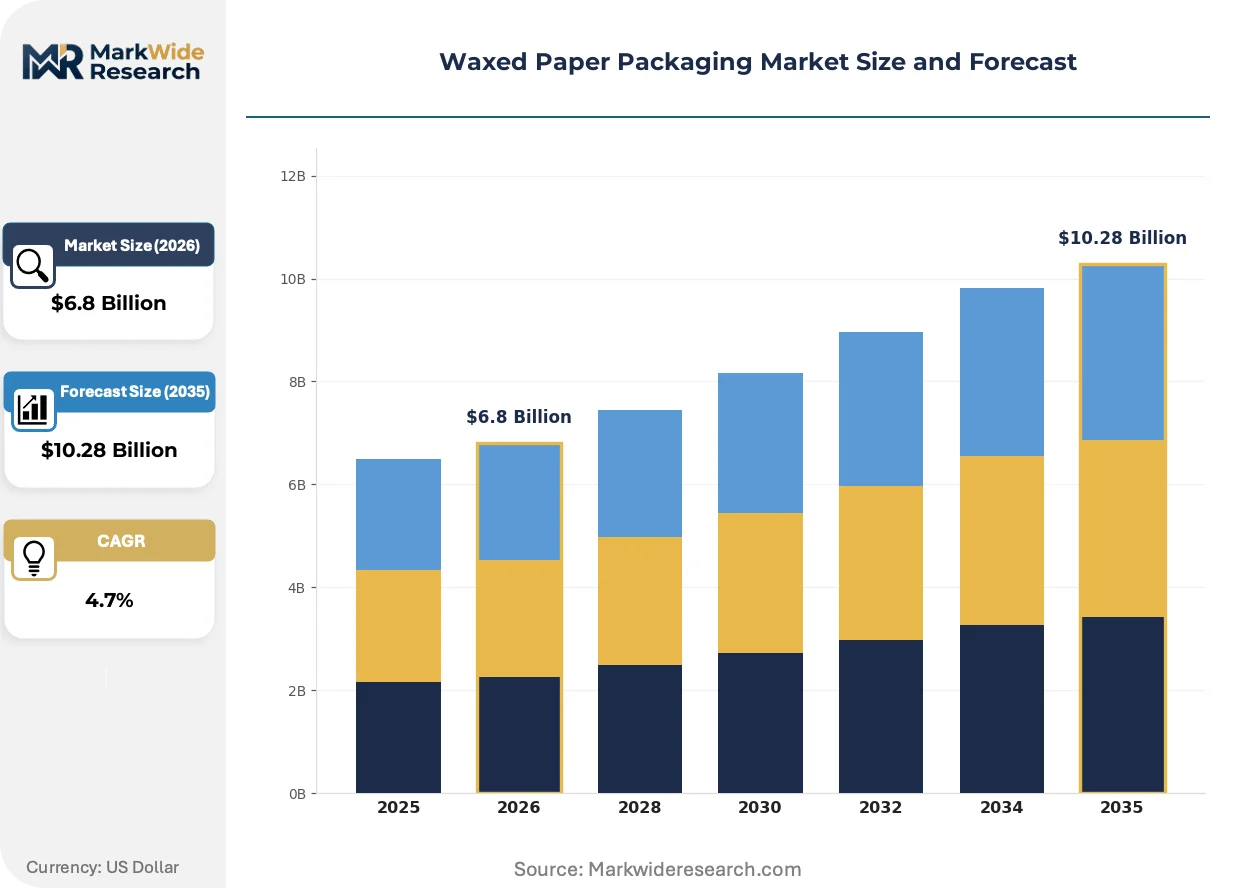
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Wrap, Baking Paper, Cupstock, Thermal Paper End User: Food Service, Retail, Industrial, Hospitality Thickness: Lightweight, Mediumweight, Heavyweight, Ultra-heavyweight Certification: FDA Approved, FSC Certified, Recyclable, Compostable |
| Companies Covered | International Paper, WestRock, Novolex, Bomarko Inc., Smurfit Kappa Group, Georgia-Pacific LLC, Pactiv Evergreen Inc., Packaging Products (Coatings) Ltd, Oji Holdings Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Waxed Paper Packaging Market Evolving Landscape
Coating chemistry and substrate engineering are converging to expand waxed paper performance into temperature and moisture regimes previously reserved for plastic laminates. These technical advances are reshaping competitive positioning among converters.
Water-based barrier coatings incorporating bio-wax emulsions are overtaking solvent-based paraffin systems in North American quick-service specifications. Burger chains with drive-through volume exceeding 10,000 units daily are qualifying these grades for hot-hold packaging. The shift is compressing demand for conventional waxed paper in premium food-service segments while opening margin recovery for suppliers with emulsion coating assets.
REACH restrictions on microplastics in consumer products are accelerating migration toward wax-only barrier systems across EU food-contact applications. The ECHA restriction proposal targets intentional microplastic additives in single-use items, directly affecting polyethylene-laminated paper alternatives. Cupstock and hot-food wrap categories are responding with accelerated reformulation timelines ahead of 2027 enforcement windows.
Direct mill-to-chain procurement contracts are displacing distributor-mediated purchasing for volume buyers with national footprints. Quick-service operators with 5,000-plus locations are establishing dedicated supply agreements with integrated paper-coating mills. This pattern is most visible in the United States, where Aramark, Compass Group, and institutional food-service managers are consolidating vendor lists to three qualified suppliers per substrate category.
Waxed Paper Packaging Market Segmentation
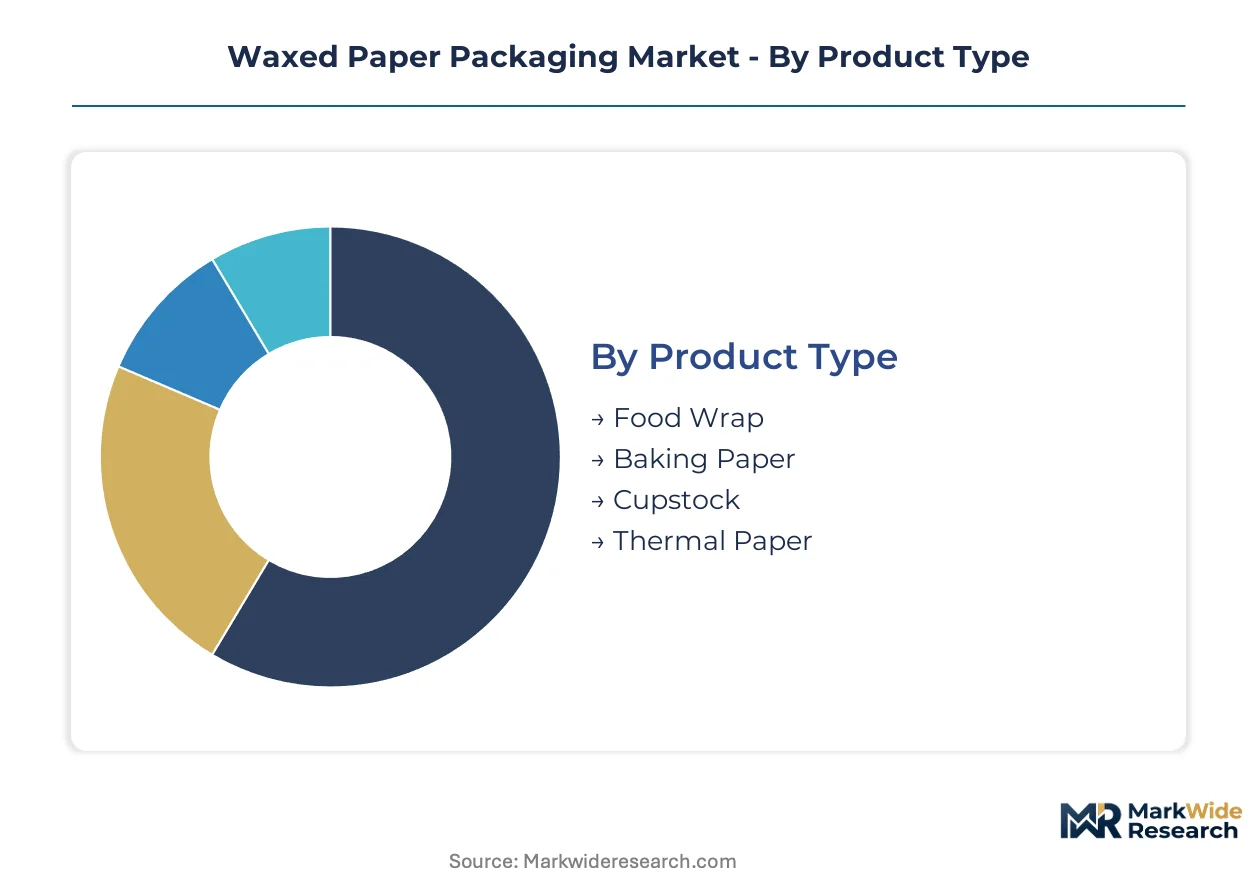
Waxed paper packaging segmentation reveals how technical specifications and certification tiers create distinct supply pools. Buyers with different volume scales and regulatory exposure sort into non-overlapping procurement channels based on barrier performance and end-of-life compliance requirements.
Product Type:
Capital intensity varies sharply across coating lines, with multi-layer barrier systems demanding extrusion and emulsion assets that smaller converters cannot finance.
- Food Wrap:Single or double-sided paraffin or vegetable-wax coatings applied to bleached kraft achieve oil-kit values of 4-8 for direct food contact. Quick-service burger and sandwich chains in the United States are consolidating procurement around compostable-certified grades as corporate sustainability mandates harden.
- Cupstock:Precision roll-fed substrates require uniform caliper control and edge wicking resistance for hot-drink sleeve forming under thermal stress. Premium pricing reflects the technical precision needed for leak-proof performance in drive-through coffee operations.
- Baking Paper:Silicone hybrid coatings extend thermal tolerance to 220°C for oven-release applications in commercial bakeries.
- Thermal Paper:Wax-impregnated grades serve specialized labeling and ticketing functions with moisture-resistant print surfaces.
Most installed capacity flows through Food Wrap. Expansion is steepest in Cupstock as hot-beverage chains retrofit packaging specifications.
End User:
Volume concentration and certification requirements diverge across buyer types, with institutional procurement programs driving standardization.
- Food Service:National quick-service chains and contract caterers specify lot-to-lot barrier consistency with oil-kit testing protocols. Aramark and Compass Group are consolidating vendor lists to three qualified suppliers per substrate category in the United States.
- Retail:Supermarket deli counters and in-store bakeries demand FSC chain-of-custody documentation as a de facto tender requirement.
- Industrial:Corrugated box liners and interleaving applications prioritize moisture vapor transmission rates below 10 g/m²/day.
- Hospitality:Hotel breakfast services and banquet operations source through broadline distributors with limited technical specification leverage.
Food Service commands the largest volume share. Retail is gaining share fastest as multinational grocers extend certified procurement mandates.
Thickness:
Basis weight selection determines coating line speed and wax pickup efficiency, with heavier grades requiring extended drying tunnels.
- Lightweight:Sub-40 gsm substrates serve interleaving and portion-control wrapping with minimal barrier requirements.
- Mediumweight:40-60 gsm grades balance flexibility and grease resistance for standard food-service wraps.
- Heavyweight:60-90 gsm constructions absorb higher wax loadings for extended hot-hold performance in burger chain packaging.
- Ultra-heavyweight:Above 90 gsm boards provide structural rigidity for cupstock and premium bakery box liners.
Mediumweight grades absorb the majority of coating capacity. Heavyweight is climbing the fastest as hot-hold packaging specifications tighten.
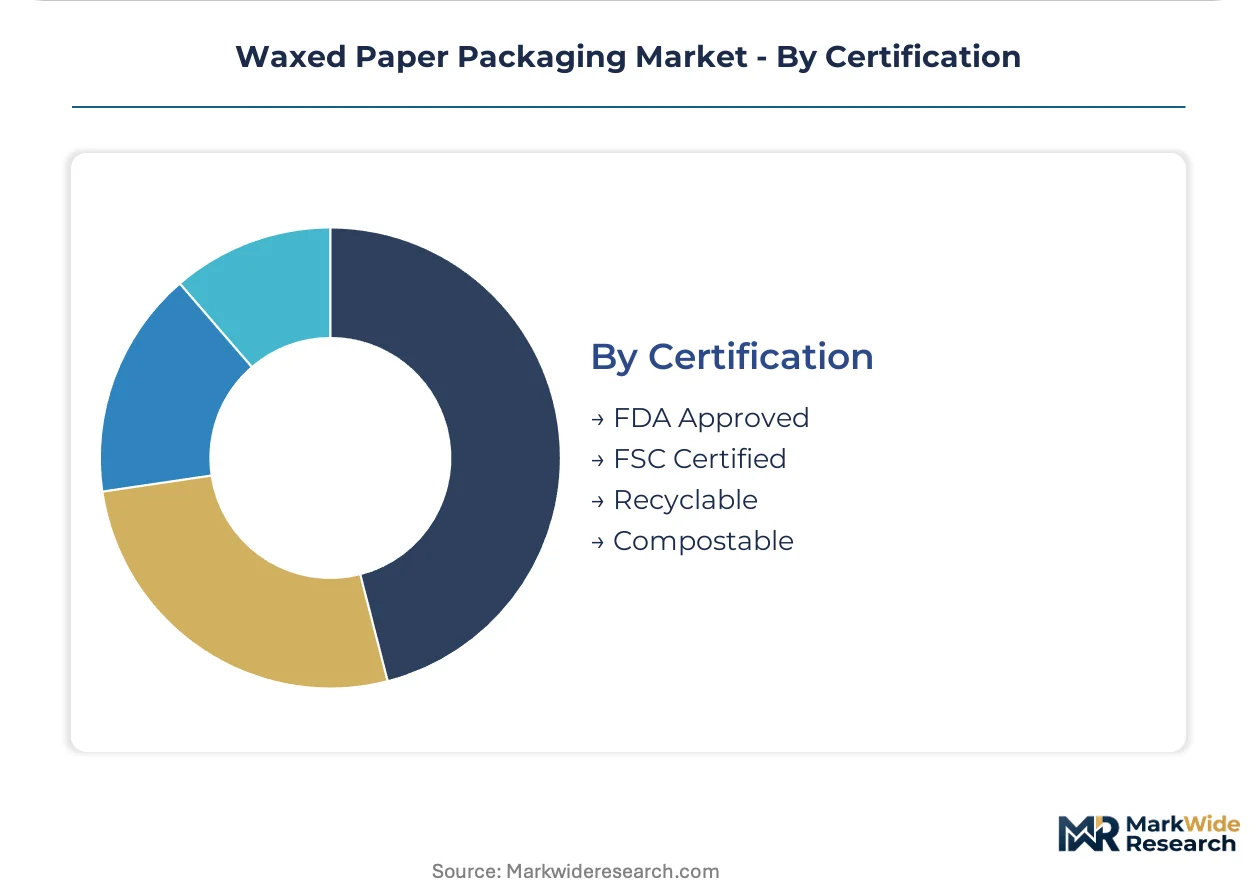
Certification:
Compliance tier directly determines market access, with multi-jurisdictional suppliers facing formulation complexity from diverging test protocols.
- Compostable:ASTM D6400 and EN 13432 certification requires vegetable-based wax formulations that achieve grease-barrier parity with paraffin. Quick-service chains with 5,000-plus locations now mandate this tier as a tender precondition.
- FSC Certified:Chain-of-custody documentation filters uncertified mills from qualified vendor lists for multinational food retailers.
- FDA Approved:21 CFR 176.170 compliance governs wax and wax-polymer coatings for United States food-contact applications.
- Recyclable:Repulpability certification through FSC or equivalent programs addresses paper mill acceptance criteria for post-consumer fiber recovery.
FDA Approved grades retain the broadest installed base. Compostable is expanding most quickly as single-use plastic bans harden across North America and Western Europe.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States quick-service restaurant chains drive the largest volume procurement of certified compostable waxed paper grades, with major food-service operators consolidating vendor relationships around integrated coating mills.
United States
Aramark and Compass Group are consolidating vendor lists to three qualified suppliers per substrate category, pulling volume toward mills with captive pulp supply. FDA regulations under 21 CFR 176.170 govern wax and wax-polymer coatings for food-contact applications. The Southeast region, particularly Georgia and the Carolinas, hosts concentrated coating capacity serving burger chains with drive-through volumes exceeding 10,000 units daily.
Germany
Industrial composting infrastructure and corporate sustainability mandates are accelerating procurement of EN 13432-certified grades across bakery and deli chains. REACH restrictions on microplastics in consumer products are driving reformulation away from polyethylene-laminated alternatives. The North Rhine-Westphalia corridor around Düsseldorf and Cologne anchors converter operations supplying quick-service chains across the Benelux region.
France
Citeo packaging fee modulation rewards compostable materials with lower eco-modulation rates, creating cost advantages over conventional plastic laminates. The EU Single-Use Plastics Directive Article 5 restrictions are tightening enforcement through 2025-2026 implementation deadlines. The Île-de-France region, centered on Paris, concentrates demand from national retail deli and bakery chains.
India
Quick-service pizza and burger chains in Mumbai, Delhi, and Bangalore are adopting waxed paper liners as FSSAI tightens plastic-contact restrictions for hot foods. Central government plastic waste management rules are accelerating substitution in food-service packaging. The Maharashtra-Gujarat industrial corridor hosts emerging converter capacity serving western India food-service expansion.
Japan
Convenience store chains and bento box distributors are specifying vegetable-based wax coatings for prepared food packaging. METI circular economy guidelines are influencing procurement standards for single-use food-contact materials. The Kanto region around Tokyo anchors premium cupstock demand from hot-beverage retail chains.
Waxed Paper Packaging Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue bio-based coating specializations and regional food-service contracts. The market exhibits tiered concentration, with integrated pulp-to-paper mills controlling feedstock access and independent converters competing on coating flexibility. Three archetypes dominate: integrated forest products conglomerates with captive kraft supply; specialty converters with emulsion coating assets; and regional players serving local bakery and deli chains. Capacity expansion and strategic partnerships represent the dominant competitive moves, as buyers consolidate procurement around qualified suppliers with statistical process control systems.
Among North American integrated producers, International Paper, WestRock, and Novolex occupy positions that exemplify distinct strategic archetypes. International Paper represents the forest-products conglomerate model with captive pulp networks. WestRock anchors the containerboard-integrated specialty coating tier. Novolex exemplifies direct-chain relationship building with quick-service operators demanding consistent lot-to-lot barrier performance.
| Leading Market Players |
|---|
| International Paper |
| WestRock |
| Novolex |
| Bomarko Inc. |
| Smurfit Kappa Group |
| Georgia-Pacific LLC |
| Pactiv Evergreen Inc. |
| Packaging Products (Coatings) Ltd |
| Oji Holdings Corporation |
| Others |
Value Network & Pricing Analysis
Water-based barrier coating emulsions are displacing solvent-based paraffin systems across North American quick-service specifications, simultaneously compressing conversion costs for qualified suppliers while concentrating procurement leverage among integrated mills with captive coating assets. This technical transition rewards backward-integrated producers that control pulp-to-coating workflows, squeezing independent converters on both feedstock access and pricing power.
Pricing Analysis
Paraffin wax feedstock costs transmit directly to finished goods pricing through petroleum market exposure, with vegetable-based alternatives commanding premium-mid-economy pricing differentiation based on compostable certification status. Price differentiation separates ASTM D6400-certified grades from conventional FDA-approved tiers, with volume buyers above 5,000 locations extracting steepest discounts. Cost compression in standard paraffin grades is intensifying because quick-service chains are consolidating vendor lists to three qualified suppliers per substrate category. Small independent converters exhibit highest price sensitivity due to feedstock purchasing scale disadvantages, while national institutional food-service operators leverage multi-year contracts to lock in supply security.
Supply Chain Analysis
Regional distribution centers in Georgia, North Carolina, and the Carolinas anchor hub-and-spoke patterns serving burger chains with drive-through volumes exceeding 10,000 units daily. Geographic supply concentrates in the United States, Germany, and India, with North American virgin kraft supply controlled by a handful of mill complexes. Raw material dependencies rest on paraffin wax, vegetable wax feedstocks, and bleached kraft pulp. Single-source vulnerability in coating-grade pulp supply creates structural risk, particularly for independent converters lacking captive fiber access. Distribution runs through direct mill-to-chain procurement contracts that displace distributor-mediated purchasing for volume buyers with national footprints.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
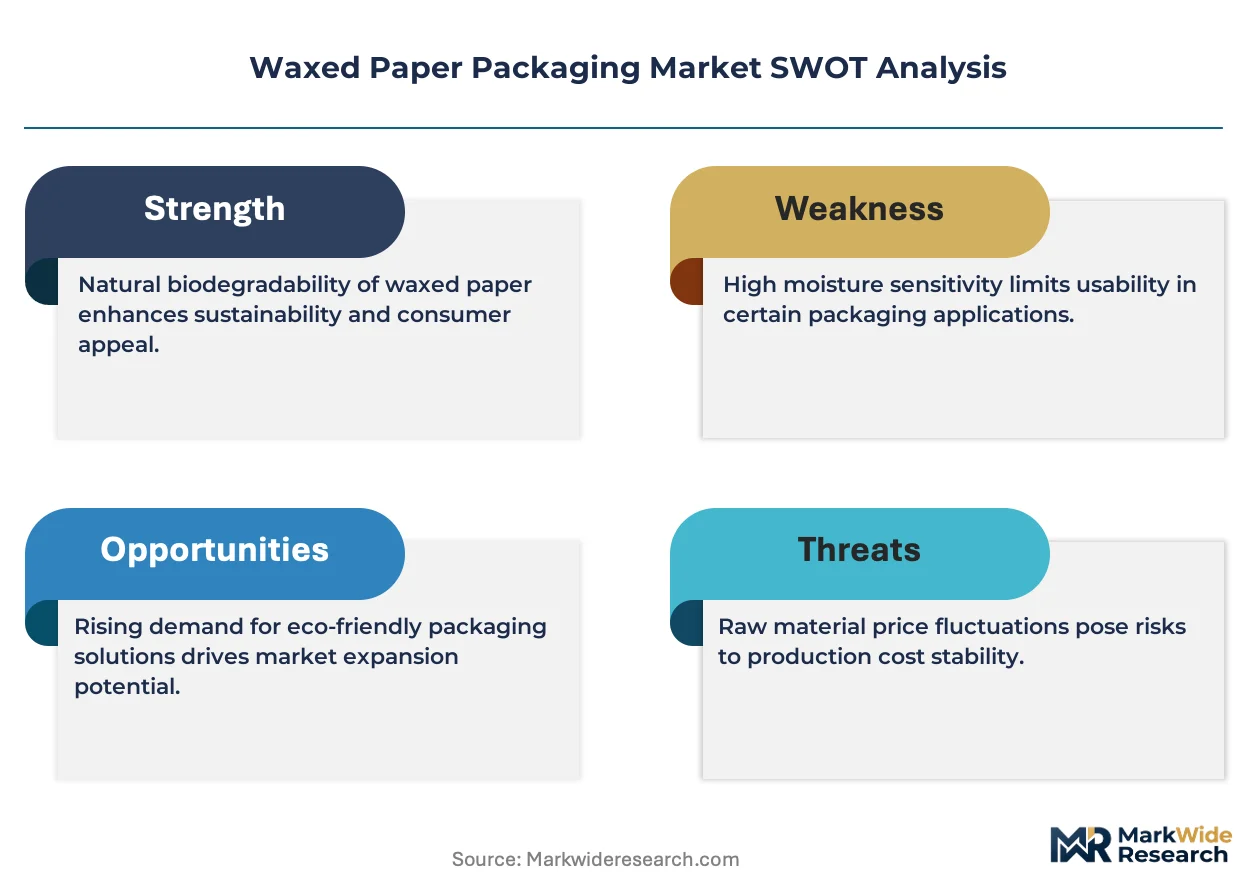
This market offers margin expansion through vegetable-wax formulation premiums and coating-asset consolidation, as sustainability mandates shift procurement toward certified compostable grades that command pricing power over conventional paraffin alternatives.
For Market Incumbents: Acquire emulsion coating production lines to secure qualification status with quick-service chains consolidating vendor lists. Defensive moves center on backward integration into vegetable wax supply agreements and statistical process control system deployment to guarantee lot-to-lot barrier consistency. Silicone-coated parchment substitution in high-temperature bakery applications above 200°C threatens traditional waxed paper volume, making compostable certification investment the critical retention lever for food-service contracts. For New Entrants and Emerging Players: Regional bakery chains and home meal-kit delivery channels represent underserved buyer archetypes with limited incumbent penetration. White-space targets include cold-chain logistics providers requiring moisture-resistant interleaving for pre-portioned proteins, and India quick-service pizza chains in Mumbai and Delhi facing FSSAI plastic-contact restrictions. A specification-led go-to-market approach with extended producer responsibility scheme alignment opens initial contract opportunities. For Investors and Strategic Acquirers: Valuations sit cheapest among independent converters with coating flexibility but lacking captive pulp supply. Long-term viability over a five-to-ten year window hinges on compostable certification asset bases as single-use plastic bans harden across North America and Western Europe. Acquisition targets should screen for ASTM D6400 and EN 13432 qualified production capacity. The signal to watch is quick-service chain procurement consolidation velocity, as buyer concentration toward integrated mills accelerates distressed asset availability.| Strategic Initiative | Industry Significance |
|---|---|
| Vegetable-Wax Coating Capacity Expansion | ASTM D6400 certification unlocks quick-service chain procurement mandates in the United States. |
| Backward Integration into Pulp Supply | Captive kraft feedstock insulates margin pressure from North American mill concentration. |
| Statistical Process Control System Deployment | Inline coating weight monitoring satisfies Aramark and Compass Group lot-to-lot consistency requirements. |
| Direct Mill-to-Chain Procurement Contracts | Displacing distributor intermediation captures volume from national operators with 5,000-plus locations. |
| Extended Producer Responsibility Alignment | Citeo eco-modulation rate optimization in France rewards compostable grades with cost advantages over plastic laminates. |
Research Methodology
Multiple input streams — primary interviews with coating mill operations directors, quick-service chain procurement managers, and FSC certification auditors; secondary validation through FDA 21 CFR filings, EU REACH restriction proposals, and trade customs data; and bottom-up capacity modeling against top-down food-service packaging demand — were reconciled to produce market estimates. Conversations with emulsion coating technology suppliers and vegetable wax feedstock distributors supplemented volume assumptions. The analysis triangulates across these sources to bound uncertainty ranges.
Historical volume trajectories were cross-referenced against panel input from industry participants to anchor growth assumptions across the projection horizon. Segmentation dimensions modeled include product type, certification tier, end-user category, and regional regulatory cluster. CAGRs derive from fitted trend analysis adjusted for policy implementation timelines. Forecast inputs incorporate EU Single-Use Plastics Directive enforcement schedules and FSSAI plastic-contact restriction phasing in India.
Inputs from primary stakeholder interviews and regulatory filing databases were available through the study window; gaps in real-time composting infrastructure deployment data introduce uncertainty bands around end-of-life value proposition assumptions. Forecasts reflect documented assumptions regarding coating technology adoption curves and buyer consolidation velocity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Corrugated Board Market
Paper & Paperboard Packaging
Composite Cardboard Tube Packaging Market
Paper & Paperboard Packaging
Paper Cups Market
Paper & Paperboard Packaging
Micro Flute Paper Market
Paper & Paperboard Packaging
Latin America Paper Packaging Market
Paper & Paperboard Packaging
Paper Cone Cup Market
Paper & Paperboard Packaging
Eco-Friendly Paper Plates Market
Paper & Paperboard Packaging
Europe Paper Packaging Market
Paper & Paperboard Packaging
Middle East and Africa Corrugated Box Market
Paper & Paperboard Packaging
Hanging Box Market
Paper & Paperboard Packaging
Global Fanfold Corrugated Market
Paper & Paperboard Packaging
Paperboard Packaging Market
Paper & Paperboard Packaging
Canada Paper Packaging Market
Paper & Paperboard Packaging
Global VCI Paper Market
Paper & Paperboard Packaging
Flowpack Paper Packaging Market
Paper & Paperboard Packaging
Europe Paper Cone Market