
 Corrugated Packaging Market | 2026-2036
Corrugated Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Corrugated Packaging Market Intelligence
FSC Chain of Custody certification is rotating as the primary gating mechanism for supplier qualification among multinational brand owners. International Paper Company leverages its North American containerboard integration to sustain volume leadership in retail-ready packaging. Smurfit Kappa Group anchors European supply through its recycled fiber network and pan-regional plant footprint. WestRock Company differentiates via automated packaging machinery bundling with substrate supply.
Corrugated packaging consists of fluted paperboard sheets laminated between flat linerboards, typically constructed from Kraft pulp or recycled fibers with burst strengths ranging from 200 to 1,000 lb/in² depending on wall configuration. The material functions primarily as protective containment for distribution, cushioning goods against impact and compression during transit. Single-wall boards dominate volume in consumer goods logistics, while triple-wall configurations command premium positioning in heavy industrial and export applications where load-bearing requirements exceed standard thresholds. Die-cut formats represent the fastest-growing product category as brand owners replace generic boxes with shelf-ready displays and returnable e-commerce mailers.
EPA guidelines on recycled content thresholds and FDA food-contact safety standards for packaging substrates shape formulation choices and mill investment cycles in the United States. The EU Green Deal and associated CSRD reporting obligations push converters toward certified fiber sourcing and carbon footprint disclosure across supply chains. Stakeholders must monitor evolving extended producer responsibility schemes and decide between regional compliance investments versus global certification standardization.
Market Dynamics
The corrugated packaging sector faces structural compression from the EU Packaging and Packaging Waste Regulation, which mandates minimum recycled content thresholds and extended producer responsibility schemes that reshape mill investment cycles and converter qualification protocols across European supply chains.
Growth Catalysts
- E-commerce fulfillment density:Third-party logistics providers in Germany's industrial corridor are specifying triple-wall configurations for automotive and machinery export protection, driving specification upgrades.
- FSC Chain of Custody mandates:The EU Green Deal's certified fiber sourcing requirements are rotating as primary gating mechanisms for multinational brand owner supplier qualification.
- Die-cut automation:Digital cutting and creasing technologies are enabling shelf-ready display formats that replace generic RSC boxes in retail distribution.
Market Restraints
- Recycled fiber cost volatility:Old corrugated container price swings in European spot markets compress converter margins when pulp substitution economics invert.
- German supply concentration:The country's industrial corridor hosts disproportionate linerboard capacity, creating single-point vulnerability for just-in-time automotive packaging supply.
- Plastic film substitution:Stretch hood and shrink wrap systems retain cost advantages for unitized pallet loads in beverage distribution.
Strategic Opportunities
- Returnable e-commerce mailers:Die-cut formats with adhesive-free closure systems address last-mile packaging waste in France's CSRD-reporting retail sector.
- Automated packaging machinery bundling:Converters pairing substrate supply with case erecting and sealing equipment capture line integration decisions at German automotive Tier 1 suppliers.
- Carbon footprint disclosure services:The EU CSRD's scope 3 reporting obligations create annuity revenue streams for certified fiber networks with verified chain-of-custody documentation.
Industry Challenges
- Recycled fiber quality variance:Contamination rates in municipal post-consumer streams degrade burst strength consistency, forcing mills to blend in higher-cost Kraft pulp.
- Extended producer responsibility compliance timelines:Member-state implementation divergence under the EU Packaging and Packaging Waste Regulation creates fragmented certification requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Corrugated Packaging Market |
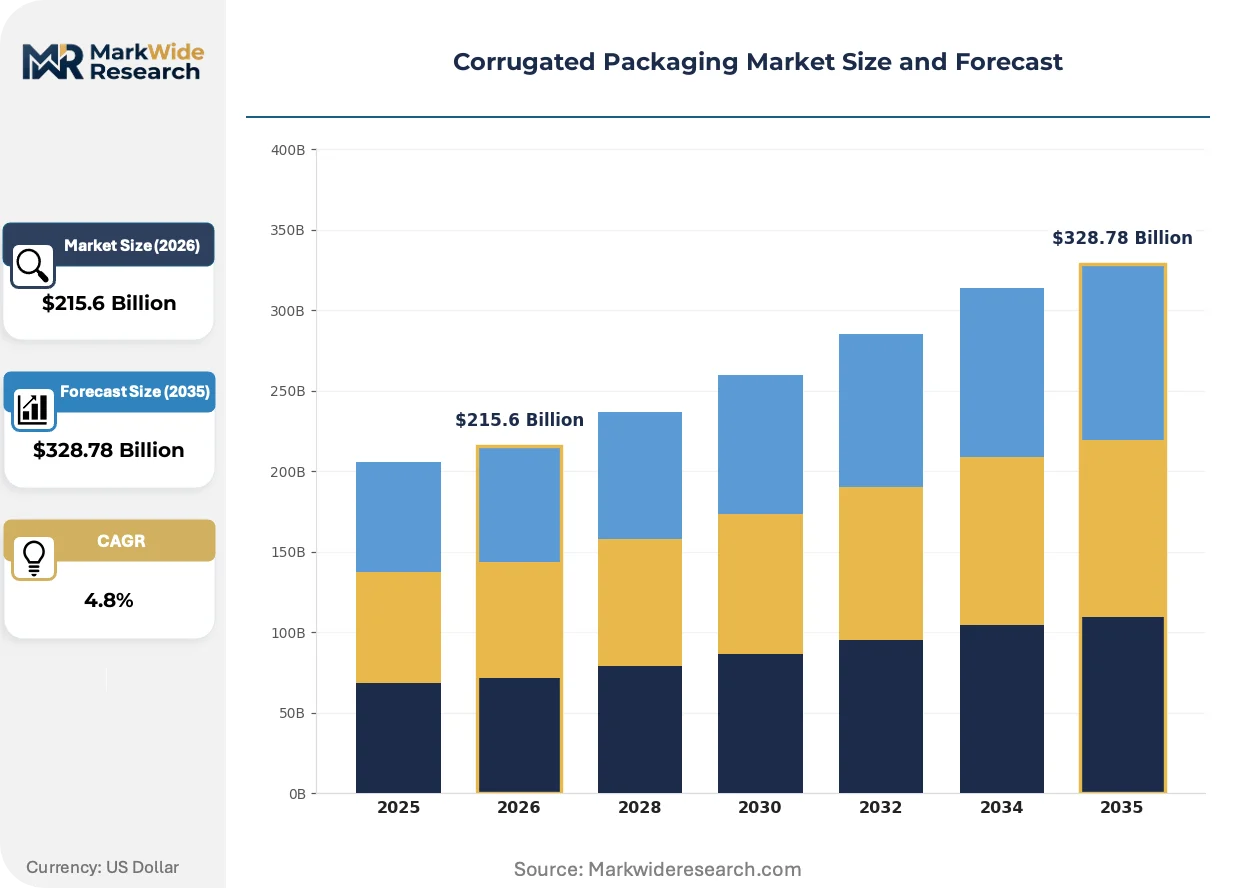
| Market Size in 2026 | $215.6 Billion |
| Market Size in 2035 | $328.78 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-wall, Double-wall, Triple-wall, Die-cut End User: Food & Beverage, Pharmaceutical, Electronics, Personal Care Distribution Channel: Direct Sales, Retail, E-commerce, Wholesale Packaging Type: Boxes, Sheets, Trays, Pallets |
| Companies Covered | International Paper Company, WestRock Company, Smurfit Kappa Group, DS Smith Plc, Mondi Group, Packaging Corporation of America, Rengo Co. Ltd., Oji Holdings Corporation, Georgia-Pacific LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Corrugated Packaging Market Strategic Shifts & Innovations
Digital printing and smart packaging integration are compressing minimum order quantities and enabling batch-level traceability, while regulatory pressure on recyclability accelerates format standardization and adhesive chemistry reformulation across European converter networks.
Water-based barrier coatings are supplanting polyethylene extrusion layers in food-contact corrugated applications. Bakery and fresh produce distributors in Spain and Italy are specifying these fluorocarbon-free alternatives to meet EFSA migration limits. The shift is compressing capital recovery timelines for legacy extrusion laminators while enabling mills to market single-material recyclability to EPR-scheme auditors.
The EU Green Deal's packaging recyclability mandates are forcing adhesive reformulation across the value chain. Hot-melt and starch-based bonding systems must now demonstrate fiber liberation in standard pulping protocols to avoid "non-recyclable" classification. German automotive parts suppliers are qualifying converters with third-party recyclability certifications ahead of 2025 EPR fee modulation.
Brand owners are consolidating corrugated specifications to reduce SKU complexity and improve recycling stream purity. Retailers in France's grocery sector are pushing for standardized box sizes and print-free interiors to simplify sortation at material recovery facilities. The behavior is most visible in private-label supply chains where procurement teams negotiate pan-European format agreements.
Corrugated Packaging Market Segmentation
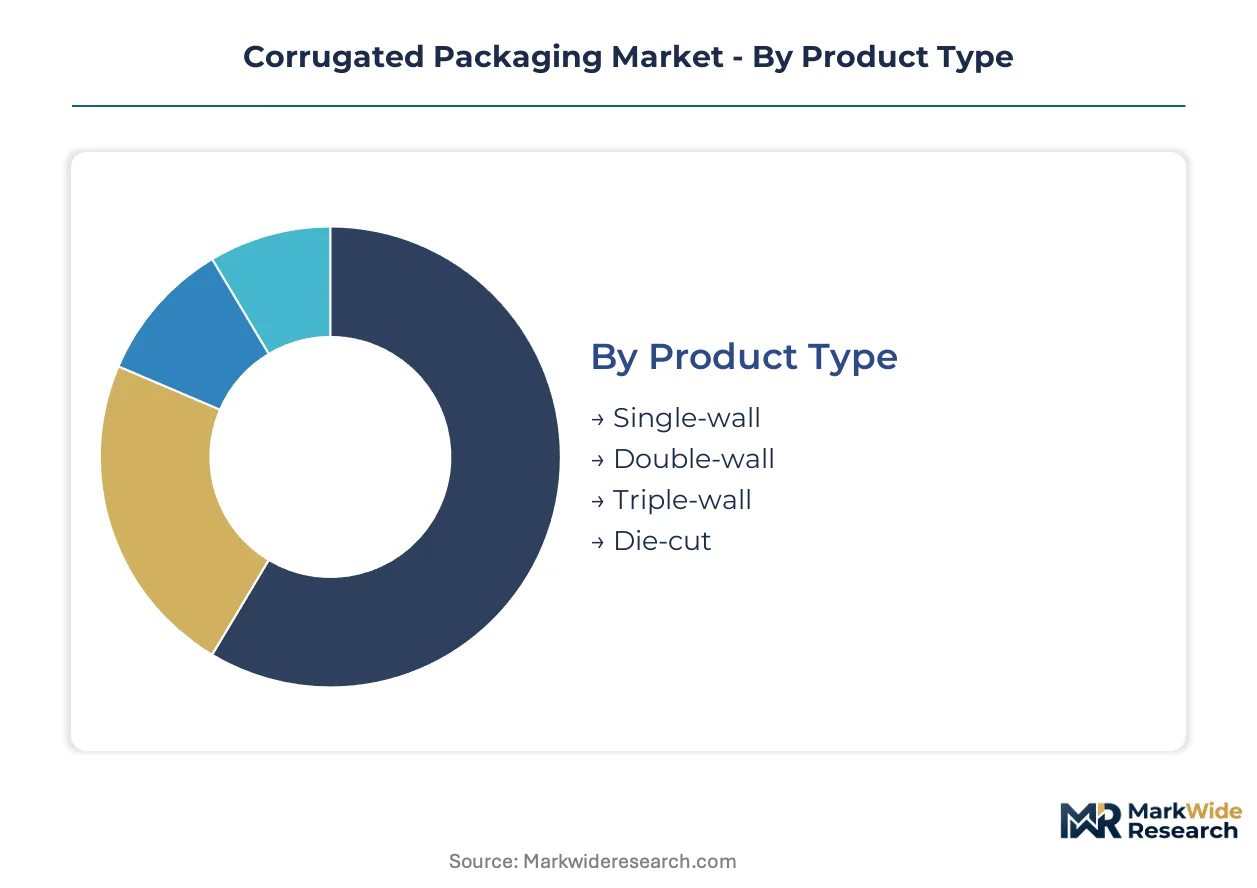
Corrugated packaging specifications diverge sharply across load-bearing requirements and end-use contamination sensitivity. Substitution threats from rigid plastics and flexible films reshape priority rankings within each segment category.
Product Type:
Single-wall boards face the most acute substitution pressure from lightweight plastic alternatives in consumer goods logistics.
- Single-wall:Constructed from one fluted medium sandwiched between two linerboards with burst strengths typically ranging from 200 to 275 lb/in². E-commerce fulfillment networks in Germany's industrial corridor specify this grade for parcel shipments under 30 pounds, though margin compression intensifies when old corrugated container prices spike.
- Die-cut:Precision-cut formats with adhesive-free closure systems enable shelf-ready displays and returnable mailers. France's CSRD-reporting retail sector is consolidating procurement around these formats to simplify material recovery facility sortation and demonstrate scope 3 packaging waste reductions.
- Double-wall:Two fluted layers deliver 350 to 500 lb/in² burst strength for medium-duty industrial applications.
- Triple-wall:Three fluted layers exceed 700 lb/in² for heavy machinery and automotive export protection where palletized loads face extended transit stress.
Single-wall anchors the volume base while die-cut gains share at the steepest rate.
End User:
Food and beverage applications command the widest specification spread due to EFSA migration limits and moisture barrier requirements.
- Food & Beverage:Water-based barrier coatings are supplanting polyethylene extrusion layers in bakery and fresh produce distribution across Spain and Italy. The shift enables single-material recyclability claims that satisfy EPR-scheme auditors while compressing capital recovery timelines for legacy extrusion equipment.
- Pharmaceutical:Cold-chain corrugated shippers with phase-change material integration protect temperature-sensitive biologics. German automotive parts suppliers are qualifying converters with third-party recyclability certifications ahead of EPR fee modulation.
- Electronics:Anti-static coatings and precision-fit cushioning address high-value device protection in last-mile delivery.
- Personal Care:Premium unboxing experiences drive specification toward printed litho-laminated finishes with rigid structural integrity.
Food and beverage dominates tonnage while pharmaceutical specifications expand most quickly.
Distribution Channel:
Direct sales relationships concentrate around just-in-time automotive supply where line integration decisions lock in substrate suppliers.
- Direct Sales:Converters pairing substrate supply with automated case erecting and sealing equipment capture multi-year contracts at German automotive Tier 1 suppliers. The bundling strategy raises switching costs and secures volume commitments through machinery financing arrangements.
- E-commerce:Third-party logistics providers specify standardized box sizes and print-free interiors to simplify sortation at material recovery facilities. Private-label procurement teams negotiate pan-European format agreements that reduce SKU complexity.
- Retail:Big-box distributors maintain regional converter relationships for promotional display stock.
- Wholesale:Volume resellers aggregate demand from small and mid-sized manufacturers without direct mill relationships.
Direct sales locks in the highest margin contracts while e-commerce channels scale fastest.
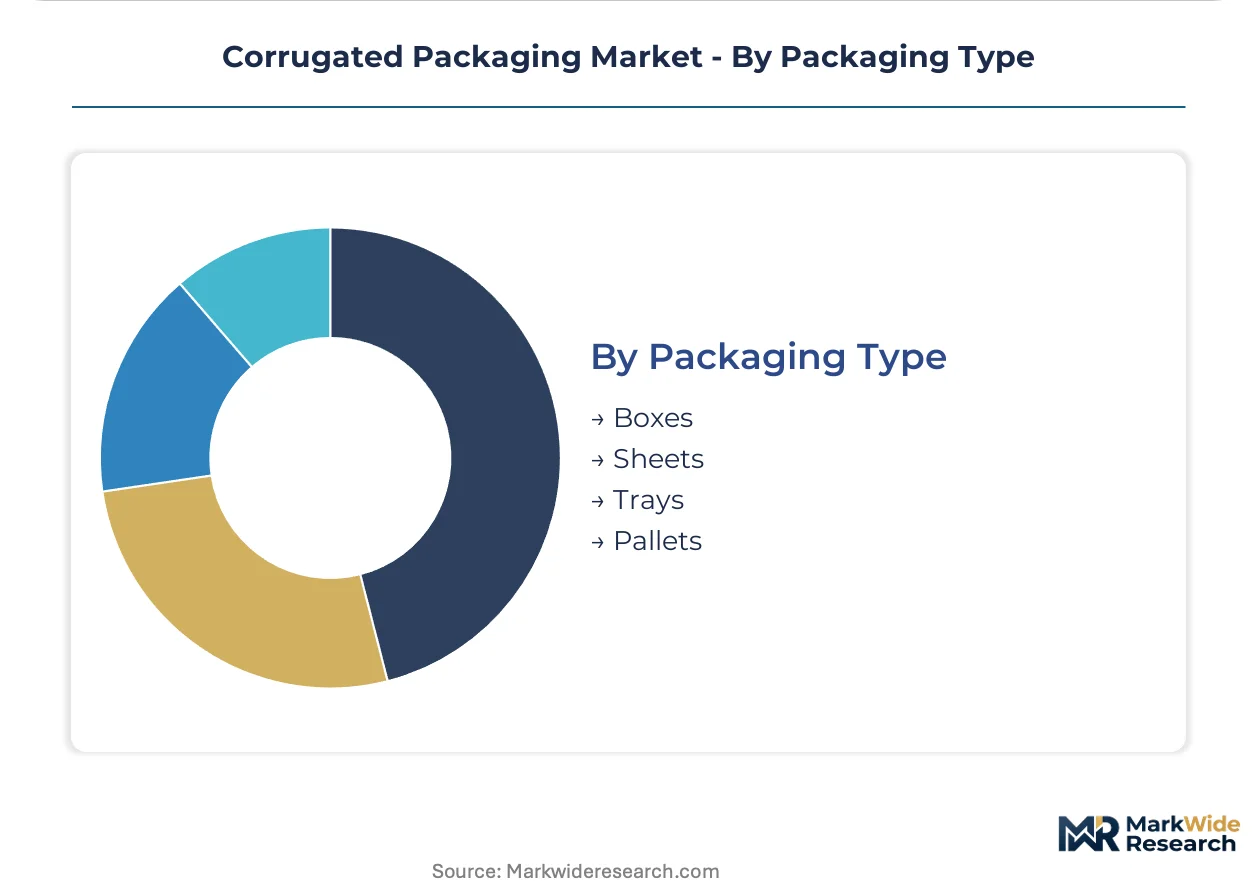
Packaging Type:
Sheet formats face displacement from unitized pallet containment systems in beverage distribution networks.
- Boxes:Regular slotted containers remain the default for general merchandise distribution, though specification consolidation is eliminating non-standard sizes from private-label supply chains.
- Trays:Shelf-ready display formats with pre-applied adhesive strips replace traditional boxes in French grocery sector negotiations. Retailers demand print-free interiors and standardized dimensions to improve material recovery facility yields.
- Sheets:Layer pads and divider sheets protect stacked goods during transit.
- Pallets:Corrugated pallet alternatives compete with wood and plastic in single-use export applications.
Boxes retain the installed base while trays climb the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Packaging and Packaging Waste Regulation is redirecting capital flows toward certified fiber networks and extended producer responsibility compliance infrastructure across major manufacturing economies.
Germany
Automotive Tier 1 suppliers in Stuttgart and Munich are qualifying triple-wall configurations for machinery export protection under KBA transit standards. The country's EPR fee modulation timeline pressures converters to secure third-party recyclability certifications by 2025. Bavaria's industrial corridor hosts disproportionate linerboard capacity, creating single-point vulnerability for just-in-time automotive packaging supply.
United States
EPA recycled content thresholds and FDA food-contact safety standards reshape formulation choices at Gulf Coast containerboard mills. E-commerce fulfillment networks in Dallas-Fort Worth and Chicago specify die-cut formats with adhesive-free closure systems for last-mile efficiency. The Southeast's integrated pulp-to-box infrastructure sustains cost leadership in retail-ready packaging.
China
MIIT dual carbon goals and GB standards for packaging recyclability accelerate water-based barrier coating adoption in Yangtze River Delta food processing clusters. NMPA migration limits for food-contact substrates compress capital recovery timelines for legacy polyethylene extrusion equipment. Guangdong's electronics manufacturing belt drives anti-static corrugated specifications for high-value device protection.
France
CSRD scope 3 reporting obligations push Paris-based retailers toward standardized box sizes and print-free interiors to simplify material recovery facility sortation. ANSM guidance on pharmaceutical cold-chain packaging validates corrugated shippers with phase-change material integration. The Île-de-France grocery sector consolidates procurement around shelf-ready display formats to demonstrate packaging waste reductions.
Japan
METI circular economy roadmaps and JIS quality standards reinforce fiber liberation requirements for hot-melt adhesive systems in Osaka-Kobe packaging converter networks. PMDA validation protocols for temperature-sensitive biologics expand cold-chain corrugated specifications. Chubu region automotive parts suppliers are pre-qualifying converters with verified chain-of-custody documentation ahead of EPR alignment.
Corrugated Packaging Market Key Industry Players
Listed leaders compete with private specialists across capital intensity and geographic coverage dimensions. The vendor base clusters around three tiers: North American integrated containerboard producers, European recycled fiber networks, and Asia-Pacific regional converters. Strategic archetypes include substrate-machinery bundlers, certified fiber specialists, and scale-driven commodity suppliers. M&A activity concentrates on regional converter acquisitions to secure EPR scheme compliance capabilities, while capacity expansion targets water-based coating lines to displace polyethylene extrusion.
Within the integrated containerboard tier, International Paper Company and WestRock Company exemplify North American volume leadership through captive pulp supply. Smurfit Kappa Group anchors European positioning via pan-regional recycled fiber networks and plant footprint density. These three entities represent distinct competitive vectors: machinery bundling, certified sourcing, and geographic consolidation.
| Leading Market Players |
|---|
| International Paper Company |
| WestRock Company |
| Smurfit Kappa Group |
| DS Smith Plc |
| Mondi Group |
| Packaging Corporation of America |
| Rengo Co. Ltd. |
| Oji Holdings Corporation |
| Georgia-Pacific LLC |
| Others |
Cost & Logistics Intelligence
Long-term offtake agreements between German automotive Tier 1 suppliers and Bavarian linerboard mills lock in both fiber access and price visibility, insulating converters from OCC spot volatility while embedding recyclability certification costs into contract structures. These arrangements concentrate procurement leverage among buyers with multi-year machinery bundling relationships, compressing margin flexibility for non-integrated competitors.
Pricing Analysis
Certification level—FSC Chain of Custody versus uncertified fiber—creates the primary spread in converter pricing to multinational brand owners. Three-tier pricing structure across premium certified, standard recycled-content, and economy spot-market grades reflects the EU Green Deal's supplier qualification mandates. Cost compression in standard grades intensifies as old corrugated container price spikes force Kraft pulp blending. Small and mid-sized manufacturers without direct mill relationships exhibit the highest price sensitivity, while automotive Tier 1 suppliers with machinery bundling contracts demonstrate the least.
Supply Chain Analysis
Bavaria's industrial corridor functions as a chokepoint where disproportionate linerboard capacity concentrates just-in-time automotive packaging supply. Germany, the United States, and China anchor global containerboard production, with each market drawing from distinct fiber networks—recycled post-consumer streams, integrated Kraft pulp, and mixed furnish respectively. Single-source vulnerability in German automotive supply chains stems from geographic concentration of triple-wall capacity. Distribution runs through direct sales relationships with bundled machinery financing, e-commerce third-party logistics specifications, and wholesale volume resellers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The corrugated packaging sector is approaching a platform-economics inflection where automated packaging machinery interoperability—case erectors, sealers, and digital cutting systems—will determine supplier lock-in more than substrate cost alone.
For Market Incumbents: Secure multi-year machinery bundling contracts at German automotive Tier 1 suppliers before EPR fee modulation accelerates converter consolidation. Backward integration into water-based barrier coating lines displaces legacy polyethylene extrusion capacity threatened by EFSA migration limits. Certification investment in FSC Chain of Custody documentation creates switching costs against emerging recycled-fiber specialists. For New Entrants and Emerging Players: Differentiate on carbon footprint disclosure services for France's CSRD-reporting retail sector, where scope 3 packaging waste verification commands premium positioning. Target returnable e-commerce mailer formats with adhesive-free closure systems in underpenetrated Southern European markets. A go-to-market angle pairing die-cut automation with material recovery facility sortation consulting bypasses incumbent machinery bundling advantages. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap converters with established EPR scheme compliance capabilities and verified chain-of-custody documentation across multiple EU member states. Long-term viability over a five-to-ten year window hinges on water-based coating line conversion ahead of polyethylene extrusion obsolescence. The signal to watch is German automotive supplier pre-qualification timelines for third-party recyclability certifications.| Strategic Initiative | Industry Significance |
|---|---|
| Machinery Bundling Expansion | Converters pairing substrate supply with automated case erecting equipment capture line integration decisions at Stuttgart automotive plants. |
| Water-Based Coating Conversion | Mills displacing polyethylene extrusion lines meet EFSA migration limits for Spanish bakery distribution while enabling single-material recyclability claims. |
| Certified Fiber Network Acquisition | Regional converter purchases secure EPR scheme compliance capabilities and pan-European FSC Chain of Custody documentation. |
| Die-Cut Automation Investment | Digital cutting and creasing technologies enable shelf-ready display formats that replace generic RSC boxes in French grocery negotiations. |
| Carbon Disclosure Service Launch | Verified chain-of-custody documentation creates annuity revenue streams from CSRD scope 3 reporting obligations across Paris-based retailers. |
Research Approach
A standing panel of containerboard mill operations directors, automotive Tier 1 supplier procurement managers, corrugated converter plant managers, and e-commerce third-party logistics specification engineers provided ongoing calibration across the study period. Primary interview insights combined with secondary validation from EU Packaging and Packaging Waste Regulation implementation documents, EPA recycled content threshold guidelines, FSC Chain of Custody certification databases, and customs trade data for OCC and Kraft pulp flows. Bottom-up volume modeling across product types and end-use segments triangulated against top-down macroeconomic indicators.
Consistency checks validated volume and value outputs against external benchmarks including pan-European containerboard production statistics, German automotive export packaging specifications, and CSRD reporting disclosure patterns across major retail groups. The analytical framework segmented the market by wall configuration, end-use contamination sensitivity, and distribution channel integration depth across the projection horizon. CAGRs derived from elasticity-adjusted demand curves incorporating e-commerce fulfillment density trends, EPR scheme implementation timelines, and fiber substitution economics.
The analysis sits within stated boundaries; outcomes outside sustained EU regulatory enforcement or abrupt OCC price dislocation would require recalibration. Forecasts reflect assumptions regarding EPR fee modulation adherence, water-based coating adoption curves, and machinery bundling contract renewal rates. Practitioners should keep alternative scenarios live as member-state implementation divergence under the EU Packaging and Packaging Waste Regulation evolves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Paper Cones Market
Paper & Paperboard Packaging
Pre-Impregnated Paper Market
Paper & Paperboard Packaging
Parchment Paper Market
Paper & Paperboard Packaging
Food Contact Paper and Board Market
Paper & Paperboard Packaging
Countertop Paper Napkin Dispenser Market
Paper & Paperboard Packaging
Machine Glazed Kraft Paper Market
Paper & Paperboard Packaging
Kraft Paper Bakery Bags Market
Paper & Paperboard Packaging
Coated Recycled Paperboard Market
Paper & Paperboard Packaging
Testliner Market
Paper & Paperboard Packaging
Macerated Paper Padded Mailers Market
Paper & Paperboard Packaging
Chipboard Box Market
Paper & Paperboard Packaging
Tissue and Hygiene Paper Packaging Market
Paper & Paperboard Packaging
North America Paper Cone Market
Paper & Paperboard Packaging
Natural Sack Kraft Papers Market
Paper & Paperboard Packaging
Europe Mailer Packaging Market
Paper & Paperboard Packaging
Compostable Paper Tray Market