
 Binder's Board Market | 2026-2036
Binder's Board Market Size, Share, and Industry Trends Forecast 2026-2036
Binder's Board Market Outlook
Bookbinding demand is realigning toward premium hardcover editions and specialty publishing, while educational textbook consumption softens in print formats. Smurfit Kappa Group leverages its integrated European containerboard network to secure recycled fiber supply for binder's board grades. Mondi Group anchors its position through specialized kraftliner and cartonboard operations serving Central European binderies. Eska BV differentiates via high-stiffness solid board formulations targeting luxury packaging converters.
Binder's board is a rigid paper-based substrate manufactured from multi-ply laminated fiber sheets, typically calendered to densities between 0.70 and 1.20 g/cm³ and engineered for structural integrity in book covers, luxury packaging, and display applications. Multi-layer constructions command premium positioning due to superior bending resistance and surface uniformity required for foil stamping and lamination. Recycled fiber grades face margin compression from sorting and de-inking costs, while virgin fiber substrates sustain price premiums in archival and museum-quality segments.
EPA guidelines on recycled content claims and EU REACH chemical restrictions on coatings influence formulation choices across North American and European production bases. FDA indirect food contact standards limit certain recycled fiber streams for packaging applications adjacent to consumable goods. Stakeholders must monitor evolving extended producer responsibility schemes and fiber certification requirements that will reshape sourcing economics and product specifications.
Market Dynamics
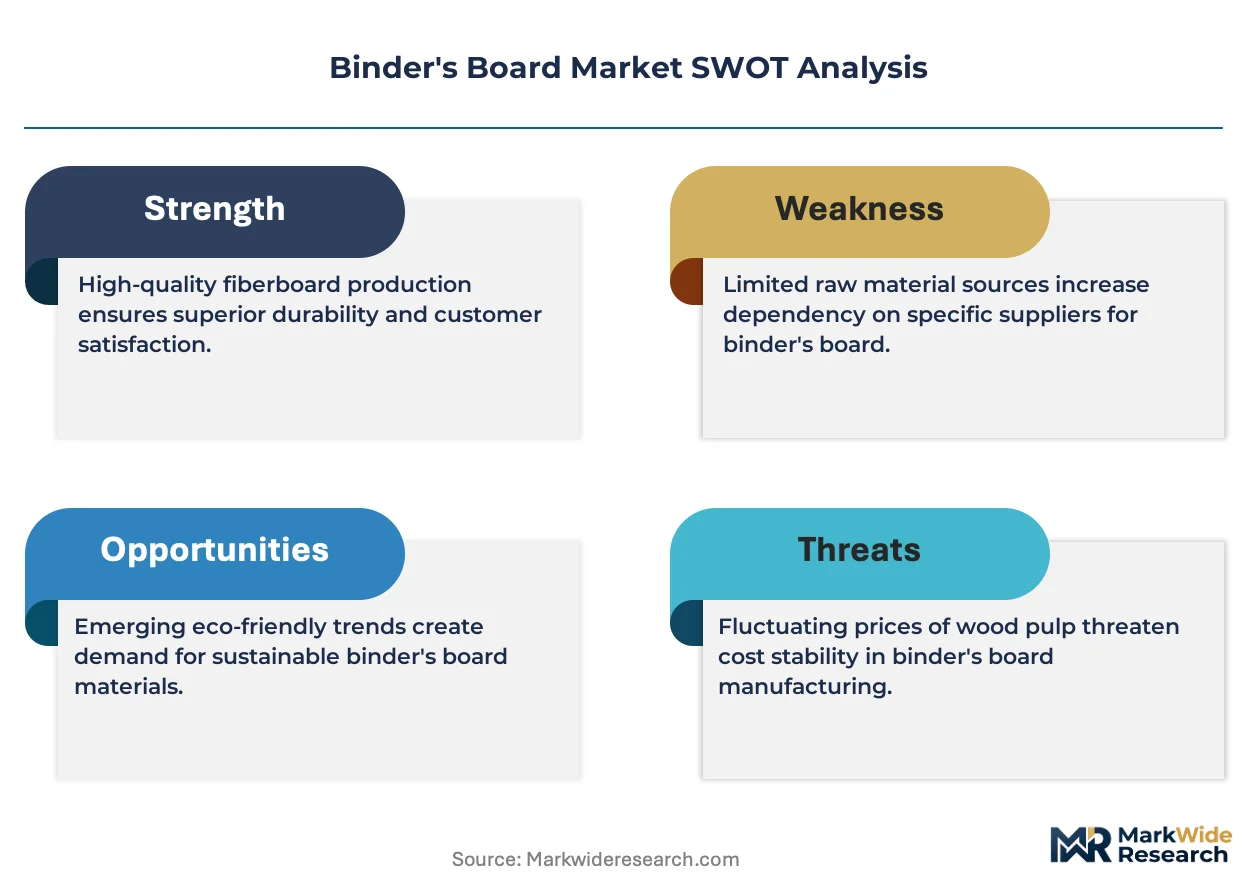
EU packaging regulations mandating recycled fiber content are restructuring raw material sourcing economics across binder's board production, forcing mills to reconfigure pulping operations and de-inking investments.
Growth Catalysts
- REACH chemical restrictions:European coating reformulation requirements are accelerating demand for compliant water-based barrier treatments in luxury packaging substrates.
- Luxury goods packaging:Premium cosmetics and spirits brands are specifying rigid structural boards with enhanced bending resistance for shelf presence.
- German mill clustering:Proximity between specialty board production and major converting operations in the Rhineland reduces logistics costs and lead times.
Market Restraints
- Recycled fiber cost volatility:Sorting and de-inking expenses compress margins on post-consumer pulp grades relative to virgin kraft alternatives.
- Supply concentration risk:Premium binder's board capacity clusters among integrated European containerboard networks with captive fiber supply.
- Archival substitution limits:Museum-quality segments resist recycled content due to lignin acidity concerns and long-term dimensional stability requirements.
Strategic Opportunities
- Extended producer responsibility schemes:EU packaging waste directives create certified recycled fiber premiums for compliant mills.
- Digital print compatibility:Surface uniformity improvements enable short-run hardcover production for on-demand publishing workflows.
- India specialty packaging:Emerging domestic luxury goods manufacturing is generating import substitution demand for rigid cartonboard grades.
Industry Challenges
- De-inking technical expertise:Recycled fiber processing requires specialized chemical engineering talent scarce in traditional papermaking regions.
- Multi-ply lamination capex:Calendering and bonding equipment for high-stiffness solid board demands significant capital deployment with extended payback periods.
- FDA indirect food contact compliance:Recycled fiber streams face contamination testing protocols that delay product qualification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Binder's Board Market |
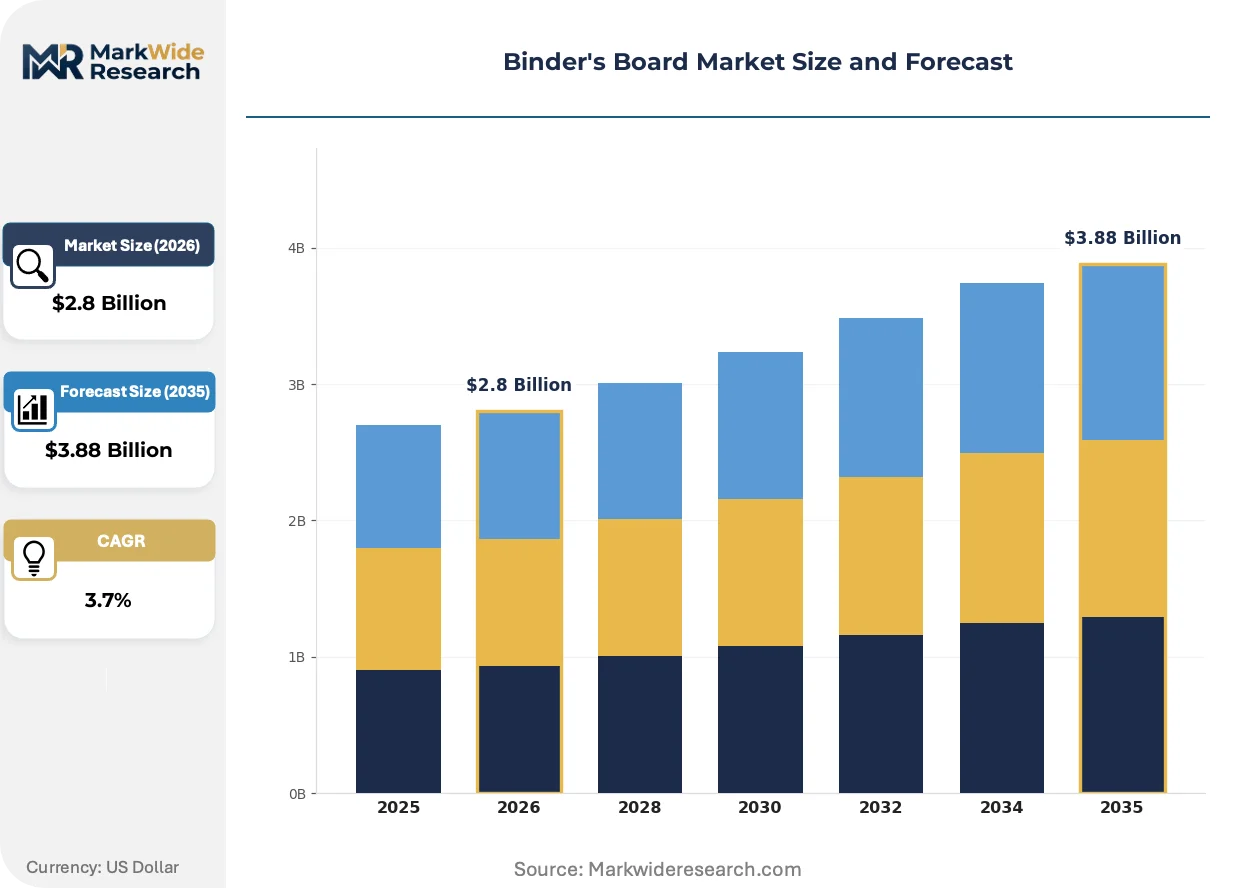
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $3.88 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Layer, Multi-Layer, Reinforced, Coated Application: Packaging, Bookbinding, Stationery, Display Material: Recycled Fiber, Virgin Fiber, Composite, Synthetic End User: Publishing, Retail, Manufacturing, Education |
| Companies Covered | Smurfit Kappa Group, Eska BV, Nippon Paper Industries Co., Ltd., Mondi Group, International Paper Company, Mayr-Melnhof Karton AG, WestRock Company, Stora Enso Oyj, Metsa Board Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Binder's Board Market Strategic Shifts
Active coating technologies and fiber engineering advances are redefining surface performance specifications across publishing and packaging end-uses.
High-stiffness solid board formulations are converging with nanocellulose reinforcement layers to achieve enhanced structural integrity at reduced basis weights. Luxury packaging converters in Germany and France are qualifying these grades for rigid box applications previously served by heavier traditional constructions. This convergence is compressing material intensity requirements while maintaining performance thresholds for foil stamping and UV coating adhesion.
EU Green Deal packaging sustainability targets are mandating minimum recycled content thresholds for consumer-facing applications. Mills serving European binderies must now document fiber provenance through chain-of-custody certification to maintain supplier status. Premium archival segments remain exempt but face customer pressure to demonstrate carbon footprint reductions.
Consolidated buying by multinational publishing houses is compressing supplier bases and extending contract durations. Long-term supply agreements with fixed-volume commitments are displacing spot purchasing for standard binder's board grades. This pattern concentrates procurement leverage among three to four major European book manufacturers while squeezing smaller regional mills.
Binder's Board Market Segmentation
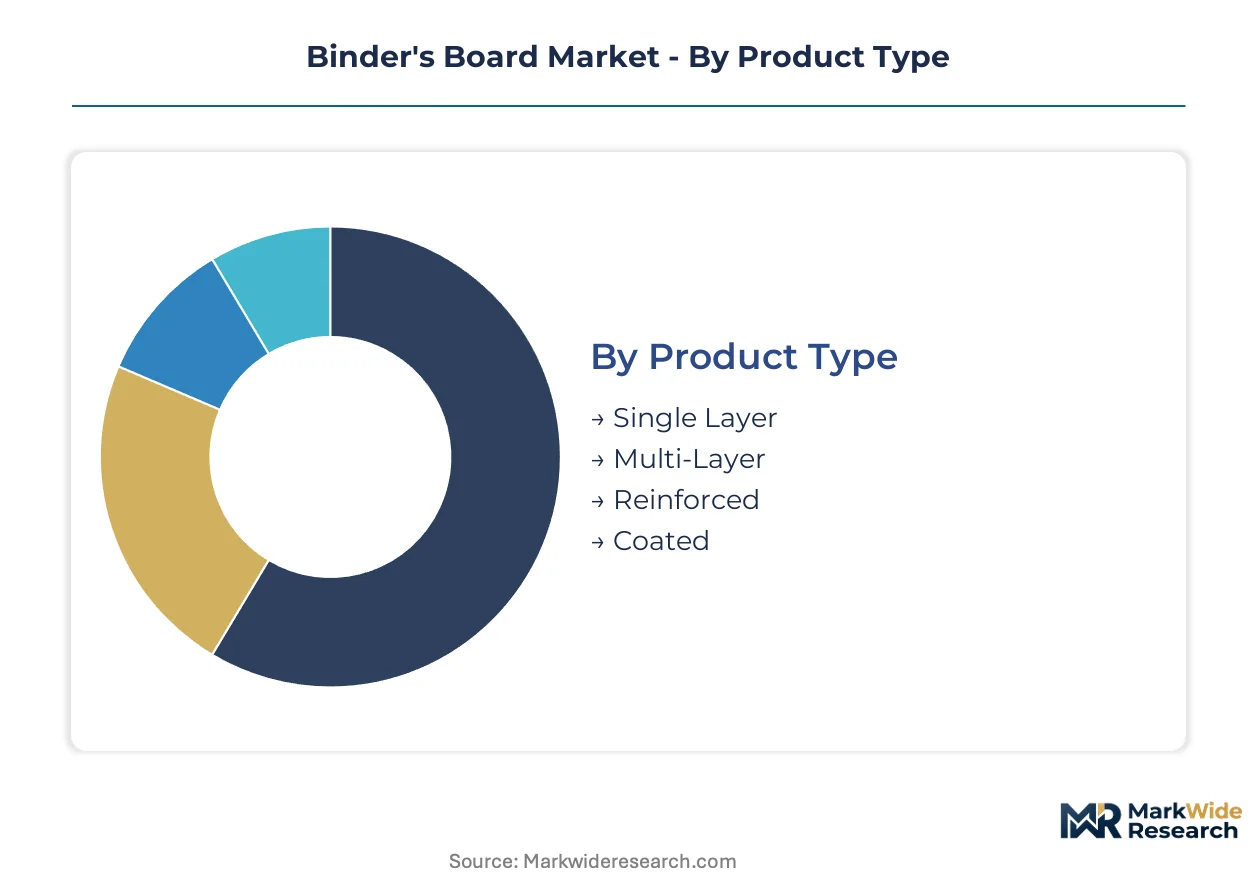
Binder's board segmentation reflects divergent performance requirements across structural rigidity, surface finish, and fiber provenance specifications. Buyers prioritize caliper consistency and bending resistance for luxury packaging, while archival segments demand lignin-free substrates with dimensional stability over decades.
Product Type:
Structural complexity drives pricing tiers, with laminations and reinforcements commanding premiums for high-stiffness applications.
- Multi-Layer:Laminated constructions bond three to seven fiber plies under heat and pressure, achieving densities between 0.90 and 1.20 g/cm³ with superior bending resistance. German and French luxury packaging converters specify these grades for rigid cosmetic boxes and spirits presentation cases where foil stamping quality is non-negotiable.
- Reinforced:Nanocellulose or synthetic fiber inclusions enhance structural integrity at reduced basis weights. Specialty board mills near Düsseldorf and Stuttgart are qualifying reinforced formulations for automotive sample books and industrial catalog covers requiring durability under repeated handling.
- Single Layer:Homogeneous fiber construction calendered to moderate density serves cost-sensitive educational textbook covers and mass-market stationery.
- Coated:Clay or polymer surface treatments enable high-resolution digital printing and UV coating adhesion for short-run premium publishing workflows.
Multi-Layer leads on scale; Reinforced leads on momentum.
Application:
End-use specifications fragment demand across dimensional stability requirements, print compatibility, and handling durability.
- Packaging:Rigid structural substrates for luxury goods demand enhanced bending resistance and surface uniformity for lamination and foil stamping. Premium cosmetics and spirits brands in Germany and France specify caliper tolerances within ±3% for automated box-making lines.
- Bookbinding:Hardcover editions require lay-flat properties and spine flexibility without cracking. Specialty publishing houses concentrate procurement among Rhineland-based suppliers offering chain-of-custody certification for recycled content claims.
- Display:Point-of-sale fixtures and permanent retail installations specify edge crush resistance and moisture stability for extended service life in climate-controlled environments.
- Stationery:Binder covers and file folders prioritize cost efficiency and punchability over structural performance, sourcing predominantly from integrated containerboard networks with captive recycled fiber supply.
Packaging dominates current volume; Bookbinding is expanding most quickly as premium editions displace mass-market paperbacks.
Material:
Fiber provenance determines regulatory compliance pathways and end-use eligibility, particularly for EU packaging mandates and archival applications.
- Recycled Fiber:Post-consumer pulp grades face margin compression from sorting and de-inking costs, yet EU Green Deal thresholds mandate minimum recycled content for consumer-facing packaging. Mills investing in advanced flotation de-inking capture certified fiber premiums from compliant brand owners.
- Virgin Fiber:Unbleached kraft and bleached chemical pulp sustain price premiums in museum-quality segments where lignin acidity concerns exclude recycled alternatives. Archival binderies specify alpha-cellulose content exceeding 87% for century-scale dimensional stability.
- Composite:Blended fiber formulations balance cost and performance for mid-tier publishing and commercial display applications.
- Synthetic:Polypropylene or polyester inclusions enhance moisture resistance and durability for outdoor signage and industrial tagging applications.
Virgin Fiber commands price leadership; Recycled Fiber is climbing the fastest on regulatory tailwinds.
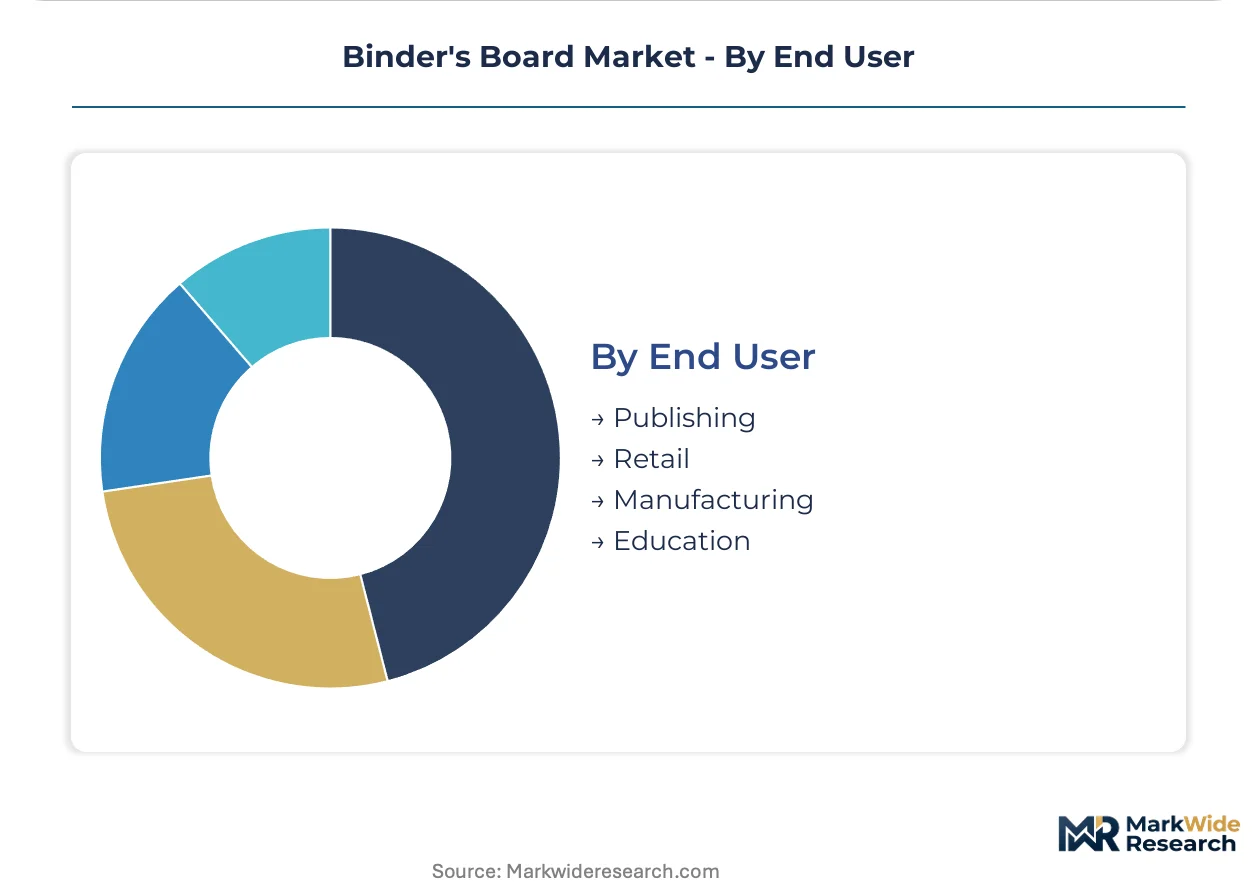
End User:
Procurement concentration and contract structures vary sharply across customer scale and specification tolerance.
- Publishing:Consolidated multinational houses extend long-term supply agreements with fixed-volume commitments, squeezing smaller regional mills. Three to four major European book manufacturers now concentrate leverage over standard binder's board grades.
- Retail:Luxury goods brands specify rigid structural boards with documented carbon footprint reductions, requiring chain-of-custody certification from Rhineland and Bavarian mill clusters.
- Manufacturing:Industrial sample books, technical documentation, and product catalogs demand durability under warehouse and field conditions, sourcing from specialized kraftliner operations.
- Education:Textbook consumption softens in print formats as digital adoption accelerates, compressing volume for standard-grade binder's board in North American and European markets.
Publishing leads on contract value; Retail leads on specification intensity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting binder's board production toward jurisdictions with lower compliance costs for recycled fiber processing, even as EU Green Deal mandates concentrate premium-grade manufacturing in high-standard environments.
Germany
Rhineland mill clusters near Düsseldorf and Cologne supply luxury packaging converters with certified chain-of-custody documentation. REACH chemical restrictions on coatings force continuous reformulation of water-based barrier treatments. Bavarian specialty board operations around Munich and Stuttgart are qualifying reinforced grades for automotive sample books and industrial catalog covers.
United States
EPA guidelines on recycled content claims shape formulation strategies for domestic binderies serving educational and trade publishing segments. FDA indirect food contact standards limit certain post-consumer fiber streams for packaging applications adjacent to consumable goods. Integrated containerboard networks in the Southeast and Pacific Northwest maintain captive pulp supply for standard-grade production.
France
Luxury cosmetics and spirits brands in the Île-de-France region specify rigid structural boards with documented carbon footprint reductions. EU packaging waste directives create certified recycled fiber premiums for compliant mills serving Parisian converting operations. Auvergne-Rhône-Alpes hosts specialized kraftliner operations supplying Central European binderies with archival-grade substrates.
China
Domestic luxury goods manufacturing in the Yangtze River Delta generates import substitution demand for rigid cartonboard grades previously sourced from European mills. Dual carbon goals under national climate policy are accelerating de-inking technology investments at major pulp and paper complexes. Shandong Province specialty board producers are expanding capacity for export-oriented packaging converters.
India
Emerging domestic luxury goods manufacturing in Maharashtra and Gujarat is driving demand for high-stiffness solid board formulations. BIS certification requirements for packaging materials influence supplier qualification timelines for multinational brands entering the market. Tamil Nadu converting clusters near Chennai are developing technical capabilities for foil stamping and UV coating adhesion on imported substrates.
Binder's Board Market Competitive Environment
Capacity expansion dominates the current landscape as integrated European containerboard networks reconfigure pulping operations to capture certified recycled fiber premiums. The vendor base clusters around three structural tiers: multinational paper conglomerates with captive fiber supply, regional specialty board mills serving geographic niches, and niche converters focused on archival-grade formulations. Strategic archetypes include backward-integrated giants controlling upstream pulp assets, technology-focused specialists in nanocellulose reinforcement, and sustainability-certified mills commanding green premiums. M&A activity and geographic expansion into Asian growth markets represent the dominant competitive vectors.
Within the integrated conglomerate tier, Smurfit Kappa Group and Mondi Group exemplify the backward-integrated model leveraging European containerboard networks for recycled fiber security. Eska BV occupies a specialist position emphasizing high-stiffness solid board formulations. These three entities represent distinct competitive archetypes: scale-driven fiber integration, geographic diversification across Central European converting clusters, and technical differentiation through engineered structural properties.
| Leading Market Players |
|---|
| Smurfit Kappa Group |
| Eska BV |
| Nippon Paper Industries Co., Ltd. |
| Mondi Group |
| International Paper Company |
| Mayr-Melnhof Karton AG |
| WestRock Company |
| Stora Enso Oyj |
| Metsa Board Corporation |
| Others |
Value Chain & Pricing Dynamics
EU recycled fiber content mandates are forcing mills to absorb de-inking cost premiums, compressing margins on post-consumer grades while virgin fiber substrates sustain archival premiums. This specification pressure concentrates pricing power among Rhineland and Bavarian mill clusters with captive pulping assets and certified chain-of-custody documentation.
Pricing Analysis
Distributor markups on specialty binder's board grades compress as direct mill-to-converter relationships displace intermediaries in Germany and France. Three-tier pricing structure across premium, standard, and economy levels separates archival virgin fiber from certified recycled grades and mass-market homogeneous constructions. Cost compression in recycled fiber tiers is intensifying because flotation de-inking investments lag EU Green Deal compliance timelines. Educational publishers exhibit highest price sensitivity, while luxury cosmetics brands prioritize specification compliance over unit cost.
Supply Chain Analysis
Chain-of-custody certification gates supplier status for EU luxury packaging converters, forcing mills to document fiber provenance through audited tracking systems. Production concentrates in Germany, France, and the Netherlands, with Rhineland clusters serving Parisian and Düsseldorf converting operations. Raw material supply draws from post-consumer recovered paper streams, unbleached kraft pulp, and nanocellulose reinforcement additives. Single-source vulnerability runs through German specialty board mills controlling premium multi-ply capacity. Distribution runs through integrated containerboard networks with direct mill-to-converter logistics contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU regulatory compliance costs in Germany and France create sourcing opportunities for Indian and Chinese mills with lower de-inking investment burdens.
For Market Incumbents: Lock in long-term supply agreements with fixed-volume commitments from consolidating multinational publishing houses before procurement leverage concentrates further. Defend margin position by deepening backward integration into captive recycled fiber sorting operations near Düsseldorf and Stuttgart, neutralizing post-consumer pulp cost volatility that threatens standard-grade profitability.
For New Entrants and Emerging Players: Capture white-space in Indian luxury packaging conversion as domestic cosmetics and spirits manufacturing generates import substitution demand for rigid cartonboard grades. Target Maharashtra and Gujarat binderies with technical partnerships for foil stamping qualification, leveraging BIS certification gaps that delay European competitor entry timelines.
For Investors and Strategic Acquirers: Asymmetric upside sits with nanocellulose reinforcement specialists commanding technical differentiation premiums as basis weight reduction becomes mandatory across EU packaging sustainability targets. Acquisition candidates include mid-cap German mills with stranded de-inking assets that could be repurposed for certified fiber premium capture. Watch for inflection when EU extended producer responsibility schemes create transferable recycling credit markets.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recovered Fiber Sorting | Captures certified recycled fiber premiums under EU Green Deal mandates. |
| Nanocellulose Reinforcement Layer Qualification | Enables basis weight reduction for luxury packaging converters in Germany. |
| Chain-of-Custody Certification Investment | Secures supplier status with Parisian cosmetics brands requiring carbon documentation. |
| Geographic Expansion into Indian Converting Clusters | Addresses import substitution demand from Maharashtra luxury goods manufacturing. |
| Long-Term Supply Agreement with Publishing Consolidators | Locks in volume commitments before three-to-four buyer concentration completes. |
Study Parameters
Multiple input streams — mill production data, converter procurement patterns, and regulatory filing documentation — were reconciled through bottom-up and top-down triangulation. Primary interviews with specialty board plant managers, luxury packaging procurement leads, and Rhineland bindery technical directors were validated against secondary sources including EU REACH substance registrations, EPA recycled content guideline interpretations, and trade flow customs records.
Historical capacity utilization trends were cross-referenced against expert panel assessments of de-inking technology deployment timelines across the analysis window. Segmentation modeling incorporated product type, fiber provenance, end-use application, and geographic production hub dimensions. CAGRs were derived from installed capacity expansion announcements, demand elasticity estimates for archival versus packaging grades, and substitution dynamics between recycled and virgin fiber substrates.
Underlying measurement precision varies by segment; virgin fiber archival grades carry tighter precision than emerging recycled fiber packaging categories due to established century-scale performance documentation. Forecasts reflect assumptions about EU packaging waste directive implementation pacing and FDA indirect food contact standard evolution. A model refresh is warranted upon material change in extended producer responsibility scheme adoption timelines or breakthrough de-inking cost reductions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Europe Paper Packaging Market
Paper & Paperboard Packaging
Cardboard Tubs Market
Paper & Paperboard Packaging
Global Solid Board Market
Paper & Paperboard Packaging
Saudi Arabia Paper and Paperboard Packaging Market
Paper & Paperboard Packaging
Envelope Market
Paper & Paperboard Packaging
Tea Filter Paper Market
Paper & Paperboard Packaging
Tacky Transfer Paper Market
Paper & Paperboard Packaging
North America Paper Packaging Market
Paper & Paperboard Packaging
Hanging Box Market
Paper & Paperboard Packaging
Folding Paperboard Boxes Market
Paper & Paperboard Packaging
Latin America Paper Packaging Market
Paper & Paperboard Packaging
Heat Sealable Pulp Board Tray Market
Paper & Paperboard Packaging
Middle East and Africa Corrugated Box Market
Paper & Paperboard Packaging
Poly Coated Paperboard Market
Paper & Paperboard Packaging
Kraftliner Market
Paper & Paperboard Packaging
Vietnam Paper Packaging Market