
 Folding Paperboard Boxes Market | 2026-2036
Folding Paperboard Boxes Market Size, Share, and Industry Trends Forecast 2026-2036
Folding Paperboard Boxes Market Foresight
The premium-commodity split in folding paperboard boxes is repositioning around barrier performance and print fidelity versus cost-optimized virgin kraft grades. Smurfit WestRock leverages integrated pulp-to-box operations across multiple continents to sustain margin capture in coated specialties. Graphic Packaging International anchors North American beverage multipack demand through in-house printing and cutting capabilities.
Folding paperboard boxes are rigid containers manufactured from layered cellulose fiber sheets, typically 200–400 gsm, scored and folded into rectangular configurations without permanent adhesive sealing during forming; they function primarily as protective, printable, and stackable enclosures for consumer goods distribution. Bleached Kraft grades dominate pharmaceutical and personal care applications where surface smoothness supports high-resolution lithographic printing and compliance with FDA contact regulations. Recycled Paperboard competes aggressively in dry-food and household product segments where cost sensitivity outweighs optical properties, while Foil-Laminated variants command premium placement in cosmetics and luxury confectionery channels.
The EU Packaging and Packaging Waste Regulation and FDA 21 CFR food-contact substance notifications jointly shape material substitution timelines and testing burdens for converters serving multinational brand owners. REACH restrictions on perfluorinated chemicals in grease-resistant coatings are forcing reformulation investments across European production networks. Stakeholders must monitor emerging state-level extended producer responsibility frameworks in the United States and pending GB standards revisions in China to anticipate compliance cost reallocations before contract renewal cycles.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is compressing substitution timelines as converters race to meet recycled content mandates before enforcement windows close. This regulatory pressure cascades through material specifications, testing protocols, and contract renegotiations across European production networks.
Growth Catalysts
- REACH reformulation mandates:Perfluorinated chemical restrictions in grease-resistant coatings are accelerating investment in bio-based barrier technologies. European converters are retooling coating lines ahead of compliance deadlines.
- Chilled ready-meal packaging:Food and beverage brands are specifying coated paperboard for temperature-sensitive applications. Germany's consolidated grocery retail sector is driving private-label specification convergence.
- Barrier performance tiering:Premium cosmetics and luxury confectionery channels are demanding foil-laminated variants with extended shelf-life properties. Surface smoothness requirements are tightening across pharmaceutical applications.
Market Restraints
- Pulp cost volatility:Softwood fiber prices fluctuate with Nordic supply disruptions and energy input spikes. Integrated producers maintain margin buffers unavailable to merchant converters.
- Recycled fiber quality degradation:Post-consumer waste streams contain rising contamination levels. FDA 21 CFR food-contact notifications impose testing burdens that slow material substitution.
- Plastic substitution economics:Polypropylene and PET retain cost advantages in moisture-critical applications. Barrier-coated paperboard carries 15-30% premiums at equivalent performance tiers.
Strategic Opportunities
- Extended producer responsibility frameworks:Emerging state-level EPR legislation in the United States creates design-for-recycling consulting revenue streams. Brand owners require compliance pathway mapping.
- Digital printing convergence:Inkjet and electrophotographic systems enable short-run versioning for regional promotional campaigns. Beverage multipack converters are capturing versioning premiums.
- Pharmaceutical serialization integration:Track-and-trace mandates are expanding printable surface requirements. Folding carton specifications now incorporate authentication features previously outsourced to labels.
Industry Challenges
- Coating chemist talent scarcity:Reformulation expertise in bio-based barriers commands premium compensation. European technical universities produce insufficient polymer science graduates for packaging specialization.
- Legacy cutting die compatibility:New barrier coatings alter crease recovery and fold endurance. Tooling investments compound material transition costs for mid-scale converters.
- Multi-jurisdiction certification timelines:Simultaneous EU, FDA, and GB standards compliance requires parallel testing protocols. Contract renewal cycles compress available validation windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Folding Paperboard Boxes Market |
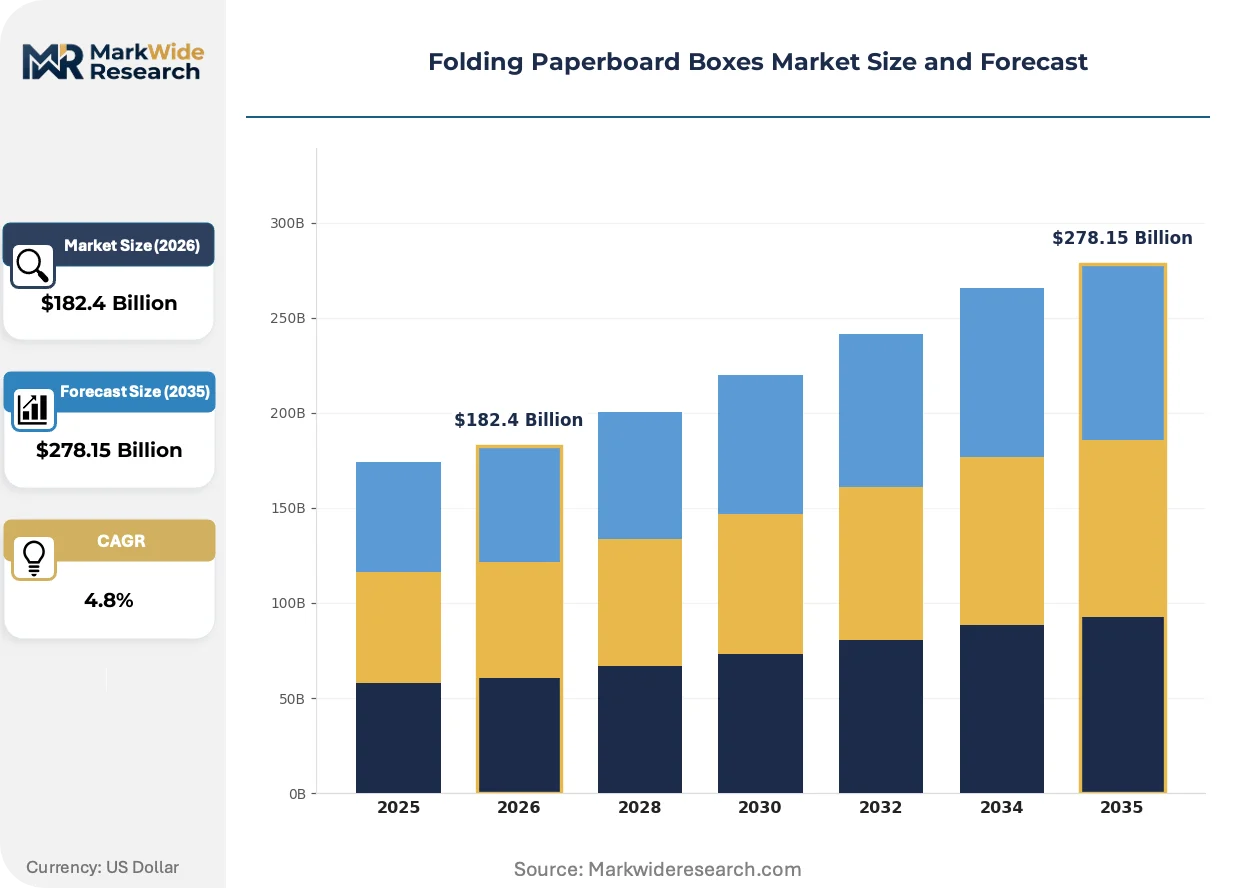
| Market Size in 2026 | $182.4 Billion |
| Market Size in 2035 | $278.15 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Die-Cut Boxes, Telescope Boxes, Auto-Lock Bottom, Seal-End Boxes, Reverse Tuck End Material Grade: Bleached Kraft, Unbleached Kraft, Recycled Paperboard, Virgin Paperboard, Foil-Laminated End Use Industry: Consumer Electronics, Food & Beverage, Personal Care, Pharmaceuticals, Household Products Distribution Channel: Direct Sales, E-Commerce, Wholesale Distributors, Retail Stores |
| Companies Covered | Smurfit WestRock, Graphic Packaging International, International Paper, WestRock Company, Mayr-Melnhof Karton AG, Amcor plc, Stora Enso, Huhtamaki, Oji Holdings Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Folding Paperboard Boxes Market Shifts & Advancements
Active barrier technologies and digital production workflows are compressing minimum order quantities while expanding customization capabilities. Material science advances are redefining performance boundaries between commodity and specialty grades.
Water-based barrier coatings are converging with oxygen-scavenging additive systems to create single-material structures that replace multi-layer laminates. Pharmaceutical and personal care brands are piloting these solutions for moisture-sensitive applications. The technology is converging with existing converting infrastructure to avoid capital-intensive equipment replacement.
REACH restrictions on perfluorinated chemicals are forcing coating reformulations across European production networks. Industrial consequence includes accelerated R&D spend and supplier qualification delays. Dry-food segments with lower barrier requirements are absorbing reformulation costs faster than chilled applications.
Brand owner specification consolidation is compressing supplier approval processes. Germany's grocery retail sector is consolidating private-label packaging standards, reducing qualified supplier lists. This concentration is most visible in beverage multipack and ready-meal segments where scale economies dominate sourcing decisions.
Folding Paperboard Boxes Market Segmentation
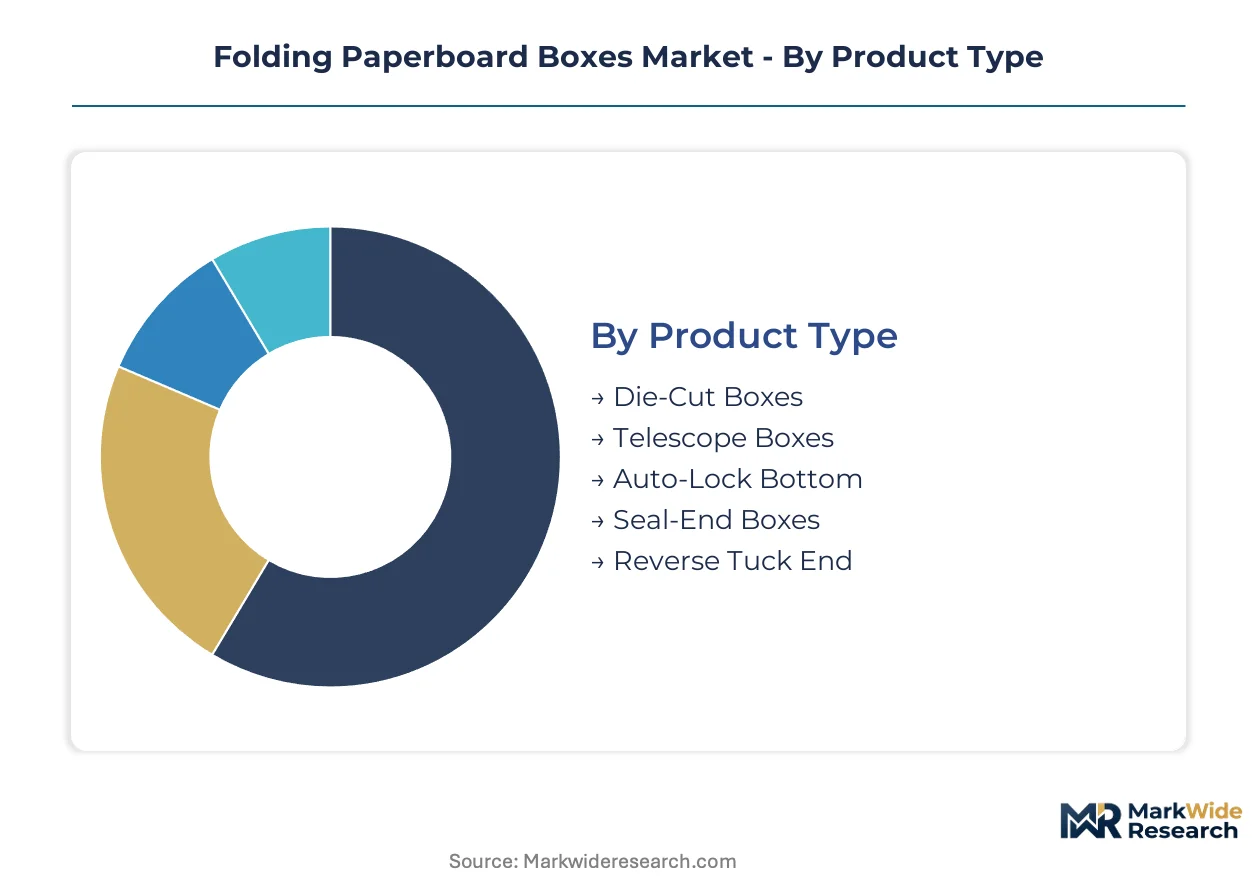
Converters and brand owners select folding paperboard configurations based on run length, barrier requirements, and fulfillment velocity. Specification decisions cascade through material grade selection, forming method, and distribution channel alignment.
Product Type:
Forming complexity and labor efficiency at the packing line drive converter selection among structural variants.
- Die-Cut Boxes:Precision-cut creases and slots enable rapid assembly without specialized tooling. Germany's consolidated grocery retail sector specifies die-cut configurations for private-label ready-meal packaging where throughput velocity dominates.
- Auto-Lock Bottom:Pre-glued base flaps interlock during erection, eliminating tape or adhesive at the fulfillment stage. E-commerce fulfillment centers favor this structure for subscription box programs where pack-out speed determines labor cost per unit.
- Telescope Boxes:Separate lid and tray components suit gift and premium confectionery applications requiring reveal presentation.
- Seal-End Boxes:Manufacturer-sealed closures protect pharmaceutical and personal care products from tampering and environmental exposure.
- Reverse Tuck End:Economical friction closures serve dry-food and household product segments where cost sensitivity outweighs premium unboxing requirements.
Volume sits with Reverse Tuck End; growth tilts toward Auto-Lock Bottom.
Material Grade:
Surface smoothness, fiber origin, and barrier performance stratify raw material procurement across end-use specifications.
- Bleached Kraft:Alpha-cellulose dominance delivers high brightness and print fidelity for lithographic reproduction. FDA 21 CFR food-contact notifications govern its use in pharmaceutical and personal care applications where surface quality supports brand differentiation.
- Recycled Paperboard:Post-consumer fiber content satisfies EU Packaging and Packaging Waste Regulation mandates. Dry-food and household product segments absorb this grade fastest as REACH restrictions on coatings complicate food-contact migration testing.
- Unbleached Kraft:Natural fiber coloration signals sustainability positioning in organic and natural product channels.
- Virgin Paperboard:Consistent fiber length preserves structural integrity in moisture-variable climates.
- Foil-Laminated:Metallized barrier layers extend shelf life for moisture- and oxygen-sensitive contents in cosmetics and luxury confectionery.
Procurement concentrates on Recycled Paperboard; premium positioning drives Foil-Laminated expansion.
End Use Industry:
Regulatory exposure and product value density determine specification tolerance for material cost premiums.
- Food & Beverage:Chilled ready-meal applications demand coated paperboard with grease-resistant barriers. Germany's private-label consolidation is compressing supplier qualification timelines for temperature-sensitive specifications.
- Pharmaceuticals:Serialization mandates expand printable surface requirements. Folding cartons now integrate track-and-trace authentication features previously outsourced to labels.
- Personal Care:Premium unboxing experiences drive foil-laminated and specialty-coated specifications.
- Consumer Electronics:Protective cushioning requirements favor rigid box structures with insert compatibility.
- Household Products:Cost-optimized recycled grades dominate detergent and cleaning product multipacks.
Shipment volume clusters in Food & Beverage; specification complexity climbs fastest in Pharmaceuticals.
Distribution Channel:
Order fragmentation and lead-time compression reshape converter channel strategy.
- Direct Sales:Long-term contracts with multinational brand owners stabilize capacity utilization. Beverage multipack converters leverage in-house printing and cutting capabilities to capture versioning premiums through direct relationships.
- E-Commerce:Digital printing convergence enables short-run versioning for regional promotional campaigns. Subscription box startups require Auto-Lock Bottom structures with rapid turnaround.
- Wholesale Distributors:Inventory pooling serves mid-scale converters lacking scale for mill-direct procurement.
- Retail Stores:Point-of-purchase display integration demands coordinated structural and graphic design.
Contract value aggregates in Direct Sales; order frequency expands most quickly through E-Commerce.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Düsseldorf anchors European folding paperboard procurement as Germany's grocery retail consolidation compresses supplier qualification timelines for chilled ready-meal specifications.
United States
Beverage multipack demand and pharmaceutical serialization mandates drive specification complexity. FDA 21 CFR food-contact notifications govern material substitution timelines for converters serving multinational brand owners. The Chicago-Milwaukee corridor concentrates integrated pulp-to-box operations.
Germany
Private-label packaging standardization across consolidated grocery retail accelerates coated paperboard adoption for temperature-sensitive applications. REACH restrictions on perfluorinated chemicals in grease-resistant coatings force reformulation investments. The Rhine-Ruhr industrial cluster hosts specialized barrier coating R&D facilities.
China
Consumer electronics protective packaging and e-commerce subscription box programs expand demand for rigid structural configurations. GB standards revisions pending in food-contact categories create compliance preparation cycles. The Yangtze River Delta concentrates die-cutting and digital printing convergence capabilities.
India
Dry-food segments absorb recycled paperboard grades fastest as cost sensitivity outweighs optical property requirements. FSSAI food-contact regulations intersect with state-level plastic substitution incentives. Maharashtra's Nashik-Pune corridor emerges as a converting hub for FMCG contract packaging.
Japan
Premium cosmetics and luxury confectionery channels sustain foil-laminated specifications with extended shelf-life properties. METI circular economy guidelines shape design-for-recycling consulting demand. The Kanto region maintains precision folding and authentication feature integration capabilities.
Folding Paperboard Boxes Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the folding paperboard value chain. Integrated pulp-to-box operators capture margin buffers unavailable to merchant converters dependent on spot fiber markets. Three archetypes dominate: multinational integrated giants with captive pulp supply, regional specialists in barrier-coated specialties, and digital-native converters serving versioning-intensive e-commerce channels. Consolidation through mill acquisitions and coating technology licensing agreements represents the primary competitive trajectory.
Among European-based integrated producers, Mayr-Melnhof Karton AG and Stora Enso exemplify the multinational archetype with captive fiber and coating capabilities. Smurfit WestRock occupies a position spanning multiple continents through combined containerboard and folding carton operations. These entities represent the scale-driven tier where backward integration into pulp production insulates margin capture from Nordic softwood price volatility.
| Leading Market Players |
|---|
| Smurfit WestRock |
| Graphic Packaging International |
| International Paper |
| WestRock Company |
| Mayr-Melnhof Karton AG |
| Amcor plc |
| Stora Enso |
| Huhtamaki |
| Oji Holdings Corporation |
| Others |
Supply & Pricing Matrix
Softwood pulp costs cascade through three distinct pricing tiers as Nordic fiber supply disruptions and energy input spikes compress margins at merchant converters while integrated producers sustain capture. Barrier-coated specialties command 15-30% premiums over virgin kraft grades, with foil-laminated variants anchoring the top tier for cosmetics and luxury confectionery channels.
Pricing Analysis
Throughput-based pricing anchors converter contracts as brand owners tie unit economics to packing line velocity and crease recovery performance. Three-tier pricing structure across premium, standard, and economy levels stratifies by barrier certification grade and volume scale, with pharmaceutical serialization mandates lifting premium tier tolerance. Cost compression in commodity recycled grades is intensifying because post-consumer contamination degrades fiber quality and FDA testing burdens slow substitution. Dry-food and household product segments exhibit highest price sensitivity, while pharmaceutical and personal care buyers absorb premiums for print fidelity and compliance documentation.
Supply Chain Analysis
Coating chemist scarcity in Germany, Finland, and Sweden constrains barrier reformulation capacity as REACH deadlines accelerate. Raw material sourcing draws from Brazilian eucalyptus pulp, Nordic softwood fiber, and metallized film substrates, with bio-based barrier R&D tethered to European technical university pipelines. Single-source vulnerability concentrates in specialized grease-resistant coating formulations as perfluorinated chemical restrictions force supplier qualification delays. Distribution runs through mill-direct contracts with multinational brand owners, wholesale pooling for mid-scale converters, and digital-native channels serving e-commerce versioning demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU recycled content mandates and REACH reformulation deadlines are forcing weaker converters out, creating acquisition opportunities for capitalized players with captive pulp and coating capabilities.
For Market Incumbents: Cement barrier coating R&D leadership through in-house polymer science recruitment and university partnership pipelines in the Rhine-Ruhr cluster. Acquire distressed mid-scale converters in Germany to consolidate private-label supplier lists before grocery retail specification windows close. Vertical integration into metallized film lamination insulates margin capture from specialty substrate supply constraints. For New Entrants and Emerging Players: Enter via digital printing convergence for beverage multipack versioning, where short-run promotional campaigns escape scale barriers of lithographic infrastructure. Target e-commerce subscription box programs requiring Auto-Lock Bottom structures with rapid turnaround capabilities. Lead with design-for-recycling consulting services as emerging state-level EPR frameworks in the United States create compliance pathway revenue. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional specialists with captive barrier coating capabilities in Germany and the Chicago-Milwaukee corridor as pulp cost volatility eliminates merchant converter viability. Long-term viability hinges on backward integration into pulp production and certification depth across EU, FDA, and GB standards. Watch for GB standards revision announcements in China as inflection signals for Asia-Pacific capacity reallocation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulp Production | Captive softwood fiber supply insulates margin capture from Nordic price volatility. |
| Bio-Based Barrier Coating R&D Investment | REACH compliance deadlines force reformulation ahead of perfluorinated chemical restrictions. |
| Digital Printing Capability Expansion | Inkjet and electrophotographic systems capture versioning premiums in beverage multipacks. |
| Pharmaceutical Serialization Integration | Track-and-trace mandates expand folding carton specifications into authentication features. |
| Design-for-Recycling Consulting Launch | Extended producer responsibility frameworks create compliance pathway revenue streams. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with folding carton plant managers, procurement leads at FMCG brand owners, coating R&D directors, and grocery retail category buyers. Bottom-up volume modeling triangulated against top-down macroeconomic indicators, with secondary validation drawing from EU Packaging and Packaging Waste Regulation implementation timelines, FDA 21 CFR food-contact notification databases, and REACH restriction proposal tracking.
Segmentation granularity spanned material grade, structural configuration, end-use industry, and distribution channel across the analysis window, with regional clusters modeled at country level for Germany, United States, China, India, and Japan. CAGRs derived from historical shipment trajectories, capacity utilization rates at integrated producers, and substitution elasticity estimates for plastic-to-paperboard conversion in chilled ready-meal applications.
Revisions become necessary when REACH enforcement timelines accelerate, GB standards revisions diverge from FDA harmonization pathways, or pulp cost volatility exceeds historical bands. Material deviation in these triggers warrants pause and re-evaluation of capacity expansion and acquisition assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Disposable Paper Plates Market
Paper & Paperboard Packaging
Middle-East and Africa Corrugated Packaging Market
Paper & Paperboard Packaging
Converting Paper Market
Paper & Paperboard Packaging
Eco-Friendly Paper Plates Market
Paper & Paperboard Packaging
Coated Sack Kraft Paper Market
Paper & Paperboard Packaging
North America Corrugated Packaging Market
Paper & Paperboard Packaging
Masking Paper Market
Paper & Paperboard Packaging
Tissue and Hygiene Paper Packaging Market
Paper & Paperboard Packaging
Global Fanfold Corrugated Market
Paper & Paperboard Packaging
Protective Paperboard Market
Paper & Paperboard Packaging
Vietnam Paper Packaging Market
Paper & Paperboard Packaging
Kitchen Oil Absorbing Paper Market
Paper & Paperboard Packaging
Global Corrugated Board Packaging Market
Paper & Paperboard Packaging
Wax-Coated Paper Market
Paper & Paperboard Packaging
Testliner Market
Paper & Paperboard Packaging
Wrapping Paper Market