
 Insulated Paper Bags Market | 2026-2036
Insulated Paper Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Insulated Paper Bags Market Foresight
Buyer concentration across food service chains is pivoting toward national quick-service restaurant operators that demand insulated packaging at franchise scale. International Paper Company leverages its North American pulp integration to supply thermal-grade kraft substrates directly to bag converters. Smurfit Kappa Group PLC anchors European demand through its pan-regional corrugated and paperboard logistics network. Novolex competes on proprietary film-to-fiber lamination technology that improves heat retention in paper-based formats.
Insulated paper bags combine cellulose-based substrates with reflective foil or foam interlayers to maintain internal temperatures during transport, typically achieving thermal resistance values between 0.5 and 2.0 m²·K/W depending on construction. The primary commercial purpose centers on protecting perishable food and temperature-sensitive pharmaceuticals during last-mile delivery without plastic dependency. Kraft paper material dominates current volume owing to established recycling infrastructure and FDA food-contact approval pathways, while biodegradable paper variants attract premium positioning among sustainability-focused retailers. Bottom gusset bags lead in food service adoption because their expanded base accommodates container stability, whereas stand up pouches capture faster growth in meal-kit subscription channels where vertical shelf presentation matters.
The FDA regulates food-contact substances in insulated paper bags through 21 CFR standards, while the EU Packaging and Packaging Waste Directive sets recovery targets that member states enforce through national agencies like Germany's KBA-adjacent environmental offices. China's SAMR enforces GB standards for composite packaging that include thermal paper constructions, creating compliance complexity for exporters. Stakeholders must monitor how fragmented national recycling rules reshape material specifications before committing capital to regional production lines.
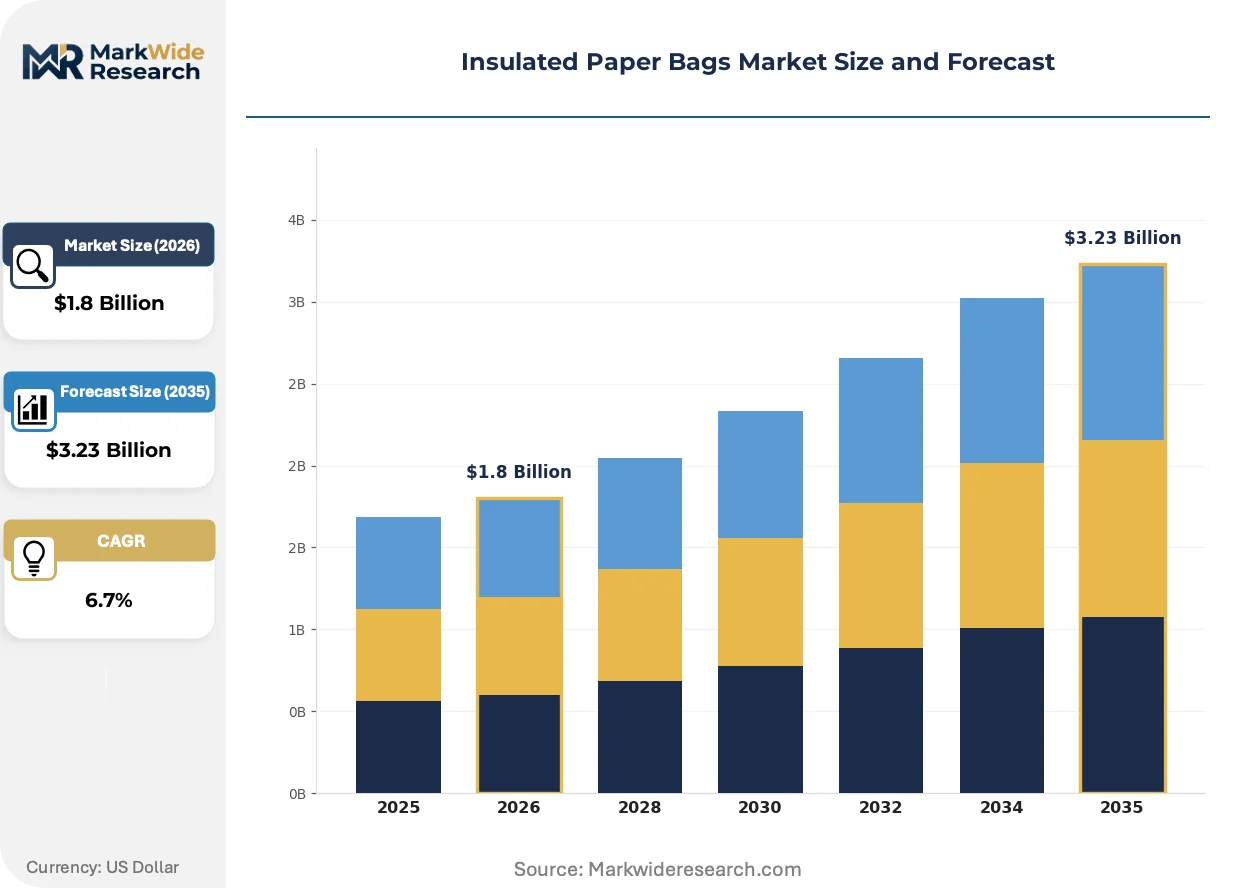
Market Dynamics
Quick-service restaurant chains in the United States, Germany, and China are consolidating procurement specifications around thermal-grade kraft substrates, forcing substrate suppliers to align production with franchise-level volume commitments and FDA, EU Packaging and Packaging Waste Directive, and SAMR compliance pathways simultaneously.
Growth Catalysts
- EU Single-Use Plastics Directive:Member states including Germany and France enforce material transition mandates that compel food service operators to replace polystyrene and plastic film with cellulose-based thermal packaging.
- Quick-service restaurant cold-chain expansion:National chains in the United States are scaling delivery radius requirements, creating pull for bags achieving thermal resistance above 1.5 m²·K/W.
- Meal-kit subscription channels:Vertical shelf presentation requirements in refrigerated logistics are accelerating stand-up pouch formats with integrated foil interlayers.
Market Restraints
- Pulp cost volatility:Kraft paper substrate pricing fluctuates with North American softwood pulp futures, compressing converter margins during supply tightness.
- Recycling infrastructure fragmentation:Germany's KBA-adjacent environmental offices enforce stricter composite packaging sorting rules than Italian or Spanish agencies, complicating pan-European product standardization.
- Performance ceiling of fiber-based insulation:Cellulose-foam laminations struggle to match expanded polystyrene thermal resistance above 2.5 m²·K/W, limiting penetration in frozen pharmaceutical transport.
Strategic Opportunities
- India's quick-service penetration:FSSAI food-contact approvals for imported thermal substrates remain underdeveloped, creating first-mover advantage for converters establishing local lamination capacity.
- Biodegradable paper variants:Premium positioning among sustainability-focused retailers in California and New York commands price premiums for ASTM D6400-certified compostable constructions.
- Pharmaceutical last-mile:Temperature-sensitive biologics distribution in China requires validated cold-chain packaging that SAMR GB standards now explicitly cover for composite paper-foil formats.
Industry Challenges
- Multi-jurisdiction certification timelines:Simultaneous FDA 21 CFR, EU REACH, and SAMR GB testing extends product launch cycles by 8-14 months for global bag converters.
- Lamination equipment reconfiguration:Shifting from solvent-based to water-based adhesive systems for food-contact compliance demands capital deployment in film-to-fiber bonding lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Insulated Paper Bags Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Bags, Bottom Gusset Bags, Die Cut Bags, Stand Up Pouches End User: Food Service, Retail, Packaging Suppliers, E-commerce Material: Recycled Paper, Kraft Paper, Coated Paper, Biodegradable Paper Capacity: Small, Medium, Large, Custom Sizes |
| Companies Covered | International Paper Company, WestRock Company, Smurfit Kappa Group PLC, Uline, Novolex, Georgia-Pacific LLC, OJI Holding Corporation, DS Smith Plc, Hood Packaging Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Insulated Paper Bags Market Shifts & Advancements
Material science advances in reflective foil interlayers and bio-based foam cores are compressing the performance gap between paper-based and plastic thermal packaging, while regulatory pressure accelerates format standardization across major demand clusters.
Multilayer kraft-foil-kraft constructions with embossed air-gap patterns are consolidating as the dominant thermal architecture for quick-service delivery. Chains including McDonald's franchise operators in the United States and Germany specify this format for orders maintaining temperature above 60°C for 30 minutes. The technology is consolidating converter capacity around North American pulp-integrated suppliers capable of captive metallized film production.
REACH restrictions on per- and polyfluoroalkyl substances are eliminating oil-resistant coatings previously standard in food-contact paper packaging. EU member states enforce these limits through ECHA-registered compliance schemes, forcing bag producers to migrate toward silicone-based or bio-wax barrier treatments. Cold-chain grocery delivery networks in the Netherlands and Denmark face the steepest reformulation timelines due to earlier national PFAS phase-out commitments.
Consolidated procurement desks at national restaurant chains are compressing supplier rosters from regional converters to three approved vendors per geography. United States-based Yum! Brands and Domino's Pizza operators now mandate direct mill relationships for thermal substrate traceability. This concentration is most visible in the Northeast corridor, where New York state plastic bag bans intersect with corporate sustainability scorecards requiring recycled content verification.
Insulated Paper Bags Market Segmentation
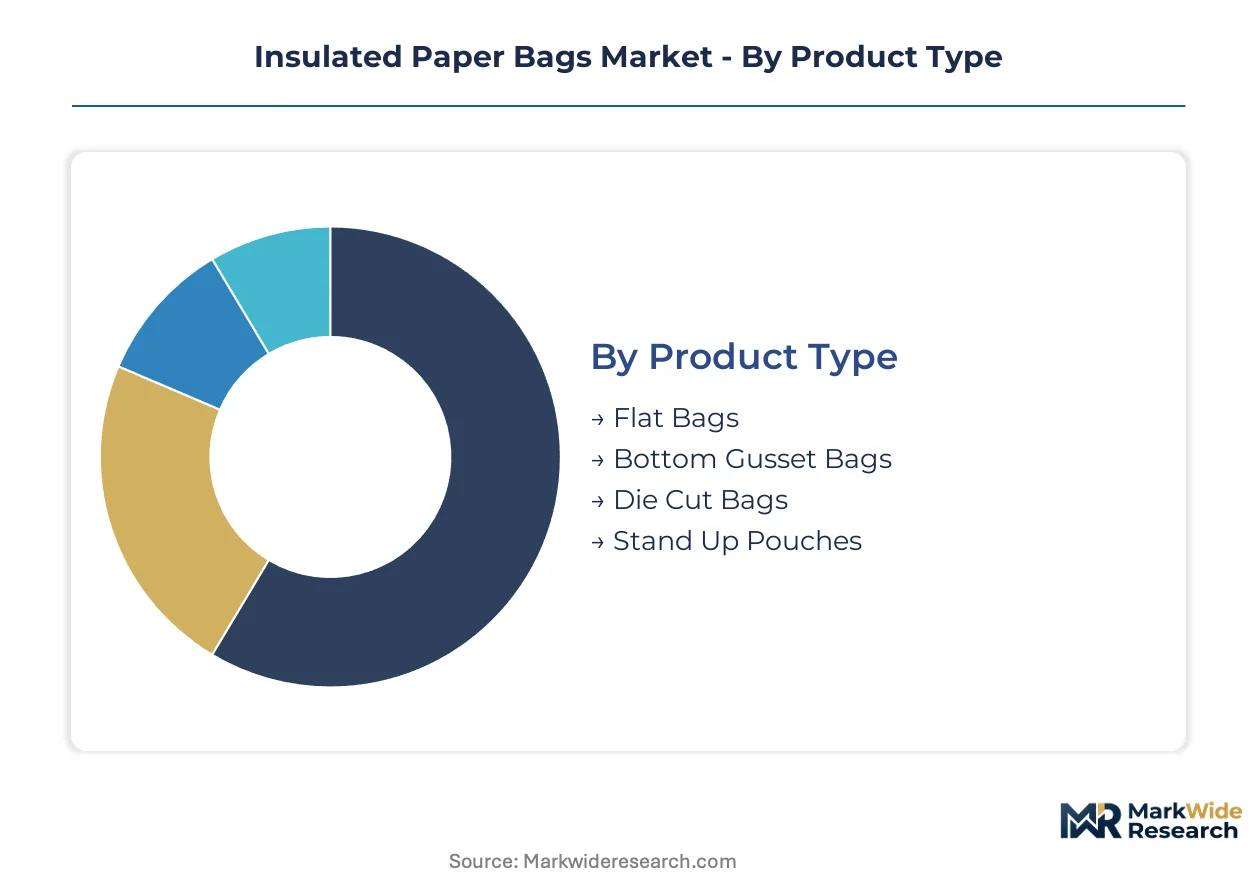
Insulated paper bag converters configure production lines around thermal performance specifications that vary sharply by end-use temperature requirements and recycling infrastructure constraints. Material choices and format geometries determine lamination complexity, directly affecting capital deployment decisions and margin structures across converter tiers.
Product Type:
Supply concentration in quick-service restaurant procurement is driving format standardization toward architectures that balance thermal resistance with automated fulfillment line compatibility.
- Bottom Gusset Bags:Expanded base geometry accommodates container stability in pizza and prepared meal delivery, with McDonald's and Domino's franchise operators in the United States and Germany specifying this format for orders maintaining temperature above 60°C for 30 minutes. Demand concentrates in national quick-service chains scaling cold-chain delivery radius requirements.
- Stand Up Pouches:Vertical shelf presentation architecture integrates foil interlayers for meal-kit subscription channels where refrigerated logistics require compact footprint optimization. HelloFresh and Blue Apron procurement specifications in California and New York are accelerating converter capacity reconfiguration toward this format.
- Flat Bags:Simple two-ply kraft construction serves pharmacy and small-item retail with minimal thermal retention requirements.
- Die Cut Bags:Handle-integrated formats target boutique food service and specialty retail with custom branding surface area.
Today's leader: Bottom Gusset Bags. Tomorrow's challenger: Stand Up Pouches.
End User:
Cost tier differentiation separates volume-committed national accounts from fragmented regional operators with diverging specification tolerance.
- Food Service:Thermal-grade kraft substrates with embossed air-gap patterns dominate quick-service procurement, with Yum! Brands mandating direct mill relationships for substrate traceability. FDA 21 CFR compliance pathways and recycled content verification requirements compress supplier rosters to three approved vendors per geography in the United States Northeast corridor.
- E-commerce:Cold-chain grocery delivery networks in the Netherlands and Denmark specify multilayer constructions with silicone-based barrier treatments replacing phased-out PFAS coatings under ECHA-registered REACH restrictions.
- Retail:California and New York state plastic bag bans intersect with corporate sustainability scorecards requiring ASTM D6400-certified compostable constructions for premium positioning.
- Packaging Suppliers:Converter intermediaries serving fragmented food service and retail accounts with standardized stock formats.
Food Service commands current volume concentration. E-commerce represents the steepest expansion trajectory as grocery delivery networks scale.
Material:
Application requirements determine barrier specification, with FDA food-contact approval pathways and EU Packaging and Packaging Waste Directive recovery targets creating divergent compliance burdens.
- Kraft Paper:Established North American softwood pulp supply chains and FDA 21 CFR approval pathways dominate volume, with International Paper Company leveraging captive metallized film production for thermal-grade substrates.
- Biodegradable Paper:ASTM D6400-certified compostable constructions command price premiums among sustainability-focused retailers in California and New York with corporate sustainability scorecard requirements.
- Recycled Paper:Post-consumer content specifications vary by German KBA-adjacent environmental office rules versus Italian or Spanish agency enforcement, complicating pan-European standardization.
- Coated Paper:Silicone-based and bio-wax barrier treatments replacing eliminated PFAS coatings under EU REACH restrictions for cold-chain grocery delivery in Denmark and the Netherlands.
Kraft Paper holds supply chain scale. Biodegradable Paper is gaining share fastest among premium sustainability segments.
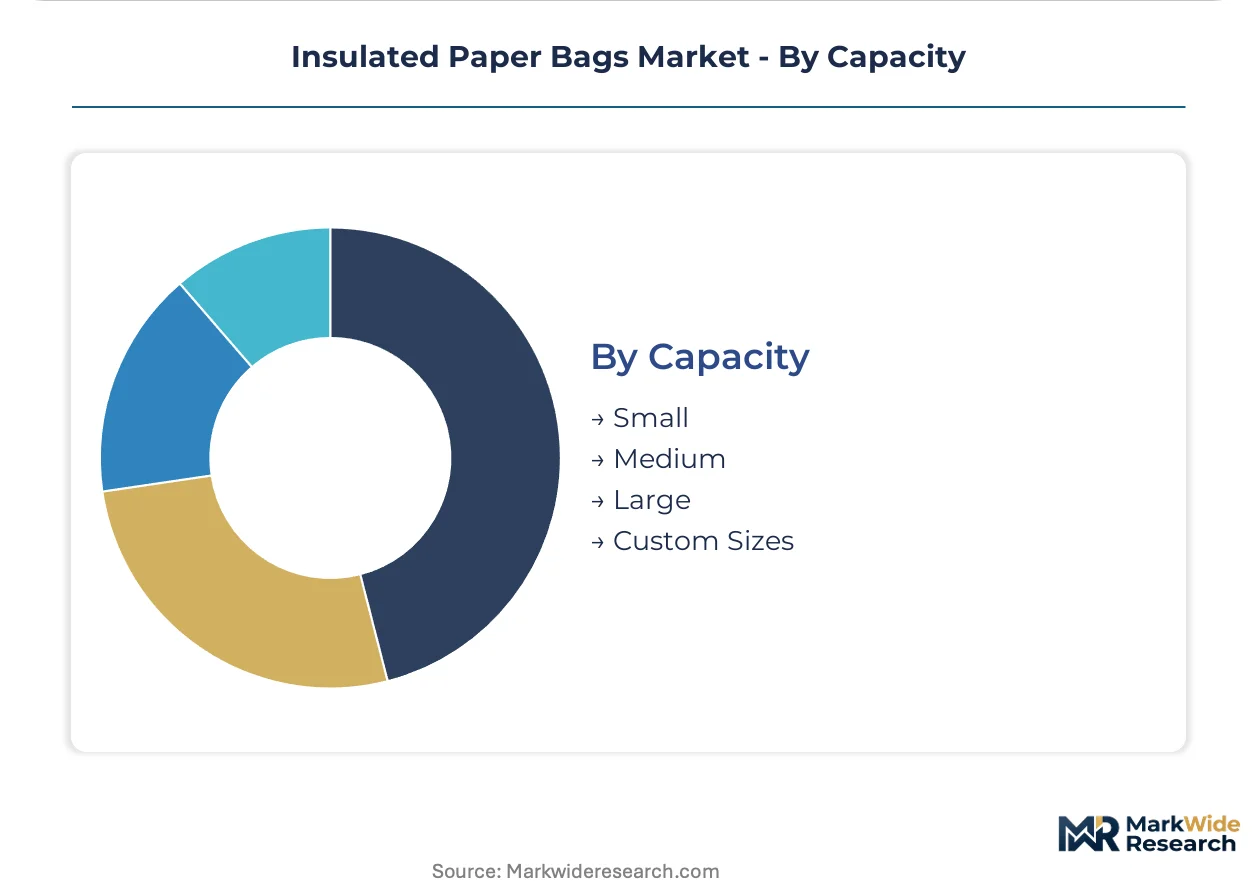
Capacity:
Customer type segmentation separates franchise-scale procurement with custom specification tolerance from stock-format purchasers with rigid size standards.
- Large:Catering and family-meal formats with expanded base dimensions for container stability in institutional food service.
- Custom Sizes:Pharmaceutical last-mile distribution in China requires SAMR GB-standard validated cold-chain packaging with precise dimensional tolerance for temperature-sensitive biologics.
- Medium:Standard quick-service individual meal formats with thermal resistance targets between 0.5 and 2.0 m²·K/W.
- Small:Single-item pharmacy and specialty retail with minimal insulation requirements.
Medium capacity dominates transaction volume. Custom Sizes are climbing the fastest as pharmaceutical cold-chain validation requirements proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States generates franchise-scale procurement volumes that Germany cannot replicate, while China's cold-chain pharmaceutical demand is expanding faster than either market.
United States
Yum! Brands and Domino's Pizza operators mandate direct mill relationships for thermal substrate traceability, compressing supplier rosters to three approved vendors per geography. FDA 21 CFR food-contact standards govern kraft paper approval pathways. The Northeast corridor concentrates procurement activity where New York state plastic bag bans intersect with corporate sustainability scorecards requiring recycled content verification.
Germany
McDonald's franchise operators specify embossed air-gap kraft-foil-kraft constructions maintaining temperatures above 60°C for 30 minutes. The EU Packaging and Packaging Waste Directive recovery targets are enforced through KBA-adjacent environmental offices with stricter composite packaging sorting rules than southern European counterparts. The Rhine-Ruhr industrial cluster hosts converters reconfiguring lamination equipment for water-based adhesive compliance.
China
Temperature-sensitive biologics distribution requires SAMR GB-standard validated cold-chain packaging with precise dimensional tolerance. Quick-service restaurant chains are scaling delivery radius requirements, creating pull for thermal resistance above 1.5 m²·K/W. The Yangtze River Delta concentrates converter capacity serving both domestic pharmaceutical networks and export markets.
India
FSSAI food-contact approvals for imported thermal substrates remain underdeveloped, creating first-mover advantage for converters establishing local lamination capacity. Quick-service penetration is accelerating among national chains expanding cold-chain delivery infrastructure. Maharashtra and Karnataka industrial corridors attract initial converter investments targeting undeveloped certification pathways.
Netherlands
Cold-chain grocery delivery networks specify multilayer constructions with silicone-based barrier treatments replacing phased-out PFAS coatings under ECHA-registered REACH restrictions. Earlier national PFAS phase-out commitments impose steeper reformulation timelines than neighboring markets. The Randstad logistics hub concentrates last-mile fulfillment operations driving insulated format specification.
Insulated Paper Bags Market Competitive Landscape
North American pulp-integrated producers anchor one tier; European pan-regional packaging specialists hold converter relationships across fragmented national agencies. Supplier rosters compress from regional converters to three approved vendors per geography as procurement desks consolidate. Two strategic archetypes dominate: captive metallized film producers and proprietary lamination technology specialists. Competitive moves center on backward integration into substrate supply and geographic expansion into underdeveloped certification markets.
Within the integrated pulp-to-converter tier, International Paper Company and Georgia-Pacific LLC represent North American scale advantages through captive substrate production. Smurfit Kappa Group PLC exemplifies European pan-regional logistics network leverage. Novolex occupies a position among technology-differentiated specialists competing on film-to-fiber bonding capabilities.
| Leading Market Players |
|---|
| International Paper Company |
| WestRock Company |
| Smurfit Kappa Group PLC |
| Uline |
| Novolex |
| Georgia-Pacific LLC |
| OJI Holding Corporation |
| DS Smith Plc |
| Hood Packaging Corporation |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between FDA 21 CFR-validated thermal substrates and commodity kraft constructions manifests in both margin structures and supply chain tiering, with premium laminations commanding dedicated metallized film production lines while standard grades flow through fragmented converter networks.
Pricing Analysis
Capacity additions in the Yangtze River Delta are reshaping price floors for thermal-grade kraft substrates. Three-tier pricing structure across premium, standard, and economy levels separates SAMR GB-validated pharmaceutical formats from quick-service restaurant specifications and generic retail stock. Price differentiation hinges on thermal resistance certification and captive pulp integration. Pricing pressure stems from North American softwood pulp futures volatility. Quick-service franchise operators show lowest price sensitivity due to corporate sustainability scorecard mandates, while regional retail converters face acute margin compression.
Supply Chain Analysis
Single-source vulnerability sits with North American metallized film production for embossed air-gap kraft-foil-kraft constructions. Supply concentrates in the United States, Germany, and China for thermal-grade substrate manufacturing. Raw material dependencies include softwood pulp, aluminum foil interlayers, and water-based adhesive systems. Tariff exposure on Chinese foil imports threatens converter margin stability. Distribution runs through pan-regional logistics networks anchored by Smurfit Kappa in Europe and International Paper in North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. Quick-service restaurant chains are consolidating procurement around premium thermal resistance specifications above 1.5 m²·K/W.
For Market Incumbents: Acquire captive metallized film production capacity to defend against substrate traceability mandates from Yum! Brands and Domino's Pizza operators. Secure water-based adhesive lamination lines ahead of ECHA-registered REACH compliance deadlines. Backward integration into North American pulp supply insulates margin pressure from futures volatility. For New Entrants and Emerging Players: Begin with FSSAI food-contact approval pathways in Maharashtra and Karnataka corridors, where undeveloped certification infrastructure creates first-mover positioning. Target pharmaceutical last-mile distribution in China requiring SAMR GB-validated custom dimensional tolerance. Lead with silicone-based barrier treatments replacing phased-out PFAS coatings. For Investors and Strategic Acquirers: Consolidation pressure builds where procurement desks compress supplier rosters to three approved vendors per geography. Long-term viability favors converters with dual FDA-EU certification capabilities and captive substrate supply. Watch for PFAS phase-out acceleration in Netherlands and Denmark as inflection signal for barrier treatment reformulation demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Metallized Film Production | Yum! Brands mandates direct mill relationships for thermal substrate traceability verification. |
| Water-Based Adhesive System Conversion | ECHA-registered REACH restrictions eliminate solvent-based bonding for EU food-contact compliance. |
| Pharmaceutical Cold-Chain Validation Investment | SAMR GB standards now explicitly cover composite paper-foil formats for biologics distribution. |
| Biodegradable Paper Certification Acquisition | ASTM D6400-certified compostable constructions command California and New York premium positioning. |
| Pan-European Logistics Network Expansion | Germany's KBA-adjacent environmental offices enforce stricter sorting rules than Italian or Spanish agencies. |
Research Methodology
Multiple input streams — converter production data, quick-service procurement specifications, and regulatory filing databases — were reconciled across primary interviews with thermal substrate plant managers, FDA regulatory affairs leads, quick-service chain procurement directors, and lamination equipment specialists. Secondary validation drew from EU Packaging and Packaging Waste Directive enforcement records, SAMR GB standard documentation, North American softwood pulp futures exchanges, and SEC 10-K disclosures from integrated paper producers. Bottom-up volume modeling triangulated against top-down market sizing.
Data-stream reconciliation anchored forecast outputs across the projection horizon. Segmentation dimensions modeled include product format geometry, end-use temperature requirement, material barrier specification, and regional regulatory cluster. CAGRs were derived from trajectory fitting against historical volume elasticities and policy-mandated substitution timelines. Industry-specific inputs incorporated EU Single-Use Plastics Directive enforcement schedules and quick-service cold-chain delivery radius expansion rates.
Several conditions sit outside the modeled scope, including abrupt pulp supply disruptions, unilateral national recycling rule fragmentation, and breakthrough plastic-alternative technologies. Forecasts reflect documented assumptions about regulatory enforcement consistency and franchise procurement consolidation timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Honeycomb Mailers Market
Paper & Paperboard Packaging
Europe Paper Cone Market
Paper & Paperboard Packaging
Release Paper Market
Paper & Paperboard Packaging
Food Wrapping Paper Market
Paper & Paperboard Packaging
UAE Corrugated Board Packaging Market
Paper & Paperboard Packaging
Cold Seal Paper Market
Paper & Paperboard Packaging
Asia Pacific Paper Packaging Market
Paper & Paperboard Packaging
Commercial Paper Bags Market
Paper & Paperboard Packaging
Impregnated Paper Market
Paper & Paperboard Packaging
Paperboard Packaging Market
Paper & Paperboard Packaging
SCK Paper Market
Paper & Paperboard Packaging
Stationery Films Packaging Market
Paper & Paperboard Packaging
United States Corrugated Packaging Market
Paper & Paperboard Packaging
Aluminum Foil Laminated Paper Market
Paper & Paperboard Packaging
Indonesia Paper Packaging Market
Paper & Paperboard Packaging
Paper Release Liners Market