
 Eosinophilia Therapeutics Market | 2026-2036
Eosinophilia Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Eosinophilia Therapeutics Market Foresight
Project finance and milestone-based partnership structures is rewriting competitive entry in eosinophilia therapeutics, lowering capital barriers for mid-stage developers. Sanofi leverages its established Dupixent infrastructure to anchor biologic distribution across academic medical centers. Takeda Pharmaceutical Company Limited sustains deep R&D investment in eosinophil-driven gastrointestinal indications. AstraZeneca competes through respiratory-specialist channel control and pulmonology-focused medical affairs teams.
Eosinophilia therapeutics encompass pharmaceutical interventions targeting elevated eosinophil counts, including monoclonal antibodies that bind interleukin-5 or its receptor, small-molecule inhibitors of eosinophil chemotaxis, and corticosteroid regimens that suppress eosinophilopoiesis, with biologics commanding the highest development investment due to their precision mechanism and durable response rates. The biologics segment leads value generation as IL-5 and IL-4/IL-13 pathway inhibitors capture severe asthma and hypereosinophilic syndrome indications with premium pricing and chronic administration profiles. Monoclonal antibodies represent the fastest-expanding category, driven by subcutaneous delivery innovations and label expansions into nasal polyposis and eosinophilic esophagitis. Corticosteroids remain the volume backbone for acute exacerbation management despite long-term toxicity limitations that constrain margin expansion.
FDA orphan drug designation and EMA PRIME eligibility are compressing development timelines for eosinophil-targeted therapies, while Japan's PMDA sakigake framework accelerates priority review for biologics addressing unmet needs in hypereosinophilic syndrome. These regulatory pathways shape demand by determining which therapies gain accelerated access and favorable reimbursement positioning in major markets. Stakeholders must monitor evolving biosimilar entry timelines and payer contracting dynamics for IL-5 inhibitors as patent cliffs approach for first-generation biologics.
Market Dynamics
Hospital-based site-of-care consolidation is compressing distribution pathways for biologic therapies, concentrating purchasing power within academic medical centers and specialty infusion networks. Payer preference for consolidated administration sites now dictates formulary positioning and rebate negotiations across major markets.
Growth Catalysts
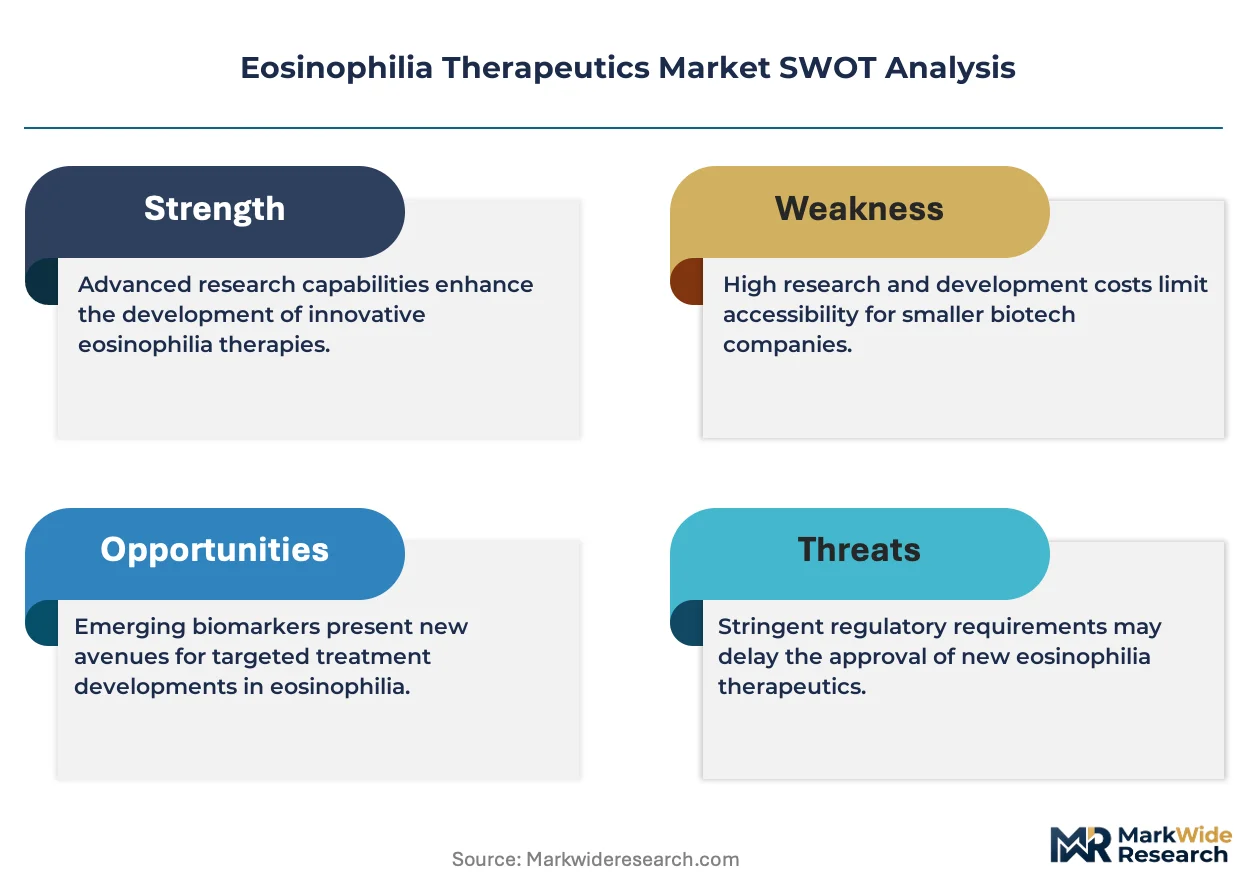
- FDA Orphan Drug Incentives:Tax credits and extended exclusivity timelines accelerate development of eosinophil-targeting therapies for hypereosinophilic syndrome. Developers prioritize rare disease indications to compress regulatory review periods.
- Subcutaneous Delivery Innovation:Self-administration platforms reduce reliance on infusion centers and expand addressable patient populations. Home-based biologic administration improves adherence metrics and reduces healthcare system costs.
- Japan PMDA Sakigake Framework:Priority review designation for biologics addressing unmet needs accelerates commercial launch timelines. Japanese reimbursement density supports premium pricing for innovative eosinophil modulators.
Market Restraints
- Cold Chain Infrastructure Requirements:Temperature-controlled logistics for biologic therapies impose distribution cost premiums. Limited specialized transportation capacity constrains market expansion into emerging regions.
- Biosimilar Entry Timelines:Patent cliff approaches for first-generation IL-5 inhibitors threaten originator revenue streams. Payer contracting dynamics favor lower-cost alternatives once interchangeability designations arrive.
- EMA PRIME Eligibility Bottlenecks:Accelerated assessment pathways create manufacturing scale-up pressures. Developers struggle to align commercial supply with compressed approval timelines.
Strategic Opportunities
- Eosinophilic Esophagitis Indication Expansion:Gastroenterology represents an underpenetrated specialty channel for IL-4/IL-13 pathway inhibitors. Label expansion into pediatric populations extends market exclusivity periods.
- Digital Therapeutic Adjuvants:Remote patient monitoring platforms integrated with biologic regimens improve real-world evidence collection. Payers increasingly reimburse technology-enabled adherence programs.
- Germany AMNOG Early Benefit Assessment:Structured price negotiation pathways provide predictable reimbursement for innovative therapies. Positive benefit ratings unlock rapid uptake within statutory health insurance.
Industry Challenges
- Specialized Immunology Talent Scarcity:Clinical development teams with eosinophil biology expertise command compensation premiums. Recruitment bottlenecks delay trial initiation and regulatory submission timelines.
- Multi-Site Manufacturing Qualification:Biosimilar competition forces capacity expansion across geographically distributed facilities. FDA and EMA inspection backlogs extend facility approval timelines.
- Legacy Corticosteroid Switching Friction:Long-established prescribing patterns in primary care resist biologic adoption. Physician education investments required to overcome therapeutic inertia.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Eosinophilia Therapeutics Market |
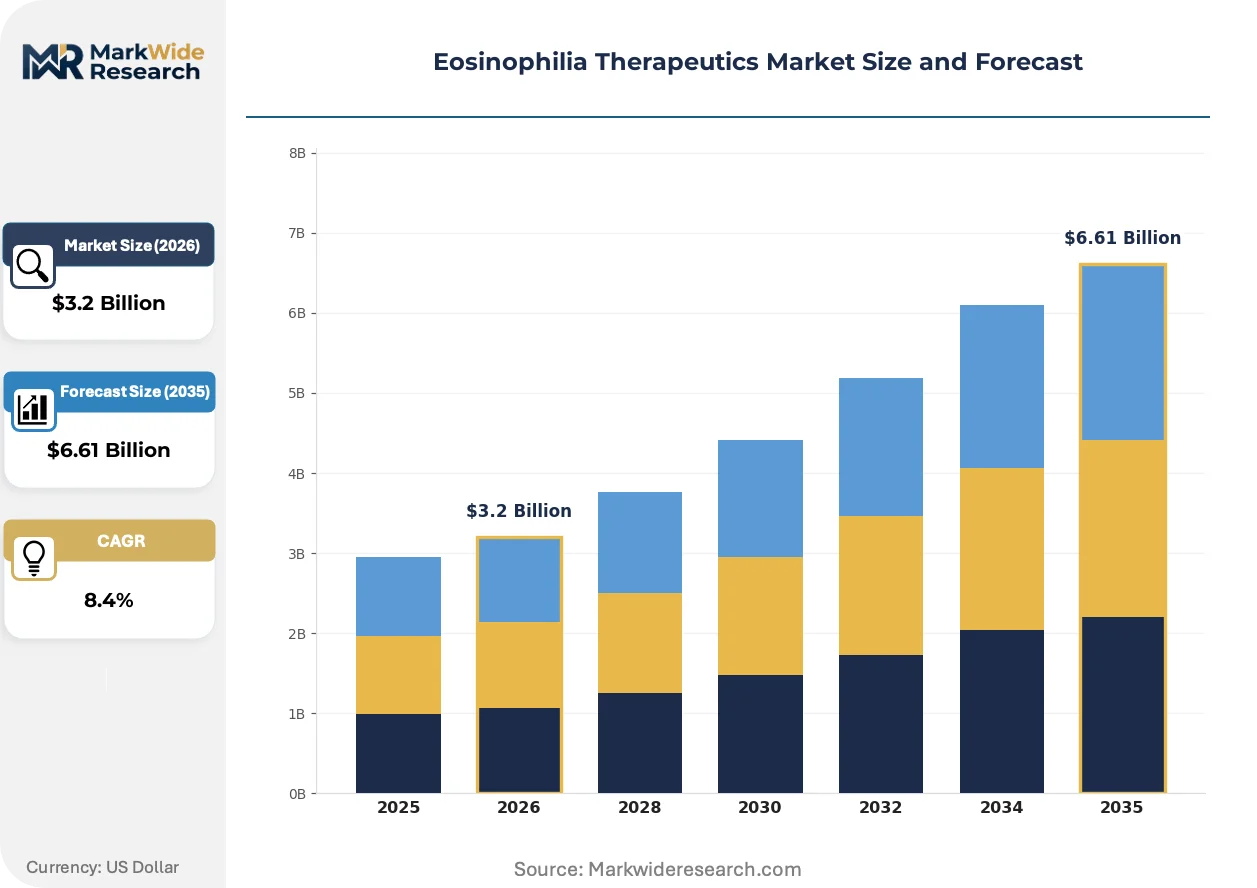
| Market Size in 2026 | $3.2 Billion |
| Market Size in 2035 | $6.61 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biologics, Small Molecules, Monoclonal Antibodies, Corticosteroids Therapy Area: Allergic Disorders, Autoimmune Diseases, Respiratory Illnesses, Neoplastic Conditions End User: Hospitals, Clinics, Research Institutions, Homecare Settings Administration Route: Oral, Injectable, Intravenous, Inhalation |
| Companies Covered | Sanofi, Takeda Pharmaceutical Company Limited, AstraZeneca, GSK plc, Regeneron Pharmaceuticals, Ellodi Pharmaceuticals, Bristol-Myers Squibb Company, Allakos Inc, Teva Pharmaceutical Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Eosinophilia Therapeutics Market Shifts & Advancements
Precision targeting of eosinophil lineage commitment is collapsing traditional therapeutic categories, blurring boundaries between respiratory, dermatologic, and gastrointestinal indications. Innovators now compete on pathway selectivity rather than anatomical specialization.
Subcutaneous anti-IL-5 receptor antagonists are collapsing the distinction between hospital-based infusion and home self-administration. Severe asthma patients and hypereosinophilic syndrome cohorts adopt pen-injector formats at accelerating velocity. Site-of-care economics favor therapies eliminating nursing supervision requirements.
EMA's PRIME eligibility criteria now explicitly reward biomarker-stratified trial designs for eosinophil-driven conditions. Developers incorporating blood eosinophil count thresholds into enrollment protocols secure accelerated assessment timelines. Respiratory biologics with predefined responder populations dominate centralized EU reimbursement negotiations.
Pulmonology practices increasingly unbundle diagnostic testing from therapeutic dispensing. Academic medical centers in the United States consolidate biologic purchasing through specialty pharmacy carve-outs. Germany's statutory health insurance funds drive this consolidation through reference pricing mechanisms for site-neutral drug administration.
Eosinophilia Therapeutics Market Segmentation
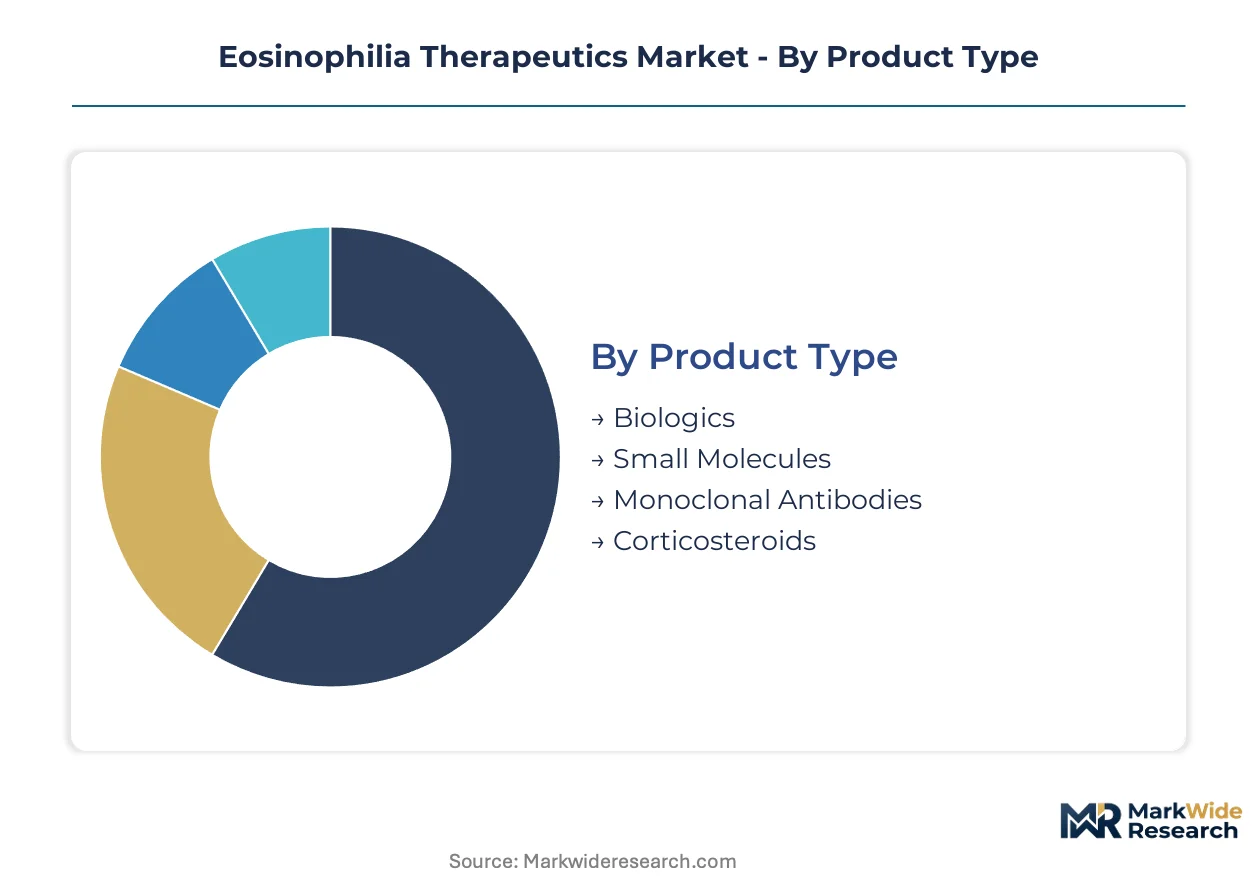
Eosinophilia therapeutics segmentation reveals divergent commercial trajectories across molecular platforms and care settings. Product type stratification separates premium biologics from commoditized corticosteroids, while administration route determines site-of-care economics and patient adherence profiles.
Product Type:
Mature corticosteroid infrastructure coexists with emerging biologic platforms, creating a dual-speed market with distinct margin and volume characteristics.
- Biologics:Recombinant protein therapeutics targeting IL-5, IL-4, and IL-13 cytokine pathways with precision mechanism. United States academic medical centers concentrate demand for these therapies, driven by FDA orphan drug incentives that compress development timelines and extend exclusivity periods. Hospital-based infusion networks favor biologics for their durable response rates in severe asthma and hypereosinophilic syndrome.
- Monoclonal Antibodies:Engineered immunoglobulins with high binding affinity for eosinophil surface markers or signaling molecules. Subcutaneous pen-injector formats from developers like Sanofi and AstraZeneca are displacing intravenous administration, expanding addressable populations into homecare settings where self-administration improves adherence metrics.
- Small Molecules:Synthetic compounds modulating eosinophil chemotaxis and survival signaling with oral bioavailability.
- Corticosteroids:Systemic and inhaled glucocorticoid regimens suppressing eosinophilopoiesis through broad immunosuppression.
Corticosteroids retain volume leadership; monoclonal antibodies hold the steepest expansion curve.
Therapy Area:
Application concentration varies sharply by disease prevalence, diagnostic infrastructure, and specialist referral density across major markets.
- Respiratory Illnesses:Severe eosinophilic asthma and chronic rhinosinusitis with nasal polyposis dominate prescription volumes. Germany's statutory health insurance funds drive rapid uptake through AMNOG early benefit assessments, while Japan's pulmonology specialist networks concentrate biologic adoption in urban academic centers.
- Allergic Disorders:Atopic dermatitis and allergic rhinitis with eosinophil-driven inflammation represent expanding indications. Dupilumab and similar IL-4/IL-13 pathway inhibitors from Sanofi and Regeneron capture demand in United States dermatology practices, where biomarker-stratified prescribing is standard.
- Autoimmune Diseases:Eosinophilic granulomatosis with polyangiitis and related vasculitides requiring immunomodulation.
- Neoplastic Conditions:Hypereosinophilic syndrome and eosinophilic leukemias with clonal eosinophil proliferation.
Respiratory illnesses command the largest revenue pool; allergic disorders are climbing the fastest in patient numbers.
End User:
Customer type segmentation reflects site-of-care consolidation trends and reimbursement mechanics that favor institutional purchasing power.
- Hospitals:Academic medical centers and specialty infusion networks administer intravenous biologics under close monitoring. United States payers increasingly mandate hospital-based administration for high-cost therapies, consolidating purchasing volume within integrated delivery networks that extract favorable rebate terms.
- Homecare Settings:Self-administration platforms for subcutaneous therapies reduce systemic costs and improve quality-of-life metrics. Japanese reimbursement policy explicitly supports home nursing for biologic injection, accelerating patient migration from clinic-based care.
- Clinics:Community pulmonology and allergy practices managing stable patients on maintenance therapy.
- Research Institutions:Academic centers conducting investigator-initiated trials and real-world evidence generation.
Hospitals retain volume leadership; homecare settings hold the steepest expansion curve.
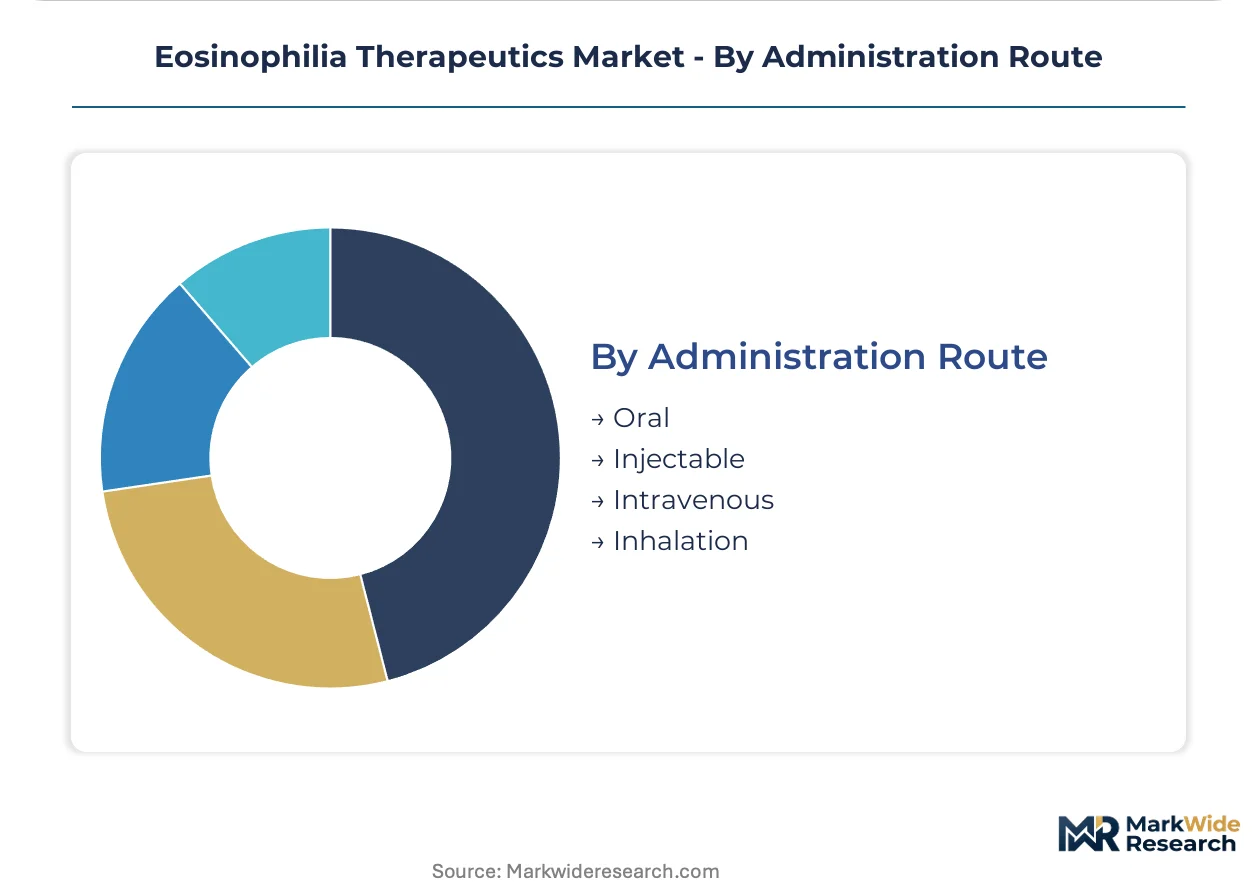
Administration Route:
Delivery modality determines cold chain requirements, nursing supervision needs, and patient autonomy in chronic disease management.
- Injectable:Subcutaneous pen devices and pre-filled syringes enable self-administration without professional supervision. AstraZeneca's Fasenra and GSK's Nucala compete on injection frequency and device ergonomics, with United States formulary committees weighing total cost of administration.
- Intravenous:Hospital-based infusion of biologics requiring temperature-controlled logistics and nursing oversight. Germany's reference pricing for site-neutral drug administration pressures manufacturers to demonstrate outcome advantages over subcutaneous alternatives.
- Oral:Small-molecule corticosteroids and emerging kinase inhibitors with patient-friendly dosing.
- Inhalation:Topical corticosteroid delivery for respiratory eosinophilia with localized action.
Intravenous retains volume leadership; injectable holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA orphan drug incentives and Japan's PMDA sakigake framework are accelerating biologic approvals across major markets. Germany's AMNOG pathway provides predictable reimbursement for innovative eosinophil-targeting therapies.
United States
Academic medical centers in Boston, New York, and California concentrate biologic administration volume as payers mandate hospital-based site-of-care for high-cost therapies. FDA orphan drug designation compresses development timelines for hypereosinophilic syndrome indications. The Research Triangle and Greater Boston clusters anchor clinical trial infrastructure for IL-5 pathway inhibitors.
Germany
Statutory health insurance funds drive rapid uptake of respiratory biologics through AMNOG early benefit assessments that unlock favorable reimbursement. EMA PRIME eligibility accelerates centralized EU approval timelines for biomarker-stratified trials. The Rhine-Ruhr and Bavarian medical clusters concentrate specialist pulmonology referral networks.
Japan
PMDA's sakigake priority review designation accelerates commercial launches for biologics addressing unmet needs in eosinophilic esophagitis. Reimbursement density under universal health coverage supports premium pricing for innovative monoclonal antibodies. Tokyo and Osaka academic centers concentrate biologic prescribing among respiratory and gastroenterology specialists.
United Kingdom
NICE technology appraisals determine formulary access for IL-4/IL-13 pathway inhibitors in severe asthma and atopic dermatitis. The NHS England specialized commissioning framework concentrates biologic distribution within designated tertiary centers. London, Manchester, and Birmingham hospital networks dominate eosinophilia therapeutic administration.
Switzerland
Swissmedic's accelerated assessment pathways align with EMA timelines for orphan-designated eosinophil-targeting therapies. Premium pricing acceptance within mandatory health insurance supports innovative biologic launches. Basel and Zurich pharmaceutical clusters anchor European headquarters for major developers in this therapeutic class.
Eosinophilia Therapeutics Market Competitive Landscape
Channel-controlling players compete with product-specialist players across academic medical center networks and specialty infusion sites. The market exhibits tiered consolidation with established respiratory biologic developers holding formulary advantages and mid-stage developers pursuing indication-specific differentiation. Three archetypes dominate: large-cap pharmaceutical companies with existing immunology infrastructure, emerging biotechs with precision pathway assets, and generic manufacturers preparing biosimilar entry. Competitive moves center on label expansion into gastrointestinal indications and subcutaneous delivery format development.
Within the large-cap tier, Sanofi, AstraZeneca, and GSK plc exemplify channel-controlling players leveraging established pulmonology and allergy specialist relationships. Sanofi anchors the competitive set through its Dupixent infrastructure across academic medical centers. AstraZeneca occupies a position emphasizing respiratory-specialist medical affairs and pulmonology-focused distribution. GSK plc sits within the same tier with existing IL-5 inhibitor market presence. These three represent the dominant competitive anchors as patent cliffs approach for first-generation biologics and biosimilar competition intensifies.
| Leading Market Players |
|---|
| Sanofi |
| Takeda Pharmaceutical Company Limited |
| AstraZeneca |
| GSK plc |
| Regeneron Pharmaceuticals |
| Ellodi Pharmaceuticals |
| Bristol-Myers Squibb Company |
| Allakos Inc |
| Teva Pharmaceutical Industries |
| Others |
Supply & Pricing Matrix
Single-source dependency on temperature-controlled logistics networks determines both biologic pricing tier spreads and supply chain configuration in eosinophilia therapeutics. Cold chain infrastructure bottlenecks compress margin structures for subcutaneous delivery formats while concentrating distribution power within integrated hospital systems.
Pricing Analysis
Regulatory designation tier creates the primary spread between orphan-designated biologics and standard-of-care corticosteroids. Pricing stratifies across premium IL-5 pathway inhibitors, mid-tier IL-4/IL-13 modulators, and economy corticosteroid regimens. Cost compression in the corticosteroid tier intensifies because of biosimilar preparation and formulary exclusion pressures. Community pulmonology practices exhibit highest price sensitivity; academic medical centers with carve-out pharmacy arrangements demonstrate lowest sensitivity due to rebate capture mechanisms.
Supply Chain Analysis
Export-control restrictions on recombinant protein manufacturing technology limit capacity expansion into emerging production jurisdictions. Active pharmaceutical ingredient synthesis concentrates in Switzerland, Ireland, and Singapore, with fill-finish operations anchored in Germany and the United States. Supply chain risk rests on single-source vulnerability for monoclonal antibody cell line development. Distribution runs through specialty pharmacy networks integrated with academic medical center purchasing consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized immunology talent scarcity constrains pipeline velocity, with clinical development teams possessing eosinophil biology expertise commanding compensation premiums that compress R&D budgets across the competitive set.
For Market Incumbents: Harden manufacturing network resilience through multi-site qualification across geographically distributed facilities to preempt FDA and EMA inspection backlogs. Deepen channel control within academic medical center specialty pharmacy carve-outs to defend against biosimilar entry pressure. Prioritize subcutaneous pen-injector format development to capture site-of-care economics favoring home administration.
For New Entrants and Emerging Players: Pursue eosinophilic esophagitis indication expansion as the most penetrable specialty channel, where gastroenterology prescribing remains underdeveloped relative to respiratory and dermatology saturation. Target pediatric population label extensions to extend market exclusivity periods. Deploy digital therapeutic adjuvant bundling as the primary go-to-market angle to differentiate from established biologic-only competitors.
For Investors and Strategic Acquirers: The market sits at a consolidation-preparation phase that favors precision-pathway asset accumulation ahead of patent cliff impacts. Long-term viability hinges on pipeline depth across IL-5, IL-4, and IL-13 pathway diversification rather than single-molecule dependency. Target acquisition archetypes include emerging biotechs with biomarker-stratified trial designs and EMA PRIME eligibility. Watch PMDA sakigake designation velocity as the inflection signal indicating regulatory pathway efficiency for portfolio prioritization.
| Strategic Initiative | Industry Significance |
|---|---|
| Orphan Drug Designation Pursuit | FDA tax credits and extended exclusivity compress development timelines for hypereosinophilic syndrome indications. |
| Subcutaneous Delivery Format Development | Self-administration platforms from AstraZeneca and Sanofi expand addressable populations beyond infusion center constraints. |
| Gastroenterology Label Expansion | Eosinophilic esophagitis indication broadens prescriber base into underpenetrated specialty channels. |
| Digital Therapeutic Adjuvant Integration | Remote patient monitoring platforms improve real-world evidence collection for payer reimbursement negotiations. |
| Multi-Site Manufacturing Qualification | Geographically distributed facilities mitigate biosimilar competition pressures and regulatory inspection bottlenecks. |
Research Methodology
A spread of perspectives from drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers converged on the working assumptions underlying this analysis. Primary interviews with payer access specialists and biologic distribution channel partners were cross-referenced against FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital procurement databases. Bottom-up patient-flow modeling and top-down revenue triangulation validated segmentation splits across therapy areas and administration routes.
Demand-supply balance dynamics anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include molecular platform, therapy area, administration route, patient population severity tier, and regional regulatory cluster. CAGRs were derived from patient volume trajectories and pricing elasticity assumptions calibrated to formulary access patterns. Forecast inputs incorporated biosimilar entry timeline scenarios and site-of-care consolidation velocity.
Sensitivities concentrate around biosimilar interchangeability designations and cold chain logistics cost trajectories. Forecasts reflect assumptions on regulatory pathway efficiency and payer contracting dynamics. Material shifts in FDA orphan drug incentive structures or EMA PRIME eligibility criteria would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Global Occupational Medicines Market
Specialty Medicine
Piriformis Syndrome Treatment Market
Specialty Medicine
Autism Spectrum Disorder Management Market
Specialty Medicine
Middle East and Africa Kidney Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Carcinoid Syndrome Management Market
Specialty Medicine
Chromoblastomycosis Treatment Market
Specialty Medicine
Tularemia Therapeutics Market
Specialty Medicine
Nephrogenic Systemic Fibrosis (NSF) Treatment Market
Specialty Medicine
Global Hammertoe Market
Specialty Medicine
Impetigo Therapeutic Market
Specialty Medicine
Global Primary Immunodeficiency Therapeutics Market
Specialty Medicine
Narcolepsy Market
Specialty Medicine
Frontotemporal Dementia Management Market
Specialty Medicine
Global Spinal Muscular Atrophy Treatment Market
Specialty Medicine
Seasonal Allergy Market
Specialty Medicine
Bipolar Disorder Therapeutics Market