
 HER2 Positive Gastric Cancer Market | 2026-2036
HER2 Positive Gastric Cancer Market Size, Share, and Industry Trends Forecast 2026-2036
HER2 Positive Gastric Cancer Market Foresight
GCP certification for clinical investigators is rotating as the decisive qualification gating which sponsors and contract research organizations can execute pivotal HER2 gastric cancer trials. AstraZeneca leverages its antibody-drug conjugate portfolio to sustain leadership in targeted therapy development. Bristol-Myers Squibb anchors its position through immuno-oncology combinations that integrate HER2 blockade with checkpoint inhibition. Pfizer competes on manufacturing scale and global distribution reach for established monoclonal antibody supply.
HER2 positive gastric cancer denotes adenocarcinoma of the stomach or gastroesophageal junction exhibiting HER2 protein overexpression or gene amplification, typically assessed via immunohistochemistry scoring of 3+ or fluorescence in situ hybridization positivity, treated with biologic agents that disrupt receptor-mediated signaling and induce antibody-dependent cellular cytotoxicity. Monoclonal antibodies occupy the largest revenue share as the backbone of approved frontline regimens, while combination treatments represent the fastest-expanding segment as developers stack HER2 inhibition with chemotherapy and immunotherapy to overcome resistance mechanisms. Intravenous administration dominates current delivery, though subcutaneous formulations are gaining development priority for outpatient clinic adoption.
FDA accelerated approval designations and EMA conditional marketing authorizations shape development economics by enabling earlier revenue recognition based on surrogate endpoints, while China's NMPA priority review channels compress regulatory timelines for domestic and multinational sponsors. The EU AI Act and GDPR impose compliance burdens on diagnostic algorithms used for HER2 scoring in digital pathology workflows. Stakeholders must monitor biomarker testing standardization and payer evidence requirements as the field shifts toward personalized combination sequencing.
Market Dynamics
FDA accelerated approval pathways and EMA conditional marketing authorizations are compressing development timelines for HER2-directed therapies, while biomarker testing standardization struggles to keep pace with expanding eligible patient populations across oncology departments.
Growth Catalysts
- Accelerated regulatory pathways:FDA breakthrough therapy designations and EMA priority medicines status enable earlier commercialization based on surrogate endpoints, reducing time-to-revenue for novel antibody-drug conjugates.
- Biomarker testing infrastructure:Immunohistochemistry and fluorescence in situ hybridization platform expansion in United States, China, and Japan tertiary care centers is identifying treatment-eligible patients at earlier disease stages.
- Combination therapy protocols:HER2 blockade integration with checkpoint inhibitors and cytotoxic chemotherapy is extending progression-free survival in frontline gastric adenocarcinoma management.
Market Restraints
- Diagnostic access inequality:HER2 testing penetration remains concentrated in urban academic medical centers, leaving community oncology practices in India and Southeast Asia with limited molecular profiling capacity.
- Biosimilar competition timing:Patent expirations for established monoclonal antibodies are attracting multiple biosimilar developers, threatening originator pricing power before next-generation modalities achieve market dominance.
- Reimbursement evidence thresholds:Payers in Germany and France are tightening health technology assessment criteria, demanding real-world evidence beyond registrational trial data for combination regimen coverage.
Strategic Opportunities
- Subcutaneous formulation development:Outpatient administration convenience is driving investment in subcutaneous delivery systems that reduce infusion center burden and expand community clinic access.
- China's NMPA priority review channels:Domestic and multinational sponsors are leveraging accelerated timelines to bridge development gaps between Western and Chinese market entry dates.
- Digital pathology integration:Artificial intelligence-assisted HER2 scoring algorithms are reducing inter-pathologist variability and enabling decentralized diagnostic quality assurance.
Industry Challenges
- GCP investigator certification scarcity:Qualified principal investigators capable of executing pivotal gastric cancer trials are concentrated in a limited network of academic research organizations, creating site activation bottlenecks.
- Combination regimen complexity:Sequencing multiple biologic agents with chemotherapy requires sophisticated pharmacy infrastructure and nursing protocols that strain resource-constrained treatment centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | HER2 Positive Gastric Cancer Market |
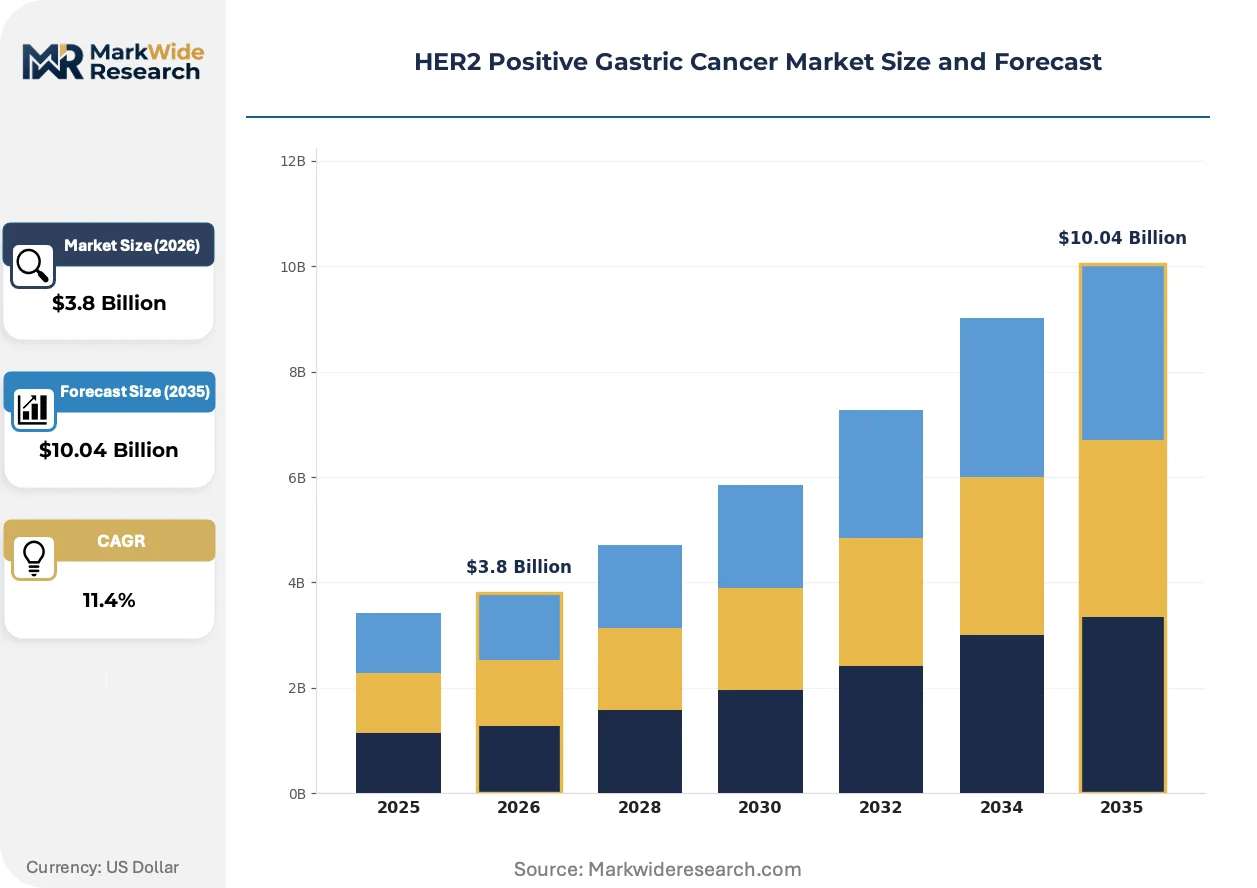
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Targeted Therapies, Chemotherapy, Combination Treatments End User: Hospitals, Cancer Research Institutes, Outpatient Clinics, Specialty Treatment Centers Treatment Setting: Adjuvant, Neoadjuvant, Palliative Care, Advanced Stage Administration Route: Intravenous, Oral, Subcutaneous, Intramuscular |
| Companies Covered | AstraZeneca, Bayer, Bristol-Myers Squibb, Ono Pharmaceutical, Hutchison Medipharma, LintonPharm, Shanghai Henlius Biotech, Sanofi, Pfizer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
HER2 Positive Gastric Cancer Market Shifts & Advancements
Antibody-drug conjugate engineering is advancing payload potency and linker stability, while diagnostic workflows integrate artificial intelligence to standardize biomarker interpretation across distributed pathology networks.
Next-generation antibody-drug conjugates with cleavable linkers and membrane-permeable payloads are bifurcating the therapeutic landscape. Oncology departments at Mayo Clinic and Memorial Sloan Kettering are prioritizing these constructs for patient populations with acquired resistance to first-generation HER2 blockade. This technology is bifurcating clinical trial enrollment criteria and forcing sponsors to stratify protocols by prior exposure history.
EU AI Act classification rules for medical device software are imposing conformity assessment requirements on automated HER2 scoring algorithms. Digital pathology vendors must now demonstrate algorithmic transparency and bias mitigation to maintain CE marking validity. European reference laboratories are responding by consolidating vendor relationships and demanding ISO 13485 certification from artificial intelligence diagnostic partners.
Hospital procurement committees are unbundling diagnostic testing from therapeutic purchasing, creating separate contracting streams for biomarker assays and biologic agents. Integrated delivery networks in Texas and California are negotiating multi-year molecular diagnostics agreements independent of pharmaceutical formularies. This structural separation is most pronounced in United States academic medical centers with captive pathology operations.
HER2 Positive Gastric Cancer Market Segmentation
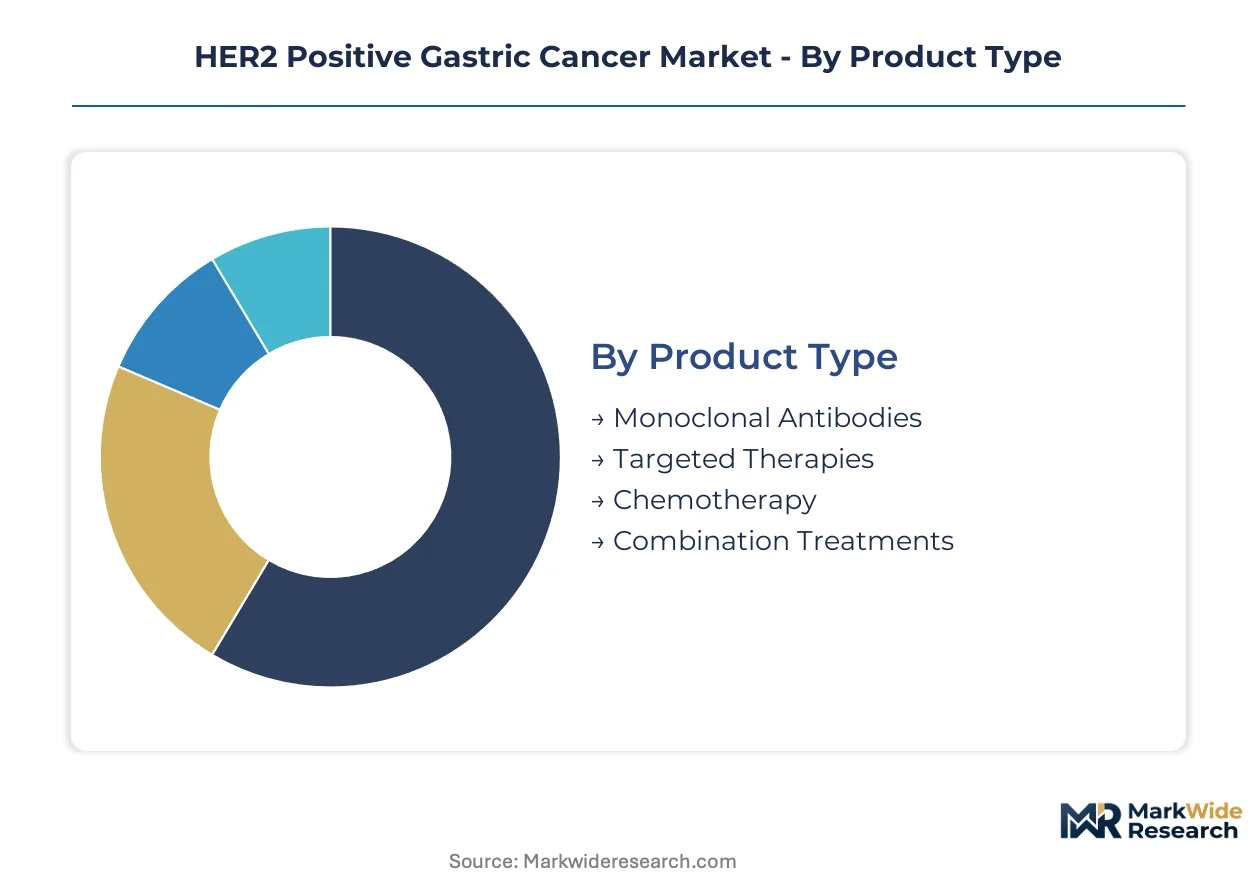
Segmentation in the HER2 positive gastric cancer market reveals how therapeutic innovation, care delivery infrastructure, and patient disease staging create distinct commercial battlegrounds. Each dimension shapes procurement patterns, regulatory requirements, and prescriber behavior differently across United States, Chinese, and Japanese hospital systems.
Product Type:
Domestic manufacturing concentration varies sharply by modality, with monoclonal antibody production anchored in United States and European biologics facilities while combination treatments draw active pharmaceutical ingredients from Chinese and Indian contract manufacturers.
- Monoclonal Antibodies:These biologic agents bind HER2 extracellular domains to block receptor dimerization and trigger antibody-dependent cellular cytotoxicity. Demand concentrates in tertiary academic medical centers across the United States, Japan, and Germany where infusion infrastructure and reimbursement pathways are mature. Manufacturing scale and cold-chain logistics requirements limit production to established biopharmaceutical hubs.
- Combination Treatments:Regimens stack HER2-directed therapy with checkpoint inhibitors and cytotoxic chemotherapy to overcome resistance mechanisms. United States oncology departments at Mayo Clinic and Memorial Sloan Kettering are driving protocol adoption fastest, though European payers are tightening health technology assessment criteria for coverage.
- Targeted Therapies:Small molecule tyrosine kinase inhibitors and antibody-drug conjugates with cleavable linkers are advancing through FDA breakthrough therapy and EMA priority medicines pathways.
- Chemotherapy:Platinum-fluoropyrimidine backbones remain standard-of-care components in first-line regimens, with generic competition compressing pricing power in European markets.
Monoclonal antibodies hold the largest share; momentum sits with combination treatments.
End User:
Procurement authority and reimbursement complexity stratify across facility types, with hospitals commanding volume-based purchasing power while specialty treatment centers negotiate value-based contracts for complex combination protocols.
- Hospitals:Integrated delivery networks and academic medical centers manage the majority of HER2 positive gastric cancer cases through inpatient oncology units and infusion centers. United States hospital systems in Texas and California are unbundling diagnostic testing from therapeutic purchasing, creating separate contracting streams that alter vendor relationships.
- Specialty Treatment Centers:Focused gastric cancer programs at centers like MD Anderson and Dana-Farber attract referral patterns for resistant or recurrent disease, driving demand for next-generation antibody-drug conjugates and clinical trial enrollment.
- Cancer Research Institutes:Principal investigator networks at these sites execute pivotal trials, though GCP certification scarcity concentrates qualified sites in limited academic research organizations.
- Outpatient Clinics:Community oncology practices are gaining capacity for subcutaneous formulation administration, expanding access beyond urban academic centers.
Hospitals dominate volume; specialty treatment centers are expanding most quickly as complex combination protocols concentrate expertise.
Treatment Setting:
Regulatory approval pathways and evidence requirements differ substantially by disease stage, with adjuvant and neoadjuvant settings demanding larger randomized trials and longer follow-up than advanced-stage accelerated approvals.
- Advanced Stage:Metastatic or unresectable disease represents the initial regulatory approval pathway for most HER2-directed therapies, with FDA accelerated approval and EMA conditional marketing authorization enabling earlier commercialization based on surrogate endpoints.
- Neoadjuvant:Preoperative therapy to downstage tumors and improve surgical outcomes is gaining trial investment, particularly in Japanese and South Korean centers with high gastric cancer surgical volumes.
- Adjuvant:Post-surgical therapy to eliminate micrometastatic disease requires prolonged disease-free survival data that extends development timelines and regulatory review periods.
- Palliative Care:Symptom-focused management in end-stage disease emphasizes quality-of-life endpoints and oral formulation convenience for home administration.
Advanced stage holds the largest share; neoadjuvant applications are climbing the fastest as perioperative strategies reshape surgical oncology protocols.
Administration Route:
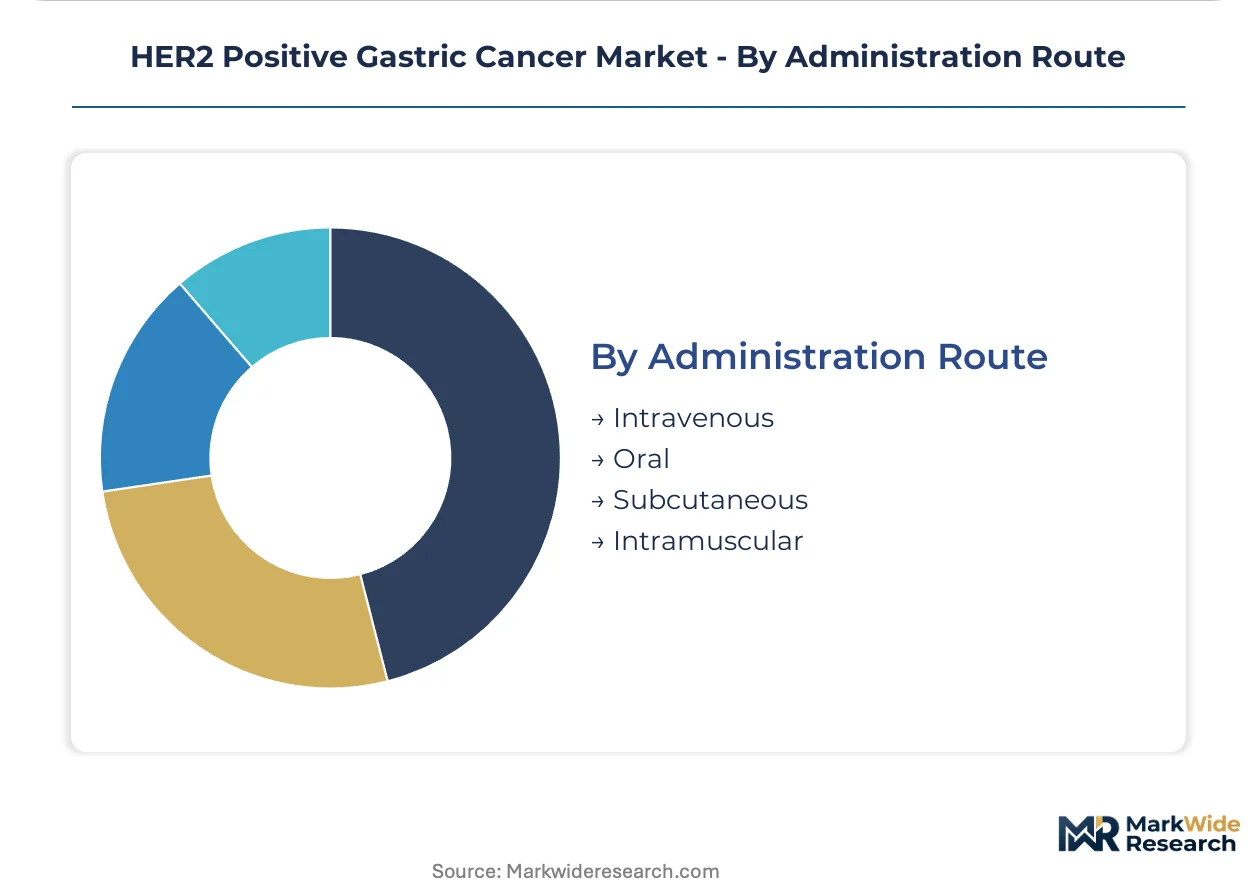
Formulation development priorities reflect pressure to reduce infusion center burden and enable community clinic expansion, with subcutaneous delivery systems attracting the majority of new product investment.
- Intravenous:Infusion-based delivery dominates current administration, requiring specialized nursing protocols and pharmacy infrastructure that concentrates treatment at academic medical centers.
- Subcutaneous:Outpatient administration convenience is driving development priority for formulations that reduce chair time and enable decentralized care delivery in United States community oncology networks.
- Oral:Small molecule tyrosine kinase inhibitors offer home administration flexibility, though bioavailability and adherence monitoring challenges limit adoption in combination regimens.
- Intramuscular:Depot formulations for sustained release remain experimental in HER2-directed therapy, with limited clinical trial activity relative to other routes.
Intravenous administration holds the largest share; subcutaneous formulations are gaining share fastest as outpatient convenience becomes a competitive differentiator.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Oncology procurement committees in United States academic medical centers, Chinese tertiary hospitals, and Japanese cancer institutes concentrate the majority of HER2 testing and treatment demand. These buyer archetypes command volume-based purchasing power and shape regional competitive dynamics.
United States
Mayo Clinic and Memorial Sloan Kettering drive adoption of next-generation antibody-drug conjugates for resistant disease populations. FDA breakthrough therapy designations compress development timelines for novel modalities. Texas and California integrated delivery networks are unbundling diagnostic testing from therapeutic purchasing, creating separate contracting streams that alter vendor negotiations.
China
NMPA priority review channels attract domestic and multinational sponsors seeking accelerated market entry timelines. Shanghai Henlius Biotech and Hutchison Medipharma anchor local development of biosimilars and novel biologics. Yangtze River Delta tertiary care centers are expanding immunohistochemistry platform capacity to identify treatment-eligible patients at earlier disease stages.
Japan
PMDA sakigake designation system enables earlier commercialization for innovative HER2-directed therapies. Tokyo and Osaka metropolitan cancer centers concentrate surgical oncology expertise and perioperative protocol development. Japanese hospital systems are investing in subcutaneous formulation infrastructure to reduce infusion center burden.
Germany
G-BA health technology assessment criteria are tightening evidence requirements for combination regimen reimbursement, demanding real-world data beyond registrational trials. Bavaria and North Rhine-Westphalia academic medical centers maintain strong principal investigator networks for pivotal gastric cancer studies. German pathology laboratories are consolidating vendor relationships under EU AI Act compliance pressures.
South Korea
MFDS fast-track review pathways support accelerated approval for antibody-drug conjugates with demonstrated efficacy in HER2-positive populations. Seoul National University Hospital and Samsung Medical Center drive neoadjuvant protocol adoption with high surgical volumes for gastric adenocarcinoma. Korean biotechnology clusters are expanding contract manufacturing capacity for linker-payload technologies.
HER2 Positive Gastric Cancer Market Competitive Landscape
Player mix skews toward multinational pharmaceutical conglomerates with established oncology portfolios and emerging biotechnology specialists with targeted therapy platforms. The competitive structure consolidates around three archetypes: antibody-drug conjugate innovators leveraging payload engineering, immuno-oncology integrators combining checkpoint inhibition with HER2 blockade, and biosimilar developers targeting patent-expired monoclonal antibodies. Dominant competitive moves include strategic partnerships for diagnostic co-development and geographic expansion through NMPA priority review channel utilization.
Within the multinational pharmaceutical tier, AstraZeneca and Bristol-Myers Squibb occupy positions as archetype anchors for targeted therapy and immuno-oncology integration respectively. AstraZeneca represents the antibody-drug conjugate engineering approach with its portfolio focus on linker-payload optimization. Bristol-Myers Squibb exemplifies the checkpoint inhibitor combination strategy. Among China-based biotechnology developers, Shanghai Henlius Biotech sits within the emerging specialist tier pursuing accelerated domestic regulatory pathways. Pfizer anchors the manufacturing scale archetype with global distribution infrastructure for established monoclonal antibody supply.
| Leading Market Players |
|---|
| AstraZeneca |
| Bayer |
| Bristol-Myers Squibb |
| Ono Pharmaceutical |
| Hutchison Medipharma |
| LintonPharm |
| Shanghai Henlius Biotech |
| Sanofi |
| Pfizer |
| Others |
Supply & Pricing Matrix
Sixty-to-ninety-day cold-chain logistics lead times for antibody-drug conjugates concentrate pricing power with United States and European biologics manufacturers possessing validated GMP infrastructure, while Asian contract manufacturers compete on linker-payload chemistry cost structures.
Pricing Analysis
Cost-plus contracts with active pharmaceutical ingredient indexation dominate biologic procurement between hospital systems and originator manufacturers. Price differentiation hinges on FDA breakthrough therapy designation status and GMP certification tier, with originator monoclonal antibodies commanding premium positioning against emerging biosimilar entrants. Pricing pressure stems from patent cliff timing for established HER2 blockers as multiple biosimilar developers file abbreviated biologics license applications. Community oncology practices exhibit highest price sensitivity due to reimbursement lag and infusion center overhead constraints.
Supply Chain Analysis
Inbound logistics costs through Shanghai and Rotterdam port corridors fluctuate with container availability for temperature-controlled biologics transport. Manufacturing concentrates in United States, Ireland, and Singapore biologics facilities for fill-finish operations, while linker-payload chemistry draws from Chinese and South Korean contract manufacturers. Supply chain risk centers on single-source dependencies for cytotoxin payloads used in antibody-drug conjugate engineering. Distribution runs through specialty pharmacy networks and hospital-based infusion centers with captive procurement committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive-moat structure where regulatory entrenchment through FDA accelerated approval and EMA conditional marketing authorization creates sticky incumbent positions that resist rapid displacement.
For Market Incumbents: Fortify diagnostic co-development partnerships to lock in biomarker testing workflows ahead of biosimilar entry. Secure principal investigator networks through exclusive site agreements, as GCP-certified gastric cancer trial capacity concentrates in limited academic research organizations. Deepen backward integration into linker-payload manufacturing to defend margin position against contract manufacturer pricing leverage. For New Entrants and Emerging Players: Subcutaneous formulation administration gaps in United States community oncology networks offer white-space entry points where incumbents under-serve outpatient clinic infrastructure. Target neoadjuvant protocol development in Japanese and South Korean surgical centers with high gastric adenocarcinoma resection volumes. Pursue NMPA priority review channel partnerships to compress China market entry timelines relative to Western regulatory sequences. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across antibody-drug conjugate manufacturing infrastructure as multi-product facilities require dedicated containment suites for cytotoxic payload handling. Five-to-ten year viability favors developers with integrated diagnostic-therapeutic platforms and established payer access pathways. Signal to monitor: EU AI Act compliance certification attainment by digital pathology vendors as a proxy for diagnostic workflow consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Diagnostic-Therapeutic Co-Development | Lock-in effects with hospital pathology laboratories reduce biosimilar switching probability. |
| Subcutaneous Formulation Advancement | Mayo Clinic and Memorial Sloan Kettering prioritize outpatient administration convenience for patient retention. |
| NMPA Priority Review Channel Utilization | Shanghai Henlius Biotech and Hutchison Medipharma leverage accelerated timelines to bridge Western-China entry gaps. |
| Principal Investigator Network Consolidation | GCP certification scarcity concentrates qualified gastric cancer trial sites in limited academic research organizations. |
| EU AI Act Compliance Certification | Digital pathology vendors must demonstrate algorithmic transparency to maintain CE marking validity for HER2 scoring. |
Research Methodology
A standing panel of drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists provided ongoing calibration across primary interview cycles. Secondary validation drew from FDA filings, EMA submissions, ClinicalTrials.gov protocols, and formulary database audits. Bottom-up patient-flow modeling and top-down pharmaceutical revenue triangulation anchored market size estimation.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions included treatment line, administration route, biomarker testing platform, and regional regulatory cluster. CAGRs derived from patient incidence projections, therapy penetration curves, and pricing trajectory assumptions with antibody-drug conjugate adoption rates and biosimilar entry timing as key forecast inputs.
Forecasts assume regulatory continuity in FDA accelerated approval and EMA conditional marketing authorization frameworks; material policy shifts would require re-modeling. Diagnostic reimbursement stability and biomarker testing penetration trajectories underpin patient identification assumptions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Bronchiectasis Therapeutic Market
Specialty Medicine
Spinal and Bulbar Muscular Atrophy Treatment Market
Specialty Medicine
Retroperitoneal Fibrosis Treatment Market
Specialty Medicine
Complex Regional Pain Syndrome (CRPS) Market
Specialty Medicine
Tropical Spastic Paraparesis Market
Specialty Medicine
Adrenogenital Syndrome Treatment Market
Specialty Medicine
Chromoblastomycosis Treatment Market
Specialty Medicine
Balantidiasis Treatment Market
Specialty Medicine
Vitiligo Treatment Market
Specialty Medicine
Latin America Bladder Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Chemotherapy Induced Thrombocytopenia Market
Specialty Medicine
Global Cough Hypersensitivity Syndrome Treatment Market
Specialty Medicine
Gouty Arthritis Market
Specialty Medicine
Stress Urinary Incontinence Market
Specialty Medicine
Partial Onset Seizures Market
Specialty Medicine
Ovarian Cysts Market