
 Global Occupational Medicines Market | 2026-2036
Global Occupational Medicines Market Size, Share, and Industry Trends Forecast 2026-2036
Global Occupational Medicines Market Foresight
The EU Green Deal's occupational health sustainability benchmarks is recalibrating employer procurement criteria across European manufacturing. Concentra anchors its network scale through employer-facing clinic placement near logistics corridors. Sonic Healthcare leverages laboratory infrastructure to extend diagnostic reach into workplace screening contracts. Medcor differentiates through on-site clinical staffing models that reduce employer lost-time metrics.
Occupational medicines comprise pharmaceuticals and biologics formulated for work-acquired conditions, including sustained-release analgesics with 12-24 hour half-lives for repetitive-strain injuries and adjuvanted vaccines against bloodborne pathogen exposure in healthcare settings. Their primary purpose centers on restoring worker functional capacity while meeting employer liability mitigation requirements. Workplace Safety applications dominate volume through regulatory-mandated injury protocols, while Disease Management segments capture margin pools from chronic condition monitoring in aging industrial workforces. Oral delivery modes sustain the largest share through patient compliance advantages, though injection formats lead growth in vaccination and biologic therapy categories.
OSHA in the United States, EU-OSHA across Europe, and ISO 45001 standards collectively shape product registration pathways, employer compliance thresholds, and clinical service accreditation requirements that determine market access. China's NMPA and Germany's BfArM impose additional pharmacovigilance obligations on workplace-administered therapeutics that elevate documentation costs for cross-border suppliers. Stakeholders must monitor regulatory divergence between preventive service mandates and pharmaceutical reimbursement classifications as employers assume greater direct payment responsibility for workforce health outcomes.
Market Dynamics
Employer direct payment responsibility for workforce health outcomes is compressing traditional pharmaceutical reimbursement pathways while elevating preventive service procurement. This structural shift forces suppliers to reconfigure around occupational health service contracts rather than product-centric distribution.
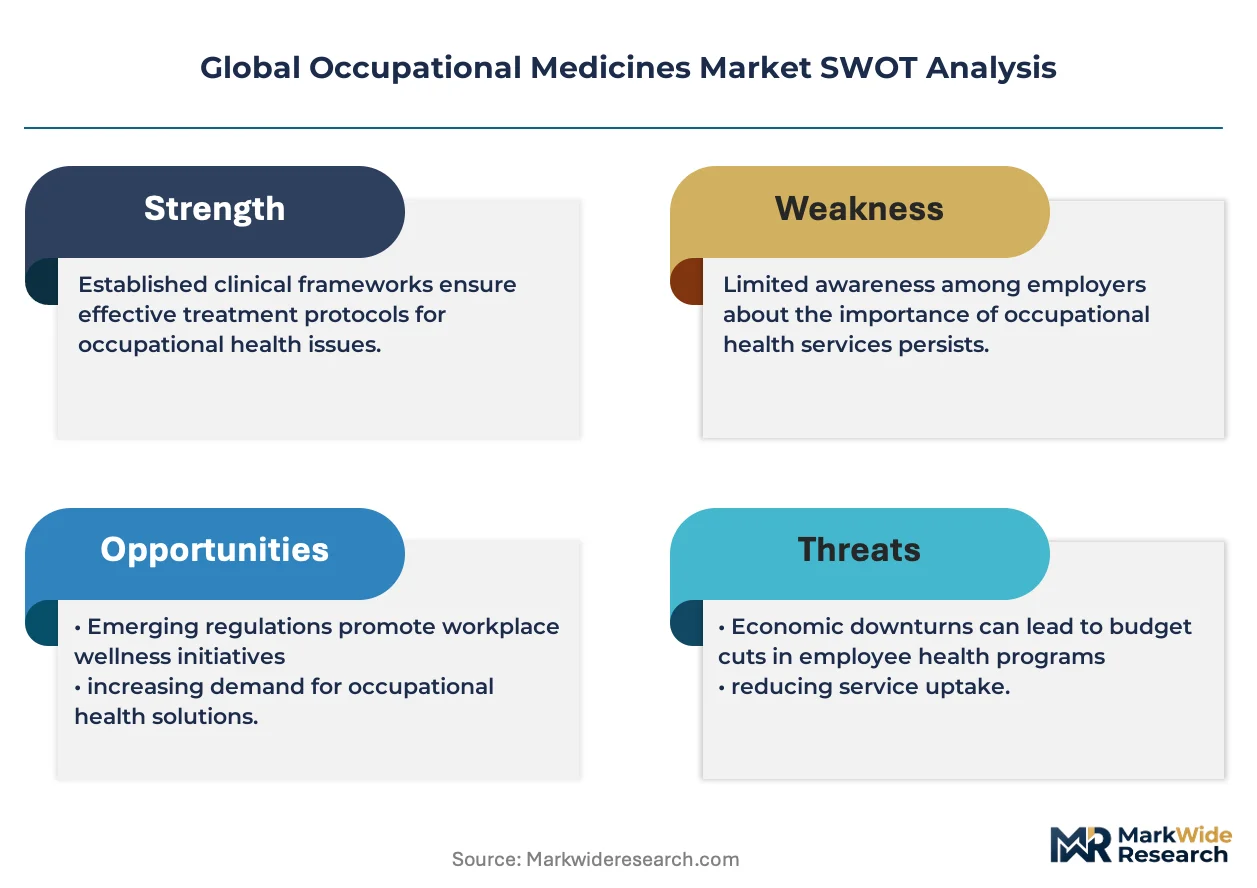
Growth Catalysts
- OSHA workplace health mandates:United States employers face tightening accountability for occupational illness prevention, expanding mandatory screening and treatment protocols across manufacturing facilities.
- EU Green Deal sustainability benchmarks:European manufacturing procurement criteria now embed occupational health sustainability metrics, redirecting supplier selection toward certified preventive service providers.
- Repetitive-strain injury pharmacology:Sustained-release analgesics with extended half-lives address chronic musculoskeletal conditions in aging industrial workforces, particularly logistics and heavy assembly operations.
Market Restraints
- Cross-border pharmacovigilance documentation:China's NMPA and Germany's BfArM impose divergent post-market surveillance obligations on workplace-administered therapeutics, elevating compliance costs for multinational suppliers.
- Input concentration in adjuvant chemistry:Bloodborne pathogen vaccine production depends on concentrated aluminum salt suppliers, creating vulnerability to raw material availability shocks.
- Biologic cold chain infrastructure gaps:Workplace vaccination programs in emerging industrial corridors lack consistent temperature-controlled distribution, limiting biologic therapy penetration.
Strategic Opportunities
- On-site clinical staffing models:Direct employer employment of occupational health personnel bypasses traditional clinic networks, capturing lost-time reduction value previously extracted by third-party providers.
- ISO 45001 certification acceleration:Employers pursuing integrated management system accreditation drive demand for bundled occupational medicine services aligned with standardized health and safety frameworks.
- Workplace diagnostic laboratory integration:Screening contract consolidation with existing laboratory infrastructure extends service reach without greenfield facility investment.
Industry Challenges
- Occupational medicine specialist scarcity:Board-certified practitioners concentrate in urban medical centers, leaving industrial corridor employers competing for limited clinical workforce.
- Legacy electronic health record incompatibility:Workplace-administered treatment documentation systems fail to interface with employer HR platforms, fragmenting health outcome tracking.
- Multi-jurisdiction licensing complexity:Mobile clinical staff serving distributed facility networks face credentialing friction across state and national boundaries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Occupational Medicines Market |
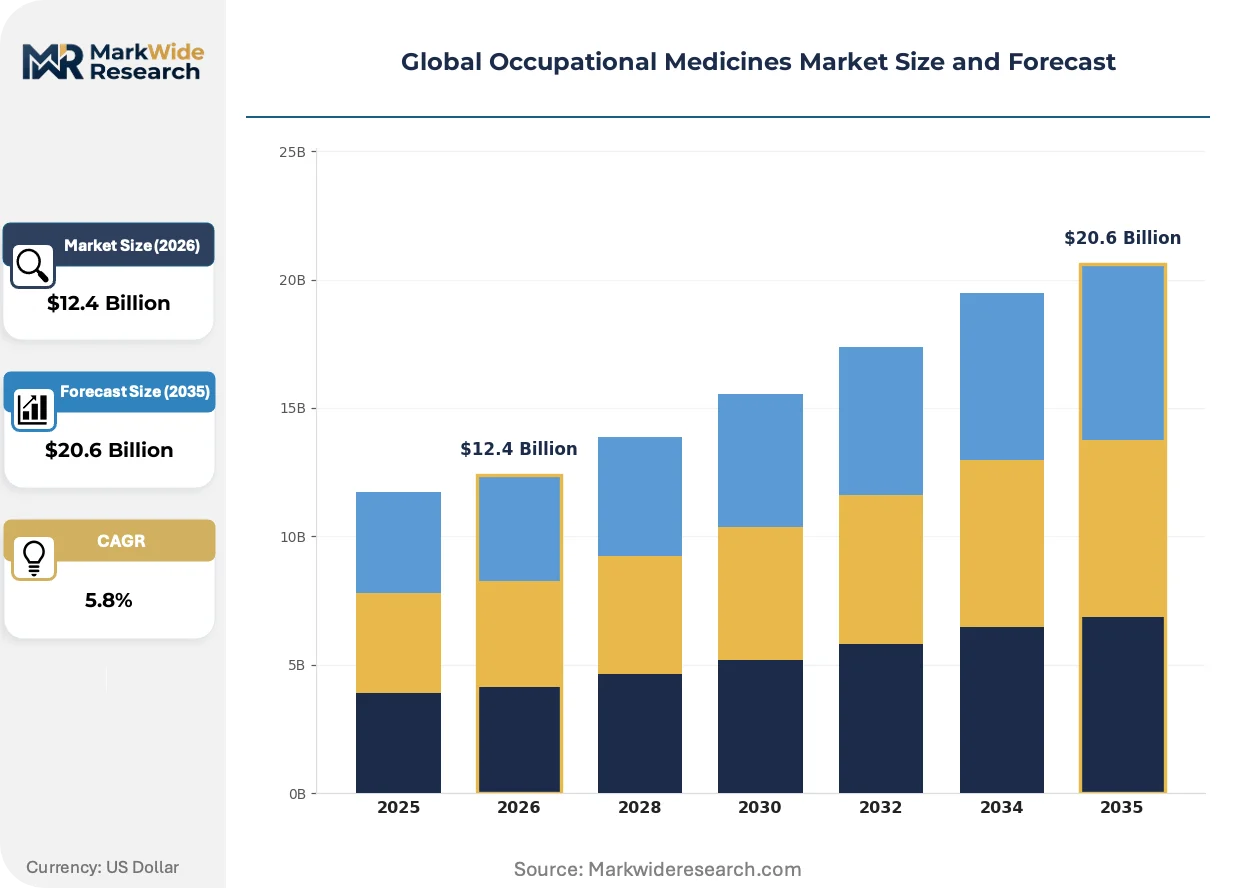
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $20.6 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analgesics, Anti-inflammatories, Vaccines, Antimicrobials End User: Hospitals, Clinics, Occupational Health Providers, Corporates Application: Workplace Safety, Disease Management, Health Screening, Emergency Response Delivery Mode: Injections, Oral, Inhalation, Transdermal |
| Companies Covered | Concentra, Occucare International, WorkCare, HealthWorks Medical, Workwell Occupational Medicine, HCA Healthcare, Medcor, Sonic Healthcare, Johnson & Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Occupational Medicines Market Shifts & Advancements
Digital biomonitoring platforms and point-of-care diagnostics are compressing the latency between exposure detection and clinical intervention. These technologies enable real-time workforce health surveillance previously constrained by periodic screening schedules.
Wearable musculoskeletal strain sensors is rewriting injury prevention protocols in repetitive-task environments. Logistics operators and automotive assembly plants deploy continuous motion-tracking devices to flag ergonomic risk before tissue damage manifests. This capability compresses the traditional reactive treatment model into preemptive biomechanical adjustment.
EU-OSHA's evolving occupational exposure limit frameworks for chemical and biological agents are tightening permissible workplace concentrations across European manufacturing. German and French regulators lead implementation, forcing reformulation of topical treatments and respiratory prophylactics. Pharmaceutical suppliers respond with accelerated stability testing to demonstrate compliance under stricter environmental condition specifications.
Employer purchasing consortia in heavy industry verticals are consolidating occupational health service contracts to extract volume pricing and standardize care protocols. This concentration displaces fragmented local clinic relationships with national managed care arrangements. The pattern is most visible in United States logistics networks, where centralized procurement functions at major distributors mandate uniform screening and treatment standards across dispersed distribution centers.
Global Occupational Medicines Market Segmentation
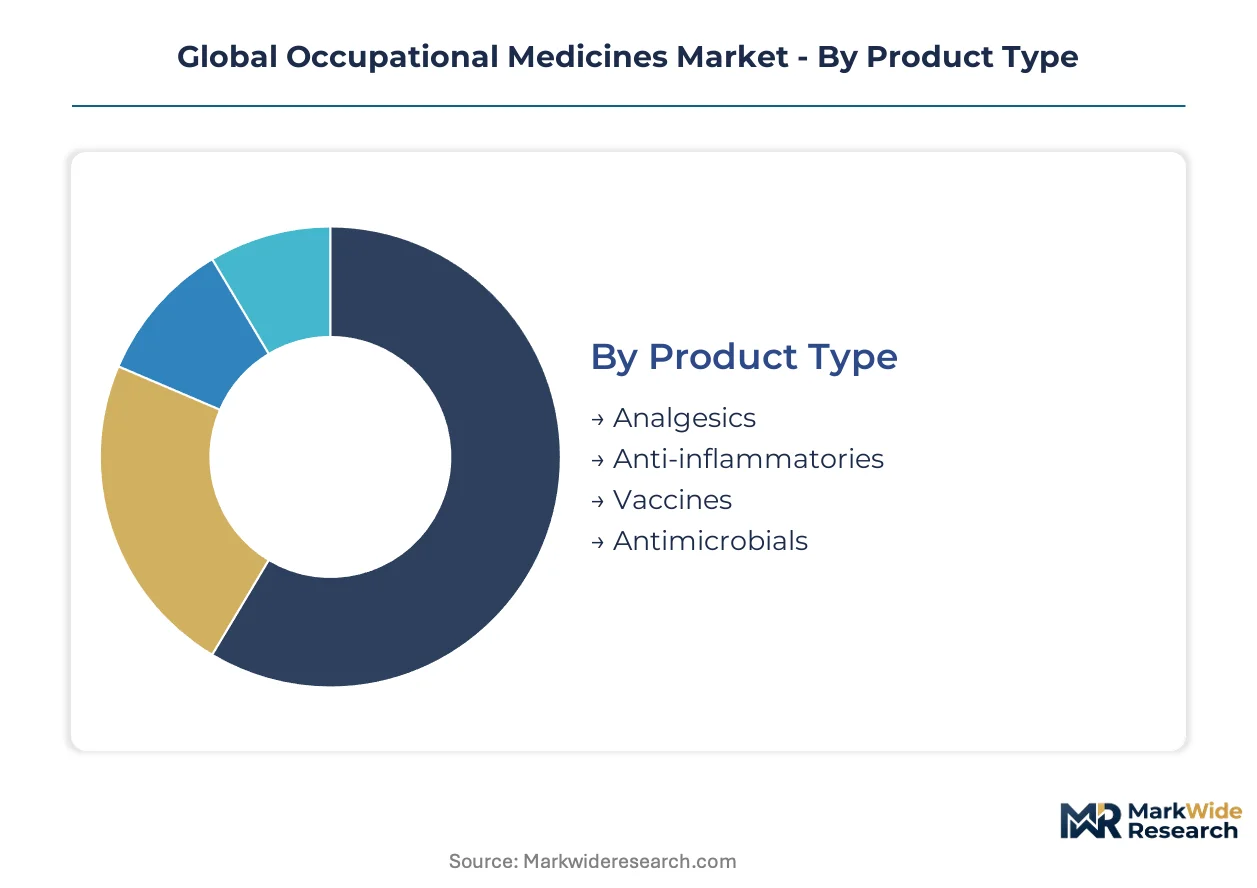
Employer procurement patterns in occupational medicines diverge sharply between regulatory-mandated safety protocols and discretionary wellness investments. Understanding these segment boundaries clarifies where pricing power concentrates versus where volume contracts dominate purchasing decisions.
Product Type:
Procurement scale and margin capture depend heavily on whether products address acute workplace injuries or chronic condition prevention.
- Analgesics:Sustained-release formulations with 12-24 hour half-lives dominate repetitive-strain injury management in logistics and heavy assembly operations. German automotive manufacturers and United States distribution centers drive demand concentration as aging workforces elevate chronic musculoskeletal condition prevalence.
- Vaccines:Adjuvanted formulations against bloodborne pathogens serve healthcare worker protection mandates under OSHA and EU-OSHA exposure protocols. Bloodborne pathogen vaccination contracts in United States hospital systems and French healthcare networks sustain volume leadership despite cold chain infrastructure gaps in emerging industrial corridors.
- Anti-inflammatories:Topical and oral NSAID formulations address acute soft-tissue injuries in manufacturing environments with high ergonomic risk profiles.
- Antimicrobials:Prophylactic and therapeutic agents target occupational skin infections and wound management in construction and agricultural worker populations.
Analgesics lead on scale; vaccines lead on momentum.
End User:
Service delivery economics shift dramatically based on whether clinical infrastructure is employer-controlled or third-party operated.
- Occupational Health Providers:Specialized clinic networks like Concentra anchor employer contracts through logistics corridor proximity and standardized screening protocols. United States manufacturing and transportation employers favor these providers for regulatory compliance documentation and centralized billing.
- Corporates:Direct employer employment of on-site clinical staff—exemplified by Medcor's staffing models—captures lost-time reduction value that previously flowed to external providers. Large-scale logistics operators in the United States and German industrial conglomerates accelerate this insourcing trend.
- Hospitals:Emergency departments and occupational medicine divisions handle severe workplace trauma and regulatory-mandated post-exposure protocols.
- Clinics:Community-based primary care facilities serve smaller employers lacking dedicated occupational health infrastructure.
Occupational health providers dominate current contract volume; corporates are expanding most quickly through direct staffing models.
Application:
Regulatory mandate intensity determines whether applications generate recurring revenue streams or episodic procurement.
- Workplace Safety:OSHA-mandated injury response protocols and EU-OSHA exposure frameworks create non-discretionary demand for immediate treatment and documentation. United States manufacturing facilities and German chemical processing plants sustain the largest safety protocol volumes.
- Disease Management:Chronic condition monitoring in aging industrial workforces captures premium margins through longitudinal care relationships. China's heavy industrial zones and United States logistics hubs concentrate demand as workforce demographics shift.
- Health Screening:Pre-employment and periodic medical examinations satisfy regulatory entry and maintenance requirements.
- Emergency Response:Acute exposure and trauma interventions address immediate workplace health crises.
Workplace safety commands the largest revenue base; disease management shows the steepest expansion trajectory as workforce aging accelerates.
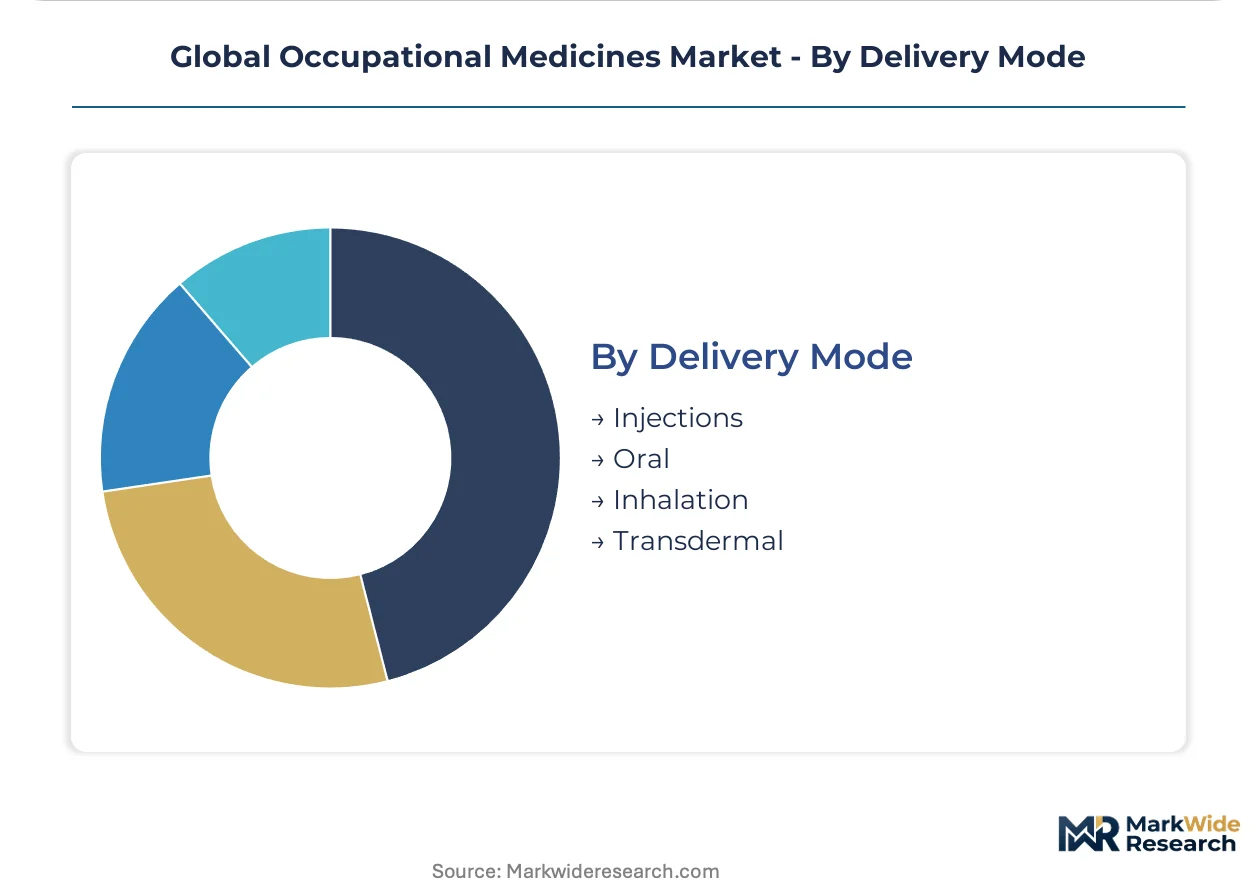
Delivery Mode:
Patient compliance requirements and biologic stability constraints create divergent infrastructure needs across administration formats.
- Oral:Tablet and capsule formulations sustain the largest volume share through patient self-administration convenience and minimal cold chain requirements. Analgesic and anti-inflammatory prescribing in United States and Chinese manufacturing facilities reinforces this dominance.
- Injections:Vaccine and biologic therapy administration leads growth categories despite distribution complexity. German healthcare networks and United States hospital systems drive injection format expansion through comprehensive bloodborne pathogen protection programs.
- Inhalation:Respiratory prophylactics address occupational asthma and chemical exposure in industrial processing environments.
- Transdermal:Sustained-release patches deliver analgesic therapy with controlled absorption profiles for chronic pain management.
Oral formats dominate current procurement volumes; injections gain share fastest through biologic therapy expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered industrial occupational health protocols during the Bismarck-era social insurance expansion, establishing workplace medicine as a formal discipline before scaling across heavy manufacturing corridors. This historical foundation shaped regulatory frameworks now replicated across industrialized economies.
United States
OSHA-mandated injury response protocols and employer liability frameworks sustain the largest national market for workplace safety pharmaceuticals. The Department of Labor enforces record-keeping standards that elevate documentation requirements for musculoskeletal treatments. Texas and California logistics hubs concentrate demand for repetitive-strain injury management as e-commerce distribution networks expand.
Germany
BfArM pharmacovigilance obligations and EU-OSHA exposure limit frameworks tighten workplace-administered therapeutic standards. The country's national pharmaceutical regulator imposes post-market surveillance documentation that elevates compliance costs for cross-border suppliers. Bavarian automotive clusters and North Rhine-Westphalia chemical processing zones anchor chronic condition monitoring contracts.
China
Aging industrial workforces in heavy manufacturing zones elevate chronic respiratory and musculoskeletal condition management needs. NMPA workplace therapeutic documentation requirements diverge from European standards, fragmenting supplier registration pathways. Yangtze River Delta electronics assembly corridors and Pearl River Delta logistics hubs concentrate preventive service procurement.
France
ANSM workplace health product oversight and EU Green Deal sustainability benchmarks recalibrate employer procurement criteria toward certified preventive providers. French regulators lead implementation of tightened occupational exposure limits for chemical agents. Île-de-France healthcare networks and Auvergne-Rhône-Alpes manufacturing clusters sustain bloodborne pathogen vaccination contract volumes.
Global Occupational Medicines Market Competitive Landscape
Capital-heavy clinic network operators compete with asset-light staffing specialists across divergent service delivery models. Market structure consolidates around three strategic tiers: national clinic chains with logistics corridor proximity, employer-direct staffing providers, and laboratory infrastructure extenders. Competitive positioning hardens through M&A consolidation of regional occupational health practices and ISO 45001 certification bundling.
Within the clinic network tier, Concentra anchors employer-facing placement strategies through standardized screening protocols. Medcor exemplifies the direct staffing archetype with on-site clinical employment models that compress lost-time metrics. Sonic Healthcare occupies a position among laboratory infrastructure extenders, leveraging diagnostic reach into workplace screening contracts without greenfield facility investment.
| Leading Market Players |
|---|
| Concentra |
| Occucare International |
| WorkCare |
| HealthWorks Medical |
| Workwell Occupational Medicine |
| HCA Healthcare |
| Medcor |
| Sonic Healthcare |
| Johnson & Johnson |
| Others |
Supply & Pricing Matrix
Captive clinic network ownership by major occupational health providers anchors supply position and pricing power across employer contract negotiations. This vertical integration into service delivery compresses third-party margin extraction while enabling volume-based rate locking with pharmaceutical distributors.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs employer procurement contracts. Certification grade under ISO 45001 and service bundling intensity drive price differentiation between tiers. Cost compression in economy-tier screening packages is intensifying because employer purchasing consortia extract volume concessions. Small manufacturing employers without dedicated procurement functions demonstrate highest price sensitivity, while integrated logistics operators with national footprints accept premium rates for lost-time reduction guarantees.
Supply Chain Analysis
Workforce availability constraints in German chemical processing zones and Chinese Yangtze River Delta manufacturing corridors shape supplier geographic placement decisions. Active pharmaceutical ingredient sourcing draws from India and China, while adjuvant chemistry for bloodborne pathogen vaccines rests on concentrated aluminum salt suppliers. Single-source vulnerability in cold chain biologics distribution elevates supply risk for workplace vaccination programs. Distribution runs through employer-direct staffing models and third-party clinic networks in parallel channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where OSHA workplace health mandates and EU-OSHA exposure frameworks generate recurring compliance-driven demand. The structural shift toward employer direct payment responsibility creates durable revenue visibility for preventive service providers.
For Market Incumbents: Deploy ISO 45001 certification bundling to lock in multi-year employer contracts before competitor accreditation spreads. Acquire regional occupational health practices in Texas and California logistics corridors to defend corridor proximity advantages against staffing-model disruptors. Deepen backward integration into diagnostic laboratory infrastructure to capture screening contract value.
For New Entrants and Emerging Players: Digital biomonitoring platforms with real-time musculoskeletal strain detection offer a technology-first wedge into repetitive-task manufacturing environments. White-space concentration sits in mid-sized German automotive suppliers lacking on-site clinical staffing. Target employer consortia in United States distribution networks with wearable sensor subscription models that bypass traditional clinic relationships.
For Investors and Strategic Acquirers: Roll-up economics work for regional occupational health practices because employer purchasing consolidation favors national contract coverage over fragmented local relationships. The five-to-ten year viability window favors platforms with integrated clinic-laboratory-staffing capabilities. Watch EU Green Deal occupational health sustainability benchmark implementation velocity as inflection indicator for European manufacturing procurement redirection.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 45001 Certification Acceleration | Employers pursuing integrated management system accreditation drive bundled service procurement aligned with standardized frameworks. |
| On-Site Clinical Staffing Expansion | Direct employer employment of occupational health personnel captures lost-time reduction value from third-party providers. |
| Diagnostic Laboratory Integration | Screening contract consolidation with existing laboratory infrastructure extends service reach without greenfield facility investment. |
| Digital Biomonitoring Platform Deployment | Wearable musculoskeletal strain sensors enable preemptive ergonomic adjustment before tissue damage manifests in repetitive-task environments. |
| Regional Occupational Health Practice Acquisition | M&A consolidation captures corridor proximity advantages and employer contract relationships in logistics-intensive geographies. |
Research Methodology
Multiple input streams — occupational health clinic operators, pharmaceutical regulatory affairs specialists, employer benefits directors, and logistics procurement managers — were reconciled against OSHA compliance documentation, EU-OSHA exposure limit frameworks, FDA workplace therapeutic filings, and hospital system GPO contract databases. Bottom-up employer spending estimates and top-down pharmaceutical shipment data were cross-validated to anchor market sizing.
Data-stream reconciliation across product type, end user, application, and delivery mode segmentation dimensions generated volume and value outputs over the projection horizon. CAGRs were derived from regression analysis of historical employer health expenditure patterns and regulatory mandate expansion timelines. Workforce aging demographics and chronic condition prevalence curves informed disease management segment trajectory modeling.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU Green Deal implementation pace and NMPA-BfArM regulatory divergence. Forecasts reflect assumptions around OSHA mandate enforcement continuity and employer liability framework stability. Material deviation in bloodborne pathogen vaccination mandate expansion or biologic cold chain infrastructure investment warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Lipoprotein Metabolism Disorders Treatment Market
Specialty Medicine
Tonsil Cancer Market
Specialty Medicine
Global Cancer Therapy Market
Specialty Medicine
Cholangiocarcinoma Market
Specialty Medicine
Hidradenitis Suppurativa (HS) Treatment Market
Specialty Medicine
Global Specialty Injectable Generics Market
Specialty Medicine
Global Non-Oncology Precision Medicine Market
Specialty Medicine
North America Precision Medicine Market
Specialty Medicine
Sex Cord-Gonadal Stromal Tumor Market
Specialty Medicine
HTLV-1 Associated Myelopathy (HAM) Market
Specialty Medicine
TIL Therapy Market
Specialty Medicine
Pituitary Stalk Interruption Syndrome Treatment Market
Specialty Medicine
Hepatic Insufficiency/Liver Failure Market
Specialty Medicine
Marfan Syndrome Treatment Market
Specialty Medicine
Global Sarcopenia Treatment Market
Specialty Medicine
Tinnitus Management Market