
 Global Post Traumatic Stress Disorder (PTSD) Therapeutics Market | 2026-2036
Global Post Traumatic Stress Disorder (PTSD) Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Post Traumatic Stress Disorder (PTSD) Therapeutics Market Foresight
Fixed-dose combination packaging of antidepressants with anxiolytics is hardening as the default outpatient configuration, reducing pill burden for chronic PTSD patients. Pfizer Inc. leverages its manufacturing scale to supply standardized combination tablets across retail pharmacy networks. Jazz Pharmaceuticals specializes in controlled-substance delivery formats that meet DEA scheduling requirements. Bionomics Ltd. competes through novel mechanism candidates targeting fear-extinction pathways.
Post Traumatic Stress Disorder therapeutics encompass pharmacological agents and psychosocial interventions designed to modulate dysregulated stress-response circuitry, including hyperactive amygdala signaling and impaired prefrontal cortical regulation. Selective serotonin reuptake inhibitors remain the first-line pharmacotherapy class, while novel psychedelic agents represent the fastest-growing product type as regulators establish clinical trial frameworks. Cognitive Behavioral Therapy anchors the therapy area segment with the most extensive reimbursement coverage, though digital therapeutics within delivery mode are capturing margin pools through scalable, software-enabled deployment.
The FDA, EMA, and WHO set divergent standards for psychiatric drug approval and post-market surveillance, with the FDA's breakthrough therapy designation creating the most rapid commercialization pathway. WHO's inclusion of PTSD in mental health priority lists shapes national formulary decisions in lower-income markets. Stakeholders must monitor how psychedelic-assisted therapy rescheduling progresses across jurisdictions, as this will determine which development pipelines achieve viable market access.
Market Dynamics
The FDA's breakthrough therapy designation for psychedelic-assisted treatments is compressing clinical trial timelines and attracting venture capital into novel mechanism research. This regulatory acceleration is redrawing competitive boundaries between established psychiatric drug portfolios and emerging biotech pipelines.
Growth Catalysts
- Telehealth Infrastructure Expansion:Military veterans in rural United States regions now access Cognitive Behavioral Therapy through VA-connected platforms, eliminating geographic barriers to specialized care.
- EMA's Priority Medicines Scheme:Accelerated assessment pathways for PTSD therapeutics in Europe are shortening time-to-market for novel anxiolytic combinations targeting fear-extinction deficits.
- Digital Therapeutics Reimbursement:Software-enabled interventions are securing CPT codes from private United States payers, creating sustainable revenue streams outside traditional pharmaceutical models.
Market Restraints
- Controlled-Substance Scheduling:DEA restrictions on MDMA and psilocybin create manufacturing quotas, distribution lockboxes, and prescriber certification requirements that inflate operational overhead.
- Specialized Psychiatric Workforce Concentration:Trauma-trained clinicians cluster in urban United States coastal corridors, leaving interior regions and lower-income markets with inadequate prescriber density.
- Placebo Response Variability:High placebo rates in PTSD trials inflate required sample sizes and extend study durations, compressing effective patent life for approved molecules.
Strategic Opportunities
- Japan's Aging Veteran Population:METI funding for mental health innovation and PMDA's acceptance of foreign trial data create expedited entry for established SSRI combinations.
- Biomarker-Guided Patient Stratification:Amygdala reactivity signatures and cortisol awakening response profiles are enabling precision matching of pharmacotherapy to neurobiological subtype.
- Employer-Sponsored Mental Health Benefits:Fortune 500 companies in the United States are expanding behavioral health carve-outs, creating direct-to-employer channels that bypass traditional pharmacy benefit managers.
Industry Challenges
- Psychedelic-Assisted Therapy Training Bottlenecks:Certification programs for therapists administering MDMA and psilocybin are producing fewer than 1,000 qualified practitioners annually against projected demand.
- Real-World Evidence Collection Infrastructure:Post-market surveillance for novel mechanisms requires patient registries and long-term outcome tracking that stretch limited pharmacovigilance resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Post Traumatic Stress Disorder (PTSD) Therapeutics Market |
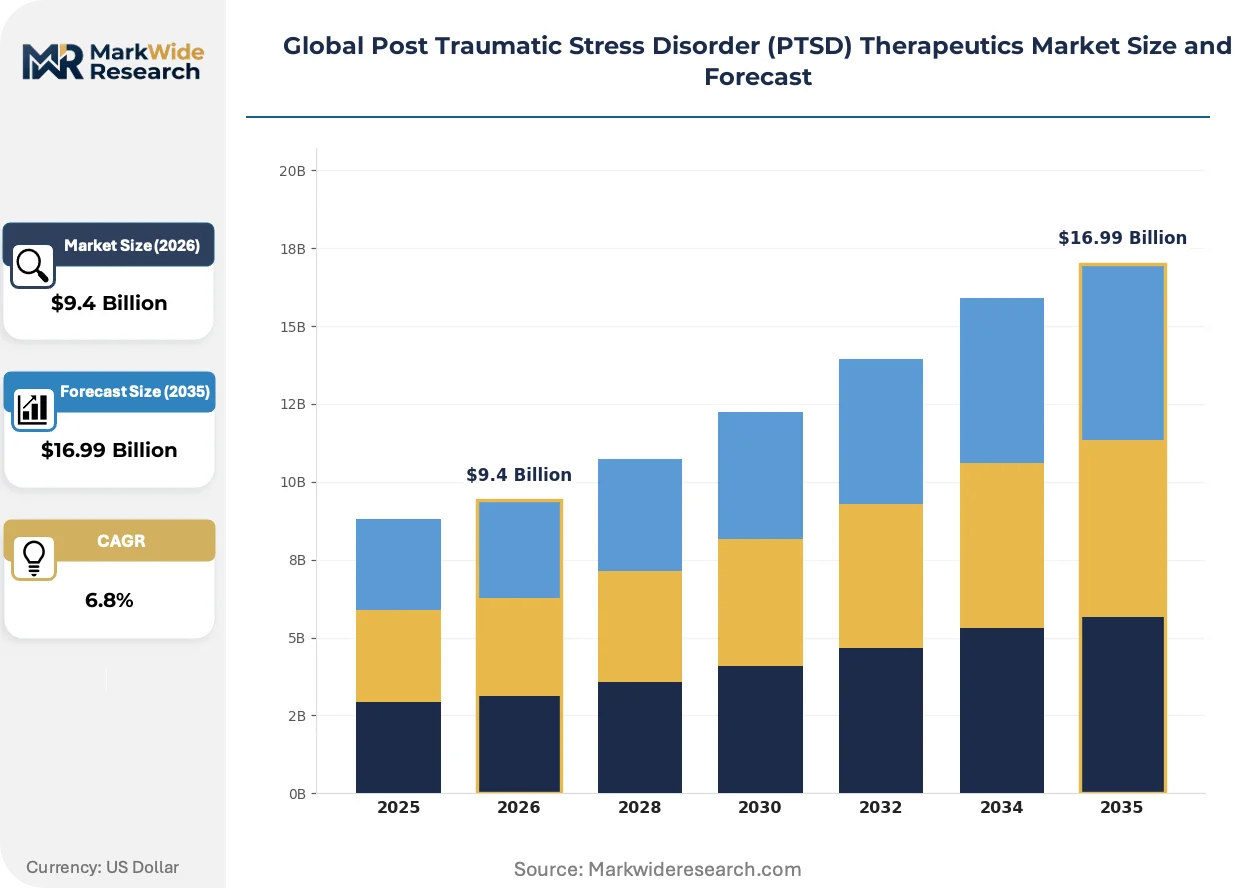
| Market Size in 2026 | $9.4 Billion |
| Market Size in 2035 | $16.99 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Therapy Area: Cognitive Behavioral Therapy, Eye Movement Desensitization, Prolonged Exposure, Psychodynamic Therapy, Group Therapy, Pharmacotherapy Product Type: Antidepressants, Anxiolytics, Beta Blockers, Alpha Agonists, Antipsychotics, Novel Psychedelic Agents End User: Military Veterans, Mental Health Clinics, Rehabilitation Centers, Psychiatric Hospitals, Outpatient Facilities, Telehealth Services Delivery Mode: Oral Tablets, Injectable Solutions, Transdermal Patches, Digital Therapeutics, Intranasal Sprays, Sublingual Films |
| Companies Covered | Pfizer Inc., GlaxoSmithKline plc., Otsuka Pharmaceutical, Jazz Pharmaceuticals, Teva Pharmaceutical Industries, AstraZeneca PLC, Aurobindo Pharma Limited, Bionomics Ltd., Aptinyx, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Post Traumatic Stress Disorder (PTSD) Therapeutics Market Shifts & Advancements
Neuroscience-driven drug discovery is converging with digital phenotyping to enable personalized PTSD treatment protocols. These advances are compressing the gap between biomarker identification and therapeutic intervention.
Psychedelic-assisted psychotherapy is integrating controlled-dosing protocols with structured therapeutic support to modulate fear-extinction learning. United States academic medical centers are establishing dedicated treatment centers at accelerating pace. This convergence is integrating psychiatric medication with psychosocial intervention into reimbursable bundled episodes of care.
REACH compliance requirements for pharmaceutical manufacturing in Europe are mandating greener synthesis routes and solvent recovery systems. EMA's environmental risk assessment guidelines now extend to active pharmaceutical ingredients in psychiatric drug classes. Manufacturers serving European markets are reformulating production processes to meet these expanded obligations.
Subscription-based mental health platforms are displacing fee-for-service psychiatric consultations among commercially insured populations in the United States. Employers and health plans are consolidating vendor relationships around integrated digital-physical care models. This consolidation is most visible in California and Texas, where large employer concentrations drive contract scale.
Global Post Traumatic Stress Disorder (PTSD) Therapeutics Market Segmentation
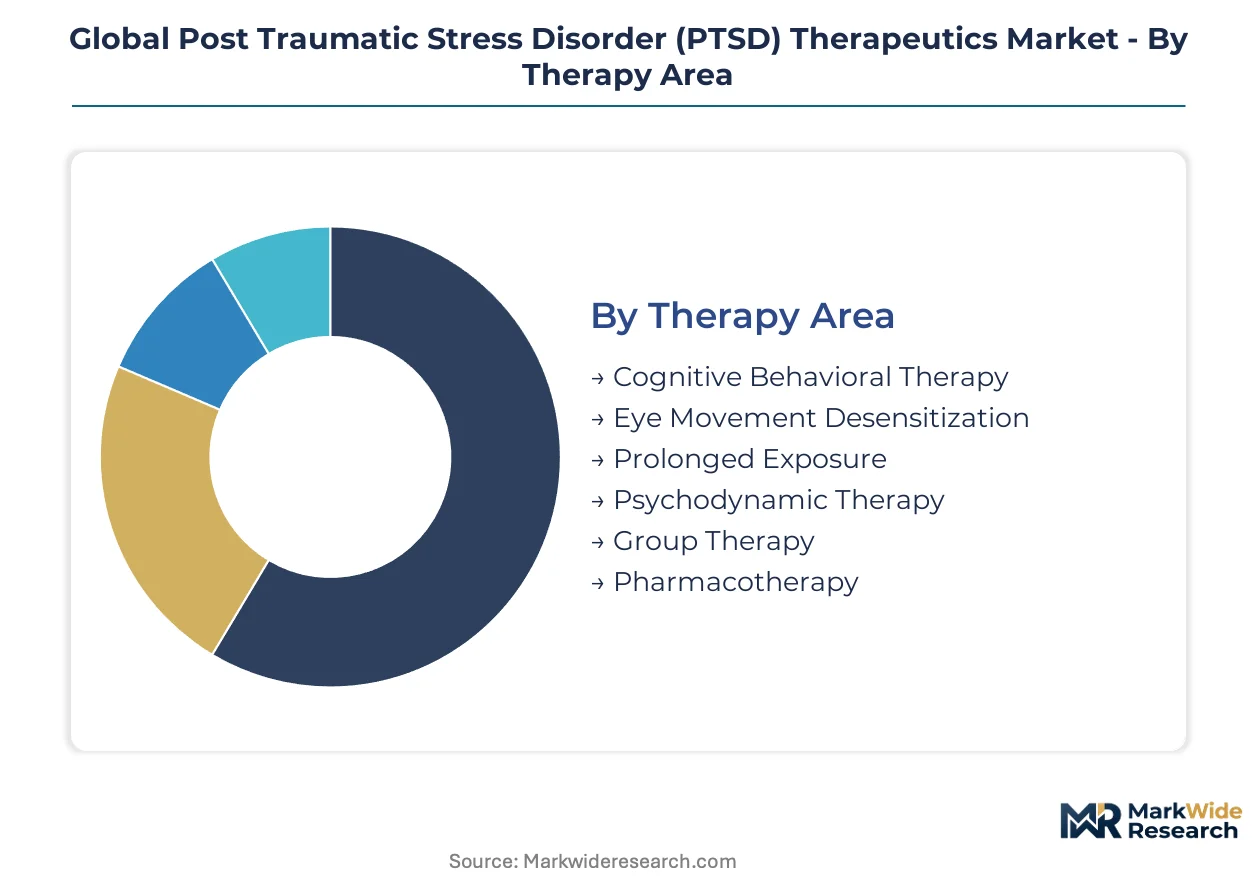
PTSD therapeutics segmentation reveals how treatment modalities layer across acute intervention, chronic management, and maintenance phases. Each dimension carries distinct reimbursement codes, prescriber certification requirements, and patient adherence profiles that shape commercial strategy.
Therapy Area:
Integration depth varies sharply: standalone protocols dominate outpatient reimbursement while embedded combinations drive psychiatric hospital throughput.
- Cognitive Behavioral Therapy:Structured protocols targeting trauma-related cognition through exposure hierarchies and cognitive restructuring. Demand clusters in United States urban corridors where VA-connected platforms and private practice networks achieve density; CPT code stability sustains margin predictability for licensed practitioners.
- Pharmacotherapy:Serotonin-modulating agents and novel mechanism candidates delivered through oral and parenteral routes. Military veterans in rural United States regions access these through telehealth-prescribed regimens; prescriber certification requirements for controlled substances create geographic access disparities.
- Eye Movement Desensitization:Bilateral stimulation protocols for trauma memory reprocessing.
- Prolonged Exposure:Graduated in-vivo and imaginal exposure hierarchies.
- Psychodynamic Therapy:Long-term interpretive approaches addressing unconscious conflict patterns.
- Group Therapy:Peer-supported trauma processing in structured cohort formats.
Volume placements concentrate in Cognitive Behavioral Therapy; the faster expansion belongs to Pharmacotherapy as novel psychedelic agents advance through regulatory pipelines.
Product Type:
Cost tier stratification separates chronic maintenance agents from breakthrough-designated candidates carrying premium pricing and restricted distribution.
- Novel Psychedelic Agents:MDMA and psilocybin formulations administered in supervised clinical settings with structured psychosocial support. FDA breakthrough therapy designation compresses development timelines; DEA scheduling creates manufacturing quotas and distribution lockbox requirements that constrain supply scaling.
- Antidepressants:Selective serotonin reuptake inhibitors and serotonin-norepinephrine reuptake inhibitors forming first-line chronic management. Fixed-dose combinations with anxiolytics dominate retail pharmacy dispensing in the United States; generic penetration has compressed branded pricing power.
- Anxiolytics:Benzodiazepine and non-benzodiazepine agents for acute symptom control.
- Beta Blockers:Propranolol and analogs targeting adrenergic hyperarousal symptoms.
- Alpha Agonists:Clonidine and guanfacine for sleep disruption and hypervigilance.
- Antipsychotics:Atypical agents reserved for severe dissociative or psychotic features.
Revenue concentration sits with Antidepressants; Novel Psychedelic Agents are climbing the fastest as academic medical centers establish dedicated treatment infrastructure.
End User:
Customer type fragmentation reflects how care delivery splits between institutional procurement and individual patient routing.
- Military Veterans:The most rapidly expanding population segment as VA healthcare infrastructure and telehealth platforms broaden rural access. United States federal funding prioritizes trauma-specific programming; specialized prescriber networks concentrate in coastal metropolitan areas.
- Telehealth Services:Software-enabled platforms delivering Cognitive Behavioral Therapy and medication management through synchronous video consultation. Private payer CPT code recognition in the United States enables sustainable revenue models outside traditional facility-based billing.
- Mental Health Clinics:Outpatient specialty practices with trauma-trained clinician staffing.
- Rehabilitation Centers:Residential and intensive outpatient programs for complex comorbid presentations.
- Psychiatric Hospitals:Inpatient acute stabilization and medication initiation settings.
- Outpatient Facilities:General medical settings with integrated behavioral health services.
Patient volume flows through Mental Health Clinics; the steepest expansion trajectory belongs to Telehealth Services as geographic barriers to specialized care erode.
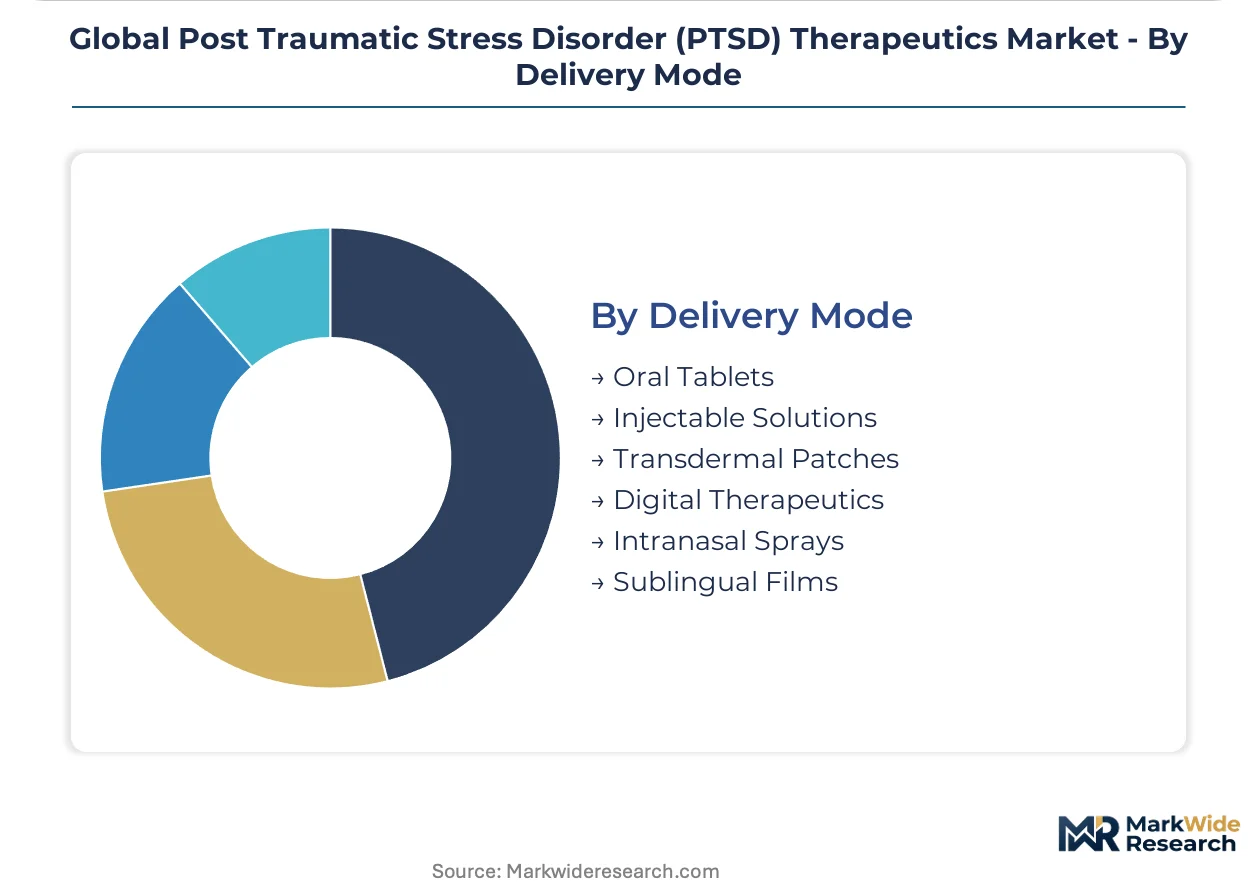
Delivery Mode:
Supply concentration and margin structure diverge between commoditized oral formulations and specialized delivery systems requiring manufacturing investment.
- Oral Tablets:Standardized solid-dose formulations dominating antidepressant and anxiolytic prescribing. Retail pharmacy networks in the United States achieve lowest-cost distribution; pill burden reduction through fixed-dose combinations drives formulation preference.
- Digital Therapeutics:Software-based interventions delivering structured Cognitive Behavioral Therapy protocols through mobile and web platforms. FDA breakthrough device designation and private payer CPT code recognition in the United States enable scalable deployment without manufacturing infrastructure.
- Injectable Solutions:Long-acting formulations for adherence-challenged populations.
- Transdermal Patches:Steady-state delivery systems for agents with narrow therapeutic indices.
- Intranasal Sprays:Rapid-onset delivery for acute agitation and dissociative episodes.
- Sublingual Films:Rapid-dissolve formats improving bioavailability and patient acceptance.
Prescription volume concentrates in Oral Tablets; Digital Therapeutics are gaining share fastest as employer-sponsored mental health benefits consolidate around integrated platform vendors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Clinical trial activity concentrates in the United States while manufacturing scale distributes across European and Asian pharmaceutical hubs. Patient access programs and regulatory frameworks diverge sharply between established Western markets and emerging economies. Telehealth infrastructure penetration varies by national broadband policy and healthcare reimbursement design.
United States
VA healthcare infrastructure and private payer coverage create the largest addressable patient base for PTSD therapeutics. FDA breakthrough therapy designation for psychedelic-assisted treatments compresses development timelines and attracts venture capital. Academic medical centers in Boston, Baltimore, and San Francisco are establishing dedicated treatment centers at accelerating pace.
Germany
EMA's Priority Medicines Scheme accelerates assessment pathways for novel anxiolytic combinations targeting fear-extinction deficits. REACH compliance requirements mandate greener synthesis routes and solvent recovery systems for psychiatric active pharmaceutical ingredients. The Rhine-Main pharmaceutical cluster around Frankfurt hosts manufacturing operations serving European distribution networks.
Japan
METI funding for mental health innovation and PMDA's acceptance of foreign trial data create expedited entry for established SSRI combinations. The aging veteran population drives demand for trauma-specific programming. Tokyo and Osaka metropolitan areas concentrate specialized psychiatric workforce and clinical research infrastructure.
United Kingdom
NHS England's mental health transformation program expands access to evidence-based psychological therapies including trauma-focused CBT. MHRA regulatory pathways align with EMA standards while maintaining independent assessment capacity. London's academic hospital networks anchor clinical trial recruitment for novel mechanism candidates.
Australia
TGA's provisional approval pathways enable early access to breakthrough-designated psychiatric therapies. The Department of Veterans' Affairs funds specialized PTSD treatment programs for defense force personnel. Melbourne and Sydney host the primary concentration of trauma-trained clinicians and research institutions.
Global Post Traumatic Stress Disorder (PTSD) Therapeutics Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the PTSD therapeutics landscape. Large pharmaceutical portfolios leverage manufacturing scale and retail pharmacy distribution networks. Biotech specialists concentrate on novel mechanism candidates targeting fear-extinction pathways. Competitive dynamics center on regulatory approval speed and prescriber certification infrastructure.
Among diversified pharmaceutical manufacturers, Pfizer Inc. and GlaxoSmithKline plc. occupy positions anchored by established antidepressant portfolios and global distribution capabilities. Jazz Pharmaceuticals exemplifies the specialized controlled-substance delivery segment with DEA-compliant manufacturing formats. Bionomics Ltd. represents the emerging biotech archetype focused on novel neurobiological targets. These three company types illustrate how competitive positioning stratifies across scale-driven, regulatory-specialized, and innovation-focused vectors.
| Leading Market Players |
|---|
| Pfizer Inc. |
| GlaxoSmithKline plc. |
| Otsuka Pharmaceutical |
| Jazz Pharmaceuticals |
| Teva Pharmaceutical Industries |
| AstraZeneca PLC |
| Aurobindo Pharma Limited |
| Bionomics Ltd. |
| Aptinyx |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up telehealth platforms anchor the PTSD therapeutics supply base, concentrating patient routing power while compressing reimbursement rates through direct-to-employer contracting. This ownership pattern tightens pricing discipline across both digital and pharmaceutical delivery channels.
Pricing Analysis
Cost-down pressure on generic antidepressant tiers accelerates because retail pharmacy consolidation concentrates buyer leverage. Three-tier pricing structure across premium psychedelic-assisted therapy, standard SSRI maintenance, and economy generic anxiolytic levels dominates the landscape. FDA breakthrough designation and DEA scheduling requirements differentiate premium from standard tiers. Military veterans through VA procurement demonstrate highest price sensitivity, while self-insured employers show lowest sensitivity for digital therapeutic subscriptions.
Supply Chain Analysis
Direct-to-patient telehealth channels handle rural veteran demand, bypassing traditional psychiatric hospital distribution. Active pharmaceutical ingredient production concentrates in India, China, and the United States. Novel psychedelic formulations draw from specialized GMP facilities and certified therapist networks. Single-source vulnerability in DEA-licensed manufacturing creates supply constraints for controlled-substance therapies. Distribution runs through VA mail-order pharmacies and retail chains for oral formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
PTSD therapeutics is becoming a vertical-integration race as players capture upstream biomarker discovery and downstream patient data platforms to secure pricing power.
For Market Incumbents: Hedge against psychedelic-assisted therapy disruption by acquiring digital phenotyping capabilities and securing DEA-licensed manufacturing capacity. Consolidate prescriber certification infrastructure to maintain channel control against emerging biotech entrants. Biomarker-guided patient stratification represents the critical defensive lever. For New Entrants and Emerging Players: AI-enabled digital therapeutics with FDA breakthrough device designation offer the most penetrable wedge into employer-sponsored mental health benefits. Target Fortune 500 behavioral health carve-outs in Texas and California where contract scale justifies platform investment. Pursue direct-to-employer sales bypassing traditional pharmacy benefit managers. For Investors and Strategic Acquirers: FDA rescheduling proceedings for MDMA and psilocybin are the leading indicator that novel mechanism pipelines will achieve viable market access. Five-to-ten year viability favors vertically integrated platforms combining drug development with digital delivery infrastructure. Watch DEA manufacturing quota expansions as the inflection signal for supply-scaling feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | FDA breakthrough therapy designation compresses development timelines for novel psychedelic candidates. |
| Regulatory Approval Pathway | DEA rescheduling proceedings determine market access feasibility for MDMA and psilocybin formulations. |
| Manufacturing Scale-Up | GMP capacity expansion for controlled substances requires specialized licensing and secure distribution infrastructure. |
| Pipeline Diversification | Fear-extinction pathway targets reduce reliance on serotonin-modulating mechanisms facing generic erosion. |
| Strategic Partnership | Academic medical center alliances establish dedicated treatment centers and therapist certification pipelines. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this PTSD therapeutics analysis. Primary interviews with drug development executives, regulatory affairs leads, formulary directors, and payer access specialists validated market sizing assumptions. FDA filings, EMA submissions, ClinicalTrials.gov entries, and hospital procurement databases supplied quantitative benchmarks. Bottom-up patient population estimates triangulated against top-down pharmaceutical revenue reconstructions.
Granularity-level modeling addressed therapy area, product type, end user, and delivery mode dimensions at the country level across the projection horizon. CAGRs derived from segment-level volume and value trajectories incorporating regulatory approval probability weightings. Psychedelic-assisted therapy training pipeline capacity and telehealth platform penetration served as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including off-label prescribing patterns and compounding pharmacy activity. Forecasts reflect assumptions about DEA scheduling timelines and reimbursement code stability that external regulatory actions could revise. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Rhabdomyosarcoma Treatment Market
Specialty Medicine
Diverticulitis Disease Market
Specialty Medicine
Specialty Generics Market
Specialty Medicine
Cystinuria Treatment Market
Specialty Medicine
Malignant Pleural Effusion Market
Specialty Medicine
Alcoholic Liver Diseases Treatment Market
Specialty Medicine
Global Glaucoma Therapeutics Market
Specialty Medicine
Chronic Obstructive Pulmonary Disease Therapeutics Market
Specialty Medicine
Global Pemphigus Vulgaris Market
Specialty Medicine
Myelofibrosis Market
Specialty Medicine
Atopic Dermatitis Market
Specialty Medicine
Chronic Myeloid Leukemia Treatment Market
Specialty Medicine
Japan Idiopathic Pulmonary Fibrosis Treatment Market
Specialty Medicine
Folliculotropic Mycosis Fungoides Treatment Market
Specialty Medicine
Dural Arteriovenous Fistulas Treatment Market
Specialty Medicine
Major Depressive Disorder (MDD) Treatment Market