
 Nasal Polyposis Treatment Market | 2026-2036
Nasal Polyposis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Nasal Polyposis Treatment Market Foresight
Biologic monoclonal antibody delivery via prefilled syringes and autoinjector platforms is reshaping patient adherence models in nasal polyposis care. Regeneron Pharmaceuticals leverages its IL-4Rα pathway expertise to sustain clinical differentiation against conventional steroid therapy. Sanofi anchors commercial scale through co-developed dupilumab access across hospital and specialty pharmacy channels. OptiNose competes with intranasal delivery devices that target drug deposition beyond the nasal valve.
Nasal polyposis treatment addresses chronic inflammatory outgrowths of sinonasal mucosa, typically exceeding 5 mm in diameter and obstructing nasal airflow, olfaction, and paranasal sinus drainage. The condition demands sustained anti-inflammatory intervention, with biologics now targeting type 2 inflammation pathways including IL-4, IL-5, and IgE-mediated cascades. Intranasal corticosteroids retain the largest volume share across delivery modes, though biologics command disproportionate value pools due to pricing power in refractory populations. Immunotherapy segments within therapy areas are gaining structural traction as payers evaluate step-therapy protocols and biomarker-directed patient selection.
FDA regulates biologic approvals through the Center for Drug Evaluation and Research, while EMA's Committee for Medicinal Products for Human Use governs centralized European market access for nasal polyposis indications. Both frameworks mandate rigorous phase III polyp score and nasal congestion endpoints, which directly shape trial design costs and commercialization timelines. Stakeholders must monitor evolving biosimilar entry timelines and payer step-edit requirements that will determine margin sustainability beyond originator exclusivity periods.
Market Dynamics
Biologics targeting type 2 inflammation pathways are compressing the chronic rhinosinusitis with nasal polyps treatment paradigm, displacing long-term oral corticosteroid dependence with IL-4Rα and IL-5 pathway inhibitors that require specialized infusion infrastructure.
Growth Catalysts
- EMA Centralized Authorization:The European Medicines Agency's streamlined biologics pathway accelerates cross-border market access across Germany, France, and the United Kingdom, reducing regulatory duplication for sponsors.
- Type 2 Biomarker Testing:Peripheral eosinophil count and total IgE assays enable precision patient selection, expanding eligible populations for biologic therapy beyond refractory surgical candidates.
- Specialty Pharmacy Networks:Hospital-outpatient and mail-order channels build cold-chain distribution capacity for monoclonal antibodies, extending reach into community settings previously served only by intranasal corticosteroids.
Market Restraints
- Biologics Manufacturing Concentration:Single-source contract manufacturing organizations in Switzerland and Ireland create supply vulnerability for fill-finish operations of prefilled autoinjector devices.
- Step-Therapy Mandates:United States commercial payers and Medicare Advantage plans require documented failure on intranasal corticosteroids and short-course oral steroids before biologic prior authorization approval.
- Intranasal Corticosteroid Substitution:Fluticasone propionate and mometasone furoate aqueous sprays retain first-line positioning in mild-to-moderate disease, limiting biologic penetration to severe phenotypes.
Strategic Opportunities
- Underpenetrated Asia-Pacific Markets:Japan's Ministry of Health, Labour and Welfare expanded biologic reimbursement in 2023, while South Korea's Health Insurance Review and Assessment Service reviews dupilumab for formulary inclusion.
- Real-World Evidence Pathways:FDA's 21st Century Cures Act enables supplemental indication submissions using patient registry data, potentially accelerating label expansion beyond polyp score endpoints.
- Digital Adherence Platforms:Smartphone-connected autoinjectors with injection logging and symptom tracking integrate into specialty pharmacy services, differentiating biologic brands through outcomes data capture.
Industry Challenges
- Biosimilar Development Expertise:Complex glycosylation patterns of IL-4Rα and IL-5 monoclonals demand analytical method development capabilities scarce among emerging-market contract research organizations.
- Site-of-Care Reimbursement Fragmentation:Hospital outpatient department, physician office, and home administration settings carry divergent Medicare reimbursement rates, complicating patient access coordination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nasal Polyposis Treatment Market |
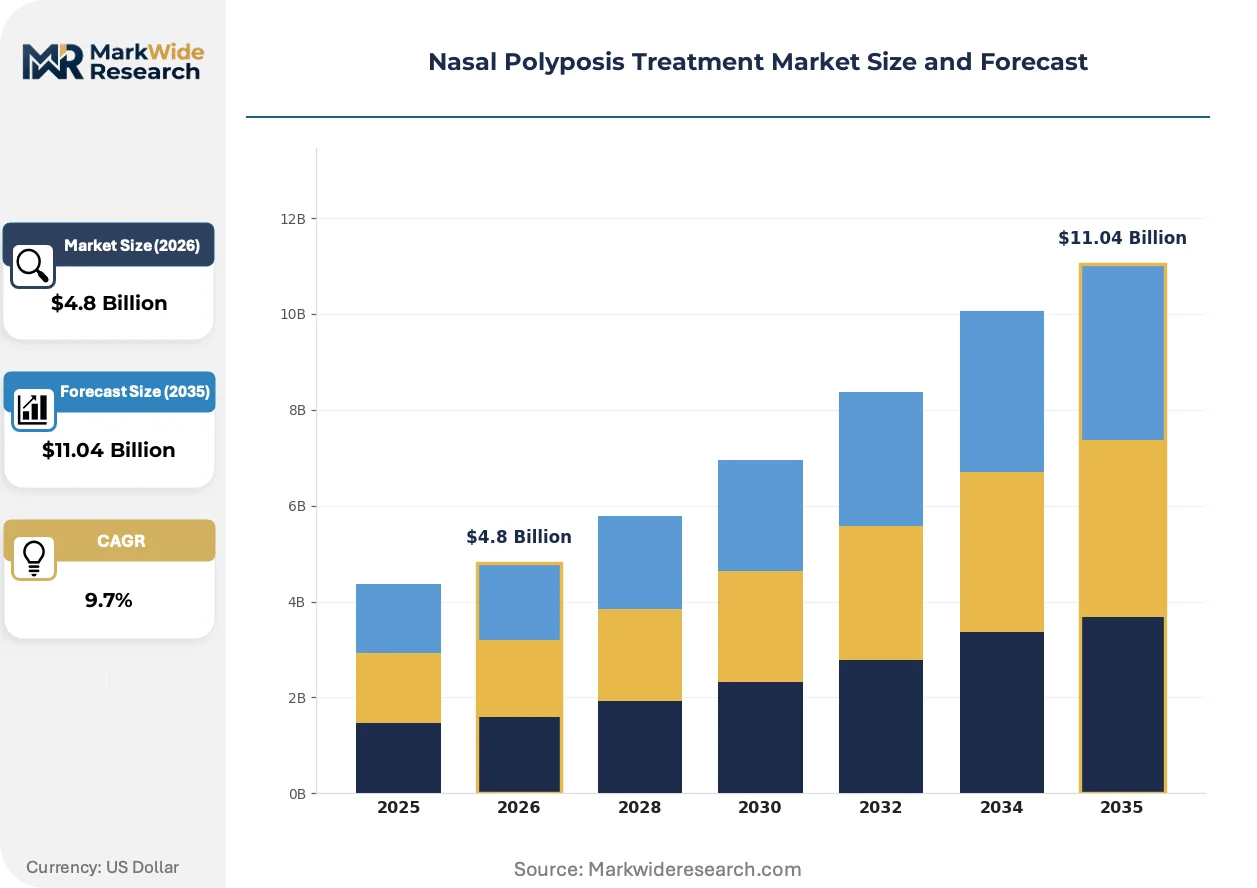
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Intranasal Corticosteroids, Biologics, Antibiotics, Saline Nasal Sprays Therapy Area: Immunotherapy, Surgical Interventions, Pharmacotherapy, Combination Therapy Delivery Mode: Topical Administration, Systemic Administration, Inhalation, Injectable End User: Hospitals, Outpatient Clinics, Homecare Settings, Specialty Pharmacies |
| Companies Covered | Sanofi, Regeneron Pharmaceuticals, GlaxoSmithKline, Novartis, AstraZeneca, OptiNose, Teva Pharmaceutical Industries, Merck & Co, Johnson & Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nasal Polyposis Treatment Market Shifts & Advancements
Delivery technology convergence and biomarker-directed therapy selection are restructuring how anti-inflammatory agents reach sinonasal tissue, with device innovation competing alongside molecular targeting for clinical differentiation.
Autoinjector platforms for subcutaneous biologic administration is hybridizing patient self-management with remote monitoring capabilities. Severe chronic rhinosinusitis with nasal polyps patients in the United States and Germany adopt these devices at accelerating rates, reducing hospital infusion center dependency. This hybridization compresses site-of-care costs while expanding prescriber willingness to initiate biologic therapy outside academic medical centers.
EMA's Medical Device Regulation (MDR) reclassification of drug-device combination products intensifies conformity assessment requirements for intranasal delivery systems. Manufacturers must now submit technical documentation to notified bodies for combination products previously regulated as medicinal products alone. Nasal spray devices targeting beyond-the-valve deposition face extended timeline pressures in the European Union, while United States FDA 510(k) pathways maintain faster clearance for equivalent technologies.
Specialty pharmacy benefit managers consolidate prior authorization processing for biologics under exclusive distribution arrangements. United States payers channel dupilumab and omalizumab dispensing through limited networks of accredited specialty pharmacies, displacing traditional community pharmacy dispensing. This concentration is most visible in Medicare Part B and commercial employer-sponsored plans, where pharmacy outcomes contracts tie reimbursement to polyp score improvement metrics.
Nasal Polyposis Treatment Market Segmentation
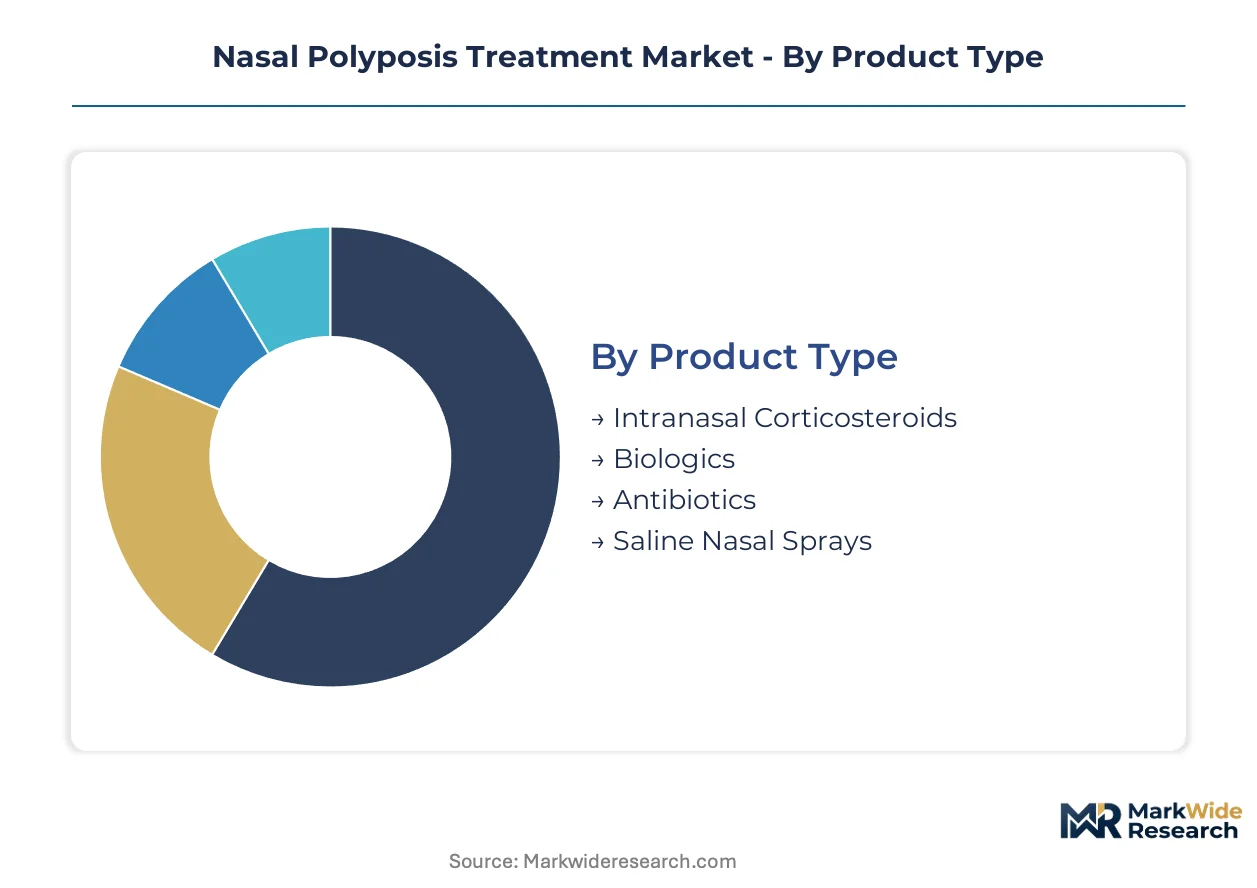
Nasal polyposis treatment markets fragment across therapeutic modality, site of care, and patient severity phenotypes. Segment-specific regulatory pathways and reimbursement mechanics create divergent margin profiles that shape manufacturer portfolio prioritization.
Product Type:
Cycle times vary sharply: intranasal formulations refresh annually with generic substitution, while biologics lock in decade-long development-to-patent-expiry windows.
- Intranasal Corticosteroids:Aqueous suspensions of fluticasone propionate, mometasone furoate, and budesonide deliver high-potency anti-inflammatory action directly to sinonasal mucosa. First-line positioning across mild-to-moderate disease in the United States and Germany sustains volume dominance despite generic erosion. Step-therapy mandates from commercial payers reinforce prescription volume by requiring documented failure before biologic escalation.
- Biologics:Monoclonal antibodies targeting IL-4Rα, IL-5, and IgE pathways require cold-chain distribution and specialty pharmacy handling. Dupilumab and omalizumab concentrate demand among refractory chronic rhinosinusitis with nasal polyps patients who have failed surgical and corticosteroid interventions. Medicare Part B reimbursement frameworks and hospital outpatient payment rates determine prescriber willingness to initiate therapy.
- Antibiotics:Short-course oral and topical formulations address acute bacterial superinfection complicating chronic inflammation. Prescription volumes track seasonal exacerbation patterns and regional antibiotic stewardship protocols.
- Saline Nasal Sprays:Isotonic and hypertonic irrigation solutions provide mechanical debridement and mucociliary clearance support. Over-the-counter accessibility and low price points sustain consumer-direct purchase patterns outside formal reimbursement channels.
Intranasal corticosteroids anchor the volume base while biologics gain share at the steepest rate.
Therapy Area:
Cost tier stratification separates acute episodic intervention from chronic disease management investment levels.
- Immunotherapy:Biologic monoclonal antibodies and emerging small-molecule modulators target type 2 inflammation pathways with precision. EMA centralized authorization and FDA breakthrough therapy designations accelerate access for severe phenotypes with elevated peripheral eosinophil counts.
- Surgical Interventions:Endoscopic sinus surgery and polypectomy retain role in anatomical correction and salvage therapy. German and United Kingdom hospital reimbursement frameworks favor ambulatory surgical center migration where clinically appropriate.
- Pharmacotherapy:Conventional oral corticosteroids, leukotriene antagonists, and antihistamines address symptom control and acute exacerbation. Long-term oral steroid exposure limits utilization duration due to metabolic and bone density toxicity concerns.
- Combination Therapy:Coordinated biologic plus intranasal corticosteroid regimens optimize polyp score and olfaction outcomes. Payer prior authorization complexity increases with multi-agent protocols requiring documented sequential failure criteria.
Pharmacotherapy retains the broadest patient reach while immunotherapy commands the highest per-patient revenue intensity.
Delivery Mode:
Volume concentration follows administration convenience, with patient self-administration expanding fastest outside institutional settings.
- Topical Administration:Nasal sprays, drops, and irrigation systems deposit active agents directly onto inflamed mucosal surfaces. Device engineering focused on beyond-the-valve deposition differentiates premium formulations from commodity alternatives.
- Systemic Administration:Oral corticosteroids and antibiotics achieve therapeutic levels through gastrointestinal absorption and hepatic metabolism. Short-course burst therapy limits systemic exposure while managing acute inflammatory flares.
- Inhalation:Nebulized and dry powder delivery systems target lower respiratory inflammation in patients with overlapping asthma and nasal polyposis. United States pulmonology and allergy specialty overlap creates prescriber coordination challenges.
- Injectable:Subcutaneous autoinjector and prefilled syringe platforms enable home administration of biologic monoclonal antibodies. Specialty pharmacy networks manage cold-chain logistics and patient training for self-injection protocols.
Topical administration sustains the highest prescription frequency while injectable formats expand prescriber addressable market through site-of-care flexibility.
End User:
Customer type segmentation maps to reimbursement complexity and clinical decision-making authority concentration.
- Hospitals:Academic medical centers and community hospitals manage severe refractory cases requiring multidisciplinary otolaryngology-allergy coordination. Inpatient and observation status determinations affect Medicare severity-adjusted diagnosis-related group reimbursement.
- Outpatient Clinics:Office-based otolaryngology and allergy-immunology practices initiate and monitor biologic therapy with remote patient monitoring support. United States site-of-care payment differentials influence infusion versus self-administration selection.
- Homecare Settings:Patient-directed intranasal corticosteroid and saline irrigation administration dominates maintenance therapy volume. Digital adherence platforms with smartphone-connected devices capture outcomes data for payer contracting.
- Specialty Pharmacies:Accredited limited distribution networks handle biologic dispensing, prior authorization processing, and patient support services. Exclusive arrangements with national payers consolidate volume among three to five dominant channel participants.
Homecare settings generate the highest prescription volume while specialty pharmacies capture the steepest revenue per transaction expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biologics trade flows concentrate in high-value corridors linking manufacturing sites in Switzerland and Ireland to demand centers in the United States and Germany. Import dependency for fill-finish operations creates supply vulnerability, while regulatory harmonization efforts reshape cross-border market access timelines.
United States
Medicare Part B reimbursement frameworks anchor biologic demand among severe chronic rhinosinusitis with nasal polyps patients. FDA breakthrough therapy designations for IL-4Rα and IL-5 pathway inhibitors compress approval timelines. Boston and San Francisco biotech clusters host pivotal trial infrastructure and specialist prescriber networks.
Germany
Ambulatory surgical center migration for endoscopic sinus procedures reduces hospital reimbursement costs while expanding intervention capacity. EMA centralized authorization enables rapid formulary inclusion across statutory health insurance funds. The Rhine-Main region concentrates otolaryngology-allergy specialist practices managing biologic therapy initiation.
Japan
Ministry of Health, Labour and Welfare expanded biologic reimbursement coverage in 2023, unlocking access for refractory nasal polyposis patients. PMDA accelerated review pathways for type 2 inflammation-targeted therapies align with global regulatory convergence. Tokyo and Osaka academic medical centers lead real-world evidence collection for post-market surveillance.
United Kingdom
NICE technology appraisals impose cost-effectiveness thresholds that delay biologic access pending health economic submissions. NHS England specialized commissioning frameworks centralize funding decisions for high-cost immunotherapy agents. The Manchester and Birmingham hospital networks pilot biomarker-directed patient selection protocols.
South Korea
Health Insurance Review and Assessment Service formulary reviews for dupilumab signal expanding biologic access in previously underserved markets. MFDS regulatory harmonization with ICH guidelines streamlines multinational trial participation. Seoul Capital Area tertiary hospitals build cold-chain distribution partnerships with specialty pharmacy networks.
Nasal Polyposis Treatment Market Competitive Landscape
On the supply side, the industry is consolidating around biologic monoclonal antibody platforms with high manufacturing barriers and extended development cycles. Large-cap pharmaceutical sponsors dominate through co-development arrangements and specialty pharmacy channel control. Three archetypes define competitive positioning: IL pathway specialists leveraging immunology expertise, device-therapy combination innovators targeting delivery differentiation, and diversified respiratory players extending franchise reach. Dominant competitive moves include strategic partnerships for autoinjector platform access and geographic licensing arrangements for underpenetrated Asia-Pacific markets.
Within the IL pathway specialist tier, Regeneron Pharmaceuticals and Sanofi exemplify integrated development and commercialization models. Sanofi anchors scale through co-developed biologic access across hospital and specialty pharmacy channels. OptiNose occupies a distinct position among device-centric competitors targeting intranasal deposition beyond the nasal valve. GlaxoSmithKline and AstraZeneca represent diversified respiratory players extending established inflammation and immunology franchises into nasal polyposis indications.
| Leading Market Players |
|---|
| Sanofi |
| Regeneron Pharmaceuticals |
| GlaxoSmithKline |
| Novartis |
| AstraZeneca |
| OptiNose |
| Teva Pharmaceutical Industries |
| Merck & Co |
| Johnson & Johnson |
| Others |
Supply & Pricing Matrix
Basel and Zurich manufacturing clusters anchor European fill-finish capacity for monoclonal antibody autoinjectors, with their output constraints directly translating into pricing leverage for originator biologics in United States and German markets. Cold-chain infrastructure scarcity at these Swiss sites amplifies cost pass-through to downstream specialty pharmacy channels.
Pricing Analysis
Next-generation IL-4Rα and IL-5 pathway inhibitors command substantial premiums over legacy intranasal corticosteroid formulations, while oral steroid burst therapy occupies a collapsing mid-tier. Three-tier pricing structure across premium biologics, standard intranasal sprays, and economy saline irrigation separates reimbursement-eligible immunotherapy from over-the-counter maintenance options. Cost compression in the intranasal corticosteroid tier intensifies because generic substitution has eroded originator brand premiums. Hospital outpatient clinics exhibit the lowest price sensitivity due to Medicare severity-adjusted reimbursement, while homecare direct purchasers remain most responsive to out-of-pocket differentials.
Supply Chain Analysis
Upstream bioreactor feedstock and cell culture media production concentrates in Switzerland, Ireland, and the United States, with single-source contract manufacturing organizations dominating fill-finish operations for prefilled syringe devices. Active pharmaceutical ingredients for biologics draw from recombinant protein expression systems, glass primary packaging, and specialized elastomeric closure components. Single-source vulnerability in Swiss fill-finish capacity creates supply interruption exposure during regulatory inspections or equipment failures. Distribution runs through hospital outpatient departments, physician office infusion centers, and accredited specialty pharmacy networks with exclusive payer arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The nasal polyposis treatment market sits at a platform-economics inflection where biologic autoinjector ecosystems and digital adherence platforms are redefining competitive moats through interoperability with electronic health record systems and payer outcomes contracts.
For Market Incumbents: Entrench formulary positioning through backward integration into autoinjector manufacturing capacity in the Rhine-Main region, securing supply continuity against Swiss single-source vulnerability. Deepen specialty pharmacy exclusive distribution arrangements to lock out biosimilar challengers before patent cliff exposure. Prioritize FDA supplemental indication submissions using real-world evidence pathways to extend label protection. For New Entrants and Emerging Players: Pursue device-therapy combination white space in beyond-the-valve intranasal deposition systems, where EMA MDR reclassification has delayed incumbent product cycles. Target South Korean and Japanese markets where Health Insurance Review and Assessment Service and Ministry of Health, Labour and Welfare reimbursement expansions have opened access windows. Anchor go-to-market strategy through academic medical center real-world evidence partnerships rather than direct payer contracting. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors IL pathway specialists with integrated development-commercialization capabilities and existing specialty pharmacy channel control. Five-to-ten year viability hinges on biosimilar defense duration and step-therapy mandate erosion. Signal to watch: FDA biosimilar interchangeability determinations for IL-4Rα monoclonals as inflection indicator for originator margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Biologic Manufacturing Scale-Up | Expands fill-finish capacity in Basel and Zurich clusters to address autoinjector supply constraints. |
| Specialty Pharmacy Network Partnership | Secures exclusive distribution through Medicare Part B accredited channels against competitor access. |
| Real-World Evidence Pathway Submission | Leverages FDA 21st Century Cures Act provisions for label expansion beyond polyp score endpoints. |
| Digital Adherence Platform Integration | Connects smartphone-autoinjector systems to electronic health records for payer outcomes contracting. |
| Asia-Pacific Licensing Arrangement | Unlocks Japanese and South Korean reimbursement via Ministry of Health, Labour and Welfare and HIRA formulary inclusion. |
Research Methodology
Initial hypotheses were tested against primary input from drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers and refined through secondary validation across FDA filings, EMA submissions, ClinicalTrials.gov, and CMS Medicare reimbursement databases. Bottom-up prescription volume modeling and top-down epidemiological prevalence estimates were triangulated to anchor market sizing.
Demand-supply-balance framing structured the analytical framework across the projection horizon, with segmentation dimensions covering treatment line, delivery mode, site of care, and regional regulatory cluster. CAGRs were derived from patient flow modeling through step-therapy protocols and biologic eligibility expansion scenarios. Forecast inputs incorporated biomarker testing penetration rates and specialty pharmacy network expansion trajectories.
Macroeconomic conditions sit as an overlay; deviation in Medicare reimbursement rates, commercial payer step-edit stringency, or biosimilar approval timelines would shift the trajectory. Cross-checking against IQVIA prescription audit data and Symphony Health claims databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Leukemia Inhibitory Factor (LIF) Market
Specialty Medicine
Americas Gerd and Nerd Treatment Market
Specialty Medicine
Intestine (Small) Cancer Therapeutics Market
Specialty Medicine
Middle East and Africa Primary Angle-Closure Glaucoma Market
Specialty Medicine
Behcet's Syndrome Market
Specialty Medicine
Essential Thrombocythemia Market
Specialty Medicine
Pleurisy Market
Specialty Medicine
Epistaxis Market
Specialty Medicine
Global Chronic Lower Back Pain (CLBP) Market
Specialty Medicine
Disruptive Behavior Disorders Market
Specialty Medicine
Lateral Epicondylitis (Tennis Elbow) Treatment Market
Specialty Medicine
Global Fungal Keratitis Treatment Market
Specialty Medicine
Global Appendicitis Market
Specialty Medicine
Chronic Obstructive Pulmonary Disease Therapeutics Market
Specialty Medicine
Pyoderma Gangrenosum Therapeutics Market
Specialty Medicine
Global Laryngeal Cancer Therapeutics Market