
 Acute Hepatic Porphyria (AHP) Treatment Market | 2026-2036
Acute Hepatic Porphyria (AHP) Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Acute Hepatic Porphyria (AHP) Treatment Market Outlook
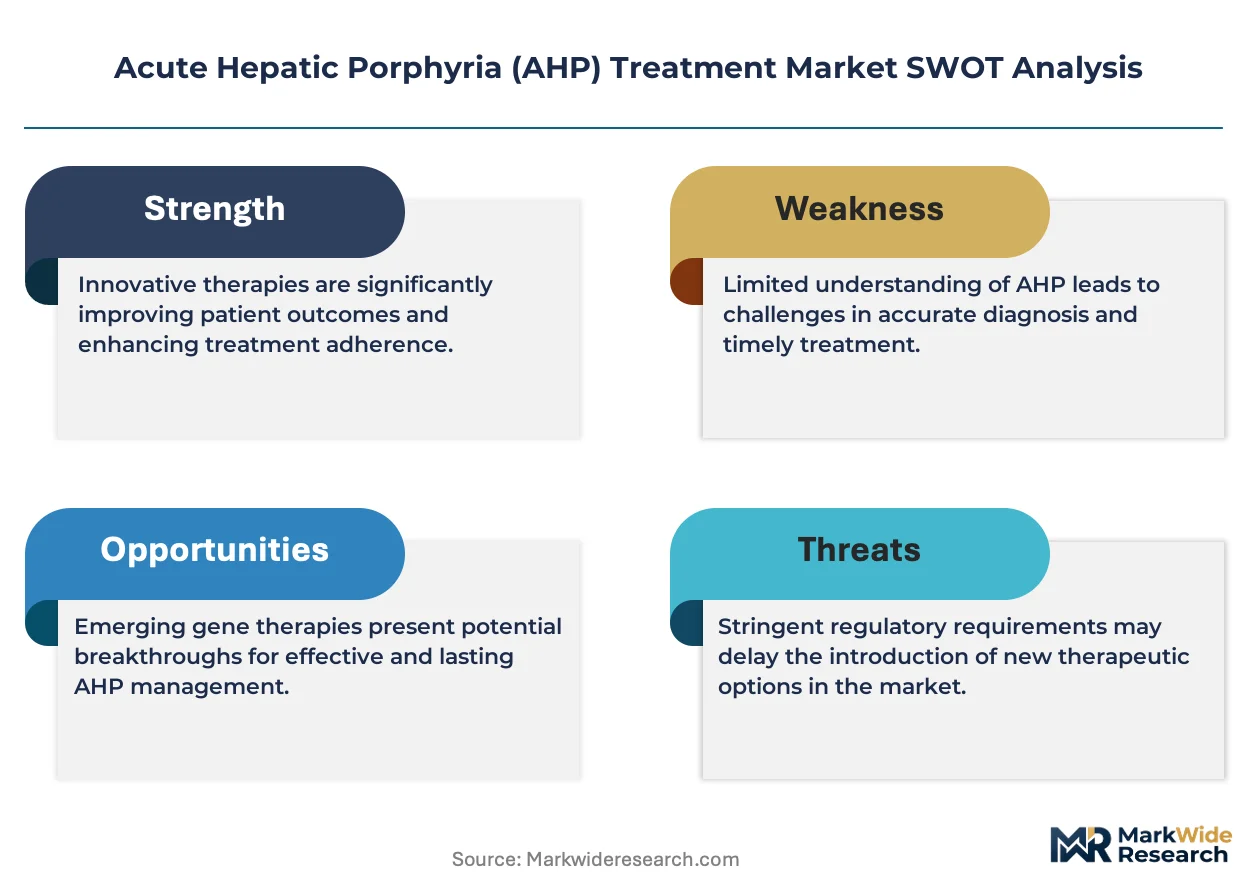
EMA orphan drug incentives is repositioning the commercial calculus for rare disease therapeutics in Europe. Alnylam Pharmaceuticals leverages its RNA interference platform to sustain leadership in targeted AHP therapies. Recordati Rare Diseases anchors its European commercial infrastructure around ultra-rare metabolic conditions including porphyria subtypes.
Acute Hepatic Porphyria treatment encompasses therapeutic interventions targeting the four autosomal dominant hepatic porphyrias—acute intermittent porphyria, variegate porphyria, hereditary coproporphyria, and ALAD-deficiency porphyria—characterized by neurovisceral attacks driven by aminolevulinic acid and porphobilinogen accumulation. These interventions function to suppress hepatic ALAS1 expression, replenish heme regulatory pools, or modulate disease-triggering metabolic pathways. Small molecules currently dominate prescription volumes through established hemin formulations and glucose-loading protocols, while gene therapy represents the fastest-expanding development category as investigational AAV and RNAi constructs advance through clinical pipelines. Biologics command premium pricing tiers due to manufacturing complexity and targeted mechanisms, with intravenous delivery sustaining hospital-based administration as the primary revenue channel.
FDA orphan drug exclusivity provisions and EMA priority medicines pathways shape development timelines and market access trajectories for AHP innovators. Japan's PMDA Sakigake designation accelerates domestic review for novel porphyria therapies addressing unmet neurological burden. Stakeholders must monitor regulatory convergence around gene therapy manufacturing standards and real-world evidence requirements as these frameworks determine which modalities achieve sustainable reimbursement.
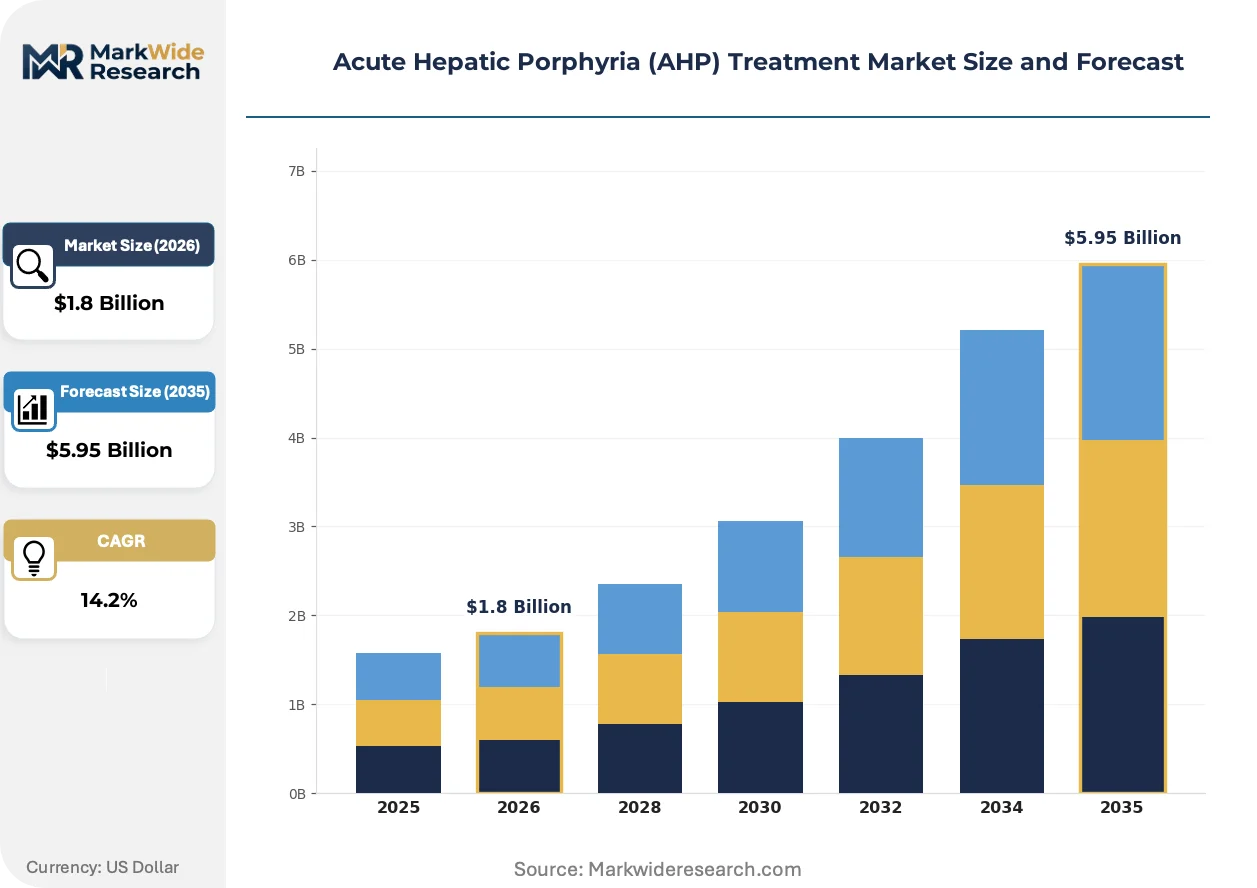
Market Dynamics
RNA interference platforms are compressing development timelines for hepatic porphyria therapeutics while FDA orphan drug exclusivity provisions reshape competitive entry barriers. Alnylam's givosiran success has triggered pipeline congestion as developers race to secure priority review vouchers.
Growth Catalysts
- FDA Orphan Drug Incentives:Seven-year market exclusivity and tax credits for clinical trial costs accelerate investment in ultra-rare metabolic disease portfolios. Sponsors prioritize hepatic porphyria subtypes with validated biomarker endpoints.
- Specialty Clinic Expansion:Dedicated porphyria centers in the United States, Germany, and Japan concentrate patient referrals and streamline diagnostic confirmation. These hubs generate treatment-naïve cohorts for novel therapy adoption.
- Gene Therapy Manufacturing Maturation:Scalable AAV production platforms reduce cost-per-dose for investigational ALAS1-targeting constructs. Contract development organizations now offer dedicated rare disease viral vector suites.
Market Restraints
- Hemin Supply Concentration:Plasma-derived hemin formulations depend on fractionation capacity concentrated in North American and European blood product facilities. Viral inactivation requirements constrain batch release timelines.
- Diagnostic Latency:Mean time from symptom onset to confirmed porphyria diagnosis exceeds four years in most healthcare systems. Delayed identification compresses addressable patient pools for prophylactic therapies.
- Reimbursement Complexity:Intravenous hemin administration requires hospital-based prior authorization in most U.S. commercial plans. Site-of-care restrictions fragment prescribing authority between emergency departments and infusion centers.
Strategic Opportunities
- Subcutaneous Formulation Development:Self-administered RNAi or small-molecule alternatives to intravenous hemin could shift treatment to home settings. Patient preference data from European porphyria registries supports this route.
- Real-World Evidence Pathways:EMA's adaptive licensing frameworks accept post-authorization efficacy data from national porphyria networks. France's ANSM has piloted disease-specific patient registry integration for accelerated assessment.
- Pediatric Indication Expansion:Current therapies lack approved dosing for adolescent acute intermittent porphyria patients. Juvenile toxicity studies represent unclaimed regulatory exclusivity extensions.
Industry Challenges
- Biomarker Standardization:Urinary porphobilinogen quantification lacks harmonized reference ranges across reference laboratories. Discordant results complicate clinical trial enrollment and therapeutic monitoring.
- Gene Therapy Cold Chain Integrity:AAV vector stability requirements demand validated -80°C distribution networks to specialty treatment centers. Infrastructure gaps in Southern and Eastern Europe limit trial site activation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acute Hepatic Porphyria (AHP) Treatment Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Small Molecules, Gene Therapy, Biologics, Enzyme Replacement Therapy Delivery Mode: Intravenous, Subcutaneous, Oral, Inhalation End User: Hospitals, Specialty Clinics, Homecare Settings, Research Laboratories Application: Emergency Treatment, Long-term Management, Diagnostic Applications, Clinical Research |
| Companies Covered | Alnylam Pharmaceuticals, Inc., Recordati Rare Diseases, Mitsubishi Tanabe Pharma Corporation, Lundbeck A/S, Teva Pharmaceutical Industries Ltd., Pfizer Inc., Sanofi S.A., Takeda Pharmaceutical Company Limited, JCR Pharmaceuticals Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acute Hepatic Porphyria (AHP) Treatment Market Strategic Shifts
RNA interference mechanisms are displacing enzyme replacement as the dominant therapeutic modality in hepatic porphyria, while regulatory convergence around gene therapy manufacturing standards compresses development timelines. Patient advocacy networks increasingly shape trial design and access protocols.
Givosiran and follow-on RNAi constructs targeting hepatic ALAS1 expression is consolidating clinical development pipelines around periodic subcutaneous dosing models. Specialty porphyria centers in the United States and Western Europe are adopting these therapies as first-line prophylaxis for recurrent attack patients. The shift is compressing hospitalization revenue for acute hemin administration while expanding pharmacy benefit management complexity.
EMA's priority medicines designation and FDA's breakthrough therapy pathways are accelerating review timelines for novel porphyria therapeutics with demonstrated attack reduction endpoints. These frameworks compress Phase 3 duration requirements when surrogate biomarkers correlate with clinical benefit. Small-molecule developers now target these pathways to compete with established RNAi franchises.
Patient registries maintained by national porphyria associations are displacing traditional clinical trial sites as primary evidence generation platforms. Germany's porphyria network and the British Porphyria Association collect longitudinal attack frequency and quality-of-life data that sponsors leverage for label expansion. This distributed model reduces per-patient trial costs while complicating data standardization across heterogeneous healthcare systems.
Acute Hepatic Porphyria (AHP) Treatment Market Segmentation
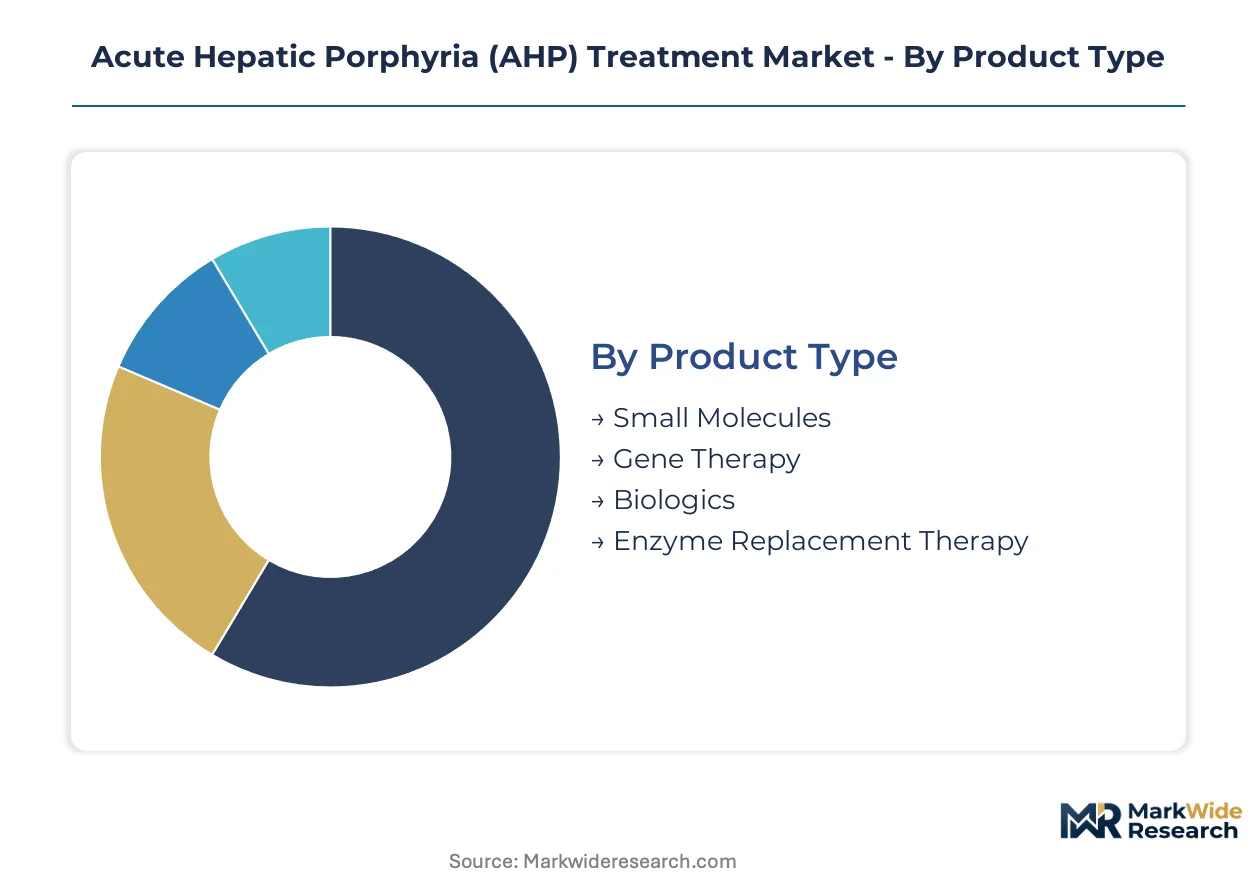
Treatment modality selection in Acute Hepatic Porphyria hinges on attack severity, reimbursement pathways, and site-of-care logistics. Segmentation reveals how RNA interference platforms are compressing the addressable market for plasma-derived hemin across referral networks.
Product Type:
Mechanism of action determines manufacturing complexity, regulatory exclusivity duration, and pricing tier placement across hospital formularies.
- Small Molecules:Hemin formulations and glucose-loading protocols constitute the established standard of care. Hospital emergency departments in the United States and Germany rely on these interventions for acute attack termination, though plasma fractionation constraints limit supply elasticity during demand surges.
- Gene Therapy:AAV-mediated ALAS1 suppression and RNAi constructs targeting hepatic heme biosynthesis represent the most active investigational category. Subcutaneous dosing models from Alnylam Pharmaceuticals and competing sponsors are gaining priority review designations from FDA and EMA.
- Biologics:Recombinant enzyme preparations command premium reimbursement through specialty pharmacy channels. Manufacturing complexity restricts production to contracted biologics facilities with validated viral clearance protocols.
- Enzyme Replacement Therapy:Investigational approaches targeting porphobilinogen deaminase deficiency remain preclinical. Academic consortia in Japan and the United Kingdom anchor early-stage development.
Small molecules lead on scale; gene therapy leads on momentum.
Delivery Mode:
Route of administration shapes patient compliance, site-of-care economics, and prior authorization complexity in commercial reimbursement.
- Intravenous:Hospital-based hemin infusion dominates acute attack management. United States commercial plans require emergency department prior authorization, fragmenting prescribing authority between infusion centers and acute care settings.
- Subcutaneous:Self-administered RNAi formulations enable home-based prophylaxis. Patient registries from France's ANSM pilot programs demonstrate preference for this route among recurrent attack cohorts.
- Oral:Small-molecule prophylaxis candidates target maintenance dosing between acute episodes. Bioavailability challenges limit current pipeline candidates to early-phase trials.
- Inhalation:Nebulized hemin formulations remain experimental. Academic investigators at German porphyria centers are evaluating pulmonary absorption kinetics.
Intravenous infusion retains volume concentration; subcutaneous delivery is climbing the fastest.
End User:
Care setting determines reimbursement pathway, patient acquisition cost, and therapy persistence metrics for chronic prophylaxis.
- Hospitals:Emergency departments generate the highest per-patient revenue through acute hemin administration. Site-of-care restrictions in U.S. commercial plans constrain shift to lower-acuity settings.
- Specialty Clinics:Dedicated porphyria centers in Boston, Munich, and Tokyo concentrate diagnostic confirmation and novel therapy enrollment. These hubs generate treatment-naïve cohorts for RNAi adoption.
- Homecare Settings:Subcutaneous RNAi administration is shifting prophylactic treatment from hospital infusion to specialty pharmacy distribution. Home nursing services manage first-dose supervision requirements.
- Research Laboratories:National porphyria networks in Germany and the United Kingdom collect longitudinal biomarker data. Sponsors leverage these registries for post-authorization efficacy submissions to EMA.
Hospitals anchor current revenue; specialty clinics are gaining share fastest.
Application:
Clinical use case determines dosing frequency, outcome measurement, and regulatory evidence requirements.
- Emergency Treatment:Acute neurovisceral attack termination requires immediate intravenous hemin availability. Plasma-derived supply concentration in North American fractionation facilities creates geographic access disparities.
- Long-term Management:Prophylactic RNAi dosing targets attack prevention in recurrent patients. Alnylam's givosiran has established this category as the primary growth vector in specialty pharmacy channels.
- Diagnostic Applications:Biomarker quantification supports clinical trial enrollment and therapeutic monitoring. Urinary porphobilinogen reference standardization remains unresolved across reference laboratories.
- Clinical Research:Gene therapy trials require centralized administration at academic medical centers with AAV handling capabilities. Infrastructure gaps in Southern and Eastern Europe limit site activation.
Emergency treatment commands current spending; long-term management shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Acute Hepatic Porphyria treatment capacity first consolidated in tertiary referral centers across the United States and Germany during the 1980s hemin formulation era. Japan's specialized metabolic disease networks expanded subsequently. Contemporary market development reflects this historical concentration of diagnostic expertise and plasma fractionation infrastructure.
United States
FDA orphan drug exclusivity provisions have concentrated novel therapy development in Boston and San Francisco biotechnology clusters. Massachusetts General Hospital and the University of Texas Southwestern anchor national porphyria referral networks. Specialty pharmacy distribution channels for subcutaneous RNAi prophylaxis are expanding through CVS Caremark and OptumRx networks.
Germany
Germany's statutory health insurance system guarantees hemin access through hospital emergency departments nationwide. EMA priority medicines designation accelerates market entry for Munich and Heidelberg-based developers. The German Porphyria Network in Freiburg coordinates longitudinal patient registry data for post-authorization efficacy submissions.
Japan
PMDA Sakigake designation compresses review timelines for therapies addressing neurological burden in acute intermittent porphyria. Tokyo and Osaka academic medical centers concentrate the nation's diagnostic capacity. JCR Pharmaceuticals anchors domestic enzyme replacement development through Kobe manufacturing facilities.
United Kingdom
The British Porphyria Association maintains Europe's most comprehensive attack frequency database from Birmingham and London treatment centers. NHS England's specialized commissioning framework centralizes high-cost drug access decisions. Manchester Royal Infirmary leads gene therapy trial site activation for AAV-mediated ALAS1 suppression.
France
ANSM pilot programs integrate national porphyria registry data into adaptive licensing frameworks. Paris and Lyon referral centers generate treatment-naïve cohorts for novel therapy adoption. Hospital-based prior authorization requirements for intravenous hemin sustain emergency department revenue concentration in Île-de-France.
Acute Hepatic Porphyria (AHP) Treatment Market Competitive Environment
The competitive structure tilts toward platform-technology specialists with validated RNA interference capabilities. Consolidation around hepatic gene silencing mechanisms has compressed development timelines while raising barriers for small-molecule entrants. Two strategic archetypes dominate: RNAi platform holders with periodic dosing franchises, and plasma fractionation-dependent incumbents with established hospital supply relationships. Competitive moves center on subcutaneous formulation development and real-world evidence partnerships with national porphyria networks.
Among RNA interference specialists, Alnylam Pharmaceuticals exemplifies the platform-holder archetype through its hepatic ALAS1-targeting portfolio. Recordati Rare Diseases occupies a position within the European ultra-rare disease commercialization tier, anchoring metabolic condition infrastructure across Italy and Germany. Mitsubishi Tanabe Pharma Corporation represents the Asia-Pacific specialty pharmaceutical segment with established hospital infusion channel relationships in Tokyo and Osaka.
| Leading Market Players |
|---|
| Alnylam Pharmaceuticals, Inc. |
| Recordati Rare Diseases |
| Mitsubishi Tanabe Pharma Corporation |
| Lundbeck A/S |
| Teva Pharmaceutical Industries Ltd. |
| Pfizer Inc. |
| Sanofi S.A. |
| Takeda Pharmaceutical Company Limited |
| JCR Pharmaceuticals Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Plasma fractionation capacity in North American and European blood product facilities anchors cost structures for acute hemin administration, with viral inactivation batch requirements cascading through hospital procurement tiers to shape reimbursement negotiations between specialty pharmacies and commercial payers.
Pricing Analysis
Three-tier pricing structure across premium RNAi prophylaxis, standard plasma-derived hemin, and economy glucose-loading protocols segments the market by mechanism sophistication and manufacturing complexity. Price differentiation hinges on orphan drug exclusivity duration and site-of-care administration requirements, with hospital-based infusion commanding premium reimbursement over home-administered alternatives. Cost compression in standard hemin tiers intensifies as biosimilar entrants target plasma-derived formulations, while gene therapy candidates face pricing resistance from pharmacy benefit managers. Academic medical centers demonstrate lowest price sensitivity due to bundled reimbursement models, whereas independent specialty clinics negotiate aggressively on per-dose contracts.
Supply Chain Analysis
Single-source vulnerability sits with plasma collection networks concentrated in the United States, Germany, and Austria for hemin precursor materials. Raw material dependencies span donor plasma availability, chromatography resins for viral clearance, and validated cold-chain packaging for AAV vector stability. Supply chain risk centers on regulatory restriction around blood product importation during fractionation facility inspections. Distribution runs through hospital-based specialty pharmacies for acute administration, with specialty pharmacy direct-to-patient models expanding for subcutaneous prophylaxis.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as treatment-naïve cohorts migrate toward premium RNAi prophylaxis with demonstrated attack reduction endpoints, compressing addressable volume for commodity hemin formulations.
For Market Incumbents: Anticipate erosion in hospital infusion revenue as subcutaneous RNAi adoption accelerates among recurrent attack patients at Boston and Munich referral centers. Consolidate position through backward integration into plasma fractionation capacity or exclusive distribution partnerships with German porphyria networks. Prioritize real-world evidence generation via France's ANSM registry integration to defend formulary placement against gene therapy entrants. For New Entrants and Emerging Players: A mid-tier pricing gap between premium Alnylam givosiran and generic hemin alternatives creates white-space opportunity for oral small-molecule prophylaxis candidates. Target adolescent acute intermittent porphyria populations lacking approved dosing protocols, where regulatory exclusivity extensions remain unclaimed. Pursue licensing agreements with JCR Pharmaceuticals for Asia-Pacific commercial infrastructure rather than building de novo hospital channel relationships. For Investors and Strategic Acquirers: Consolidation pressure builds where RNAi platform holders seek manufacturing scale and national porphyria registry access to compress post-authorization evidence costs. Frame long-term viability around gene therapy manufacturing capabilities with validated -80°C distribution networks, as AAV cold chain infrastructure becomes the binding constraint on addressable patient expansion. Watch EMA convergence on gene therapy manufacturing standards as the inflection signal for acquisition timing.| Strategic Initiative | Industry Significance |
|---|---|
| Subcutaneous Formulation Development | Shifts administration from hospital emergency departments to home-based specialty pharmacy channels. |
| Real-World Evidence Partnership | Leverages German Porphyria Network longitudinal data for EMA adaptive licensing submissions. |
| Pediatric Indication Expansion | Captures unclaimed regulatory exclusivity for adolescent acute intermittent porphyria dosing protocols. |
| Plasma Fractionation Backward Integration | Secures captive hemin supply against viral inactivation batch release constraints. |
| Gene Therapy Cold Chain Infrastructure | Enables AAV trial site activation across Southern and Eastern European referral networks. |
Study Parameters
Direct dialogue with drug development executives, regulatory affairs leads at EMA and FDA, formulary directors at CVS Caremark and OptumRx, and hospital procurement managers at Massachusetts General Hospital and Munich referral centers grounded qualitative insights. Secondary validation drew from FDA orphan drug filings, EMA priority medicines designations, ClinicalTrials.gov AHP protocol registrations, and national porphyria registry publications. Bottom-up patient cohort modeling triangulated against top-down therapy revenue estimates across the analysis window.
Segmentation outputs by treatment modality, delivery route, and care setting combined with attack frequency epidemiology to generate volume and value trajectories. CAGRs derived from patient pool expansion in specialty clinic catchment areas and therapy switching assumptions between acute hemin and prophylactic RNAi. Forecast inputs incorporated PMDA Sakigake designation timelines and EMA adaptive licensing pilot program adoption rates.
The model assumes a particular technology adoption path; alternative pathways for AAV-mediated ALAS1 suppression would alter the outlook if manufacturing yields fail to achieve projected cost reductions. Forecasts reflect assumptions around diagnostic latency improvement and reimbursement pathway consolidation that may shift with biomarker standardization progress. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Marfan Syndrome Treatment Market
Specialty Medicine
Global Scleroderma Therapeutics Market
Specialty Medicine
Glioma Therapeutics Market
Specialty Medicine
Eosinophilic Granulomatosis with Polyangiitis Treatment Market
Specialty Medicine
Global Dry Eye Syndrome Treatment Market
Specialty Medicine
Nephroblastoma Therapeutics Market
Specialty Medicine
Dermatomyositis Treatment Market
Specialty Medicine
Disruptive Behavior Disorder (DBD) Treatment Market
Specialty Medicine
Diamond-Blackfan Anemia Syndrome Therapeutics Market
Specialty Medicine
Global Appendicitis Market
Specialty Medicine
Global Laryngeal Cancer Therapeutics Market
Specialty Medicine
Neuromuscular Disorders Treatment Market
Specialty Medicine
Autism Spectrum Disorder Management Market
Specialty Medicine
Urinary Retention Market
Specialty Medicine
Mantle Cell Lymphoma Market
Specialty Medicine
Behcet's Syndrome Market