
 Neurodegenerative Disorder Market | 2026-2036
Neurodegenerative Disorder Market Size, Share, and Industry Trends Forecast 2026-2036
Neurodegenerative Disorder Market Analytics
Consolidation among hospital purchasing networks is realigning how neurodegenerative therapies reach end users. Pfizer Inc. leverages its primary care infrastructure to sustain broad distribution of symptomatic treatments across integrated delivery networks. Biogen Inc. differentiates through specialized neurology field forces that anchor its presence in academic medical centers. F. Hoffmann-La Roche Ltd competes via diagnostic-therapeutic bundling that extends its footprint in Alzheimer's care pathways.
Neurodegenerative disorders encompass progressive conditions characterized by neuronal loss, protein aggregation pathology, and declining cognitive or motor function, with diagnosis relying on biomarker confirmation through cerebrospinal fluid analysis or PET imaging. The primary commercial purpose centers on slowing disease progression, managing symptoms, and preserving patient functional independence across extended treatment horizons. Disease-modifying therapies command the highest development investment intensity, while symptomatic treatment retains the largest installed revenue base due to established reimbursement and broader prescriber comfort. Gene therapy and stem cell therapy represent the fastest-expanding technology segments, though pharmacotherapy continues to dominate near-term prescription volumes.
The FDA, EMA, and Japan's PMDA collectively govern neurodegenerative drug approval standards, with each regulator tightening evidentiary requirements for surrogate endpoints in Alzheimer's trials. The FDA's accelerated approval framework permits earlier market entry contingent on confirmatory trials, while EMA's benefit-risk reassessment mechanisms and PMDA's sakigake designation system shape competitive timelines across jurisdictions. Stakeholders must monitor how payer evidence requirements evolve alongside regulatory flexibility, as post-approval pricing negotiations increasingly hinge on real-world functional outcomes rather than biomarker changes alone.
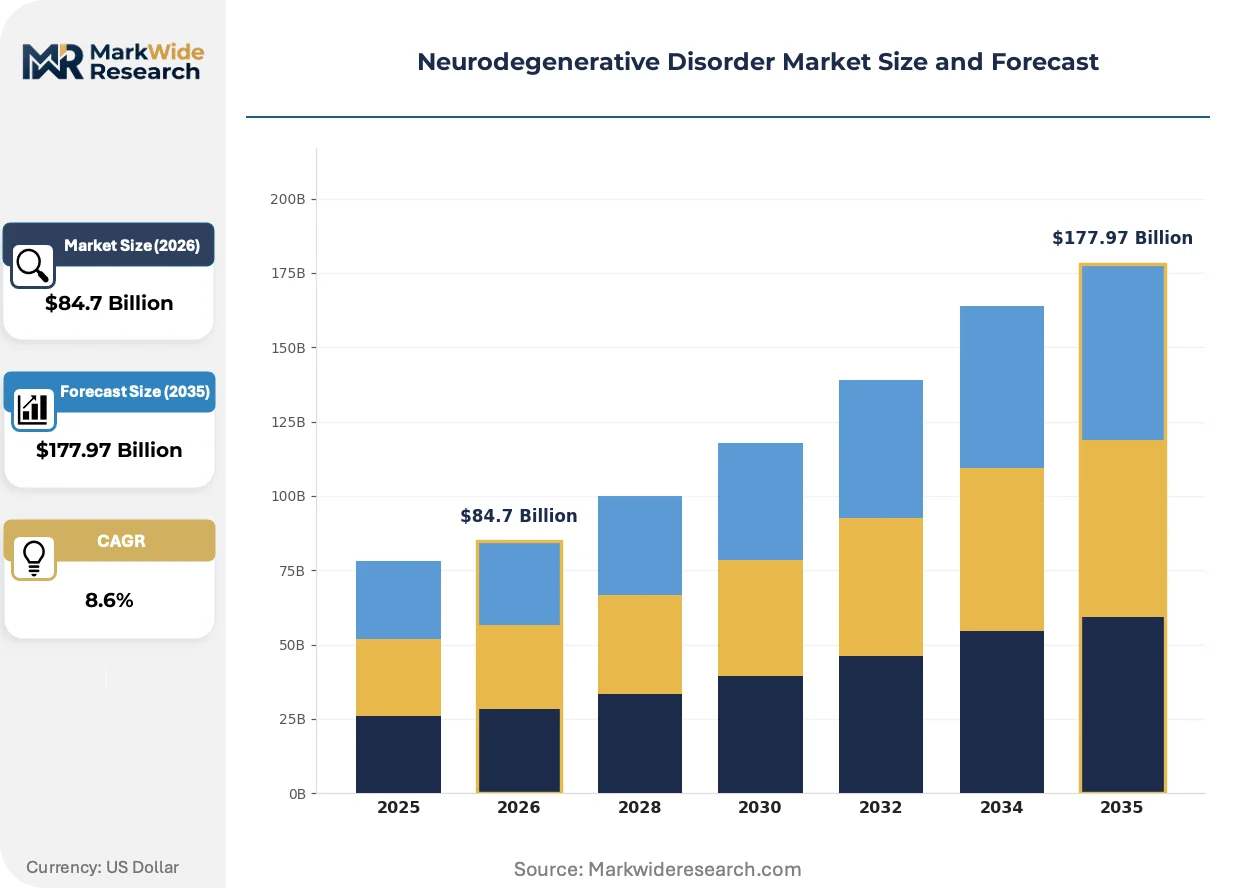
Market Dynamics
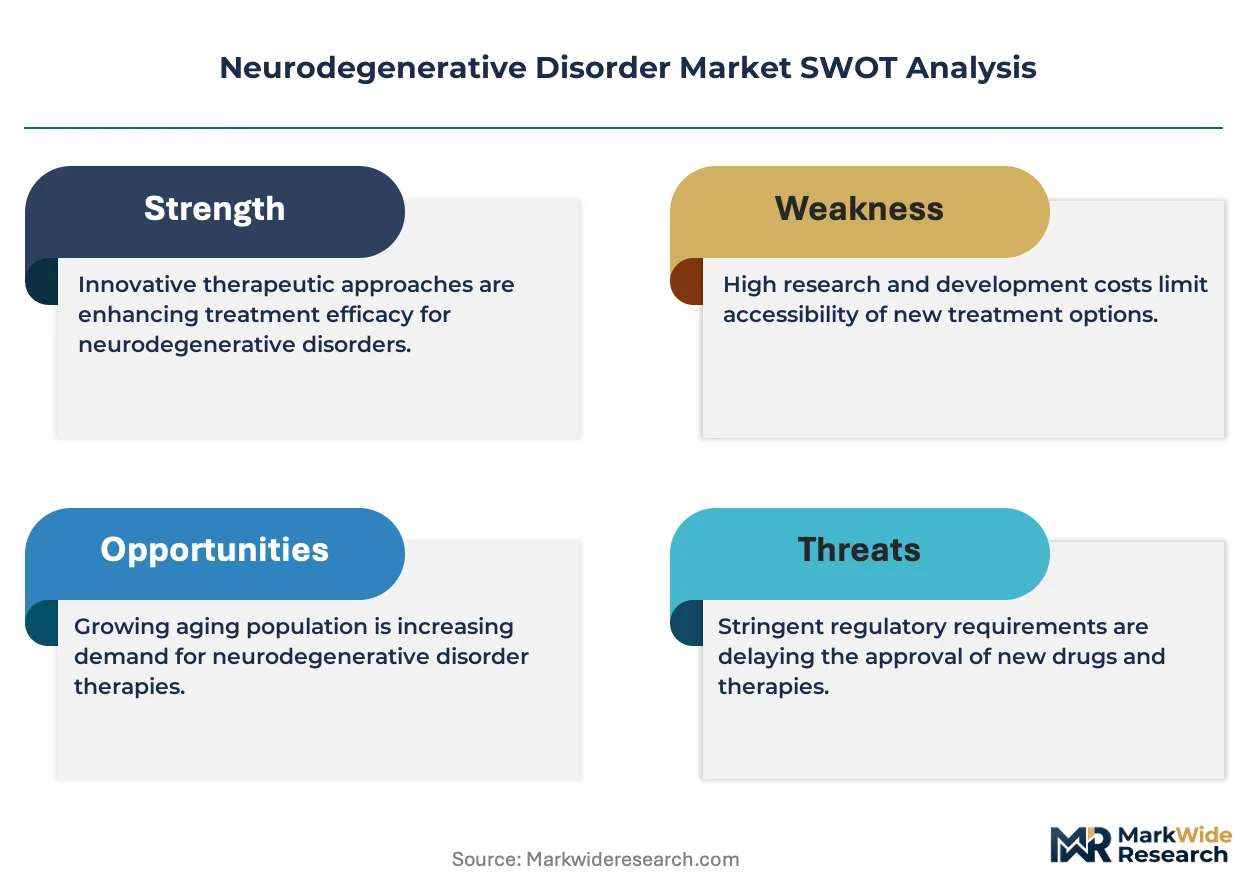
Hospital purchasing network consolidation is compressing distribution margins for neurodegenerative therapeutics while simultaneously elevating the importance of integrated diagnostic-therapeutic bundles in competitive positioning.
Growth Catalysts
- FDA Accelerated Approval Pathway:The framework permits earlier market entry for Alzheimer's therapies contingent on confirmatory trials, compressing development-to-revenue timelines.
- Biomarker-Confirmed Diagnostics:Cerebrospinal fluid analysis and PET imaging are expanding addressable patient pools by enabling pre-symptomatic identification.
- Germany's Reimbursement Framework:Premium therapy access is supported by statutory health insurance coverage for disease-modifying treatments in academic medical centers.
Market Restraints
- Specialized Manufacturing Concentration:Aseptic fill-finish capacity for biologics concentrates among contract manufacturers in Switzerland and Ireland, creating supply vulnerability.
- EMA Benefit-Risk Reassessment Mechanisms:Post-approval regulatory friction escalates when surrogate endpoints fail to translate into functional outcomes in confirmatory trials.
- Small Molecule API Cost Volatility:Active pharmaceutical ingredient synthesis for symptomatic treatments faces input pressure from specialized chemical intermediate suppliers.
Strategic Opportunities
- Japan's Sakigake Designation System:Priority review incentives for regenerative medicines and gene therapies accelerate regulatory timelines for novel modalities.
- Home-Based Administration Channels:Subcutaneous formulations and digital therapeutic monitoring are creating direct-to-patient distribution pathways outside hospital networks.
- Digital Biomarker Convergence:Wearable sensor data combined with machine learning algorithms is enabling remote functional assessment for clinical trial endpoints.
Industry Challenges
- Specialized Neurology Talent Scarcity:Clinical trial investigators with amyloid PET interpretation expertise and gene therapy administration training are concentrated in academic medical centers.
- Legacy EHR Integration Complexity:Biomarker data streams and digital therapeutic platforms require reconfiguration of electronic health record architectures in integrated delivery networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Neurodegenerative Disorder Market |
| Market Size in 2026 | $84.7 Billion |
| Market Size in 2035 | $177.97 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Neuroprotective Agents, Disease-Modifying Therapies, Symptomatic Treatment, Biomarkers Application: Alzheimer's Disease, Parkinson's Disease, Amyotrophic Lateral Sclerosis, Huntington's Disease End User: Hospitals, Clinics, Homecare Settings, Research Institutions Technology: Gene Therapy, Stem Cell Therapy, Pharmacotherapy, Diagnostic Imaging |
| Companies Covered | Pfizer Inc., Johnson & Johnson, F. Hoffmann-La Roche Ltd, AbbVie Inc., Sanofi S.A., Novartis AG, Biogen Inc., Merck & Co. Inc., Eli Lilly and Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Neurodegenerative Disorder Market Evolving Landscape
Gene therapy manufacturing platforms are compressing production economics while regulatory frameworks adapt to novel endpoints. Digital biomarkers and decentralized trial infrastructure are simultaneously reshaping evidence generation and patient access pathways.
Antisense oligonucleotide chemistry is modularizing across neurodegenerative indications, enabling rapid sequence adaptation for tau, C9orf72, and ataxin targets. Academic medical centers in the United States and Japan are adopting these platforms for investigator-initiated trials. This technology is modularizing the traditional drug development timeline by allowing shared manufacturing infrastructure across multiple orphan indications.
The FDA's accelerated approval framework is tightening evidentiary standards for surrogate endpoints in Alzheimer's trials, requiring sponsors to pre-specify functional outcome confirmation strategies. Biogen and Eisai's lecanemab experience has established precedent for accelerated approval contingent on Phase IV commitments. Disease-modifying therapy developers are responding by embedding digital functional assessment tools into confirmatory trial designs.
Integrated delivery networks are consolidating formulary decision-making for neurodegenerative therapeutics, displacing individual physician prescribing autonomy. Hospital purchasing committees in the United States now require health technology assessment submissions for premium therapies. This concentration is most visible in Medicare Advantage plans, where payers are deploying step-therapy protocols and prior authorization requirements for symptomatic treatments.
Neurodegenerative Disorder Market Segmentation
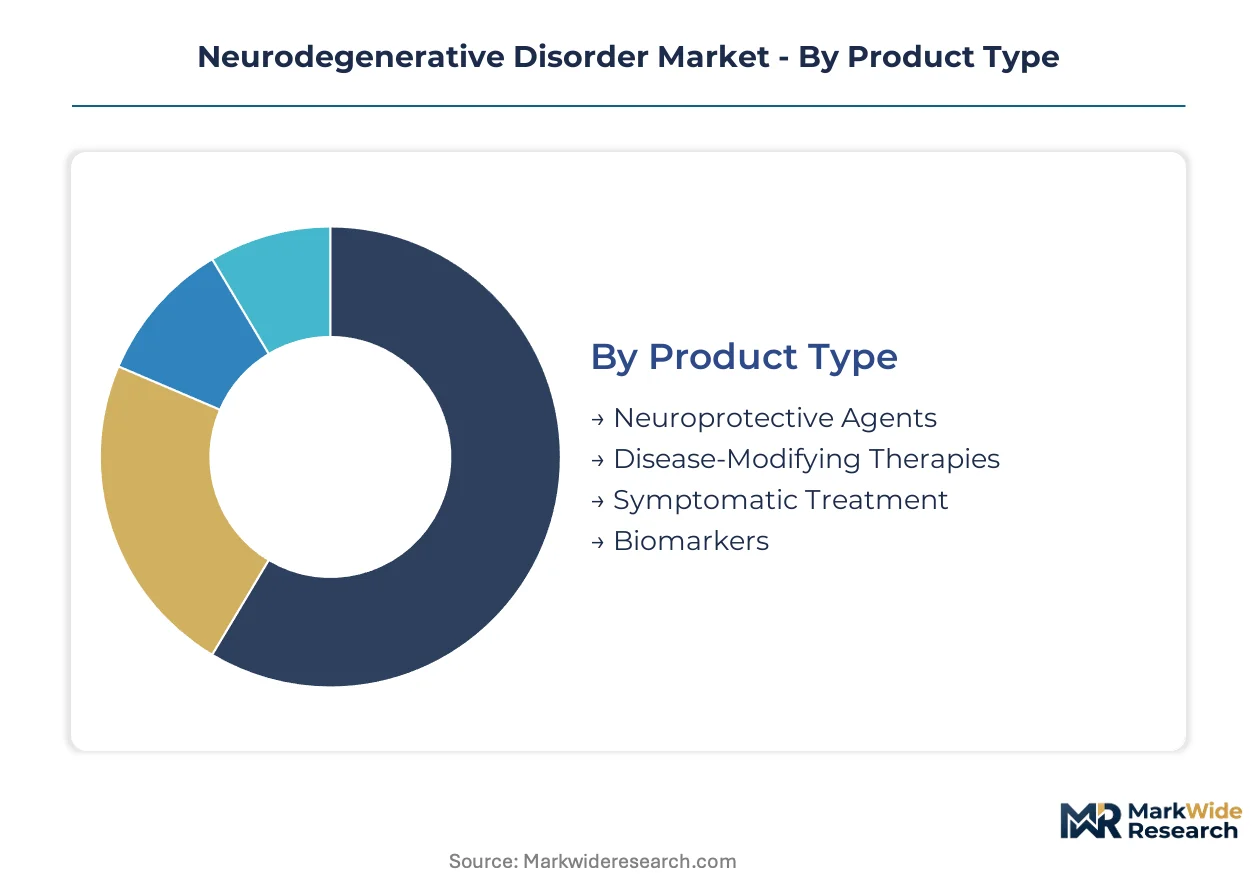
Neurodegenerative therapeutics fragment across therapeutic intent, biological mechanism, and care delivery setting. Each segmentation dimension carries distinct margin profiles, regulatory pathways, and prescriber access requirements that shape commercial strategy.
Product Type:
Customization intensity varies sharply across this category, from standardized small-molecule symptomatic agents to patient-specific gene therapy constructs requiring bespoke manufacturing protocols.
- Disease-Modifying Therapies:These biologics target underlying pathophysiology through amyloid clearance, tau stabilization, or neuroinflammation modulation. Demand clusters in academic medical centers within the United States, Germany, and Japan where reimbursement frameworks support premium pricing contingent on biomarker confirmation.
- Symptomatic Treatment:Small-molecule agents addressing motor dysfunction, cognitive decline, or behavioral symptoms through dopaminergic, cholinergic, or glutamatergic modulation. Volume concentrates in primary care networks and general neurology practices where prescriber familiarity and established formularies sustain broad access.
- Neuroprotective Agents:Compounds designed to interrupt neuronal death cascades prior to irreversible structural damage.
- Biomarkers:Cerebrospinal fluid assays and PET imaging agents enabling pre-symptomatic diagnosis and treatment monitoring.
Most installed capacity flows through Symptomatic Treatment. Expansion is steepest in Disease-Modifying Therapies.
Application:
Patient population scale inversely correlates with biological complexity and unmet medical need across this dimension.
- Alzheimer's Disease:The largest addressable population among neurodegenerative indications, characterized by amyloid and tau pathology driving progressive cognitive impairment. Investment intensity from Biogen, Eisai, and Eli Lilly has concentrated FDA approvals and confirmatory trial infrastructure in the United States.
- Parkinson's Disease:Motor dysfunction through dopaminergic neuron degeneration creates sustained demand for levodopa formulations and emerging gene therapy approaches. Deep brain stimulation device manufacturers and neurology practices in Germany and Japan anchor adoption of advanced interventions.
- Amyotrophic Lateral Sclerosis:Rapidly progressive motor neuron disease with limited therapeutic options and concentrated orphan drug development.
- Huntington's Disease:Inherited polyglutamine repeat disorder with antisense oligonucleotide therapies entering late-stage development.
Revenue concentration remains heaviest in Alzheimer's Disease. Pipeline velocity is accelerating fastest in Amyotrophic Lateral Sclerosis.
End User:
Site-of-care economics and reimbursement mechanics create divergent margin structures across delivery settings.
- Hospitals:Integrated delivery networks consolidate infusion center capacity for biologic administration and complex diagnostic workups. Purchasing committee control over formulary placement intensifies price pressure while privileging vendors with comprehensive diagnostic-therapeutic bundles.
- Homecare Settings:Subcutaneous formulation development and remote patient monitoring technologies are shifting administration outside institutional settings. Medicare Advantage plans in the United States increasingly authorize home infusion for disease-modifying therapies to reduce hospital cost exposure.
- Clinics:Outpatient neurology practices manage stable patients on oral symptomatic regimens with periodic monitoring.
- Research Institutions:Academic medical centers host clinical trials and early-access programs for investigational modalities.
Patient volume still concentrates in Hospitals. Capacity expansion is proceeding most aggressively in Homecare Settings.
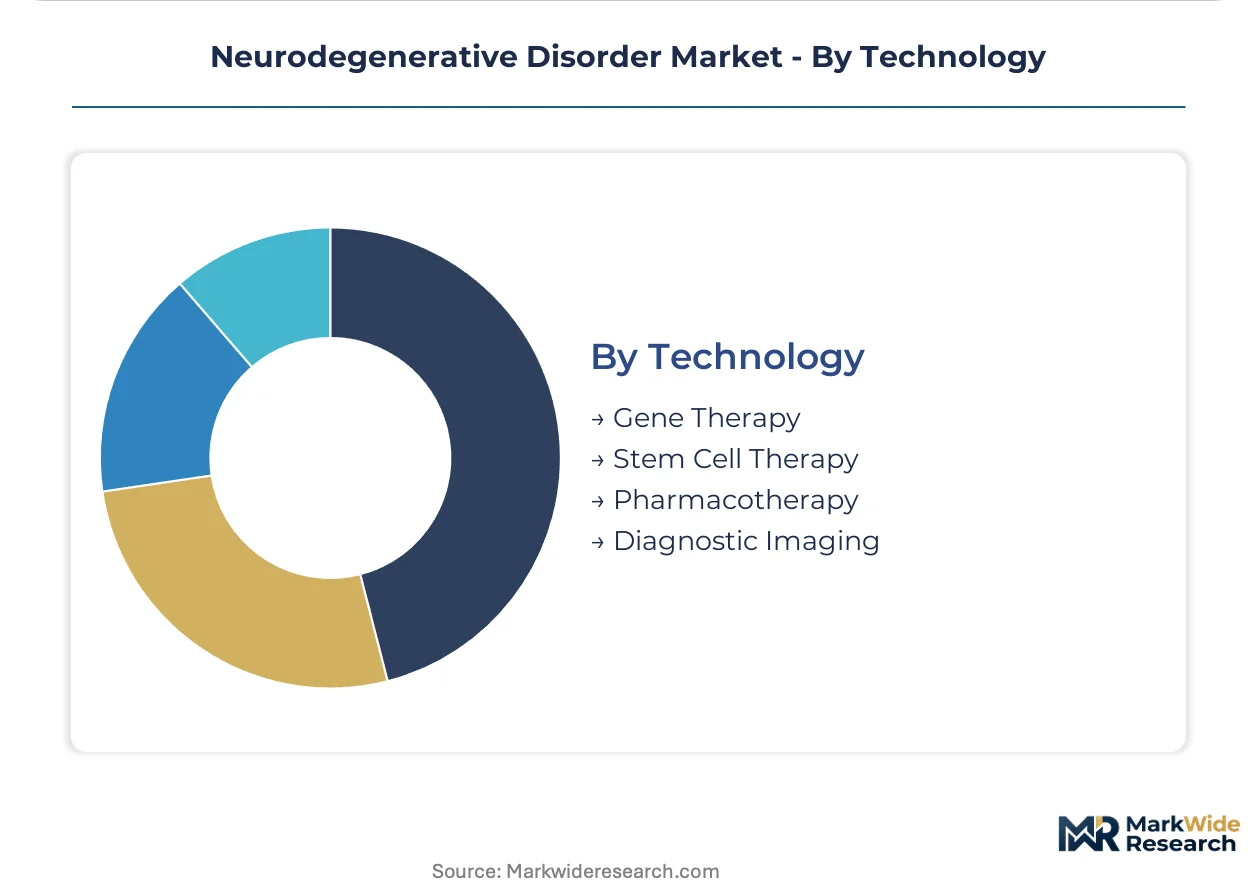
Technology:
Manufacturing sophistication and regulatory novelty separate established pharmacological approaches from emerging platform technologies.
- Gene Therapy:Adeno-associated viral vectors and antisense oligonucleotides enable targeted genetic intervention for inherited forms of ALS, Huntington's, and Parkinson's. Manufacturing capacity constraints in aseptic fill-finish operations concentrate production among contract manufacturers in Switzerland and Ireland.
- Pharmacotherapy:Small-molecule and monoclonal antibody platforms dominate prescription volumes through established synthesis routes and distribution infrastructure. Scale economies in active pharmaceutical ingredient production sustain cost positions for symptomatic agents across generic and branded portfolios.
- Stem Cell Therapy:Pluripotent and neural progenitor cell approaches remain investigational with limited commercial availability.
- Diagnostic Imaging:Amyloid and tau PET tracers enable patient selection and treatment monitoring for disease-modifying trials.
Commercial traction remains anchored in Pharmacotherapy. Platform development investment is concentrating most heavily in Gene Therapy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's PMDA sakigake designation accelerates regenerative medicine approvals faster than Germany's statutory health insurance negotiations enable premium therapy access. Both systems concentrate neurodegenerative clinical trial infrastructure in academic medical centers.
United States
Medicare Advantage plans deploy step-therapy protocols for symptomatic treatments while the FDA's accelerated approval pathway compresses development timelines for Alzheimer's therapies. The Greater Boston cluster anchors amyloid PET interpretation expertise and gene therapy administration training at Massachusetts General Hospital and Brigham and Women's Hospital.
Germany
Statutory health insurance covers disease-modifying treatments in academic medical centers where aging demographics sustain premium therapy demand. The EMA's benefit-risk reassessment mechanisms create post-approval friction when surrogate endpoints fail to translate into functional outcomes. The Munich and Heidelberg clusters concentrate antisense oligonucleotide manufacturing partnerships.
Japan
PMDA's sakigake designation system prioritizes review incentives for regenerative medicines and gene therapies. METI coordinates domestic manufacturing capacity for aseptic fill-finish operations. The Kanto region around Tokyo hosts the highest density of amyloid PET imaging facilities and neurology field forces.
Switzerland
Contract manufacturers concentrate aseptic fill-finish capacity for biologics, creating supply vulnerability but also specialized production expertise. Swissmedic maintains alignment with EMA standards while offering distinct timelines for orphan neurodegenerative indications. The Basel cluster integrates diagnostic-therapeutic bundling for Alzheimer's care pathways.
United Kingdom
NICE technology appraisals determine NHS access to disease-modifying therapies, with real-world evidence requirements tightening post-approval pricing negotiations. The MHRA operates independently from EMA processes since Brexit, creating parallel submission pathways. The Cambridge-London corridor concentrates digital biomarker development and decentralized trial infrastructure.
Neurodegenerative Disorder Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across neurodegenerative therapeutics, creating a tiered structure where scale-driven pharmaceutical holding companies anchor volume while biotechnology specialists capture premium positioning. The market consolidates around three strategic archetypes: primary care infrastructure deployers, specialized neurology field force operators, and diagnostic-therapeutic bundlers. M&A activity concentrates on gene therapy platform acquisitions and antisense oligonucleotide chemistry capabilities, while strategic partnerships focus on digital biomarker co-development and decentralized trial infrastructure.
Among diversified pharmaceutical conglomerates, Pfizer Inc. and Johnson & Johnson exemplify primary care infrastructure deployment archetypes that sustain broad distribution across integrated delivery networks. Within the specialized biotechnology tier, Biogen Inc. occupies a position representing neurology field force concentration in academic medical centers. F. Hoffmann-La Roche Ltd sits within the diagnostic-therapeutic bundling archetype, extending footprint through Alzheimer's care pathway integration.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Johnson & Johnson |
| F. Hoffmann-La Roche Ltd |
| AbbVie Inc. |
| Sanofi S.A. |
| Novartis AG |
| Biogen Inc. |
| Merck & Co. Inc. |
| Eli Lilly and Company |
| Others |
Value Network & Pricing Analysis
Captive manufacturing of aseptic fill-finish capacity in Switzerland and Ireland anchors supply positions for biologic neurodegenerative therapies while simultaneously underwriting pricing power for contract development and manufacturing organizations serving branded developers. This integration pattern concentrates cost leverage among European production hubs and amplifies margin pressure on developers lacking backward integration into specialized biologics manufacturing.
Pricing Analysis
Capacity additions in Switzerland are reshaping price floors for gene therapy manufacturing while contract manufacturers consolidate bargaining power. Three-tier pricing structure across premium disease-modifying biologics, standard symptomatic small molecules, and economy generic dopaminergic agents dominates procurement negotiations. Pricing pressure stems from hospital purchasing committee consolidation in the United States demanding health technology assessment submissions. Academic medical centers exhibit lowest price sensitivity due to statutory reimbursement frameworks, while primary care networks face highest sensitivity under Medicare Advantage step-therapy protocols.
Supply Chain Analysis
Single-source vulnerability sits with Swiss and Irish contract manufacturers controlling aseptic fill-finish capacity for monoclonal antibodies and gene therapy vectors. Raw material dependencies include specialized chemical intermediates from India, recombinant cell lines from the United States, and PET imaging isotopes from cyclotron facilities in Germany and Japan. Supply chain risk centers on regulatory restriction from EMA benefit-risk reassessment mechanisms disrupting batch releases. Distribution runs through integrated delivery network infusion centers consolidating formulary decision-making for biologic administration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Neurodegenerative Disorder Market represents a late-cycle quality story as demand shifts decisively toward biomarker-confirmed disease-modifying therapies commanding premium reimbursement in academic medical centers.
For Market Incumbents: Anticipate margin compression from hospital purchasing network consolidation by embedding diagnostic-therapeutic bundling capabilities and securing captive aseptic fill-finish capacity in Switzerland or Ireland. Counter antisense oligonucleotide platform threats from emerging biotechnology specialists through targeted gene therapy manufacturing acquisitions. Prioritize backward integration into PET imaging agent production to anchor Alzheimer's care pathway control. For New Entrants and Emerging Players: FDA's accelerated approval pathway in the United States opens a window for digital biomarker-enabled trial designs that compress development timelines against established players. White-space targets include homecare administration channels for subcutaneous formulations and decentralized clinical trial infrastructure serving Medicare Advantage populations. Penetrate through investigator-initiated trial partnerships at Massachusetts General Hospital and Brigham and Women's Hospital leveraging existing amyloid PET expertise. For Investors and Strategic Acquirers: Roll-up economics work for antisense oligonucleotide platform specialists because modular chemistry across tau, C9orf72, and ataxin targets enables shared manufacturing infrastructure and rapid indication expansion. Long-term viability hinges on 5-10 year regulatory framework stability for surrogate endpoint acceptance. Target acquisition archetypes include digital biomarker developers with FDA-qualified drug development tools. Watch for inflection when confirmatory trial readouts from lecanemab-class therapies validate real-world functional outcomes as reimbursement currency.| Strategic Initiative | Industry Significance |
|---|---|
| Diagnostic-Therapeutic Bundling | Roche's Alzheimer's care pathway integration secures formulary placement through PET imaging anchoring. |
| Gene Therapy Platform Acquisition | Antisense oligonucleotide chemistry capabilities enable rapid sequence adaptation across orphan neurodegenerative indications. |
| Home-Based Administration Development | Subcutaneous formulations bypass hospital purchasing committee control and reduce Medicare Advantage cost exposure. |
| Digital Biomarker Co-Development | Wearable sensor data combined with machine learning enables remote functional assessment for FDA confirmatory trials. |
| Aseptic Fill-Finish Capacity Expansion | Switzerland and Ireland contract manufacturers concentrate biologic production expertise creating supply scarcity leverage. |
Research Methodology
Coverage spans the United States, Germany, Japan, Switzerland, and the United Kingdom, with primary inputs from each market's academic medical centers and regulatory agencies. Primary interviews engaged drug development executives at biotechnology firms, regulatory affairs leads navigating FDA and EMA accelerated approval frameworks, hospital procurement managers within integrated delivery networks, and payer access specialists at Medicare Advantage plans. Secondary validation drew from FDA filings, EMA submission documents, ClinicalTrials.gov protocol registries, and hospital formulary databases. Bottom-up patient population modeling and top-down revenue triangulation anchored market size estimates.
Granularity-level modeling operated at the intersection of therapeutic intent, biological mechanism, and care delivery setting across the projection horizon. Segmentation dimensions included disease-modifying versus symptomatic treatment lines, small-molecule versus biologic dosage forms, intravenous versus subcutaneous administration routes, and regional regulatory clusters reflecting FDA, EMA, and PMDA approval pathways. CAGRs were derived from epidemiological trend analysis, pricing trajectory assessment, and technology adoption curve modeling. Forecast inputs incorporated amyloid PET imaging facility expansion rates and gene therapy manufacturing capacity utilization.
Revisions become necessary when surrogate endpoint evidentiary standards tighten materially, confirmatory trial readouts fail to demonstrate functional outcomes, or hospital purchasing network consolidation accelerates beyond modeled thresholds. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Global Hypoparathyroidism Treatment Market
Specialty Medicine
Metabolic Disorders Therapeutics Market
Specialty Medicine
Global Multiple Sclerosis Therapeutics Market
Specialty Medicine
Hidradenitis Suppurativa (HS) Treatment Market
Specialty Medicine
Piriformis Syndrome Market
Specialty Medicine
Klinefelter Syndrome Treatment Market
Specialty Medicine
Pemphigus Vulgaris (PV) Treatment Market
Specialty Medicine
Ulcerative Colitis Therapeutics Market
Specialty Medicine
Kaposi Sarcoma Market
Specialty Medicine
GCC Idiopathic Pulmonary Fibrosis Treatment Market
Specialty Medicine
Buruli Ulcer Treatment Market
Specialty Medicine
Global Lupus Market
Specialty Medicine
Treatment-Resistance Depression Treatment Market
Specialty Medicine
Veno-Occlusive Hepatic Disease Therapeutics Market
Specialty Medicine
Global Lichen Nitidus Treatment Market
Specialty Medicine
Hunter Syndrome Treatment Market