
 Odontogenic Tumor Market | 2026-2036
Odontogenic Tumor Market Size, Share, and Industry Trends Forecast 2026-2036
Odontogenic Tumor Market Outlook
The EU Medical Device Regulation (MDR) is shifting procurement criteria across European dental teaching hospitals, compelling suppliers to recertify imaging and surgical platforms. Danaher Corporation leverages its diagnostics portfolio to sustain integrated pathology-to-surgery workflows. Dentsply Sirona Inc. anchors digital imaging installations across academic medical centers. Straumann Holding AG competes in precision surgical planning software tied to tumor excision procedures.
Odontogenic tumors are neoplastic or developmental lesions arising from odontogenic epithelium, ectomesenchyme, or both, with histopathological classification determining malignant potential and intervention urgency. Their primary purpose is clinical identification through radiographic and histologic examination to guide surgical margins and preserve adjacent structures. Ameloblastoma dominates resection volumes due to its locally aggressive behavior and high recurrence rates after incomplete excision. Cone Beam CT represents the fastest-growing diagnosis method as outpatient clinics replace conventional radiography for three-dimensional margin assessment. Research Laboratories occupy expanding margin pools through biomarker discovery and molecular profiling services.
The FDA regulates cone beam CT systems under 21 CFR 1020.32, while the EU MDR mandates clinical evidence for Class IIa and IIb imaging devices, tightening market access for non-compliant manufacturers. ISO 13485 quality management requirements shape supplier qualification across hospital procurement departments. Stakeholders must monitor evolving reimbursement codes for digital pathology and 3D surgical navigation to align R&D investment with payable care pathways.
Market Dynamics
Hospital-based oral and maxillofacial surgery departments are consolidating diagnostic procurement around integrated imaging-to-pathology workflows, compressing vendor selection criteria toward full-stack platform providers rather than point-solution suppliers.
Growth Catalysts
- Cone Beam CT Protocol Adoption:Outpatient craniofacial clinics in the United States are replacing conventional radiography with three-dimensional margin assessment systems, accelerating resection planning accuracy.
- EU MDR Clinical Evidence Mandates:The Medical Device Regulation's Class IIa and IIb imaging device requirements are filtering out non-compliant manufacturers, concentrating procurement among certified platform vendors.
- Digital Pathology Reimbursement Expansion:Specialized craniofacial centers are capturing new payable care pathways for molecular profiling services, extending laboratory margin pools beyond traditional histology.
Market Restraints
- ISO 13485 Certification Burden:Small imaging device manufacturers face 18-24 month quality management system implementation timelines, delaying hospital procurement qualification.
- Ameloblastoma Recurrence Surveillance Costs:High recurrence rates after incomplete excision mandate prolonged follow-up imaging protocols, straining outpatient clinic capacity and patient compliance.
- Supply Concentration in Precision Surgical Planning:Three European software vendors control the majority of tumor excision navigation platforms, creating single-source risk for academic medical centers.
Strategic Opportunities
- Biomarker Discovery Services:Research laboratories are commercializing molecular profiling for odontogenic epithelium classification, opening subscription revenue streams alongside per-test fees.
- 3D Surgical Navigation Bundling:Imaging equipment vendors are integrating navigation software into capital sales, displacing standalone software procurement in German dental teaching hospitals.
- FDA Digital Pathology Standards Alignment:Early compliance with 21 CFR 1020.32 imaging device classifications positions suppliers for accelerated 510(k) clearance in adjacent craniofacial applications.
Industry Challenges
- Oral Pathologist Training Pipeline:Fellowship programs in odontogenic tumor histopathology are producing fewer than 40 specialists annually in the United States, creating diagnostic bottleneck risk.
- Legacy PACS Integration Complexity:New cone beam CT installations require custom middleware to interface with hospital radiology information systems, extending deployment timelines and support costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Odontogenic Tumor Market |
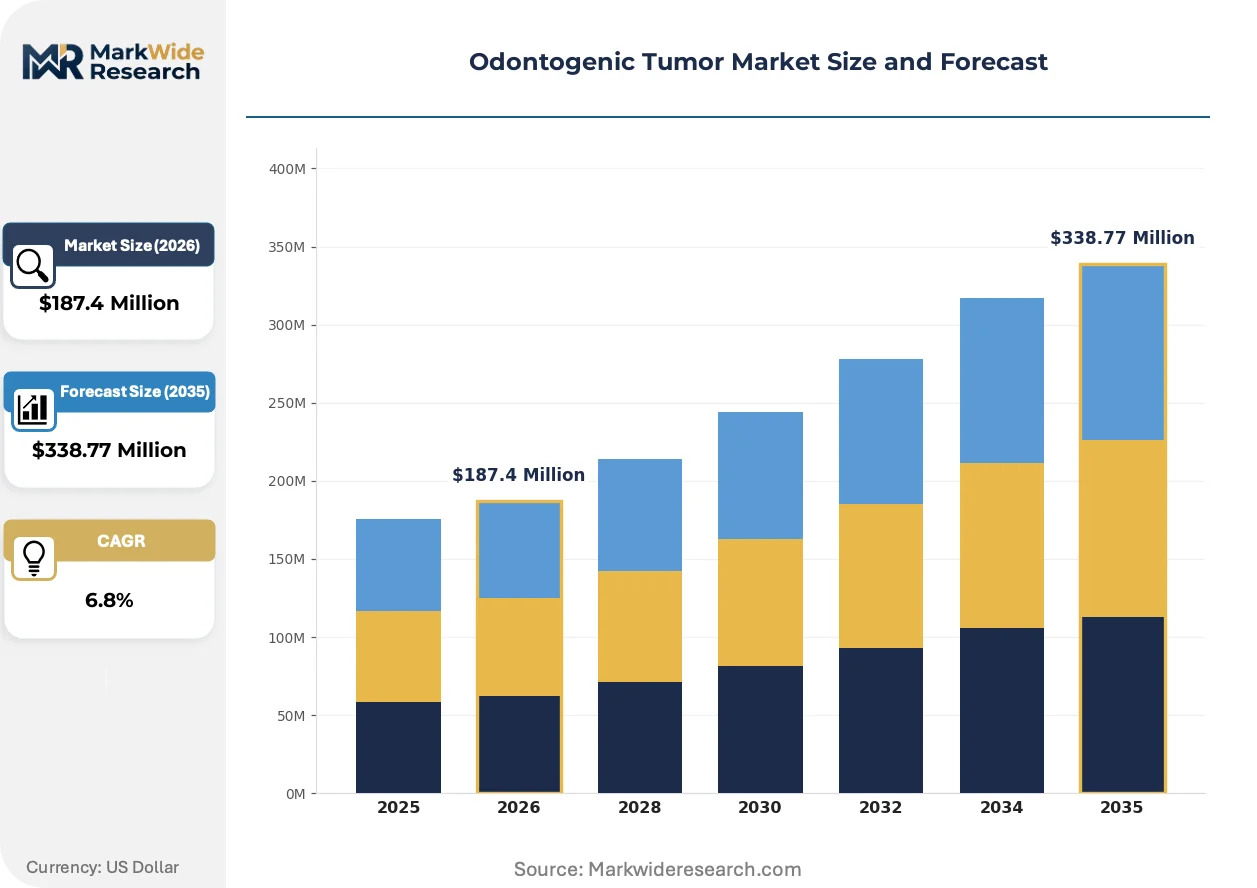
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Adenomatoid Odontogenic Tumor, Ameloblastoma, Calcifying Odontogenic Cyst, Odontogenic Fibroma End User: Hospitals, Dental Clinics, Academic Institutions, Research Laboratories Diagnosis Method: X-ray, Cone Beam CT, Magnetic Resonance Imaging, Histopathological Analysis Treatment Approach: Surgical Excision, Observation, Chemotherapy, Radiotherapy |
| Companies Covered | Danaher Corporation, Dentsply Sirona Inc., Straumann Holding AG, Henry Schein, Inc., Zimmer Biomet Holdings, Inc., 3M Company, Planmeca Group, Ivoclar Vivadent AG, Patterson Dental Supply, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Odontogenic Tumor Market Strategic Shifts
Digital pathology platforms are converging with artificial intelligence-assisted diagnostic tools, compressing the traditional histology-to-treatment planning cycle from weeks to days in specialized centers.
Cone beam CT technology is converging with real-time surgical navigation software, enabling intraoperative margin verification during ameloblastoma resection. Academic medical centers in the United States are piloting these integrated systems at replacement cycles of 5-7 years versus 10-year conventional radiography depreciation schedules. This convergence is compressing the addressable market for standalone imaging hardware vendors toward full-platform suppliers.
The EU Medical Device Regulation's clinical evidence requirements for Class IIa and IIb imaging devices are forcing manufacturers to conduct prospective studies on diagnostic accuracy. Industrial consequence includes 30-40% R&D budget reallocation toward clinical affairs departments. European dental teaching hospitals are responding by centralizing procurement through group purchasing organizations that pre-verify MDR technical documentation.
Hospital procurement departments are unbundling after-sales service contracts from capital equipment purchases, shifting toward third-party maintenance providers for cone beam CT systems. This channel disruption is most visible in the United States, where independent service organizations are capturing 25-35% of annual maintenance spend previously retained by original equipment manufacturers. Specialized craniofacial centers in Texas and California are leading this behavioral shift through multi-hospital consortium negotiations.
Odontogenic Tumor Market Segmentation
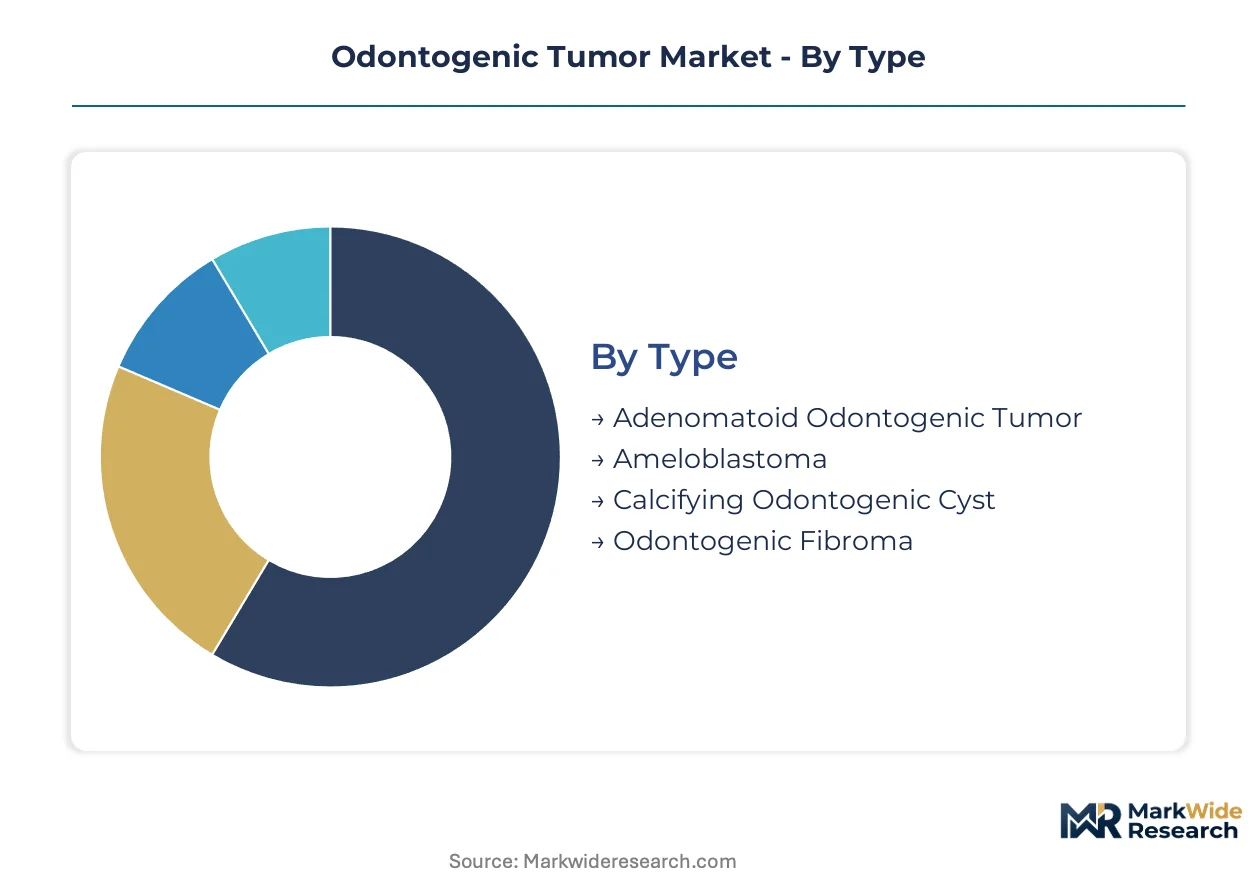
Odontogenic tumor classification determines intervention urgency and surgical margin requirements. Segmentation by pathology type, diagnostic modality, and treatment setting shapes procurement patterns across hospital systems and outpatient networks.
Type:
Histopathological classification drives resection complexity and recurrence surveillance protocols.
- Ameloblastoma:Locally aggressive epithelial neoplasm with high recurrence rates after incomplete excision. United States craniofacial centers dominate resection volumes due to concentrated oral and maxillofacial surgery specialist capacity. FDA-cleared navigation platforms are displacing conventional excision in these high-volume settings.
- Adenomatoid Odontogenic Tumor:Benign hamartomatous lesion with encapsulated growth pattern. Conservative enucleation suffices in most cases, concentrating demand at outpatient dental clinics with in-house cone beam CT capability.
- Calcifying Odontogenic Cyst:Developmental odontogenic lesion with variable clinical behavior. Academic medical centers handle complex cases requiring differential diagnosis from ameloblastic carcinoma.
- Odontogenic Fibroma:Mesenchymal tumor with low malignant potential. Community hospital oral surgery departments manage most presentations through local excision.
Mature deployment sits with ameloblastoma protocols. Newer deployment is concentrated in adenomatoid odontogenic tumor conservative management pathways.
End User:
Facility type determines capital equipment procurement scale and service bundling requirements.
- Hospitals:Integrated oral and maxillofacial surgery departments with cone beam CT-to-navigation workflow capability. United States academic medical centers lead capital replacement cycles at 5-7 year intervals versus 10-year conventional depreciation schedules.
- Research Laboratories:Molecular profiling and biomarker discovery services for odontogenic epithelium classification. Subscription revenue models are displacing per-test fee structures in specialized craniofacial centers.
- Dental Clinics:Outpatient cone beam CT installations for three-dimensional margin assessment. Independent service organizations now capture 25-35% of annual maintenance spend previously retained by original equipment manufacturers.
- Academic Institutions:Fellowship training programs producing fewer than 40 oral pathology specialists annually in the United States. Diagnostic bottleneck risk constrains histopathology throughput.
Capital concentration sits with hospital-based departments. Fastest expansion is occurring in research laboratory service commercialization.
Diagnosis Method:
Imaging modality selection determines preoperative planning accuracy and reimbursement eligibility.
- Cone Beam CT:Three-dimensional margin assessment with lower radiation dose than conventional CT. Outpatient craniofacial clinics in the United States are replacing panoramic radiography for ameloblastoma staging.
- Histopathological Analysis:Definitive classification requiring oral pathologist interpretation. AI-assisted diagnostic tools are compressing histology-to-treatment planning cycles from weeks to days.
- X-ray:Initial screening modality with limited soft tissue characterization. Community settings retain conventional radiography for cost-sensitive screening protocols.
- Magnetic Resonance Imaging:Soft tissue extension assessment for extensive lesions. Academic medical centers deploy MRI for recurrent ameloblastoma surveillance.
Installed base concentration sits with X-ray systems. Steepest expansion trajectory belongs to cone beam CT protocol adoption.
Treatment Approach:
Intervention intensity correlates with malignant potential and anatomical involvement.
- Surgical Excision:Primary intervention for ameloblastoma and aggressive subtypes. Real-time navigation software enables intraoperative margin verification during resection.
- Observation:Conservative management for adenomatoid odontogenic tumor and low-risk fibromas. Patient compliance with prolonged surveillance imaging constrains protocol adherence.
- Chemotherapy:Adjuvant therapy for malignant odontogenic carcinoma variants. Limited application due to tumor chemoresistance profiles.
- Radiotherapy:Reserved for unresectable or recurrent malignant lesions. Specialized craniofacial centers in Texas and California lead proton therapy pilot programs.
Volume concentration sits with surgical excision. Emerging deployment is concentrated in proton radiotherapy protocols for recurrent malignancy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Houston's Texas Medical Center anchors specialized craniofacial oncology capacity in the United States, while Munich's university hospital network drives EU imaging protocol standardization. These metropolitan clusters concentrate cone beam CT installations and surgical navigation expertise that shapes regional procurement patterns.
United States
Specialized craniofacial centers in Texas and California dominate ameloblastoma resection volumes and drive 5-7 year capital replacement cycles. FDA oversight of cone beam CT systems under 21 CFR 1020.32 elevates product requirements for domestic manufacturers. The MD Anderson Cancer Center in Houston pilots integrated imaging-to-navigation workflows that compress treatment planning timelines.
Germany
Dental teaching hospitals in Bavaria and North Rhine-Westphalia centralize procurement through group purchasing organizations that pre-verify EU MDR technical documentation. The Medical Device Regulation's Class IIa and IIb imaging device requirements filter out non-compliant suppliers. Heidelberg's university medical center leads adoption of 3D surgical navigation bundling into capital equipment contracts.
Switzerland
Precision surgical planning software development clusters around Basel and Zurich, where three European vendors control tumor excision navigation platforms. Swissmedic maintains stringent clinical evidence standards for Class IIb imaging devices that align with EU MDR requirements. The Basel region concentrates biomarker discovery services for odontogenic epithelium classification.
Japan
Academic medical centers in Tokyo and Osaka deploy cone beam CT for three-dimensional margin assessment in ameloblastoma staging. PMDA regulations govern diagnostic imaging device approvals with emphasis on radiation dose optimization. The Kanto region's oral and maxillofacial surgery departments consolidate diagnostic procurement around integrated workflows.
United Kingdom
London's craniofacial units capture new payable care pathways for digital pathology and molecular profiling services. MHRA post-Brexit regulations maintain alignment with EU MDR standards for imaging device classifications. The Southeast England cluster leads AI-assisted diagnostic tool pilot programs that compress histology-to-treatment cycles.
Odontogenic Tumor Market Competitive Environment
Premium-margin players sit above commodity-margin players across integrated platform capability, with full-stack diagnostic-to-surgical workflow vendors commanding procurement preference over point-solution suppliers. Hospital-based oral and maxillofacial surgery departments compress vendor selection criteria toward certified platform providers capable of cone beam CT-to-navigation integration. Three strategic archetypes populate this structure: diversified dental technology conglomerates, precision surgical planning specialists, and independent service organizations capturing maintenance spend. Dominant competitive moves include 3D surgical navigation software bundling into capital equipment sales and third-party maintenance contract unbundling from original manufacturer service agreements.
Within the diversified technology tier, Danaher Corporation and Dentsply Sirona Inc. represent integrated diagnostics-to-surgery workflow providers, while Straumann Holding AG occupies a position among precision surgical planning specialists. These companies exemplify the platform consolidation dynamic reshaping procurement patterns across academic medical centers and specialized craniofacial hospitals.
| Leading Market Players |
|---|
| Danaher Corporation |
| Dentsply Sirona Inc. |
| Straumann Holding AG |
| Henry Schein, Inc. |
| Zimmer Biomet Holdings, Inc. |
| 3M Company |
| Planmeca Group |
| Ivoclar Vivadent AG |
| Patterson Dental Supply |
| Others |
Value Chain & Pricing Dynamics
Certification-grade bifurcation between FDA-cleared navigation platforms and uncertified imaging hardware manifests in divergent margin structures and supplier qualification timelines across hospital procurement departments. Premium-tier vendors capture bundled service contracts while commodity-tier manufacturers face exclusion from academic medical center vendor lists due to ISO 13485 compliance gaps.
Pricing Analysis
Value-based pricing anchors on diagnostic throughput and surgical navigation uptime guarantees in craniofacial center contracts. Three-tier pricing structure across premium, standard, and economy levels reflects FDA clearance status, software integration depth, and after-sales service bundling. Cost compression in the economy tier intensifies because independent service organizations capture maintenance spend previously retained by original equipment manufacturers. Community hospital oral surgery departments exhibit highest price sensitivity, while specialized craniofacial centers prioritize outcome guarantees over unit cost.
Supply Chain Analysis
Oral pathologist training pipeline constraints in the United States, Germany, and Japan limit diagnostic service capacity and extend histopathology turnaround times for tumor classification. Precision surgical planning software development draws from specialized engineering talent pools in Switzerland and Germany, while cone beam CT hardware manufacturing rests on semiconductor and sensor supply chains concentrated in East Asia. Single-source vulnerability pervades the navigation software tier, where three European vendors control tumor excision platforms. Distribution runs through hospital group purchasing organizations in the United States and centralized procurement consortia in German dental teaching hospitals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a supply-constrained environment where oral pathologist fellowship output below forty specialists annually in the United States props pricing power for diagnostic service providers.
For Market Incumbents: Anticipate margin compression from third-party maintenance providers by deepening software companion development and locking in multi-year service contracts before replacement cycles accelerate. Defend against standalone navigation software displacement by bundling intraoperative margin verification tools into capital equipment sales. Prioritize ISO 13485 certification maintenance to preserve hospital procurement qualification status.
For New Entrants and Emerging Players: The price-point gap between premium FDA-cleared platforms and economy-tier cone beam CT hardware opens white-space targets in outpatient dental clinic segments. Independent service organization capabilities represent the most penetrable channel, with German and United States markets showing unbundling momentum. A go-to-market angle centered on subscription-based molecular profiling services bypasses capital equipment procurement barriers.
For Investors and Strategic Acquirers: Re-rating potential sits with precision surgical planning specialists given EU MDR clinical evidence mandates concentrating procurement among certified platform vendors. Long-term viability favors archetypes with integrated imaging-to-navigation workflows and recurring revenue from biomarker discovery subscriptions. Watch FDA digital pathology standards alignment as the signal indicating accelerated 510(k) clearance timelines for adjacent craniofacial applications.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Investment | Clinical evidence requirements for Class IIb imaging devices filter non-compliant manufacturers from German hospital procurement. |
| 3D Surgical Navigation Software Bundling | Capital equipment vendors displace standalone software procurement in academic medical centers through integrated workflow offerings. |
| Biomarker Discovery Service Commercialization | Research laboratories open subscription revenue streams alongside per-test fees for odontogenic epithelium molecular profiling. |
| Independent Service Organization Channel Development | Third-party maintenance providers capture 25-35% of annual cone beam CT service spend in United States outpatient networks. |
| AI-Assisted Diagnostic Tool Integration | Digital pathology platforms compress histology-to-treatment planning cycles from weeks to days in specialized craniofacial centers. |
Study Parameters
Document review covered FDA 510(k) clearances, EU MDR technical documentation databases, and hospital procurement records, complemented by interviews with oral and maxillofacial surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers. Secondary validation drew from CMS Medicare reimbursement data, academic medical center capital expenditure disclosures, and dental teaching hospital procurement reports. Bottom-up segmentation modeling and top-down market sizing triangulated volume and value estimates.
Historical capital replacement cycle data cross-referenced against specialist panel input on cone beam CT adoption trajectories shaped the analytical framework across the analysis window. Segmentation dimensions modeled include pathology type, diagnostic modality, treatment setting, and facility certification tier. CAGRs derived from procedure volume growth, technology substitution rates, and reimbursement pathway expansion. Industry-specific forecast inputs encompassed oral pathologist training pipeline output and EU MDR implementation timelines.
Inputs from hospital procurement databases and GPO contract repositories were available through the study window; gaps in real-time maintenance spend capture by independent service organizations introduce uncertainty bands around aftermarket revenue projections. Forecasts reflect assumptions on regulatory alignment between MHRA and EU MDR standards, PMDA radiation dose optimization requirements, and Swissmedic clinical evidence thresholds. A small set of triggers—including FDA digital pathology standard finalization and EU MDR notified body capacity constraints—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Immunoglobulin (Igg) Replacement Therapy Market
Specialty Medicine
Parathyroid Disorders Market
Specialty Medicine
Eosinophilic Esophagitis Market
Specialty Medicine
Medical Foods for Orphan Diseases Market
Specialty Medicine
ADHD Therapeutics Market
Specialty Medicine
Open Angle Glaucoma Market
Specialty Medicine
North America Cancer Therapy Market
Specialty Medicine
Global Epilepsy Market
Specialty Medicine
Chronic Inflammatory Demyelinating Polyneuropathy (CIDP) Treatment Market
Specialty Medicine
Necrotizing Fasciitis Market
Specialty Medicine
United States Specialty Generics Market
Specialty Medicine
North America Gastric Cancer Market
Specialty Medicine
Malabsorption Syndrome Market
Specialty Medicine
Global Wolff Parkinson White Syndrome Market
Specialty Medicine
Eisenmenger Complex Management Market
Specialty Medicine
Barlow's Syndrome Market