
 Ilmenite Market | 2026-2036
Ilmenite Market Size, Share, and Industry Trends Forecast 2026-2036
Ilmenite Market Outlook
Pigment manufacturers are bifurcating from steel-sector buyers as titanium dioxide feedstock quality requirements tighten. Iluka Resources leverages its synthetic rutile upgrading technology to capture premium chloride-route demand. Rio Tinto sustains long-haul supply contracts through its integrated Quebec operations and Atlantic shipping network. Kenmare Resources anchors East African volume with dredge mining at Moma, while Richards Bay Minerals competes on TiO2 grade consistency from South African coastal deposits.
Ilmenite is a titanium-iron oxide mineral with the formula FeTiO3, typically containing 45-55% TiO2 in its natural form and serving as the dominant feedstock for titanium metal and pigment production through sulfate or chloride processing routes. Natural ilmenite dominates raw material flows into sulfate-route TiO2 plants across Asia, while upgraded ilmenite commands structural premiums as chloride-route expansions in the Middle East and China require higher-grade feedstock with controlled impurity profiles. Synthetic ilmenite occupies a narrow specialty niche where chemical consistency outweighs unit cost, and powder form leads industrial consumption due to faster dissolution kinetics in sulfuric acid digestion circuits.
China's MEE enforces stricter tailings discharge limits on domestic mining operations, pushing ore processors toward imported upgraded material with lower heavy metal content. India's CEA and state pollution control boards are tightening coastal mineral concession rules for beach sand operations in Tamil Nadu and Kerala, constraining V.V. Mineral and The Kerala Minerals and Metals expansion timelines. Australia's EPA frameworks in Western Australia govern Rio Tinto and Iluka Resources rehabilitation bonds, embedding compliance costs into long-term supply contracts. Stakeholders must track how carbon border adjustments and TiO2 slag capacity decisions in Saudi Arabia and China redirect ilmenite grade premiums before committing to upstream mining investments.
Market Dynamics
Chloride-route titanium dioxide plants are forcing a bifurcation in feedstock quality tiers, squeezing natural ilmenite suppliers while rewarding upgraded material processors with premium offtake agreements.
Growth Catalysts
- Dual carbon goals:China's MEE mandates drive ore processors toward imported upgraded ilmenite with lower chromium and heavy metal content, redirecting procurement toward compliant suppliers.
- Beach sand mining:India's coastal mineral concessions in Tamil Nadu and Kerala sustain dredge-based production volumes for sulfate-route pigment plants serving domestic coatings demand.
- Synthetic rutile upgrading:Acid-leach and reduction technologies enable 90%+ TiO2 products that command structural premiums from Middle Eastern chloride-route expansions.
Market Restraints
- Slag capacity tightness:Limited chloride-route slag output from South African and Canadian smelters concentrates high-grade feedstock supply among three integrated producers.
- Tailings compliance costs:Australia's EPA rehabilitation bond requirements in Western Australia embed multi-year liability reserves into project economics, elevating breakeven thresholds.
- Rutile substitution:Natural and synthetic rutile grades above 95% TiO2 capture premium chloride-route demand that upgraded ilmenite cannot satisfy, capping price ceilings.
Strategic Opportunities
- Saudi Arabia TiO2 slag investments:Greenfield chloride-route capacity planned for the Gulf creates captive demand for imported high-grade ilmenite with controlled calcium and magnesium levels.
- India's PLI scheme:Domestic pigment production incentives under the chemical sector performance-linked initiative attract integrated mine-to-pigment investments in coastal Odisha and Gujarat.
- Direct shipping ore channels:Bulk vessel contracts from Mozambican and Senegalese deposits bypass traditional trader intermediaries, compressing delivered cost to Chinese processors.
Industry Challenges
- Metallurgical testwork timelines:Chloride-route qualification protocols require 18-24 month digestion trials at Saudi and Chinese pigment plants before volume contracts activate.
- Dredge fleet maintenance:Kenmare Resources and other marine operators face compressed dry-dock schedules for cutter suction upgrades that sustain ore grade consistency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ilmenite Market |
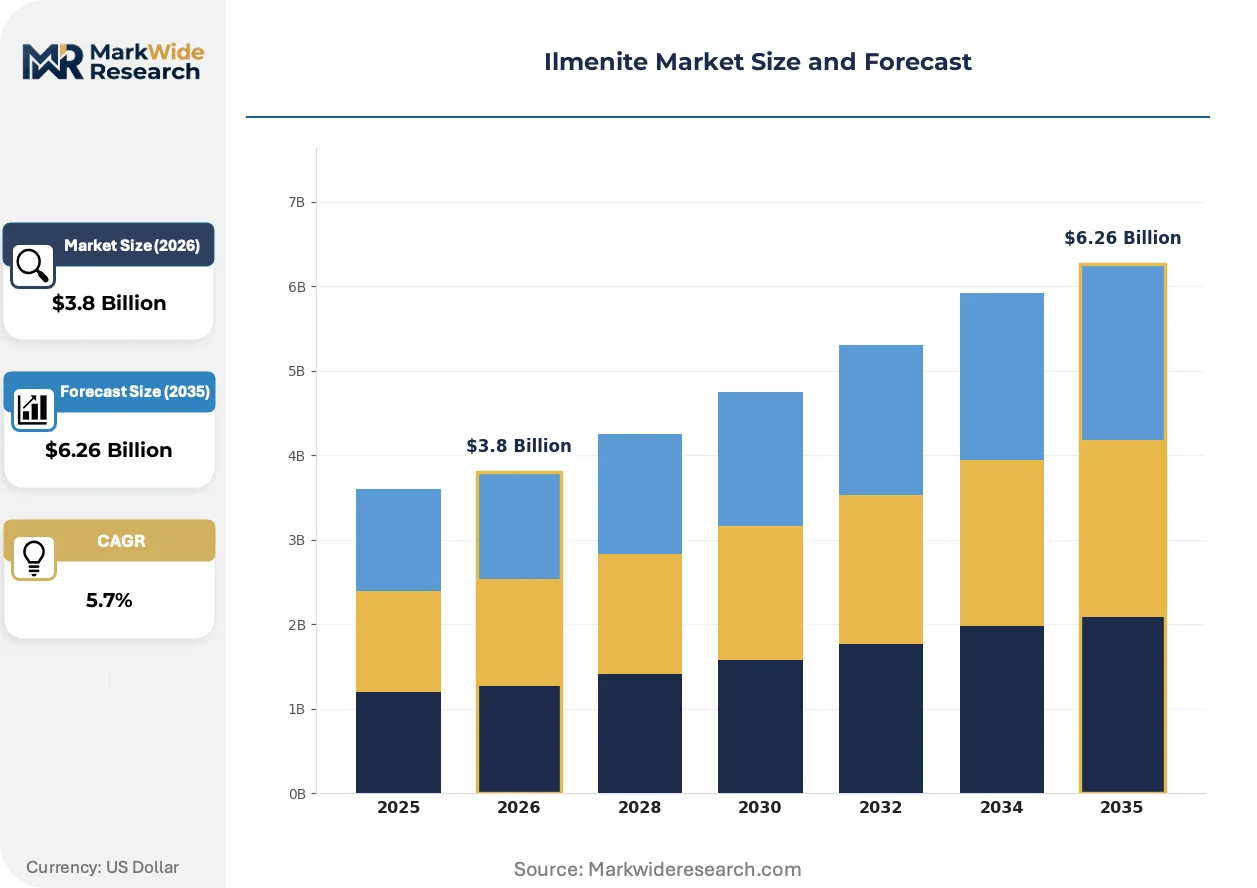
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Ilmenite, Synthetic Ilmenite, Upgraded Ilmenite, Ground Ilmenite End Use Industry: Steel Manufacturing, Titanium Dioxide Production, Paints & Coatings, Aerospace Distribution Channel: Direct Sales, Distributors, E-commerce, Retail Form: Powder, Granules, Lumps, Pellets |
| Companies Covered | Iluka Resources, Rio Tinto, Kenmare Resources, Abbott Blackstone, Base Resources, V.V. Mineral, Richards Bay Minerals, Trimex Sands, The Kerala Minerals and Metals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ilmenite Market Strategic Shifts
Electrothermal upgrading and acid-leach beneficiation are compressing the cost gap between natural ilmenite and synthetic rutile, reshaping feedstock procurement mathematics for chloride-route operators.
Acid-leach beneficiation circuits are displacing traditional smelting routes for producing synthetic rutile from ilmenite concentrate. Saudi pigment producers are adopting Becher-process and Murso-process variants at scale. This technology is displacing Australian and South African synthetic rutile in Middle Eastern supply chains by eliminating high-temperature energy costs.
REACH authorization requirements for titanium dioxide nanoparticles are tightening impurity disclosure standards across EU coatings applications. The regulation forces upstream suppliers to certify heavy metal content below 50 ppm thresholds. Pigment manufacturers serving automotive and architectural coatings in Germany and France now demand batch-level assay documentation.
Long-term offtake contracting is consolidating procurement among top-tier pigment producers with balance sheet capacity to prepay for dedicated mine output. Spot market liquidity for standard-grade ilmenite is thinning as Chinese sulfate-route plants lock in 3-5 year supply agreements. This pattern concentrates most visibly in coastal processing clusters spanning Shandong, Jiangsu, and Guangdong provinces.
Ilmenite Market Segmentation
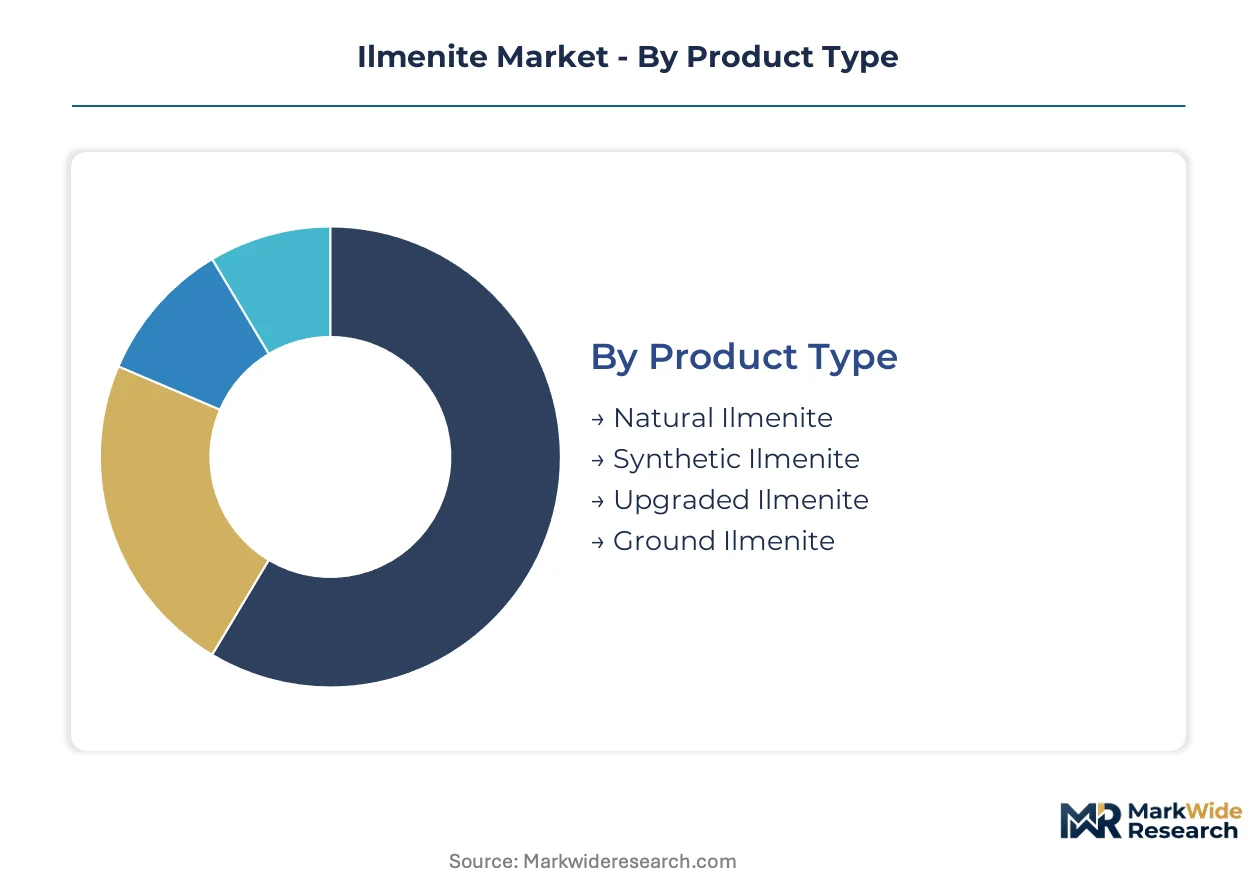
Feedstock grade differentiation determines contract structures and margin capture across the ilmenite value chain. Procurement channels bifurcate between long-term offtake agreements for upgraded material and spot-market transactions for standard-grade ore. Understanding segment flows reveals where capital deployment concentrates.
Product Type:
Direct sales contracts lock in 3-5 year supply commitments for high-grade streams, while distributors handle spot volumes for sulfate-route processors with flexible feedstock requirements.
- Natural Ilmenite:Raw ore containing 45-55% TiO2 serves sulfate-route pigment plants across Shandong and Jiangsu provinces. China's MEE tailings restrictions are compressing domestic supply, redirecting procurement toward Australian and African beach sand deposits with controlled chromium content.
- Upgraded Ilmenite:Beneficiated material reaching 60-65% TiO2 commands structural premiums from chloride-route expansions in Saudi Arabia and China. Acid-leach and reduction technologies enable qualification for high-purity pigment production where impurity thresholds sit below 50 ppm heavy metals.
- Synthetic Ilmenite:Chemically consistent material occupies specialty niches in aerospace-grade titanium sponge production. Laboratory-scale consistency outweighs unit cost in metallurgical applications requiring precise FeTiO3 ratios.
- Ground Ilmenite:Finely milled product accelerates dissolution kinetics in sulfuric acid digestion circuits. Powder form dominates industrial consumption where reaction efficiency determines throughput economics.
Natural ilmenite dominates installed base. Upgraded ilmenite is where expansion concentrates.
End Use Industry:
Margin structures vary sharply across end-use tiers, with pigment-grade contracts embedding quality premiums that steel-sector procurement cannot match.
- Titanium Dioxide Production:Chloride-route plants require 90%+ TiO2 feedstock with controlled calcium and magnesium levels, sourcing upgraded material through dedicated mine contracts. Saudi greenfield capacity and Chinese dual carbon compliance are reshaping procurement mathematics toward imported high-grade streams.
- Paints & Coatings:Architectural and automotive coating applications in Germany and France now demand REACH-certified heavy metal documentation below 50 ppm thresholds. Pigment manufacturers serving these markets require batch-level assay certificates from upstream suppliers.
- Steel Manufacturing:Titanium-bearing slag applications consume lower-grade ilmenite in electric arc furnace operations. Steel-sector buyers compete on unit cost rather than impurity profiles, creating price tier separation from pigment-grade procurement.
- Aerospace:Titanium metal production for airframe components requires synthetic rutile or upgraded ilmenite with precise metallurgical characteristics. Qualification protocols demand 18-24 month digestion trials before volume contracts activate.
Titanium dioxide production anchors volume demand. Paints and coatings is where value capture concentrates.
Distribution Channel:
Channel selection reflects buyer scale and feedstock criticality, with integrated pigment producers bypassing intermediaries to secure supply certainty.
- Direct Sales:Long-term offtake agreements concentrate among top-tier chloride-route operators with balance sheet capacity to prepay for dedicated mine output. Rio Tinto and Iluka Resources leverage direct contracts to embed rehabilitation bond costs into pricing structures.
- Distributors:Trader intermediaries handle spot volumes for Chinese sulfate-route plants with flexible procurement requirements. Liquidity is thinning as coastal processors lock in multi-year supply agreements.
- E-commerce:Digital platforms facilitate sample procurement and small-batch orders for specialty metallurgical applications. Laboratory-scale buyers access certified material without minimum volume commitments.
- Retail:Minimal presence in industrial feedstock markets, limited to educational and research-grade material in institutional quantities.
Direct sales dominates contract value. Distributors handle residual spot volume.
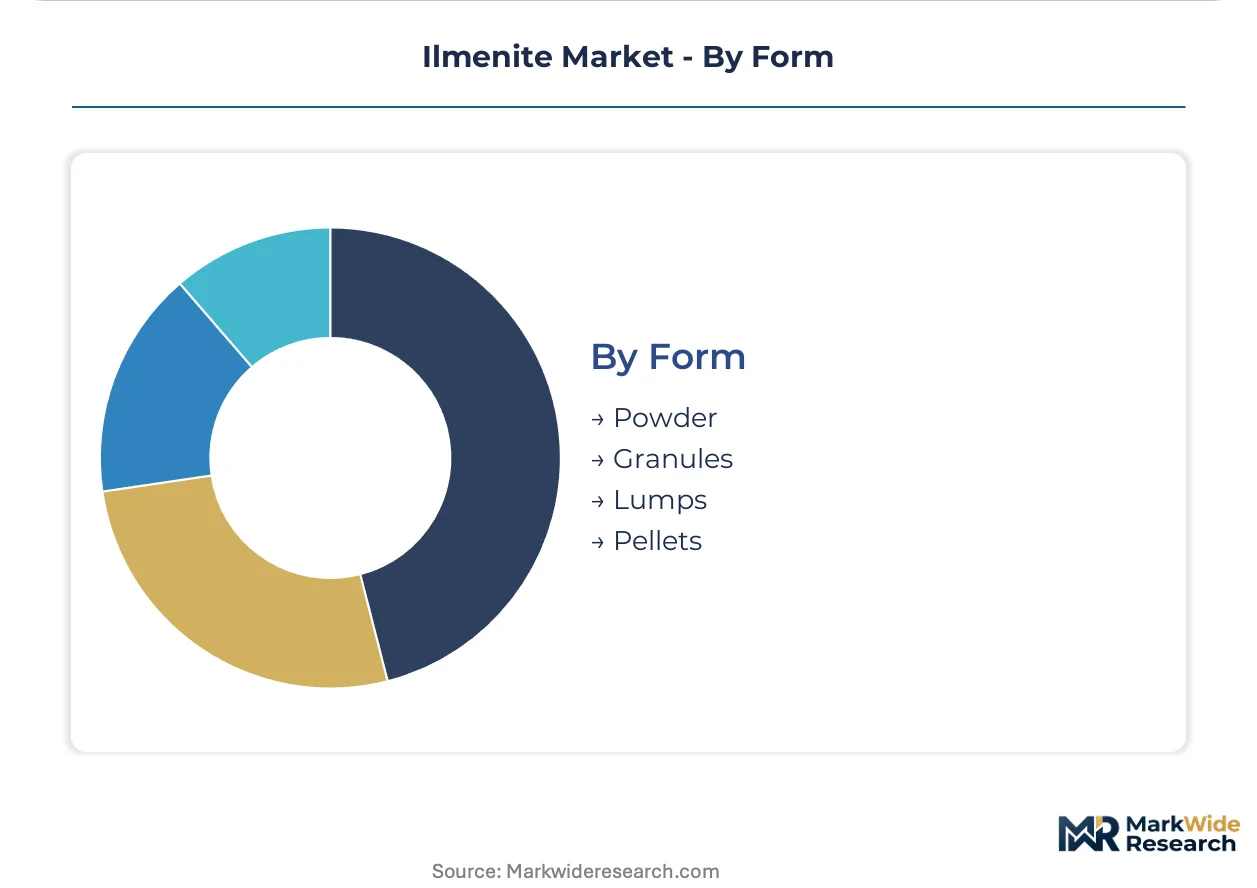
Form:
Physical form selection links directly to processing route economics, with dissolution kinetics driving powder preference in sulfate circuits.
- Powder:Finely milled material with high surface area accelerates sulfuric acid digestion rates. Faster reaction kinetics translate to higher throughput in continuous pigment production lines.
- Granules:Intermediate sizing suits fluidized bed chlorination processes where controlled particle distribution optimizes reaction efficiency. Saudi chloride-route expansions specify narrow granulometry bands.
- Lumps:Coarse material serves traditional smelting routes and steel-sector applications where dissolution speed matters less than bulk handling efficiency.
- Pellets:Agglomerated form reduces dust generation in shipping and handling, meeting MEE environmental compliance for coastal processing facilities in China.
Powder dominates sulfate-route consumption. Granules is where chloride-route qualification concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Richards Bay Coal Terminal anchors South Africa's export capacity, while the Beira Corridor rail link channels Mozambican ore to coastal processors. These infrastructure assets determine regional supply hierarchies.
China
Chloride-route expansions in Shandong and Jiangsu provinces drive feedstock procurement toward upgraded material with controlled chromium levels. The MEE enforces stricter tailings discharge limits that compress domestic mining output. Coastal processing clusters spanning Qingdao and Lianyungang redirect ore flows toward imported compliant supply.
Australia
Western Australia's mineral sands sector supplies sulfate-route plants across Asia through the Port of Bunbury export terminal. The EPA mandates rehabilitation bond requirements that embed multi-year liability reserves into project economics. Iluka Resources operates integrated mining and synthetic rutile upgrading facilities near Perth.
India
Domestic pigment production incentives under the PLI scheme attract integrated mine-to-pigment investments. The CEA and state pollution control boards tighten coastal mineral concession rules for beach sand operations in Tamil Nadu and Kerala. V.V. Mineral and The Kerala Minerals and Metals face constrained expansion timelines at Mannavalakurichi and Chavara deposits.
Saudi Arabia
Greenfield chloride-route TiO2 capacity planned for Jubail Industrial City creates captive demand for imported high-grade feedstock. The SFDA and industrial development frameworks govern chemical sector investments. Ras Al-Khair processing zones specify narrow calcium and magnesium thresholds for metallurgical testwork qualification.
Mozambique
The Moma heavy mineral sands deposit anchors East African volume through dredge mining operations. Bulk vessel contracts bypass traditional trader intermediaries to compress delivered cost to Chinese processors. Nampula Province coastal deposits feed directly into sulfate-route digestion circuits.
Ilmenite Market Competitive Environment
Listed leaders compete with private specialists across integrated mining and upgrading capabilities. The vendor base spans three tiers: diversified mining conglomerates with synthetic rutile technology, pure-play mineral sands operators with dredge-based extraction, and regional traders handling spot volumes for flexible processors. Archetypes include integrated upstream-downstream operators, coastal deposit specialists, and distribution intermediaries. Capacity expansion and long-term offtake contracting represent the dominant competitive moves.
Among Australia-based diversified miners, Rio Tinto and Iluka Resources exemplify integrated upstream-downstream archetypes with synthetic rutile upgrading positions. Kenmare Resources occupies the pure-play mineral sands specialist tier, anchoring East African supply through dredge-based extraction. These three entities represent distinct strategic positioning across the feedstock quality spectrum.
| Leading Market Players |
|---|
| Iluka Resources |
| Rio Tinto |
| Kenmare Resources |
| Abbott Blackstone |
| Base Resources |
| V.V. Mineral |
| Richards Bay Minerals |
| Trimex Sands |
| The Kerala Minerals and Metals |
| Others |
Value Chain & Pricing Dynamics
Synthetic rutile displacement of natural rutile in chloride-route feedstock is redrawing procurement geography while compressing grade premiums across the titanium dioxide value chain. This substitution dynamic redirects ore flows toward acid-leach upgrading facilities in Australia and Saudi Arabia, elevating transport costs for unprocessed material while rewarding integrated processors with captive beneficiation capacity.
Pricing Analysis
Volume-discount tiering structures separate pigment-grade contract holders from spot-market sulfate-route buyers, with long-term offtake agreements embedding 15-20% price advantages for committed volume. Price differentiation hinges on TiO2 assay thresholds and MEE-compliant heavy metal certification below 50 ppm. Cost compression in standard-grade natural ilmenite is intensifying as Chinese domestic supply tightens under tailings restrictions. Steel-sector procurement exhibits highest price sensitivity, while chloride-route pigment plants prioritize quality consistency over unit economics.
Supply Chain Analysis
Strait of Malacca transit underwrites the bulk of Asia-Pacific feedstock movement, with vessel routing through Singapore anchoring delivery cost structures for Chinese coastal processors. Supply concentrates in Australia, Mozambique, and South Africa, with dredge mining operations at Moma and Richards Bay feeding sulfate-route digestion circuits. The supply chain rests on heavy mineral sand deposits, acid-leach upgrading capacity, and bulk vessel charter availability. Single-source vulnerability concentrates in South African slag smelter output for high-grade chloride-route material. Distribution runs through direct sales contracts with integrated pigment producers and residual spot volumes via mineral traders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Feedstock grade fragmentation creates niche capture opportunities as chloride-route and sulfate-route pigment plants diverge in procurement specifications. This demand-side bifurcation rewards specialized upgrading investments over undifferentiated volume plays.
For Market Incumbents: Secure long-term offtake agreements with Saudi greenfield chloride-route capacity before metallurgical qualification timelines lock in competitor supply. Anchor backward integration into acid-leach upgrading technology to defend margin position against synthetic rutile substitution pressure. Prioritize rehabilitation bond cost recovery through embedded pricing structures with Australian EPA compliance requirements. For New Entrants and Emerging Players: Differentiate on MEE-compliant low-chromium assay certification to capture displaced Chinese domestic supply demand. Target direct shipping ore channels from Mozambican and Senegalese deposits bypassing trader intermediaries. Pursue coastal Odisha and Gujarat mine-to-pigment integration under India's PLI scheme incentives. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mineral sands specialists holding dredge-based extraction positions without captive upgrading technology. Five-to-ten year viability hinges on chloride-route expansion execution in the Middle East and China. Watch Saudi TiO2 slag capacity commissioning timelines as the critical inflection signal for feedstock grade premium direction.| Strategic Initiative | Industry Significance |
|---|---|
| Acid-Leach Upgrading Capacity Expansion | Enables 90%+ TiO2 synthetic rutile output qualifying for Saudi chloride-route offtake. |
| Long-Term Supply Agreement | Locks in 3-5 year volume commitments with Chinese coastal processors ahead of spot market thinning. |
| Joint Venture | Combines African dredge mining with Asian upgrading technology to compress delivered cost structures. |
| Backward Integration | Captures synthetic rutile margin spread through in-house beneficiation of ilmenite concentrate. |
| Green Manufacturing Transition | Aligns with China's MEE tailings standards and EU REACH heavy metal disclosure requirements. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC mineral company filings, and EPA rehabilitation bond disclosures. Interviews with mineral sands plant managers, TiO2 pigment procurement leads, and heavy mineral sand distribution channel partners informed supply chain dynamics. Secondary sources include China MEE regulatory filings, India CEA coastal concession records, and Saudi SFDA industrial development frameworks. Bottom-up volume modeling triangulates against top-down value chain analysis across feedstock grade tiers.
Segmentation dimensions modeled span product type, end-use industry, distribution channel, and physical form across the analysis window. Grade differentiation between natural, upgraded, and synthetic ilmenite streams shapes procurement channel bifurcation. CAGRs derive from volume trajectory analysis in titanium dioxide production, paints and coatings, steel manufacturing, and aerospace applications. Forecast inputs incorporate chloride-route capacity expansion timelines and MEE tailings compliance cost pass-through assumptions.
The analysis sits within stated boundaries; outcomes outside sustained Saudi greenfield execution or Chinese dual carbon policy enforcement would require recalibration. Forecasts reflect assumptions regarding metallurgical qualification protocols and dredge fleet maintenance schedules. Practitioners should keep alternative scenarios live as carbon border adjustment mechanisms and TiO2 slag capacity decisions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals & Minerals
Nickel Mining Market
Metals & Minerals
Recycled Scrap Metal Market
Metals & Minerals
Titanium Ore Market
Metals & Minerals
Global Mining Metals Market
Metals & Minerals
Wegscheiderite Market
Metals & Minerals
Moissanite Market
Metals & Minerals
Global Base Metal Mining Market
Metals & Minerals
Recycled Lead Market
Metals & Minerals
Tantalum Pentoxide Market
Metals & Minerals
Selenium Market
Metals & Minerals
USA and Canada Copper Market
Metals & Minerals
Pyroxenite Market
Metals & Minerals
Chromite Market
Metals & Minerals
Flake Graphite Market
Metals & Minerals
Recycled Aluminum Market
Metals & Minerals
Global Artificial Rutile Market