
 Japan Material Testing Market | 2026-2036
Japan Material Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Material Testing Market Intelligence
Digital twin integration with physical testing workflows is rewriting how Japanese manufacturers validate material performance across product lifecycles. Shimadzu Corporation leverages its spectroscopy heritage to anchor high-end materials characterization for semiconductor and battery supply chains. Illinois Tool Works Inc. competes through its Instron brand's dominance in mechanical testing platforms deployed across Toyota and Honda supplier networks. Mitutoyo Corporation specializes in dimensional metrology extensions that bridge quality control with materials traceability requirements.
Material testing encompasses the systematic evaluation of mechanical, thermal, chemical, and structural properties through standardized protocols such as ISO 6892 for tensile strength determination or ASTM E8 for metallic materials, serving to certify fitness-for-purpose before commercial deployment. Fatigue testing commands premium positioning as Japanese aerospace primes and bearing manufacturers pursue extended component life under cyclical loading regimes. Composites testing represents the fastest-growing material type segment, driven by CFRP adoption in Toyota's fuel cell stacks and Mitsubishi Heavy Industries' aircraft programs. Polymers testing retains mature, high-volume status through electronics packaging and automotive interior applications where JIS K 7113 compliance remains mandatory.
METI enforces industrial standards alignment through JIS certification mandates that shape procurement specifications for domestic manufacturers and export-oriented suppliers alike. PMDA's medical device materials guidelines and the Ministry of Land, Infrastructure, Transport and Tourism's construction material certifications create overlapping compliance obligations that expand testing scope. Stakeholders must monitor how Japan's Green Transformation policy redirects testing investment toward hydrogen-compatible alloys and recycled material qualification protocols.
Market Dynamics
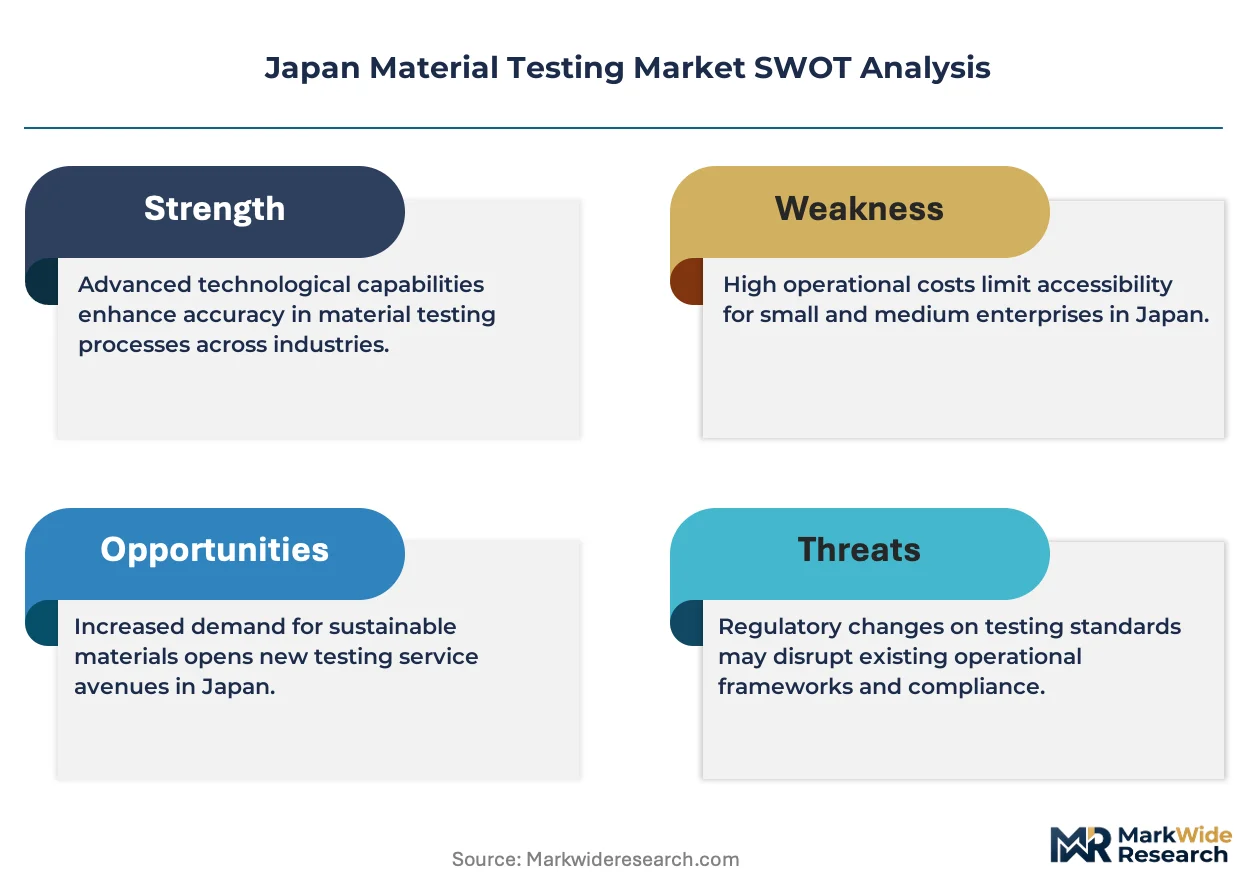
Digital twin integration with physical testing workflows is compressing validation cycles across Japanese automotive and aerospace supply chains. METI's carbon-neutral manufacturing mandates are forcing simultaneous compliance with JIS certification updates and Green Transformation material qualification protocols.
Growth Catalysts
- Green Transformation Policy:METI's hydrogen-compatible alloy qualification requirements are generating new testing demand from steelmakers and chemical processors supplying fuel cell manufacturers.
- CFRP Adoption Surge:Mitsubishi Heavy Industries' aircraft programs and Toyota's fuel cell stack enclosures require expanded composites testing capacity for thermoplastic matrix validation.
- Nagoya-Toyota Corridor Concentration:The clustering of aerospace and automotive laboratories around Toyota City and Nagoya creates dense buyer networks that reduce customer acquisition costs for testing service providers.
Market Restraints
- Equipment Import Dependency:High-end fatigue testing systems and electron microscopes rely on German and US suppliers, exposing laboratories to yen volatility and extended lead times.
- Certification Timeline Friction:JIS standard revision cycles lag behind automotive OEM material innovation schedules, creating approval bottlenecks for novel aluminum-lithium alloys and solid-state battery electrolytes.
- Specialized Labor Scarcity:The pool of technicians qualified for both mechanical testing and materials science interpretation remains shallow relative to demand from bearing manufacturers and semiconductor packaging firms.
Strategic Opportunities
- Recycled Material Qualification:METI's circular economy directives for construction and automotive sectors create first-mover advantage for laboratories developing closed-loop polymer and metal certification protocols.
- Medical Device Expansion:PMDA's biocompatibility testing guidelines for implantable devices open adjacent revenue streams beyond industrial materials into titanium orthopedic and polymer cardiovascular applications.
- Digital Twin Convergence:Integration of AI-driven predictive models with physical test data is enabling subscription-based monitoring services for infrastructure operators managing bridge and tunnel asset lifecycles.
Industry Challenges
- Legacy System Integration:Established laboratories face technical debt from decades-old LIMS platforms that resist API connectivity with modern simulation software and cloud data architectures.
- Multi-Regulatory Overlap:Testing houses must simultaneously satisfy METI industrial standards, PMDA medical guidelines, and Ministry of Land, Infrastructure, Transport and Tourism construction certifications without unified audit frameworks.
- Capital Equipment Obsolescence:The shift toward in-situ testing and real-time monitoring threatens depreciation schedules for traditional benchtop mechanical testing platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Material Testing Market |
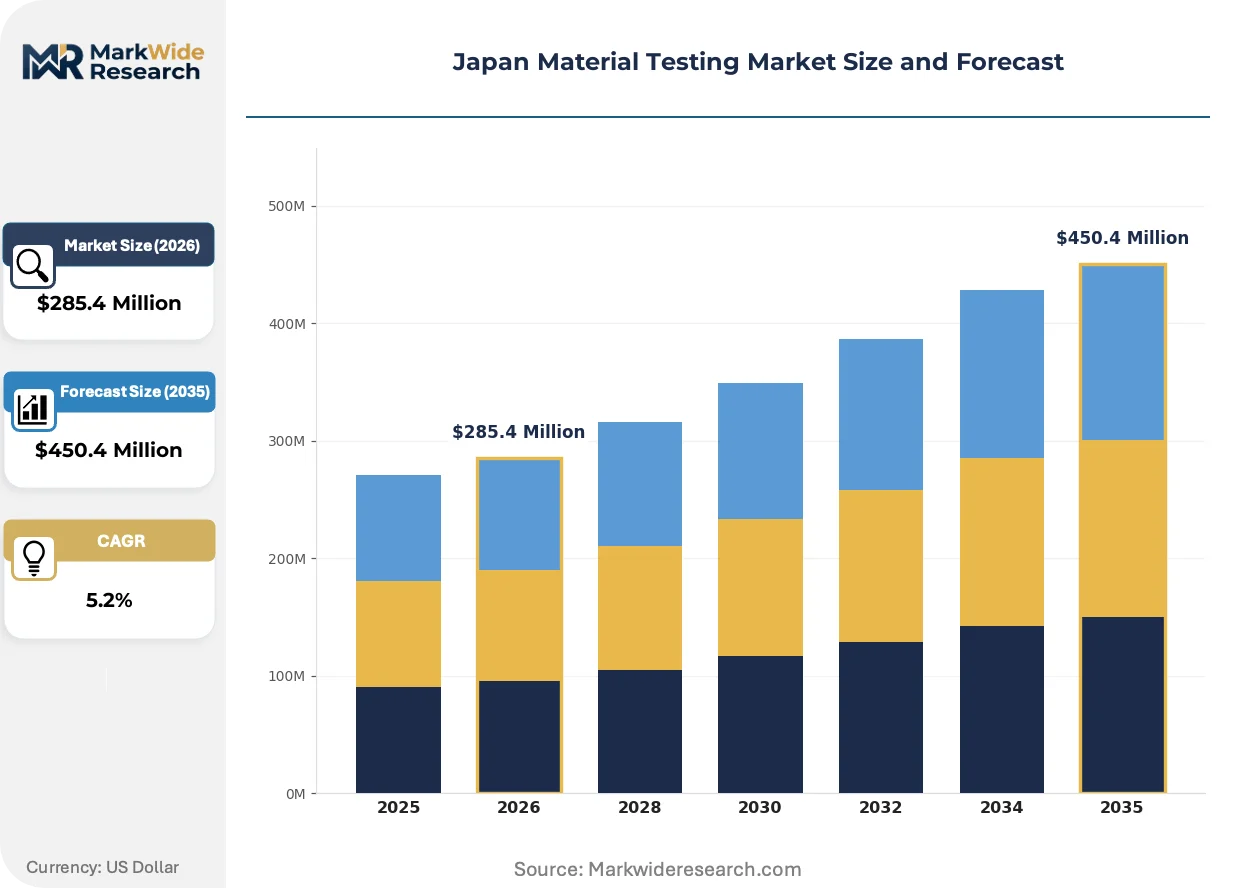
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $450.4 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Testing Type: Tensile, Compression, Bending, Fatigue Material Type: Metals, Polymers, Ceramics, Composites Application Area: Aerospace, Automotive, Construction, Electronics End User: Manufacturers, R&D Institutions, Quality Assurance, Government Agencies |
| Companies Covered | Shimadzu Corporation, Illinois Tool Works Inc., Mitutoyo Corporation, HORIBA Ltd., Olympus Corporation, Thermo Fisher Scientific Inc., Intertek Group PLC, SGS SA, Bureau Veritas SA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Material Testing Market Strategic Shifts & Innovations
Japanese material testing is pivoting from static certification toward continuous performance monitoring embedded within manufacturing workflows. Three developments are restructuring competitive positioning and buyer expectations.
Non-destructive evaluation systems equipped with ultrasonic phased arrays and computed tomography are digitizing quality assurance protocols across Toyota and Honda supplier networks. Tier-1 automotive stampers now deploy inline inspection stations that feed real-time porosity and crack detection data directly into production control systems. This convergence is compressing the traditional separation between R&D characterization and shop-floor quality control.
METI's 2024 JIS Z 2241 revision for metallic materials tensile testing mandates digital data traceability and automated specimen handling, eliminating manual measurement protocols that dominated Japanese laboratories for decades. The regulation forces mid-tier testing houses to retool or exit mechanical testing entirely. Aerospace primes and bearing manufacturers are responding by consolidating supplier panels toward laboratories with integrated robotics and blockchain-anchored certification records.
Japanese automotive OEMs are unbundling after-sales material validation from equipment procurement contracts, shifting toward per-test pricing and third-party laboratory accreditation. This disintermediation pressures captive testing facilities at steel mills and chemical companies to open capacity to external customers. The transformation is most visible in the Kansai industrial belt, where former in-house laboratories at Osaka-based polymer producers now compete for electronics packaging certification work.
Japan Material Testing Market Segmentation
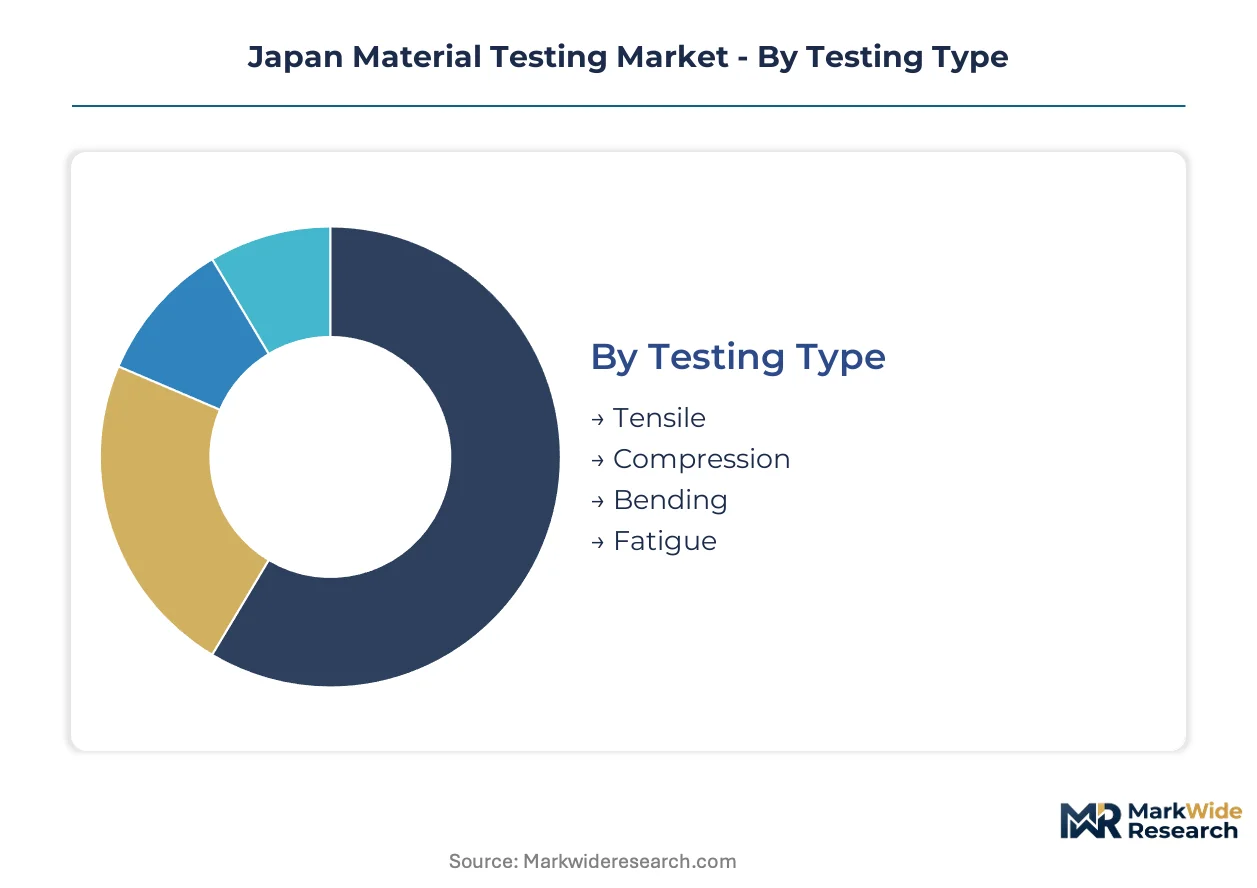
Material testing in Japan fragments across four intersecting dimensions that determine laboratory equipment procurement and service pricing. Testing type and material category together dictate capital intensity, while application area and end user shape compliance obligations and contract structures.
Testing Type:
Maturity varies sharply across mechanical testing protocols, with legacy methods facing displacement from integrated characterization workflows.
- Tensile:The foundational stress-strain characterization under JIS Z 2241 governs metallic material certification for automotive stampers and construction steel suppliers. Nagoya-Toyota corridor laboratories deploy automated specimen handling to meet METI's digital traceability mandates.
- Fatigue:Cyclic loading protocols command premium positioning as Japanese bearing manufacturers and aerospace primes pursue extended component life validation. Demand concentrates around MHI aircraft programs and Toyota's next-generation powertrain development.
- Compression:Crush resistance evaluation serves construction aggregate certification and automotive crash structure validation with standardized fixture requirements.
- Bending:Flexural modulus determination supports polymer composite qualification for electronics packaging and fuel cell stack enclosures.
Tensile retains volume leadership; fatigue holds the steepest expansion curve.
Material Type:
Cost tier stratification separates commodity metals testing from advanced composites characterization requiring specialized environmental chambers.
- Metals:Ferrous and non-ferrous alloy certification dominates laboratory throughput through JIS-mandated tensile and hardness protocols. Steelmakers around Kobe and Kitakyushu maintain captive testing capacity for sheet metal qualification.
- Composites:Thermoplastic matrix validation and CFRP delamination resistance testing are expanding most quickly through MHI SpaceJet programs and Toyota fuel cell stack enclosures. Environmental conditioning requirements drive capital intensity.
- Polymers:Electronics packaging materials and automotive interior components sustain high-volume testing through JIS K 7113 compliance mandates.
- Ceramics:Structural ceramic qualification serves semiconductor processing equipment and medical implant applications with specialized fracture toughness protocols.
Metals retains volume leadership; composites holds the steepest expansion curve.
Application Area:
Customer type differentiation separates production-line quality control from R&D-stage material development with diverging price sensitivity.
- Automotive:Toyota and Honda supplier networks generate dense demand for mechanical testing across powertrain, chassis, and electrification components. Tier-1 stampers require rapid turnaround for production release decisions.
- Aerospace:MHI and Kawasaki Heavy Industries programs demand fatigue and non-destructive evaluation with NADCAP accreditation requirements that limit qualified supplier pools.
- Electronics:Semiconductor packaging and printed circuit board materials require thermal cycling and moisture sensitivity characterization with cleanroom-compatible protocols.
- Construction:Ministry of Land, Infrastructure, Transport and Tourism certification mandates govern rebar, concrete, and structural steel testing with periodic audit requirements.
Automotive retains volume leadership; aerospace holds the steepest expansion curve.
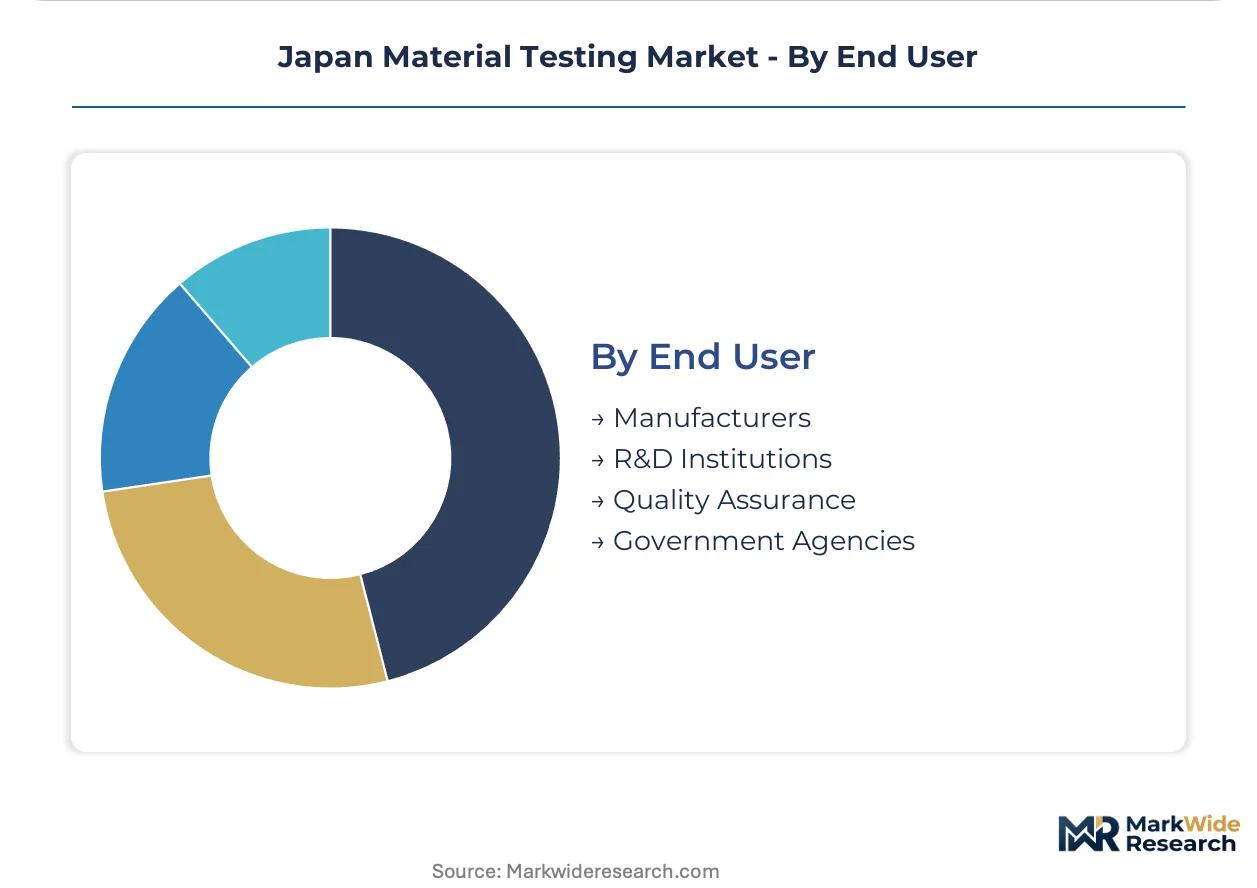
End User:
Supply concentration clusters testing demand around manufacturing corridors with distinct procurement patterns.
- Manufacturers:Steel mills, chemical companies, and automotive suppliers operate captive laboratories that are opening capacity to external customers under per-test pricing models.
- Quality Assurance:Third-party certification bodies and accredited laboratories serve export-oriented suppliers requiring multi-standard compliance documentation.
- R&D Institutions:National laboratories and university materials science departments focus on novel alloy development and failure mechanism research with lower volume but higher specification diversity.
- Government Agencies:METI and Ministry of Land, Infrastructure, Transport and Tourism facilities support standards development and regulatory enforcement with limited commercial competition.
Manufacturers retains volume leadership; quality assurance holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan exports precision testing equipment and certification services throughout East Asian manufacturing supply chains, with particular intensity into South Korean semiconductor and Chinese automotive production networks.
Kanto/Tokyo
Metropolitan Tokyo concentrates headquarters operations for Shimadzu Corporation and HORIBA Ltd alongside METI regulatory oversight functions. The corridor links Yokohama aerospace suppliers with Tsukuba research institutions for advanced materials development. Testing laboratories here service semiconductor equipment manufacturers in the Tama Hills technology cluster.
Chubu/Nagoya
Toyota City anchors the densest automotive materials validation network in Japan, with Tier-1 supplier laboratories clustered within fifty kilometers of headquarters operations. METI's Green Transformation directives flow through Nagoya-based industry associations to hydrogen-compatible alloy developers. Mitutoyo Corporation maintains dimensional metrology operations serving bearing manufacturers throughout Aichi Prefecture.
Kansai/Osaka
Osaka-based polymer producers have opened former captive laboratories to external electronics packaging certification work. The Kansai industrial belt sustains high-volume JIS K 7113 compliance testing for automotive interior components. Steelmakers around Kobe maintain sheet metal qualification capacity integrated with shipbuilding and construction supply chains.
Kyushu
Kitakyushu steel complexes operate integrated materials testing facilities for construction rebar and structural beam certification. The region serves as a secondary hub for ferrous alloy validation under Ministry of Land, Infrastructure, Transport and Tourism mandates. Local laboratories face consolidation pressure from Nagoya-based competitors pursuing per-test pricing models.
Japan Material Testing Market Key Industry Players
Channel-controlling players compete with product-specialist players across three discernible tiers. The market structure consolidates around instrumentation manufacturers with spectroscopy heritage, diversified industrial conglomerates with mechanical testing platforms, and third-party certification bodies with multi-standard accreditation capabilities. Strategic archetypes include integrated equipment-service hybrids, pure-play testing laboratories, and metrology specialists extending into materials traceability. Dominant competitive moves encompass laboratory automation investments and blockchain-anchored certification system deployment.
Among precision instrumentation specialists, Shimadzu Corporation and HORIBA Ltd occupy positions exemplifying the equipment-service hybrid archetype, while Mitutoyo Corporation represents the metrology-to-materials-traceability extension pattern. These Japanese-origin entities anchor competitive dynamics against international certification bodies including Intertek Group PLC and SGS SA, which exemplify the third-party multi-standard compliance model. The competitive tension between domestic equipment manufacturers and global testing houses is reshaping procurement patterns as automotive OEMs unbundle after-sales validation from equipment contracts.
| Leading Market Players |
|---|
| Shimadzu Corporation |
| Illinois Tool Works Inc. |
| Mitutoyo Corporation |
| HORIBA Ltd. |
| Olympus Corporation |
| Thermo Fisher Scientific Inc. |
| Intertek Group PLC |
| SGS SA |
| Bureau Veritas SA |
| Others |
Cost & Logistics Intelligence
The Nagoya-Toyota industrial corridor concentrates over half of Japan's automotive materials testing capacity, creating localized pricing power for laboratories serving Toyota and Honda supplier networks. Equipment import dependency on German fatigue systems and US electron microscopes exposes service providers to yen volatility that feeds into per-test pricing premiums for NADCAP-accredited work.
Pricing Analysis
Cost-plus contracts with steel rebar indexation dominate construction materials certification, while automotive testing has shifted toward per-test pricing with volume discounts for Tier-1 stampers. Price differentiation hinges on JIS accreditation tier and digital traceability compliance, with METI-mandated automated specimen handling compressing margins for mid-tier laboratories. Pricing pressure stems from former captive steel mill laboratories opening capacity to external customers under aggressive rate structures. Tier-1 automotive suppliers exhibit highest price sensitivity due to unbundled procurement contracts, whereas aerospace primes prioritize NADCAP accreditation over unit cost.
Supply Chain Analysis
Tariff exposure between Japan and China dominates supply chain risk for testing consumables and environmental chamber components. High-end fatigue testing systems draw from Germany and the United States, while electron microscope supply rests on Dutch and Japanese manufacturers. Single-source vulnerability concentrates in precision load cell production from German specialists. Distribution runs through authorized equipment distributors in Osaka and Tokyo, with aftermarket service contracts increasingly unbundled from initial hardware procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's material testing market fragments across regulatory jurisdictions, creating niche opportunities as METI's Green Transformation redirects qualification protocols toward hydrogen-compatible alloys and recycled materials.
For Market Incumbents: Pre-empt consolidation by acquiring mid-tier laboratories in the Kansai industrial belt before former captive polymer testing facilities capture electronics packaging share. Invest in blockchain-anchored certification systems to defend against Intertek and SGS SA's multi-standard accreditation expansion. METI's JIS Z 2241 digital traceability mandates favor laboratories with integrated robotics infrastructure.
For New Entrants and Emerging Players: Pursue recycled material qualification protocols for automotive closed-loop polymer certification under METI circular economy directives. The most penetrable segment lies in medical device biocompatibility testing, where PMDA guidelines create accreditation bottlenecks that specialized entrants can exploit. Establish partnerships with Osaka-based former captive laboratories to leverage existing JIS K 7113 compliance infrastructure.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among equipment-service hybrids with installed base monitoring contracts. Long-term viability centers on laboratories integrating AI-driven predictive models with physical test data for infrastructure asset lifecycle services. The acquisition target archetype combines NADCAP aerospace accreditation with automotive Tier-1 supplier relationships. Watch for METI hydrogen alloy qualification protocol finalization as inflection indicator for testing demand redirection.
| Strategic Initiative | Industry Significance |
|---|---|
| Laboratory Automation Investment | Robotic specimen handling satisfies METI's JIS Z 2241 digital traceability mandates for metallic materials. |
| Blockchain Certification Deployment | Tamper-proof records differentiate service providers competing for Toyota supplier network contracts. |
| Recycled Material Protocol Development | First-mover laboratories capture METI circular economy mandates for automotive and construction sectors. |
| Medical Device Accreditation Expansion | PMDA biocompatibility guidelines open adjacent revenue streams beyond industrial materials testing. |
| Digital Twin Integration | AI-driven predictive models enable subscription monitoring services for bridge and tunnel infrastructure operators. |
Research Approach
Cross-validation between laboratory operations directors and METI regulatory affairs specialists anchors the qualitative findings in this study. Primary interviews with equipment procurement managers at Tier-1 automotive stampers, quality assurance leads at bearing manufacturers, and technical directors at third-party certification bodies combined with secondary validation from JIS standard revision documentation, METI policy circulars, and customs data on testing equipment imports. Bottom-up triangulation across regional laboratory capacity assessments and top-down reconciliation with industrial production indices ensures methodological robustness.
Calibration against historical JIS certification volume trends and automotive production cycles shapes the analytical framework across the projection horizon. Segmentation dimensions include testing type, material category, application area, and end-user procurement pattern, with additional modeling of accreditation tier effects on pricing power. CAGRs derive from regression analysis linking equipment installed base expansion to METI regulatory compliance deadlines. Industry-specific inputs incorporate CFRP adoption curves from Mitsubishi Heavy Industries programs and hydrogen-compatible alloy development timelines from steelmaker R&D disclosures.
Sensitivities concentrate around JIS standard revision timing, yen exchange rate volatility affecting equipment import costs, and automotive OEM platform standardization decisions. Forecasts reflect documented assumptions regarding METI policy implementation schedules and Green Transformation funding allocation. Material shifts in solid-state battery commercialization timelines or aluminum-lithium alloy approval pathways would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
Solid Density Tester Market
Testing Equipment
Global Analytical Standards Market
Testing Equipment
Chloride Reagents Kits Market
Testing Equipment
Abrasion Tester Market
Testing Equipment
Steel Testing Equipment Market
Testing Equipment
Paper Moisture Meter Market
Testing Equipment
Water Testing Equipment Market
Testing Equipment
Global Laboratory Analytical Instruments and Consumables Market
Testing Equipment
Micro Carbon Residue Tester Market
Testing Equipment
Drop Weight Tear Tester Market
Testing Equipment
Global Asbestos Testing Market
Testing Equipment
Global Adsorption Equipment Market
Testing Equipment
Asia-Pacific Process Analytics Market
Testing Equipment
Combustion Testing Equipment Market
Testing Equipment
Chlorine Meter Market
Testing Equipment
Corrosion Testing Services Market