
 Andalusite Market | 2026-2036
Andalusite Market Size, Share, and Industry Trends Forecast 2026-2036
Andalusite Market Analysis
Premium-grade andalusite with low iron and titanium content is rebalancing away from commodity volumes as steelmakers tighten raw-material specifications. Sibelco leverages its South African deposit base to sustain long-term refractory supply contracts. Imerys Refractory Minerals anchors European demand through kiln-fired processing capabilities. Andalucita S.A. differentiates via direct-shipping ore grades that bypass intermediate beneficiation.
Andalusite is an aluminum nesosilicate mineral (Al₂SiO₅) formed under low-pressure, high-temperature metamorphic conditions, prized for its exceptional thermal shock resistance and low thermal expansion in refractory linings exceeding 1,650°C service temperatures. Processed andalusite commands structural priority in the product mix because kiln calcination unlocks the full refractory performance that rough ore cannot deliver. Refractory materials applications dominate the value pool, while ceramics and glass manufacturing segments compete for limited high-purity supply.
EPA emissions standards for steel foundries and REACH substance restrictions in Europe shape mineral purity requirements and processing disclosures. China's MIIT refractory industry consolidation directives and GB standards for industrial minerals further constrain market access for ungraded supply. Stakeholders must monitor evolving regulatory thresholds for trace element content, as compliance certification becomes the decisive filter for contract eligibility in premium refractory supply chains.
Market Dynamics
Steel decarbonization mandates are compressing refractory replacement cycles and forcing raw-material purity upgrades across integrated mills and electric arc furnace operators worldwide.
Growth Catalysts
- China's MIIT consolidation directives:Smaller refractory producers face forced exit, concentrating demand among certified suppliers capable of delivering REACH-compliant andalusite grades to export markets.
- Kiln-fired processing expansion:Advanced calcination unlocks full thermal shock resistance above 1,650°C, enabling longer lining life in steel ladles and cement rotary kilns.
- South African Northern Cape deposit development:Premium low-iron ore bodies anchor long-term supply contracts with European refractory manufacturers seeking impurity transparency.
Market Restraints
- Energy cost volatility:Natural gas and electricity prices for calcination operations in Europe and South Africa compress margins for processed andalusite versus Chinese competitors.
- Supply concentration risk:Over 70% of premium-grade ore originates from South Africa's Northern Cape, exposing buyers to logistics disruptions and currency fluctuations.
- Pyrophyllite substitution:Lower-cost aluminum silicate alternatives capture volume in standard-grade refractory applications where thermal performance thresholds permit trade-offs.
Strategic Opportunities
- India's refractory capacity buildout:Domestic steel production targets under the PLI scheme create demand for high-purity andalusite imports as local beneficiation capacity lags.
- EU Green Deal carbon border adjustments:Embodied emissions tracking favors low-carbon calcination routes, rewarding South African producers with grid-independent solar thermal processing investments.
- Direct-shipping ore bypass:Unprocessed premium grades command premium pricing from ceramic tile manufacturers seeking to avoid kiln firing costs and trace element contamination.
Industry Challenges
- REACH dossier preparation timelines:European chemical safety documentation requirements extend qualification periods for new supply sources by 18-24 months.
- Geometallurgical assay standardization:Inconsistent iron and titanium reporting protocols across laboratories create contract disputes and rejected shipments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Andalusite Market |
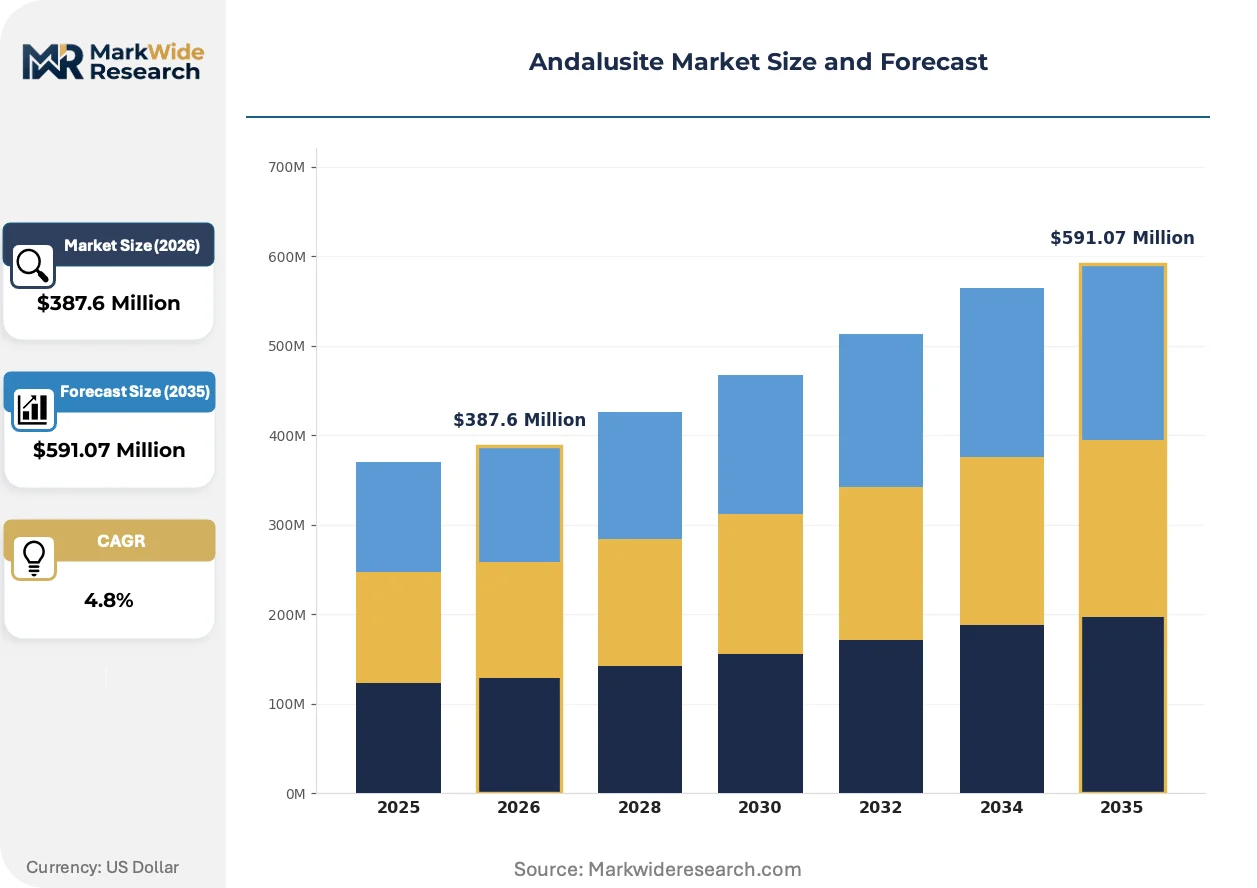
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $591.07 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rough Andalusite, Processed Andalusite, Andalusite Powder, Andalusite Granules Application: Refractory Materials, Ceramics, Glass Manufacturing, Metallurgy End Use Industry: Construction, Electronics, Automotive, Aerospace Packaging Type: Bulk Bags, Bags, Drums, Containers |
| Companies Covered | Andalusite Resources, Sibelco, Imerys Refractory Minerals, Resco Products, Latin Resources, Andalucita S.A., Xinrong Yilong Andalusite Co. Ltd, Shijiazhuang Mining, LKAB Minerals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Andalusite Market Emerging Trajectories
Digital traceability platforms and alternative calcination chemistries are reshaping how refractory-grade minerals move from mine to furnace lining.
Sensor-based ore sorting is decentralizing beneficiation decisions from central processing plants to mine-site operations. South African producers deploy X-ray transmission and laser-induced breakdown spectroscopy units at pit rims to segregate premium grades before transport. This technology compresses waste volumes and reduces downstream energy consumption by eliminating uneconomic material early in the value chain.
REACH substance restrictions are tightening disclosure thresholds for trace heavy metals in refractory minerals placed on the European market. ECHA evaluations of aluminum silicate classifications now require expanded toxicological data packages from non-EU exporters. Chinese and South African suppliers are responding by establishing EU-based representative offices and third-party certification partnerships to maintain market access.
Steelmaker procurement departments are consolidating mineral suppliers and demanding life-cycle carbon footprints alongside traditional technical specifications. Long-term offtake agreements now incorporate Scope 3 emissions clauses that penalize high-calcination routes. This behavioral shift favors producers with renewable energy integration and penalizes gas-dependent processing in price-sensitive contract negotiations.
Andalusite Market Segmentation
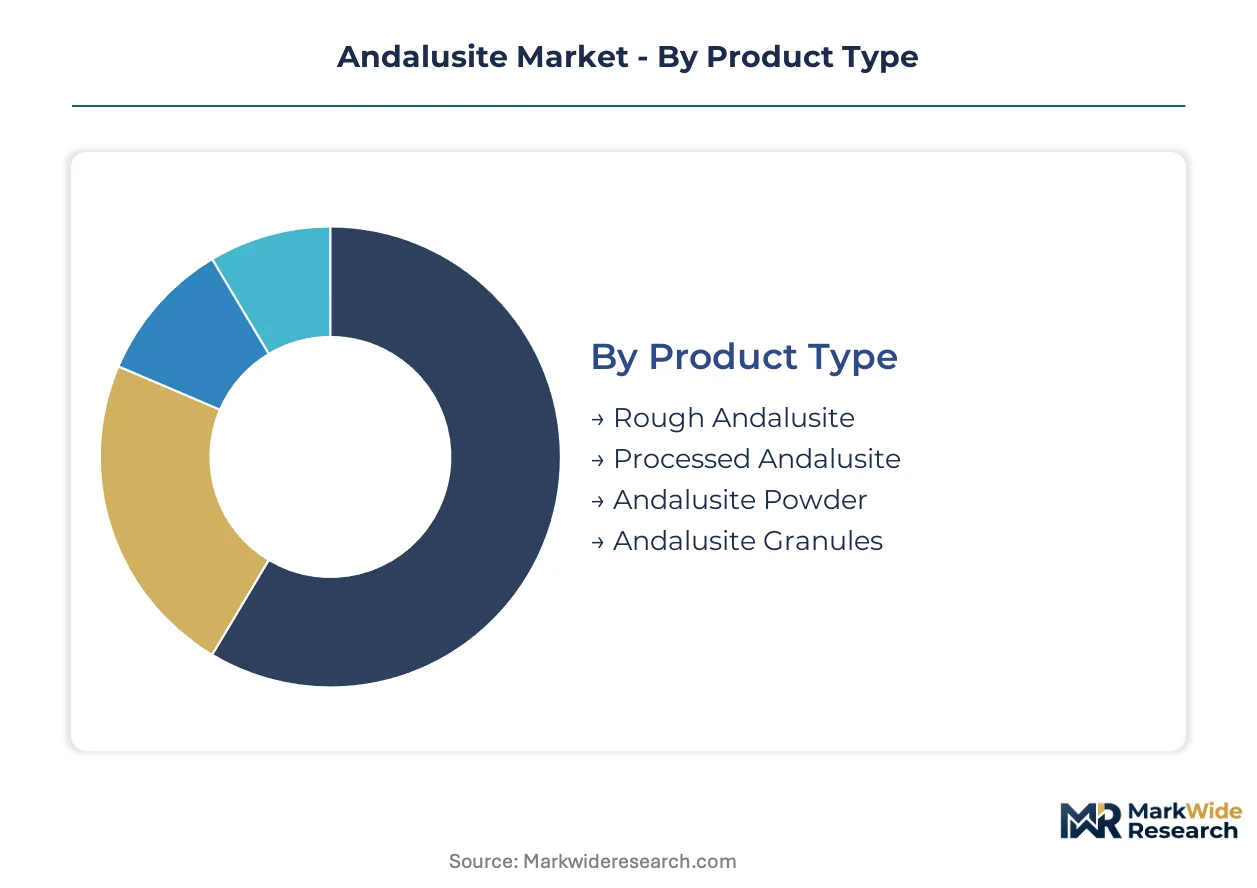
Andalusite market segmentation reveals how mineral processing depth, application thermal requirements, and logistics configuration fragment pricing power across the value chain. Buyers in steel and ceramics pay premiums for specification-matched grades while commodity segments compete on delivered cost.
Product Type:
Supply concentration in South Africa's Northern Cape deposits creates tiered availability across beneficiation stages, with kiln capacity determining which grades reach premium contract eligibility.
- Processed Andalusite:Kiln-calcined material achieves full mullitization, unlocking thermal shock resistance above 1,650°C required in steel ladle linings and cement rotary kilns. European refractory manufacturers anchor long-term offtake agreements with South African processors holding REACH dossiers. Processed andalusite absorbs the bulk of installed capacity; andalusite powder is expanding most quickly.
- Rough Andalusite:Direct-shipping ore bypasses calcination, preserving natural crystal structure for ceramic tile manufacturers seeking to avoid kiln firing costs and trace element contamination from fuel combustion. Chinese importers source rough grades for domestic beneficiation under MIIT consolidation directives.
- Andalusite Powder:Finely milled grades serve precision casting and investment foundry applications where particle size distribution controls slurry rheology.
- Andalusite Granules:Sized fractions for gunning and ramming mixes in blast furnace maintenance and repair operations.
Processed andalusite captures the margin pool; powder grades are climbing the fastest on ceramics demand.
Application:
End-use thermal thresholds stratify the market, with service temperatures above 1,400°C filtering out lower-purity alternatives and concentrating value in steel and cement applications.
- Refractory Materials:Steel decarbonization mandates compress replacement cycles and force purity upgrades across integrated mills and electric arc furnace operators. Ladles, tundishes, and continuous casting refractories specify low-iron andalusite to prevent manganese oxide contamination in ultra-low-carbon steel grades. Refractory materials command the dominant value share; glass manufacturing is gaining share fastest.
- Ceramities:Sanitaryware and technical ceramics manufacturers in Spain and Italy source premium low-iron grades for white-body applications where color consistency determines batch acceptance.
- Glass Manufacturing:Furnace regenerator checkerwork and forehearth linings demand thermal shock resistance through repeated heating cycles, with European float glass producers qualifying South African supply for ETS compliance.
- Metallurgy:Foundry ladle linings and crucibles for non-ferrous casting use standard grades where iron content tolerances relax.
Refractory applications anchor volume commitments; glass manufacturing shows the steepest expansion trajectory on furnace rebuild schedules.
End Use Industry:
Customer technical sophistication and procurement scale determine contract structures, with steel-linked construction and automotive sectors driving specification stringency.
- Construction:Cement kiln refractory linings and precast shapes for infrastructure projects specify calcined andalusite for alkali resistance in high-temperature zones.
- Automotive:Catalytic converter substrate manufacturing and exhaust system ceramics pull high-purity powder grades for thermal management components.
- Electronics:Technical ceramics for semiconductor processing equipment use ultra-low-iron andalusite in kiln furniture and wafer handling systems.
- Aerospace:Investment casting of turbine blades and structural superalloys requires premium powder grades with certified trace element limits.
Construction absorbs the dominant procurement volume; aerospace commands the highest per-kilogram pricing.
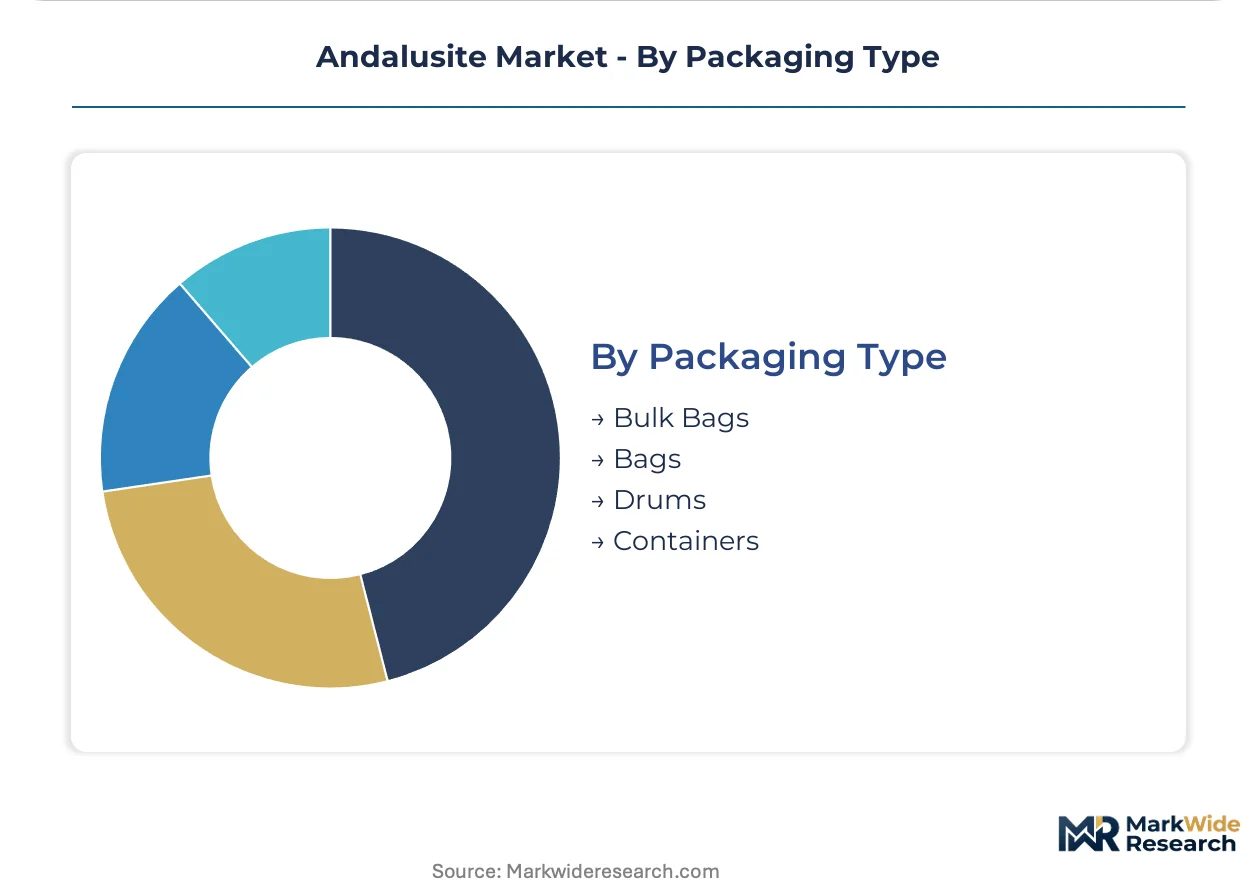
Packaging Type:
Logistics configuration and contamination risk shape packaging selection, with bulk formats favored by integrated refractory producers and unitized packaging serving distributed ceramic manufacturers.
- Bulk Bags:One-tonne flexible intermediate bulk containers dominate ocean freight from South Africa to European refractory plants, minimizing handling costs and dust exposure.
- Bags:25-50kg multiwall paper sacks serve ceramic tile manufacturers requiring batch-scale dosing flexibility and moisture protection.
- Drums:Steel or fiber drums protect high-value powder grades from contamination during air freight and specialty chemical distribution.
- Containers:Dedicated ISO tank containers and lined box containers for moisture-sensitive premium grades requiring climate-controlled transport.
Bulk bags carry the majority of seaborne tonnage; drums are expanding fastest on specialty ceramics air freight.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Northern Cape mining belt around Hotazel anchors global premium-grade andalusite supply, with South African processors serving European refractory manufacturers through long-term offtake agreements. Steel decarbonization mandates across major economies are redrawing procurement geography as buyers seek impurity transparency and low-carbon calcination routes.
South Africa
Refractory materials manufacturers in Germany and France source directly from Northern Cape deposits for REACH-compliant supply chains. The country's Department of Mineral Resources and Energy oversees mining licensing in the manganese-rich belt near Kuruman. Port Elizabeth bulk terminals handle seaborne exports of kiln-calcined grades to European steel hubs.
China
Domestic steel production targets under MIIT consolidation directives concentrate demand among certified refractory producers capable of processing imported rough andalusite. GB standards for industrial minerals constrain market access for ungraded supply. Xinjiang and Inner Mongolia processing clusters beneficiate African ore for ladles and cement rotary kilns.
Germany
Ruhr Valley refractory manufacturers specify low-iron andalusite for ultra-low-carbon steel grades in electric arc furnace operations. ECHA REACH dossier requirements extend qualification periods for new supply sources by 18-24 months. Duisburg logistics corridors distribute processed material to integrated mills across North Rhine-Westphalia.
India
Domestic steel capacity buildout under the PLI scheme creates import demand for high-purity andalusite as local beneficiation capacity lags. Bureau of Indian Standards certification protocols govern refractory mineral quality for infrastructure projects. Odisha and Jharkhand steel clusters source premium grades for blast furnace rebuild schedules.
United States
EPA emissions standards for steel foundries shape mineral purity requirements in Great Lakes manufacturing regions. OSHA workplace exposure limits affect handling protocols for andalusite powder in investment casting operations. Pittsburgh and Cleveland refractory distributors maintain inventory positions for automotive and aerospace casting customers.
Andalusite Market Vendor Landscape
Premium-margin players sit above commodity-margin players across beneficiation depth and regulatory certification vectors. Supply concentrates among integrated miners with kiln-fired processing capabilities and third-party traders sourcing rough ore for domestic calcination. Three archetypes dominate: deposit-owning processors with REACH dossiers, trading houses aggregating African supply for Asian markets, and specialty distributors serving precision ceramics. Competitive moves center on solar thermal calcination investments and EU representative office establishment for regulatory compliance.
Among South Africa-based deposit owners, Andalusite Resources and Andalucita S.A. occupy positions within the premium-tier supply chain, while Sibelco represents the integrated multinational archetype with diversified industrial mineral portfolios. Imerys Refractory Minerals anchors European demand through kiln-fired processing capabilities. These named entities exemplify how geographic concentration of ore quality translates into contract eligibility for steelmaker procurement departments consolidating supplier bases.
| Leading Market Players |
|---|
| Andalusite Resources |
| Sibelco |
| Imerys Refractory Minerals |
| Resco Products |
| Latin Resources |
| Andalucita S.A. |
| Xinrong Yilong Andalusite Co. Ltd |
| Shijiazhuang Mining |
| LKAB Minerals |
| Others |
Supply Flow & Price Mechanics
Deposit-owning processors with captive kiln capacity anchor pricing discipline through long-term offtake structures that lock in volume commitments before marginal competitors can qualify. South African family-controlled mining houses leverage Northern Cape ore quality premiums to resist spot-market commoditization, while European refractory manufacturers absorb cost pass-throughs to secure REACH-compliant supply chains.
Pricing Analysis
Yield-guaranteed pricing tied to ladle lining performance anchors contract structures for kiln-calcined grades serving steel decarbonization mandates. Three-tier pricing structure across premium, standard, and economy levels separates REACH-certified supply from MIIT-compliant Chinese grades and unbeneficiated rough ore. Cost compression in European calcination tiers is intensifying because natural gas price volatility erodes margin buffers against South African solar-thermal competitors. Integrated steel mills show least price sensitivity, while ceramic tile manufacturers sourcing direct-shipping ore exhibit highest elasticity to freight rate fluctuations.
Supply Chain Analysis
Dual-sourcing requirements from European refractory manufacturers mandate parallel qualification of South African and Chinese supply channels to mitigate concentration risk. Geographic supply concentrates in South Africa, China, and India, with raw material dependencies resting on Northern Cape ore bodies, Xinjiang processing chemicals, and Jharkhand steel slag additives. Single-source vulnerability from Port Elizabeth bulk terminal congestion threatens just-in-time delivery to Ruhr Valley manufacturers. Distribution runs through seaborne bulk charter contracts to Antwerp and Duisburg, with drum-packaged air freight serving aerospace investment casting clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into kiln-fired processing capacity and captive ore reserves defines the vertical-integration race, as steelmaker procurement departments consolidate supplier bases around carbon-footprint transparency.
For Market Incumbents: Deepen solar thermal calcination investments in South Africa's Northern Cape to defend margin position against gas-dependent European competitors facing ETS compliance costs. Secure long-term ore reserve extensions through Department of Mineral Resources and Energy licensing rounds before pyrophyllite substitution accelerates in standard-grade applications. Prioritize EU representative office establishment to compress REACH dossier preparation timelines for new supply sources. For New Entrants and Emerging Players: Premium-economy price-point gaps in Indian refractory supply create white-space entry around PLI scheme steel capacity buildout where local beneficiation capacity lags. Target direct-shipping ore segments for ceramic tile manufacturers seeking to bypass kiln firing costs and trace element contamination. Pursue joint venture structures with established Northern Cape deposit owners to shortcut 18-24 month qualification periods. For Investors and Strategic Acquirers: Distressed-cycle entries favor kiln-capable mid-tier processors in South Africa's Northern Cape with stranded ore reserves and incomplete REACH certification. Long-term viability over the next decade hinges on carbon-border adjustment alignment and renewable energy integration depth. Watch for EU Green Deal carbon border adjustment implementation timing as inflection indicator for processed versus rough ore demand shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Kiln Capacity | South African processors with captive calcination secure REACH-compliant supply chain positioning against gas-dependent European competitors. |
| Long-term Supply Agreement | Ruhr Valley refractory manufacturers lock in Northern Cape ore quality premiums through multi-year offtake structures with carbon-footprint clauses. |
| Green Manufacturing Transition | Solar thermal processing investments in Hotazel mining belt align with EU Green Deal embodied emissions tracking requirements. |
| Joint Venture | Indian steel clusters partner with African deposit owners to bridge beneficiation capacity gaps under PLI scheme production targets. |
| Geographic Expansion | EU representative office establishment by Chinese and South African suppliers compresses ECHA qualification timelines for new market entry. |
Methodological Framework
Multi-period observation of kiln capacity utilization rates, REACH dossier submission timelines, and steel decarbonization mandate implementation anchored the trend analysis, supplemented by interviews with refractory procurement directors, plant managers at Northern Cape processing facilities, ECHA regulatory affairs specialists, and Indian steel mill technical directors. Secondary validation drew from customs and trade data, SEC filings of listed industrial mineral processors, MIIT industry consolidation directives, and ETS compliance disclosure databases. Bottom-up volume modeling across beneficiation stages triangulated against top-down steel production forecasts.
Input-output matrix framing connected ore grade assays to calcination energy requirements and downstream refractory performance specifications across the projection horizon. Segmentation dimensions modeled include product type (processed, rough, powder, granules), application thermal threshold, end-use industry technical sophistication, and regional regulatory cluster. CAGRs were derived from installed capacity expansion schedules and steel industry demand elasticity estimates. Forecast inputs incorporated ECHA substance restriction evaluation timelines and MIIT consolidation exit timelines for smaller Chinese refractory producers.
Inputs from ECHA pre-registration databases and South African Department of Mineral Resources and Energy licensing records were available through the study window; gaps in private kiln capacity utilization rates introduce uncertainty bands around processed andalusite supply elasticity. Forecasts reflect assumptions on carbon border adjustment implementation scope and pyrophyllite substitution penetration ceilings. Deviation in EU Green Deal carbon border adjustment enforcement timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals & Minerals
Mineral Ingredients Market
Metals & Minerals
Cesium Market
Metals & Minerals
Flake Graphite Market
Metals & Minerals
Selenium Market
Metals & Minerals
Hot Briquetted Iron (HBI) Market
Metals & Minerals
Titanium Ore Market
Metals & Minerals
Recycled Antimony Market
Metals & Minerals
Solder Materials Market
Metals & Minerals
Global Fabricated Metal Products Market
Metals & Minerals
Lithium Ingots Market
Metals & Minerals
Manganese Market
Metals & Minerals
Precious Metals E-Waste Recovery Market
Metals & Minerals
Recycled Lead Market
Metals & Minerals
US Lithium Market
Metals & Minerals
Sapphire Mining Market
Metals & Minerals
Dead Sea Mineral Market