
 Cooling Water Treatment Chemicals Market | 2026-2036
Cooling Water Treatment Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Cooling Water Treatment Chemicals Market Analysis
Smart dosing systems integrated with IoT sensors is rewriting operational protocols across cooling water management, enabling real-time alkalinity and conductivity adjustments that slash chemical overfeed. Kemira leverages its polymer chemistry expertise to dominate high-stress evaporative cooling applications in Nordic power clusters. Kurita Water Industries Ltd anchors its position through captive membrane technology that extends service intervals in closed-loop manufacturing circuits. Ecolab Inc. differentiates via digital platform bundling that ties chemical supply to performance guarantees across multi-site industrial portfolios.
Cooling water treatment chemicals comprise formulated blends of corrosion inhibitors, biocides, scale dispersants, and pH buffers dosed into recirculating systems to prevent heat transfer degradation and metallic failure, with active concentrations typically maintained between 50 and 200 ppm depending on cycle chemistry and makeup water hardness. Biocides command the largest share of product-type revenue as chlorine alternatives gain preference in facilities facing halogenated discharge restrictions. Open loop systems represent the fastest-growing application segment, driven by once-through cooling retrofits in coastal power plants and refinery complexes where intake structure biofouling mandates aggressive biological control.
The EPA enforces cooling water intake structure standards under Section 316(b) of the Clean Water Act, compelling facilities to evaluate chemical treatment against closed-cycle cooling alternatives, while OSHA's Process Safety Management standards govern bulk chemical storage and handling protocols at industrial sites. State-level regulators in California and Texas impose additional discharge temperature and biocide residual limits that shape local formulation requirements. Stakeholders must monitor evolving PFAS restrictions, as fluorosurfactant-based corrosion inhibitors face substitution pressure from state-level chemical disclosure mandates and anticipated federal listing actions.
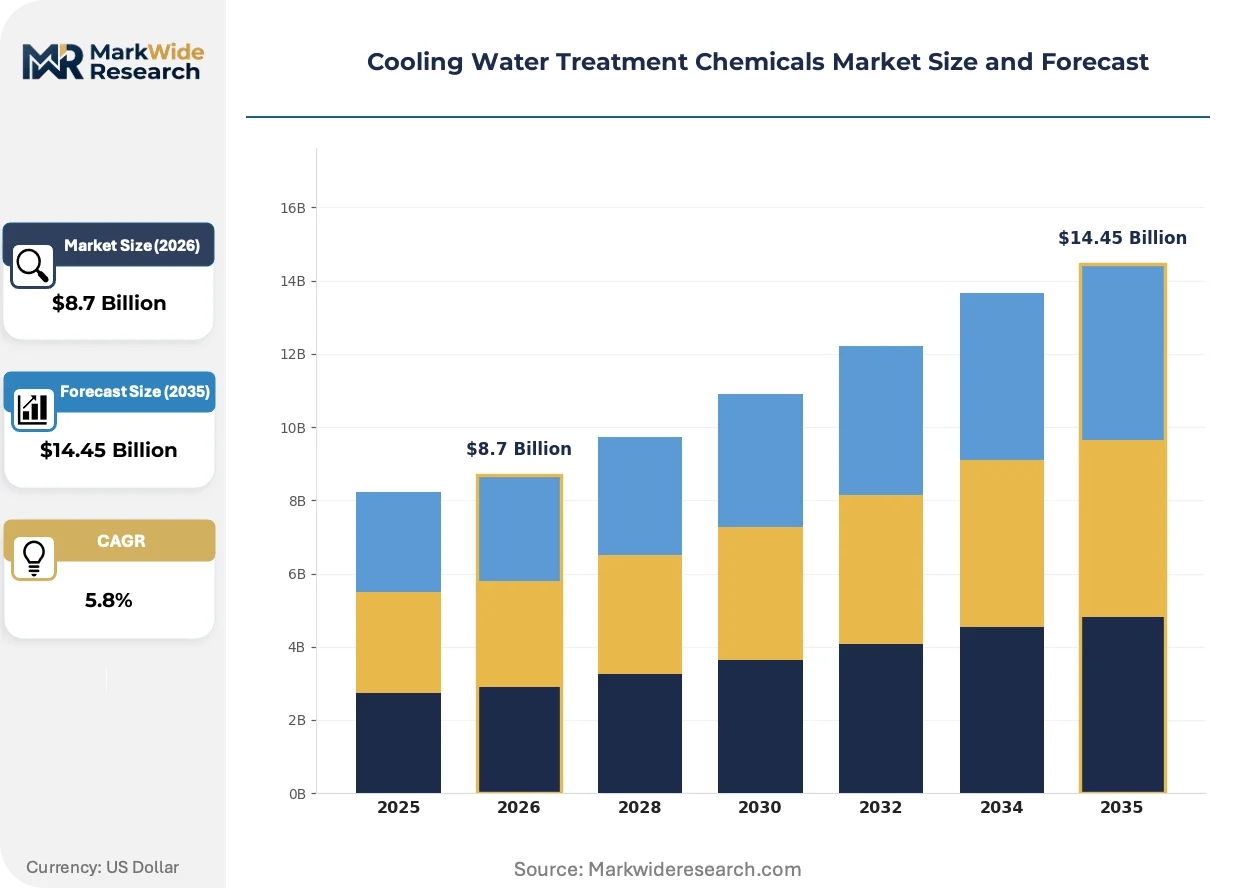
Market Dynamics
Smart dosing systems integrated with IoT sensors are collapsing traditional operational protocols across cooling water management, forcing chemical suppliers to bundle digital capabilities with formulation supply or surrender margin to platform-native competitors.
Growth Catalysts
- EPA Section 316(b) enforcement:Cooling water intake structure standards compel coastal power plants to intensify chemical biofouling control, expanding treatment program scope and chemical volumes.
- Data center liquid cooling expansion:Hyperscale facilities in the United States are retrofitting evaporative cooling towers with precision chemical management to protect aluminum heat exchangers from galvanic corrosion.
- Phosphonate scale inhibitor advances:Next-generation threshold inhibitors enable higher cycle concentrations in hard-water regions, reducing blowdown volumes and extending chemical replacement intervals.
Market Restraints
- Fluorosurfactant regulatory pressure:State-level PFAS disclosure mandates in California and anticipated federal listing actions are forcing substitution of fluorinated corrosion inhibitors with less performant alternatives.
- Halogenated biocide discharge restrictions:Chlorine alternative formulations command 40-60% price premiums over traditional oxidizing biocides, compressing margins for facilities facing strict effluent limitation guidelines.
- Specialty polymer supply concentration:Acrylic acid derivatives and phosphonate intermediates concentrate among German and Chinese chemical manufacturers, exposing formulators to feedstock volatility.
Strategic Opportunities
- Closed-loop manufacturing circuits in India:Textile and pharmaceutical processing clusters lack captive water treatment expertise, creating white space for outsourced chemical management contracts.
- EU F-Gas Regulation alignment:Refrigerant phase-down timelines are accelerating absorption chiller deployment, requiring compatible corrosion inhibition chemistries for lithium bromide systems.
- Digital platform bundling:Performance-guaranteed service models that tie chemical supply to heat transfer efficiency metrics are displacing transactional procurement in multi-site industrial portfolios.
Industry Challenges
- Cross-functional skill scarcity:Facilities struggle to hire operators conversant in both water chemistry fundamentals and IoT sensor calibration, slowing smart dosing adoption.
- Legacy DCS integration friction:Chemical feed automation projects stall when programmable logic controllers lack API compatibility with cloud-based analytics platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cooling Water Treatment Chemicals Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biocides, Corrosion Inhibitors, Scale Inhibitors, pH Adjusters End User: Power Generation, Manufacturing, Oil & Gas, Food Processing Application: Closed Loop Systems, Open Loop Systems, Cooling Towers, Evaporative Coolers Form: Liquid, Powder, Granular, Tablets |
| Companies Covered | Kemira, Kurita Water Industries Ltd, Ecolab Inc., Buckman, ChemTreat Inc., Veolia, Nouryon, DuBois Chemicals, Solenis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cooling Water Treatment Chemicals Market Emerging Trajectories
Real-time alkalinity and conductivity adjustments via sensor-fed automation are rewriting how facilities manage chemical overfeed, compressing the traditional manual testing and batch dosing paradigm into continuous micro-adjustment protocols.
Electrochemical scale prevention technology is collapsing conventional phosphonate-dependent treatment programs in once-through cooling systems. Coastal power plants in Texas and Florida are piloting electrolytic devices that precipitate hardness ions at electrode surfaces, eliminating chemical scale inhibitor consumption entirely. This hardware substitution threatens to commoditize the largest product-type revenue segment in open-loop applications.
REACH authorization procedures for biocidal active substances are tightening formulation flexibility across European manufacturing circuits. ECHA's ongoing substance evaluations are disqualifying legacy isothiazolinone blends, forcing reformulation toward DBNPA and glutaraldehyde alternatives with shorter half-lives and higher dosing frequencies. German chemical suppliers are accelerating registration dossiers for novel quaternary ammonium compounds to preserve market access.
Performance-based procurement contracts are displacing volume-based chemical supply agreements in United States industrial portfolios. Multi-site operators now demand heat transfer coefficient guarantees rather than ppm maintenance targets, transferring operational risk to chemical service providers. This behavioral shift concentrates contract awards among vendors with captive analytical laboratories and field engineering capabilities, fragmenting share among regional specialists unable to underwrite performance guarantees.
Cooling Water Treatment Chemicals Market Segmentation
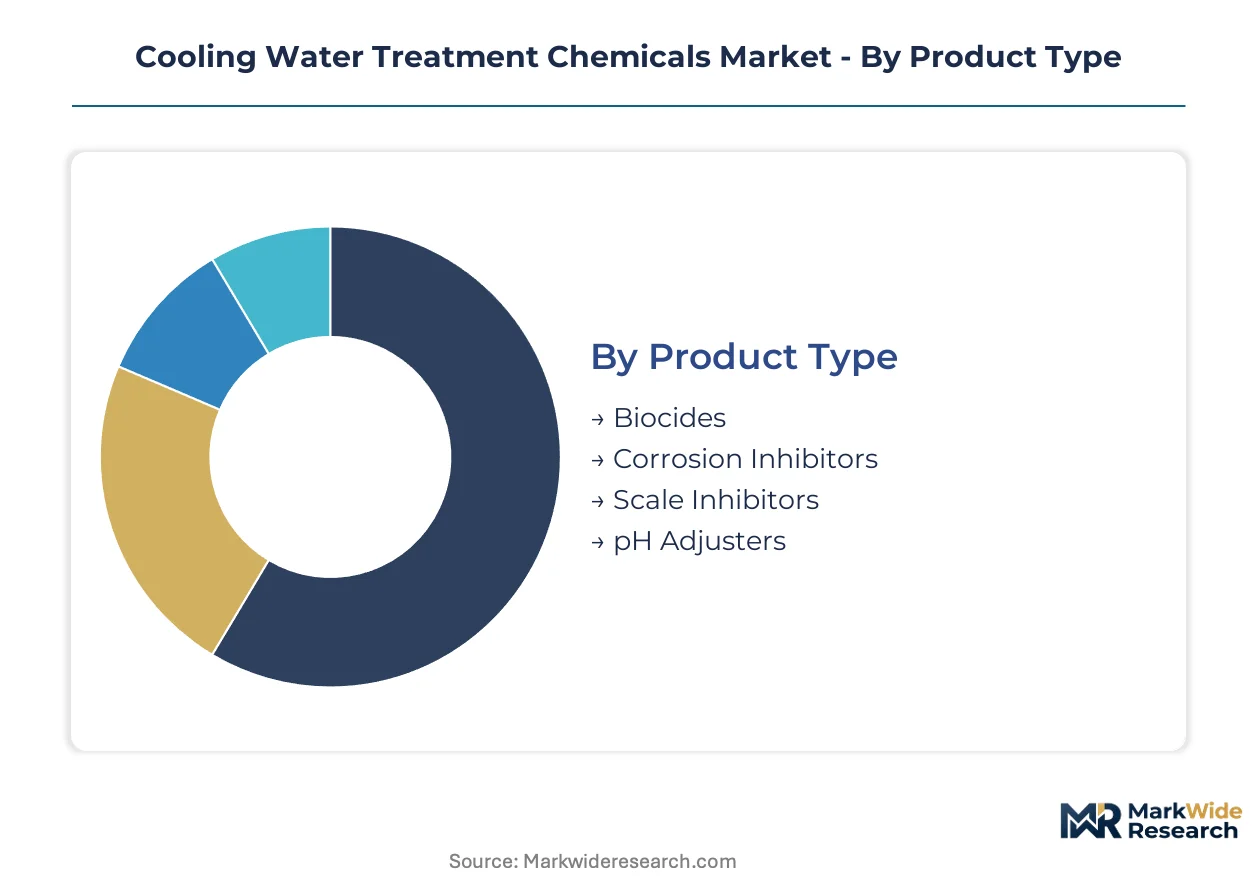
Chemical treatment programs vary sharply by system design, water chemistry, and regulatory exposure. Segmentation reveals where formulation complexity concentrates and which customer types drive premium pricing.
Product Type:
Use-case spectrum spans aggressive biological control in coastal intakes to precision pH management in hyperscale data centers.
- Biocides:Oxidizing and non-oxidizing formulations eliminate microbial biofilms that degrade heat transfer surfaces. Chlorine alternatives command price premiums in United States facilities facing EPA effluent limitation guidelines for halogenated discharge.
- Corrosion Inhibitors:Film-forming amines and molybdate blends protect carbon steel and aluminum components from galvanic failure. Fluorosurfactant-based inhibitors face substitution pressure in California and other states with PFAS disclosure mandates.
- Scale Inhibitors:Phosphonate and polymer-based threshold inhibitors prevent calcium carbonate and silica precipitation in hard-water regions.
- pH Adjusters:Sulfuric acid and caustic soda formulations maintain alkalinity within corrosion-minimizing bands.
Established volume favors biocides; emerging adoption favors corrosion inhibitors reformulated without fluorinated chemistries.
End User:
Customer concentration tracks cooling water intensity and regulatory scrutiny intensity.
- Power Generation:Thermal utilities operate the largest open-loop cooling volumes, dosing biocides and scale inhibitors at concentrations between 50 and 200 ppm. United States coal and natural gas fleets drive replacement chemical demand as aging plants extend service life.
- Manufacturing:Closed-loop circuits in automotive and electronics fabrication require precision corrosion inhibition to protect aluminum heat exchangers. Data center liquid cooling retrofits are expanding treatment program scope.
- Oil & Gas:Refinery cooling towers and offshore platform once-through systems demand aggressive biofouling control.
- Food Processing:Pasteurization and refrigeration circuits require food-grade biocide formulations with minimal residual toxicity.
Power generation anchors current procurement volumes; manufacturing exhibits the steepest expansion trajectory.
Application:
System architecture determines chemical consumption rates and automation requirements.
- Open Loop Systems:Once-through cooling at coastal power plants and refineries demands continuous biocide dosing to control intake structure biofouling. Texas and Florida facilities pilot electrochemical scale prevention as a chemical-free alternative.
- Closed Loop Systems:Recirculating manufacturing circuits require lower chemical volumes but higher concentration precision. Captive membrane technology extends service intervals in these applications.
- Cooling Towers:Evaporative systems concentrate dissolved solids through cycles of concentration, demanding integrated scale and corrosion control.
- Evaporative Coolers:Smaller-scale systems in commercial and light industrial settings use simplified dosing protocols.
Open loop systems concentrate current spend; closed loop systems gain share through manufacturing reshoring.
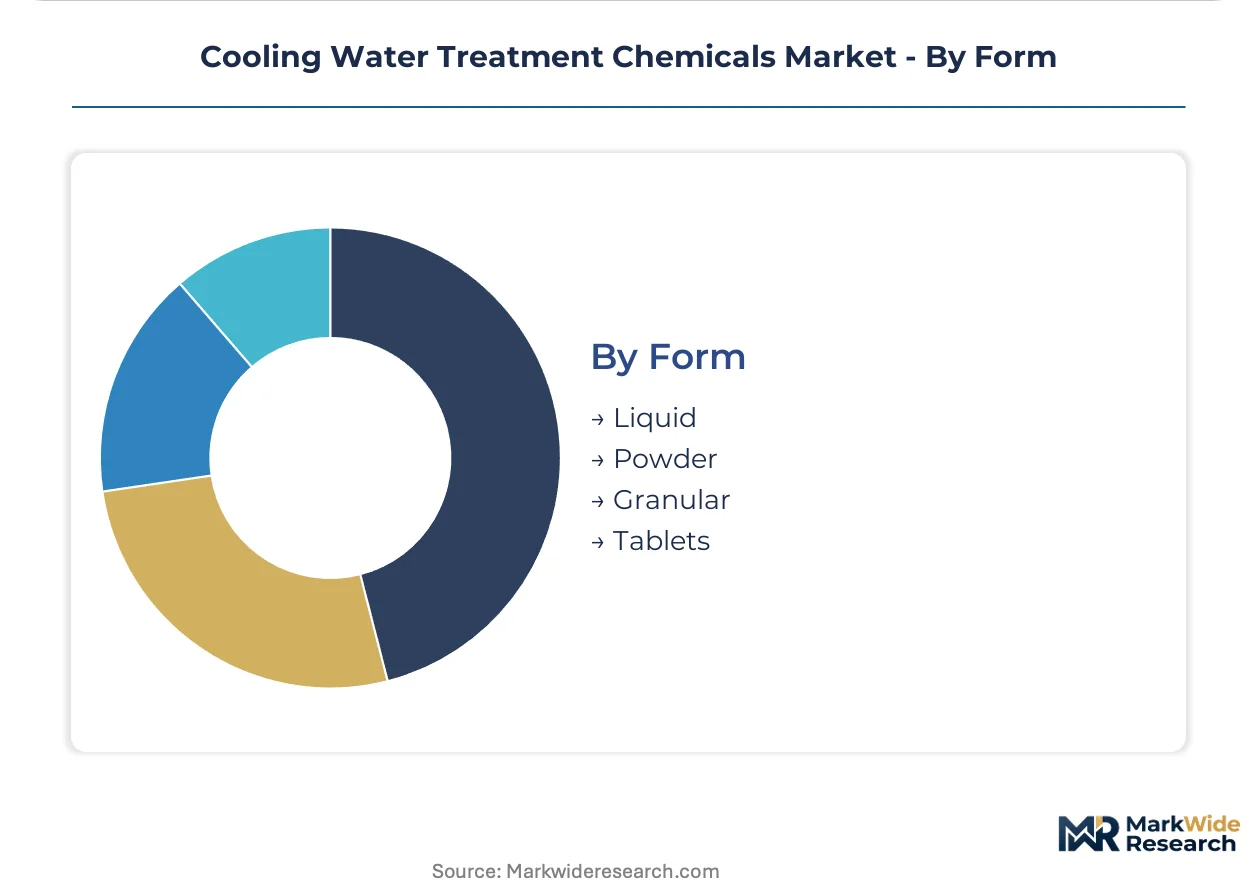
Form:
Physical state shapes logistics economics and dosing automation compatibility.
- Liquid:Pump-ready formulations dominate large-volume industrial applications. Smart dosing systems with IoT sensor integration favor liquid feeds for real-time alkalinity adjustment.
- Powder:Concentrated dry blends reduce transportation costs for remote oil field and mining operations.
- Granular:Controlled-release formulations suit smaller cooling towers without automated feed equipment.
- Tablets:Pre-measured dosing simplifies maintenance in commercial HVAC and food processing applications.
Liquid forms dominate procurement volumes; tablet and granular formats expand in distributed, low-automation installations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in specialty water treatment chemicals favor established manufacturing bases in Germany and the United States, while import-dependent power sectors in India and Southeast Asia drive formulation demand growth. Trade flows concentrate phosphonate intermediates and polymer feedstocks through Rotterdam and Houston chemical corridors.
United States
Aging thermal power fleets in Texas and Florida intensify biocide consumption for intake structure biofouling control. EPA Section 316(b) enforcement compels coastal facilities to evaluate chemical treatment against closed-cycle cooling alternatives. Data center clusters in Northern Virginia and Phoenix retrofit evaporative cooling towers with precision aluminum corrosion inhibition programs.
Germany
Industrial manufacturing circuits in the Ruhr and Bavaria demand captive membrane technology for extended service intervals in closed-loop systems. REACH authorization procedures for biocidal active substances tighten formulation flexibility, forcing reformulation toward DBNPA alternatives. Chemical suppliers in Ludwigshafen accelerate registration dossiers for novel quaternary ammonium compounds.
China
Coastal refinery complexes in Shandong and Guangdong pilot electrochemical scale prevention as a chemical-free alternative to phosphonate-dependent programs. The Ministry of Ecology and Environment tightens discharge standards for industrial cooling systems. Yangtze River Delta manufacturing reshoring expands closed-loop treatment program scope.
India
Textile and pharmaceutical processing clusters in Gujarat and Maharashtra lack captive water treatment expertise, creating white space for outsourced chemical management contracts. Central Electricity Authority guidelines shape thermal power plant cooling water chemistry protocols. Chennai and Hyderabad data center construction drives evaporative cooling chemical volumes.
Saudi Arabia
Desalination-integrated power plants on the Gulf coast dose aggressive scale inhibitors against extreme hardness and temperature conditions. The national water regulator imposes discharge temperature limits that shape local formulation requirements. Jubail Industrial City petrochemical complexes represent concentrated demand for open-loop biocide programs.
Cooling Water Treatment Chemicals Market Vendor Landscape
On the supply side, the industry is consolidating around chemical suppliers with captive analytical laboratories and field engineering capabilities capable of underwriting performance guarantees. Three strategic archetypes dominate: polymer chemistry specialists serving high-stress evaporative applications, membrane technology integrators extending service intervals in closed loops, and digital platform bundlers tying chemical supply to efficiency metrics. Competitive moves concentrate on M&A to acquire IoT dosing capabilities and strategic partnerships to secure phosphonate intermediate supply.
Among Nordic and Japanese specialists, Kemira and Kurita Water Industries Ltd occupy positions anchored in regional power cluster relationships and captive technology development. Ecolab Inc. exemplifies the platform-native archetype, bundling digital capabilities with formulation supply to displace transactional procurement in multi-site industrial portfolios. These three companies represent distinct competitive vectors: polymer chemistry depth, membrane integration expertise, and performance-guaranteed service models.
| Leading Market Players |
|---|
| Kemira |
| Kurita Water Industries Ltd |
| Ecolab Inc. |
| Buckman |
| ChemTreat Inc. |
| Veolia |
| Nouryon |
| DuBois Chemicals |
| Solenis |
| Others |
Supply Flow & Price Mechanics
German and Chinese phosphonate intermediate manufacturers anchor feedstock pricing, concentrating margin capture upstream while downstream formulators absorb volatility through long-term offtake contracts. This upstream concentration forces United States and European blenders to index pricing against acrylic acid derivative spot markets, compressing formulation margins when feedstock costs spike.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake pricing, with premium-mid-economy pricing differentiation driven by certification grade and volume scale. Price differentiation separates EPA-compliant formulations from standard industrial grades, with the latter facing cost compression due to halogenated biocide discharge restrictions. Power generation utilities exhibit the highest price sensitivity, while data center operators prioritize performance guarantees over unit cost.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk assessment for acrylic acid derivatives and specialty polymer feedstocks. Manufacturing concentrates in Germany, China, and the United States, with raw material dependencies centering on phosphonate intermediates, isothiazolinone biocide actives, and molybdate corrosion inhibitors. Single-source vulnerability in Chinese phosphonate production feeds from concentrated intermediate capacity. Distribution runs through Rotterdam and Houston chemical corridors to regional blending facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where IoT-enabled dosing systems are collapsing transactional chemical supply into performance-guaranteed service models, with interoperability between sensor hardware and cloud analytics becoming the critical ecosystem battleground.
For Market Incumbents: Build captive analytical laboratory moats to underwrite heat transfer efficiency guarantees that displace transactional procurement. Deepen backward integration into phosphonate intermediate production to secure feedstock cost control against Chinese supply volatility. Acquire IoT dosing platform capabilities before platform-native competitors capture multi-site industrial portfolios. For New Entrants and Emerging Players: Pursue outsourced chemical management contracts in India's textile and pharmaceutical processing clusters, where captive water treatment expertise remains scarce. Target closed-loop manufacturing circuits in reshoring geographies as the most penetrable application segment. Lead with digital platform bundling that ties chemical supply to measurable efficiency outcomes rather than volume-based supply. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed regional water treatment specialists that lack captive membrane technology or field engineering scale. Long-term viability favors vendors with performance-guaranteed service models and multi-site underwriting capabilities. Watch electrochemical scale prevention pilot results in Texas and Florida coastal power plants as the signal indicating potential hardware substitution of the largest product-type revenue segment.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phosphonate Intermediates | Secures feedstock cost control against German and Chinese supply concentration. |
| IoT Dosing Platform Acquisition | Captures smart dosing capabilities essential for performance-guaranteed service models. |
| Long-term Supply Agreement with Power Utilities | Locks in replacement chemical volumes from aging United States thermal fleets. |
| Joint Venture in India's Processing Clusters | Establishes outsourced chemical management presence in white-space geographies. |
| Green Manufacturing Transition | Aligns formulation portfolios with REACH authorization and PFAS substitution mandates. |
Methodological Framework
Initial hypotheses were tested against primary input from plant managers at power generation facilities, procurement leads at downstream manufacturing OEMs, distribution channel partners in specialty chemical corridors, and technical R&D directors at formulation companies, then refined against customs and trade data, American Chemistry Council and Cefic industry reports, SEC 10-K filings, and EPA effluent limitation guideline documents. Bottom-up segmentation modeling and top-down macroeconomic anchoring were cross-validated to ensure analytical consistency.
Demand-supply balance dynamics across the analysis window were modeled through segmentation by grade tier, end-use industry, application system type, and regional production hub. CAGRs were derived from trend extrapolation of replacement chemical volumes and new installation demand. Forecast inputs incorporated EPA Section 316(b) enforcement timelines and data center liquid cooling retrofit acceleration patterns.
Macroeconomic conditions sit as an overlay; deviation in industrial power demand, feedstock energy costs, or trade policy stringency would shift the trajectory. Forecasts reflect documented assumptions about regulatory implementation pace and technology substitution rates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water & Sludge Treatment
Aquarium Water Treatment Market
Water & Sludge Treatment
Africa Water Treatment Chemicals Market
Water & Sludge Treatment
Oil and Gas Water Treatment Chemicals Market
Water & Sludge Treatment
Ultrapure Water Market
Water & Sludge Treatment
South America Membrane Water and Wastewater (WWT) Treatment Market
Water & Sludge Treatment
Water Gel Market
Water & Sludge Treatment
Global Valves in Water and Wastewater Market
Water & Sludge Treatment
United States Water Treatment Chemicals Market
Water & Sludge Treatment
Electrodeionization (EDI) Technology Market
Water & Sludge Treatment
Global Water Clarifiers Market
Water & Sludge Treatment
Europe Water Treatment Chemicals Market
Water & Sludge Treatment
US Liquid Waste Management Market
Water & Sludge Treatment
Global Wood Activated Carbon Market
Water & Sludge Treatment
North America Water Treatment Chemicals Market
Water & Sludge Treatment
Water Softening Systems Market
Water & Sludge Treatment
Europe Membrane Water Treatment Chemicals Market