
 Global Submerged Coil Heat Exchanger Market | 2026-2036
Global Submerged Coil Heat Exchanger Market Size, Share, and Industry Trends Forecast 2026-2036
Global Submerged Coil Heat Exchanger Market Outlook
ASME Section VIII certification-grade fabrication is redrawing competitive boundaries in submerged coil heat exchanger supply. Alfa Laval leverages its marine-certified production lines to dominate Nordic offshore installations. Kelvion Holding GmbH anchors European chemical processing demand through specialized corrosion-resistant alloy coils. SPX Flow competes in food-grade sanitary designs with extensive clean-in-place validation capabilities.
A submerged coil heat exchanger consists of helical or serpentine tubing bundles immersed directly within a process fluid vessel, typically fabricated from stainless steel 316L, titanium, or Hastelloy alloys, with heat transfer coefficients ranging from 200 to 800 W/m²K depending on coil geometry and fluid agitation. Its primary purpose is to heat or cool tank contents without external pumping loops, minimizing footprint in batch chemical reactors and cryogenic storage systems. Shell & tube configurations retain the largest installed base across heavy chemical processing, while plate-type submerged coils capture faster growth in pharmaceutical bioreactor temperature control where cleanability mandates dominate specification sheets. HVAC applications represent a mature margin pool with established replacement cycles, whereas offshore installations command premium pricing due to ABS and DNV certification requirements.
EPA refrigerant management rules under Section 608 shape product development timelines for US-manufactured coils, while the EU F-Gas Regulation phases down hydrofluorocarbon-based heat transfer fluids in European equipment. China's GB standards for pressure vessels and Japan's METI energy-efficiency labeling program create divergent compliance pathways across major manufacturing geographies. Stakeholders must monitor refrigerant chemistry transitions and pressure equipment directive harmonization to anticipate specification shifts before they disrupt procurement cycles.
Market Dynamics
Corrosion-resistant alloy substitution is compressing procurement cycles across chemical processing and offshore energy installations, forcing fabricators to requalify welding procedures and pressure-test protocols at unprecedented velocity.
Growth Catalysts
- EU F-Gas Regulation phase-down:Hydrofluorocarbon restrictions in European process cooling systems accelerate replacement of conventional shell-and-tube bundles with submerged coil designs compatible with natural refrigerants.
- Offshore platform electrification:North Sea and Gulf of Mexico operators specify ABS-certified titanium coils for subsea thermal management in floating production systems.
- Stainless steel 316L tubing:Pharmaceutical bioreactor manufacturers specify this alloy for clean-in-place validation compliance, expanding coil demand in batch temperature control.
Market Restraints
- Titanium sponge price volatility:Aerospace and medical sectors compete for limited sponge supply, compressing margins on corrosion-resistant coil fabrication.
- ASME Section VIII certification backlog:Qualified third-party inspectors concentrate in Germany and the United States, extending lead times for pressure vessel compliance documentation.
- Plate-type heat exchanger substitution:Compact welded plate designs capture pharmaceutical cleanability specifications previously held by submerged coils in small-volume reactor applications.
Strategic Opportunities
- India specialty chemical expansion:Gujarat and Maharashtra industrial corridors lack localized submerged coil fabrication, creating import substitution potential for certified regional producers.
- Green hydrogen electrolyzer thermal management:Alkaline and PEM electrolysis systems require submerged cooling coils for electrolyte temperature stabilization at megawatt scale.
- Carbon border adjustment mechanism:EU CBAM incentivizes European fabricators to source low-carbon titanium and nickel alloys, rewarding early supply chain decarbonization investments.
Industry Challenges
- Orbital TIG welding technician scarcity:Precision tube-to-tubesheet welding for Hastelloy coils requires certifications held by fewer than 200 specialists across North America and Europe.
- Legacy DNV-GL certification migration:Offshore operators demand updated DNV-ST-C203 documentation for fatigue life assessment, forcing recertification of installed coil fleets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Submerged Coil Heat Exchanger Market |
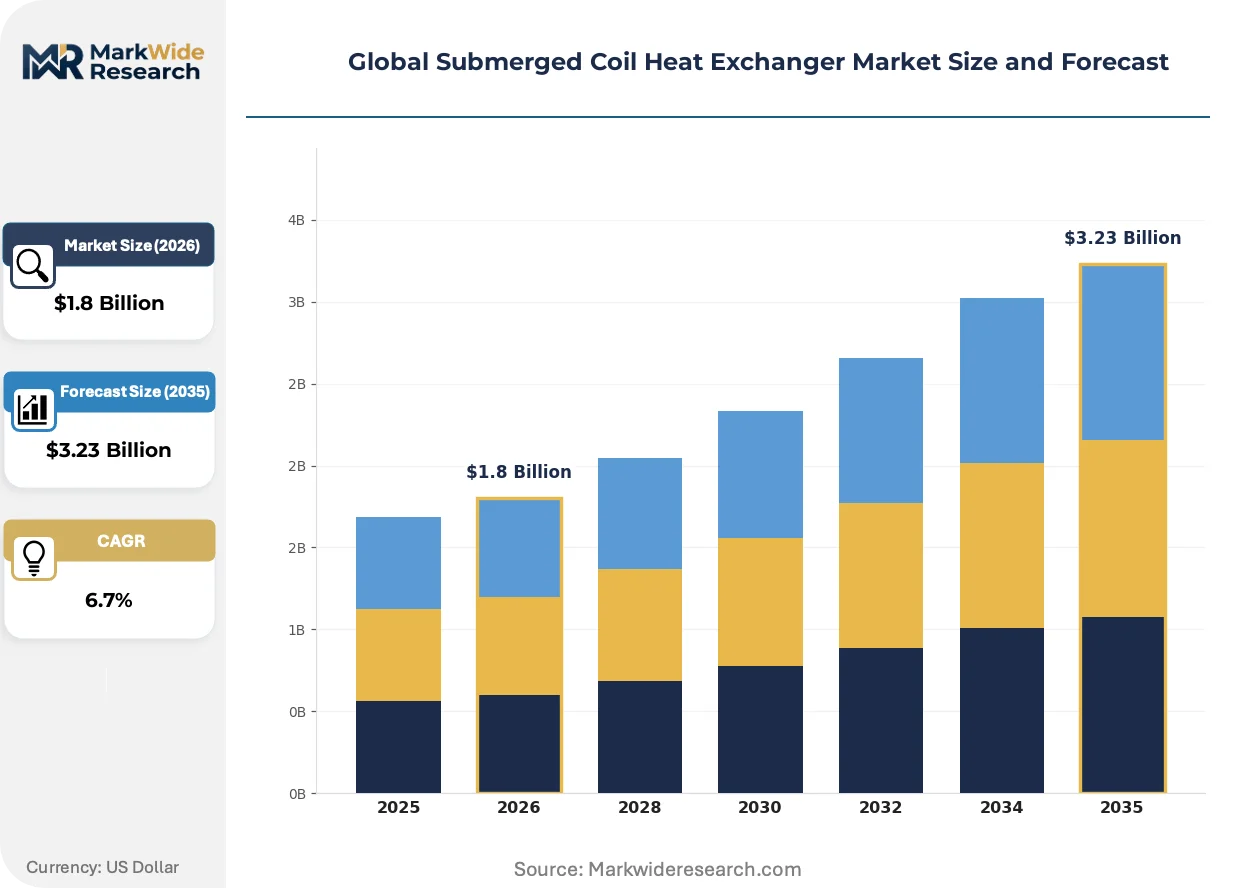
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shell & Tube, Plate, Air Cooled, Double Pipe Application: Chemical Processing, Oil & Gas, Food & Beverage, HVAC End User: Manufacturing, Energy, Pharmaceutical, Marine Installation Type: Onshore, Offshore, Industrial, Commercial |
| Companies Covered | Alfa Laval, Kelvion Holding GmbH, SPX Flow, Standard Xchange, API Heat Transfer, Hughes Anderson, Brask, Danfoss, GEA Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Submerged Coil Heat Exchanger Market Strategic Shifts
Additive manufacturing of titanium coil manifolds is compressing lead times for complex geometries previously machined from solid billet, while digital twin integration enables predictive corrosion monitoring in submerged applications.
Serpentine coil geometries with enhanced surface roughness are fragmenting the traditional helical design standard. Offshore platform operators in Norway specify these profiles for improved heat transfer coefficients in crude oil preheating vessels. The technology is fragmenting procurement specifications across North Sea engineering contractors, forcing design houses to maintain parallel calculation methodologies.
EPA Section 608 refrigerant management rules mandate leak detection and repair protocols for heat transfer systems above 50-pound charge thresholds. US chemical processors now specify hermetically sealed submerged coils to minimize fugitive emissions liability. Food-grade facilities in California and Texas accelerate retrofit timelines to preempt state-level enforcement variations.
Specification authority is migrating from engineering-procurement-construction firms to end-user reliability teams. Chemical operators in Germany and China now issue detailed welding procedure specifications directly to coil fabricators, compressing traditional distributor channels. This pattern concentrates most visibly in BASF Ludwigshafen and Sinopec Zhenhai refinery expansion projects.
Global Submerged Coil Heat Exchanger Market Segmentation
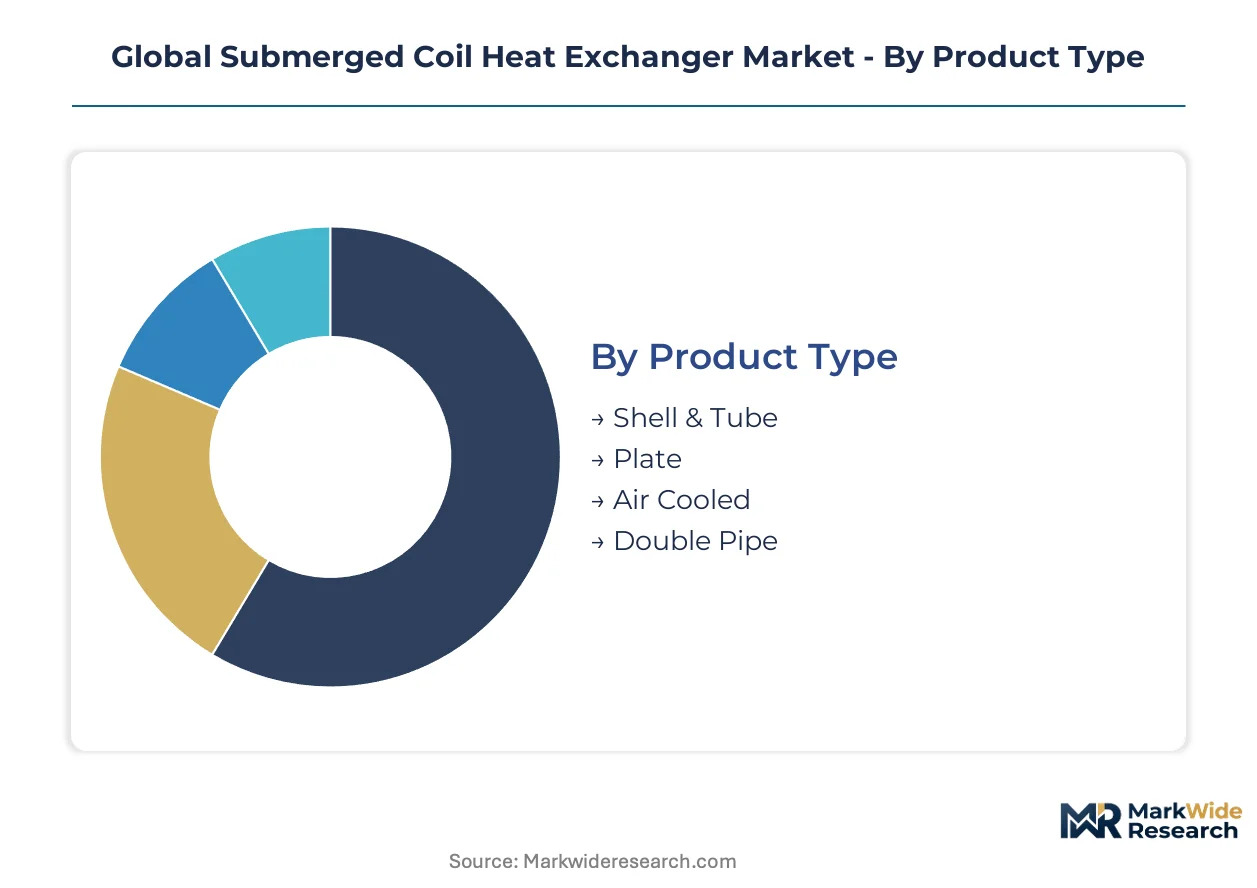
Submerged coil heat exchanger procurement patterns diverge sharply across product geometries and installation contexts, with regulatory compliance requirements determining specification authority in each segment cluster.
Product Type:
EU F-Gas Regulation phase-down mandates and EPA Section 608 refrigerant management rules create divergent certification burdens across coil geometries, with natural refrigerant compatibility becoming the dominant selection filter.
- Shell & Tube:Concentric tube bundles with fixed tube sheets dominate heavy chemical processing installations. BASF Ludwigshafen and Sinopec Zhenhai specify these configurations for batch reactor temperature control, driven by ASME Section VIII pressure vessel compliance requirements and established maintenance protocols.
- Plate:Compact welded plate coils with enhanced surface area density capture pharmaceutical bioreactor specifications previously held by tubular designs. Clean-in-place validation requirements from FDA and EMA favor these geometries in sterile processing environments.
- Air Cooled:Finned coil assemblies for process cooling in water-scarce regions.
- Double Pipe:Concentric tube-in-tube configurations for high-pressure hydrocarbon service.
Established volume favors Shell & Tube; emerging adoption favors Plate.
Application:
Cost tier differentiation separates premium corrosion-resistant alloys from standard stainless specifications, with titanium and Hastelloy commanding multiples in offshore and aggressive chemical service.
- Chemical Processing:Batch reactor cooling and heating applications specify 316L, titanium, or Hastelloy coils depending on acid concentration and chloride exposure. Gujarat and Maharashtra industrial corridors in India lack localized fabrication capacity, forcing import dependence for corrosion-resistant designs.
- Oil & Gas:Floating production systems in the North Sea and Gulf of Mexico demand ABS-certified and DNV-ST-C203 compliant coils for subsea thermal management. Norway's Equinor and US operators specify enhanced surface roughness serpentine geometries for crude oil preheating vessels.
- Food & Beverage:Sanitary-grade 316L coils with clean-in-place validation for dairy and beverage processing.
- HVAC:Mature replacement market with established stainless steel specifications for commercial building thermal storage.
Margin concentration sits with Oil & Gas; volume scale concentrates in Chemical Processing.
End User:
Customer type determines specification authority migration patterns, with reliability engineering teams displacing traditional procurement channels in concentrated end-user segments.
- Manufacturing:General industrial process heating and cooling across discrete manufacturing sectors.
- Energy:Green hydrogen electrolyzer thermal management represents emerging demand concentration. Alkaline and PEM electrolysis systems at megawatt scale require submerged cooling coils for electrolyte temperature stabilization.
- Pharmaceutical:Batch bioreactor temperature control with stringent cleanability mandates. EMA and FDA validation requirements drive 316L specification with orbital TIG welding protocols.
- Marine:Offshore platform and subsea installations with ABS and DNV certification requirements.
Specification authority concentrates in Pharmaceutical; certification complexity peaks in Marine.
Installation Type:
Geography-linked regulatory regimes fragment procurement standards, with EU CBAM carbon border adjustments and divergent pressure equipment directives creating compliance complexity.
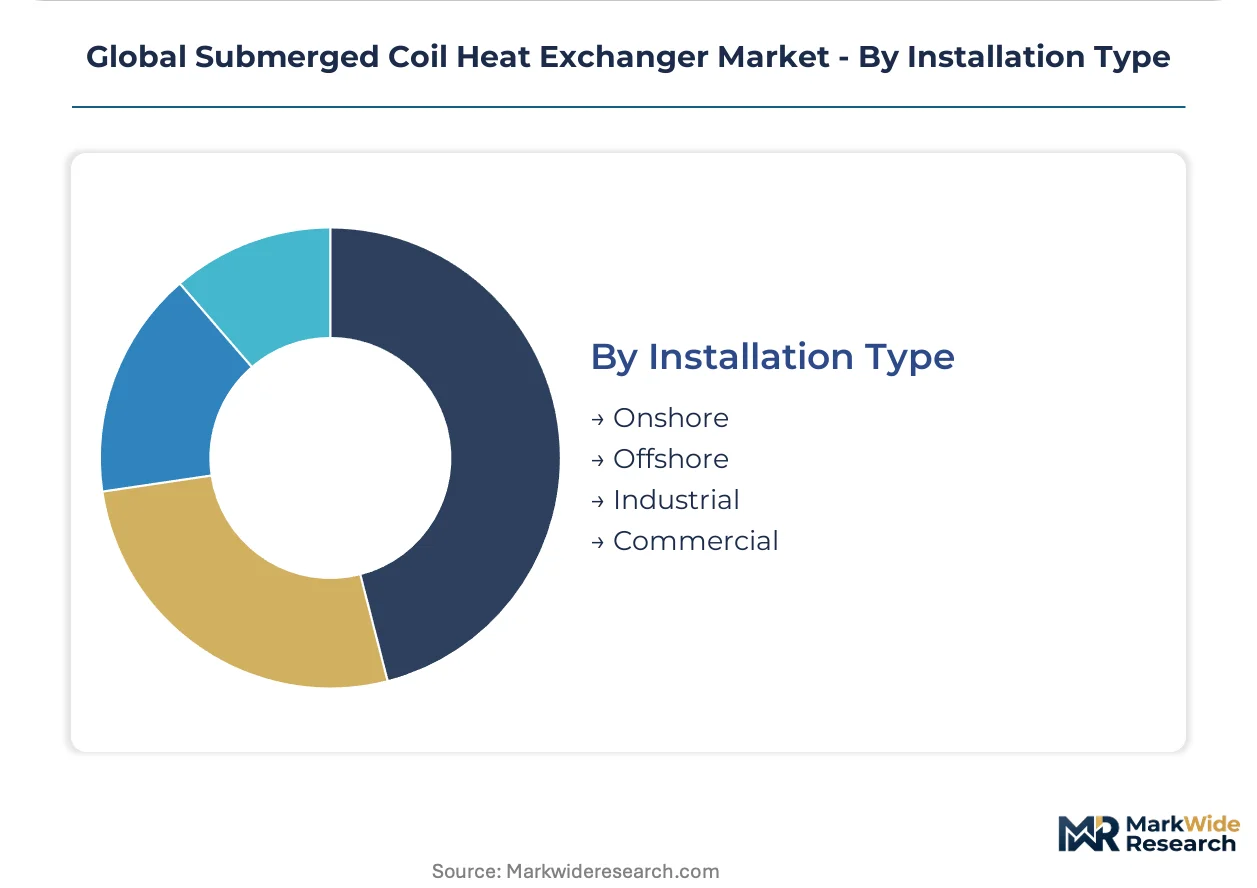
- Onshore:Fixed industrial facilities with established ASME and GB standard compliance pathways. Germany's TÜV and China's SAMR inspection regimes dominate qualification timelines.
- Offshore:Floating production systems and subsea installations with DNV-ST-C203 fatigue life assessment requirements. Norway, UK, and US Gulf Coast operators drive specification for titanium coils in corrosive seawater environments.
- Industrial:Heavy process manufacturing with batch operation cycles.
- Commercial:Building services and light industrial applications with standardized maintenance intervals.
Lead time compression favors Onshore; premium pricing concentrates in Offshore.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances in corrosion-resistant alloy coils concentrate procurement leverage in Germany, China, and the United States, where fabrication capacity outstrips domestic demand. India and Japan remain net importers of ASME-certified pressure vessel components.
United States
Gulf Coast petrochemical expansions in Texas and Louisiana drive titanium coil specifications for sour gas service. EPA Section 608 refrigerant management rules mandate hermetic sealing for systems above 50-pound charge thresholds. Houston engineering firms now issue welding procedure specifications directly to fabricators, bypassing traditional distributor channels.
Germany
BASF Ludwigshafen and Bayer Leverkusen anchor European demand for Hastelloy coils in chlor-alkali processing. EU F-Gas Regulation phase-down accelerates natural refrigerant-compatible submerged coil retrofits. TÜV inspection backlogs extend ASME Section VIII certification timelines to 14 weeks for pressure vessel compliance documentation.
China
Sinopec Zhenhai and private chemical operators in Shandong specify 316L coils for batch reactor temperature control. GB standards for pressure vessels and SAMR inspection regimes create divergent compliance pathways from Western certification. Yangtze River Delta fabricators lack orbital TIG welding capacity for pharmaceutical-grade bioreactor coils.
India
Gujarat and Maharashtra specialty chemical corridors lack localized submerged coil fabrication, forcing import dependence for corrosion-resistant designs. BIS pressure equipment standards remain partially harmonized with ASME, creating dual-certification burdens. Reliance Industries Jamnagar complex sources titanium coils from European suppliers due to domestic capability gaps.
Japan
Tokyo Bay chemical processors specify compact plate-type submerged coils for pharmaceutical bioreactor applications. METI energy-efficiency labeling programs incentivize heat transfer coefficient optimization in process cooling systems. Osaka-based engineering houses concentrate specification authority for offshore platform electrification projects in Southeast Asian waters.
Global Submerged Coil Heat Exchanger Market Competitive Environment
Listed leaders compete with private specialists across certification-grade fabrication, creating tiered supply dynamics. The vendor base concentrates around ASME Section VIII qualified shops in Germany and the United States, with capability scarcity compressing procurement cycles. Three archetypes dominate: marine-certified offshore specialists, pharmaceutical-grade sanitary fabricators, and corrosion-resistant alloy generalists. Strategic moves center on backward integration into titanium sponge sourcing and geographic expansion into India's import-dependent chemical corridors.
Among Nordic marine-certified producers, Alfa Laval occupies a position exemplifying offshore electrification demand capture. German GmbH-structured entities including Kelvion Holding GmbH anchor European chemical processing specifications through specialized alloy capabilities. SPX Flow represents the sanitary-grade archetype, with clean-in-place validation positioning in food and pharmaceutical segments. These three fabricators collectively illustrate how certification authority and alloy specialization stratify competitive positioning across divergent end-use requirements.
| Leading Market Players |
|---|
| Alfa Laval |
| Kelvion Holding GmbH |
| SPX Flow |
| Standard Xchange |
| API Heat Transfer |
| Hughes Anderson |
| Brask |
| Danfoss |
| GEA Group |
| Others |
Value Chain & Pricing Dynamics
Corrosion-resistant alloy substitution toward titanium and Hastelloy coils is redrawing supply geography toward Germany and the United States while compressing pricing economics for standard 316L stainless configurations. This material shift simultaneously elevates certification premiums for ASME Section VIII-compliant fabricators and erodes margins on commodity-grade tubular bundles.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation separates ABS-certified titanium coils for offshore platforms from sanitary-grade 316L for pharmaceutical bioreactors and commodity stainless bundles for HVAC retrofits. Pricing pressure stems from titanium sponge competition with aerospace and medical sectors, compressing margins on corrosion-resistant fabrication. Chemical processors in Germany exhibit lowest price sensitivity due to EU F-Gas Regulation compliance mandates, while Indian specialty chemical operators demonstrate highest sensitivity given import dependence and BIS dual-certification burdens.
Supply Chain Analysis
Container availability constraints on Hamburg-Shanghai and Rotterdam-Singapore trade lanes extend inbound logistics costs for titanium sponge and nickel alloy feedstock. Supply concentrates in Germany, China, and the United States for ASME-certified pressure vessel fabrication, with raw material dependencies on Ukrainian titanium sponge, Indonesian nickel, and Chinese rare earth processing agents. Single-source vulnerability sits with orbital TIG welding technician scarcity—fewer than 200 certified specialists across North America and Europe. Distribution runs through engineering-procurement-construction firms in mature markets, while direct specification authority from reliability teams is displacing traditional channels in Germany and the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue from predictive corrosion monitoring and recertification management is expanding faster than hardware sales, creating annuity streams that offset titanium raw material volatility.
For Market Incumbents: Shield market position by deepening backward integration into titanium sponge sourcing and expanding orbital TIG welding training partnerships with German TÜV and US ASME accreditation bodies. Plate-type heat exchanger substitution in pharmaceutical bioreactors threatens coil demand in small-volume applications, demanding defensive certification investments in FDA and EMA clean-in-place validation protocols. For New Entrants and Emerging Players: ASME Section VIII certification fast-track through third-party inspector partnerships in Germany offers entry into India's import-dependent Gujarat and Maharashtra chemical corridors. White-space targets include green hydrogen electrolyzer thermal management for alkaline and PEM systems at megawatt scale, and EU CBAM-compliant low-carbon alloy sourcing for European fabricators. Go-to-market positioning should emphasize hermetic sealing capabilities for EPA Section 608 compliance in US chemical processing. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors marine-certified specialists with captive titanium sourcing. Long-term viability over a multi-year window hinges on exposure to offshore platform electrification and green hydrogen buildout cycles. Acquisition target archetype: mid-cap fabricators with DNV-ST-C203 documentation capabilities and underutilized ASME certification capacity. The signal to watch is EU F-Gas Regulation enforcement intensity accelerating natural refrigerant retrofit timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Titanium Sponge | Captive supply secures margin stability against aerospace and medical sector competition. |
| Orbital TIG Welding Certification Expansion | Training partnerships with TÜV and ASME address technician scarcity constraining output. |
| Hermetic Sealing Product Line Development | EPA Section 608 compliance positioning captures US chemical processor retrofit demand. |
| India Regional Fabrication Facility | Localized capacity addresses Gujarat and Maharashtra import dependence for corrosion-resistant designs. |
| Predictive Corrosion Monitoring Platform | Digital twin integration creates recurring service revenue attached to installed coil fleets. |
Study Parameters
A standing panel of plant engineers at BASF Ludwigshafen and Sinopec Zhenhai, procurement leads at Alfa Laval and Kelvion, aftermarket service heads at SPX Flow, and reliability directors at Equinor provided ongoing calibration across the study period. Primary interview findings triangulated against secondary sources including SEC 10-K filings from listed heat exchanger manufacturers, German TÜV and Chinese SAMR pressure vessel certification databases, EU F-Gas Regulation implementation reports, and US EPA Section 608 enforcement data. Bottom-up coil shipment analysis by alloy grade and geometry cross-validated against top-down chemical processing capacity expansion tracking.
Consistency checks validated volume and value outputs against external benchmarks including industrial heat exchanger trade flows and regional pressure vessel import statistics. The analytical framework modeled segmentation across product geometry, application severity, end-user specification authority, and installation regulatory regime throughout the forecast period. CAGRs derived from alloy-grade demand curves, certification backlog timelines, and retrofit cycle analysis for EU F-Gas and EPA refrigerant compliance. Industry-specific inputs included titanium sponge price indices, orbital TIG welding technician supply estimates, and green hydrogen electrolyzer deployment pipelines.
Underlying assumptions cover sustained EU F-Gas phase-down enforcement, stable ASME Section VIII certification capacity, and continued titanium sponge supply competition from aerospace, with deviation risk concentrated in China GB standard harmonization delays and India BIS certification pathway changes. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
US Residential Furnace Market
HVAC Equipment
Linear Slot Diffuser Market
HVAC Equipment
Global Portable Air Conditioner Market
HVAC Equipment
US Compressed Air Treatment Equipment Market
HVAC Equipment
Underfloor Air Distribution Systems Market
HVAC Equipment
United States HVAC Equipment and Services Market
HVAC Equipment
Hydronic Radiators Market
HVAC Equipment
Air Conditioning Systems Market
HVAC Equipment
Radiant Heating and Cooling Systems Market
HVAC Equipment
Global Home Ventilation System Market
HVAC Equipment
United States Residential Heating Equipment Market
HVAC Equipment
Air Conditioning Equipment Market
HVAC Equipment
Europe Air Conditioning Equipment Market
HVAC Equipment
Commercial Water Heater Market
HVAC Equipment
US HVAC Services Market
HVAC Equipment
GCC Portable Air Conditioners Market