
 Germany Commercial HVAC Market | 2026-2036
Germany Commercial HVAC Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Commercial HVAC Market Insights
Germany is rewriting competitive dynamics in commercial climate systems through precision manufacturing and energy efficiency integration. Robert Bosch GmbH leverages its Stuttgart engineering base to dominate heat pump development for mid-scale commercial properties. Vaillant Group anchors the retrofit segment with modular gas-to-electric transition systems. Daikin Industries Ltd competes through VRF technology leadership in premium office installations across Frankfurt and Munich.
Germany Commercial HVAC encompasses engineered systems for temperature, humidity, and air quality management in non-residential buildings, typically operating between 2 kW and 5 MW cooling capacity with seasonal efficiency ratings exceeding 200% for heat pump configurations. These systems serve retail complexes, manufacturing plants, and public infrastructure by maintaining occupant comfort and process-critical environments. Heating systems command established replacement cycles while ventilation and air conditioning segments capture accelerated investment from building energy renovation mandates. Ductless and VRF technologies are displacing legacy ducted configurations in urban commercial retrofits where spatial constraints limit centralized distribution infrastructure.
The EU F-Gas Regulation and Germany's Building Energy Act shape refrigerant selection and system efficiency thresholds, compelling manufacturers to redesign compressor architectures and adopt propane and CO2 alternatives. KBA vehicle certification protocols indirectly influence mobile climate system suppliers with commercial crossover capabilities. Stakeholders must monitor enforcement timelines for the EU AI Act's building automation implications and the CSRD's embodied carbon disclosure requirements affecting equipment procurement criteria.
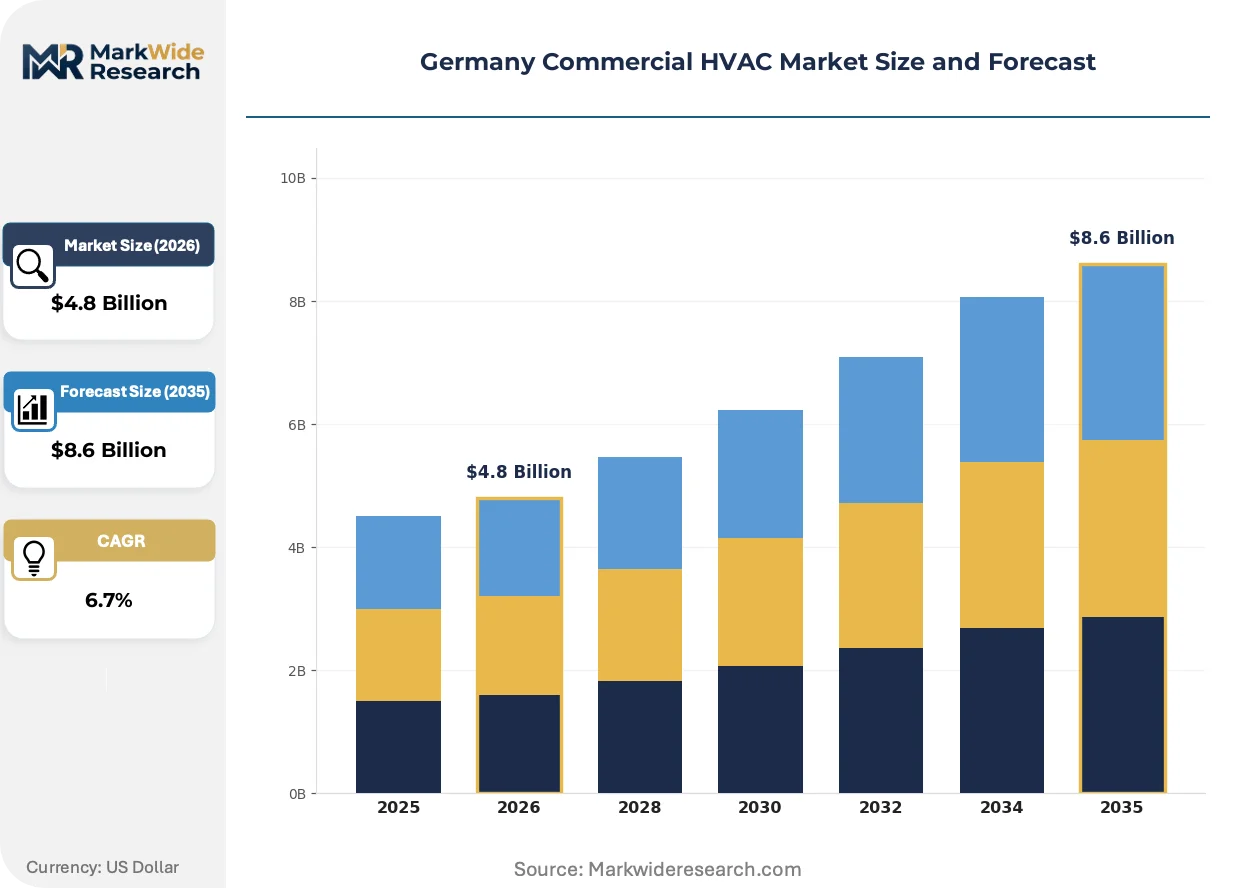
Market Dynamics
The EU F-Gas Regulation is compressing refrigerant options across Germany's commercial HVAC sector, forcing compressor architecture redesigns and accelerating transitions toward propane and CO2 alternatives in systems serving retail complexes and manufacturing plants.
Growth Catalysts
- Data Center Cooling Infrastructure:German data center operators are expanding precision cooling systems to match national digitalization targets, with Bavaria and North Rhine-Westphalia clusters driving procurement of high-capacity chiller and ventilation configurations.
- Building Energy Act Mandates:Germany's Gebäudeenergiegesetz compels energy renovation in existing commercial stock, accelerating replacement cycles for gas-fired heating with heat pump and hybrid electric systems.
- Propane (R290) Refrigerant Transition:Lower-GWP hydrocarbon refrigerants are penetrating mid-scale commercial applications as manufacturers redesign charge-limited systems to comply with phasedown schedules.
Market Restraints
- Copper and Aluminum Input Volatility:Heat exchanger and coil production faces margin pressure from base metal price swings, compressing fabricator profitability on fixed-price installation contracts.
- Compressor Supply Concentration:Scroll and screw compressor manufacturing concentrates among a limited supplier base in Southern Germany and Austria, creating bottleneck risk for OEMs scaling output.
- Refrigerant Handling Certification Friction:Germany's stringent F-gas handler certification requirements limit qualified installer pools, extending project timelines for complex refrigerant transitions.
Strategic Opportunities
- East German Commercial Retrofit Gap:Saxony and Brandenburg office stock retains legacy Soviet-era heating systems, creating white space for modular gas-to-electric transition packages as energy renovation mandates extend eastward.
- AI-Enabled Predictive Maintenance:Machine learning diagnostics converging with IoT sensor networks are opening recurring revenue streams through performance-based service contracts in Frankfurt and Munich premium installations.
- Direct Digital Control Integration:Building automation system vendors are capturing specification influence by embedding HVAC control logic into unified energy management platforms, shifting procurement toward integrated solution providers.
Industry Challenges
- Heat Pump Installer Capacity Shortage:Germany faces a deficit of technicians qualified for refrigerant handling and electrical integration, extending project backlogs and forcing contractors to decline commercial retrofit work.
- Legacy Building Fabric Constraints:Pre-1990s commercial structures in Hamburg and Cologne lack thermal envelope performance for low-temperature heat pump operation, requiring costly building upgrades alongside HVAC replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Commercial HVAC Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Heating, Ventilation, Air Conditioning, Refrigeration End User: Retail, Office Buildings, Industrial Facilities, Educational Institutions Technology: Ducted, Ductless, VRF, Chiller Application: New Construction, Retrofit, Residential, Maintenance |
| Companies Covered | Robert Bosch GmbH, Vaillant Group, Daikin Industries Ltd, Johnson Controls International Plc, Carrier Global Corporation, Viessmann Group, Lennox International Inc, Danfoss A/S, Mitsubishi Electric Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Commercial HVAC Market Trends and Innovations
Digital twin technology is virtualizing system commissioning and performance optimization across Germany's commercial building stock. Three interconnected developments are compressing traditional equipment procurement and service delivery models.
Digital twin platforms for HVAC assets are virtualizing predictive maintenance and energy optimization workflows. Facility managers in Frankfurt financial district towers are deploying these systems to simulate thermal load scenarios before physical commissioning. The technology is virtualizing traditional service contracts by enabling remote fault detection and automated performance tuning, compressing technician dispatch requirements and shifting vendor relationships toward data-driven outcome guarantees.
Germany's transposition of the EU F-Gas Regulation is mandating refrigerant phase-down schedules that compress HFC availability for new commercial installations. The policy forces OEMs to redesign compressor architectures around propane and CO2 charge limits while retraining field service networks on flammable refrigerant protocols. Medium-capacity rooftop units and VRF systems face the steepest compliance curves, with manufacturers accelerating R290 platform launches ahead of 2027 quota reductions.
Performance-based energy service agreements are displacing traditional equipment purchase models among German retail chains and logistics operators. Facility owners in Bavaria manufacturing corridors now prioritize vendors offering guaranteed thermal output per kWh consumed, transferring operational risk to HVAC contractors. This contracting evolution concentrates procurement authority among national service integrators capable of underwriting multi-site performance guarantees, marginalizing regional installation-only contractors.
Germany Commercial HVAC Market Segmentation
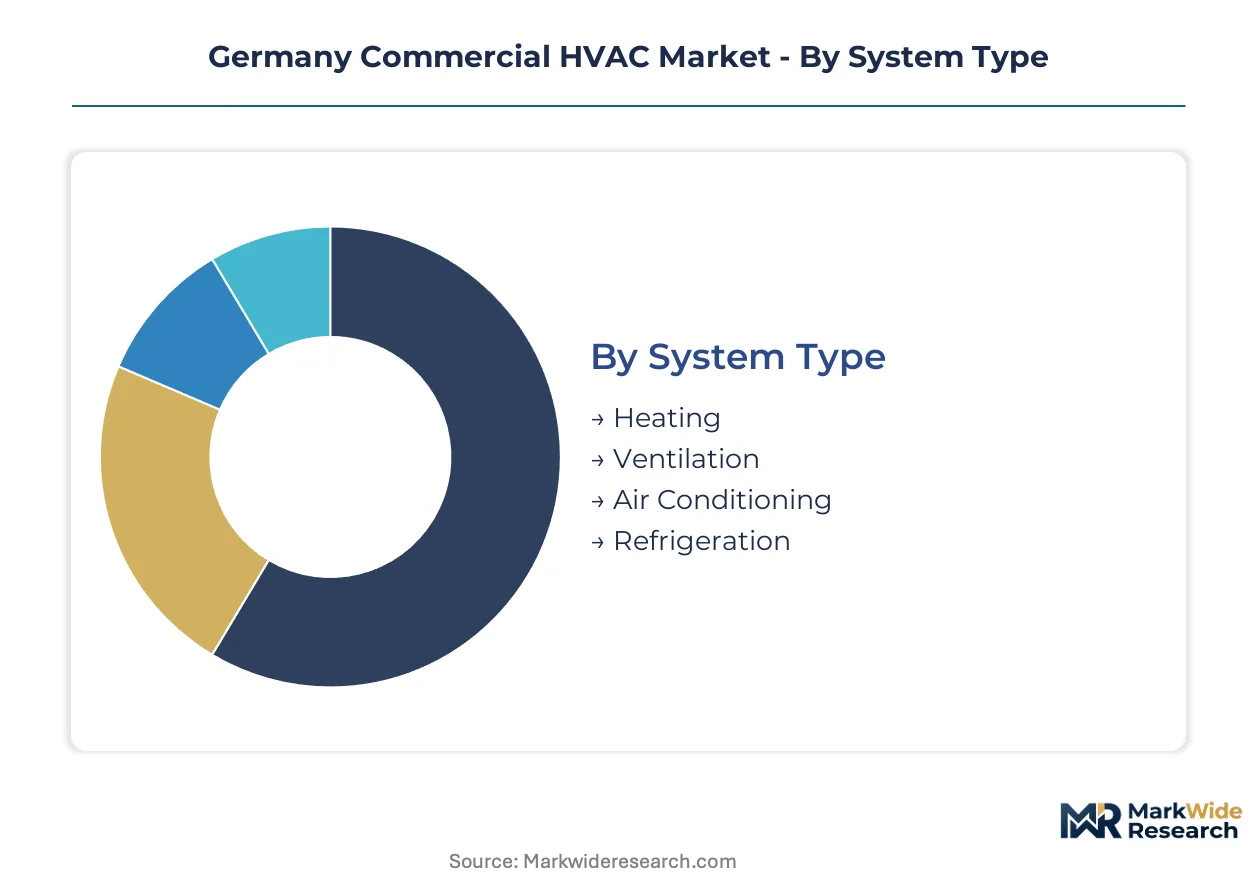
Commercial HVAC procurement in Germany follows distinct replacement rhythms across system categories. Segment-level dynamics reveal where Building Energy Act mandates accelerate turnover versus where legacy equipment persists through extended depreciation cycles.
System Type:
Heating systems command the shortest replacement cycles as Gebäudeenergiegesetz deadlines force gas-to-electric transitions, while refrigeration assets turn over slowest due to capital-intensive chiller infrastructure and long amortization schedules in food processing and cold storage facilities.
- Heating:Heat pump and hybrid electric configurations dominate new specification sheets as fossil fuel bans approach for commercial buildings. Bavaria manufacturing clusters and North Rhine-Westphalia logistics hubs drive accelerated procurement of modular gas-to-electric transition packages.
- Ventilation:Demand concentrates in post-pandemic office retrofits where indoor air quality regulations tightened. Frankfurt financial district towers and Munich corporate campuses prioritize energy recovery ventilation with heat pump integration.
- Air Conditioning:Precision cooling for data centers and server rooms anchors capacity additions. Saxony and Brandenburg emerging data center corridors specify high-efficiency split and packaged units.
- Refrigeration:Industrial cold chain and food service applications sustain demand for CO2 transcritical systems. EU F-Gas Regulation quotas compress HFC availability for supermarket and warehouse installations.
Heating anchors the volume base while ventilation gains share at the steepest rate.
End User:
Procurement authority concentrates differently across customer types, with retail chains centralizing specification decisions nationally while industrial facilities delegate to plant engineering teams with process-specific thermal requirements.
- Retail:National grocery and fashion chains standardize on R290 heat pump packages for storefront networks. Performance-based energy service agreements transfer operational risk to HVAC contractors.
- Office Buildings:Premium installations in Frankfurt and Munich specify VRF with digital twin commissioning. Facility managers prioritize vendors offering guaranteed thermal output per kWh consumed.
- Industrial Facilities:Process-critical environments in automotive and chemical sectors demand custom chiller and ventilation configurations. Hamburg and Cologne manufacturing plants face legacy building fabric constraints limiting low-temperature heat pump deployment.
- Educational Institutions:Public procurement frameworks favor standardized equipment packages with extended service contracts. Municipal building authorities in Berlin and Munich accelerate summer renovation windows.
Industrial facilities command the highest project values while retail expands most quickly through chain-wide standardization mandates.
Technology:
Spatial constraints in dense urban cores favor distributed architectures over centralized ducted systems, with charge-limited hydrocarbon refrigerants penetrating mid-scale applications fastest.
- Ducted:Central air handling units persist in airports, hospitals, and large-format retail where uniform distribution zones dominate. New construction in business parks outside Munich and Stuttgart specifies high-static rooftop configurations.
- Ductless:Split and multi-split systems capture urban commercial retrofits where core drilling and shaft space are restricted. Berlin Kreuzberg and Hamburg Altona office conversions prioritize wall-mounted and ceiling-cassette formats.
- VRF:Variable refrigerant flow dominates premium office and hospitality specifications with simultaneous heating and cooling recovery. Frankfurt banking towers and Munich luxury hotels specify heat recovery VRF with building automation integration.
- Chiller:Water-cooled and air-cooled chillers serve data centers, hospitals, and industrial process cooling above 500kW capacity. Bavaria data center clusters drive procurement of high-efficiency magnetic bearing and free-cooling configurations.
VRF captures specification influence in premium segments while ductless climbs fastest through urban retrofit constraints.
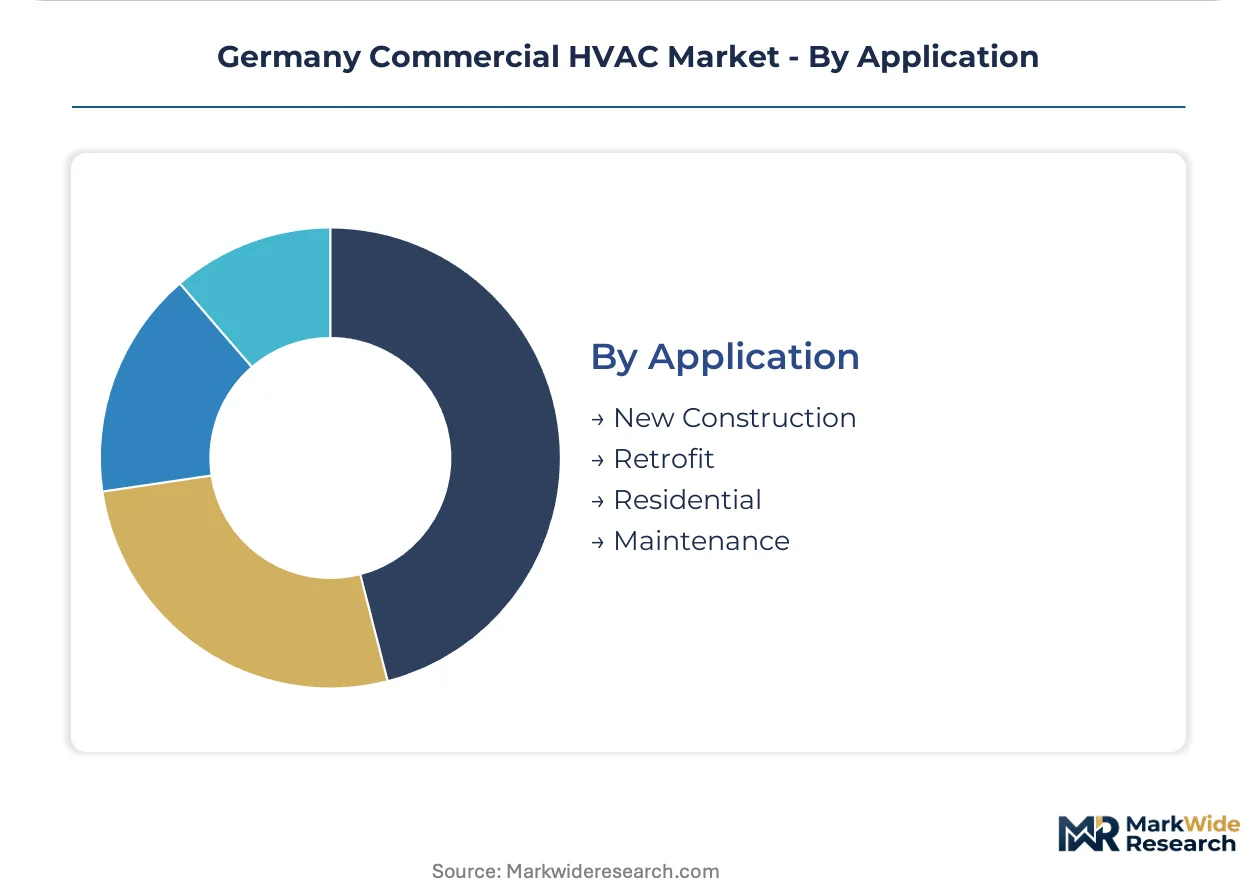
Application:
Project type determines contractor engagement models, with new construction favoring design-build integrators and retrofit work fragmenting across specialized trades facing installer capacity shortages.
- New Construction:Greenfield commercial and industrial projects specify integrated HVAC with building automation from commissioning. Hamburg HafenCity and Frankfurt Europaviertel developments embed heat pump infrastructure from foundation phase.
- Retrofit:Energy renovation mandates accelerate replacement of gas-fired heating in existing stock. East German office buildings in Saxony and Brandenburg retain Soviet-era systems creating white space for modular transition packages.
- Residential:Multi-family commercial-scale systems serve apartment blocks and student housing with centralized plant. Cologne and Düsseldorf residential towers specify air-to-water heat pumps with district heating backup.
- Maintenance:Service contracts shift toward predictive maintenance with IoT sensor networks and machine learning diagnostics. National service integrators capture multi-site agreements from retail and logistics operators.
Retrofit commands the largest project pipeline while maintenance contracts expand most quickly through performance-based contracting evolution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
KBA vehicle certification protocols intersect with commercial climate system supply chains, while the EU F-Gas Regulation shapes refrigerant transitions across German sub-regions. Bavaria and North Rhine-Westphalia anchor procurement clusters for data center cooling and industrial modernization.
Bavaria
Data center operators in Munich and Nuremberg specify high-capacity chiller configurations to match federal digitalization targets. The Building Energy Act compels energy renovation in existing commercial stock across the region. Manufacturing corridors around Augsburg drive procurement of modular gas-to-electric transition packages.
North Rhine-Westphalia
Logistics hubs in Düsseldorf and Cologne accelerate investment in heat pump infrastructure for warehouse climate control. EU F-Gas Regulation quotas compress HFC availability for new supermarket installations. The Ruhr industrial belt sustains demand for process-critical ventilation systems in automotive and chemical facilities.
Baden-Württemberg
Stuttgart engineering clusters dominate heat pump development for mid-scale commercial properties. KBA protocols influence mobile climate system suppliers with commercial crossover capabilities. Precision manufacturing in Mannheim and Karlsruhe drives specification of energy recovery ventilation with building automation integration.
Hesse
Frankfurt financial district towers prioritize VRF systems with digital twin commissioning workflows. The EU AI Act's building automation implications shape procurement criteria for unified energy management platforms. Premium office installations across the Mainhattan skyline specify guaranteed thermal output per kWh consumed.
Berlin-Brandenburg
East German commercial retrofit gaps concentrate in Soviet-era office stock across the capital region. Energy renovation mandates extend eastward, creating white space for modular transition packages. Municipal building authorities accelerate summer renovation windows for educational institutions and public infrastructure.
Germany Commercial HVAC Market Competitive Landscape
Engineering-rooted conglomerates and specialized climate technology groups split the market between integrated system platforms and component-focused supply positions. Diversified industrial holdings anchor heat pump and building automation development through captive manufacturing depth. Pure-play HVAC specialists compete through refrigerant technology leadership and regional service density. Competitive moves concentrate on backward integration into compressor manufacturing and strategic technology licensing for flammable refrigerant handling protocols.
Among Germany-based engineering conglomerates, Robert Bosch GmbH and Vaillant Group occupy positions that exemplify the diversified industrial archetype, leveraging Stuttgart and Remscheid engineering bases respectively to anchor heat pump and modular transition system development. Daikin Industries Ltd represents the multinational climate technology specialist tier, competing through VRF platform leadership in premium commercial installations. These three entities illustrate the competitive tension between integrated domestic engineering depth and global refrigerant technology specialization.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Vaillant Group |
| Daikin Industries Ltd |
| Johnson Controls International Plc |
| Carrier Global Corporation |
| Viessmann Group |
| Lennox International Inc |
| Danfoss A/S |
| Mitsubishi Electric Corporation |
| Others |
Pricing and Supply Chain Analysis
Rhine-Main logistics corridors linking Stuttgart compressor manufacturers to Bavaria data center sites transmit aluminum and copper volatility directly into equipment pricing tiers, compressing margins for fixed-price installation contracts while amplifying regional price spreads between premium VRF configurations and economy heat pump packages.
Pricing Analysis
Price spreads between Frankfurt premium installations and East German retrofit markets exceed fifty percent for equivalent capacity heat pump systems. Three-tier pricing structure across premium, standard, and economy levels differentiates on certification grade and after-sales bundling rather than base equipment specifications. Cost compression in mid-scale commercial segments is intensifying because qualified installer shortages force contractors to absorb training expenses. Municipal procurement frameworks demonstrate highest price sensitivity while data center operators prioritize guaranteed thermal output over unit economics.
Supply Chain Analysis
Extended payment terms from 60 to 90 days now dominate procurement relationships between OEMs and Bavaria fabrication facilities, straining working capital for mid-tier component suppliers. Scroll and screw compressor manufacturing concentrates in Southern Germany and Austria, drawing specialized steel alloys and rare-earth magnet materials from China and Japan. Single-source vulnerability around magnetic bearing chiller components creates bottleneck risk for scaling output. Distribution runs through national service integrators capturing specification influence via multi-site performance guarantees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
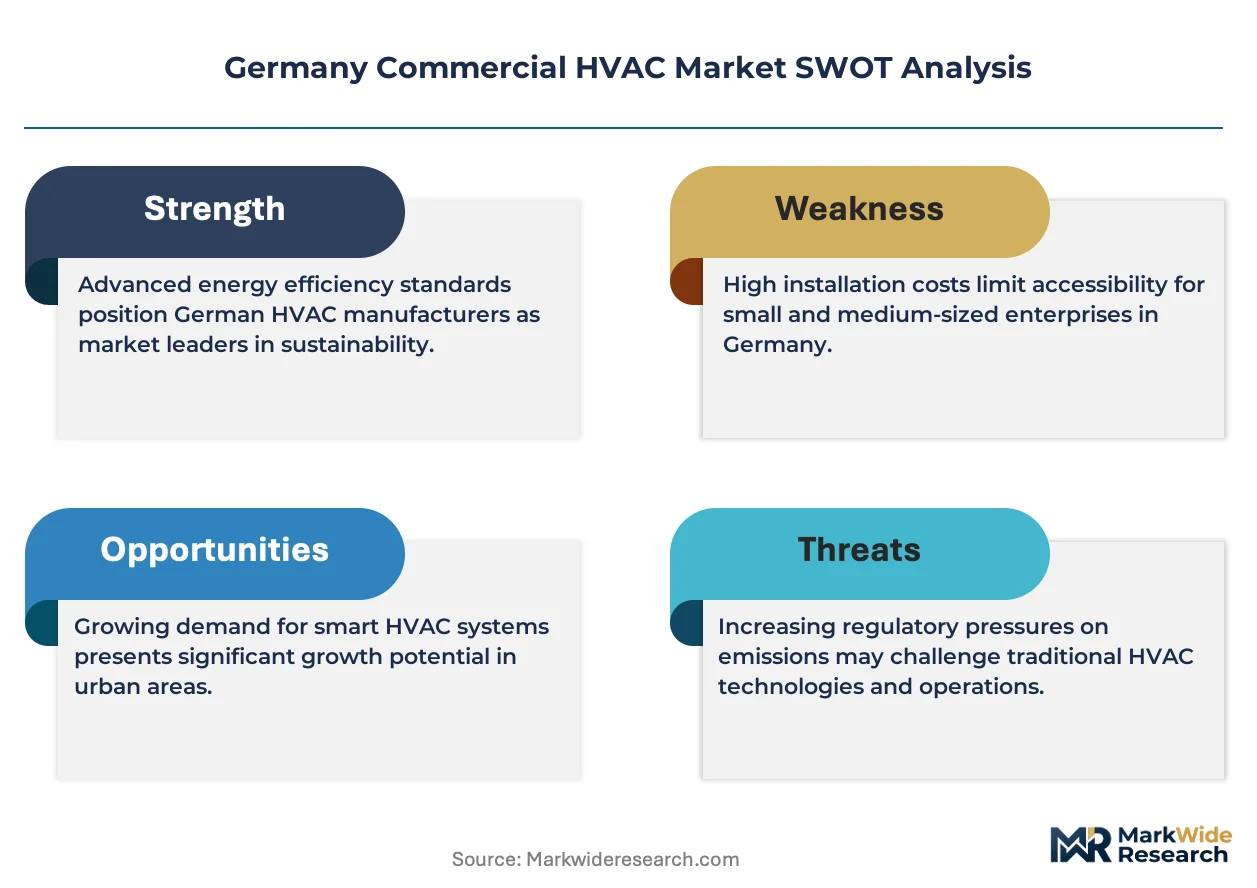
Germany's commercial HVAC sector fragments across refrigerant transition timelines, installer capacity constraints, and building fabric modernization gaps, creating niches for specialists targeting East German retrofit corridors and AI-enabled service contract platforms.
For Market Incumbents: Entrench specification authority by capturing compressor manufacturing through backward integration into Southern Germany fabrication facilities, insulating against supply concentration risk while the EU F-Gas Regulation accelerates refrigerant platform redesign cycles. Deepen building automation integration partnerships to defend against unified energy management platform vendors eroding procurement influence. For New Entrants and Emerging Players: Build out refrigerant handling certification programs targeting Saxony and Brandenburg installer deficits, converting technician training into captive distribution channels for modular gas-to-electric transition packages. White space concentrates in Soviet-era office stock where legacy building fabric constraints demand integrated envelope-HVAC solutions rather than equipment-only sales. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors national service integrators with multi-site performance guarantee underwriting capability and IoT-enabled predictive maintenance platforms. Long-term viability hinges on refrigerant transition execution and AI Act building automation compliance integration. Watch for F-Gas Regulation enforcement acceleration as inflection indicator compressing HFC equipment residual values.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Compressor Manufacturing | Captive supply of scroll and screw compressors from Stuttgart engineering clusters reduces OEM exposure to Austrian supplier bottlenecks. |
| R290 Refrigerant Platform Launch | Charge-limited hydrocarbon systems align with EU F-Gas Regulation phasedown schedules ahead of quota reductions. |
| AI-Enabled Predictive Maintenance Deployment | Machine learning diagnostics embedded in Frankfurt financial district towers shift contracts toward outcome-based recurring revenue. |
| East German Installer Certification Expansion | Qualified technician pools in Saxony and Brandenburg address capacity constraints blocking commercial retrofit project execution. |
| Building Automation System Integration | Unified energy management platforms embedding HVAC control logic capture specification influence from standalone equipment vendors. |
Research Methodology
Operator-level perspectives from HVAC contractor operations directors, facility managers at Frankfurt and Munich premium installations, refrigerant handling certification trainers, and municipal procurement officers anchored the qualitative base. Primary interview findings triangulated against secondary validation from KBA vehicle certification protocols, EU F-Gas Regulation implementation guidance, Building Energy Act enforcement timelines, and regional construction permit databases. Bottom-up equipment shipment analysis and top-down commercial building stock energy renovation mandate tracking converged on segment-level sizing.
Scenario-bracketing framed the analytical approach across the projection horizon, modeling baseline, accelerated renovation, and delayed refrigerant transition pathways. Segmentation dimensions included system type, end-user category, technology architecture, and application mode. CAGRs derived from equipment replacement cycle analysis, regulatory deadline impact assessment, and data center capacity expansion pipelines. Forecast inputs incorporated copper and aluminum price trajectory assumptions, installer training program enrollment rates, and F-Gas quota allocation mechanics.
Stress conditions across base metal price volatility, refrigerant availability constraints, and installer capacity expansion rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory enforcement intensity and technology adoption curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
France Commercial HVAC Market
HVAC Equipment
Residential Heat Pump Market
HVAC Equipment
Heating Radiator Market
HVAC Equipment
North America Industrial Air Chiller Market
HVAC Equipment
Compressor Controllers Market
HVAC Equipment
North America Residential Heat Pump Market
HVAC Equipment
HVAC System Analyzer Market
HVAC Equipment
Automatic Ducting Machine Market
HVAC Equipment
Dedicated Outdoor Air System Market
HVAC Equipment
Recirculating Chillers Market
HVAC Equipment
HVAC Air Handling Units Market
HVAC Equipment
Europe HVAC Field Device Market
HVAC Equipment
India Chillers Market
HVAC Equipment
United States HVAC Equipment and Services Market
HVAC Equipment
Fabric Ducting Market
HVAC Equipment
Europe Heating Radiator Market