
 GCC Water Heater Market | 2026-2036
GCC Water Heater Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Water Heater Market Intelligence
GCC Standardization Organization (GSO) water heater efficiency certifications is collapsing the vendor pool as only manufacturers with documented thermal performance testing can access Saudi and UAE procurement channels. Ariston Thermo SPA leverages its European testing infrastructure to sustain compliance across Gulf markets. A. O. Smith Corporation anchors its position through localized assembly in Saudi Arabia. Rheem Manufacturing Company differentiates via gas-fired tankless specialization suited to high-salinity water conditions.
A water heater is a thermally insulated vessel or instantaneous heat exchanger designed to raise and maintain water temperature between 40°C and 85°C using electric resistance elements, hydrocarbon combustion, solar thermal collectors, or vapor-compression heat pumps, primarily serving hygiene, sanitation, and process hot water needs in buildings and industrial facilities. Storage water heaters dominate replacement cycles across aging residential stock in Kuwait and Bahrain, while heat pump water heaters capture the fastest expansion in UAE commercial retrofits targeting efficiency mandates. Solar water heaters hold concentrated margin pools in Saudi Arabia's hospitality sector, where developers prioritize renewable thermal compliance for project financing.
Saudi Standards, Metrology and Quality Organization (SASO) energy performance labels and UAE's Emirates Authority for Standardization and Metrology (ESMA) efficiency tiers are forcing redesign cycles toward higher insulation values and smart controls. GSO harmonization efforts across Kuwait, Oman, and Qatar are narrowing the gap between national requirements, reducing compliance fragmentation for multi-country suppliers. Stakeholders must monitor how Saudi Arabia's renewable energy integration targets reshape specifications for auxiliary water heating in mixed-use developments.
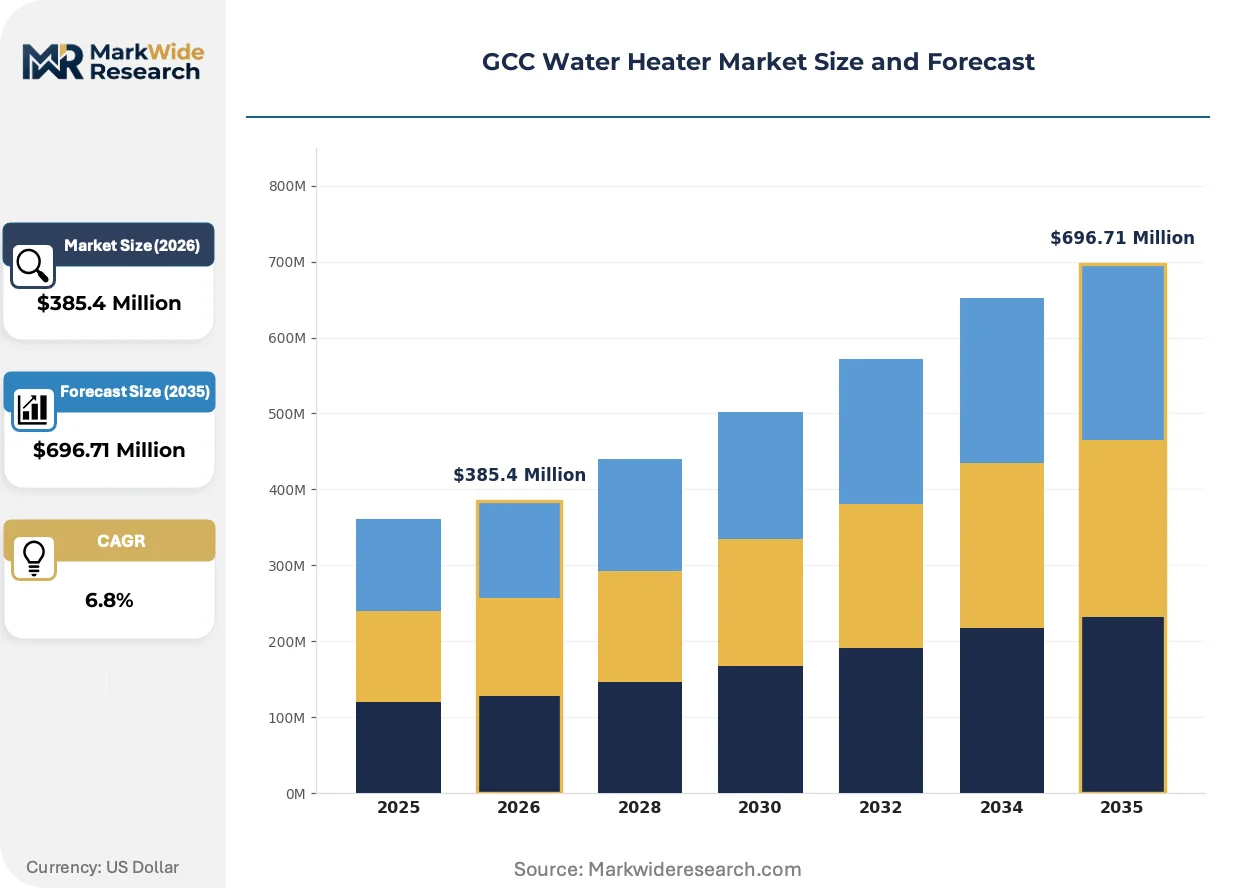
Market Dynamics
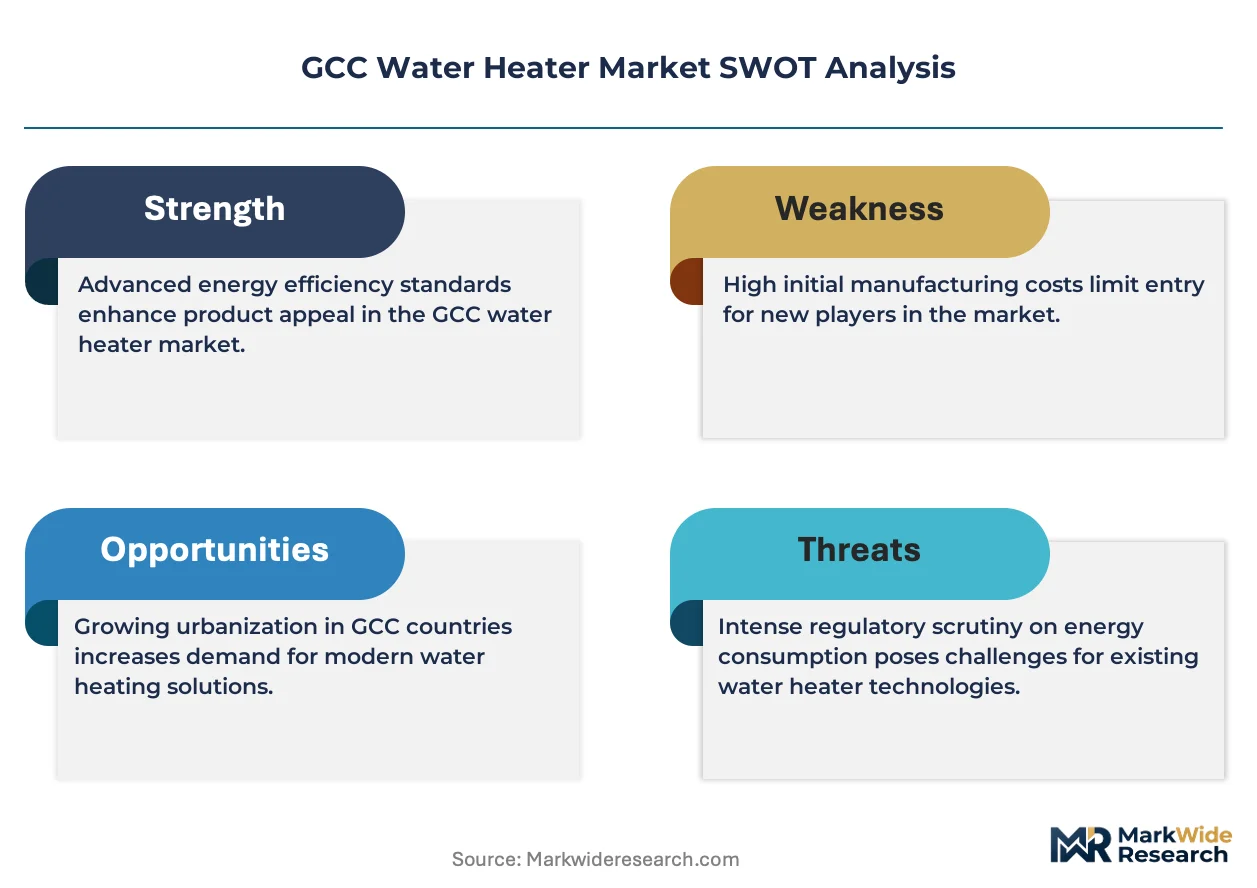
Saudi Arabia's SABER conformity platform and SASO efficiency mandates are compressing the vendor pool by disqualifying manufacturers lacking documented thermal performance testing, forcing Gulf suppliers to rebuild certification infrastructure or exit procurement channels entirely.
Growth Catalysts
- NEOM and Red Sea megaprojects:These developments specify renewable-ready water heating infrastructure, creating dedicated demand corridors for solar thermal and heat pump systems across Saudi Arabia's western province.
- ESMA efficiency tiers:The UAE's Emirates Authority for Standardization and Metrology mandates are accelerating commercial retrofit cycles in Dubai and Abu Dhabi hospitality assets.
- Heat pump water heaters:This technology captures the fastest expansion in UAE commercial buildings targeting operational cost reduction under efficiency compliance deadlines.
Market Restraints
- Copper and stainless steel input volatility:Tank and heat exchanger material costs fluctuate with commodity markets, compressing margin stability for manufacturers serving price-sensitive replacement segments in Kuwait and Bahrain.
- Testing infrastructure concentration:GSO certification validity depends on laboratories concentrated in Riyadh and Dubai, creating bottleneck risk for suppliers outside these hubs.
- High-salinity water corrosion:Coastal installations in Qatar and the UAE face accelerated tank degradation, limiting product lifespan and elevating warranty exposure for standard designs.
Strategic Opportunities
- Oman and Qatar commercial stock:These markets show underpenetrated heat pump adoption relative to Saudi Arabia and the UAE, offering first-mover positioning for efficiency-compliant suppliers.
- Smart control integration:IoT-enabled demand response and predictive maintenance features create differentiation in premium hospitality and healthcare verticals across the Gulf.
- GSO harmonization trajectory:The GCC Standardization Organization's cross-border alignment of efficiency requirements reduces compliance fragmentation, lowering market entry cost for multi-country suppliers.
Industry Challenges
- Thermal engineering talent scarcity:Heat pump system design and commissioning expertise concentrates with European and East Asian specialists, limiting local service capacity expansion.
- Legacy electrical infrastructure retrofit:Aging residential stock in Kuwait and Bahrain requires panel upgrades to support heat pump loads, extending sales cycles and elevating customer acquisition cost.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Water Heater Market |
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $696.71 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Storage Water Heaters, Instant Water Heaters, Solar Water Heaters, Heat Pump Water Heaters Technology: Electric, Gas, Solar, Hybrid End User: Residential, Commercial, Industrial, Hospitality Installation Type: Wall-mounted, Floor-standing, Outdoor, Indoor |
| Companies Covered | Ariston Thermo SPA, A. O. Smith Corporation, Rheem Manufacturing Company, Orbital Horizon, Saudi Ceramics Est., Al Huraiz Est, Whirlpool, General Electric Co., Rinnai Corporation, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Water Heater Market Strategic Shifts & Innovations
Product architectures are diverging as manufacturers optimize for competing regulatory and operational requirements across the Gulf, with efficiency mandates and water chemistry conditions driving specialization rather than standardization.
Heat pump water heater technology is fragmenting competitive positioning across the GCC. These systems extract ambient thermal energy through vapor-compression cycles, delivering efficiency multiples superior to resistance heating. Saudi hospitality developers and UAE commercial retrofitters are specifying heat pumps at accelerating rates. This technology is fragmenting the historical dominance of gas-fired and electric resistance systems, compressing addressable market share for conventional tank manufacturers.
SASO energy performance labels and GSO harmonization protocols are forcing redesign cycles toward higher insulation values and integrated smart controls. Manufacturers must retest entire product lines to maintain SABER platform eligibility, elevating compliance cost for smaller suppliers. Saudi Arabia's megaproject corridor and UAE commercial retrofits face the steepest compliance timelines, with procurement specifications already excluding pre-2023 certified models.
Buyers across Gulf hospitality and healthcare verticals are unbundling equipment procurement from installation and maintenance contracts. Developers now source water heating systems through separate engineering-procurement-construction channels, then negotiate service agreements with specialized contractors. This pattern is most visible in Saudi Arabia's Red Sea and NEOM developments, where renewable thermal compliance requirements demand integrated system design beyond standard product specifications.
GCC Water Heater Market Segmentation
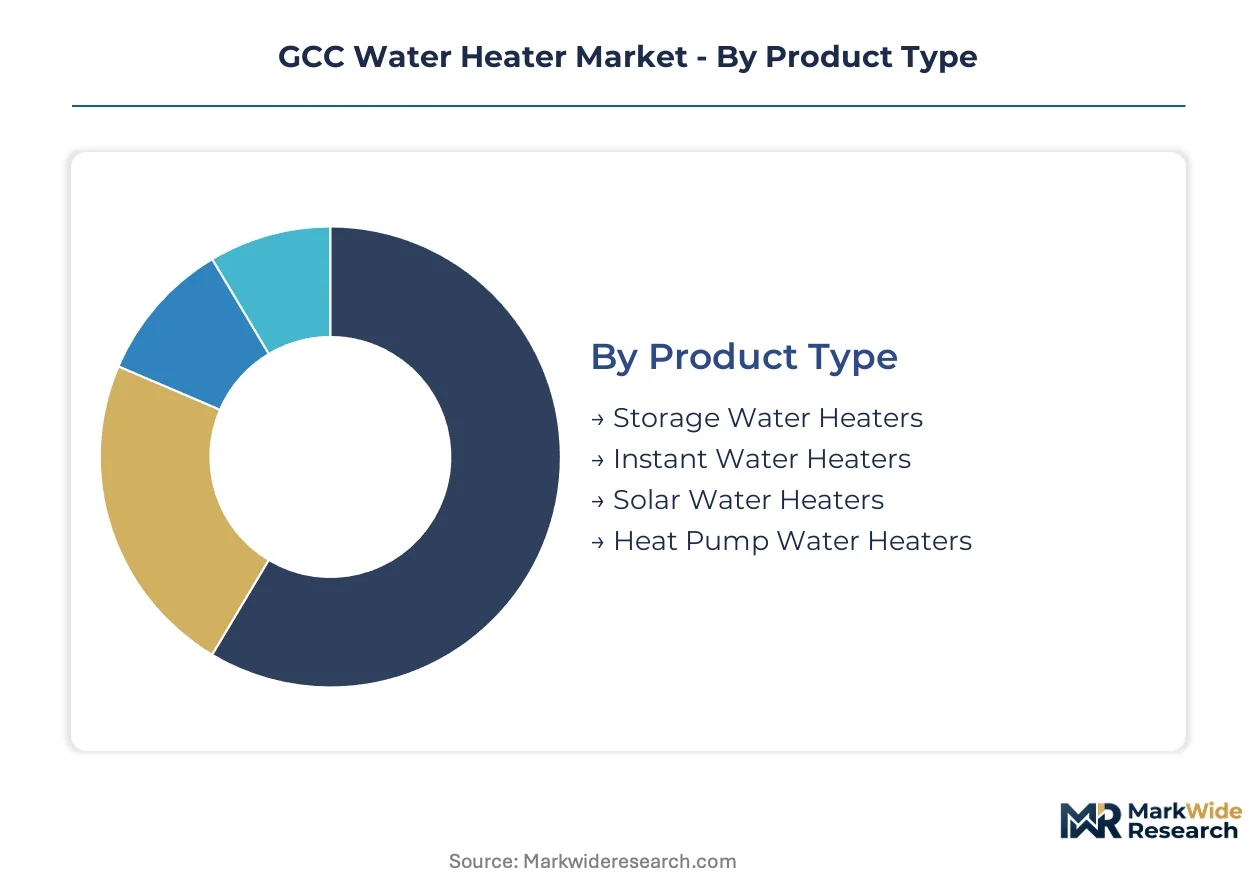
Water heater procurement across the Gulf Cooperation Council diverges sharply by application context, with hospitality megaprojects, residential replacement cycles, and commercial retrofits each demanding distinct performance specifications and compliance pathways. Segmentation clarity enables suppliers to align certification investments with addressable demand pools.
Product Type:
Domestic manufacturing concentrates on storage and instant systems for regional replacement markets, while solar and heat pump technologies flow primarily through import channels serving Saudi Arabia's western province developments.
- Storage Water Heaters:Insulated tank systems ranging from 30 to 200 liters maintain heated water reserves for residential and light commercial use. Demand concentrates in Kuwait and Bahrain's aging residential stock, where electrical infrastructure constraints favor familiar replacement technologies over heat pump conversions.
- Instant Water Heaters:Tankless designs activate heating elements or burners on flow detection, eliminating standby losses. These units capture preference in Qatar and UAE high-rise developments where space constraints and intermittent usage patterns dominate.
- Solar Water Heaters:Evacuated tube or flat-plate collector systems with integrated storage dominate Saudi hospitality procurement.
- Heat Pump Water Heaters:Vapor-compression systems extracting ambient thermal energy are expanding most quickly in UAE commercial retrofits.
Storage water heaters hold the largest share; momentum sits with heat pump water heaters.
Technology:
Cost tier stratification separates premium hybrid systems from commodity electric resistance units, with gas-fired technologies occupying a narrowing middle band as efficiency mandates tighten.
- Electric:Resistance-element systems dominate entry-level residential segments across all six GCC states. These units face margin compression from SASO efficiency label requirements demanding higher insulation values and smart control integration.
- Gas:Natural gas and LPG combustion systems serve high-volume commercial kitchens and central plant applications. Coastal installations in Dubai and Doha encounter accelerated corrosion from high-salinity water, elevating stainless steel specification rates.
- Solar:Thermal collector systems with electric or gas backup satisfy renewable compliance mandates in Saudi Arabia's NEOM and Red Sea corridors.
- Hybrid:Combined solar-electric or heat pump-electric architectures command premium positioning in healthcare and luxury hospitality verticals.
Electric systems retain volume leadership; hybrid configurations are climbing the fastest.
End User:
Application-driven specification divergence separates residential replacement simplicity from hospitality sector integrated thermal system complexity.
- Residential:Single-family and multi-family dwellings drive replacement cycles across Kuwait, Bahrain, and Oman's established housing stock. Procurement prioritizes SABER platform eligibility and price accessibility over advanced efficiency features.
- Commercial:Office buildings and retail facilities in Dubai and Abu Dhabi are accelerating heat pump adoption under ESMA efficiency tier deadlines. Retrofit timelines compress as compliance windows narrow.
- Industrial:Process hot water applications in petrochemical and food processing facilities require customized high-capacity systems.
- Hospitality:Hotels and resorts across Saudi Arabia's western province specify renewable-ready infrastructure to satisfy project financing conditions.
Residential applications dominate unit volume; hospitality commands the steepest value per installation.
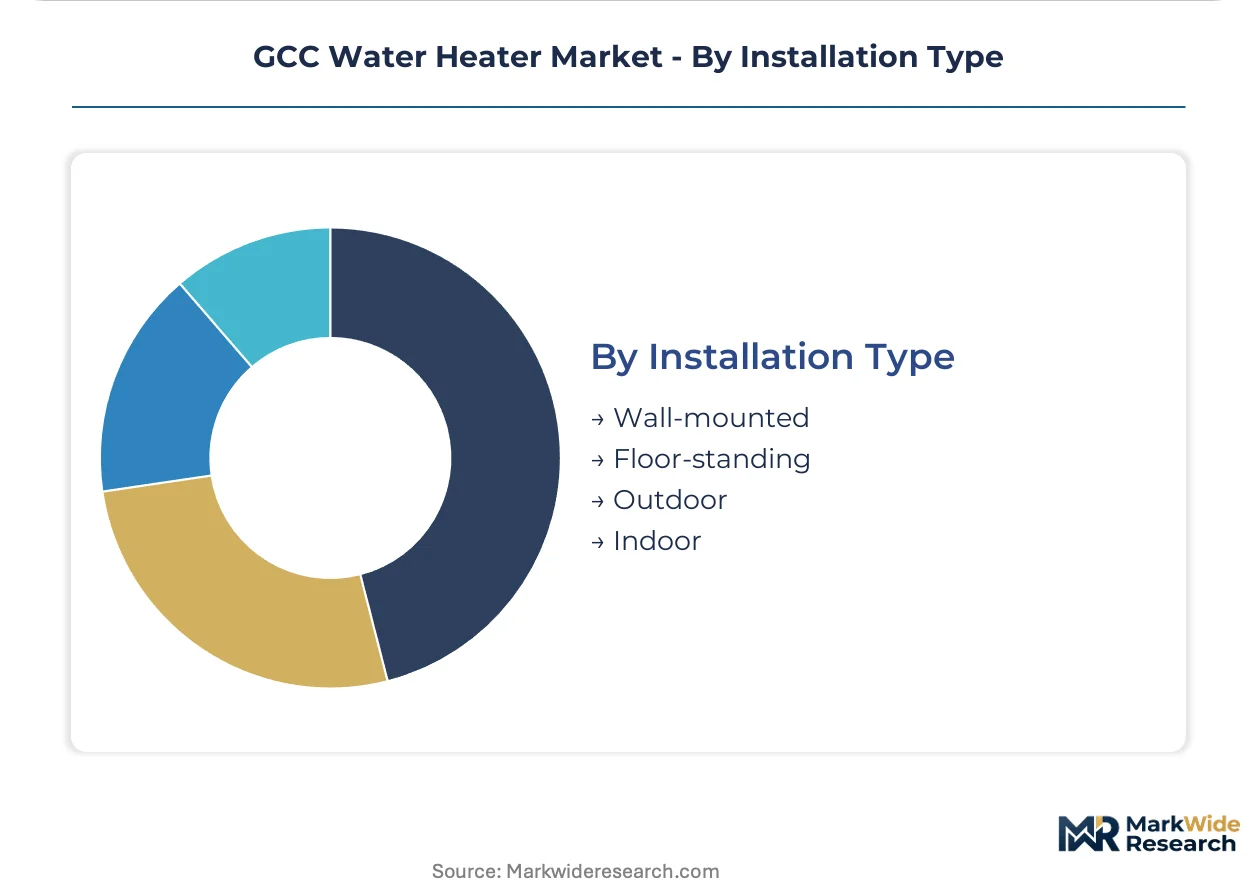
Installation Type:
Customer type and building vintage dictate mounting configurations, with new construction favoring integrated designs and retrofits accepting compromise solutions.
- Wall-mounted:Compact electric and gas instantaneous units attach to vertical surfaces in apartments and service areas. These dominate UAE and Qatar high-rise residential stock where floor space carries premium valuation.
- Floor-standing:Large-capacity storage tanks and heat pump systems require ground-level placement with ventilation clearances. Saudi commercial developments and industrial facilities specify these for centralized hot water distribution.
- Outdoor:Weather-resistant enclosures accommodate solar collectors and heat pump compressors in climates with mild winter conditions.
- Indoor:Climate-controlled equipment rooms protect sensitive components from sand, salt, and extreme summer temperatures.
Floor-standing systems anchor commercial and industrial procurement; wall-mounted units are gaining share fastest in residential vertical construction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospitality developers and commercial facility managers concentrate procurement authority across Saudi Arabia and the UAE, with efficiency mandates and megaproject specifications driving vendor selection criteria throughout the Gulf.
Saudi Arabia
NEOM and Red Sea megaprojects specify renewable-ready water heating infrastructure, creating dedicated demand corridors for solar thermal and heat pump systems. SASO energy performance labels and SABER platform conformity requirements disqualify manufacturers lacking documented thermal testing. Riyadh anchors certification laboratory capacity while Jeddah serves as the primary logistics hub for western province developments.
United Arab Emirates
Commercial retrofit cycles in Dubai and Abu Dhabi hospitality assets accelerate under ESMA efficiency tier deadlines. Heat pump water heaters capture the fastest expansion as building operators target operational cost reduction. Dubai concentrates procurement decision-making for multinational hospitality chains, with Abu Dhabi driving federal government building efficiency mandates.
Qatar
High-rise residential developments in Doha favor wall-mounted instantaneous systems where space constraints dominate specification. Coastal installations encounter accelerated tank degradation from high-salinity water, elevating stainless steel requirements. The Lusail development corridor represents the primary concentration of new construction demand.
Kuwait
Aging residential stock drives replacement cycles for storage water heaters, with electrical infrastructure constraints limiting heat pump adoption. Procurement prioritizes SABER platform eligibility and price accessibility over advanced efficiency features. Kuwait City and surrounding governates concentrate the bulk of residential replacement volume.
Oman
Commercial building stock shows underpenetrated heat pump adoption relative to Saudi Arabia and the UAE, offering positioning opportunity for efficiency-compliant suppliers. The Muscat metropolitan area concentrates hospitality and healthcare development activity. GSO harmonization efforts reduce compliance fragmentation for multi-country suppliers entering the market.
GCC Water Heater Market Key Industry Players
Player mix skews toward European and North American multinationals with established testing infrastructure, compressing addressable share for regional fabricators lacking SASO certification documentation. Market structure exhibits tiered concentration: premium-positioned heat pump specialists, mid-tier gas-fired tank manufacturers, and commodity electric resistance suppliers. Strategic moves center on local assembly investments and smart control integration partnerships.
Within the multinational tier, Ariston Thermo SPA leverages European testing infrastructure to sustain compliance across Gulf markets. A. O. Smith Corporation anchors positioning through localized assembly presence. Rheem Manufacturing Company occupies a specialization niche suited to high-salinity water conditions. These three exemplify how certification capacity and geographic proximity to Riyadh and Dubai testing hubs determine competitive viability.
| Leading Market Players |
|---|
| Ariston Thermo SPA |
| A. O. Smith Corporation |
| Rheem Manufacturing Company |
| Orbital Horizon |
| Saudi Ceramics Est. |
| Al Huraiz Est |
| Whirlpool |
| General Electric Co. |
| Rinnai Corporation |
| Others |
Cost & Logistics Intelligence
Capacity utilization at Riyadh and Dubai testing laboratories shapes vendor viability thresholds, compressing margin pools for manufacturers outside certification hub proximity while elevating price floors for SASO-compliant product tiers. Scale economies in thermal performance documentation concentrate procurement power among multinationals with European testing infrastructure, fragmenting competitive access for regional fabricators.
Pricing Analysis
Cost-plus contracts with copper and stainless steel indexation dominate procurement agreements for tank and heat exchanger components, exposing manufacturers to commodity volatility pass-through. Three-tier pricing structure across premium heat pump, standard gas-fired, and economy electric resistance levels separates certification-grade products from commodity alternatives. Price differentiation hinges on SABER platform eligibility and thermal efficiency tier, with hospitality developers in Saudi Arabia's western province showing lowest sensitivity while residential replacement buyers in Kuwait and Bahrain prioritize accessible price points. Cost compression in economy electric segments is intensifying as SASO insulation mandates force redesign cycles without corresponding value capture.
Supply Chain Analysis
China and South Korea anchor tank and compressor manufacturing for GCC-bound water heating systems, with European specialists concentrating heat pump vapor-compression technology. Raw material dependencies center on copper coil stock, stainless steel sheet for coastal corrosion resistance, and electronic control modules for smart integration features. Single-source vulnerability concentrates in Riyadh and Dubai certification laboratories, where GSO testing validity bottlenecks market entry timelines. Distribution runs through Jeddah logistics corridors for Saudi western province megaprojects and Dubai trade hubs for UAE commercial retrofit channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Heat pump penetration across GCC commercial building stock sits at early-cycle expansion, with ESMA efficiency deadlines and Saudi renewable integration targets accelerating specification shifts that lag European adoption curves by approximately half a decade.
For Market Incumbents: Fortify SABER platform eligibility through accelerated thermal performance retesting, eliminating pre-2023 certified models from procurement consideration. Deepen backward integration into stainless steel tank fabrication to offset copper price volatility exposure in high-salinity coastal installations. Prioritize localized assembly presence in Saudi Arabia to defend against emerging regional fabricators gaining SASO documentation capabilities. For New Entrants and Emerging Players: Post-installation commissioning and predictive maintenance services represent under-served layers where European specialists currently concentrate expertise, creating white-space for locally anchored service providers. Target Oman's underpenetrated commercial heat pump segment before efficiency mandates replicate Saudi and UAE compliance trajectories. Pursue engineering-procurement-construction channel partnerships in Qatar's Lusail corridor, where high-rise wall-mounted instantaneous demand favors specialized installation capabilities over product manufacturing scale. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among heat pump specialists with long-term service agreements in hospitality and healthcare verticals, where predictive maintenance contracts extend equipment lifecycle value. Five-to-ten year viability favors acquisition targets with documented GSO certification and established relationships with Saudi megaproject developers. Monitor ESMA tier advancement timelines as inflection indicator for UAE commercial retrofit acceleration rates.| Strategic Initiative | Industry Significance |
|---|---|
| SABER Certification Investment | Documented thermal performance testing unlocks Saudi procurement channels excluding uncertified competitors. |
| Localized Assembly Expansion | Saudi-based production reduces logistics cost to western province megaproject corridors. |
| Smart Control Integration Partnership | IoT-enabled demand response features differentiate premium positioning in hospitality verticals. |
| Stainless Steel Specification Upgrade | Corrosion-resistant materials address high-salinity degradation in Qatar and UAE coastal installations. |
| Heat Pump Service Capability Buildout | Commissioning expertise scarcity limits local capacity expansion for vapor-compression system deployment. |
Research Approach
A spread of perspectives from water heater procurement managers at Saudi hospitality developers, UAE facilities directors, GSO certification laboratory engineers, and European OEM regional heads converged on the working assumptions shaping demand trajectories. Primary field engagement with engineering-procurement-construction contractors and thermal system installers supplemented secondary validation through SASO efficiency label documentation, ESMA regulatory filings, customs trade records for tank and compressor imports, and hospitality project specification databases. Bottom-up unit shipment estimates triangulated against top-down construction pipeline valuations across the analysis window.
Product type, technology architecture, end-user application, and installation configuration anchored the segmentation dimensions modeled, with additional granularity on SABER certification tier and renewable-readiness specification. CAGRs derived from polynomial trend fitting to historical shipment data, adjusted for megaproject procurement acceleration and efficiency mandate compliance deadlines. Industry-specific forecast inputs incorporated copper price futures curves and coastal corrosion warranty claim rates.
Underlying assumptions cover ESMA tier enforcement continuity and Saudi megaproject completion schedules, with deviation risk concentrated in commodity price volatility and certification laboratory capacity constraints. Recalibration cycles align with material shifts in GSO harmonization protocols and renewable energy integration targets.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
US Commercial Water Heater Market
HVAC Equipment
North America HVAC Filter Change Service Market
HVAC Equipment
Helical Screw Blowers Market
HVAC Equipment
Fabric Ducting Market
HVAC Equipment
HVAC Pumps Market
HVAC Equipment
North America Commercial Heating, Ventilation, and Air Conditioning (HVAC) Equipment Market
HVAC Equipment
US Compressed Air Treatment Equipment Market
HVAC Equipment
Air Conditioning Equipment Market
HVAC Equipment
Residential Furnaces Market
HVAC Equipment
Global Air Curtain Market
HVAC Equipment
Underfloor Heating Market
HVAC Equipment
US Residential HVAC Systems Market
HVAC Equipment
South America Compressor Market
HVAC Equipment
Chilled Beams Market
HVAC Equipment
Blowers Market
HVAC Equipment
Global Air Handling Units (AHU) Market