
 Global Commercial Heat Pump Water Heater Market | 2026-2036
Global Commercial Heat Pump Water Heater Market Size, Share, and Industry Trends Forecast 2026-2036
Global Commercial Heat Pump Water Heater Market Analysis
Certified refrigeration technician availability is bifurcating the competitive landscape between established OEMs and emerging challengers. Daikin Industries leverages its captive compressor manufacturing to control component costs across air-source product lines. Rheem Manufacturing anchors North American distribution through contractor-exclusive channel programs. A. O. Smith competes on tank fabrication scale, integrating stainless-steel vessel production with heat pump module assembly.
A commercial heat pump water heater extracts thermal energy from ambient air, water, or ground sources via vapor-compression refrigeration cycles, typically achieving coefficient of performance ratings between 3.0 and 5.0 under standard test conditions. These systems serve the primary commercial purpose of generating sanitary hot water at temperatures up to 60 degrees Celsius while displacing direct fossil fuel combustion in buildings. Air-source products dominate installed volume due to lower infrastructure requirements, though geothermal configurations command premium positioning where ground-loop installation proves feasible. High-efficiency systems with inverter-driven compressors represent the fastest-expanding technology segment as operators seek part-load optimization. Hotels and hospitals together constitute the most concentrated application margin pool, given their continuous hot-water demand profiles and energy-cost sensitivity.
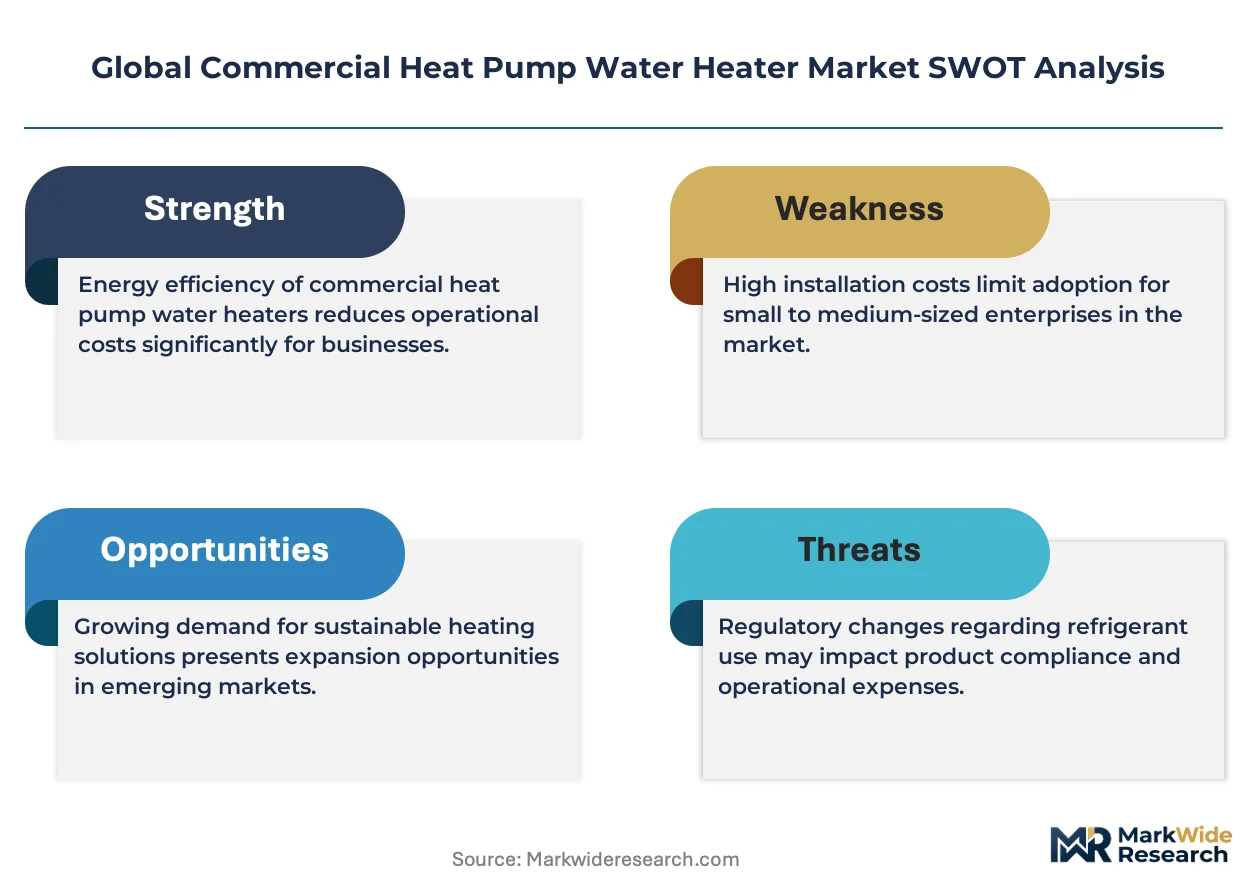
The EU F-Gas Regulation and EPA SNAP program are tightening refrigerant eligibility, compelling manufacturers to redesign systems around R-32 or R-290 alternatives with lower global-warming potential. Japan's METI Top Runner program sets escalating efficiency benchmarks that shape product development roadmaps for export-oriented suppliers. China's GB standards mandate performance testing protocols that determine market access for imported equipment. Stakeholders must monitor refrigerant transition timelines and certification reciprocity agreements to anticipate product obsolescence risks and geographic expansion constraints.
Market Dynamics
Refrigerant chemistry transitions under the EU F-Gas Regulation are forcing simultaneous product redesign and supply chain reconfiguration across the commercial heat pump water heater industry. Equipment manufacturers must validate new thermal cycles while maintaining performance parity with legacy systems.
Growth Catalysts
- EU F-Gas Regulation Phase-Down:Mandated reduction in high-GWP refrigerant availability accelerates R-32 and R-290 system development, creating replacement demand across Europe's installed base of commercial boilers.
- Hotel Sector Energy Cost Pressure:Southeast Asian hospitality operators face electricity tariff volatility that makes heat pump coefficient-of-performance economics decisive in capital planning decisions.
- Inverter-Driven Compressor Maturation:Variable-speed refrigeration technology enables part-load efficiency optimization that matches intermittent hot water demand profiles in healthcare facilities.
Market Restraints
- Copper and Aluminum Input Volatility:Heat exchanger and coil manufacturing faces commodity price swings that compress margin predictability for system assemblers.
- Certified Technician Concentration:Refrigeration installation and commissioning expertise clusters in Germany, Japan, and the United States, limiting deployment velocity in emerging demand centers.
- Ground-Loop Capital Intensity:Geothermal configurations require drilling and excavation expenditure that extends payback periods beyond standard commercial investment horizons.
Strategic Opportunities
- India Commercial Building Retrofit:Bureau of Energy Efficiency mandates for large commercial facilities create compliance-driven demand for fossil-fuel displacement in domestic hot water systems.
- Healthcare Cogeneration Integration:Combined heat and power plants in hospital campuses present thermal source pairing opportunities for hybrid water heating architectures.
- Contractor-Exclusive Channel Programs:North American distribution restructuring around certified installer networks locks in specification influence and recurring maintenance revenue.
Industry Challenges
- Refrigerant Handling Certification Scarcity:R-290 hydrocarbon systems require specialized safety training that outpaces vocational education program expansion in key installation markets.
- Legacy Boiler Integration Complexity:Facility managers confront control system incompatibility when retrofitting heat pump modules into existing building management architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Commercial Heat Pump Water Heater Market |
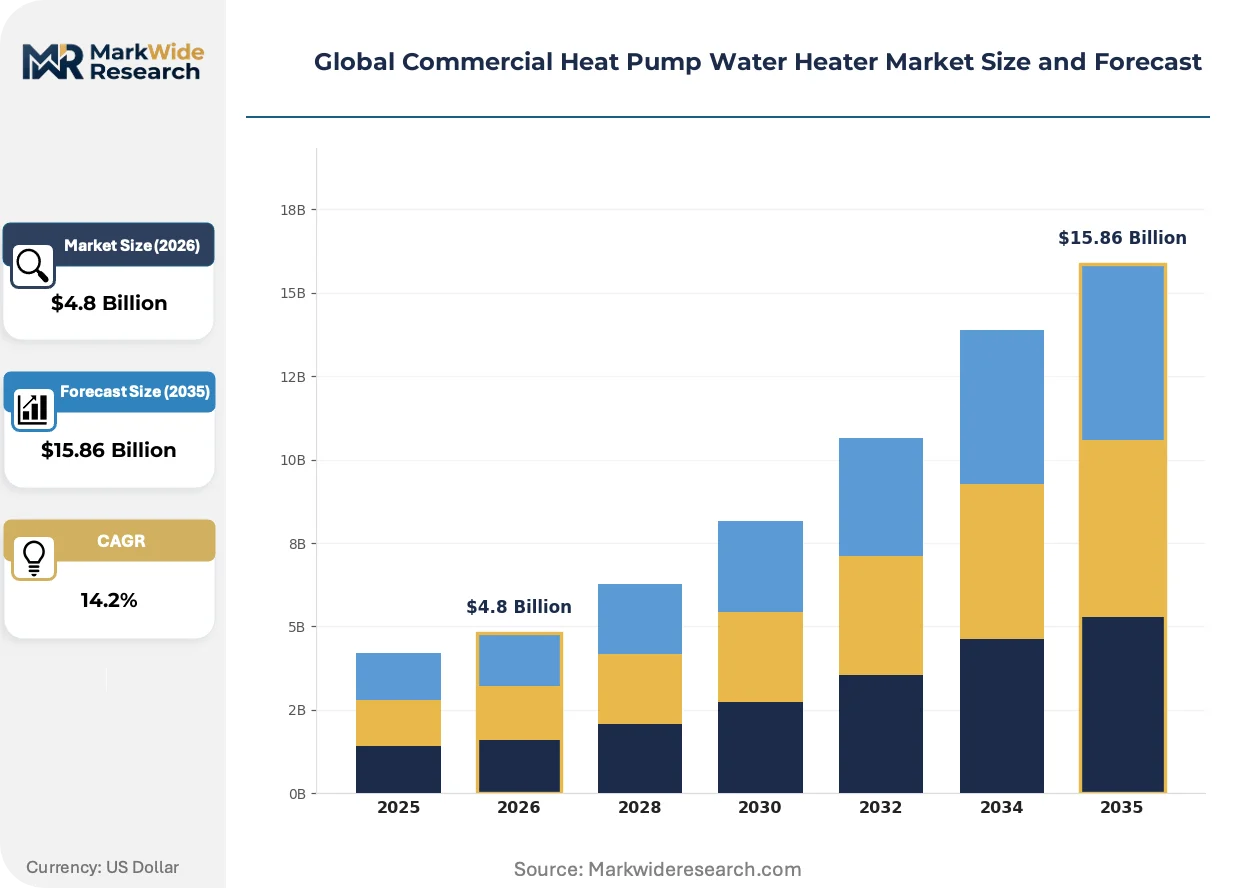
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.86 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air Source, Water Source, Geothermal, Hybrid Application: Hotels, Hospitals, Schools, Industrial Facilities End User: Commercial, Institutional, Government, Industrial Technology: Inverter Technology, Split Systems, Compact Systems, High-Efficiency Systems |
| Companies Covered | Daikin Industries Ltd., Rheem Manufacturing Company, A. O. Smith Corporation, Panasonic Corporation, LG Electronics, Ariston Group, STIEBEL ELTRON GmbH & Co., Mitsubishi Electric, NIBE Industrier AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Commercial Heat Pump Water Heater Market Emerging Trajectories
Product development trajectories center on refrigerant transition timelines and control system intelligence. Manufacturers are racing to certify lower-GWP thermal cycles while embedding predictive maintenance capabilities that reduce operational downtime.
Inverter-driven compressor technology is fragmenting the efficiency-performance tradeoff that previously locked air-source systems into fixed-speed operation. Large hotel chains in Thailand and Vietnam are specifying variable-speed units for new construction projects. This capability divergence is fragmenting supplier tiers into premium inverter-capable and standard fixed-speed portfolios.
The EU F-Gas Regulation's 2024-2030 phase-down schedule compels refrigerant inventory management and system architecture redesign. Equipment manufacturers face validation bottlenecks as notified bodies process safety certifications for flammable alternative working fluids. German commercial building retrofit contractors report extended lead times for R-32-based systems as certification queues lengthen.
Facility managers are consolidating domestic hot water procurement under energy-as-a-service contracts that transfer operational risk to equipment suppliers. Third-party ownership models displace traditional capital purchase arrangements in United States hospital and university campuses. This financing structure rotation is most visible in California and New York where utility incentive programs reward performance-guaranteed installations.
Global Commercial Heat Pump Water Heater Market Segmentation
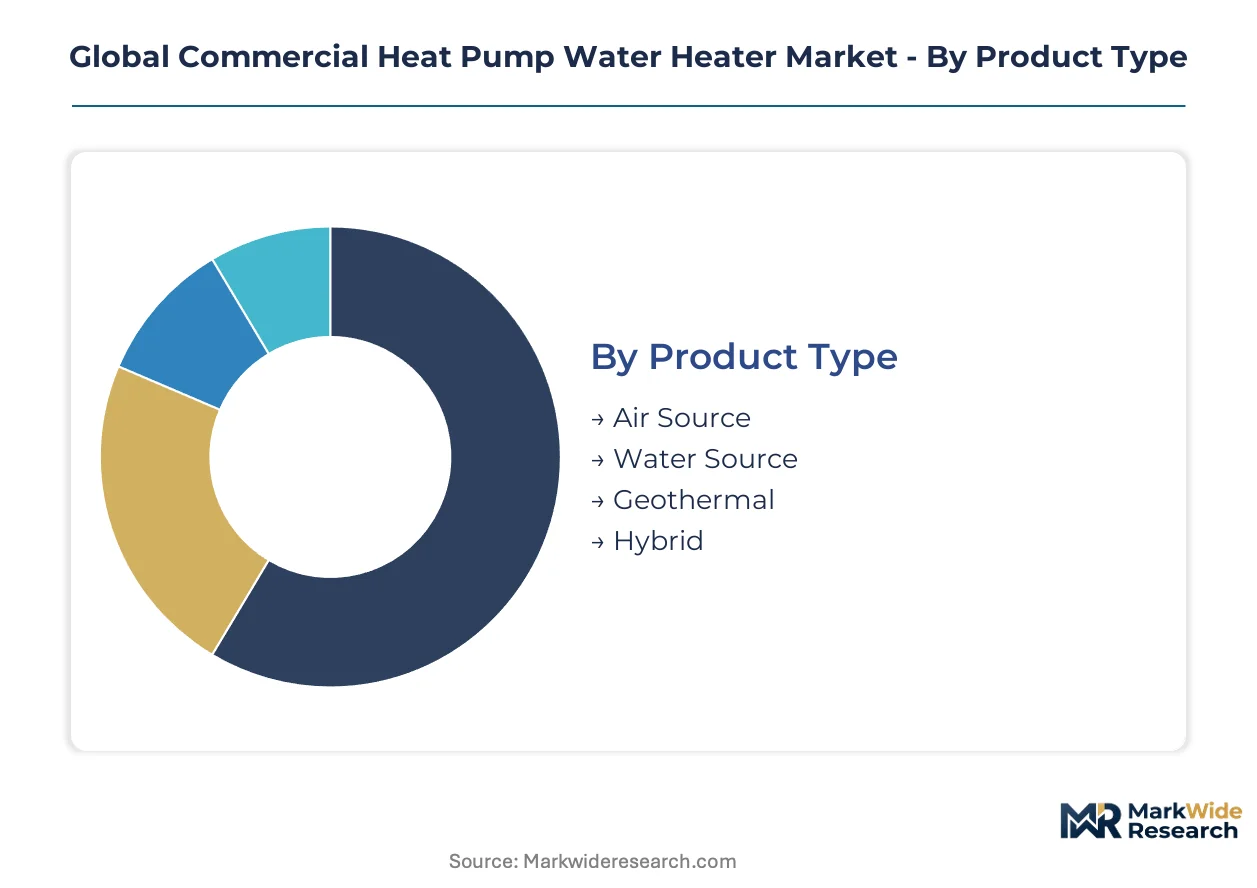
Commercial heat pump water heater procurement patterns diverge sharply across product architectures and end-use intensity. Facility managers select system configurations based on thermal source availability, capital recovery timelines, and regulatory compliance obligations in their operating jurisdictions.
Product Type:
Air-source systems dominate export volumes to Southeast Asian hospitality markets, while geothermal configurations concentrate in German and Japanese domestic retrofits where drilling infrastructure exists.
- Air Source:These systems extract ambient thermal energy through finned-coil evaporators, achieving coefficient-of-performance ratings between 3.0 and 4.5 under standard test conditions. Thai and Vietnamese hotel operators specify these units for new construction projects where electricity tariff volatility makes operational efficiency decisive in capital planning.
- Geothermal:Ground-loop configurations utilize buried heat exchangers to access stable subsoil temperatures, delivering superior year-round efficiency regardless of ambient air conditions. German facility managers prioritize these systems in commercial building retrofits where the EU F-Gas Regulation accelerates fossil-fuel displacement mandates.
- Water Source:Systems paired with lakes, rivers, or wastewater streams offer thermal stability without ground-loop excavation. Coastal hotels in Japan leverage seawater source configurations where METI efficiency benchmarks shape procurement specifications.
- Hybrid:Dual-source architectures combine heat pump operation with auxiliary electric resistance or gas-fired backup. Industrial facilities in the United States specify these units where process hot water demand exceeds single-source thermal capacity during peak loads.
Air-source units command the established base. The steepest expansion runs through geothermal configurations in markets with mature drilling contractor networks.
Application:
Customer type determines specification complexity, with continuous-operation facilities demanding redundant capacity and predictive maintenance integration.
- Hotels:Southeast Asian hospitality chains drive specification influence through centralized procurement programs that standardize inverter-driven compressor technology across property portfolios. Electricity cost pressure in Thailand and Vietnam makes coefficient-of-performance economics the primary selection criterion.
- Hospitals:Healthcare campuses require sanitary hot water at temperatures up to 60 degrees Celsius with zero redundancy failure. United States hospital operators are consolidating procurement under energy-as-a-service contracts that transfer operational risk to equipment suppliers.
- Schools:Educational facilities present intermittent demand profiles that favor part-load optimization through variable-speed compressor technology. Indian Bureau of Energy Efficiency mandates for large commercial facilities create compliance-driven retrofit demand.
- Industrial Facilities:Process heating applications require higher temperature lift than standard sanitary hot water systems. Combined heat and power plant integration in manufacturing campuses presents thermal source pairing opportunities for hybrid architectures.
Hotels anchor current installed volume. Healthcare applications are climbing the fastest as energy-as-a-service financing penetrates United States hospital procurement.
End User:
Procurement authority concentrates differently across ownership structures, with institutional buyers prioritizing lifecycle cost over first cost.
- Commercial:Private-sector facility managers face shareholder return pressure that accelerates payback period requirements. California and New York utility incentive programs reward performance-guaranteed installations in commercial building retrofits.
- Institutional:University and hospital campuses with dedicated engineering staff specify advanced control integration and predictive maintenance capabilities. Third-party ownership models displace traditional capital purchase arrangements where operational risk transfer proves attractive.
- Government:Public procurement follows mandated efficiency standards with extended evaluation horizons. China's GB standards determine market access for imported equipment in government facility tenders.
- Industrial:Manufacturing operators prioritize thermal output reliability over efficiency optimization where process continuity carries revenue risk. Ground-loop capital intensity limits geothermal penetration in industrial greenfield projects.
Commercial buyers dominate transaction volume. Institutional procurement is expanding most quickly through energy-as-a-service contract adoption.
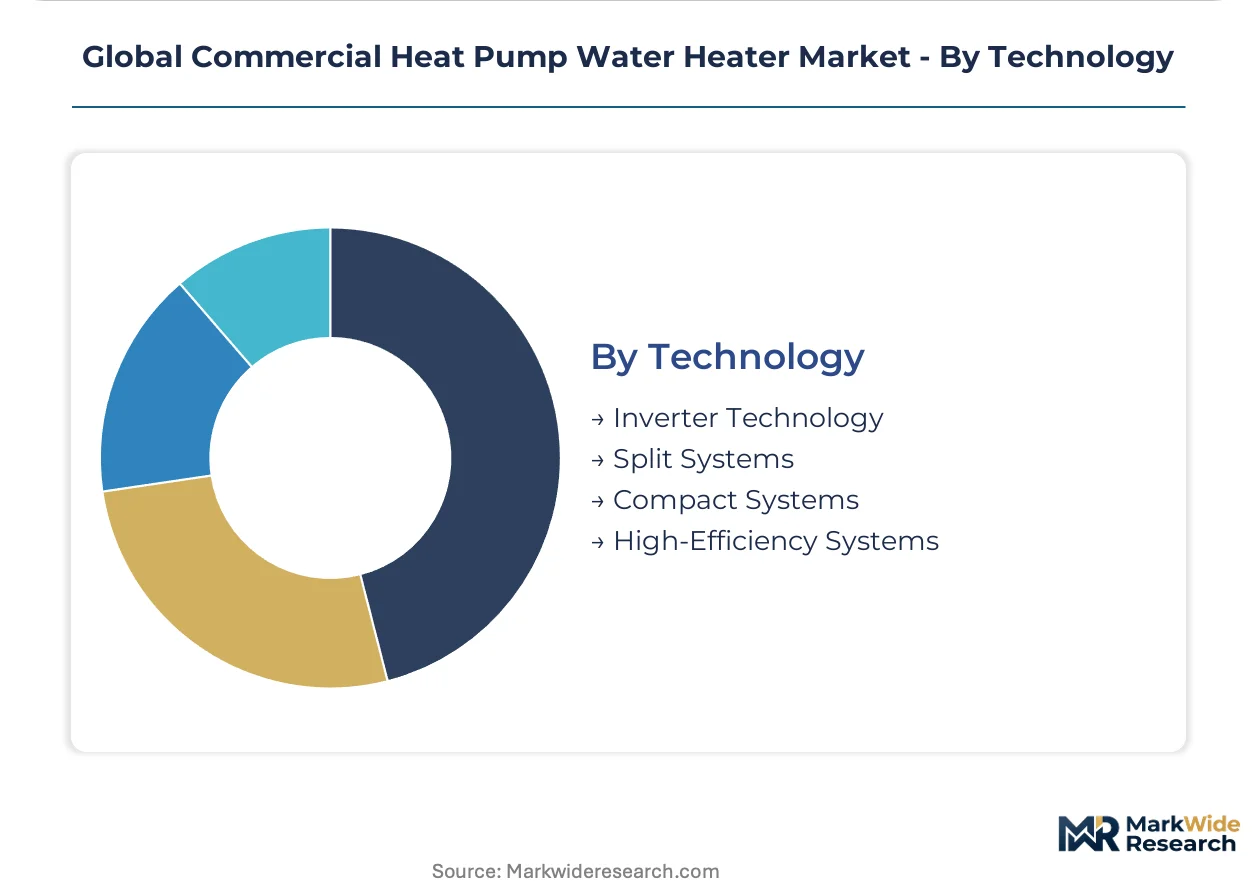
Technology:
Manufacturing scale and certification reciprocity determine which technology tiers achieve geographic penetration.
- Inverter Technology:Variable-speed compressor drives enable part-load efficiency optimization that matches intermittent hot water demand profiles. Large hotel chains in Thailand and Vietnam specify these units for new construction, fragmenting supplier tiers into inverter-capable and fixed-speed portfolios.
- High-Efficiency Systems:Advanced refrigerant cycles and optimized heat exchanger geometry push coefficient-of-performance ratings above 4.5. German commercial building retrofit contractors report extended lead times as EU F-Gas Regulation certification queues lengthen for R-32-based configurations.
- Split Systems:Separated evaporator and condenser modules enable flexible installation in constrained mechanical rooms. Japanese METI Top Runner program benchmarks shape product development roadmaps for export-oriented suppliers of split architectures.
- Compact Systems:Integrated single-package designs reduce installation labor and footprint requirements. Certified technician scarcity in emerging demand centers limits deployment velocity for complex multi-component configurations.
High-efficiency systems command specification influence in regulated European markets. Inverter technology is gaining share fastest as Southeast Asian hospitality procurement standardizes variable-speed requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial heat pump water heater deployment patterns diverge sharply by geography, with European retrofit markets prioritizing geothermal ground-loop configurations while Southeast Asian hospitality clusters favor air-source units for new construction.
Germany
Facility managers in commercial building retrofits prioritize fossil-fuel displacement for domestic hot water supply. The EU F-Gas Regulation accelerates refrigerant transitions toward R-32 and R-290 alternatives. Berlin-Brandenburg contractors report extended lead times as certification queues lengthen for lower-GWP system configurations.
United States
Hospital and university campuses consolidate procurement under energy-as-a-service contracts that transfer operational risk to equipment suppliers. EPA SNAP program restrictions on high-GWP refrigerants reshape product development roadmaps. California and New York utility incentive programs reward performance-guaranteed installations in commercial building retrofits.
Thailand
Hospitality chains drive specification influence through centralized procurement programs that standardize inverter-driven compressor technology. Electricity tariff volatility makes coefficient-of-performance economics decisive in capital planning decisions. Bangkok hotel operators specify variable-speed units for new construction projects.
Japan
Coastal hotels leverage seawater source configurations where METI Top Runner efficiency benchmarks shape procurement specifications. The national efficiency program sets escalating performance standards that determine product development priorities. Kansai region facility managers prioritize split-system architectures for constrained mechanical room installations.
India
Bureau of Energy Efficiency mandates for large commercial facilities create compliance-driven demand for fossil-fuel displacement in domestic hot water systems. Central Electricity Authority guidelines influence thermal system selection in institutional buildings. Maharashtra and Karnataka facility managers evaluate air-source units for retrofit compatibility with existing building management architectures.
Global Commercial Heat Pump Water Heater Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with captive manufacturing capabilities separating premium positioning from assembly-dependent competitors. The competitive map organizes around three strategic archetypes: diversified HVAC conglomerates with compressor manufacturing depth, tank fabrication specialists integrating vessel production with heat pump modules, and regional challengers competing on installation service density. Dominant competitive moves include backward integration into compressor supply and contractor-exclusive distribution channel construction.
Within the integrated HVAC tier, Daikin Industries and Mitsubishi Electric exemplify archetypes built on captive refrigeration component manufacturing. Rheem Manufacturing occupies a position anchored in North American distribution restructuring around certified installer networks. A. O. Smith Corporation represents the tank fabrication specialist archetype, with stainless-steel vessel production integrated alongside heat pump module assembly.
| Leading Market Players |
|---|
| Daikin Industries Ltd. |
| Rheem Manufacturing Company |
| A. O. Smith Corporation |
| Panasonic Corporation |
| LG Electronics |
| Ariston Group |
| STIEBEL ELTRON GmbH & Co. |
| Mitsubishi Electric |
| NIBE Industrier AB |
| Others |
Supply Flow & Price Mechanics
Captive compressor manufacturing scale at Daikin Industries and Mitsubishi Electric anchors cost floors across air-source product lines, concentrating pricing power among integrated OEMs while assembly-dependent challengers absorb margin compression from copper and aluminum volatility.
Pricing Analysis
Long-term energy-as-a-service contracts dominate hospital and university procurement in California and New York, transferring operational risk to suppliers while locking in recurring revenue streams. Price differentiation rests on inverter-driven compressor capability and EU F-Gas Regulation certification tier, with premium variable-speed units commanding specification influence in Thai hotel chains. Cost compression in fixed-speed portfolios intensifies as Southeast Asian electricity tariff volatility pushes buyers toward efficiency-optimized alternatives. Budget-constrained school districts in India exhibit highest price sensitivity, while German commercial retrofit contractors prioritize lifecycle cost over first cost.
Supply Chain Analysis
Strait of Malacca transit underwrites refrigerant chemical flows to Southeast Asian assembly plants, exposing just-in-time inventory models to maritime disruption. Manufacturing concentrates in China, Japan, and Germany, with captive coil fabrication and compressor production tethering output to regional metal processing capacity. Supply chains draw from copper cathode, aluminum coil, and rare-earth magnet inputs, with commodity price swings compressing assembler margins unpredictably. Single-source vulnerability clusters in Japanese inverter drive electronics, while distribution runs through contractor-exclusive networks that Rheem Manufacturing anchors across North American markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Energy-as-a-service contract penetration in United States healthcare and education sectors outpaces hardware shipment growth, elevating predictive maintenance attach rates and recurring revenue visibility above transactional equipment sales.
For Market Incumbents: Consolidate specification influence through captive compressor manufacturing expansion and R-290 hydrocarbon safety certification investment. Daikin Industries' backward integration into refrigeration components demonstrates how upstream control neutralizes emerging challenger price aggression in Southeast Asian hospitality procurement. Lock in distribution exclusivity with certified installer networks before refrigerant transition timelines fragment channel loyalty. For New Entrants and Emerging Players: Lead with water-source system architectures for Japanese coastal hotel retrofits where METI efficiency benchmarks create specification entry points against air-source incumbents. India's Bureau of Energy Efficiency compliance mandates present the most penetrable retrofit demand pool, with Maharashtra facility managers actively evaluating hybrid configurations. Pursue energy-as-a-service financing partnerships to bypass capital-budget gatekeepers in United States institutional procurement. For Investors and Strategic Acquirers: Tank fabrication specialists with stainless-steel vessel production integrated alongside heat pump module assembly present the most defensible acquisition profile. Long-term viability centers on refrigerant transition readiness and service contract recurring revenue depth. Watch EU F-Gas Regulation certification queue lengths as an inflection indicator for manufacturing margin recovery.| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Transition Certification | EU F-Gas Regulation compliance unlocks European retrofit market access before legacy inventory obsolescence. |
| Inverter Technology Licensing | Variable-speed compressor partnerships enable Southeast Asian challengers to meet Thai hotel chain specifications. |
| Energy-as-a-Service Platform Launch | Third-party ownership models transfer operational risk while capturing California utility incentive program rewards. |
| Contractor-Exclusive Channel Construction | Certified installer networks lock in specification influence and recurring maintenance revenue in North American distribution. |
| Geothermal Drilling Partnership | Ground-loop capital intensity limits German retrofit penetration without established excavation contractor alliances. |
Methodological Framework
Operator-level perspectives from facility managers, refrigeration contractors, OEM procurement leads, and energy service company executives anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation through EPA SNAP program filings, EU F-Gas Regulation implementation notices, Bureau of Energy Efficiency mandate documents, and METI Top Runner efficiency benchmark disclosures. Customs records for compressor and heat exchanger trade flows supplemented bottom-up installation tracking with top-down manufacturing output triangulation.
Sensitivity analysis across refrigerant transition timelines, electricity tariff volatility scenarios, and certified technician availability constraints shaped the analytical framework. Segmentation modeling incorporated product architecture, thermal source type, end-use intensity, and regional regulatory cluster dimensions throughout the projection horizon. CAGRs derived from unit shipment trajectories and average selling price evolution, with inverter adoption curves and energy-as-a-service contract penetration serving as industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside EU F-Gas Regulation phase-down adherence or sustained Southeast Asian electricity cost pressure would require recalibration. Forecasts reflect documented assumptions regarding refrigerant certification reciprocity and vocational training program expansion velocity. Practitioners should keep alternative scenarios live as hydrocarbon safety standard adoption and utility incentive program funding levels evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
HVAC Air Quality Monitoring Market
HVAC Equipment
Residential Heat Pump Market
HVAC Equipment
Warming Cabinet Market
HVAC Equipment
Variable Refrigerant Flow (VRF) System Market
HVAC Equipment
Scrubber Dryer Market
HVAC Equipment
North America Bus HVAC Market
HVAC Equipment
US Residential HVAC Systems Market
HVAC Equipment
North America Commercial Heating, Ventilation, and Air Conditioning (HVAC) Equipment Market
HVAC Equipment
United States Residential Heating Equipment Market
HVAC Equipment
France HVAC Market
HVAC Equipment
North America Industrial Air Chiller Market
HVAC Equipment
Industrial Blowers Market
HVAC Equipment
Global Air-To-Air Heat Pumps Market
HVAC Equipment
Underfloor Heating Market
HVAC Equipment
Underfloor Air Distribution Systems Market
HVAC Equipment
Asia-Pacific Heating Equipment Market