
 India Commercial Construction Market | 2026-2036
India Commercial Construction Market Size, Share, and Industry Trends Forecast 2026-2036
India Commercial Construction Market Insights
Market Dynamics
Premium commercial assets and commodity-grade stock are consolidating into two distinct demand pools. Larsen & Toubro leverages its integrated EPC capabilities to dominate large-scale office and infrastructure projects. Tata Projects anchors its position through technology-intensive sustainable construction methods. Shapoorji Pallonji competes across heritage restoration and modern commercial complexes with specialized craftsmanship.
Segmentation Analysis
India commercial construction encompasses the planning, engineering, and assembly of non-residential structures using reinforced concrete, structural steel, and composite materials for business operations, retail distribution, and hospitality services. Office buildings command the deepest margin pools as multinational corporations seek LEED-certified campuses in Hyderabad and Pune. Warehouses represent the fastest-expanding construction method segment, driven by e-commerce fulfillment networks requiring precast concrete shells with clear heights exceeding twelve meters. Sustainable construction methods are maturing slowly due to higher upfront capital requirements and limited contractor familiarity with green certification protocols.
Regulatory Environment
The Bureau of Indian Standards mandates IS 456 and IS 800 compliance for reinforced concrete and steel design, while state RERA authorities enforce project disclosure and escrow norms that reshape developer working capital cycles. BIS certification for structural materials and the Ministry of Environment's clearance requirements for large projects constrain market access for undercapitalized regional contractors. Stakeholders must monitor evolving state-level building codes and municipal densification policies that will determine permissible floor area ratios in India's fastest-urbanizing districts.
Market Dynamics
State-level RERA implementations are compressing developer working capital cycles while BIS structural mandates raise compliance costs, bifurcating the market between capital-rich national firms and liquidity-constrained regional contractors.
Growth Catalysts
- Warehousing demand surge:E-commerce fulfillment networks require precast concrete shells with clear heights exceeding twelve meters across Gujarat and Maharashtra logistics corridors.
- LEED certification pull:Multinational corporations specify green building standards for Hyderabad and Pune campuses, creating premium construction pipelines.
- PLI scheme tailwinds:Manufacturing-linked incentives attract industrial facility investments into Tamil Nadu and Karnataka commercial zones.
Market Restraints
- Steel price volatility:Structural steel input costs fluctuate with global commodity cycles, compressing fixed-price contract margins for mid-tier contractors.
- Cement supply concentration:Regional clinker production clusters in Rajasthan and Andhra Pradesh create logistics bottlenecks for distant project sites.
- Environmental clearance friction:Ministry of Environment timelines for large commercial projects extend pre-construction phases by eight to fourteen months.
Strategic Opportunities
- Tier-II city penetration:Kochi, Indore, and Chandigarh office markets remain underdeveloped relative to absorption potential in IT and financial services.
- Precast-MEE convergence:Modular concrete systems combined with mechanical-electrical integration reduce on-site labor dependency and accelerate envelope completion.
- RERA escrow innovation:Project-specific fund administration creates new fee-based revenue streams for construction-adjacent financial service providers.
Industry Challenges
- BIM skill scarcity:Building information modeling competency remains concentrated among top-tier contractors, limiting digital coordination adoption.
- Green certification delays:IGBC and GRIHA assessor capacity constraints extend final commissioning timelines for sustainable commercial assets.
- Subcontractor coordination complexity:Fragmented MEP and finishing trades create interface management burdens on general contractors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Commercial Construction Market |
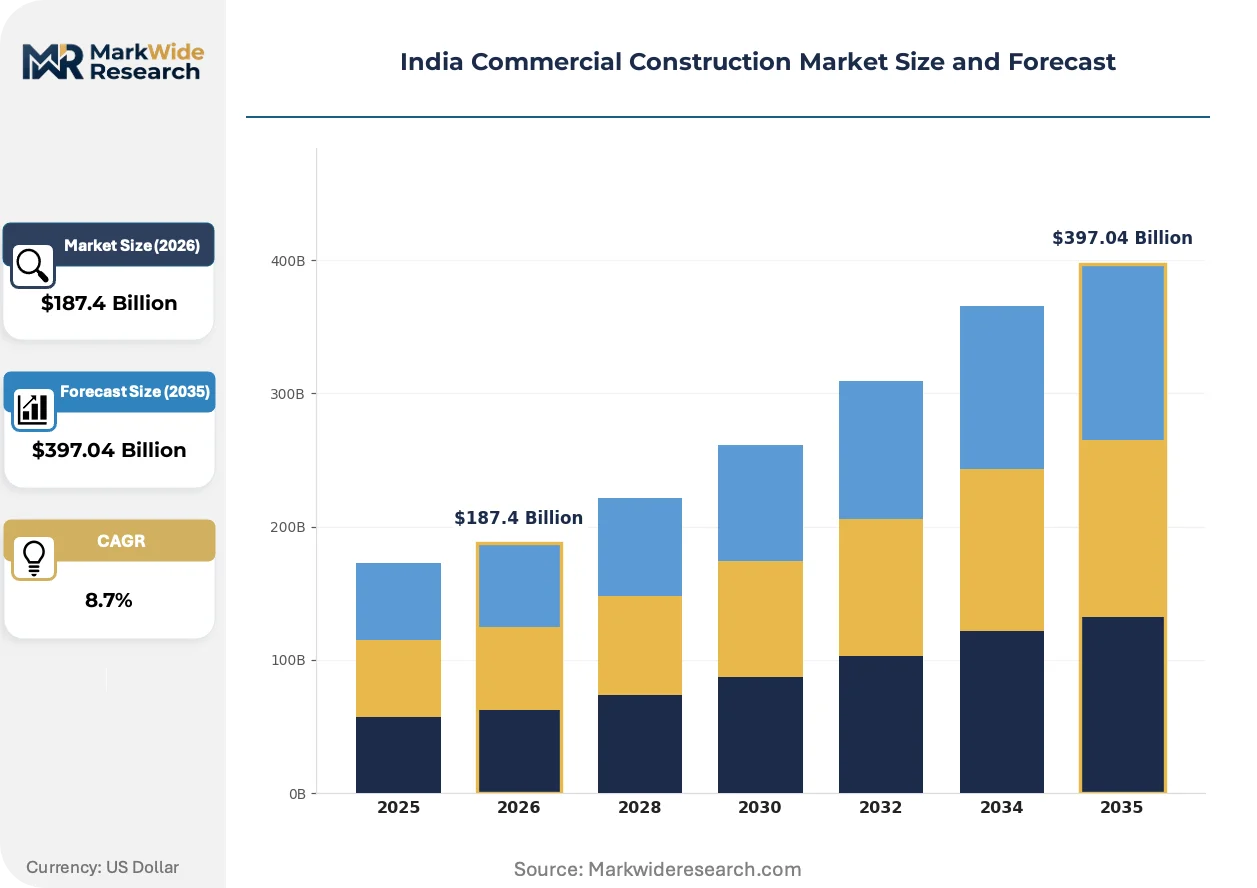
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $397.04 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Office Buildings, Retail Spaces, Warehouses, Hotels Construction Method: Modular, Precast, Traditional, Sustainable End User: Corporations, Government, Retailers, Developers Project Size: Small Scale, Mid Scale, Large Scale, Mega Projects |
| Companies Covered | Larsen & Toubro, Tata Projects, Shapoorji Pallonji, Afcons Infrastructure, NCC, Hindustan Construction Company, GMR Group, Macrotech Developers, BHUTANI INFRA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Commercial Construction Market Trends and Innovations
Digital fabrication methods and regulatory disclosure requirements are compressing traditional construction timelines while reshaping how developers sequence capital deployment across project phases.
Drone-based site surveying combined with photogrammetry is automating earthwork volume calculations and progress monitoring for large-scale commercial developments. Mid-sized contractors in Bengaluru and Hyderabad are adopting these tools to reduce manual surveying headcount. The technology is automating quality assurance workflows that previously required dedicated site engineers.
BIS amendments to IS 456 and IS 800 are mandating enhanced seismic detailing for high-rise commercial structures in seismic zones III and above. The regulatory tightening forces structural redesigns for projects exceeding fifteen stories in Delhi-NCR and Mumbai. Developers are responding by engaging specialized structural consultants earlier in schematic design phases.
Build-to-suit leasing structures are displacing speculative development as the dominant commercial construction procurement model. Institutional investors and occupiers now directly commission Grade A office and warehousing assets rather than acquiring post-completion. This shift concentrates most visibly in Mumbai's BKC corridor and Hyderabad's HITEC City periphery.
India Commercial Construction Market Segmentation
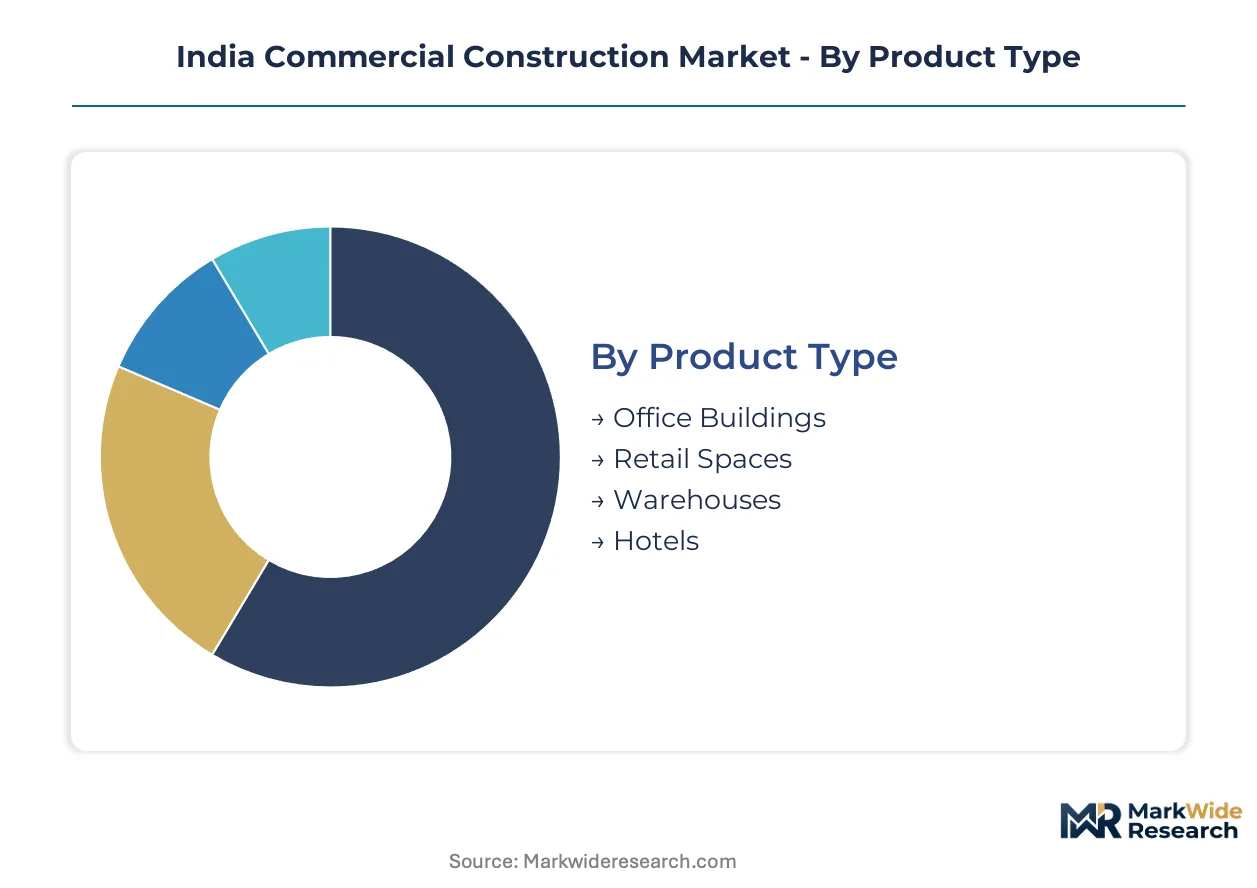
Segmentation in India's commercial construction market reveals distinct procurement patterns and margin structures across asset classes and delivery methods. Understanding these divisions allows stakeholders to align capital deployment with demand concentration zones and regulatory compliance requirements.
Product Type:
Standalone assets dominate capital allocation, while embedded hospitality and retail components integrate into mixed-use developments with shared infrastructure.
- Office Buildings:Reinforced concrete and composite steel structures designed for multinational occupancy specifications. Demand concentrates in Hyderabad and Pune for LEED-certified campuses as corporations mandate green building standards for headquarters consolidation.
- Warehouses:Precast concrete shells with clear heights exceeding twelve meters optimized for automated fulfillment systems. E-commerce logistics networks in Gujarat and Maharashtra drive the steepest expansion trajectory for this segment.
- Retail Spaces:High-street and mall configurations serving consumer distribution networks.
- Hotels:Hospitality assets ranging from business properties to luxury resorts.
Volume placements concentrate in Office Buildings; the faster expansion belongs to Warehouses.
Construction Method:
Cost tier differentiation separates capital-intensive industrialized approaches from labor-dependent conventional techniques.
- Precast:Factory-cast concrete elements assembled on-site with reduced labor dependency. Logistics corridors across Gujarat and Maharashtra adopt this method for accelerated envelope completion.
- Sustainable:Green certification-compliant techniques incorporating energy-efficient envelopes and renewable integration. Hyderabad and Pune campuses specify these methods for multinational tenant requirements.
- Modular:Volumetric units manufactured off-site for rapid assembly.
- Traditional:Cast-in-place concrete with on-site formwork and curing.
Traditional methods retain volume dominance; sustainable construction gains share fastest as certification requirements tighten.
End User:
Customer type determines project scale, specification intensity, and payment security structures.
- Corporations:Direct commissioning of build-to-suit assets with institutional capital backing. Mumbai's BKC corridor and Hyderabad's HITEC City periphery show the most visible concentration of this procurement model.
- Developers:Speculative construction with pre-leasing risk management strategies.
- Government:Public infrastructure and administrative facility projects.
- Retailers:Distribution network expansion with standardized prototype specifications.
Corporations anchor premium construction pipelines; developer activity accelerates most quickly in warehousing zones.
Project Size:
Scale thresholds determine contractor qualification requirements and regulatory scrutiny intensity.
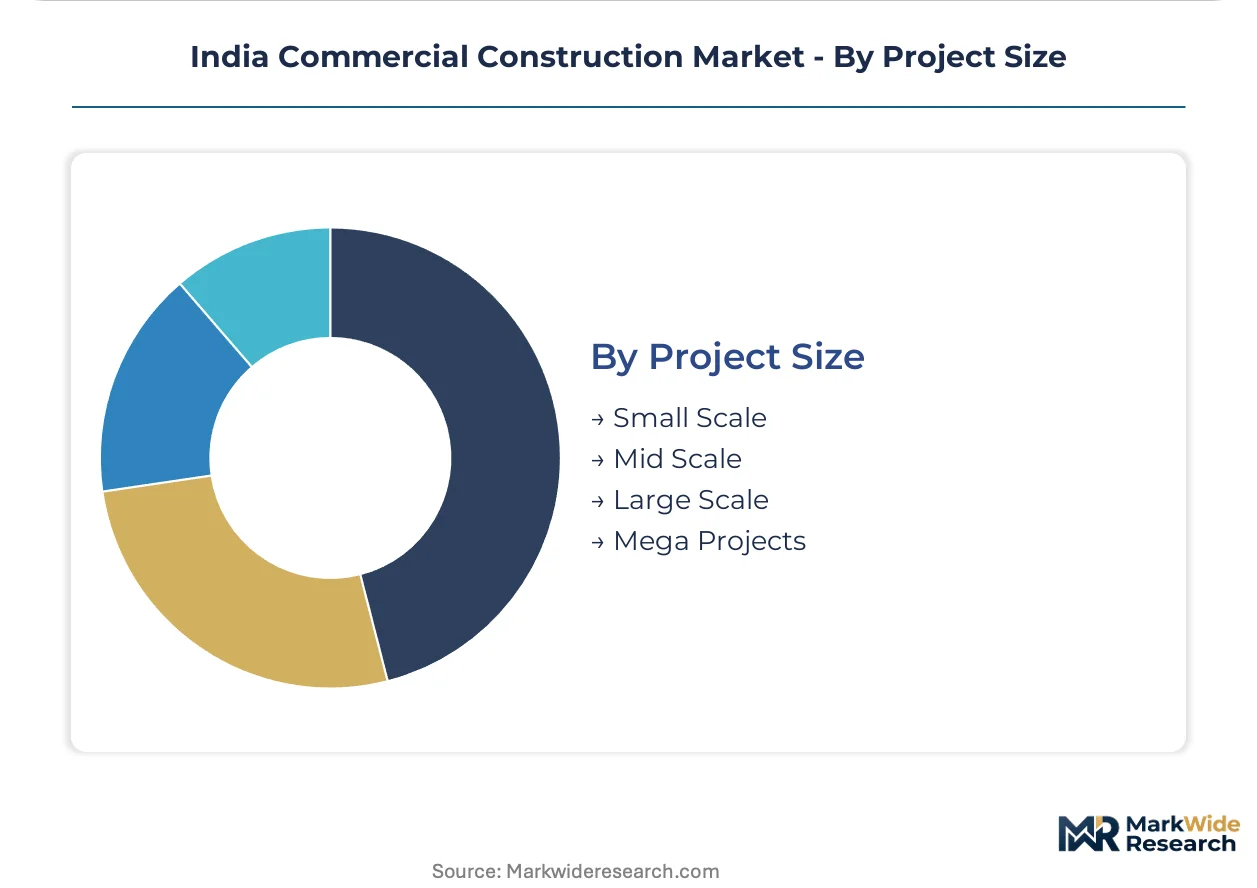
- Large Scale:Developments exceeding 500,000 square feet requiring specialized structural consultants and extended environmental clearance timelines. Delhi-NCR and Mumbai high-rise commercial structures trigger enhanced BIS seismic detailing mandates.
- Mega Projects:Integrated mixed-use developments with multi-phase capital deployment.
- Mid Scale:Regional office and retail assets with standardized delivery.
- Small Scale:Local commercial renovations and infill construction.
Large Scale projects dominate capital deployment; Mega Projects expand most quickly as institutional investors consolidate land parcels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mumbai's Bandra-Kurla Complex anchors India's commercial construction activity, drawing institutional capital toward Grade A office developments and integrated mixed-use assets.
Maharashtra
Multinational banking and financial services firms drive demand for LEED-certified campuses in Mumbai's BKC and Navi Mumbai corridors. State RERA implementation enforces strict project disclosure and escrow norms that compress developer working capital cycles. Pune's Hinjewadi IT cluster attracts technology-intensive sustainable construction methods as corporations consolidate headquarters operations.
Telangana
Hyderabad's HITEC City periphery experiences concentrated build-to-suit commissioning from global technology and pharmaceutical occupiers. BIS seismic detailing mandates for high-rise structures exceeding fifteen stories trigger enhanced structural consultant engagement. The Genome Valley-Gachibowli corridor hosts the fastest-expanding premium office pipeline outside Mumbai.
Karnataka
Bengaluru's Whitefield and Electronic City sub-markets absorb speculative Grade A office development with strong pre-leasing velocity. State-level environmental clearance requirements extend pre-construction timelines for large commercial projects. Drone-based surveying and photogrammetry adoption concentrates among mid-sized contractors seeking to automate quality assurance workflows.
Gujarat
E-commerce fulfillment networks drive warehousing demand across the Ahmedabad-Vadodara logistics corridor with clear height specifications exceeding twelve meters. PLI scheme incentives attract manufacturing-linked industrial facility investments into Sanand and Mundra zones. Precast concrete shell construction dominates envelope completion for accelerated project delivery.
Tamil Nadu
Automotive and electronics manufacturing investments concentrate in Sriperumbudur-Oragadam industrial belts with specialized facility requirements. Central environmental clearance friction extends project initiation timelines by eight to fourteen months for large-scale developments. Chennai's peripheral office markets remain underdeveloped relative to IT and financial services absorption potential.
India Commercial Construction Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification intensity and project scale dimensions. The market bifurcates between capital-rich national firms capable of absorbing compliance cost escalations and liquidity-constrained regional contractors facing BIS mandate pressures. Three archetypes dominate: integrated EPC specialists, technology-intensive sustainable builders, and heritage-craftsmanship hybrid operators. Competitive positioning hardens through build-to-suit partnership structures and precast-MEE capability acquisition.
Within the integrated EPC tier, Larsen & Toubro and Tata Projects exemplify contrasting strategic postures. Larsen & Toubro anchors large-scale office and infrastructure dominance through captive engineering and construction coordination. Tata Projects occupies a technology-forward position emphasizing sustainable construction protocols for multinational tenant specifications. Shapoorji Pallonji represents the craftsmanship-specialist archetype, spanning heritage restoration competencies and modern commercial complex delivery.
| Leading Market Players |
|---|
| Larsen & Toubro |
| Tata Projects |
| Shapoorji Pallonji |
| Afcons Infrastructure |
| NCC |
| Hindustan Construction Company |
| GMR Group |
| Macrotech Developers |
| BHUTANI INFRA |
| Others |
Pricing and Supply Chain Analysis
Skilled structural engineers concentrated in Mumbai and Hyderabad create labor-cost differentials that widen pricing-tier spreads between premium LEED-certified campuses and commodity-grade warehousing shells. BIS seismic compliance mandates for high-rise commercial structures intensify consultant premiums, compressing margins for contractors lacking in-house technical depth.
Pricing Analysis
Value-based pricing anchored to energy performance outcomes and LEED certification tiers separates premium construction pipelines from commodity warehousing bids. Three-tier pricing structure across platinum-certified, standard-compliant, and basic-specification levels reflects certification investment differentials and brand premiums. Price erosion runs through mid-scale office segments as fixed-price contracts absorb steel and cement input volatility. Corporate occupiers commissioning build-to-suit assets show least price sensitivity, while speculative developers in Tier-II cities face acute margin compression.
Supply Chain Analysis
Reverse-logistics flows for structural steel offcuts and precast concrete formwork refurbishment create secondary material markets that reduce virgin input dependency. Raw material sourcing draws from China for structural steel sections, domestic Rajasthan and Andhra Pradesh clusters for cement clinker, and South Korea for specialized seismic damping systems. Single-source vulnerability concentrates in imported high-strength steel alloys for seismic zones III and above. Distribution runs through project-specific logistics corridors with dedicated fleet arrangements for precast element transport.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India commercial construction operates as a supply-constrained market where certified structural engineer scarcity props pricing power for compliant contractors. BIS mandate enforcement tightens this bottleneck, favoring capital-rich national firms over regional competitors.
For Market Incumbents: Extend precast-MEE integration capabilities through captive manufacturing investments in Gujarat and Maharashtra logistics corridors. Acquire specialized seismic consulting practices to internalize BIS compliance costs and defend margin position against technology-intensive sustainable builders. Cement supply concentration in distant production clusters threatens cost predictability; backward integration into clinker logistics or long-term offtake agreements with Rajasthan producers reduces exposure.
For New Entrants and Emerging Players: Capture underdeveloped Tier-II city office markets in Kochi, Indore, and Chandigarh where IT and financial services absorption runs ahead of Grade A supply. Drone-based surveying and photogrammetry adoption among mid-sized contractors creates white-space for digital-native firms to automate quality assurance workflows. Position through build-to-suit partnership structures with institutional investors seeking direct commissioning relationships rather than speculative development exposure.
For Investors and Strategic Acquirers: The window for entry favors contractors with integrated precast manufacturing and in-house LEED certification capabilities. Long-term viability hinges on RERA escrow innovation and project-specific fund administration services that generate fee-based revenue streams insulated from construction cycle volatility. Monitor state-level building code amendments and municipal densification policy shifts as inflection indicators for permissible floor area ratio expansion in fastest-urbanizing districts.
| Strategic Initiative | Industry Significance |
|---|---|
| Precast Manufacturing Scale-Up | Reduces on-site labor dependency and accelerates envelope completion for e-commerce logistics networks. |
| LEED Certification Investment | Unlocks premium pipelines from multinational corporations consolidating headquarters in Hyderabad and Pune. |
| Seismic Engineering Capability Acquisition | Internalizes BIS compliance costs for high-rise structures exceeding fifteen stories in Delhi-NCR and Mumbai. |
| RERA Escrow Service Launch | Creates fee-based revenue streams from project-specific fund administration for liquidity-constrained developers. |
| Tier-II City Geographic Expansion | Captures absorption potential in IT and financial services corridors ahead of national firm penetration. |
Research Methodology
Multi-period observation of project completion timelines, certification issuance rates, and contractor qualification patterns anchored the trend analysis, supplemented by interviews with EPC contract managers, structural engineering consultants, state RERA compliance officers, and institutional investor asset directors. Secondary validation drew from BIS amendment records, state environmental clearance databases, municipal corporation building permits, and Ministry of Commerce construction input trade statistics. Bottom-up project pipeline enumeration and top-down sectoral value estimates underwent iterative reconciliation.
Segment-weighting across product type, construction method, end user, and project scale dimensions informed volume and value allocation. Office buildings, warehouses, retail spaces, and hospitality assets carried distinct margin assumptions; precast, sustainable, modular, and traditional methods received differential adoption trajectories; corporate, developer, government, and retailer procurement patterns shaped payment security and specification intensity; large, mega, mid, and small scale thresholds determined contractor qualification requirements. CAGRs derived from trend extrapolation with elasticity adjustments for regulatory enforcement intensity and capital availability cycles. Steel price volatility coefficients and environmental clearance timeline distributions served as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to BIS mandate expansion, state RERA enforcement heterogeneity, and commodity input price cycles. Practitioners should monitor state-level building code amendments, municipal densification policy shifts, and IGBC assessor capacity constraints for early signals of compliance cost trajectory revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Construction
Vietnam Prefabricated Buildings Market
Building Construction
Germany Commercial Construction Market
Building Construction
Spain Prefab Wood Buildings Market
Building Construction
UAE Prefab Wood Buildings Market
Building Construction
Africa Prefabricated Housing Market
Building Construction
GCC Green Buildings Market
Building Construction
Germany Prefab Wood Buildings Market
Building Construction
Brazil Construction Market
Building Construction
Egypt Construction Market
Building Construction
Oman Construction Market
Building Construction
Asia Pacific Modular Construction Market
Building Construction
United States Commercial Construction Market
Building Construction
Global Modular Fabrication Market
Building Construction
Kuwait Construction Market
Building Construction
Japan Construction Market
Building Construction
Guatemala Construction Market