
 HVAC Systems Market | 2026-2036
HVAC Systems Market Size, Share, and Industry Trends Forecast 2026-2036
HVAC Systems Market Intelligence
The gap between premium climate systems and commodity equipment is expanding. Daikin Industries leverages inverter-driven compressor technology to sustain margins in the VRF segment, while Midea Group competes on manufacturing scale across ductless and packaged unit categories. Carrier Global Corporation anchors its position through backward integration into refrigerant management and controls.
HVAC systems integrate heating, ventilation, and air conditioning subsystems to regulate indoor temperature, humidity, and air quality through vapor-compression cycles, forced-air distribution, and building automation interfaces; they serve the fundamental purpose of maintaining occupant comfort and equipment-safe environments across commercial, institutional, and industrial enclosures. Heat pumps are capturing disproportionate growth as electrification mandates displace fossil-fuel furnaces in new construction and retrofits across temperate climate zones. Smart thermostats and thermal energy storage technologies are concentrating margin pools at the controls layer, while packaged units remain a mature, price-competitive category dominated by replacement demand in existing commercial stock.
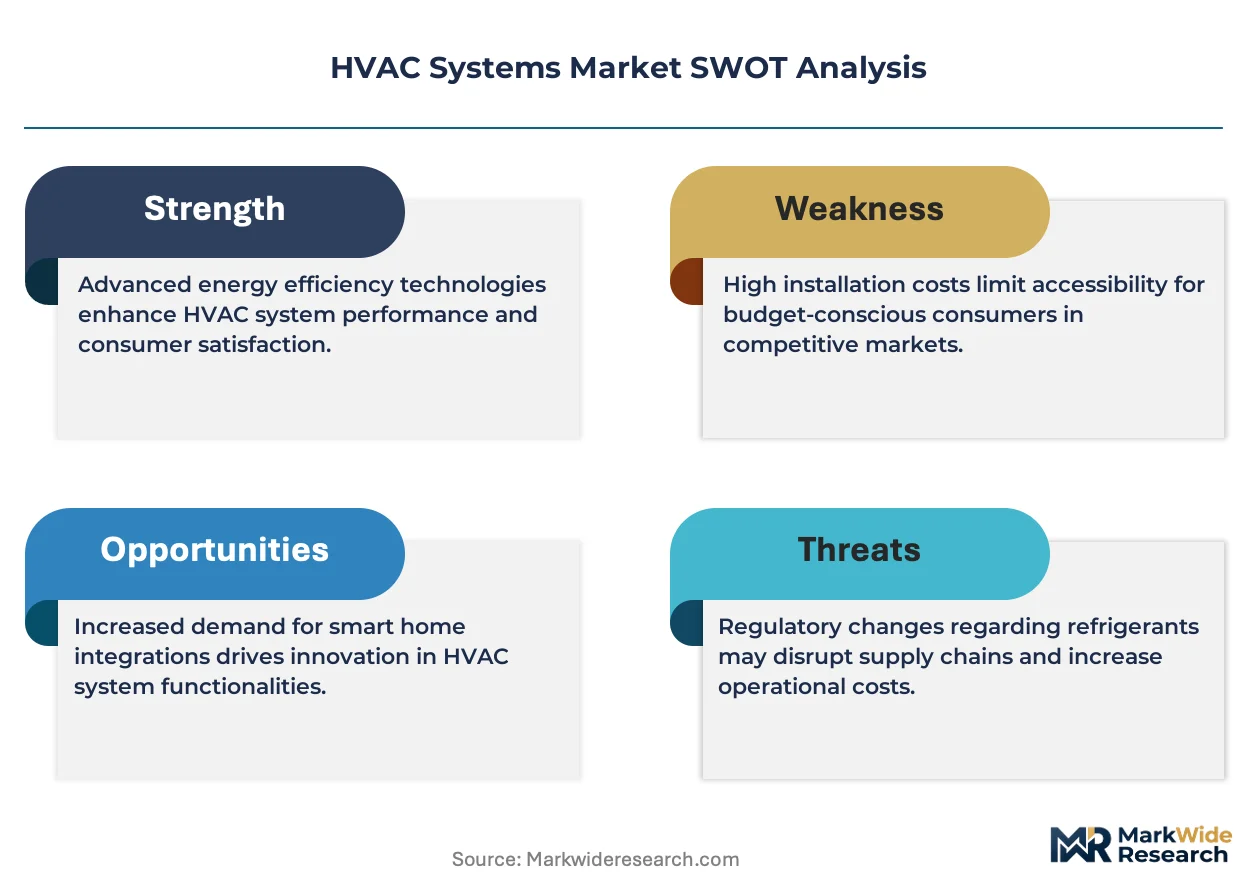
The EPA's HFC phasedown under the AIM Act, DOE appliance efficiency standards, and ASHRAE 90.1 building energy codes collectively shape product design cycles, refrigerant selection, and market access for equipment sold into the United States. The EU F-Gas Regulation and CE marking requirements create parallel compliance obligations for manufacturers serving European commercial building markets. Stakeholders must monitor how refrigerant transition timelines and efficiency tier upgrades reshape supplier qualification criteria and procurement specifications across institutional buyer segments.
Market Dynamics
The EPA's phasedown of HFC refrigerants under the AIM Act is forcing equipment manufacturers to redesign compressor architectures and retool assembly lines around low-GWP alternatives, compressing product development cycles while opening qualification gates for new chemical suppliers.
Growth Catalysts
- AI Data Center Buildouts:Hyperscale facility operators in Northern Virginia, Frankfurt, and Singapore are specifying precision cooling capacity measured in megawatts, pulling demand for high-tonnage chillers and liquid cooling integration.
- IRA Electrification Incentives:The Inflation Reduction Act's 30% tax credit for heat pump installations is accelerating replacement cycles in residential and light commercial stock across the United States.
- Natural Refrigerant Adoption:CO2 transcritical systems and propane-based units are capturing share in European supermarket and industrial refrigeration retrofits as the EU F-Gas Regulation tightens quota allocations.
Market Restraints
- Copper and Aluminum Volatility:Coil and heat exchanger fabrication depends on base metal inputs whose price swings compress margin visibility for packaged unit manufacturers.
- Compressor Supply Concentration:Scroll and rotary compressor production clusters in Thailand and eastern China, creating geographic single-point vulnerability for North American and European OEMs.
- Refrigerant Patent Thickets:Honeywell and Chemours hold blocking positions on HFO formulations, limiting formulation flexibility for second-tier equipment makers.
Strategic Opportunities
- India Building Stock Modernization:The country's commercial real estate pipeline and PLI scheme for white goods manufacturing create white space for VRF and ductless system penetration.
- Thermal Battery Integration:Ice-based and phase-change material storage systems are converging with rooftop units to enable demand-response revenue streams for building operators.
- Service Contract Digitization:Predictive maintenance platforms using equipment telemetry are opening recurring revenue pools independent of original equipment sales.
Industry Challenges
- Refrigerant Handling Certification:The transition to mildly flammable A2L and A3 refrigerants requires technician retraining and inventory segregation, slowing field deployment.
- Legacy Controls Integration:BACnet and Modbus interoperability gaps complicate smart thermostat retrofits in institutional buildings with 15-20 year BAS replacement cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | HVAC Systems Market |
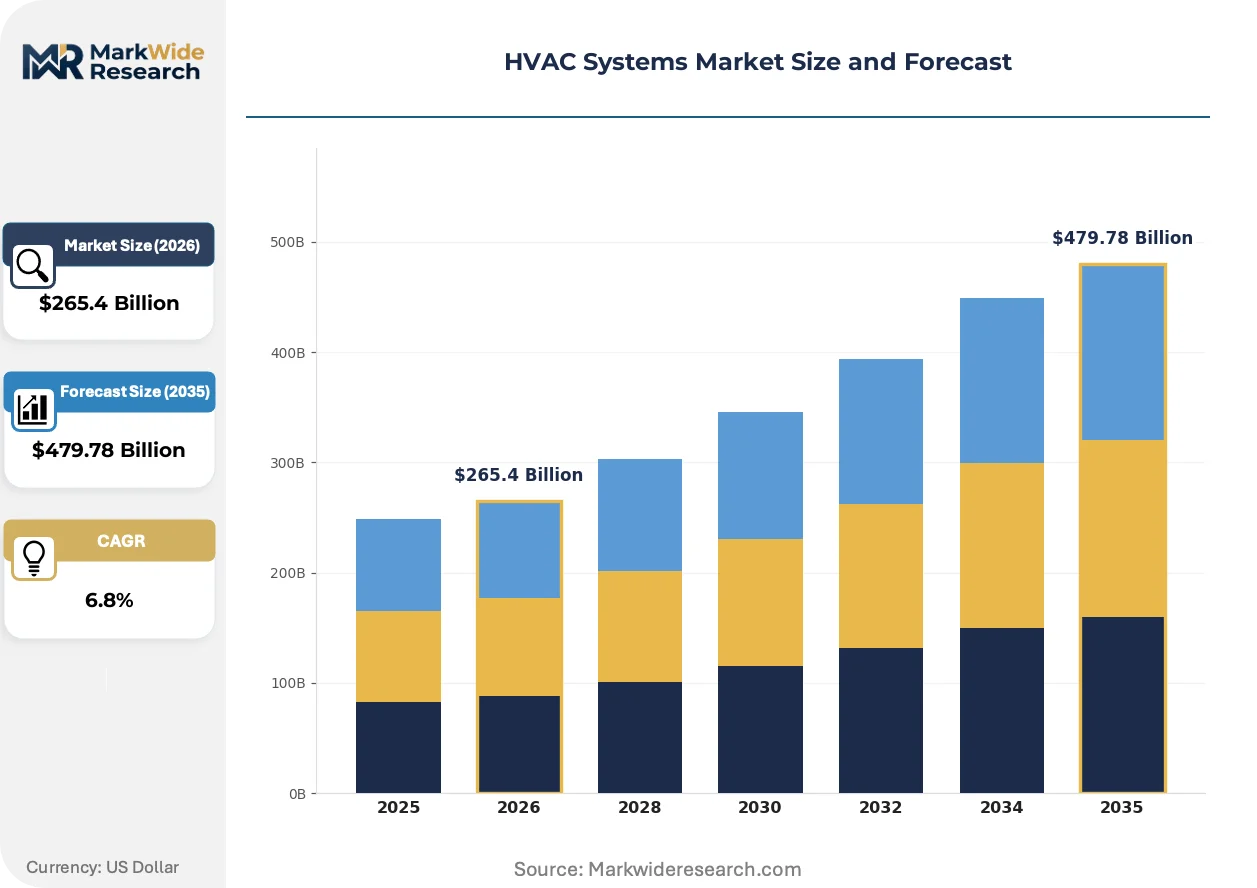
| Market Size in 2026 | $265.4 Billion |
| Market Size in 2035 | $479.78 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Central Air Conditioners, Heat Pumps, Furnaces, Air Handlers, Ductless Systems, Packaged Units Technology: Variable Refrigerant Flow, Chilled Beam, Thermal Energy Storage, Smart Thermostats, Evaporative Cooling, Radiant Heating Application: Commercial Buildings, Data Centers, Educational Institutions, Warehousing, Hospitality, Government Facilities End User: Property Managers, Facility Operators, Real Estate Developers, Hospitality Managers, Educational Administrators, Data Center Managers |
| Companies Covered | Carrier Global Corporation, Daikin Industries Ltd., Trane Technologies plc, Johnson Controls, LG Electronics Inc., Lennox International Inc., Mitsubishi Electric Corporation, Midea Group Co. Ltd., Honeywell International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
HVAC Systems Market Strategic Shifts & Innovations
Digital twin simulation and edge-computed diagnostics are compressing commissioning timelines and shifting performance risk from building operators to equipment-as-a-service providers.
Variable refrigerant flow systems are converging with dedicated outdoor air systems to enable simultaneous heating and cooling recovery across zones, a configuration hyperscale data center operators in Ashburn and Dublin are specifying for thermal load balancing. The integration reduces chiller redundancy requirements. Equipment vendors with controls software capabilities are capturing margin that previously flowed to mechanical subcontractors.
The EU F-Gas Regulation's 2030 phase-down schedule is banning new stationary equipment with GWP above 150 in multiple tranches, forcing European OEMs to validate CO2 and hydrocarbon architectures ahead of quota exhaustion. Component suppliers are consolidating test chamber capacity. The regulatory pressure is most acute in supermarket refrigeration and industrial process cooling, where long asset lives magnify compliance risk.
Building owners are unbundling equipment procurement from installation and maintenance, issuing separate RFPs for each phase and selecting vendors on segment-specific competence rather than single-source relationships. General contractors are losing specification influence to MEP engineers and commissioning agents. The pattern is most visible in United States institutional healthcare and education verticals, where capital project oversight committees demand vendor specialization transparency.
HVAC Systems Market Segmentation
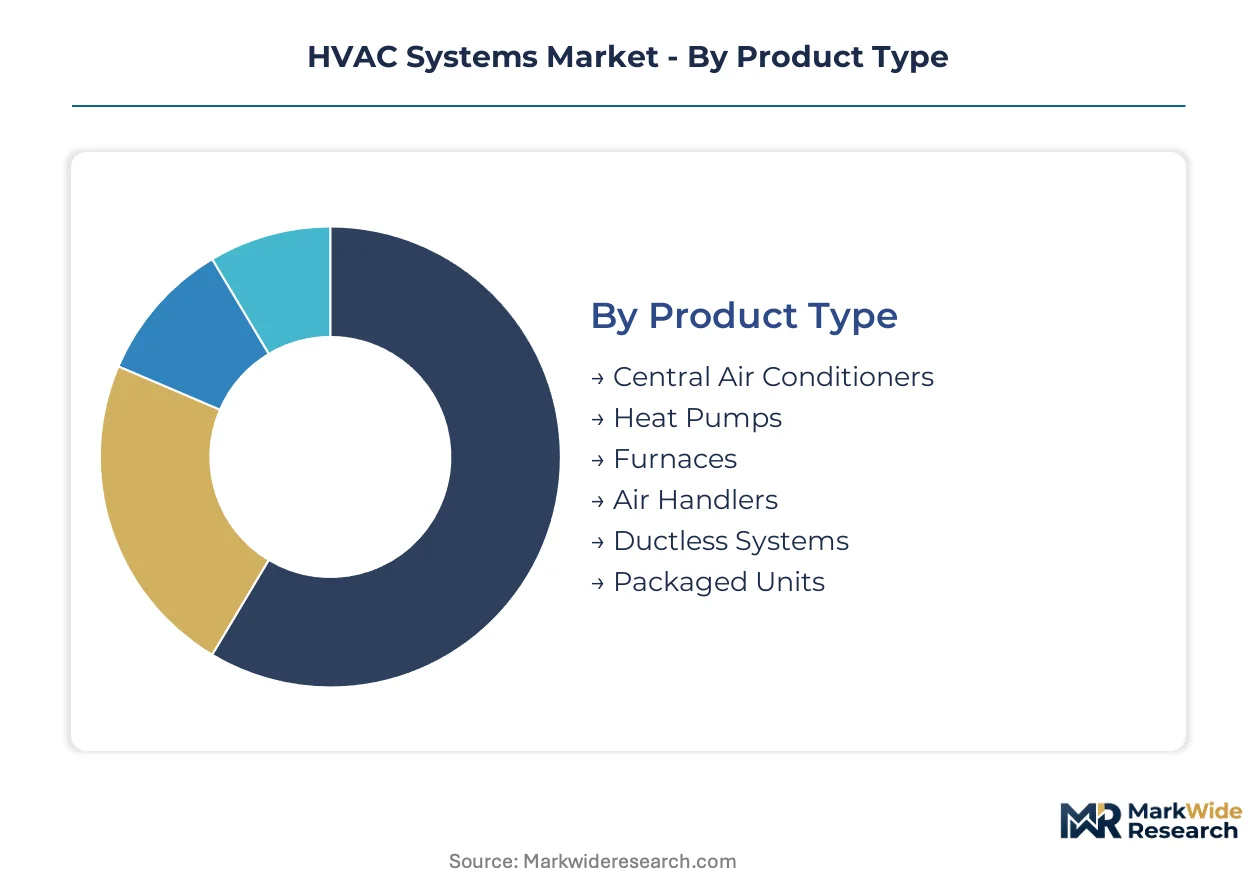
HVAC market segmentation reveals divergent margin structures across product architectures and control technologies. Equipment categories stratify sharply between premium inverter-driven systems and commodity packaged units, while application verticals concentrate demand in data center and healthcare buildouts.
Product Type:
Volume concentrates in replacement cycles for mature equipment categories, while premium capture accrues to electrification-ready heat pump architectures.
- Central Air Conditioners:Split-system and packaged rooftop configurations dominate North American commercial stock replacement. Demand clusters in Sun Belt states where ASHRAE 90.1 code updates trigger efficiency tier upgrades in existing buildings.
- Heat Pumps:Air-source and ground-source variants displace fossil-fuel furnaces under IRA electrification incentives. Cold-climate performance improvements expand viable geography into Minnesota, Wisconsin, and upstate New York.
- Furnaces:Gas-fired forced-air units retain share in legacy residential stock and industrial process heating. EPA emissions standards tighten combustion efficiency minimums.
- Air Handlers:Fan-coil and blower assemblies integrate filtration and humidity control for healthcare and laboratory specifications. Modular designs enable field customization.
- Ductless Systems:Mini-split and multi-split configurations penetrate historic building retrofits where ductwork installation is cost-prohibitive. VRF compatibility drives specification in boutique hospitality.
- Packaged Units:Self-contained rooftop systems serve single-tenant commercial and light industrial facilities. Price competition compresses margins for standardized tonnage ratings.
Today's leader: Central Air Conditioners. Tomorrow's challenger: Heat Pumps.
Technology:
Control layer technologies capture margin expansion through software-enabled optimization, while mechanical innovations face capital-intensive validation cycles.
- Variable Refrigerant Flow:Inverter-driven compressor modulation enables simultaneous heating and cooling recovery across zones. Hyperscale data center operators in Ashburn and Frankfurt specify VRF-DOAS integration for thermal load balancing.
- Chilled Beam:Passive and active hydronic systems deliver cooling without forced-air distribution. European commercial office buildouts favor the technology for acoustic performance and reduced fan energy.
- Thermal Energy Storage:Ice-based and phase-change material systems shift cooling load to off-peak hours. Utility demand-response programs create recurring revenue streams for building operators.
- Smart Thermostats:Edge-computed diagnostics and occupancy sensing compress commissioning timelines. BACnet interoperability gaps complicate retrofits in institutional buildings with legacy BAS infrastructure.
- Evaporative Cooling:Direct and indirect configurations serve arid climate zones with low wet-bulb temperatures. Water scarcity constraints limit deployment in drought-prone regions.
- Radiant Heating:Hydronic and electric floor/wall systems deliver comfort without air movement. Residential new construction in temperate zones pairs with heat pump water heaters.
Control layer technologies expand most quickly; mechanical systems face longer adoption curves.
Application:
End-use verticals separate between mission-critical facilities requiring precision environmental control and commodity comfort conditioning.
- Commercial Buildings:Office, retail, and mixed-use facilities drive replacement demand for rooftop units and split systems. Tenant improvement cycles accelerate equipment refresh in Class A properties.
- Data Centers:Hyperscale and colocation facilities specify cooling capacity measured in megawatts. Liquid cooling integration and high-tonnage chillers dominate procurement specifications.
- Educational Institutions:K-12 and university capital projects prioritize indoor air quality upgrades post-pandemic. EPA ventilation guidelines drive filtration and outdoor air volume increases.
- Warehousing:Distribution centers and cold storage facilities require zoned temperature control for inventory protection. E-commerce fulfillment growth expands square footage requirements.
- Hospitality:Hotels and resorts balance guest comfort with operational visibility through centralized energy management. Boutique properties favor ductless aesthetics.
- Government Facilities:Federal, state, and municipal buildings face procurement mandates for efficiency tier compliance. GSA schedules consolidate vendor qualification.
Data centers command premium pricing; commercial buildings anchor volume.
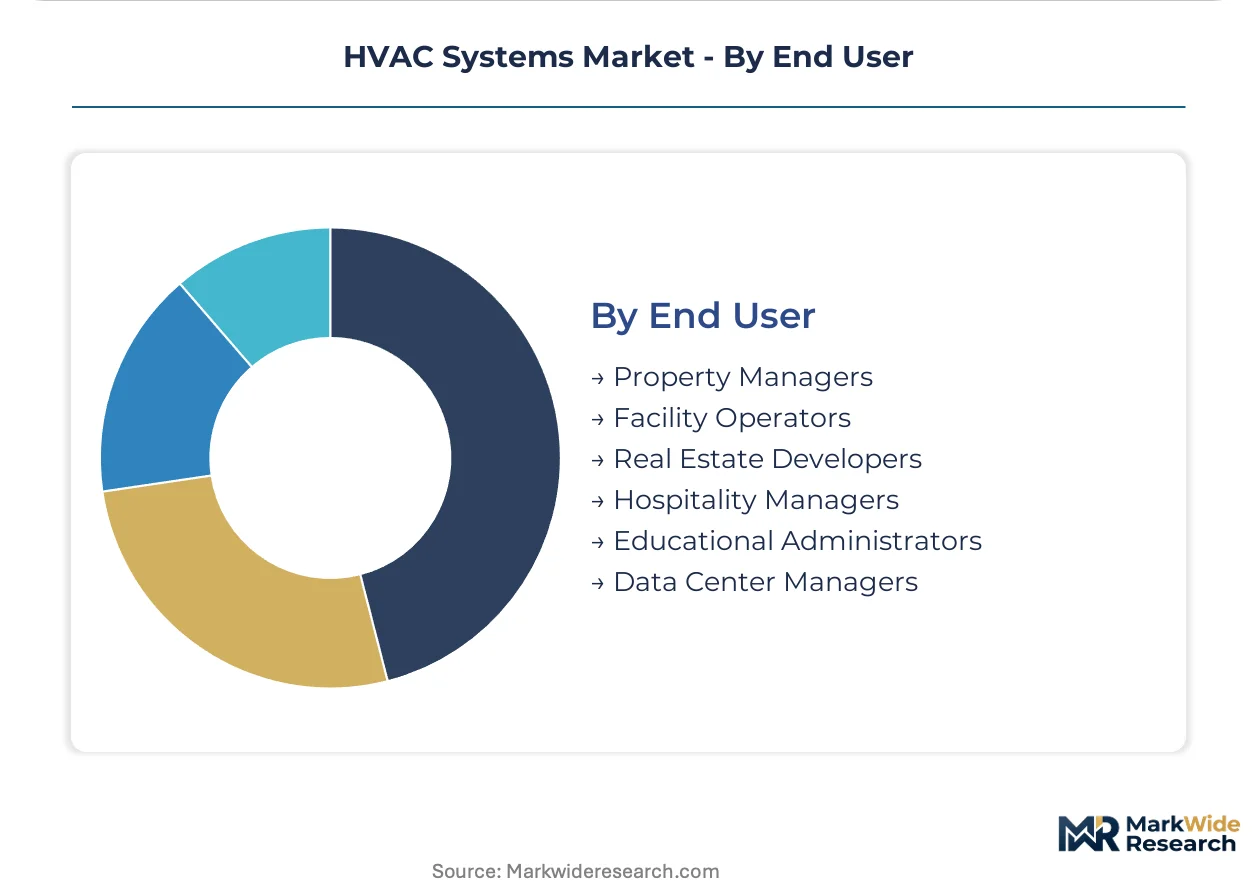
End User:
Procurement authority fragments between asset owners, operating tenants, and specialized facility managers with divergent capital planning horizons.
- Property Managers:Multi-tenant commercial portfolios prioritize equipment reliability and service contract predictability over efficiency optimization.
- Facility Operators:In-house engineering teams at hospitals and universities demand controls interoperability and technician training support.
- Real Estate Developers:Speculative construction favors first-cost minimization with code-minimum efficiency ratings.
- Hospitality Managers:Franchise operators balance brand standards with local climate adaptation and energy cost management.
- Educational Administrators:School districts and university facilities departments navigate bond financing cycles for capital equipment replacement.
- Data Center Managers:Hyperscale operators specify custom chiller configurations and liquid cooling integration with 15-year TCO modeling.
Facility operators drive specification complexity; developers resist first-cost premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled HVAC technicians and building automation engineers concentrate in Germany's industrial belt, Japan's precision manufacturing corridors, and the United States' Sun Belt construction zones. These talent clusters anchor regional demand patterns and shape equipment specification standards.
United States
Data center construction in Northern Virginia and Dallas-Fort Worth drives demand for high-tonnage chillers and liquid cooling integration. The Inflation Reduction Act's heat pump tax credits accelerate residential and commercial electrification retrofits. ASHRAE 90.1 code updates in California and New York trigger efficiency tier upgrades across existing building stock.
Germany
Commercial office buildouts in Frankfurt and Munich specify chilled beam systems and VRF-DOAS configurations for acoustic performance. The EU F-Gas Regulation's 2030 phase-down mandates CO2 and hydrocarbon refrigerant validation ahead of quota exhaustion. Bavaria's industrial corridor hosts test chamber consolidation for natural refrigerant architectures.
China
Urbanization in the Yangtze River Delta and Pearl River Delta sustains volume demand for ductless mini-split and multi-split systems. GB standards and dual carbon goals tighten efficiency minimums for equipment sold domestically. Zhejiang and Guangdong provinces concentrate compressor manufacturing clusters serving regional OEM supply chains.
India
Commercial real estate pipelines in Mumbai and Bangalore create penetration opportunities for VRF and ductless systems in high-end developments. The PLI scheme for white goods manufacturing incentivizes domestic assembly capacity expansion. Gujarat and Tamil Nadu host emerging fabrication facilities targeting institutional and hospitality verticals.
Japan
Building stock renewal in Tokyo and Osaka prioritizes earthquake-resistant equipment and zonal climate control. METI efficiency standards and JIS certification requirements shape product design cycles for domestic and export markets. Nagoya's industrial corridor anchors precision compressor and inverter technology development.
HVAC Systems Market Key Industry Players
Top-tier vendors anchor premium electrification and controls technology, while mid-scale fabricators compete on manufacturing throughput and regional distribution density. The vendor base stratifies between full-stack system integrators with refrigerant management capabilities and component-focused specialists. Two strategic archetypes dominate: inverter-driven compressor technology leaders and controls software platforms. Competitive moves concentrate on backward integration into refrigerant supply chains and capacity expansion in Southeast Asian assembly hubs.
Among Asia-Pacific-based conglomerates, Daikin Industries Ltd. and Midea Group Co. Ltd. exemplify divergent scale strategies—one through captive compressor technology development, the other through manufacturing volume across ductless categories. Carrier Global Corporation anchors the North American tier through refrigerant management integration. These three occupy positions spanning premium technology capture and cost-optimized volume deployment.
| Leading Market Players |
|---|
| Carrier Global Corporation |
| Daikin Industries Ltd. |
| Trane Technologies plc |
| Johnson Controls |
| LG Electronics Inc. |
| Lennox International Inc. |
| Mitsubishi Electric Corporation |
| Midea Group Co. Ltd. |
| Honeywell International Inc. |
| Others |
Cost & Logistics Intelligence
Backward integration into refrigerant management and compressor technology anchors pricing power for full-stack OEMs while compressing margin pools for assembly-only fabricators. Captive control over critical components insulates tier-one vendors from commodity metal volatility and creates differentiation leverage in specification-driven segments.
Pricing Analysis
Equipment procurement unbundling from installation and maintenance contracts is fragmenting buyer-vendor relationships and intensifying price transparency across standardized tonnage ratings. Three-tier pricing structure across premium inverter-driven, standard fixed-speed, and economy packaged units reflects certification grade and after-sales service bundling. Cost compression in commodity rooftop units is intensifying because copper and aluminum coil fabrication faces base metal volatility. Real estate developers exhibit highest price sensitivity; data center operators demonstrate lowest sensitivity due to TCO-driven procurement.
Supply Chain Analysis
EPA refrigerant handling certification and EU F-Gas quota compliance are gating supplier qualification and concentrating procurement authority among qualified chemical distributors. Scroll and rotary compressor production clusters in Thailand, China, and Japan feed global OEM assembly networks. Coil and heat exchanger fabrication draws from copper cathode and aluminum sheet inputs. Single-source vulnerability in Southeast Asian compressor manufacturing creates geographic concentration risk. Distribution runs through authorized dealer networks and direct MEP contractor relationships in commercial verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electrification mandates and refrigerant transition timelines are compressing replacement cycles and shifting margin capture toward controls-integrated system providers. Efficiency tier upgrades and low-GWP refrigerant validation costs favor scaled incumbents with captive R&D infrastructure.
For Market Incumbents: Deepen backward integration into refrigerant management and thermal energy storage technologies to defend against controls-layer margin erosion. Expand test chamber capacity for CO2 transcritical and hydrocarbon architectures ahead of EU F-Gas quota exhaustion. Secure technician training partnerships to accelerate A2L refrigerant field deployment and capture service contract digitization revenue pools.
For New Entrants and Emerging Players: Capture white space in India's commercial real estate pipeline and PLI-incentivized domestic assembly capacity. Target VRF and ductless penetration in Mumbai and Bangalore high-end developments where first-cost premiums face lower resistance. Lead with thermal battery integration and predictive maintenance platforms to differentiate from established mechanical-only vendors.
For Investors and Strategic Acquirers: Roll-up economics work for regional service contractors with predictive maintenance platforms because building owners are unbundling equipment procurement from long-term maintenance contracts. Five-to-ten year viability hinges on software-enabled recurring revenue capture independent of original equipment sales. Monitor IRA electrification incentive renewal timelines and EPA HFC phasedown enforcement intensity as margin inflection signals.
| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Transition Acceleration | Low-GWP validation ahead of EPA and EU F-Gas deadlines secures market access and procurement qualification. |
| Controls Software Integration | Edge-computed diagnostics and BACnet interoperability capture margin pools previously flowing to mechanical subcontractors. |
| Thermal Energy Storage Deployment | Ice-based and phase-change systems enable utility demand-response revenue streams for commercial building operators. |
| India Manufacturing Footprint Expansion | PLI scheme incentives and commercial real estate pipeline create domestic assembly capacity for VRF and ductless categories. |
| Service Contract Digitization | Predictive maintenance platforms using equipment telemetry open recurring revenue independent of equipment sales cycles. |
Research Approach
Direct dialogue with HVAC equipment procurement managers, MEP engineering consultants, facilities directors at hyperscale data centers, refrigerant supply specialists, and building automation systems integrators grounded qualitative findings. Secondary validation drew from EPA AIM Act implementation documents, DOE appliance efficiency standard dockets, ASHRAE 90.1 code revision records, EU F-Gas Regulation quota allocations, and SEC filings from publicly traded OEMs. Bottom-up equipment shipment analysis and top-down construction spending attribution were triangulated to anchor volume estimates.
Bottom-up modeling aggregated unit economics across product architectures, efficiency tiers, and application verticals; top-down validation cross-referenced regulatory compliance timelines and incentive program budgets. Segmentation dimensions included product type, technology layer, end-use vertical, and procurement authority archetype. CAGRs were derived from replacement cycle acceleration patterns and electrification mandate penetration curves. Forecast inputs incorporated IRA tax credit uptake rates and data center power density projections.
Refrigerant patent litigation outcomes, copper futures volatility spikes, and technician certification bottlenecks are the dominant revision risks to modeled assumptions. Forecasts reflect documented regulatory phase-down schedules and efficiency tier upgrade timelines. A model refresh is warranted upon material change in federal electrification incentive continuity or EPA enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Air-Conditioning Natural Convection Refrigerator Market
HVAC Equipment
Europe Hydronic Radiators Market
HVAC Equipment
Desert Air Cooler Market
HVAC Equipment
Industrial Refrigeration Equipment Market
HVAC Equipment
Asia-Pacific Heating Equipment Market
HVAC Equipment
High Pressure Heat Exchanger Market
HVAC Equipment
United States HVAC Equipment and Services Market
HVAC Equipment
Centrifugal Blower Market
HVAC Equipment
Ceiling Cassettes Market
HVAC Equipment
HVAC Louvers Market
HVAC Equipment
North America Heat Exchanger Market
HVAC Equipment
Warm Air Furnaces Market
HVAC Equipment
Thermo Ventilators Market
HVAC Equipment
North America Residential Heat Pump Market
HVAC Equipment
Swing Compressor Market
HVAC Equipment
Underfloor Heating Market