
 Middle-East and Africa Compressor Market | 2026-2036
Middle-East and Africa Compressor Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East and Africa Compressor Market Foresight
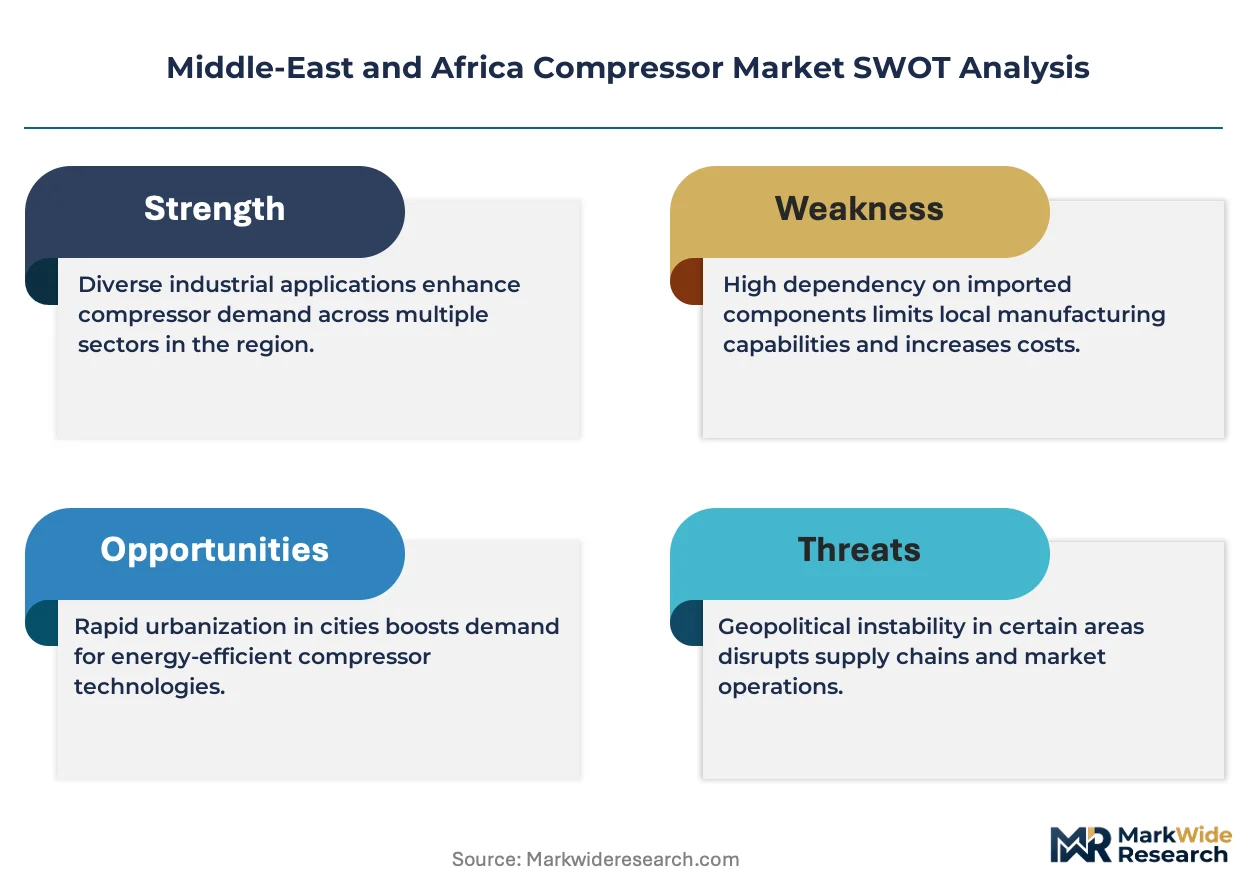
ISO 8573 air quality certification is unwinding the competitive landscape for compressor suppliers across the Middle-East and Africa. Atlas Copco AB leverages its oil-free compressor portfolio to capture premium positions in pharmaceutical and food-grade applications. Kaeser Kompressoren GmbH anchors its regional presence through localized service networks and energy audit capabilities. Siemens AG competes on integrated digital monitoring platforms that tie compressor performance into broader plant automation architectures.
A compressor is a mechanical device that increases the pressure of a gas by reducing its volume, typically achieving discharge pressures from 100 psi to over 5,000 psi depending on stage configuration and application requirements. Reciprocating compressors dominate high-pressure process gas duties in upstream oil fields where reliability under cyclic loading determines operational economics. Rotary screw compressors lead the manufacturing and automotive end-user segments due to their continuous duty capability and lower maintenance intensity compared to piston-based alternatives. Centrifugal compressors command the largest capital allocations in liquefied natural gas trains and petrochemical complexes where flow volumes exceed 10,000 cubic feet per minute.
Saudi Arabia's SFDA and the UAE's MOHAP enforce equipment safety standards for compressors deployed in pharmaceutical and healthcare environments, while regional environmental agencies adopt EU F-Gas Regulation analogs for refrigerant compressor emissions. The UAE's adoption of CE marking alignment for industrial equipment imports creates a dual-compliance burden that favors suppliers with established European certification pathways. Stakeholders must monitor how Gulf Cooperation Council harmonization of technical standards reshapes market access rules and local content requirements across member states.
Market Dynamics
SFDA and MOHAP certification mandates for pharmaceutical-grade compressed air systems are forcing Gulf-based operators to replace legacy equipment ahead of scheduled replacement cycles, creating an artificial demand spike independent of underlying industrial expansion.
Growth Catalysts
- Enhanced Oil Recovery Deployment:Saudi Aramco and ADNOC are expanding gas injection compressor capacity across mature offshore fields, requiring high-pressure reciprocating units rated for sour gas service.
- EU F-Gas Regulation Analogs:UAE environmental agencies are adopting refrigerant emission controls that mandate compressor fleet retrofits in commercial cold chain infrastructure.
- Food-Grade Air Standards:ISO 8573 Class 0 certification requirements from regional dairy and beverage processors are pulling oil-free screw compressor demand in Egypt and Morocco.
Market Restraints
- Specialized Alloy Input Volatility:Duplex stainless steel and nickel-based superalloy price swings constrain margins for centrifugal compressor manufacturers serving LNG train projects.
- European Component Concentration:High-speed magnetic bearing and variable frequency drive supply chains remain concentrated among German and Swiss suppliers, exposing regional assemblers to extended lead times.
- Reciprocating Compressor Footprint Limits:Physical size and vibration isolation requirements restrict deployment options on offshore platforms where deck space commands premium valuations.
Strategic Opportunities
- Nigeria Deepwater Gas Development:Pre-salt field monetization projects require subsea compression infrastructure that remains undersupplied by regional service networks.
- Digital Twin Integration:Convergence of edge computing platforms with compressor performance telemetry enables predictive maintenance contracts that capture recurring revenue streams.
- Local Content Mandates:Saudi Arabia's IKTVA program and UAE In-Country Value requirements create procurement preferences for suppliers establishing domestic assembly and service capabilities.
Industry Challenges
- Rotating Equipment Specialist Scarcity:Commissioning engineers qualified for centrifugal compressor aerodynamic troubleshooting command compensation premiums that inflate project overhead.
- Dual Certification Timelines:Equipment requiring concurrent SFDA pharmaceutical approval and ATEX hazardous area compliance faces extended validation cycles that delay revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East and Africa Compressor Market |
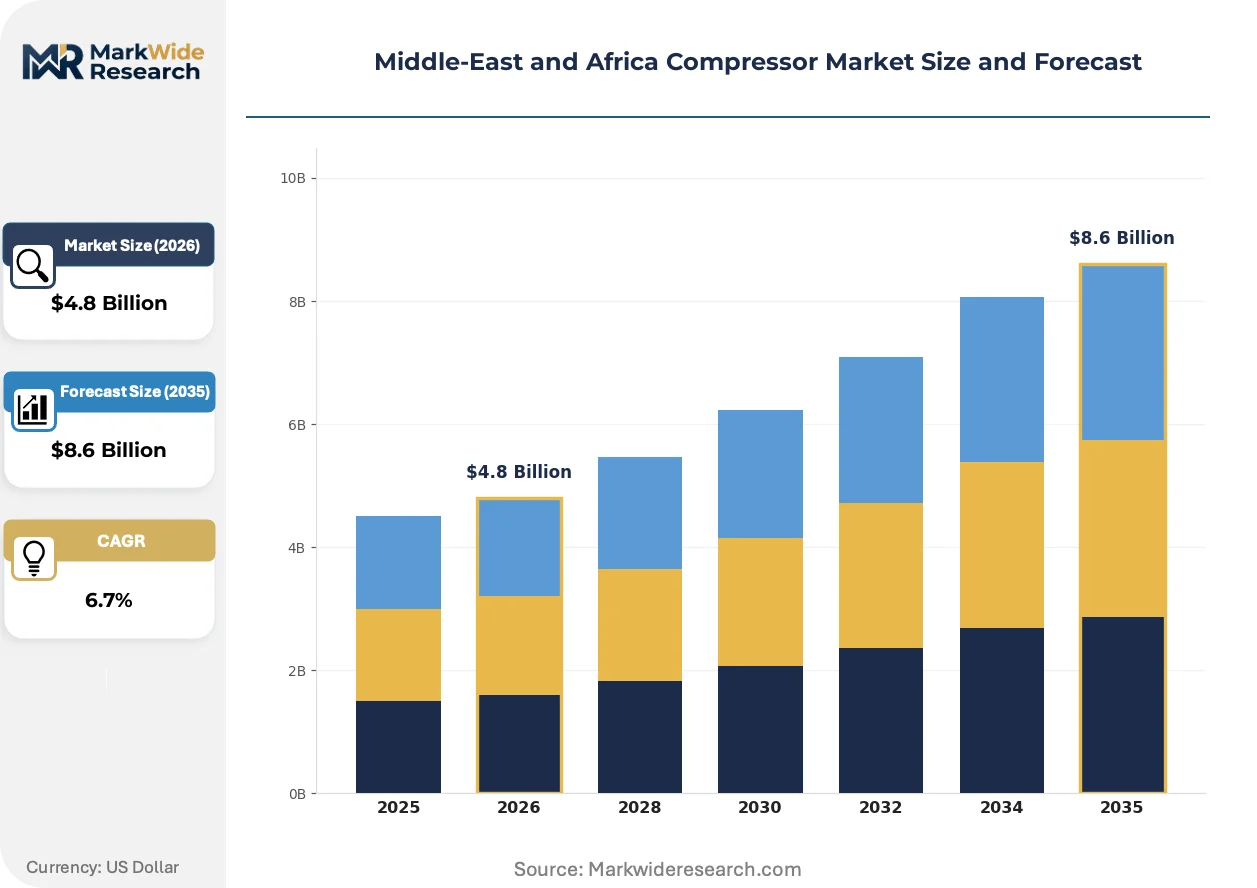
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reciprocating, Rotary Screw, Centrifugal, Scroll End User: Manufacturing, Oil & Gas, Automotive, Construction Technology: Electric, Diesel, Hybrid, Pneumatic Application: Refrigeration, Air Conditioning, Process Gas, Pneumatic Tools |
| Companies Covered | Atlas Copco AB, Kaeser Kompressoren GmbH, Mitsubishi Heavy Industries Ltd, Siemens AG, Aerzener Maschinenfabrik GmbH, Ingersoll Rand plc, Baker Hughes Co, General Electric Company, Trane Technologies PLC, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East and Africa Compressor Market Shifts & Advancements
Compressed air system architecture is pivoting from standalone units to integrated plant networks, with connectivity and energy optimization displacing pure mechanical reliability as the primary procurement criterion.
Magnetic bearing technology is fragmenting the high-speed centrifugal compressor segment by eliminating oil lubrication systems and enabling direct-drive configurations. Petrochemical complexes in Jubail and Ruwais are specifying these units for continuous process air duties. The technology is fragmenting aftermarket service structures by shifting revenue from parts replacement toward electronics diagnostics and software updates.
SFDA pharmaceutical equipment guidelines and UAE MOHAP medical gas standards are tightening validation documentation for compressor systems deployed in sterile manufacturing environments. Manufacturers must now submit complete material traceability and cleanroom compatibility certifications prior to commercial approval. Sterile fill-finish operations in Saudi Arabia and the UAE represent the most affected segment, with procurement teams prioritizing suppliers holding existing European MDR documentation.
Energy-as-a-service contracting is displacing traditional capital purchase models for large compressed air installations. Industrial clusters in Dubai's Jebel Ali Free Zone and Oman's Sohar Port are adopting performance-based agreements where suppliers retain equipment ownership and charge per cubic meter of compressed air delivered. This restructuring concentrates procurement authority with specialized energy service companies rather than end-user engineering departments.
Middle-East and Africa Compressor Market Segmentation
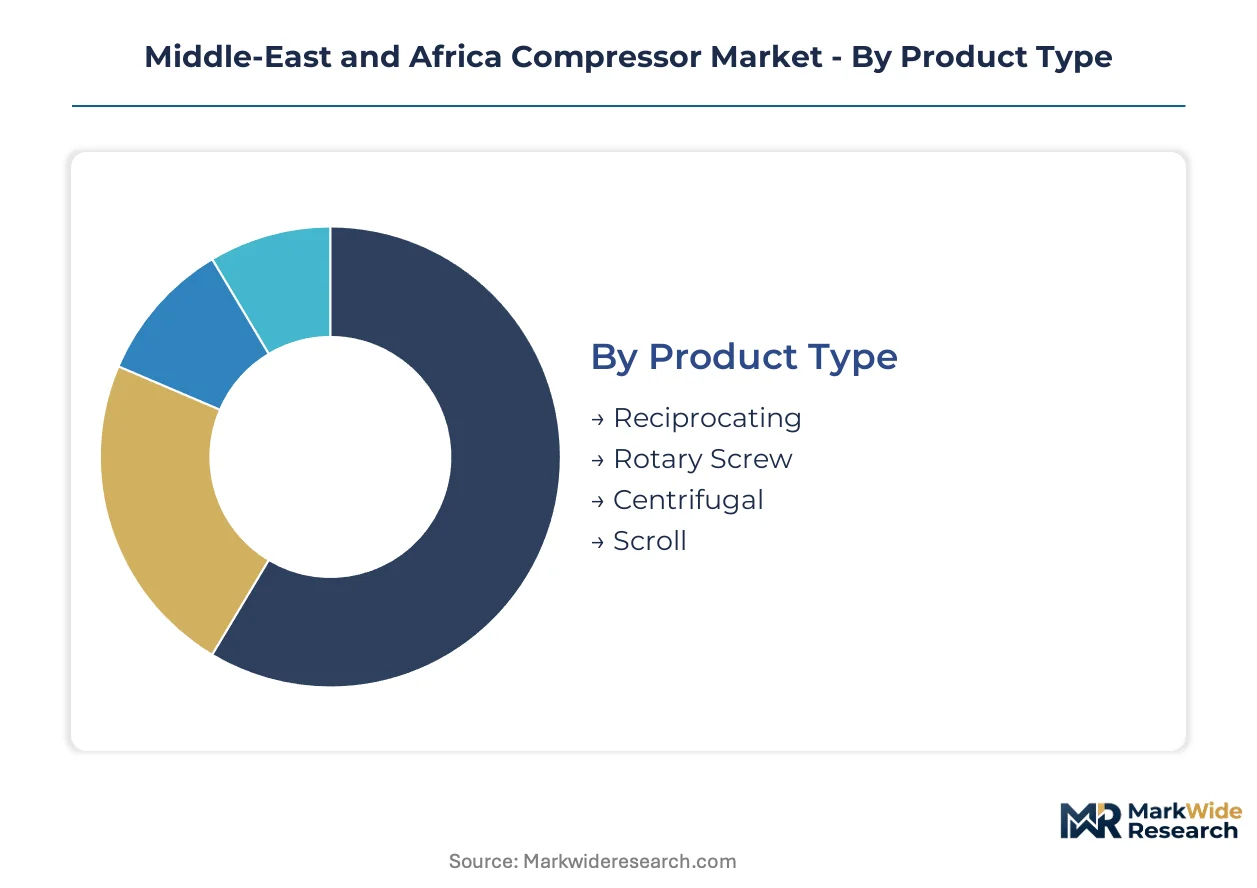
Compressor procurement patterns across the Middle-East and Africa diverge sharply between export-oriented energy infrastructure and domestic manufacturing operations. Understanding these segment boundaries clarifies why technology preferences and certification requirements vary by end-use context.
Product Type:
Reciprocating and centrifugal units dominate cross-border project flows into Gulf oil and gas developments, while rotary screw compressors serve localized manufacturing demand in Egypt and Morocco.
- Reciprocating:Piston-driven compression achieves discharge pressures exceeding 5,000 psi through multi-stage configurations. Saudi Aramco and ADNOC specify these units for sour gas injection at mature offshore fields where reliability under cyclic loading determines field economics.
- Centrifugal:Dynamic compression principles handle continuous flow volumes above 10,000 cubic feet per minute. LNG train projects in Qatar and Nigeria concentrate demand for these capital-intensive systems, though nickel-based superalloy input costs strain manufacturer margins.
- Rotary Screw:Continuous-duty rotary mechanisms serve automotive and manufacturing clusters in Dubai's Jebel Ali Free Zone with lower maintenance intensity than piston alternatives.
- Scroll:Orbiting scroll technology occupies commercial refrigeration and small-scale climate control applications across North African urban centers.
Reciprocating compressors command the established base in upstream hydrocarbon service. The steepest expansion runs through centrifugal units as LNG and petrochemical capacity additions accelerate.
End User:
Oil and gas procurement concentrates in national operator tenders with IKTVA and In-Country Value requirements, while manufacturing demand fragments across private industrial clusters.
- Oil & Gas:National operators in Saudi Arabia, the UAE, and Nigeria drive specification standards for high-pressure process gas duties. SFDA equipment certification and EU F-Gas analogs create dual compliance burdens that filter supplier participation.
- Manufacturing:Food-grade compressed air requirements under ISO 8573 Class 0 standards pull oil-free screw compressor demand from dairy and beverage processors in Egypt and Morocco. Pharmaceutical manufacturers in Saudi Arabia and the UAE face additional SFDA and MOHAP validation mandates.
- Automotive:Assembly plants and tier suppliers across South Africa and Morocco deploy rotary screw systems for paint shop and pneumatic tool applications.
- Construction:Mobile diesel-driven units serve infrastructure projects in Nigeria and Kenya where grid connectivity remains intermittent.
Oil and gas end-use commands the established base. The steepest expansion runs through manufacturing as food-grade and pharmaceutical air quality standards tighten.
Technology:
Electric drive penetration correlates with grid reliability and carbon intensity regulations, while diesel retains dominance in frontier exploration and remote construction.
- Electric:Fixed industrial installations in Saudi Arabia's Jubail and UAE's Ruwais petrochemical corridors favor grid-connected motors with variable frequency drives. European component concentration in high-speed drive supply chains exposes regional assemblers to extended lead times.
- Diesel:Self-contained power units serve Nigerian deepwater pre-salt development and East African construction camps beyond grid reach.
- Hybrid:Dual-power configurations emerge in Oman's Sohar Port industrial cluster where performance-based energy contracting structures favor operational flexibility.
- Pneumatic:Compressed air-driven actuation persists in hazardous area applications across Gulf upstream facilities where spark ignition risks mandate non-electrical alternatives.
Electric technology commands the established base. The steepest expansion runs through hybrid systems as energy-as-a-service contracting restructures procurement authority.
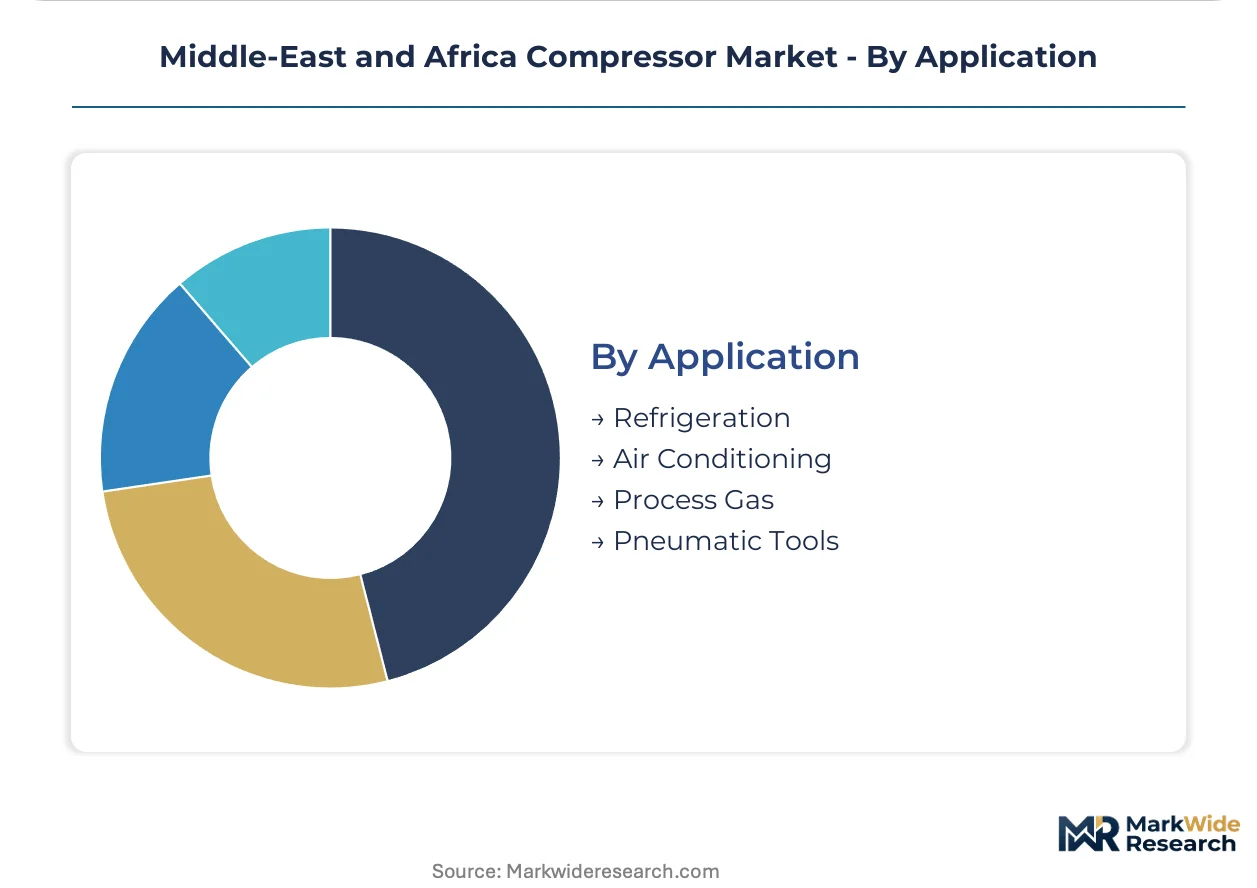
Application:
Process gas and refrigeration applications pull distinct compressor architectures, with pneumatic tools representing a fragmented maintenance-driven replacement market.
- Process Gas:Hydrocarbon handling and chemical synthesis duties specify materials traceability and sour gas compatibility. SFDA pharmaceutical guidelines and UAE MOHAP medical gas standards impose validation documentation requirements that delay equipment approval timelines.
- Refrigeration:Commercial cold chain infrastructure across the UAE faces retrofit mandates as environmental agencies adopt EU F-Gas Regulation analogs for refrigerant emission controls.
- Air Conditioning:Building climate control in Gulf commercial centers drives scroll and small rotary screw demand with seasonal load variation patterns.
- Pneumatic Tools:Construction and maintenance operations generate distributed demand for portable compressed air supply with limited premium pricing capture.
Process gas applications command the established base. The steepest expansion runs through refrigeration as regulatory retrofit cycles compress replacement timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement authority concentrates with national oil companies and petrochemical operators across the Gulf, while manufacturing demand fragments across North African industrial clusters.
Saudi Arabia
Saudi Aramco's gas injection programs and Jubail petrochemical expansions drive demand for high-pressure reciprocating and centrifugal units. SFDA pharmaceutical equipment guidelines mandate ISO 8573 Class 0 validation for sterile manufacturing air systems. Eastern Province industrial cities host the densest concentration of compressor deployments, with reliability-under-cyclic-loading specifications dominating sour gas service tenders.
United Arab Emirates
ADNOC's offshore enhanced recovery projects and Ruwais downstream complexes anchor capital-intensive centrifugal procurement. MOHAP medical gas standards and EU F-Gas Regulation analogs create dual compliance burdens for cold chain and healthcare applications. Dubai's Jebel Ali Free Zone manufacturing clusters favor rotary screw systems with energy-as-a-service contracting structures displacing traditional purchase models.
Nigeria
Deepwater pre-salt gas monetization projects generate demand for subsea compression infrastructure beyond current regional service network capacity. The country's national petroleum regulator enforces equipment traceability standards for hydrocarbon handling systems. Lagos and Port Harcourt industrial corridors concentrate manufacturing and construction demand for diesel-driven portable units where grid reliability remains intermittent.
South Africa
Automotive assembly plants and mining operations drive rotary screw and large-frame reciprocating demand across Gauteng and Eastern Cape industrial belts. The country's national standards body aligns equipment safety certification with ISO and IEC frameworks for cross-border trade compatibility. Cape Town's pharmaceutical manufacturing hub pulls oil-free compressor specifications as export-oriented facilities adopt European MDR documentation standards.
Egypt
Food-grade dairy and beverage processing expansion in the Nile Delta generates ISO 8573 Class 0 demand for oil-free screw compressors. Government industrial modernization programs subsidize energy efficiency retrofits in state-owned manufacturing facilities. Alexandria and Suez Canal Economic Zone clusters concentrate process gas applications where material traceability requirements filter supplier participation.
Middle-East and Africa Compressor Market Competitive Landscape
Player mix skews toward diversified industrial conglomerates with rotating equipment divisions alongside specialized compressor manufacturers. Market structure exhibits tiered concentration, with premium positions held by European-origin suppliers possessing established certification pathways and localized service networks. Two strategic archetypes dominate: integrated energy technology conglomerates competing on digital platform integration, and compressed air specialists anchoring positions through aftermarket service density. Competitive moves center on IKTVA and In-Country Value compliance through domestic assembly partnerships, plus predictive maintenance contract structures that capture recurring revenue.
Within the European-origin tier, Atlas Copco AB and Kaeser Kompressoren GmbH occupy positions defined by oil-free portfolio breadth and regional service network density respectively. Siemens AG represents the integrated conglomerate archetype, competing through plant automation platform integration rather than standalone compressor specifications. These three exemplify how certification pathway maturity and localized validation documentation capabilities filter market access in Gulf pharmaceutical and hydrocarbon applications.
| Leading Market Players |
|---|
| Atlas Copco AB |
| Kaeser Kompressoren GmbH |
| Mitsubishi Heavy Industries Ltd |
| Siemens AG |
| Aerzener Maschinenfabrik GmbH |
| Ingersoll Rand plc |
| Baker Hughes Co |
| General Electric Company |
| Trane Technologies PLC |
| Others |
Supply & Pricing Matrix
Twenty-six-week lead times for high-speed magnetic bearings from German suppliers concentrate pricing power with European-origin manufacturers serving Gulf petrochemical tenders. This inventory constraint anchors cost-plus contract structures indexed to nickel alloy spot markets, compressing margins for regional assemblers unable to backward-integrate into critical component production.
Pricing Analysis
Cost-plus contracts with London Metal Exchange nickel indexation dominate LNG train procurement, insulating centrifugal compressor manufacturers from alloy price volatility while transferring risk to national oil company buyers. Price differentiation rests on ISO 8573 Class 0 certification tier and after-sales service bundling density. Cost compression in standard rotary screw tiers is intensifying because Egyptian and Moroccan dairy processors prioritize capital expenditure minimization over energy efficiency premiums. Manufacturing clusters in North Africa exhibit highest price sensitivity, whereas Saudi Aramco sour gas service tenders tolerate premium positioning for demonstrated reliability-under-cyclic-loading performance.
Supply Chain Analysis
Germany and Switzerland anchor high-speed magnetic bearing and variable frequency drive production, feeding assembly operations in Saudi Arabia's Jubail Industrial City and UAE's Ruwais complex. Regional manufacturing draws from duplex stainless steel mills in Italy and nickel-based superalloy foundries in the United States. Single-source vulnerability concentrates in magnetic bearing controllers, where Swiss suppliers command exclusive intellectual property positions. Distribution runs through national oil company procurement portals and energy service company aggregators serving Dubai's Jebel Ali Free Zone manufacturing tenants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in upstream oil and gas capital expenditure recovery, with Saudi Aramco and ADNOC gas injection programs providing cyclical lift through enhanced recovery deployment cycles.
For Market Incumbents: Consolidate service network density in Saudi Arabia's Eastern Province and UAE's Ruwais corridor to defend against emerging Chinese compressor manufacturers bidding on IKTVA-compliant tenders. Anchor positions through predictive maintenance contract structures that capture recurring revenue streams from national oil company reliability-focused procurement teams. For New Entrants and Emerging Players: Differentiate on subsea compression service capabilities for Nigeria's pre-salt deepwater developments, where regional incumbent coverage remains sparse. Target Egyptian food-grade dairy processing expansion with oil-free screw compressor offerings priced below European-origin alternatives. Pursue energy-as-a-service contracting structures with Oman's Sohar Port industrial cluster to bypass capital purchase approval bottlenecks. For Investors and Strategic Acquirers: Long-term, this sits as a cyclical infrastructure play because Gulf petrochemical capacity additions and African gas monetization projects provide sustained demand visibility across decade-long investment horizons. Acquire regional aftermarket service specialists with established SFDA validation documentation capabilities. Watch magnetic bearing technology adoption rates in Jubail and Ruwais as inflection indicator for centrifugal compressor segment restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| IKTVA Domestic Assembly Partnership | Saudi Aramco procurement preferences shift toward local content-compliant suppliers. |
| Predictive Maintenance Contract Launch | Energy service companies in Dubai's Jebel Ali capture recurring revenue from manufacturing tenants. |
| ISO 8573 Class 0 Certification Investment | SFDA pharmaceutical guidelines mandate oil-free compressor validation for sterile fill-finish operations. |
| Subsea Compression Service Network Buildout | Nigeria deepwater pre-salt projects require infrastructure beyond current regional service capacity. |
| Magnetic Bearing Technology Integration | Petrochemical complexes in Jubail specify direct-drive configurations eliminating oil lubrication systems. |
Research Methodology
Initial hypotheses were tested against primary input from maintenance directors at Saudi Aramco offshore facilities, plant engineers in UAE petrochemical complexes, aftermarket service heads at European compressor manufacturers, and procurement leads at Egyptian dairy processors, then refined against customs trade data, SEC filings from listed industrial conglomerates, IEA energy infrastructure investment databases, and Gulf national oil company tender announcements. Bottom-up equipment deployment counts triangulated with top-down energy sector capital expenditure allocations.
Variance decomposition across product type, end-use industry, technology configuration, and regional regulatory cluster dimensions shaped the analytical framework over the projection horizon. CAGRs derived from segment-level deployment trajectories and replacement cycle compression effects, with specific inputs including SFDA pharmaceutical equipment guideline implementation timelines and EU F-Gas Regulation analog adoption rates across UAE environmental agencies.
Decision-makers should treat outputs as directional under sustained oil and gas capital expenditure commitment and stable nickel alloy input cost assumptions; material deviation in hydrocarbon price environments or supply chain disruption severity would warrant model refresh. Recalibration cycles align with material shifts in Gulf national oil company procurement policy and regional environmental regulation harmonization progress.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Duct Fans Market
HVAC Equipment
Dedicated Outdoor Air System Market
HVAC Equipment
Residential Furnaces Market
HVAC Equipment
Automatic Ducting Machine Market
HVAC Equipment
United Kingdom District Heating Market
HVAC Equipment
Germany Heat Pump Market
HVAC Equipment
Global Commercial Heat Pump Water Heater Market
HVAC Equipment
United Kingdom Heat Pumps Market
HVAC Equipment
Refrigeration and Air Conditioning Compressors Market
HVAC Equipment
Combustion Controls, Equipments and Systems Market
HVAC Equipment
Industrial Electric Boiler Market
HVAC Equipment
Air Humidifier and Dehumidifier Market
HVAC Equipment
Industrial Refrigeration Equipment Market
HVAC Equipment
Foamer Pump Market
HVAC Equipment
Global HVAC Filter Market
HVAC Equipment
Compressor Controllers Market