
 Utility and Industrial Boilers Market | 2026-2036
Utility and Industrial Boilers Market Size, Share, and Industry Trends Forecast 2026-2036
Utility and Industrial Boilers Market Analytics
Performance-based maintenance contracts and digital monitoring subscriptions is realigning how boiler vendors capture lifetime value from capital equipment. Mitsubishi Heavy Industries leverages its integrated turbine-boiler technology platform to sustain premium positioning in ultra-supercritical installations. Babcock & Wilcox Enterprises anchors its competitive stance through specialized waste-to-energy and biomass boiler engineering for North American utilities.
Utility and industrial boilers are pressurized vessels designed to generate steam or hot water through combustion, electric resistance, or heat recovery, typically operating at pressures from 15 psi to over 3,200 psi and temperatures exceeding 1,000°F for power generation and process heating applications. Water-tube configurations dominate utility-scale installations due to higher pressure tolerance and thermal efficiency, while modular electric boilers are gaining traction in distributed industrial heat applications where grid decarbonization progresses fastest. Natural gas retains the largest fuel-type share among new installations, though biomass and hydrogen-ready designs are capturing growing engineering attention as utilities navigate fuel diversification requirements.
EPA emissions rules under the Clean Air Act, EU Green Deal industrial decarbonization frameworks, and China's MEE air quality standards collectively tighten allowable NOx, SOx, and particulate outputs, forcing boiler upgrades or retirements across major economies. Compliance timelines vary by jurisdiction, creating uneven replacement cycles that favor vendors with multi-certification capabilities. Stakeholders must monitor hydrogen blending infrastructure readiness and carbon border adjustment mechanisms to anticipate which boiler technologies will retain investability.
Market Dynamics
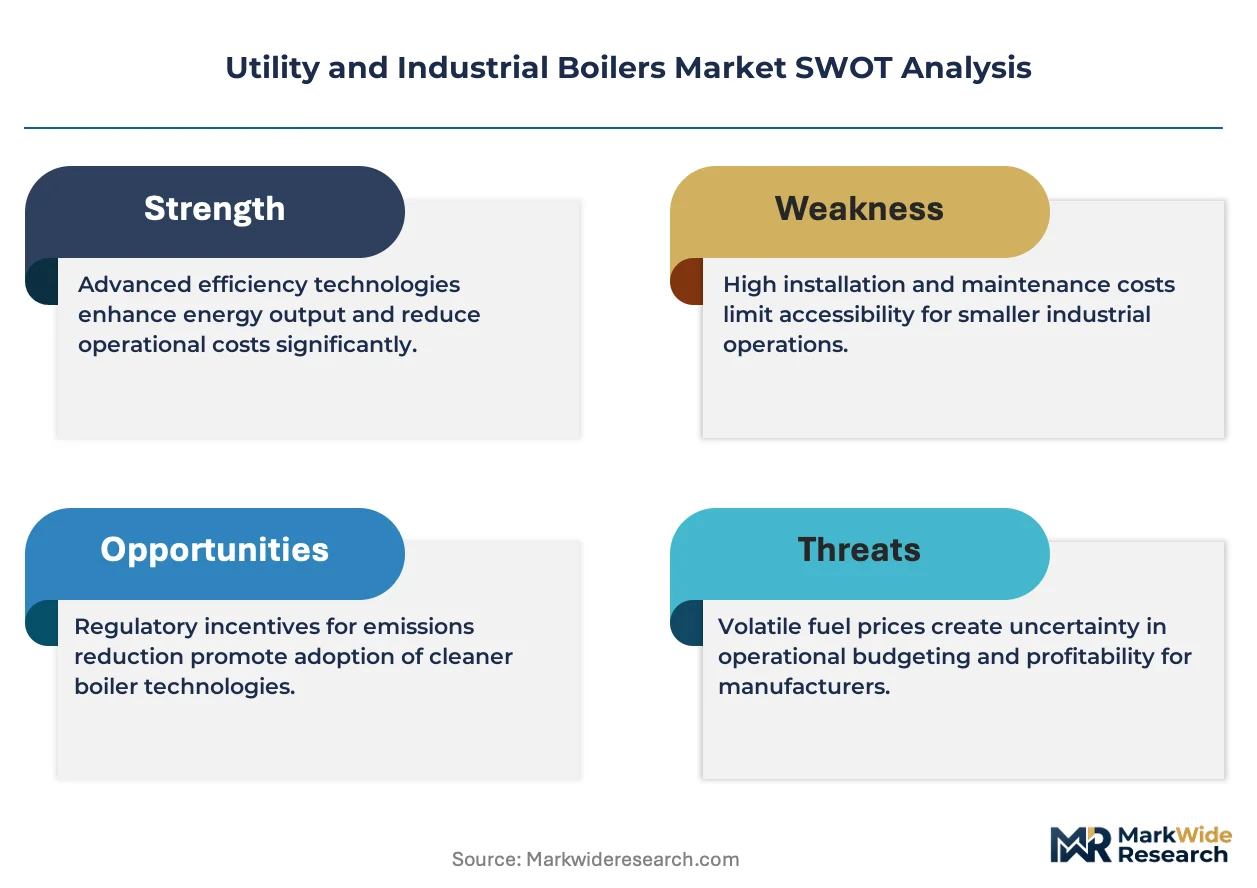
Fuel-switching mandates from EPA, EU Green Deal, and China's MEE are forcing simultaneous boiler fleet modernization and hydrogen-ready engineering investments across utility procurement cycles.
Growth Catalysts
- Ultra-supercritical steam parameters:Higher thermal efficiency thresholds above 600°C/620°C reduce coal consumption per MWh, attracting state-owned generators in China and India facing carbon intensity targets.
- EU Green Deal industrial decarbonization frameworks:Binding emissions reduction pathways for 2030 and 2050 accelerate biomass and hydrogen-ready boiler tenders among European chemical and district heating utilities.
- India's PLI scheme for clean energy components:Domestic manufacturing incentives lower landed costs for advanced boiler pressure parts, supporting fleet expansion by NTPC and state electricity boards.
Market Restraints
- Specialized alloy supply concentration:Superalloy forgings for ultra-supercritical headers and steam pipes concentrate among Japanese and German specialty steel producers, creating single-source vulnerability.
- Extended EPA compliance timelines:Staggered NOx and SOx reduction deadlines under the Clean Air Act create demand lumpiness that strains vendor capacity planning and margin stability.
- Electrification of low-temperature heat:Heat pumps and electric resistance systems displace sub-150 psi industrial boilers in food processing and textiles below 400°F operating thresholds.
Strategic Opportunities
- Hydrogen blending infrastructure readiness gaps:First-mover engineering for 30% hydrogen co-firing capability positions vendors for German and Dutch utility tenders ahead of pipeline network completion.
- Waste-to-energy regulatory tailwinds:EU landfill diversion mandates and circular economy action plans expand addressable market for grate combustion and fluidized bed boiler configurations.
- Digital twin convergence with predictive maintenance:Integration of physics-based modeling with IoT sensor networks creates recurring revenue streams from performance guarantees and availability contracts.
Industry Challenges
- Welding and metallurgical specialist scarcity:Qualified technicians for P91/P92 steel joining and post-weld heat treatment are retiring faster than apprenticeship programs replenish bench strength.
- Multi-jurisdiction certification complexity:ASME Section I, EN 12952, and GB standards divergence forces redundant design validation and extended factory acceptance testing for global vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Utility and Industrial Boilers Market |
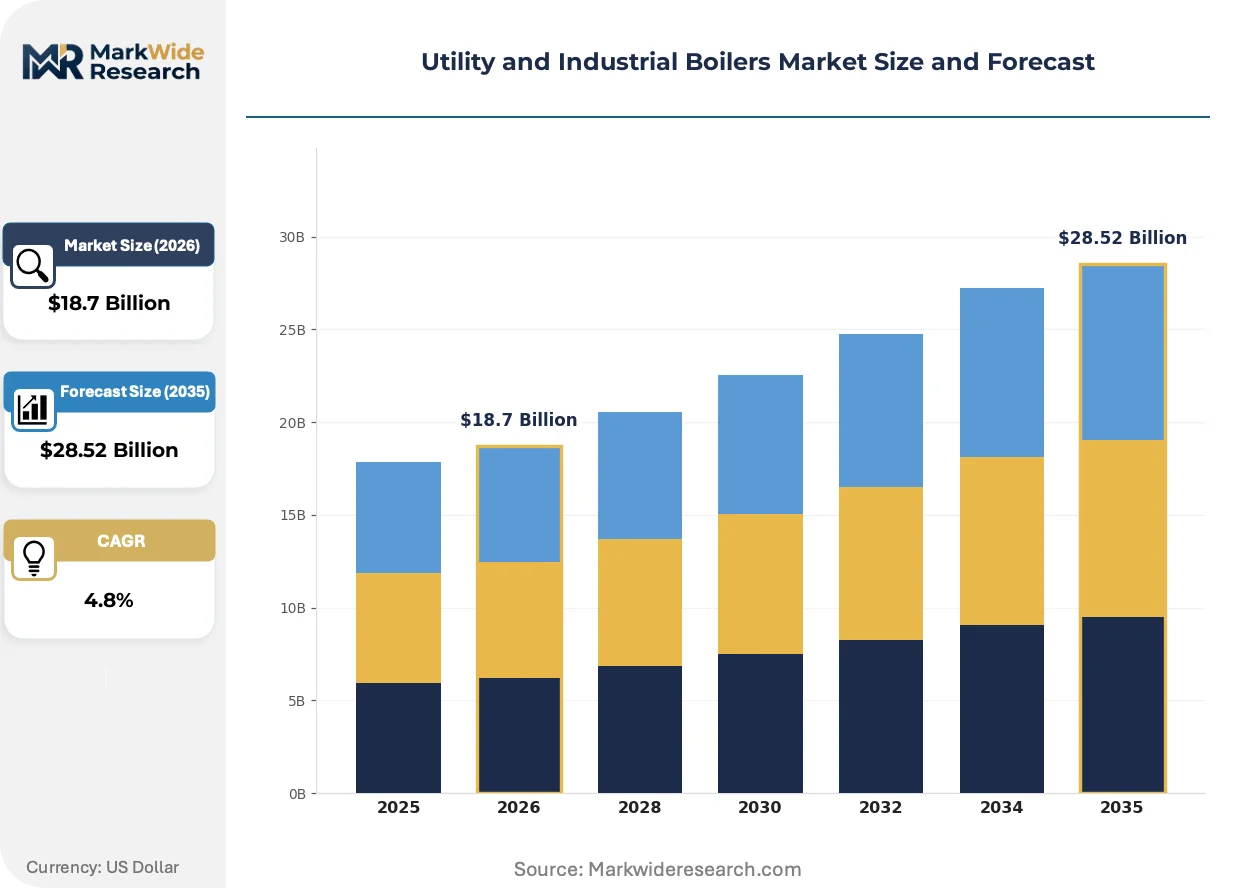
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fire-Tube, Water-Tube, Electric, Modular Fuel Type: Natural Gas, Oil, Biomass, Coal End User: Manufacturing, Power Generation, Chemical, Food & Beverage Installation Type: Onshore, Offshore, Under-Construction, Retrofit |
| Companies Covered | Mitsubishi Heavy Industries, Babcock & Wilcox Enterprises, Bosch Industriekessel, Thermax, Cleaver-Brooks, Siemens, Dongfang Electric Corporation, Wood Group, Viessmann Climate Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Utility and Industrial Boilers Market Evolving Landscape
Boiler technology trajectories center on thermal efficiency gains, fuel flexibility engineering, and digital integration that restructures how vendors monetize equipment lifecycles.
Modular electric boiler arrays are decentralizing industrial heat supply architectures. Food processors and pharmaceutical manufacturers in Denmark and Sweden deploy containerized 10-50 MW electric units to bypass combustion permitting and align with 24/7 renewable power contracting. This topology compresses project development timelines from 36 months to 12 months and fragments procurement authority from central engineering to site operations managers.
China's MEE air quality standards tighten particulate and mercury emissions thresholds for coal-fired units above 300 MW. Boiler operators must retrofit electrostatic precipitators with wet flue gas desulfurization or face dispatch curtailment. Northern Chinese provinces with the heaviest industrial concentration bear disproportionate compliance costs, accelerating consolidation among provincial power generation groups.
Long-term service agreements now unbundle from equipment supply contracts. European district heating utilities negotiate 15-year availability guarantees covering spare parts, remote monitoring, and major overhauls as separate commercial instruments. This bifurcation shifts vendor cash flow profiles toward recurring revenue and demands new balance sheet structures for performance risk underwriting, most visible in German and Finnish municipal energy company tenders.
Utility and Industrial Boilers Market Segmentation
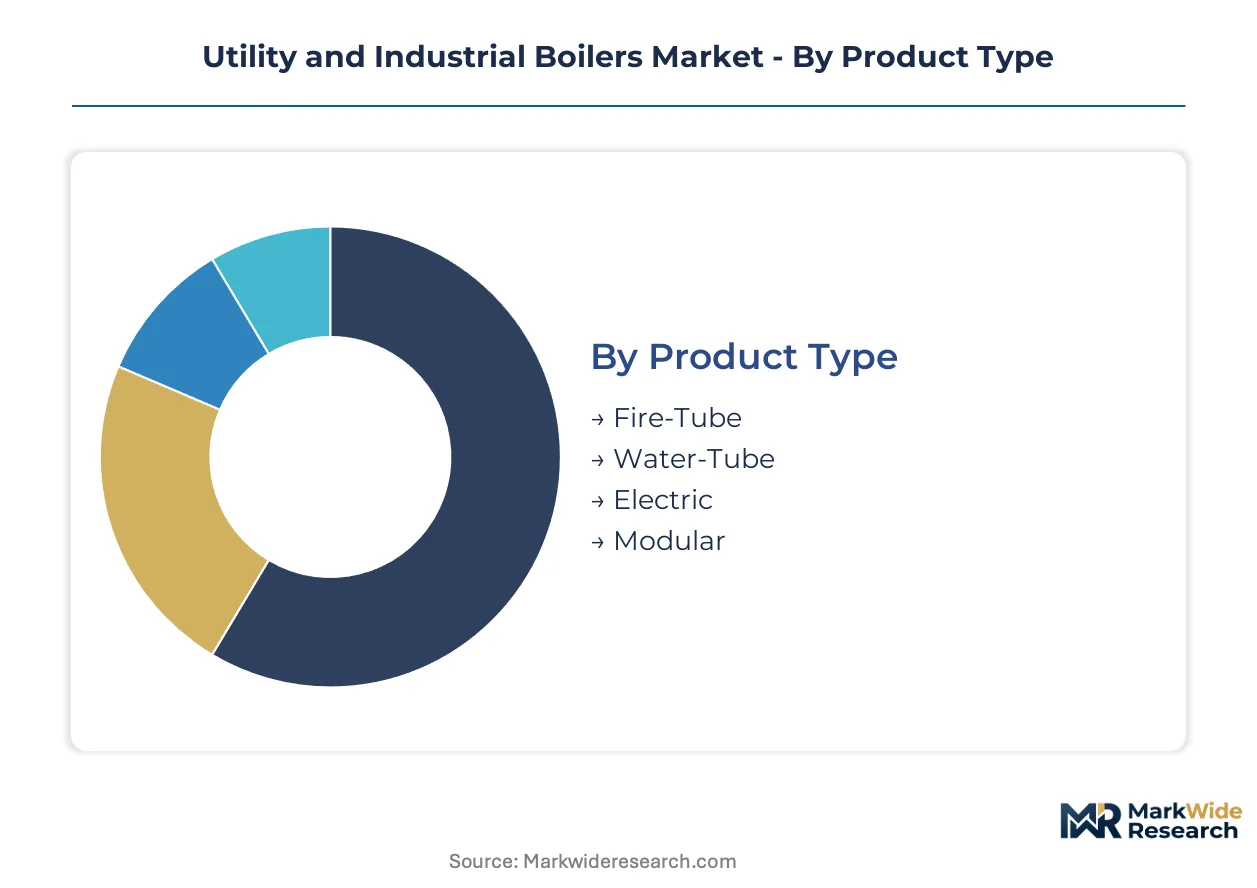
Boiler procurement patterns diverge sharply across technical configurations, fuel pathways, and installation contexts. Vendors must align engineering capabilities with segment-specific certification requirements and lifecycle service expectations to capture value.
Product Type:
Supply concentration for high-pressure components concentrates engineering margins in water-tube configurations, while modular and electric variants fragment procurement authority toward site-level operations managers.
- Water-Tube:Configurations circulate water through tubes heated externally by combustion gases, enabling pressure tolerance above 3,200 psi. State-owned generators in China and India specify these for ultra-supercritical installations where thermal efficiency thresholds exceed 600°C, driven by carbon intensity compliance mandates from China's MEE.
- Fire-Tube:Designs pass combustion gases through tubes submerged in water, suited for saturated steam applications below 300 psi. Manufacturing facilities in Germany and the Netherlands specify these for process heating below 400°F, constrained by electrification displacement from heat pump alternatives.
- Electric:Resistance or electrode configurations eliminate combustion permitting complexity. Food processors in Denmark deploy containerized 10-50 MW arrays to align with 24/7 renewable power contracting.
- Modular:Containerized or skid-mounted units compress project timelines from 36 months to 12 months. Pharmaceutical manufacturers in Sweden bypass centralized engineering procurement for distributed heat supply architectures.
Today's leader: Water-Tube. Tomorrow's challenger: Modular.
Fuel Type:
Cost tier stratification separates premium hydrogen-ready engineering from standard natural gas configurations, with biomass and coal occupying divergent regulatory trajectories.
- Natural Gas:Retains the largest share among new installations due to infrastructure maturity and combustion control precision. North American utilities specify these for NOx compliance under EPA Clean Air Act timelines, though hydrogen blending retrofit costs now factor into total cost of ownership calculations.
- Biomass:Grate combustion and fluidized bed configurations convert agricultural residues and wood pellets to process heat. EU district heating utilities in Finland and Austria tender these under Green Deal binding emissions pathways, expanding most quickly among fuel-switching investments.
- Coal:Pulverized fuel and circulating fluidized bed designs face dispatch curtailment under China's MEE air quality standards for units above 300 MW. Northern Chinese provinces bear disproportionate retrofit costs for wet flue gas desulfurization.
- Oil:Residual and distillate configurations persist in backup power and remote industrial applications where pipeline gas infrastructure remains underdeveloped. Marine and islanded manufacturing clusters in Southeast Asia specify these for fuel security.
Natural Gas dominates current procurement volumes. Biomass gains share fastest where EU landfill diversion mandates and circular economy frameworks apply.
End User:
Application-specific operating regimes dictate pressure, temperature, and redundancy specifications that fragment vendor specialization across verticals.
- Power Generation:Utilities require baseload availability above 90% with supercritical steam parameters. NTPC and Indian state electricity boards expand fleets under PLI scheme domestic manufacturing incentives for pressure parts.
- Chemical:Process steam demands span 150-1,500 psi with precise temperature control for catalytic reactions. German chemical parks tender hydrogen-ready configurations under Green Deal industrial decarbonization frameworks.
- Manufacturing:General industrial heat applications face electrification pressure below 400°F thresholds. Textile processors in South Korea displace sub-150 psi boilers with heat pumps where grid decarbonization progresses.
- Food & Beverage:Sanitary steam requirements drive stainless steel construction and clean-in-place compatibility. Containerized electric arrays gain traction in Nordic markets for bypassing combustion permitting.
Power Generation commands the highest unit values. Chemical represents the steepest expansion trajectory for hydrogen-ready engineering.
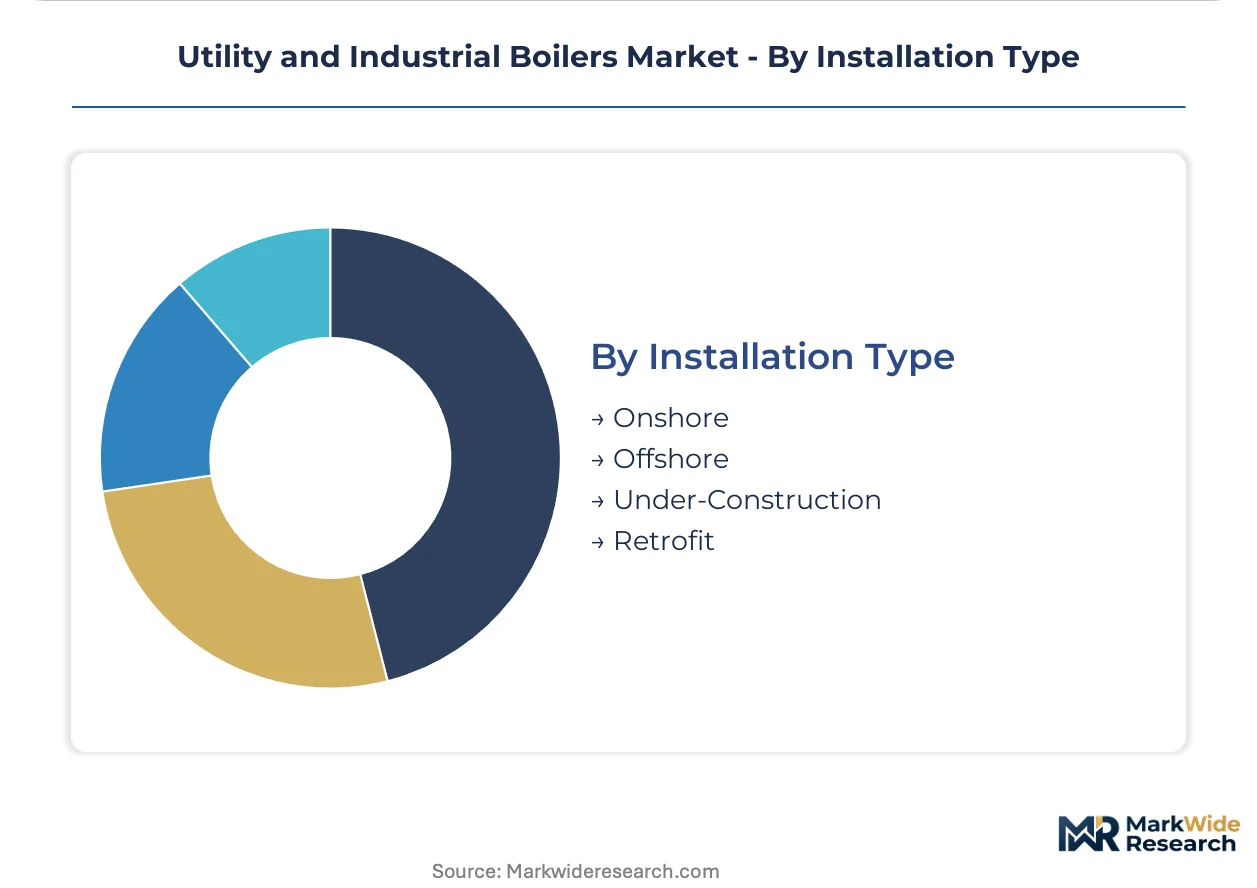
Installation Type:
Customer type bifurcation separates greenfield utility procurement from industrial retrofit urgency driven by compliance deadlines.
- Retrofit:Existing vessel modifications incorporate low-NOx burners, flue gas recirculation, and emissions control retrofits. US utilities stagger investments across EPA Clean Air Act compliance timelines, creating demand lumpiness.
- Onshore:New ground-mounted installations at industrial facilities and power plants follow ASME Section I, EN 12952, or GB standards validation protocols. Multi-jurisdiction certification complexity extends factory acceptance testing for global vendors.
- Under-Construction:Greenfield projects integrate boilers with turbine islands and emissions control systems. Ultra-supercritical installations in China and India concentrate demand for P91/P92 superalloy forgings from Japanese and German specialty steel producers.
- Offshore:Platform and FPSO configurations require compact, high-reliability designs with marine certification. North Sea oil and gas operators specify these for process heat and power generation in remote environments.
Retrofit absorbs current vendor capacity. Under-Construction offers the highest engineering margins for integrated turbine-boiler platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping boiler procurement geography as compliance cost differentials widen between jurisdictions. Manufacturing investment migrates toward markets with domestic content incentives and extended compliance timelines.
China
State-owned generators NTPC and regional power groups drive ultra-supercritical fleet expansion under MEE air quality standards. Northern provinces including Hebei and Shanxi bear disproportionate retrofit costs for wet flue gas desulfurization on coal units above 300 MW. Yangtze River Delta manufacturing clusters concentrate pressure parts fabrication under PLI-equivalent domestic manufacturing incentives.
India
NTPC and state electricity boards expand boiler procurement under the PLI scheme for clean energy components, lowering landed costs for advanced pressure parts. CEA mandates tighten emissions thresholds for thermal units, accelerating fleet modernization in coal-dependent states. Western industrial corridors in Gujarat and Maharashtra concentrate chemical and textile boiler demand facing electrification pressure below 400°F thresholds.
Germany
EU Green Deal industrial decarbonization frameworks bind chemical parks and district heating utilities to 2030 emissions pathways. Hydrogen-ready boiler tenders accelerate in the Rhine-Ruhr and Bavarian industrial clusters ahead of pipeline network completion. KBA-equivalent certification bodies enforce EN 12952 standards validation for multi-jurisdiction vendors.
United States
EPA Clean Air Act NOx and SOx reduction timelines create staggered replacement cycles across utility territories. Southeast manufacturing renaissance in Georgia and Tennessee attracts modular electric boiler deployments for food processing bypassing combustion permitting. FERC grid interconnection queues slow greenfield power generation projects, extending retrofit demand visibility.
Netherlands
EU landfill diversion mandates and circular economy action plans expand waste-to-energy boiler tenders for grate combustion configurations. Rotterdam and Eindhoven industrial zones pilot 30% hydrogen co-firing ahead of national blending infrastructure completion. Dutch utilities negotiate 15-year availability guarantees unbundled from equipment supply contracts.
Utility and Industrial Boilers Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated turbine-boiler platforms commanding premium positioning in utility-scale procurement while modular fabricators capture distributed industrial applications. Market structure concentrates engineering margins among Japanese and German superalloy forging specialists, fragmenting procurement authority toward site-level operations managers for electric and modular configurations. Three archetypes dominate: ultra-supercritical system integrators, waste-to-energy engineering specialists, and containerized electric boiler fabricators. Competitive moves center on hydrogen-ready engineering certification and long-term service agreement unbundling from equipment supply.
Within the integrated system tier, Mitsubishi Heavy Industries and Siemens exemplify turbine-boiler platform positioning, while Babcock & Wilcox Enterprises occupies a specialized engineering position in waste-to-energy configurations. Among Asian fabricators, Dongfang Electric Corporation and Thermax represent scale-driven boiler pressure parts production. These named entities anchor archetype segmentation without constraining the full competitive set.
| Leading Market Players |
|---|
| Mitsubishi Heavy Industries |
| Babcock & Wilcox Enterprises |
| Bosch Industriekessel |
| Thermax |
| Cleaver-Brooks |
| Siemens |
| Dongfang Electric Corporation |
| Wood Group |
| Viessmann Climate Solutions |
| Others |
Value Network & Pricing Analysis
EU Green Deal industrial decarbonization frameworks gate qualified supply for hydrogen-ready boiler configurations and premium-tier pricing access, as vendors must recover EN 12952 certification investments and P91/P92 superalloy procurement costs through differentiated engineering margins.
Pricing Analysis
Capacity additions in India under the PLI scheme for clean energy components are reshaping price floors for standard pressure parts while premium ultra-supercritical installations retain three-tier pricing stratification across ASME-certified, EN-compliant, and economy-grade fabricators. Price differentiation hinges on certification tier and after-sales bundling, with European district heating utilities negotiating 15-year availability guarantees as separate commercial instruments. Cost compression in fire-tube and sub-150 psi segments is intensifying because heat pumps displace low-temperature applications. Chemical processors in Germany exhibit lowest price sensitivity due to hydrogen-ready engineering mandates, while textile manufacturers in South Korea face acute margin pressure from electrification alternatives.
Supply Chain Analysis
Dual-sourcing requirements from NTPC and Chinese state-owned generators mandate multi-supplier qualification for superalloy forgings, forcing redundant ASME Section I and GB standards validation. Geographic supply concentration centers on Japan, Germany, and China for P91/P92 headers, with Yangtze River Delta clusters fabricating standard pressure parts. Raw material dependencies draw from nickel-based superalloys, high-grade carbon steel, and specialized welding consumables. Single-source vulnerability concentrates among Japanese and German specialty steel producers for ultra-supercritical steam pipes. Distribution runs through EPC contractors and direct utility procurement channels with extended factory acceptance testing timelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Utility and Industrial Boilers Market functions as a regulatory compounder where EPA Clean Air Act compliance timelines and EU Green Deal binding emissions pathways generate sustained replacement demand across staggered procurement cycles.
For Market Incumbents: Deepen backward integration into P91/P92 superalloy forging partnerships to secure supply continuity against Japanese and German single-source concentration, while expanding digital twin-enabled predictive maintenance subscriptions to capture recurring revenue from European district heating utilities. Hydrogen-ready engineering certification investments defend margin position against modular electric boiler entrants in Nordic food processing applications. For New Entrants and Emerging Players: Enter via containerized electric boiler fabrication for pharmaceutical and food processing segments in Denmark and Sweden, where 24/7 renewable power contracting bypasses combustion permitting complexity. Target modular 10-50 MW arrays for distributed heat supply architectures that fragment procurement authority from central engineering to site operations managers. Channel partnerships with renewable energy developers accelerate customer acquisition in grid-decarbonized industrial clusters. For Investors and Strategic Acquirers: Roll-up economics work for specialized waste-to-energy engineering firms because EU landfill diversion mandates and circular economy action plans expand addressable market for grate combustion configurations with limited vendor depth. Long-term viability over the next decade hinges on hydrogen blending infrastructure readiness and carbon border adjustment mechanism implementation. Monitor German and Dutch utility tender specifications for 30% hydrogen co-firing capability as the inflection indicator for premium engineering investability.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen-Ready Engineering Certification | Positions vendors for German and Dutch utility tenders ahead of pipeline network completion. |
| Digital Twin Platform Integration | Creates recurring revenue streams from 15-year availability guarantees with Finnish municipal energy companies. |
| Backward Integration into Superalloy Supply | Mitigates single-source vulnerability from Japanese and German specialty steel producers. |
| Long-Term Service Agreement Unbundling | Shifts vendor cash flow profiles toward performance-based maintenance subscriptions. |
| Modular Electric Boiler Capacity Expansion | Captures distributed industrial heat demand from pharmaceutical manufacturers in Sweden. |
Research Methodology
Coverage spans China, India, Germany, the United States, and the Netherlands, with primary inputs from each market combining interviews with utility planning officers, EPC contractors, plant engineers, and aftermarket service heads alongside secondary validation from EIA data, IEA reports, FERC filings, and project development databases. Bottom-up and top-down triangulation reconciles procurement volume estimates with installed capacity assessments.
Granularity-level modeling disaggregates the analysis window across water-tube, fire-tube, electric, and modular product configurations; natural gas, biomass, coal, and oil fuel pathways; power generation, chemical, manufacturing, and food and beverage end users; and retrofit, onshore, under-construction, and offshore installation contexts. CAGRs derive from segment-level volume trajectories and value-per-unit engineering assessments, incorporating ultra-supercritical steam parameter adoption curves and hydrogen blending infrastructure readiness timelines as industry-specific forecast inputs.
Inputs from utility procurement databases and EPC contract registries were available through the study window; gaps in real-time hydrogen pipeline construction progress introduce uncertainty bands around hydrogen-ready boiler demand timing. Forecasts reflect assumptions regarding EPA compliance timeline adherence and EU Green Deal implementation pace; deviation in China's MEE enforcement intensity or India's PLI scheme extension would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Modular Refrigeration Unit Market
HVAC Equipment
Asia Pacific Commercial HVAC Market
HVAC Equipment
China HVAC Field Device Market
HVAC Equipment
South America Screw Compressor Market
HVAC Equipment
Automatic Ducting Machine Market
HVAC Equipment
Europe HVAC Equipment Market
HVAC Equipment
Compressor Market
HVAC Equipment
Variable Air Volume Box Market
HVAC Equipment
Equipment for HVAC Market
HVAC Equipment
US HVAC Field Device Market
HVAC Equipment
United States Air Conditioning Equipment Market
HVAC Equipment
Global HVAC Packaged Unit Market
HVAC Equipment
HVAC Air Quality Monitoring Market
HVAC Equipment
North America Industrial Air Chiller Market
HVAC Equipment
HVAC Centrifugal Compressors Market
HVAC Equipment
Global Tubular Heating Elements Market