
 Commercial Refrigeration Compressor Market | 2026-2036
Commercial Refrigeration Compressor Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Refrigeration Compressor Market Intelligence
The phasedown of high global warming potential (GWP) refrigerants under the EU's F-Gas Regulation and similar mandates in the United States is rebalancing demand toward energy-efficient compressor technologies. Danfoss A/S leverages its extensive portfolio of CO2 and hydrocarbon-compatible compressors to capture this shift. Emerson Electric Co. competes on the strength of its scroll technology and digital controls integration. Bitzer SE sustains its market position through specialization in semi-hermetic reciprocating and screw compressors for large-scale industrial applications.
A commercial refrigeration compressor is a mechanical device that increases the pressure of a refrigerant vapor within a closed-loop cooling cycle. These units are engineered for high duty cycles and variable load conditions found in commercial environments. The primary function is to circulate the refrigerant, enabling heat transfer from an insulated space to the external environment. Scroll compressors continue to gain share over traditional reciprocating models due to higher efficiency and fewer moving parts. Supermarket refrigeration remains the largest application, while demand from cold storage warehousing is expanding quickly.
Product design and market access are shaped by efficiency standards from the U.S. Department of Energy (DOE) and ecodesign requirements under the European Commission. Additionally, safety standards like ISO 5149 govern the use of flammable or high-pressure natural refrigerants. These regulations compel manufacturers to innovate in both performance and material compatibility. Future investment decisions for original equipment manufacturers will hinge on navigating the trade-offs between refrigerant choice, system efficiency, and overall component cost.
Market Dynamics
The primary structural force shaping the market is the regulatory-mandated transition away from high-GWP hydrofluorocarbons. This shift compels innovation in compressor design to accommodate natural refrigerants like CO2 and propane, reordering technology preferences and supply chains.
Growth Catalysts
- Cold Chain Expansion:The build-out of refrigerated logistics in China and India creates sustained demand for compressors in warehousing and transport refrigeration.
- Regulatory Mandates:The EU's F-Gas Regulation and parallel EPA actions in the United States are accelerating the transition to low-GWP refrigerant-compatible compressors.
- Efficiency Standards:U.S. Department of Energy requirements push OEMs to adopt advanced scroll and variable-speed technologies, driving replacement sales.
Market Restraints
- Component Cost:Systems for natural refrigerants like CO2 and propane have higher initial capital costs due to specialized, high-pressure components.
- Technical Barriers:The flammability of propane and high pressures of CO2 require specialized technician training and strict safety protocols, slowing adoption.
- Supply Chain Bottlenecks:A limited supplier base for critical components like electronic expansion valves for CO2 systems creates production constraints for OEMs.
Strategic Opportunities
- Service and Aftermarket:Offering diagnostic tools and training programs for technicians working with natural refrigerants represents a significant service revenue opportunity.
- Technology Convergence:Integrating IoT connectivity with compressor controls enables predictive maintenance services and optimized energy management for end-users.
- Emerging Applications:Growth in last-mile grocery delivery creates demand for small-format, high-efficiency compressors in urban fulfillment centers.
Industry Challenges
- Technician Skill Gap:A widespread shortage of technicians certified to install and service systems using flammable or high-pressure natural refrigerants acts as a bottleneck.
- Compliance Complexity:Manufacturers must navigate divergent refrigerant phasedown timelines and efficiency standards between the EU, the US, and individual states like California.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Refrigeration Compressor Market |
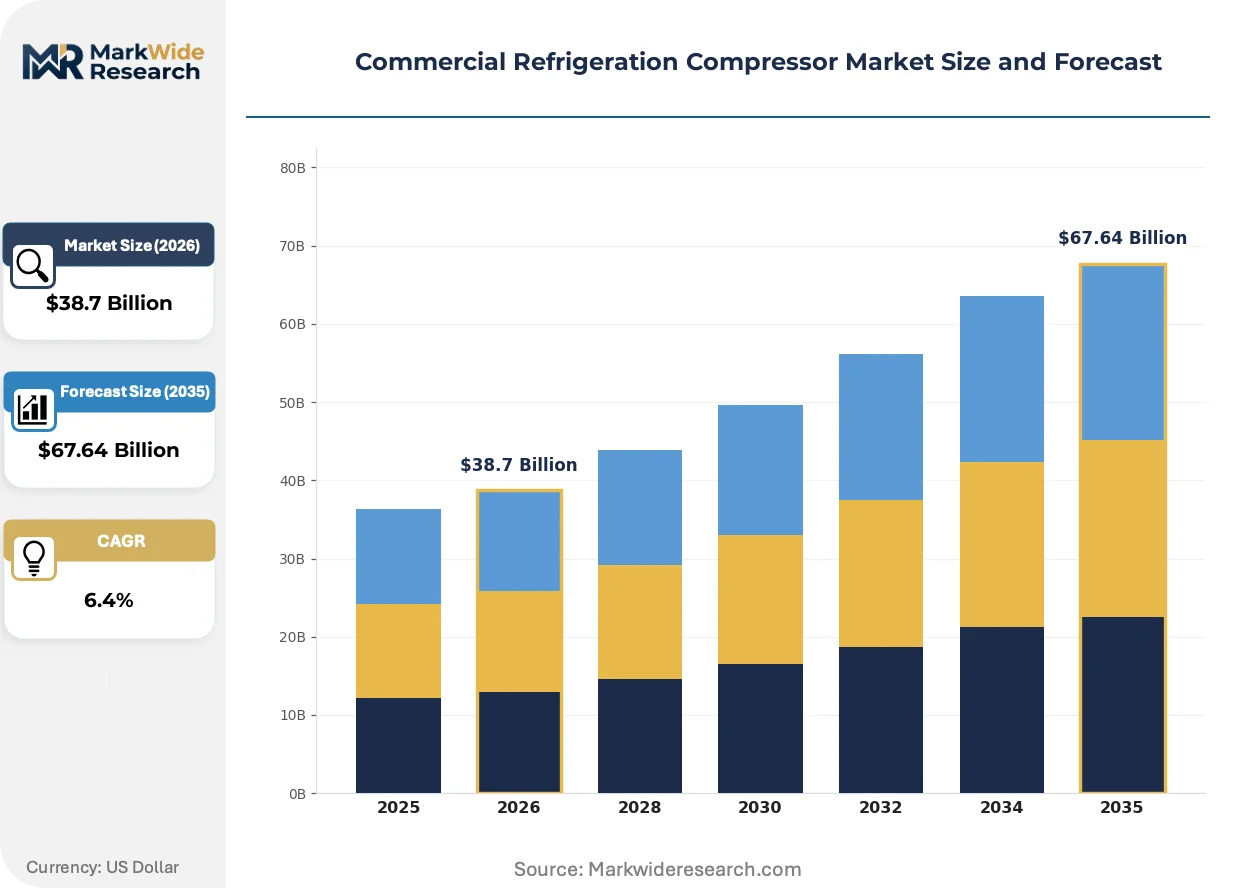
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $67.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reciprocating, Scroll, Screw, Centrifugal Technology: Hermetic, Semi-Hermetic, Open Drive, Magnetic Bearing Application: Supermarket Refrigeration, Cold Storage, Food Processing, Beverage Cooling End User: Retail Chains, Food Service Providers, Warehousing Firms, Hospitality Operators |
| Companies Covered | Danfoss A/S, Panasonic Corporation, Emerson Electric Co., Johnson Controls International plc, Bitzer SE, Mitsubishi Electric Corporation, LG Electronics, GEA Group AG, Carrier Global Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Refrigeration Compressor Market Strategic Shifts & Innovations
The convergence of sustainability mandates and digitalization is reshaping compressor design and application. This dual pressure is forcing manufacturers to innovate simultaneously on refrigerant compatibility and intelligent system controls for enhanced operational efficiency.
Variable speed drive (VSD) technology allows a compressor to modulate its motor speed, precisely matching cooling capacity to real-time demand. Supermarkets and cold storage facilities are rapidly adopting VSDs to reduce significant energy expenditures. This technology is absorbing the market share of less efficient fixed-speed and mechanical unloading compressors in new and retrofit projects.
Phasedowns of hydrofluorocarbons (HFCs) under the US EPA's AIM Act and the EU's F-Gas Regulation are a primary market driver. This industrial consequence compels OEMs to re-engineer product lines for natural refrigerants like CO2 and propane. The food service equipment segment is most affected, redesigning systems to meet new GWP limits and safety standards like ISO 5149.
Evaluation criteria for new equipment are shifting from upfront capital cost to a total cost of ownership (TCO) model. This change disrupts the traditional sales process that prioritized the lowest initial price, favoring suppliers who can quantify long-term energy savings. The trend is most visible within large supermarket chains in Europe and North America, where energy is a major operational expense.
Commercial Refrigeration Compressor Market Segmentation
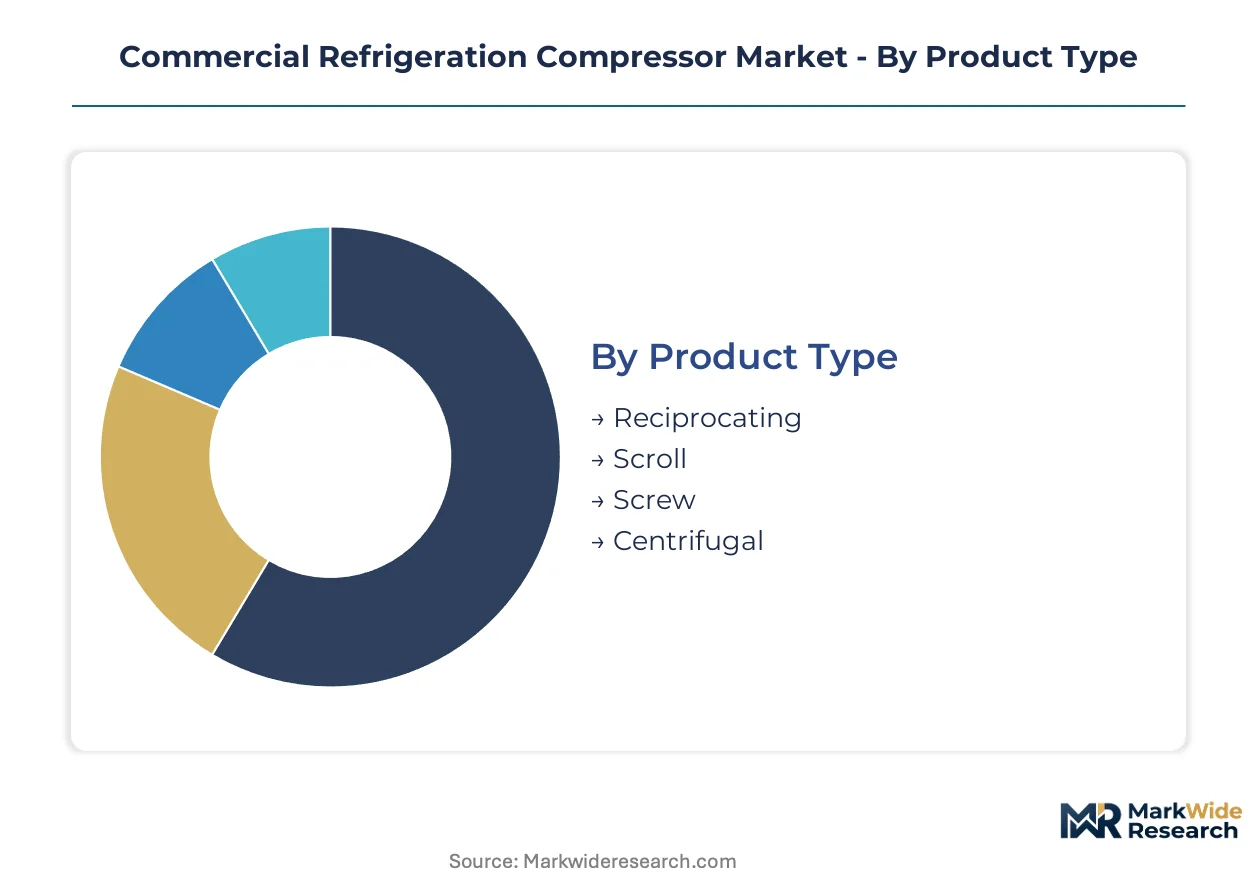
The Commercial Refrigeration Compressor Market's structure reflects diverse operational requirements across various commercial settings. Understanding these distinct segments allows manufacturers to tailor product development and market strategies effectively, addressing specific performance needs and regulatory compliance within each category.
Product Type:
The product type segmentation differentiates compressors based on their internal design and how they integrate into various refrigeration systems, from hermetically sealed units to open-drive configurations.
- Scroll:These compressors utilize two interleaved scrolls, one fixed and one orbiting, to compress refrigerant vapor. Scroll technology offers higher efficiency and fewer moving parts than traditional designs, with demand concentrating in supermarket refrigeration and new installations across Europe.
- Reciprocating:Reciprocating compressors use pistons driven by a crankshaft to compress refrigerant, offering robust performance for a wide range of capacities. This traditional technology remains prevalent in large industrial applications and legacy systems, particularly in North American cold storage facilities.
- Screw:Screw compressors employ two rotating helical rotors to compress gas, suitable for large capacity industrial refrigeration and process cooling applications.
- Centrifugal:Centrifugal compressors use a high-speed impeller to accelerate refrigerant vapor, primarily utilized in very large-scale industrial and specialized process cooling systems.
Reciprocating compressors lead volumes today; scroll compressors are gaining share fastest.
Technology:
Technology segments delineate the suitability of compressor designs for specific operational demands and environmental conditions across diverse applications.
- Hermetic:Hermetic compressors have the motor and compressor sealed within a single welded casing, preventing refrigerant leaks and reducing noise. These units are widely adopted in commercial display cases and smaller food service equipment due to their compact size.
- Semi-Hermetic:Semi-hermetic compressors feature a bolted casing, allowing for servicing and maintenance of internal components. These designs are common in medium-to-large capacity supermarket refrigeration racks and cold storage facilities, particularly in Germany.
- Open Drive:Open drive compressors feature an external motor connected to the compressor via a shaft, enabling field servicing and motor replacement for large industrial systems.
- Magnetic Bearing:Magnetic bearing compressors utilize magnetic fields to levitate the shaft, eliminating oil and friction for enhanced efficiency and reduced maintenance in specialized, high-performance applications.
Hermetic designs dominate smaller applications; semi-hermetic models drive larger commercial installations.
Application:
Application segmentation reveals how different commercial end-users deploy refrigeration compressors to meet their distinct operational needs and scale requirements.
- Supermarket Refrigeration:This application involves complex systems for display cases, walk-in coolers, and freezers, requiring compressors that handle variable loads and prioritize energy efficiency. Supermarket chains in the United States prioritize systems compliant with EPA regulations.
- Cold Storage:Cold storage facilities demand large-capacity compressors for continuous, precise temperature control over vast spaces, crucial for preserving perishable goods. The rapid build-out of cold chain infrastructure in China is driving significant demand in this segment.
- Food Processing:Food processing operations require compressors for chilling, freezing, and blast cooling, often with stringent hygiene and temperature accuracy standards.
- Beverage Cooling:This segment includes compressors for beverage display cases, vending machines, and bar refrigeration units, emphasizing reliability and energy efficiency for consistent product temperature.
Supermarket refrigeration systems consume the largest volume; cold storage demand shows the steepest expansion trajectory.
End User:
End-user categories reflect the varying levels of technological maturity and investment priorities across commercial sectors utilizing refrigeration.
- Retail Chains:Retail chains operate extensive networks of stores, requiring a mix of centralized and distributed refrigeration systems with a strong focus on energy management and remote monitoring. Urban centers integrating last-mile grocery delivery are driving new installations.
- Warehousing Firms:Warehousing firms manage large-scale cold storage facilities, prioritizing high-capacity, energy-efficient compressors to minimize operational costs. E-commerce fulfillment centers across India are expanding their refrigerated storage capacity.
- Food Service Providers:Food service providers, including restaurants and cafeterias, utilize compact refrigeration units for food preservation and preparation, demanding reliable and space-efficient compressors.
- Hospitality Operators:Hospitality operators like hotels and resorts use compressors for ice machines, walk-in coolers, and guest room mini-bars, focusing on quiet operation and consistent performance.
Retail chains represent the most established segment; warehousing firms exhibit strong demand for new installations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial refrigeration technology found its early footing in developed economies, driven by the necessity of preserving perishable goods for expanding urban populations. This historical development established foundational markets and infrastructure for compressor demand. Today, market evolution continues across diverse geographies, influenced by regulatory shifts and economic development.
China
China's rapid build-out of its national cold chain infrastructure fuels substantial demand for commercial refrigeration compressors. The dual carbon goals set by the Ministry of Ecology and Environment (MEE) promote energy-efficient and low-GWP solutions. Major industrial zones like the Yangtze River Delta are experiencing significant new cold storage facility construction, driving compressor sales.
United States
The United States market for commercial refrigeration compressors is shaped by stringent energy efficiency standards and environmental regulations. EPA actions under the AIM Act accelerate the transition to low-GWP refrigerants. Supermarket chains across California are actively investing in advanced scroll and variable-speed technologies to meet compliance requirements.
Germany
German demand for commercial refrigeration compressors prioritizes high-efficiency and natural refrigerant compatibility. Ecodesign requirements under the European Commission, along with the F-Gas Regulation, drive innovation in compressor design. Bavaria's industrial clusters are key centers for semi-hermetic compressor manufacturing and deployment in commercial settings.
India
India's expanding e-commerce sector and cold chain development are creating new opportunities for commercial refrigeration compressor installations. The Production-Linked Incentive (PLI) scheme for cold chain infrastructure encourages domestic manufacturing and adoption. Logistics hubs in Maharashtra are witnessing a surge in demand for refrigerated warehousing solutions.
Japan
Japan's commercial refrigeration sector emphasizes energy conservation and advanced compressor technologies. METI guidelines promote the adoption of highly efficient equipment and natural refrigerants to reduce environmental impact. Major urban centers like Tokyo lead the deployment of compact, high-efficiency units for food service applications and retail.
Commercial Refrigeration Compressor Market Key Industry Players
Capital-heavy producers compete with asset-light designers in the commercial refrigeration compressor market, creating a dynamic competitive environment. The industry exhibits a tiered structure, with large, diversified engineering conglomerates operating alongside specialized component manufacturers. Strategic archetypes include integrated system providers offering comprehensive solutions and pure-play compressor specialists focusing on core technology. Geographic expansion into emerging cold chain markets and technology licensing agreements are dominant competitive moves.
Specialists in advanced compressor technologies, such as Danfoss A/S, exemplify a focus on natural refrigerant compatibility and energy efficiency across various commercial applications. Emerson Electric Co. occupies a position as a technology leader, particularly with its widely adopted scroll compressor designs and digital controls integration. German-based Bitzer SE anchors the segment for robust semi-hermetic reciprocating and screw compressors, serving large-scale industrial and cold storage applications. These prominent companies represent distinct approaches to market leadership, leveraging their engineering expertise and established distribution networks within the commercial refrigeration sector.
| Leading Market Players |
|---|
| Danfoss A/S |
| Panasonic Corporation |
| Emerson Electric Co. |
| Johnson Controls International plc |
| Bitzer SE |
| Mitsubishi Electric Corporation |
| LG Electronics |
| GEA Group AG |
| Carrier Global Corporation |
| Others |
Cost & Logistics Intelligence
The performance-driven divergence between traditional HFC-compatible compressors and advanced natural refrigerant systems manifests in both pricing structures and supply chain configurations. This bifurcation influences material sourcing and manufacturing complexities across global markets.
Pricing Analysis
Contract-based long-term offtake agreements define the dominant pricing model for commercial refrigeration compressors, particularly for large OEMs. Price differentiation stems from certification levels, such as ISO 5149 compliance for natural refrigerants, and the integration of advanced technologies like variable speed drives. Pricing softness stems from intense competition in mature markets and the higher initial capital costs associated with new natural refrigerant systems. Small food service providers exhibit higher price sensitivity compared to large supermarket chains investing in long-term energy efficiency.
Supply Chain Analysis
Single-source vulnerability sits with specialized component manufacturers for high-pressure CO2 systems, particularly electronic expansion valves. Geographic supply concentration for key components draws from East Asia and specific European manufacturers. The supply chain relies on specialized high-pressure components and natural refrigerant-compatible materials, often sourced from a limited base. Regulatory restrictions, such as the EU's F-Gas Regulation, create structural risk by compelling rapid material and design shifts. Distribution runs primarily through original equipment manufacturers to system integrators and large end-users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play, driven by the varying stringency and timelines of refrigerant phasedown regulations between the European Union and the United States.
For Market Incumbents: Acquire specialized component manufacturing capabilities for natural refrigerant systems to secure critical supply and intellectual property. This move mitigates the threat of supply chain bottlenecks and emerging competitors focused solely on low-GWP solutions. Invest in R&D for advanced material compatibility and digital controls integration to maintain a technology lead in the evolving regulatory landscape.
For New Entrants and Emerging Players: A significant price-point gap exists between premium, highly efficient natural refrigerant systems and more traditional, lower-cost HFC-based units. Target the rapidly expanding cold chain infrastructure in India and China, focusing on small-format, high-efficiency compressors for urban fulfillment centers. Offer integrated IoT connectivity and predictive maintenance services as a differentiated go-to-market angle.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized technology developers focusing on natural refrigerant compatibility and energy efficiency. The long-term viability of the commercial refrigeration compressor market remains strong, propelled by global cold chain expansion and environmental mandates over the next decade. A signal to watch is the accelerated adoption rate of CO2 and propane systems in emerging markets, indicating readiness for higher initial capital outlays.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for CO2 Compressors | Increases availability of F-Gas compliant units for European markets. |
| Technology Licensing for Scroll Designs | Accelerates market penetration of efficient scroll technology in Asian cold chains. |
| Joint Venture in Electronic Expansion Valves | Secures critical component supply for high-pressure natural refrigerant systems. |
| Green Manufacturing Transition for Propane Units | Aligns production with evolving safety standards like ISO 5149. |
| Product Launch of VSD Semi-Hermetic Compressors | Captures demand from large supermarket chains prioritizing energy savings. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, forming a robust data approach. Primary research involved discussions with OEM product managers, cold storage facility operators, supermarket refrigeration engineers, and refrigerant manufacturers. Secondary validation drew from U.S. Department of Energy efficiency standards, European Commission ecodesign reports, EPA AIM Act documentation, and national cold chain investment reports from China and India. This combined approach enabled bottom-up and top-down triangulation.
The segment-weighting approach informed the analytical framework over the projection horizon. Segmentation dimensions modeled included product type, technology, application, end-user, and refrigerant type. Compound annual growth rates were derived from historical trends and future demand projections, accounting for regulatory shifts. Key forecast inputs included F-Gas phasedown schedules and cold chain infrastructure investment rates across key geographies.
Caveats apply where unforeseen regulatory changes or raw material price volatility could materially shift the outlook. Forecasts reflect assumptions regarding technological adoption rates and economic stability within the commercial refrigeration sector. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Air Handlers Market
HVAC Equipment
Europe Bus HVAC Market
HVAC Equipment
Global Air Duct Market
HVAC Equipment
Global Modular Chillers Market
HVAC Equipment
Commercial Refrigeration Equipment Market
HVAC Equipment
Japan HVAC Market
HVAC Equipment
North America Commercial HVAC Market
HVAC Equipment
Screw Compressor Market
HVAC Equipment
Ventilation Equipment Market
HVAC Equipment
United Kingdom HVAC Market
HVAC Equipment
Foamer Pump Market
HVAC Equipment
US Residential Furnace Market
HVAC Equipment
Desert Air Cooler Market
HVAC Equipment
Industrial Refrigeration Equipment Market
HVAC Equipment
Global Air Conditioner Market
HVAC Equipment
Europe Air Conditioning Equipment Market