
 Air Handlers Market | 2026-2036
Air Handlers Market Size, Share, and Industry Trends Forecast 2026-2036
Air Handlers Market Analysis
Data center operators is rotating capital toward dedicated air handling units as hyperscale facilities displace traditional commercial buyers in unit volume. Carrier Corporation leverages its chiller-air handler integration to sustain project wins in colocation builds across North America. Johnson Controls International plc anchors its position through building automation tie-ins that bundle controls with mechanical equipment. Trane Technologies plc competes on coil technology leadership, differentiating its portfolio with low-global-warming-potential refrigerant compatibility.
An air handler is a central HVAC component comprising a fan, heating or cooling coils, filters, and dampers housed within a metal casing, designed to condition and circulate air through ducted distribution systems. Units typically operate at static pressures from 0.5 to 6.0 inches water gauge depending on building scale and duct complexity. Variable Air Volume configurations now lead commercial specification due to part-load efficiency advantages over constant-volume alternatives. Heat Recovery technology is expanding fastest in institutional and industrial segments where exhaust air energy capture offsets ventilation heating and cooling penalties.
The U.S. Department of Energy sets minimum fan efficiency requirements under federal appliance standards, while the EPA's SNAP program restricts refrigerants that determine coil and heat exchanger design paths. China's GB standards for building energy efficiency mandate heat recovery in large public buildings, directly conditioning air handler specification in new construction. Stakeholders must monitor refrigerant phase-down schedules and regional efficiency code adoptions to align product roadmaps with compliance windows.
Market Dynamics
Data center thermal density from AI server racks is compressing replacement cycles and forcing mechanical infrastructure redeployment across facility portfolios. Operators now specify air handlers with 30-40% higher static pressure ratings than standard commercial units to manage concentrated heat loads.
Growth Catalysts
- GB Standards Mandate:China's building energy efficiency regulations require heat recovery systems in public buildings above specified floor areas, directly expanding specification for energy-recovery ventilator-integrated air handlers.
- Hyperscale Construction:State-backed data center clusters in Guizhou and Ningxia provinces are accelerating unit procurement for facilities exceeding 100 megawatts of IT load each.
- Fan Power Limitations:The U.S. Department of Energy's tightening appliance efficiency standards are forcing equipment upgrades across existing commercial building stock.
Market Restraints
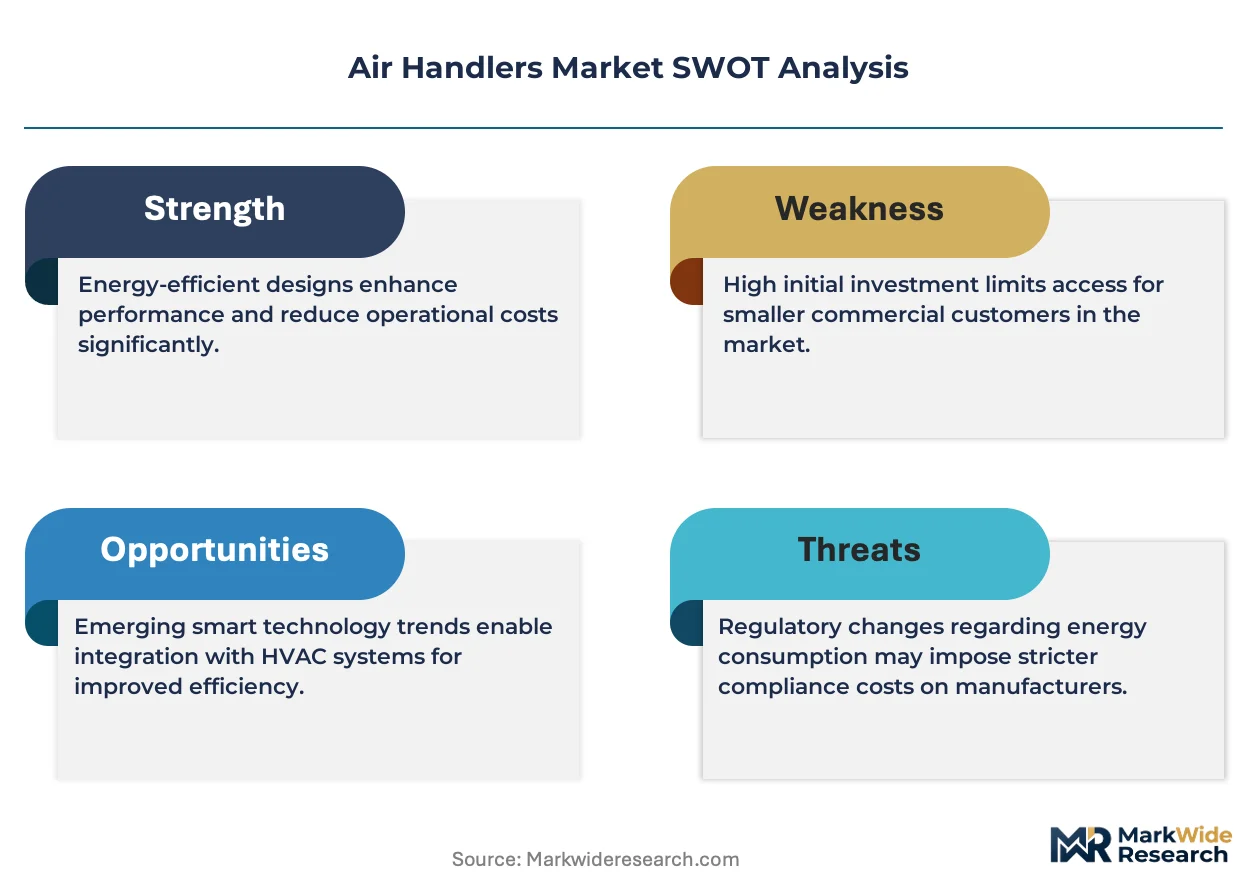
- Copper and Aluminum Volatility:Coil manufacturing depends on base metal inputs with price swings that compress margin predictability for equipment fabricators.
- Refrigerant Phase-Down Schedules:The EPA's SNAP program restrictions are forcing premature coil redesigns before capital recovery on existing production tooling.
- Skilled Technician Scarcity:Commissioning of variable air volume configurations requires controls integration expertise that remains concentrated among specialized contractors.
Strategic Opportunities
- Low-GWP Refrigerant Compatibility:Coil technology leadership in R-32 and R-454B systems opens specification windows in jurisdictions with accelerated hydrofluorocarbon phase-out timelines.
- Building Automation Convergence:Integration of air handlers with BACnet and LonWorks protocols enables recurring software revenue streams alongside equipment sales.
- Industrial Exhaust Heat Recovery:Manufacturing facilities in the U.S. Midwest are retrofitting ventilation systems to capture process heat and offset thermal loads.
Industry Challenges
- Controls Integration Complexity:Legacy pneumatic systems in existing commercial buildings resist seamless integration with digital variable frequency drive retrofits.
- Certification Timeline Compression:AHRI certification testing backlogs are extending product launch windows by four to six months for new coil configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air Handlers Market |
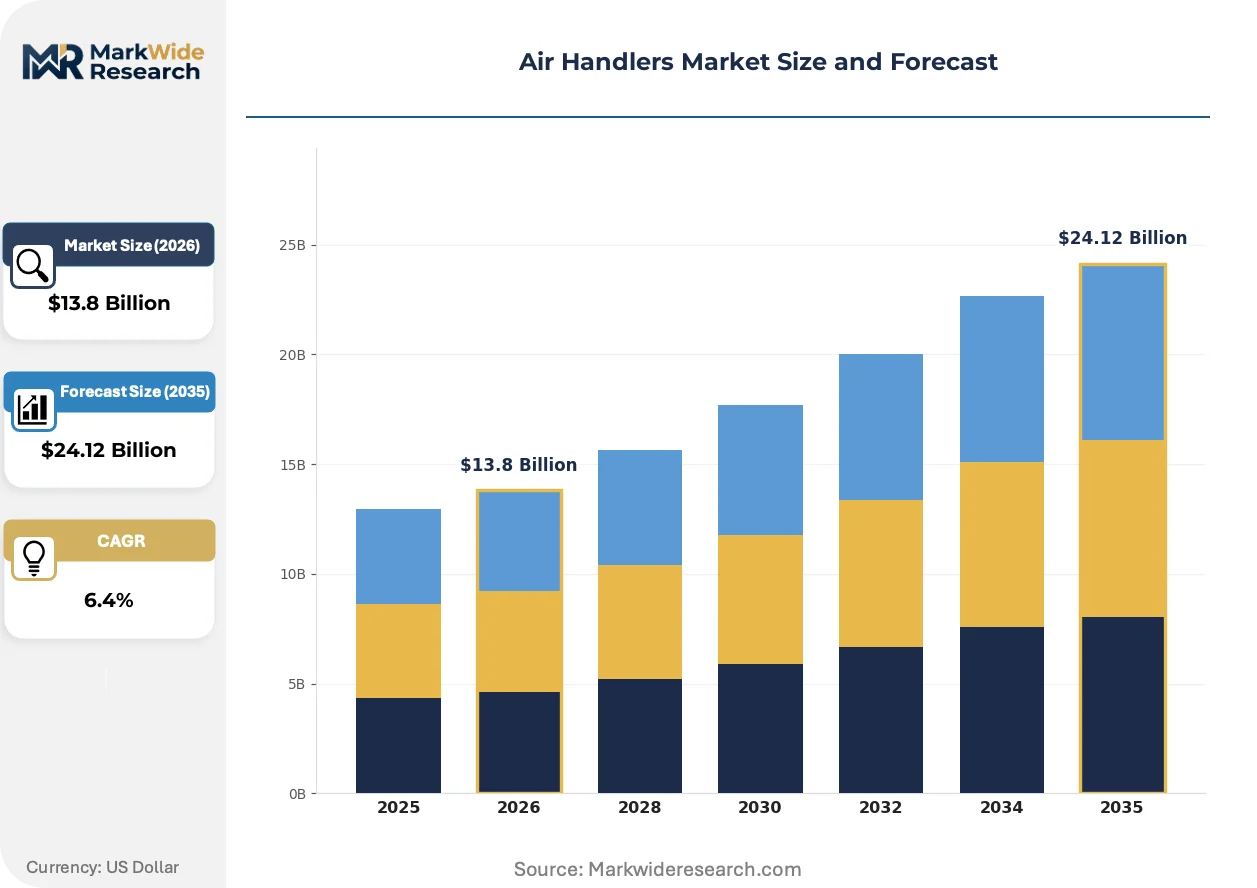
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $24.12 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Zone, Multi Zone, Rooftop, Variable Air Volume End User: Residential, Commercial, Industrial, Institutional Technology: Air Cooled, Water Cooled, Evaporative, Heat Recovery Application: HVAC, Ventilation, Dehumidification, Refrigeration |
| Companies Covered | Daikin Industries Ltd., Carrier Corporation, Johnson Controls International plc, Trane Technologies plc, Systemair AB, Lennox International Inc., Trox GmbH, Munters AB, Rheem Manufacturing Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Handlers Market Emerging Trajectories
Equipment specification is pivoting from standalone mechanical components toward integrated thermal management systems. This redefinition is compressing the vendor base and elevating system-level performance guarantees over unit efficiency metrics.
Modular air handler configurations are fragmenting the traditional custom-fabricated unit market. Data center operators in Northern Virginia and Phoenix are specifying skid-mounted, factory-tested modules that reduce field installation labor by half. This pre-engineered approach is compressing project timelines and shifting value capture from contractors to original equipment manufacturers.
The EPA's SNAP program is accelerating refrigerant transition timelines that force coil redesign commitments. Equipment manufacturers must now validate heat exchanger performance with low-global-warming-potential alternatives before regulatory deadlines lock in product architectures. Commercial rooftop applications face the steepest compliance curve due to high charge volumes and leak-prone installation environments.
Facility managers are unbundling after-sales service contracts from initial equipment procurement. Colocation operators in Dallas and Ashburn are separately negotiating multi-year maintenance agreements with specialized controls contractors rather than accepting bundled OEM service terms. This disintermediation is compressing service margins for equipment manufacturers while expanding third-party controls integrator market access.
Air Handlers Market Segmentation
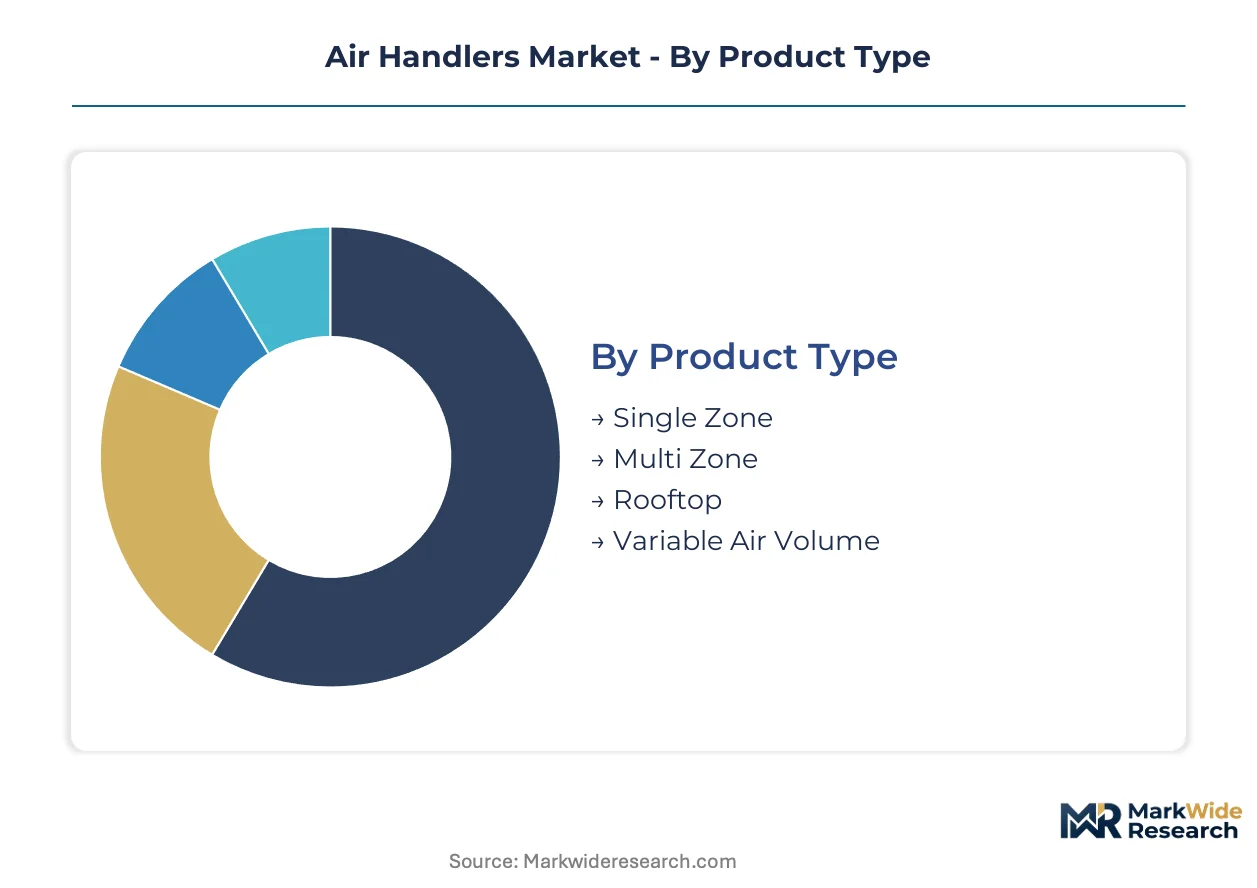
Product architecture in air handlers determines channel economics and project profitability. Specification complexity varies dramatically across segments, with some categories demanding deep controls integration while others move through commodity distribution.
Product Type:
Channel mix splits sharply between engineered-to-order project business and stocked distribution. Single Zone and Rooftop units flow through wholesale HVAC distributors with contractor pull-through, while Variable Air Volume and Multi Zone configurations route through specifying engineers and controls integrators.
- Variable Air Volume:Fan arrays with modulating dampers adjust airflow to thermal zones based on real-time demand signals. Data center operators in Northern Virginia and Phoenix specify these for hyperscale facilities where part-load efficiency dominates operating economics.
- Multi Zone:Integrated coil and damper assemblies serve multiple temperature zones from a single central unit. Colocation builds across Dallas and Ashburn are driving specification for zoned thermal management in multi-tenant environments.
- Rooftop:Self-contained weatherized packages combine heating, cooling, and air distribution in single curb-mounted enclosures.
- Single Zone:Constant-volume units with fixed-speed fans serve discrete spaces without zone-level modulation.
By volume, Rooftop leads through replacement demand in commercial building stock. By growth pace, Variable Air Volume is climbing the fastest on data center thermal density requirements.
End User:
Cost tier stratification separates premium engineered solutions from standard efficiency commodity units. Industrial and Institutional buyers absorb higher first costs for heat recovery and controls sophistication, while Residential and Commercial segments prioritize installed cost minimization.
- Industrial:Heavy-gauge casings and corrosion-resistant coils withstand process environments and continuous duty cycles. Manufacturing facilities in the U.S. Midwest are retrofitting ventilation systems to capture exhaust heat and offset thermal loads.
- Institutional:Redundant fan arrays and filtration stages meet occupancy health standards in healthcare and education settings. China's GB standards mandate heat recovery in public buildings above specified floor areas, directly expanding specification for this segment.
- Commercial:Mid-range static pressure ratings balance first cost against operating efficiency in office and retail applications.
- Residential:Compact footprint units with simplified controls serve single-family and low-rise multifamily construction.
By revenue concentration, Industrial dominates project value. By specification velocity, Institutional is gaining share fastest on regulatory mandates.
Technology:
Application context determines technology selection—process cooling demands differ fundamentally from comfort conditioning. Water Cooled and Heat Recovery systems concentrate in new construction with access to infrastructure, while Air Cooled and Evaporative units serve retrofit and water-scarce environments.
- Heat Recovery:Exhaust air energy capture through rotary wheels or plate exchangers reduces ventilation thermal penalties. State-backed data center clusters in Guizhou and Ningxia are accelerating procurement for facilities where economizer hours supplement mechanical cooling.
- Water Cooled:Shell-and-tube or brazed plate heat exchangers reject heat to cooling towers or geothermal loops. The EPA's SNAP program restrictions are forcing coil redesign commitments for low-global-warming-potential refrigerant compatibility.
- Air Cooled:Finned-tube condensers eliminate water infrastructure requirements in remote or arid installations.
- Evaporative:Direct or indirect cooling through water evaporation extends economizer operating range in dry climates.
By installed base, Air Cooled leads on retrofit accessibility. By expansion trajectory, Heat Recovery is advancing most quickly on energy code adoptions.
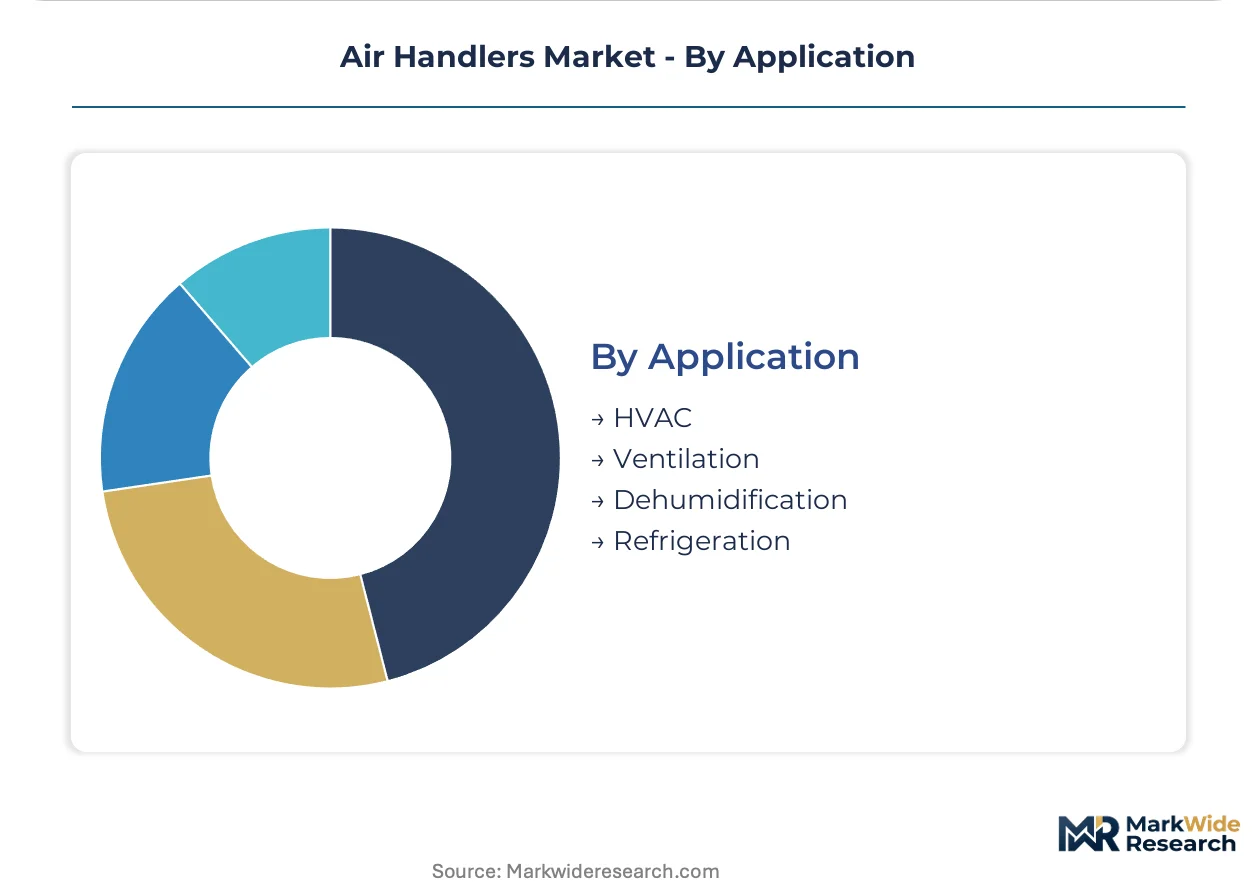
Application:
Customer type and procurement authority shape application-level demand. HVAC and Ventilation segments serve facility owner/operators with capital budgets, while Dehumidification and Refrigeration applications often flow through process engineering firms with performance guarantees.
- HVAC:Integrated heating, cooling, and air distribution for occupant comfort and indoor air quality. The U.S. Department of Energy's tightening appliance efficiency standards are forcing equipment upgrades across existing commercial building stock.
- Ventilation:Dedicated outdoor air systems with filtration and conditioning for code-compliant fresh air delivery. Modular configurations are fragmenting the traditional custom-fabricated unit market with skid-mounted, factory-tested assemblies.
- Dehumidification:Deep cooling coils or desiccant wheels control moisture levels in sensitive process or storage environments.
- Refrigeration:Low-temperature air handlers for cold storage and food processing applications.
By unit volume, Ventilation leads on code-minimum replacement cycles. By value growth, HVAC is expanding fastest on system integration premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese air handler exports flow into hyperscale data center construction across Southeast Asia and the Middle East, while German and Japanese manufacturers supply precision-engineered units to pharmaceutical and semiconductor facilities in North America and Europe.
United States
Data center construction in Northern Virginia and Phoenix drives specification for high-static-pressure units. The Department of Energy's appliance efficiency standards tighten fan power limitations across commercial building stock. Colocation operators in Dallas and Ashburn are unbundling service contracts from equipment procurement.
China
State-backed data center clusters in Guizhou and Ningxia provinces accelerate unit procurement for facilities exceeding 100 megawatts of IT load each. GB standards mandate heat recovery systems in public buildings above specified floor areas. Manufacturing concentration in the Yangtze River Delta supports both domestic deployment and export fabrication.
Germany
Industrial exhaust heat recovery retrofits in the Midwest of Germany expand ventilation system upgrades. The EU F-Gas Regulation accelerates hydrofluorocarbon phase-out timelines for coil redesign. Engineering competence clusters in Baden-Württemberg and North Rhine-Westphalia anchor precision air handling specification for pharmaceutical cleanrooms.
Japan
Semiconductor fabrication facilities in the Kanto and Kansai regions demand ultra-low particulate air handlers with redundant fan arrays. METI efficiency guidelines tighten building energy performance standards. Tokyo Metro data center operators specify modular skid-mounted configurations to compress installation timelines.
India
Commercial real estate expansion in Mumbai and Bengaluru drives mid-range static pressure unit demand. Bureau of Indian Standards certification requirements condition import flows from East Asian suppliers. IT park development in Hyderabad and Chennai concentrates specification for variable air volume configurations.
Air Handlers Market Vendor Landscape
Player mix skews toward diversified HVAC conglomerates with integrated controls capabilities. The vendor base concentrates around three strategic tiers: full-system integrators bundling chillers with air handlers, controls-centric specialists leveraging building automation tie-ins, and coil-technology leaders differentiating on refrigerant compatibility. Dominant competitive moves include M&A to capture data center project pipelines and capacity expansion in Guizhou and Ningxia to serve Chinese state-backed construction.
Within the full-system integrator tier, Carrier Corporation and Trane Technologies plc exemplify equipment bundling strategies that capture colocation and hyperscale facility contracts. Johnson Controls International plc anchors the controls-centric position through building automation convergence. Daikin Industries Ltd. occupies a scale-driven position spanning residential through industrial applications. These three archetypes—system integrators, automation bundlers, and scale manufacturers—structure competitive positioning across project-based and distribution channels.
| Leading Market Players |
|---|
| Daikin Industries Ltd. |
| Carrier Corporation |
| Johnson Controls International plc |
| Trane Technologies plc |
| Systemair AB |
| Lennox International Inc. |
| Trox GmbH |
| Munters AB |
| Rheem Manufacturing Company |
| Others |
Supply Flow & Price Mechanics
Aluminum coil substitution for copper heat exchangers is compressing raw material costs while redrawing procurement geography toward Chinese rolling mills and Korean semi-finished suppliers. This input shift simultaneously elevates price competition in mid-tier commercial units and tightens margin capture for fabricators locked into legacy copper supply contracts.
Pricing Analysis
Next-generation R-32 and R-454B refrigerant compatibility commands 15-25% premiums over legacy R-410A systems, while prior-generation constant-volume units trade at distressed prices in replacement markets. Three-tier pricing structure across premium, standard, and economy levels stratifies by static pressure rating and controls sophistication. Pricing pressure stems from copper and aluminum volatility that compresses margin predictability for coil fabricators. Commercial contractors exhibit highest price sensitivity due to bid-competitive procurement, while data center operators absorb premiums for high-static-pressure configurations.
Supply Chain Analysis
China and South Korea anchor coil manufacturing and fan motor production respectively, with Mexico emerging as a near-shore assembly hub for U.S. commercial distribution. The supply chain draws from copper cathode, aluminum coil stock, and rare-earth magnet inputs. Single-source vulnerability concentrates in high-efficiency motor laminations from specialized East Asian suppliers. Distribution runs through wholesale HVAC distributors with contractor pull-through for standard units, while engineered-to-order configurations route through specifying engineers and controls integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The air handlers market sits at an AI-driven thermal density inflection that is compressing replacement cycles and elevating specification complexity. Regulatory phase-down of high-GWP refrigerants under EPA SNAP and EU F-Gas mandates is simultaneously forcing coil redesign commitments.
For Market Incumbents: Secure data center project pipelines through chiller-air handler integration bundles that lock in multi-year service contracts. Carrier Corporation and Trane Technologies exemplify this system-level positioning. Defend against modular skid-mounted competitors by accelerating factory-test certification throughput. Backward integration into coil manufacturing insulates margin from base metal volatility.
For New Entrants and Emerging Players: AHRI certification fast-track through pre-tested coil configurations opens specification windows in U.S. commercial replacement markets. Target the U.S. Midwest industrial exhaust heat recovery retrofit segment where legacy pneumatic controls resist integration with incumbent digital platforms. White-space exists in BACnet-native air handlers for mid-market colocation builds in Dallas and Phoenix. Go-to-market through specialized controls contractors rather than OEM service channels.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors controls-centric specialists with building automation convergence capabilities. Long-term viability hinges on refrigerant transition readiness and data center exposure over the next decade. Acquisition targets should demonstrate coil technology leadership in low-GWP compatibility and established relationships with hyperscale facility developers. Monitor AHRI certification backlogs as a signal of product launch velocity and competitive positioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Transition Readiness | R-32 and R-454B coil validation opens specification windows under EPA SNAP and EU F-Gas accelerated phase-down timelines. |
| Modular Skid-Mounted Configuration | Factory-tested assemblies reduce field installation labor by half in Northern Virginia and Phoenix hyperscale builds. |
| Building Automation Convergence | BACnet and LonWorks protocol integration enables recurring software revenue alongside equipment sales for Johnson Controls. |
| Heat Recovery Technology Expansion | GB standards mandate in Chinese public buildings directly conditions air handler specification for institutional segment growth. |
| Service Contract Unbundling Defense | Multi-year maintenance agreements with specialized controls contractors protect against colocation operator disintermediation in Dallas and Ashburn. |
Methodological Framework
A standing panel of data center facility engineers, HVAC specifying engineers, controls integrators, and wholesale distribution managers provided ongoing calibration across the research process. Primary interviews with these stakeholders combined with secondary validation from AHRI certification databases, U.S. Department of Energy appliance standards filings, China GB standards documentation, and EPA SNAP program regulatory updates. Bottom-up unit shipment analysis triangulated against top-down construction spending data across commercial, institutional, and industrial verticals.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions including product architecture, end-user cost tier, cooling technology type, and application context with specific weighting for data center thermal density requirements. CAGRs derived from regression analysis of historical shipment patterns and forward-looking construction pipeline data incorporated refrigerant transition timelines and regional efficiency code adoption schedules as key inputs.
Decision-makers should treat outputs as directional under assumptions of continued AI server rack deployment, stable copper-aluminum price spreads, and regulatory adherence to published phase-down schedules; material deviation would warrant model refresh. Recalibration cycles align with material shifts in hyperscale construction permitting, AHRI certification protocol updates, and amendments to federal appliance efficiency standards.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Foamer Pump Market
HVAC Equipment
Screw Compressor Market
HVAC Equipment
Commercial Refrigeration Compressor Market
HVAC Equipment
Global Split Systems Market
HVAC Equipment
Industrial Blowers Market
HVAC Equipment
France Commercial HVAC Market
HVAC Equipment
Louver Dampers Market
HVAC Equipment
United Kingdom District Heating Market
HVAC Equipment
North America Heat Exchanger Market
HVAC Equipment
Air Conditioning Systems Market
HVAC Equipment
Europe HVAC Field Device Market
HVAC Equipment
North America HVAC Equipment Market
HVAC Equipment
Equipment for HVAC Market
HVAC Equipment
Asia Pacific Commercial HVAC Market
HVAC Equipment
Warm Air Furnaces Market
HVAC Equipment
Germany HVAC Market