
 Commercial Refrigeration Equipment Market | 2026-2036
Commercial Refrigeration Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Refrigeration Equipment Market Analysis
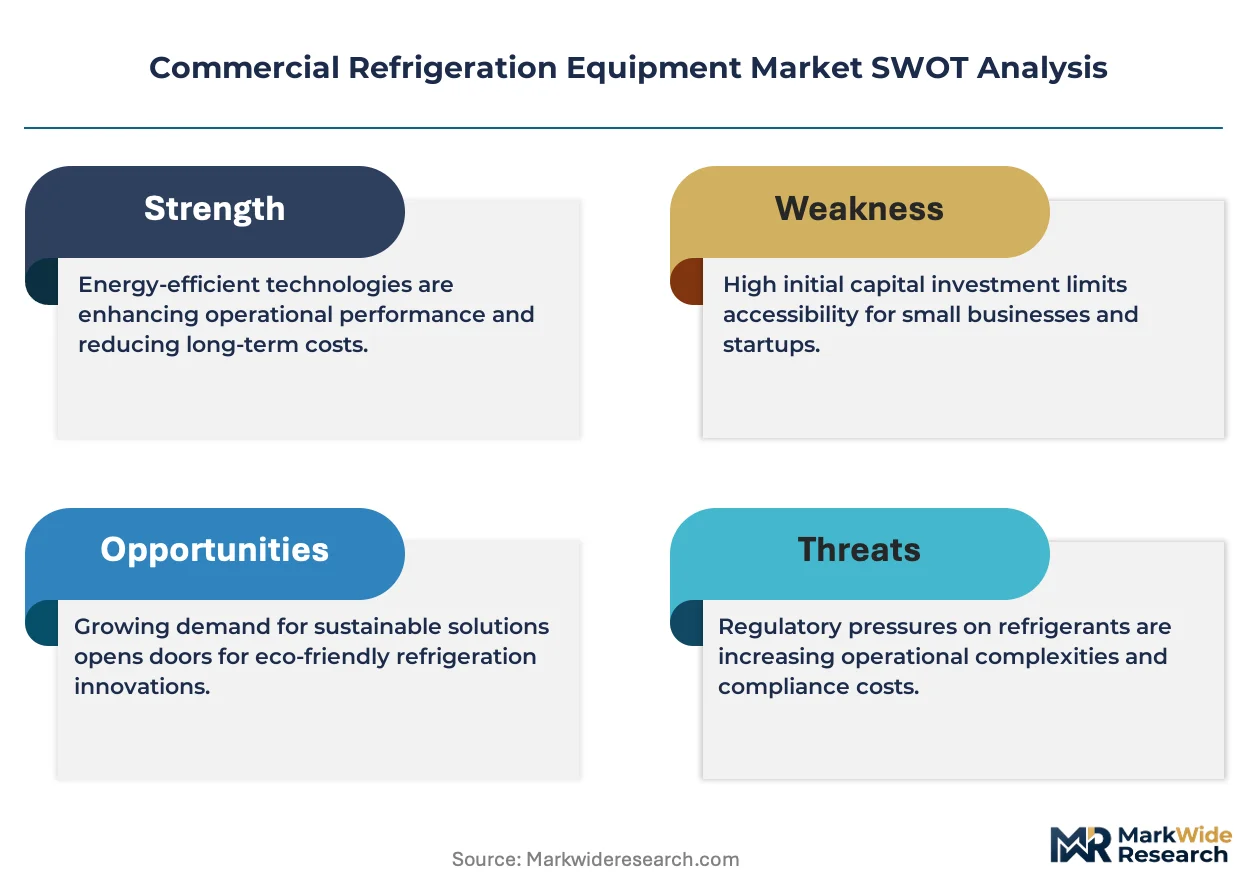
Refrigeration technician shortages across North America and Europe is reorganizing service networks and pushing end-users toward predictive maintenance contracts. Carrier Global Corporation leverages its broad distribution footprint to sustain aftermarket revenue streams. Danfoss anchors its position through component specialization in natural refrigerant systems. Hussmann Corporation dominates the North American supermarket retrofit segment with display case expertise.
Commercial refrigeration equipment encompasses engineered cooling systems designed to maintain temperatures between minus 40 degrees Celsius and 15 degrees Celsius for perishable goods in non-residential settings, utilizing vapor-compression cycles with specified refrigerants and insulation assemblies. The primary purpose centers on food safety compliance, shelf-life extension, and inventory quality preservation across food service and retail operations. Display cases command the largest installed base among product types, though blast freezers represent the fastest-growing category as prepared meal delivery expands. Walk-in coolers generate concentrated margin pools through custom engineering and installation services. The restaurants end-user segment leads absolute unit demand, while supermarkets drive premium specification requirements for energy efficiency and refrigerant transition.
The United States Environmental Protection Agency enforces phasedown schedules for hydrofluorocarbon refrigerants under the American Innovation and Manufacturing Act, directly compelling equipment redesigns and retrofit investments. The European Union F-Gas Regulation imposes stringent quota reductions that accelerate natural refrigerant adoption across member states. China's Ministry of Ecology and Environment implements dual carbon goals that tighten energy efficiency standards for commercial cold chain infrastructure. Stakeholders must monitor regulatory divergence across these three jurisdictions to align R&D portfolios and manufacturing capacity with divergent compliance timelines.
Market Dynamics
The Kigali Amendment's hydrofluorocarbon phasedown is compressing equipment replacement cycles and forcing refrigerant chemistry transitions across manufacturer portfolios. This regulatory pressure intersects with cold chain infrastructure expansion in food retail, creating simultaneous demand pull and compliance cost push.
Growth Catalysts
- Natural Refrigerant Mandates:The EPA's AIM Act and EU F-Gas Regulation are compelling supermarket operators to replace legacy systems with CO2 and ammonia-based equipment, accelerating retrofit investments across the United States and Germany.
- Prepared Meal Delivery Expansion:Blast freezer demand from central kitchen operators and meal-kit fulfillment centers is creating specification requirements for rapid temperature pull-down capabilities in food service infrastructure.
- Dual Carbon Goals in China:The Ministry of Ecology and Environment's efficiency standards for commercial cold chain are driving equipment upgrades in tier-one cities' supermarket and convenience store networks.
Market Restraints
- Copper and Aluminum Price Volatility:Heat exchanger and coil manufacturing faces margin compression from commodity input swings, squeezing mid-tier equipment producers without captive metal sourcing.
- Technician Labor Scarcity:Refrigeration service networks across North America and Europe cannot scale headcount to match installed base growth, extending equipment downtime and deferring maintenance contracts.
- Natural Refrigerant Safety Codes:Ammonia charge limits in urban building codes restrict system design flexibility for supermarket retrofits in dense metropolitan zones.
Strategic Opportunities
- Predictive Maintenance Contracts:Sensor-embedded equipment enabling remote monitoring is allowing manufacturers to capture recurring revenue streams from risk-averse supermarket chains.
- India Cold Chain Modernization:FSSAI food safety enforcement and PLI scheme subsidies for food processing infrastructure are opening specification windows for energy-efficient display cases and walk-in units.
- Refrigerant-as-a-Service Models:Leasing structures that bundle equipment, installation, and refrigerant management are penetrating the restaurant segment where capex constraints dominate purchasing decisions.
Industry Challenges
- Certification Timeline Compression:EPA SNAP approvals and UL safety listings for new natural refrigerant systems are creating launch delays that misalign with customer replacement schedules.
- Legacy Control System Integration:Building management system protocols from the 1990s lack interoperability with IoT-enabled refrigeration monitoring, forcing expensive gateway hardware deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Refrigeration Equipment Market |
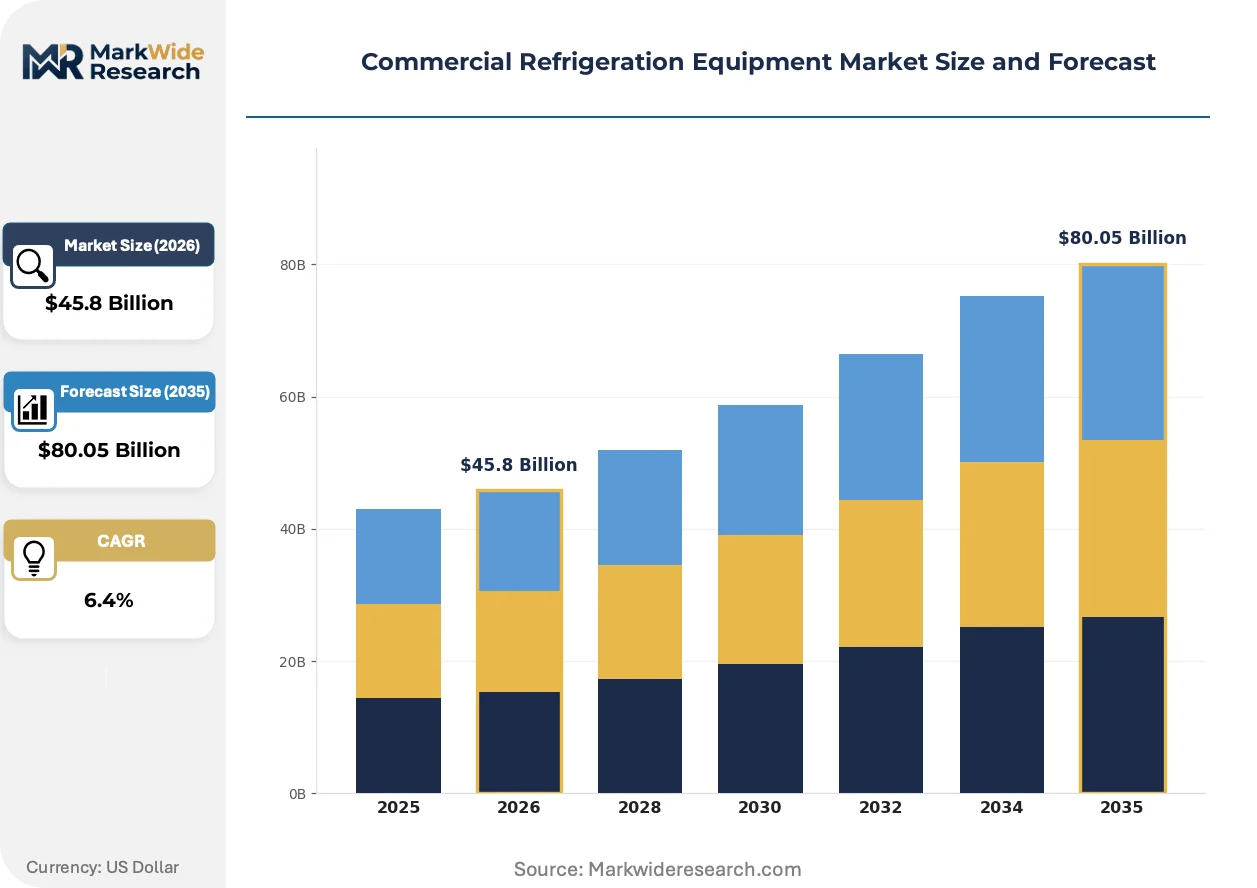
| Market Size in 2026 | $45.8 Billion |
| Market Size in 2035 | $80.05 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Display Cases, Walk-in Coolers, Ice Makers, Blast Freezers End User: Restaurants, Supermarkets, Convenience Stores, Hotels Technology: Refrigerant-Based, Thermoelectric, Hybrid, Air-Cooled Application: Food Preservation, Beverage Storage, Ice Production, Catering Services |
| Companies Covered | Daikin Industries Ltd., Johnson Controls, Hussmann Corporation, Dover Corporation, GEA Group AG, Carrier Global Corporation, Danfoss, AB Electrolux, Ali Group Srl, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Refrigeration Equipment Market Emerging Trajectories
Equipment architecture is splitting between modular distributed systems for new construction and compact drop-in replacements for constrained retrofit sites. This technical divergence is reshaping manufacturer R&D allocation and field service training curricula.
CO2 transcritical refrigeration is bifurcating the supermarket segment. The technology uses supercritical carbon dioxide as a working fluid in warm-climate applications. European chains and progressive US operators are specifying these systems for new builds, while the installed base of HFC equipment faces accelerated obsolescence. This split is compressing the market for transitional refrigerant blends and forcing component suppliers to dual-track their product roadmaps.
REACH and RoHS substance restrictions are tightening material specifications for insulation foams and electrical components in equipment bound for EU member states. Manufacturers must reformulate polyurethane blowing agents and validate alternative flame retardants to maintain market access. The compliance burden falls heaviest on small-format display case producers without dedicated regulatory affairs teams.
Restaurant procurement departments are consolidating supplier relationships from fragmented local dealers toward national service agreements with direct manufacturer accountability. This concentration is disintermediating traditional wholesale distribution in the United States. Chains with 50-plus locations now demand unified fleet management platforms spanning equipment monitoring, energy reporting, and predictive maintenance dispatch.
Commercial Refrigeration Equipment Market Segmentation
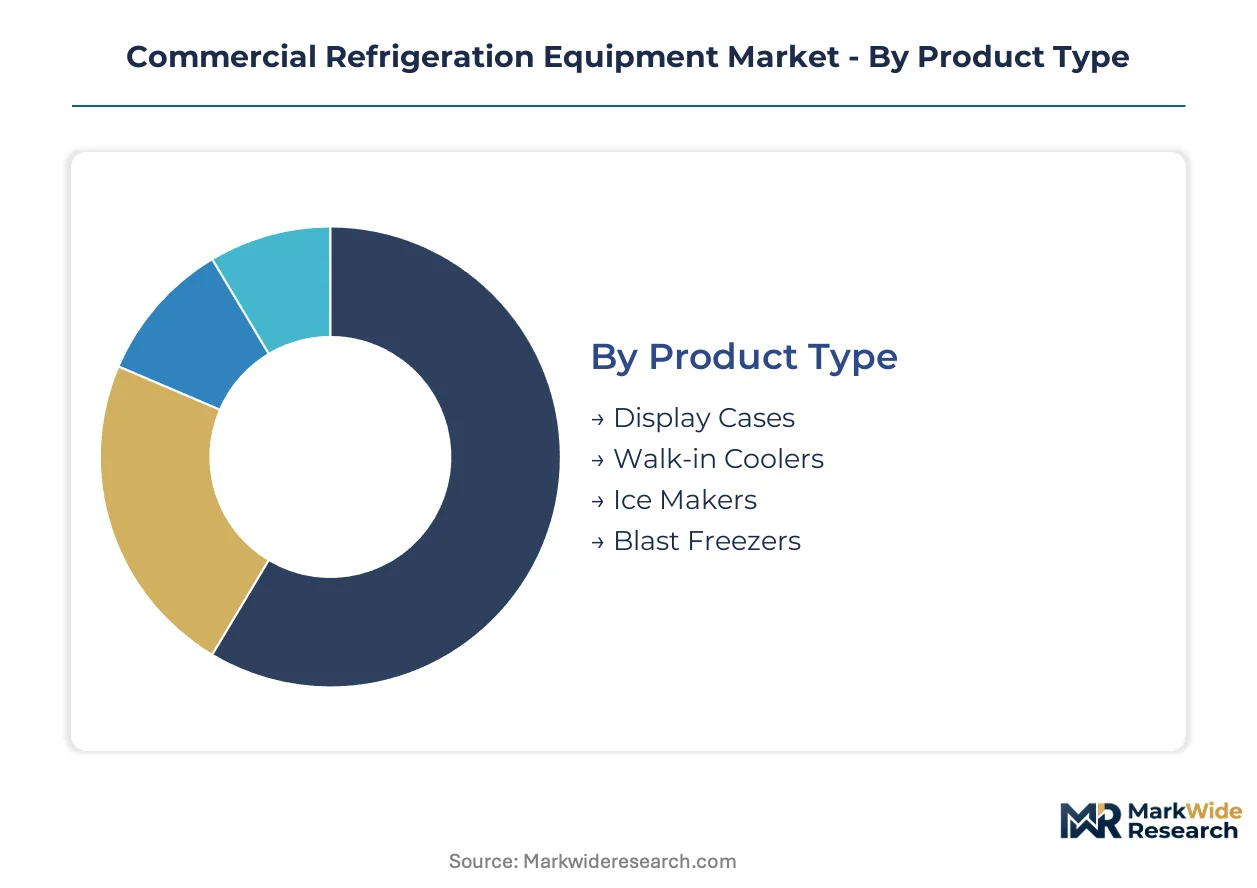
Segmentation reveals how margin pools concentrate in custom-engineered systems versus standardized units, and which end-user procurement patterns determine equipment specification tiers. Understanding these divisions exposes where manufacturers must anchor R&D investment versus where scale economics dominate.
Product Type:
Margin pools concentrate in walk-in coolers through engineering-intensive installation services, while display cases generate volume through standardized retail specifications.
- Display Cases:Engineered glass-enclosed units with integrated lighting and temperature zoning maintain 2 to 15 degrees Celsius for open retail merchandising. Demand clusters in Germany and United States supermarket retrofits where natural refrigerant mandates under the EPA AIM Act and EU F-Gas Regulation are accelerating replacement cycles.
- Walk-in Coolers:Modular insulated enclosures with custom panel configurations and vapor-sealed entry systems serve back-of-house storage applications. United States food service distributors and central kitchen operators in tier-one Chinese cities are specifying these units for prepared meal delivery infrastructure expansion.
- Ice Makers:Compact cube or flake production units with dedicated water filtration and harvest control systems serve beverage service applications.
- Blast Freezers:High-velocity forced-air units achieving minus 40 degrees Celsius for rapid product temperature pull-down in commercial kitchens.
Display cases hold installed capacity. Blast freezers are rotating up the share rankings.
End User:
Volume concentration diverges from value concentration — restaurants drive unit shipments while supermarkets command premium specification tiers.
- Restaurants:Full-service and quick-service operators deploy reach-in refrigerators, undercounter units, and prep tables across distributed kitchen footprints. Chains with 50-plus United States locations are consolidating procurement toward national manufacturer service agreements with unified fleet management platforms.
- Supermarkets:Grocery retailers specify integrated refrigeration architectures spanning display cases, walk-in coolers, and rack systems with centralized control. Operators in Germany and the United States face simultaneous pressure from EU F-Gas Regulation quotas and EPA hydrofluorocarbon phasedown schedules.
- Convenience Stores:Small-format retailers prioritize compact reach-in units and ice merchandisers with minimal footprint and plug-and-play installation.
- Hotels:Hospitality properties combine back-of-house kitchen systems with front-of-house minibar and banquet service equipment.
Restaurants dominate absolute unit demand. Supermarkets are climbing the fastest on specification value per installation.
Technology:
Technology selection determines regulatory compliance trajectory and field service capability requirements across installer networks.
- Refrigerant-Based:Vapor-compression systems utilizing hydrofluorocarbon, hydrofluoroolefin, or natural refrigerant working fluids remain the installed base standard. Transitions to CO2 transcritical and ammonia systems are accelerating in European Union member states and progressive United States operators under Kigali Amendment-aligned mandates.
- Thermoelectric:Solid-state Peltier cooling modules eliminate compressor noise and vibration for hospitality minibars and medical specimen storage. Niche adoption concentrates in hotel chains and laboratory settings where acoustic control outweighs efficiency penalties.
- Hybrid:Combined vapor-compression and thermal storage architectures optimize energy consumption through load shifting. Pilot deployments are emerging in United States utility demand-response programs and Chinese tier-one city peak-shaving initiatives.
- Air-Cooled:Condenser configurations utilizing ambient air heat rejection predominate in warm-climate installations and rooftop equipment pads.
Refrigerant-based systems hold installed capacity. Hybrid architectures are gaining share fastest among new construction specifications.
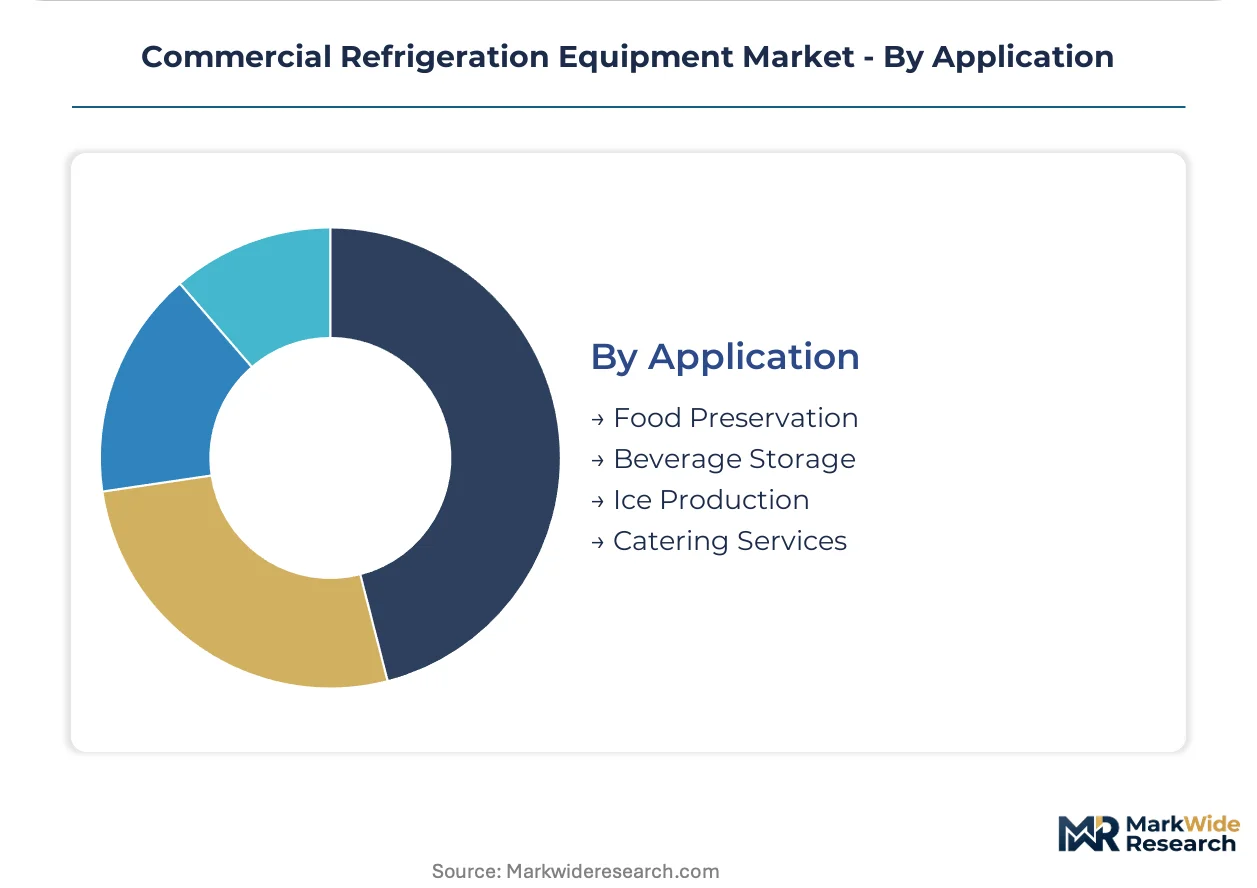
Application:
Application focus determines equipment durability specifications, control system complexity, and service interval requirements.
- Food Preservation:Temperature-controlled storage and display for perishable inventory spans the full equipment portfolio. United States supermarket operators and Chinese cold chain infrastructure investments are driving specification upgrades for HACCP compliance and shelf-life extension.
- Beverage Storage:Dedicated reach-in and merchandising equipment maintains 2 to 10 degrees Celsius for bottled and draft products. Convenience store chains in the United States and Germany are standardizing on energy-efficient glass door units with LED lighting and smart defrost controls.
- Ice Production:Cube, flake, and nugget generation systems serve food service and healthcare hydration applications.
- Catering Services:Mobile and temporary refrigeration supports off-site event execution with transportable cold holding and blast chilling capabilities.
Food preservation holds installed capacity. Beverage storage is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EPA's AIM Act enforcement is compressing equipment replacement cycles across United States food retail infrastructure. Natural refrigerant mandates under the Kigali Amendment are reshaping procurement patterns in Germany and China. Cold chain modernization investments concentrate in tier-one cities and metropolitan retail corridors.
United States
Supermarket operators face simultaneous pressure from EPA hydrofluorocarbon phasedown schedules and state-level efficiency incentives. The American Innovation and Manufacturing Act compels CO2 transcritical retrofits in California and New York Metro markets. Refrigeration service networks in Chicago and Dallas-Fort Worth cannot scale technician headcount to match retrofit demand.
Germany
Grocery retailers accelerate natural refrigerant adoption ahead of EU F-Gas Regulation quota reductions. The Kigali Amendment alignment forces equipment redesigns across Bavaria and North Rhine-Westphalia supermarket chains. Berlin-Brandenburg operators consolidate procurement toward national service agreements with predictive maintenance platforms.
China
The Ministry of Ecology and Environment's dual carbon goals tighten energy efficiency standards for commercial cold chain infrastructure. Tier-one cities including Shanghai and Beijing specify premium equipment for supermarket and convenience store network expansion. Yangtze River Delta cold chain investments concentrate in prepared meal delivery fulfillment centers.
India
FSSAI food safety enforcement and PLI scheme subsidies for food processing infrastructure open specification windows for energy-efficient equipment. Cold chain modernization concentrates in Maharashtra and Gujarat food processing corridors. Mumbai and Ahmedabad supermarket operators specify display cases with natural refrigerant compatibility.
Commercial Refrigeration Equipment Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the commercial refrigeration equipment market. The vendor base organizes around three strategic tiers: diversified industrial conglomerates with captive distribution networks, component specialists anchoring natural refrigerant transitions, and regional fabricators serving retrofit demand. Consolidation pressures concentrate in the supermarket specification segment where compliance complexity favors integrated solution providers. Competitive moves center on strategic partnerships for IoT-enabled monitoring platforms and geographic expansion into India cold chain modernization.
Within the diversified conglomerate tier, Carrier Global Corporation and Daikin Industries Ltd. occupy positions defined by scale and distribution breadth. Johnson Controls exemplifies the building systems integrator archetype, leveraging controls expertise across refrigeration and HVAC portfolios. Among component specialists, Danfoss anchors the natural refrigerant transition through compressor and valve specialization. Hussmann Corporation represents the regional dominant specialist, concentrating display case expertise in North American supermarket retrofits.
| Leading Market Players |
|---|
| Daikin Industries Ltd. |
| Johnson Controls |
| Hussmann Corporation |
| Dover Corporation |
| GEA Group AG |
| Carrier Global Corporation |
| Danfoss |
| AB Electrolux |
| Ali Group Srl |
| Others |
Supply Flow & Price Mechanics
CO2 transcritical system adoption replacing hydrofluorocarbon equipment simultaneously redraws component sourcing geography and compresses margin structures for mid-tier manufacturers without captive refrigerant valve production. This substitution dynamic relocates supply chain gravity toward European and East Asian component clusters while forcing pricing stratification between natural refrigerant-certified and legacy equipment tiers.
Pricing Analysis
Price spreads between German supermarket specifications and United States food service equipment exceed forty percent, driven by EU F-Gas Regulation compliance costs and UL safety certification tiering. Three-tier pricing structure across premium, standard, and economy levels separates CO2 transcritical systems from hydrofluoroolefin transitional units and remaining hydrofluorocarbon inventory. Cost compression in standard-tier equipment is intensifying because copper and aluminum commodity volatility squeezes heat exchanger producers. Quick-service restaurant chains with fifty-plus locations exhibit highest price sensitivity through consolidated national procurement, while German grocery retailers accept premium positioning for predictive maintenance bundling.
Supply Chain Analysis
Strait of Malacca transit underwrites compressor and electronic control shipments from East Asian manufacturing hubs to Middle Eastern and European assembly plants. Component concentration centers on China for copper tubing and printed circuit boards, Germany for precision valves and sensors, and the United States for polyurethane insulation foams. Raw material dependencies span aluminum for heat exchangers, copper for refrigerant lines, and specialized steel for compressor housings. Single-source vulnerability concentrates in CO2 transcritical compressor supply from Danish and Japanese specialists. Distribution runs through manufacturer-direct channels for supermarket chains and wholesale dealer networks for independent restaurants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as United States restaurant chains consolidate procurement from fragmented local dealers toward national manufacturer service agreements, compressing distributor margins and elevating direct accountability requirements.
For Market Incumbents: Consolidate aftermarket service networks through predictive maintenance platform acquisition, countering technician labor scarcity that extends equipment downtime for competitors. Deepen backward integration into refrigerant valve manufacturing to secure CO2 transcritical component supply against Danish specialist bottlenecks. Anchor capacity in Yangtze River Delta clusters to capture Chinese cold chain modernization tenders. For New Entrants and Emerging Players: Predictive maintenance software gaps where incumbent manufacturers under-serve independent restaurant operators present white-space entry points. Tier-two Chinese cities' convenience store expansion offers the most penetrable geography, with FSSAI enforcement creating specification windows for natural refrigerant-compatible display cases. Leasing-based refrigerant-as-a-service models bypass capex constraints dominating independent restaurant purchasing decisions. For Investors and Strategic Acquirers: EPA AIM Act enforcement reshapes the acquisition landscape toward natural refrigerant-certified equipment portfolios with installed IoT monitoring infrastructure. Long-term viability over the coming decade rests on regulatory compliance positioning rather than scale economics alone. Acquisition targets should display component specialization in CO2 transcritical systems and established UL safety listings. The signal to watch is technician training certification velocity across installer networks, indicating service capacity to match retrofit demand.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Platform Acquisition | Captures recurring revenue from risk-averse supermarket chains facing technician shortages. |
| CO2 Transcritical Compressor Backward Integration | Secures supply of critical components amid Danish and Japanese specialist concentration. |
| Yangtze River Delta Manufacturing Footprint | Positions for Chinese Ministry of Ecology and Environment efficiency standard tenders. |
| Refrigerant-as-a-Service Model Launch | Bypasses capex constraints in United States independent restaurant procurement consolidation. |
| UL Safety Certification Fast-Track Investment | Accelerates EPA SNAP approval timelines misaligned with customer replacement schedules. |
Methodological Framework
The analysis maps display case, walk-in cooler, blast freezer, and ice maker sub-sectors, each validated through refrigeration system engineers, supermarket procurement directors, food service distributor executives, and aftermarket service technicians. Primary interviews with these stakeholders combined trade association shipment data, EPA SNAP approval databases, EU F-Gas Regulation quota filings, and customs import records for copper and aluminum components. Secondary sources encompassed AHRI certification directories, EIA commercial building energy surveys, and Chinese Ministry of Ecology and Environment policy circulars. Bottom-up equipment unit estimates triangulated against top-down cold chain infrastructure investment flows.
Consistency checks validated volume and value outputs against AHRI shipment statistics, Eurostat commercial refrigeration trade flows, and Chinese customs machinery import categories. The analytical framework modeled product type, end-user segment, refrigerant technology, and application across the projection horizon. CAGRs derived from equipment replacement cycle compression under Kigali Amendment-aligned mandates and cold chain expansion in prepared meal delivery infrastructure. Forecast inputs incorporated technician labor availability indices and natural refrigerant safety code adoption timelines.
Underlying assumptions cover EPA AIM Act enforcement continuity, EU F-Gas Regulation quota trajectory, and Chinese dual carbon goal implementation pace, with deviation risk concentrated in certification timeline compression for new natural refrigerant systems. Forecasts reflect these conditions with acknowledged sensitivity to copper and aluminum commodity volatility and installer network scaling constraints. Practitioners should keep alternative scenarios live as regulatory divergence across United States, European Union, and Chinese jurisdictions evolves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Commercial RAC PD Compressor Market
HVAC Equipment
Wall Fan Coil Market
HVAC Equipment
Water Chiller Market
HVAC Equipment
Global Split Systems Market
HVAC Equipment
HVAC System Analyzer Market
HVAC Equipment
North America HVAC Filter Change Service Market
HVAC Equipment
US Compressed Air Treatment Equipment Market
HVAC Equipment
Shell and Tube Heat Exchangers Market
HVAC Equipment
India Residential Heat Pump Market
HVAC Equipment
Italy Commercial HVAC Market
HVAC Equipment
Asia Pacific Commercial HVAC Market
HVAC Equipment
HVAC Fan and Evaporator Coil Market
HVAC Equipment
Wall Hung Boilers Market
HVAC Equipment
Hot Water Circulator Pump Market
HVAC Equipment
GCC Water Heater Market
HVAC Equipment
Warming Cabinet Market