
 Europe Air Conditioning Equipment Market | 2026-2036
Europe Air Conditioning Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Air Conditioning Equipment Market Foresight
HVAC wholesaler networks across Southern Europe is reconfiguring as manufacturers bypass traditional distribution tiers to serve large installation contractors directly. Daikin Europe N.V. leverages its captive logistics infrastructure to control last-mile delivery in fragmented markets. Carrier Global Corporation anchors its position through deep relationships with pan-European facilities management providers. Mitsubishi Electric Europe B.V. competes by concentrating inverter R&D resources at its Dutch engineering center.
Europe air conditioning equipment encompasses electromechanical systems designed to regulate indoor temperature, humidity, and air quality through vapor-compression or absorption refrigeration cycles, typically operating with refrigerants below global warming potential thresholds mandated by regional phase-down schedules. These systems serve primary commercial and industrial functions including thermal comfort provision, process cooling for data centers and pharmaceutical manufacturing, and indoor air quality management in mechanically ventilated buildings. Split systems dominate residential and light commercial installations due to lower retrofit costs and minimal ductwork requirements, while central systems retain margin concentration in new-build commercial and healthcare applications where integrated building management compatibility commands pricing premiums. Inverter technology leads technology segmentation by shipment value as efficiency regulations tighten across member states, though smart-connected controls represent the fastest-adjacent growth vector as utilities deploy demand-response programs.
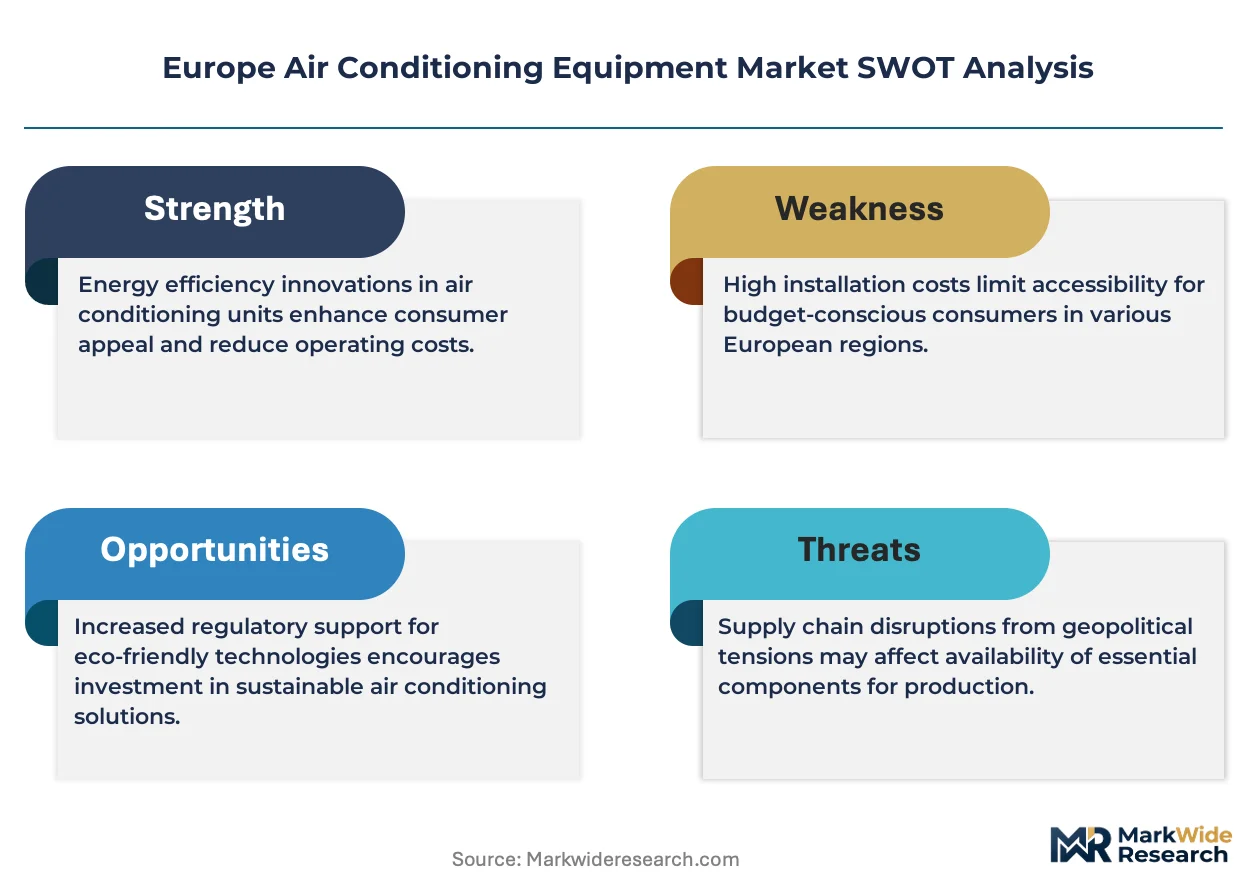
The EU F-Gas Regulation and Ecodesign Directive jointly determine refrigerant eligibility and minimum seasonal performance requirements, effectively filtering non-compliant products from market access while creating compliance cost advantages for scaled manufacturers. EMA and national environmental agencies coordinate enforcement timelines that compress transition windows for equipment lines using phased-down substances. Stakeholders must monitor refrigerant patent cliffs and heat pump technology convergence as dual threats to standalone cooling equipment margins.
Market Dynamics
The EU F-Gas Regulation's staged phase-down of hydrofluorocarbon refrigerants is compressing equipment replacement cycles and forcing manufacturers to re-engineer product lines around lower-GWP alternatives before compliance deadlines eliminate incumbent chemistries from market access.
Growth Catalysts
- Commercial building retrofit mandates:Germany's stringent building codes and green certification programs are accelerating equipment replacement in existing stock, creating pull-through demand for high-efficiency split systems and integrated heat pump configurations.
- Data center thermal load expansion:Hyperscale cloud infrastructure operators across the Netherlands and Ireland are specifying precision cooling systems with redundant capacity, driving unitary system shipments for mission-critical applications.
- Smart grid demand-response programs:Utilities in France and Spain are deploying connected thermostat incentives that favor inverter-equipped units with modulating capacity, reshaping residential replacement preferences toward connected-ready platforms.
Market Restraints
- Refrigerant input cost volatility:R-32 and R-454B supply constraints are compressing margins for mid-tier equipment as patent-protected formulations command premium pricing during the transition window.
- Installation labor scarcity:Certified F-gas handler shortages in Italy and Poland are extending project timelines and capping addressable market growth in Southern and Eastern Europe.
- Heat pump technology convergence:Reversible systems with cooling capability are displacing dedicated air conditioning units in Nordic residential markets where heating loads dominate annual runtime.
Strategic Opportunities
- Pharmaceutical process cooling:Belgian and Swiss manufacturing clusters are specifying validated cleanroom systems with continuous monitoring capabilities, opening premium segments beyond standard commercial applications.
- Direct-to-contractor distribution:Bypassing traditional wholesaler tiers to serve large installation contractors is capturing margin in fragmented Spanish and Portuguese markets where project scale justifies dedicated logistics.
- EU Green Deal renovation wave:National recovery fund allocations for building efficiency are creating subsidized demand channels in France and Italy that favor equipment with Ecodesign A+++ ratings.
Industry Challenges
- F-gas certification timeline compression:EMA-coordinated enforcement windows are forcing simultaneous product line transitions across multiple refrigerant platforms, straining R&D and inventory management capabilities.
- Legacy building management integration:BACnet and Modbus protocol fragmentation across existing commercial installations is complicating smart-connected control deployments and extending commissioning cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Air Conditioning Equipment Market |
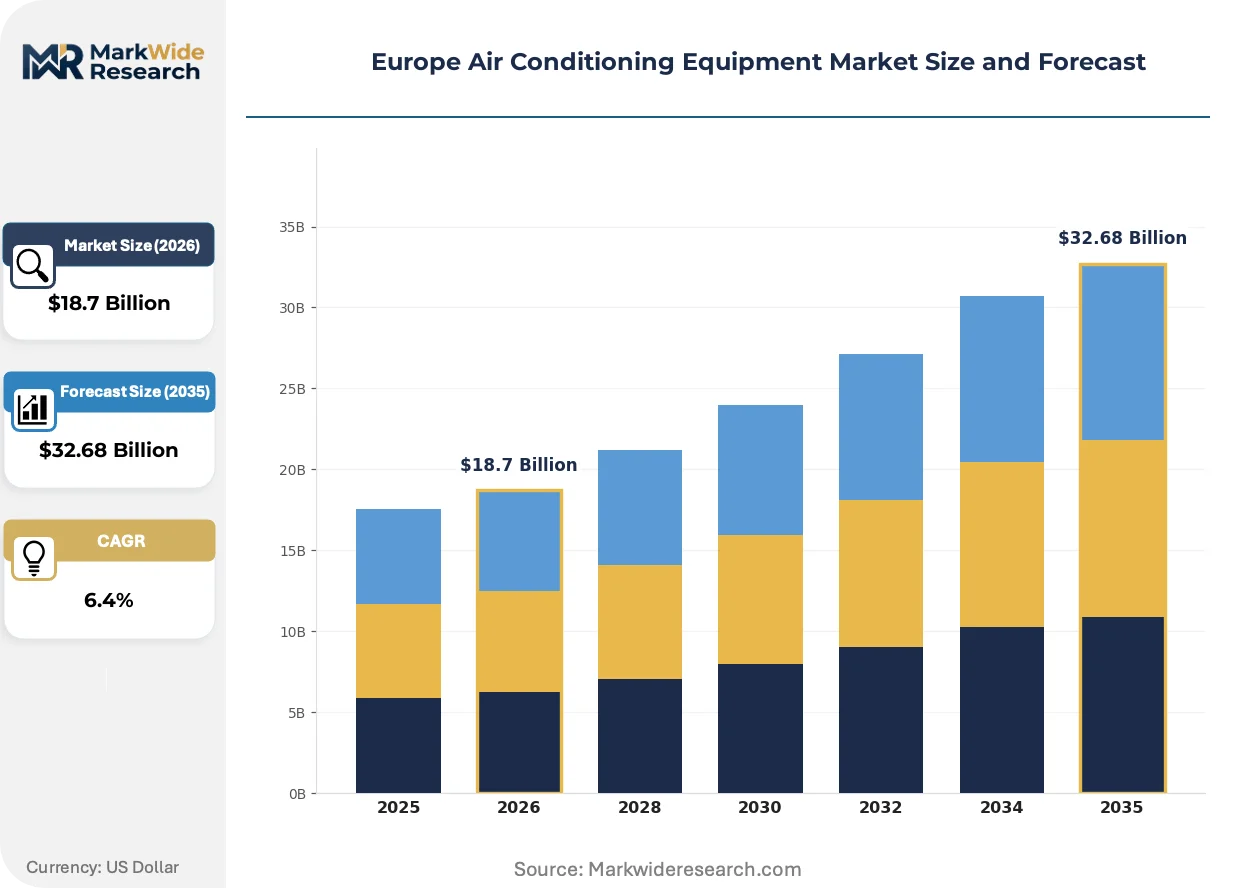
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Split Systems, Central Systems, Portable Units, Ductless Systems End User: Residential, Commercial, Industrial, Automotive Technology: Inverter, Non-Inverter, Smart Technology, Traditional Application: Cooling, Heating, Dehumidification, Air Purification |
| Companies Covered | Daikin Europe N.V., Mitsubishi Electric Europe B.V., Carrier Global Corporation, Johnson Controls-Hitachi Air Conditioning, Robert Bosch GmbH, Vaillant Group, LG Electronics Inc., Trane Technologies, Panasonic Europe Ltd, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Air Conditioning Equipment Market Shifts & Advancements
Refrigerant chemistry transitions and connected control architectures are converging to redefine equipment value propositions, with efficiency regulations and grid-interactive capabilities becoming primary purchase criteria rather than thermal performance alone.
Variable refrigerant flow systems with native heat recovery capability are collapsing the historical separation between heating and cooling equipment categories in mixed-use commercial buildings. Large German and Dutch office developers are specifying unified thermal platforms that eliminate redundant infrastructure. This convergence is compressing standalone chiller and boiler markets while expanding integrated system margins.
REACH and the EU F-Gas Regulation are jointly restricting hydrofluorocarbon availability and mandating lower-GWP alternatives in new equipment. Manufacturers are accelerating R-454B and R-1234ze adoption ahead of 2030 phase-down milestones. Medical and pharmaceutical cold chain applications face the steepest compliance curves due to stringent temperature validation requirements.
Building operators are consolidating vendor relationships and demanding outcome-based service agreements with guaranteed efficiency performance. Traditional break-fix maintenance contracts are losing share to integrated facility management providers in the UK and Nordic markets. Data center and healthcare verticals are driving this shift through total cost of ownership procurement frameworks.
Europe Air Conditioning Equipment Market Segmentation
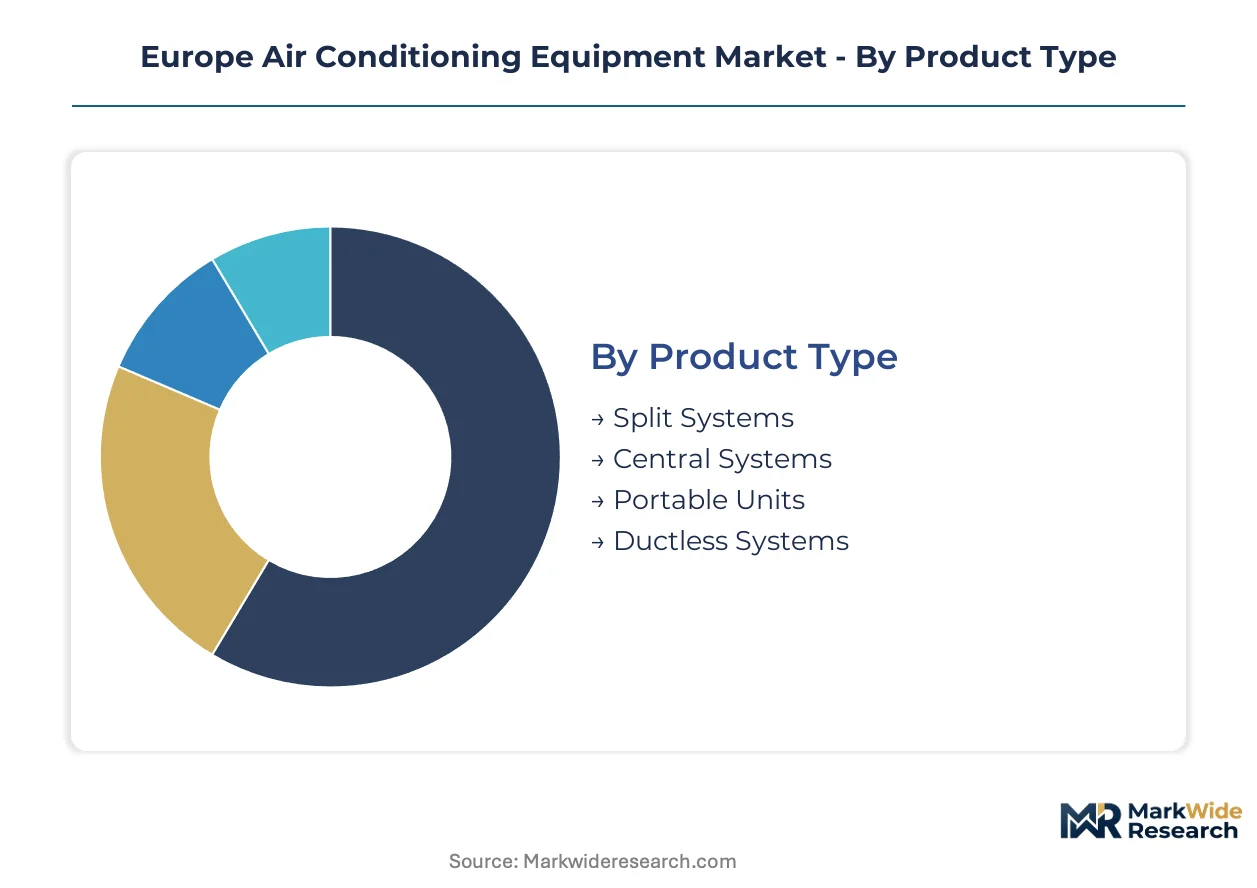
Equipment segmentation in the Europe air conditioning market reflects divergent retrofit economics, regulatory compliance windows, and end-user procurement sophistication. Understanding category boundaries clarifies where technology transitions and margin compression concentrate.
Product Type:
Installation constraints and building vintage determine product selection across residential retrofits, commercial new-builds, and industrial process applications.
- Split Systems:Vapor-compression units with separate indoor and outdoor components minimize structural modification requirements. German and French residential retrofits favor these systems where masonry construction complicates ductwork installation, though F-gas handler certification bottlenecks extend project timelines.
- Central Systems:Chiller-based architectures with integrated air handling serve large floorplates through hydronic distribution loops. New Dutch office developments specify these for building management compatibility, capturing margin through long-term service contracts despite higher upfront capital requirements.
- Portable Units:Self-contained mobile cooling for temporary or supplemental applications. Italian rental markets and Spanish hospitality seasonal demand absorb most regional volume.
- Ductless Systems:Multi-zone mini-splits serving discrete thermal zones without forced-air infrastructure. Belgian apartment renovations and Polish commercial fit-outs specify these where fire-rated shaft capacity limits central distribution.
The dominant share belongs to Split Systems, while Ductless Systems is closing the gap fastest.
End User:
Procurement sophistication and total cost of ownership frameworks separate customer tiers, with commercial and industrial buyers demanding performance guarantees unavailable in residential channels.
- Residential:Individual households purchasing through retail or contractor channels with limited technical specification involvement. French connected-thermostat subsidy programs and Italian recovery fund allocations steer replacement cycles toward inverter-equipped units.
- Commercial:Facilities managers and property developers operating under green certification mandates and utility demand-response requirements. UK and Nordic markets consolidate vendor relationships around outcome-based service agreements with guaranteed efficiency performance.
- Industrial:Process cooling for pharmaceutical manufacturing, data centers, and food processing with continuous operation requirements. Swiss and Belgian cleanroom specifications command premium pricing for validated systems with continuous monitoring capabilities.
- Automotive:OEM and aftermarket climate control for passenger and commercial vehicles. Supply relationships concentrate with tier-1 thermal system integrators serving German and Czech vehicle assembly plants.
Commercial procurement absorbs the highest equipment value per installation, though Industrial verticals sustain the steepest expansion trajectory through data center thermal load growth.
Technology:
Efficiency regulations and grid-interactive capabilities now dominate purchase criteria alongside thermal performance, compressing traditional equipment margins.
- Inverter:Variable-speed compressors modulating capacity to match thermal load rather than cycling on-off. Ecodesign Directive seasonal performance requirements and French utility demand-response programs make this the default specification for new residential and light commercial installations.
- Non-Inverter:Fixed-speed compression with binary operation. Survives only in price-sensitive replacement markets and temporary applications where capital constraints override operating cost considerations.
- Smart Technology:Connected controls with cloud-based monitoring, predictive maintenance alerts, and utility-integrated demand response. Spanish and Portuguese markets show fastest uptake where direct-to-contractor distribution accelerates platform deployment.
- Traditional:Basic electromechanical controls without connectivity or modulation capability. Restricted to economy-tier replacements in Southern European markets with less stringent enforcement of Ecodesign minimums.
Inverter platforms command the installed base majority, while Smart Technology integration is gaining share fastest through utility incentive alignment.
Application:
Functional requirements determine equipment specification complexity, with multi-mode systems capturing margin through reduced infrastructure redundancy.
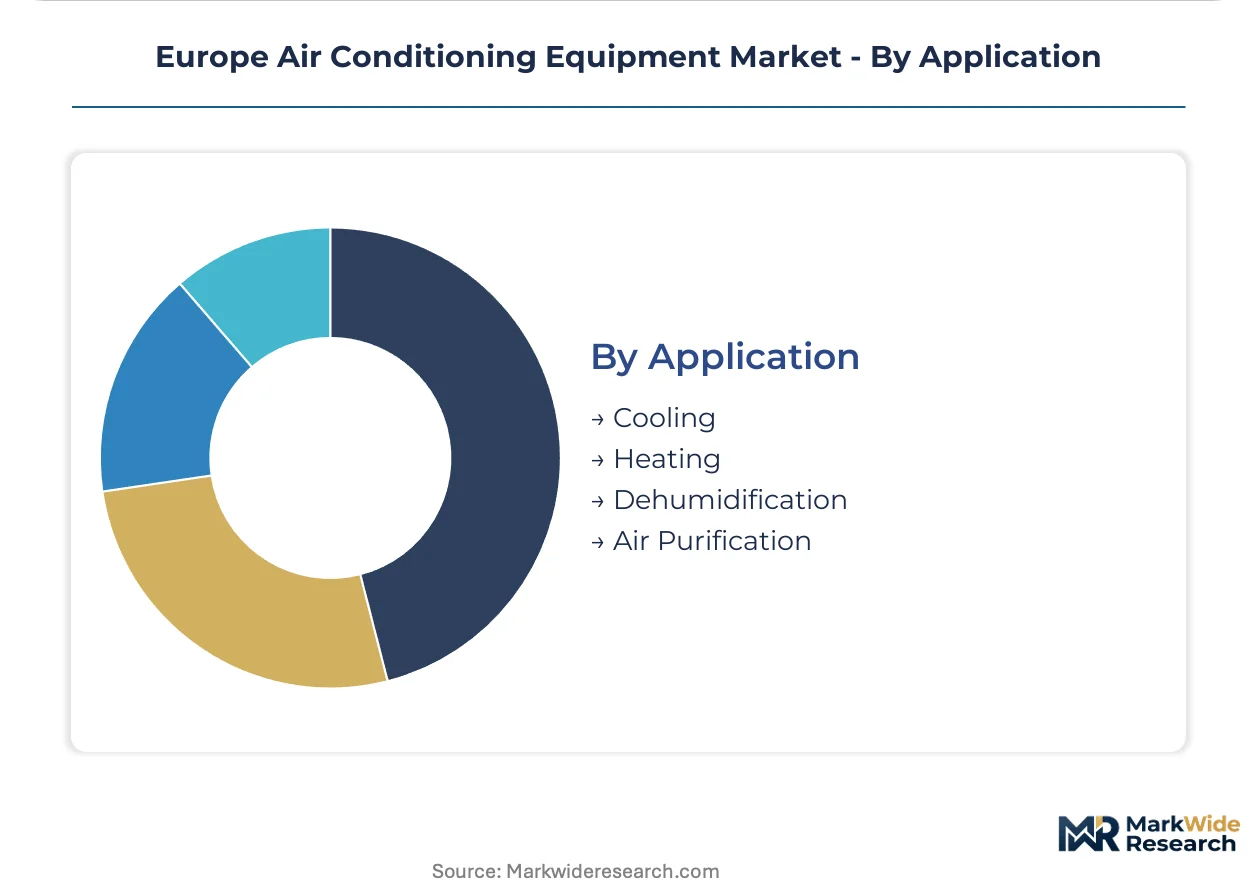
- Cooling:Dedicated temperature reduction for thermal comfort and process applications. Southern European peak load requirements and data center precision specifications sustain demand despite heat pump convergence pressures in Nordic markets.
- Heating:Reversible operation delivering thermal energy through refrigeration cycle reversal. German building code stringency and green certification programs accelerate displacement of standalone boilers in mixed-use developments.
- Dehumidification:Latent heat removal for moisture control in archives, museums, and pharmaceutical storage. Belgian and Swiss applications with stringent humidity validation requirements specify dedicated desiccant or refrigeration-based systems.
- Air Purification:Filtration and ionization integrated with thermal conditioning. Post-pandemic healthcare and hospitality specifications in Italy and France drive incremental specification of HEPA-capable air handling.
Cooling functionality retains the dominant application share, though Heating-capable reversible systems are climbing the fastest as building codes tighten across member states.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium equipment pricing in Germany exceeds Spanish market levels by substantial margins, reflecting divergent regulatory enforcement stringency and certification requirements across the region.
Germany
Stringent building codes and green certification programs drive replacement demand for high-efficiency split systems and integrated heat pump configurations. The federal KfW development bank channels renovation subsidies toward Ecodesign A+++ rated equipment. The Rhine-Ruhr metropolitan corridor concentrates commercial retrofit activity where facilities managers consolidate vendor relationships around outcome-based service agreements.
Netherlands
Hyperscale cloud infrastructure operators specify precision cooling systems with redundant capacity for mission-critical data center applications. The national government enforces strict F-gas handler certification timelines that compress equipment transition windows. Amsterdam's digital infrastructure cluster anchors regional demand for validated cleanroom systems with continuous monitoring capabilities.
France
Utility-deployed demand-response programs reshape residential replacement preferences toward connected-ready inverter platforms. The EU Green Deal renovation wave channels national recovery fund allocations into subsidized efficiency equipment procurement. The Paris-Saclay research corridor drives pharmaceutical process cooling specifications with stringent temperature validation requirements.
Italy
Certified F-gas handler shortages extend project timelines and cap addressable market growth in commercial retrofit channels. National building efficiency subsidies steer equipment selection toward connected thermostat-compatible platforms. Milan's pharmaceutical manufacturing cluster specifies premium cleanroom systems beyond standard commercial applications.
Spain
Direct-to-contractor distribution models capture margin in fragmented markets where project scale justifies dedicated logistics bypassing traditional wholesaler tiers. Regional utility incentive programs accelerate smart-connected control deployment in residential replacement cycles. Barcelona's hospitality sector sustains seasonal portable unit demand alongside permanent installation growth.
Europe Air Conditioning Equipment Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying compressors, heat exchangers, and electronic controls to branded assemblers. The vendor base concentrates around scaled manufacturers with captive logistics infrastructure and pan-European service networks. Three archetypes dominate: diversified industrial conglomerates with HVAC divisions, pure-play climate equipment specialists, and electronics manufacturers leveraging inverter R&D synergies. Competitive positioning hardens through backward integration into refrigerant supply chains and exclusive distribution arrangements with large installation contractors.
Among Japanese-origin platform integrators, Daikin Europe N.V., Mitsubishi Electric Europe B.V., and Panasonic Europe Ltd exemplify the specialist archetype with concentrated European engineering resources. These entities occupy positions where inverter technology leadership and captive logistics infrastructure create defensive moats against mid-tier competition. Their market presence anchors the premium equipment tier where efficiency regulations and smart grid integration requirements filter out non-compliant alternatives.
| Leading Market Players |
|---|
| Daikin Europe N.V. |
| Mitsubishi Electric Europe B.V. |
| Carrier Global Corporation |
| Johnson Controls-Hitachi Air Conditioning |
| Robert Bosch GmbH |
| Vaillant Group |
| LG Electronics Inc. |
| Trane Technologies |
| Panasonic Europe Ltd |
| Others |
Supply & Pricing Matrix
Compressor manufacturing concentration in China and Japan feeds directly into margin distribution across European distribution tiers, with captive production of rotary and scroll compressors allowing integrated manufacturers to extract premium pricing on inverter-equipped systems while mid-tier assemblers absorb refrigerant cost volatility.
Pricing Analysis
Configured-to-order pricing for validated pharmaceutical cleanroom systems commands substantial premiums over standard commercial split-system transactions. Three-tier pricing structure across premium, standard, and economy levels separates A+++ Ecodesign-rated equipment with smart-grid connectivity from basic inverter units and fixed-speed replacements. Pricing pressure stems from R-32 and R-454B supply constraints as patent-protected formulations command premium pricing during the F-gas transition window. Residential replacement buyers through retail channels exhibit highest price sensitivity, while pharmaceutical and data center procurement teams prioritize total cost of ownership over upfront capital.
Supply Chain Analysis
Upstream refrigerant and compressor feedstock flows concentrate manufacturing dependency in China, Japan, and South Korea for critical rotating components and electronic expansion valves. European equipment assembly draws from copper tube mills in Germany and Poland, aluminum fin stock from Belgium, and rare-earth magnetic materials for high-efficiency motors sourced from Chinese processing facilities. Single-source vulnerability around semiconductor-based inverter controllers creates supply chain risk as automotive and industrial demand competes for foundry capacity. Distribution runs through consolidating wholesaler networks in Northern Europe and direct-to-contractor channels in fragmented Southern European markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Outcome-based service agreements with guaranteed efficiency performance are expanding faster than hardware shipments, as UK and Nordic facilities managers consolidate vendor relationships around long-term thermal performance contracts rather than transactional equipment procurement.
For Market Incumbents: Entrench market position through captive logistics infrastructure controlling last-mile delivery in fragmented Spanish and Portuguese markets, while accelerating backward integration into lower-GWP refrigerant supply chains before EMA-coordinated enforcement windows eliminate incumbent chemistries. Heat pump technology convergence poses substitution threat to standalone cooling equipment margins; defend through integrated system platforms with native heat recovery capability specified by German and Dutch office developers.
For New Entrants and Emerging Players: Build out specialist capabilities in pharmaceutical process cooling for Belgian and Swiss manufacturing clusters, where validated cleanroom systems with continuous monitoring capabilities command premium pricing beyond standard commercial applications. Southern European markets show penetrable whitespace where certified F-gas handler shortages extend project timelines for established competitors; enter through direct-to-contractor distribution models capturing margin in fragmented markets where project scale justifies dedicated logistics.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed HVAC service aggregators consolidating maintenance contracts across UK and Nordic markets. Long-term viability hinges on recurring revenue attachment rates exceeding hardware replacement cycles; target platforms with installed base visibility enabling outcome-based service transitions. Watch for refrigerant patent cliff timing as inflection indicator compressing margins for non-integrated assemblers dependent on licensed formulations.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Refrigerant Supply | Captures margin from R-454B and R-1234ze formulations ahead of EU F-Gas phase-down milestones. |
| Direct-to-Contractor Distribution Expansion | Bypasses wholesaler tiers in fragmented Spanish and Portuguese markets where project scale justifies dedicated logistics. |
| Smart-Connected Control Platform Deployment | Aligns with French and Spanish utility demand-response programs reshaping residential replacement preferences. |
| Pharmaceutical Cleanroom System Validation | Opens premium segments in Belgian and Swiss clusters with stringent temperature monitoring requirements. |
| Integrated Heat Recovery System Development | Collapses historical separation between heating and cooling categories in German mixed-use commercial developments. |
Research Methodology
The analysis maps split systems, central chillers, ductless multi-zone units, and portable equipment, each validated through facilities managers at commercial property developers, pharmaceutical plant engineers, data center infrastructure heads, and HVAC contractor business owners. Primary interview data triangulates against EMA enforcement timelines, EU F-Gas Regulation phase-down schedules, Ecodesign Directive compliance databases, and national building efficiency subsidy disclosures. Bottom-up equipment shipment tracking reconciles with top-down construction spend and retrofit activity indices.
Assumptions held fixed include regulatory enforcement timelines under REACH and the EU F-Gas Regulation, while refrigerant chemistry transition speeds and heat pump substitution rates were varied across scenarios. The projection horizon models equipment type, end-user vertical, technology tier, and application mode as core segmentation dimensions, with regional regulatory cluster and installation labor availability as secondary stratifiers. CAGRs derive from fitted growth curves applied to validated base-year estimates, incorporating data center thermal load expansion and commercial building retrofit mandate intensity as industry-specific demand drivers.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese compressor manufacturers into European system assembly would shift outcomes through price disruption in standard equipment tiers. Cross-checking against national customs data for refrigerant and compressor import volumes is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Europe Air to Water Heat Pump Market
HVAC Equipment
Commercial Refrigeration Equipment Market
HVAC Equipment
US HVAC Services Market
HVAC Equipment
Cooling Tower Market
HVAC Equipment
North America HVAC Filter Change Service Market
HVAC Equipment
Europe Residential Fan Coil Convectors Market
HVAC Equipment
United Kingdom Commercial HVAC Market
HVAC Equipment
Industrial Heating Equipment Market
HVAC Equipment
Ceiling Cassettes Market
HVAC Equipment
Louver Dampers Market
HVAC Equipment
Desert Air Cooler Market
HVAC Equipment
Europe HVAC Equipment Market
HVAC Equipment
Thermocompressors Market
HVAC Equipment
Global Variable Refrigerant Flow (VRF) Market
HVAC Equipment
United Kingdom Heat Pumps Market
HVAC Equipment
Asia-Pacific Heating Equipment Market