
 Desert Air Cooler Market | 2026-2036
Desert Air Cooler Market Size, Share, and Industry Trends Forecast 2026-2036
Desert Air Cooler Market Outlook
BEE star-rating certification is reorganizing competitive access across the desert air cooler landscape. Symphony Limited leverages its captive distribution network to dominate organized retail channels in western India. Voltas sustains manufacturing scale through backward integration into sheet-metal and fan-motor production. Bajaj Electricals anchors its position via brand recognition in tier-2 and tier-3 cities where replacement cycles drive volume.
Desert air coolers are evaporative cooling devices engineered around honeycomb cellulose pads with airflow capacities ranging from 3,000 to 20,000 cubic meters per hour, designed to lower dry-bulb temperatures through water-phase-change heat absorption in low-humidity environments. Portable coolers command the largest volume share among product types due to apartment-friendly footprints and sub-$200 price points, while industrial coolers capture disproportionate margin pools from factory and warehouse deployments. The residential end-user segment remains structurally mature in northern India but shows expansion potential in institutional buyers across Middle Eastern geographies where district cooling infrastructure remains underdeveloped.
India's BIS mandates minimum energy performance standards for room air coolers, while the country's PLI scheme for white goods manufacturing incentivizes domestic component sourcing above 60 percent value thresholds. The UAE's ESMA efficiency regulations and Saudi Arabia's SASO quality marks create parallel compliance corridors for exporters targeting Gulf Cooperation Council procurement channels. Stakeholders must monitor evaporative pad material innovations and water-recirculation efficiency gains as regulatory thresholds tighten and commercial buyers prioritize total-cost-of-ownership metrics over upfront equipment pricing.
Market Dynamics
Evaporative pad material innovation is fragmenting competitive positioning as cellulose honeycomb designs face displacement from engineered polymer alternatives with superior water retention and structural durability in India's western states.
Growth Catalysts
- PLI Scheme Incentives:India's production-linked incentive scheme for white goods manufacturing accelerates domestic component sourcing above 60 percent value thresholds, reducing import dependency for fan motors and pump assemblies.
- Institutional Procurement in the Middle East:District cooling infrastructure gaps across Saudi Arabia and the UAE drive commercial adoption of high-capacity industrial desert coolers for warehouse and factory deployments.
- Honeycomb Cellulose Pad Advances:Cross-fluted pad geometries with enhanced wetting efficiency expand addressable temperature differentials in extreme arid conditions above 45 degrees Celsius dry-bulb.
Market Restraints
- Input Cost Volatility:ABS plastic resin and galvanized sheet steel prices fluctuate with petrochemical feedstock cycles, compressing margin stability for enclosure and tank fabricators.
- Climate Dependency:Evaporative cooling effectiveness collapses above 70 percent relative humidity, structurally limiting addressable geographies to true desert and semi-arid zones.
- Water Scarcity Constraints:Municipal supply restrictions in Rajasthan and Gujarat during peak summer months constrain continuous operation for residential units without storage tank modifications.
Strategic Opportunities
- Solar-Evaporative Hybrid Integration:DC motor compatibility with photovoltaic arrays opens off-grid deployment across rural Maharashtra where grid reliability remains intermittent.
- IoT-Enabled Predictive Maintenance:Sensor-embedded coolers with water-level and pump-failure alerts create recurring revenue streams through subscription monitoring services for commercial estates.
- SASO Quality Mark Penetration:Saudi Arabia's standardization body certification creates compliant access corridors for Indian exporters targeting Gulf Cooperation Council institutional procurement channels.
Industry Challenges
- Skilled Technician Scarcity:Evaporative pad replacement and pump calibration require trained service personnel, yet vocational certification programs remain underdeveloped in tier-3 Indian cities.
- BIS Certification Timelines:Bureau of Indian Standards testing protocols for energy performance labeling extend product launch cycles by 4-6 months, delaying seasonal market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Desert Air Cooler Market |
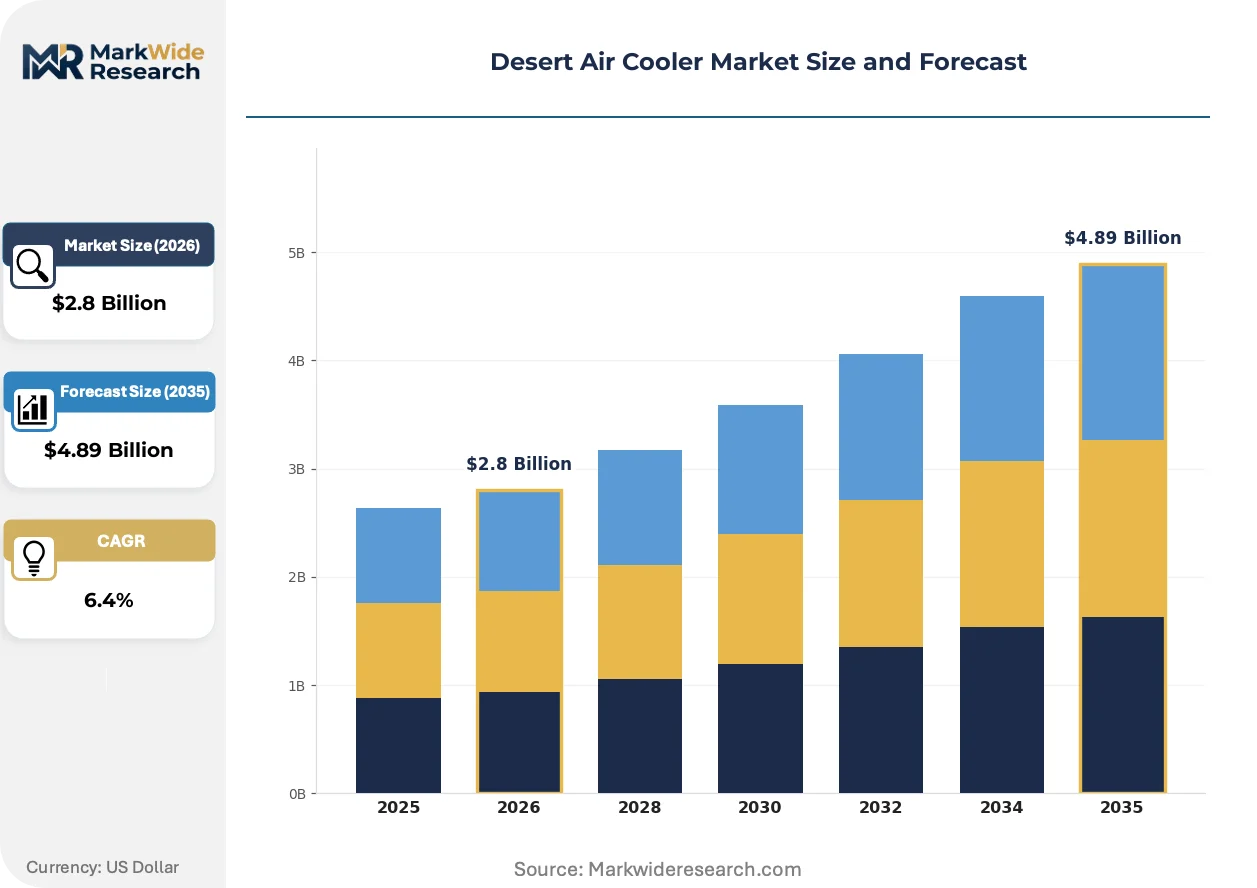
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Coolers, Window Coolers, Rooftop Coolers, Industrial Coolers End User: Residential, Commercial, Industrial, Institutional Cooling Technology: Evaporative Cooling, Direct Cooling, Indirect Cooling, Dual Cooling Distribution Channel: Online Retail, Offline Retail, Wholesale, Direct Sales |
| Companies Covered | Kenstar, Yika, Symphony Limited, Daikin, Panasonic, Bajaj Electricals, Midea, Champion Cooler, Voltas, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Desert Air Cooler Market Strategic Shifts
Material science breakthroughs and regulatory efficiency mandates are compressing traditional equipment lifecycles while opening premium positioning for connected, sensor-enabled cooling platforms.
Advanced polymer-based evaporative media is fragmenting the incumbent cellulose pad supply base. These engineered materials deliver 40 percent longer service intervals and resist mineral scaling in hard-water conditions. Commercial buyers in Saudi industrial zones are specifying polymer pads for continuous-duty applications. The technology is fragmenting procurement patterns as total-cost-of-ownership calculations displace upfront price sensitivity in specification decisions.
India's BIS energy-efficiency labeling mandates are tightening minimum performance thresholds for room air coolers. The regulation forces redesign of fan-motor assemblies and water-distribution systems to achieve higher cubic-meters-per-hour ratings per watt consumed. Western Indian manufacturers are consolidating testing laboratory partnerships to accelerate certification throughput before seasonal demand peaks.
Direct-to-installer digital platforms are compressing traditional distributor margins in tier-2 cities. E-commerce marketplaces with same-day delivery capabilities are capturing replacement-unit purchases from established electrical goods retailers. This channel rotation is most visible in Gujarat's Ahmedabad and Surat urban clusters where smartphone penetration among contractor networks exceeds national averages.
Desert Air Cooler Market Segmentation
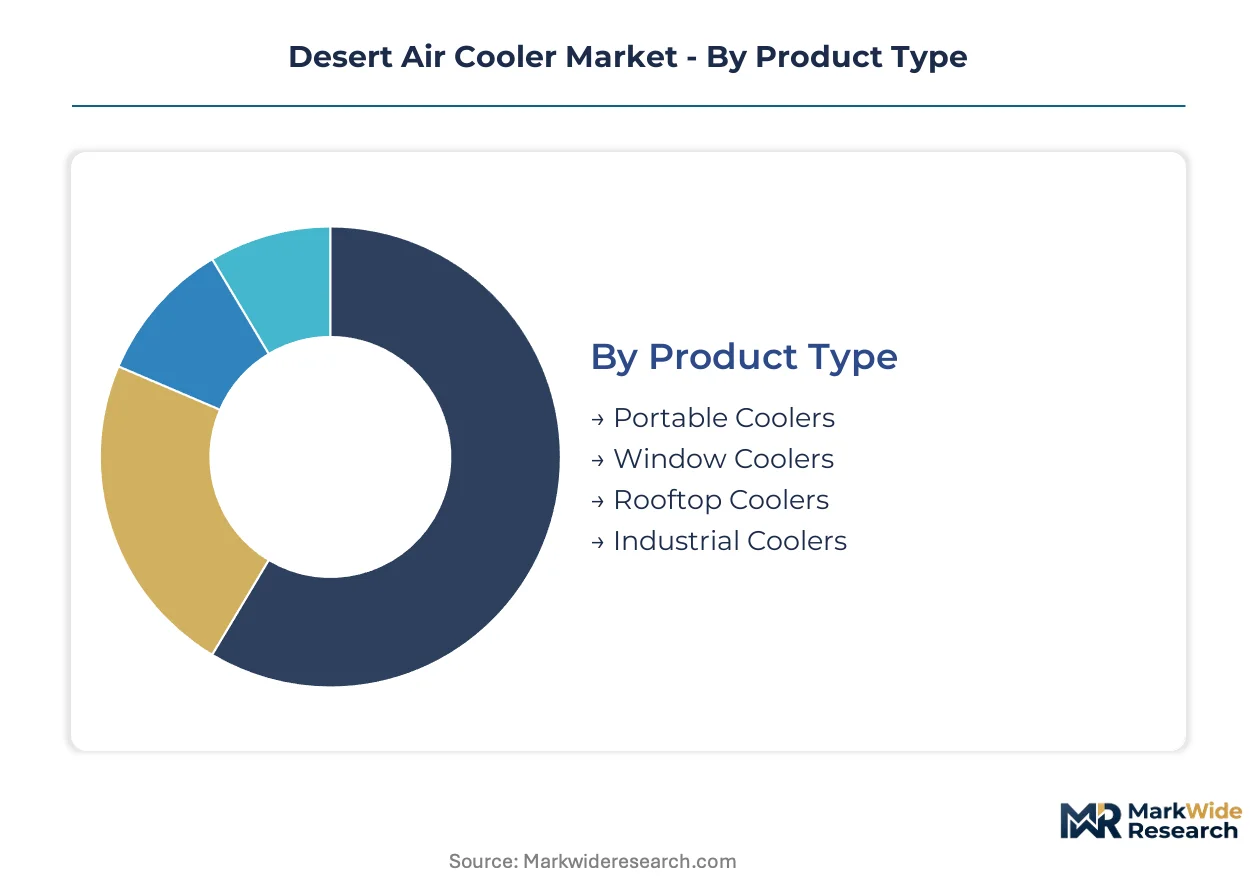
Desert air cooler segmentation reveals divergent margin structures across product architectures and procurement channels. Cooling technology choices determine service interval economics, while distribution channel selection shapes working capital intensity for manufacturers targeting institutional buyers versus residential replacement cycles.
Product Type:
Margin pools concentrate in industrial and rooftop installations where specification engineering and installation services add value beyond hardware.
- Portable Coolers:Compact units with 3,000–8,000 cubic meters per hour airflow, constructed from ABS plastic enclosures with castor-mounted mobility. Demand concentrates in Gujarat's Ahmedabad and Surat apartment clusters where tenant turnover drives annual replacement cycles and sub-$200 price points dominate volume.
- Industrial Coolers:Fixed installations delivering 15,000–20,000 cubic meters per hour through galvanized steel housings with three-phase motor drives. Saudi factory procurement in Riyadh and Jeddah industrial zones specifies these units for continuous-duty warehouse cooling where district cooling infrastructure remains absent.
- Window Coolers:Through-wall units with axial fan configurations for permanent residential installation.
- Rooftop Coolers:Central ducted systems with down-discharge configurations for commercial building integration.
Industrial coolers hold installed capacity. Portable units are rotating up the share rankings.
End User:
Application type dictates equipment specification rigor and total-cost-of-ownership calculation sophistication.
- Residential:Individual household purchases prioritizing noise reduction and compact footprints for balcony or window mounting. Rajasthan's Jaipur and Jodhpur urban households drive seasonal demand spikes during pre-monsoon months when dry-bulb temperatures exceed 45 degrees Celsius.
- Industrial:Factory and warehouse operators specifying continuous-duty equipment with polymer evaporative pads for mineral scaling resistance. UAE logistics hubs in Dubai's Jebel Ali Free Zone deploy these units for ambient temperature control in high-bay storage facilities.
- Commercial:Retail and hospitality operators with intermittent duty cycles and aesthetic enclosure requirements.
- Institutional:Government and educational procurement with formal tender processes and extended warranty demands.
Industrial end users anchor specification standards. Institutional procurement is climbing the fastest.
Cooling Technology:
Technology selection determines water consumption rates and addressable humidity ranges.
- Evaporative Cooling:Direct water-phase-change systems using cellulose or polymer pads with 80–90 percent saturation efficiency. Maharashtra's Nashik and Nagpur manufacturing corridors adopt these systems for cost-sensitive production floor cooling where relative humidity remains below 50 percent.
- Indirect Cooling:Heat-exchanger configurations separating process air from wet scavenger air, enabling operation up to 60 percent relative humidity. Saudi Arabia's coastal Dammam industrial zone specifies these units for humidity-buffered environments.
- Direct Cooling:Simplified single-pass water spray configurations for lowest first-cost deployment.
- Dual Cooling:Hybrid architectures combining evaporative pre-cooling with mechanical refrigeration for extreme condition fallback.
Evaporative cooling holds installed capacity. Indirect systems are expanding most quickly.
Distribution Channel:
Channel selection shapes customer acquisition economics and post-sale service attachment rates.
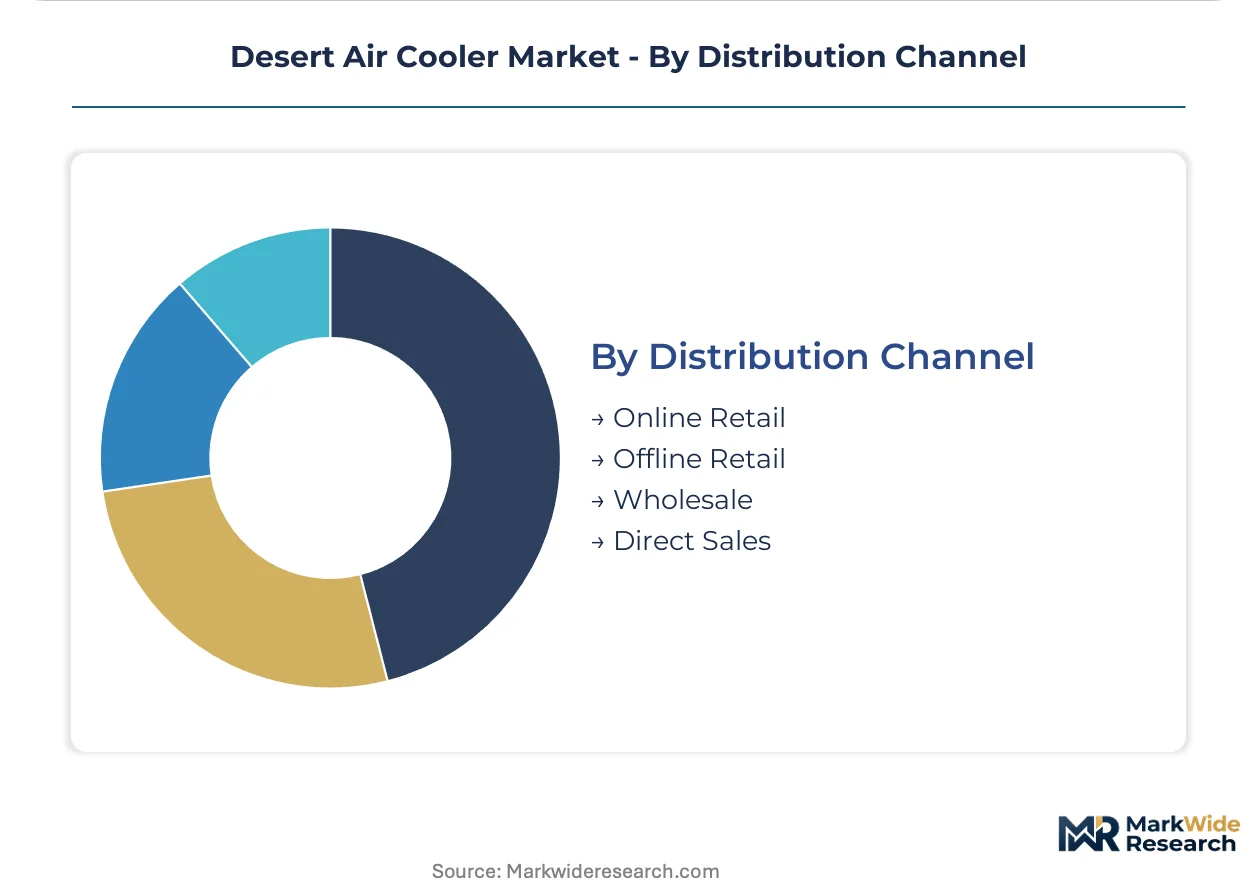
- Online Retail:E-commerce platforms with same-day delivery capabilities capturing replacement purchases in Gujarat's tier-2 cities. Contractor networks with smartphone penetration above national averages drive specification-through-mobile behavior.
- Offline Retail:Established electrical goods retailers with demonstration floors and seasonal inventory buildup. Rajasthan's organized retail chains in Jaipur maintain pre-season stock positions for immediate availability.
- Wholesale:Bulk procurement corridors for contractor and project-based volume.
- Direct Sales:Manufacturer-to-institutional relationships for specification-engineered industrial deployments.
Offline retail holds installed capacity. Online channels are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Jebel Ali Port's container throughput underwrites the UAE's position as a Gulf distribution hub for evaporative cooling equipment bound for Saudi industrial zones and African markets.
India
Rajasthan's pre-monsoon heat waves exceeding 45 degrees Celsius drive residential replacement cycles, while Gujarat's manufacturing corridor anchors component supply chains. BIS energy-efficiency labeling mandates force redesign of fan-motor assemblies ahead of seasonal demand peaks. Symphony Limited dominates organized retail channels across Ahmedabad and Surat urban clusters through captive distribution networks.
Saudi Arabia
Riyadh and Jeddah industrial zones specify continuous-duty desert coolers for warehouse cooling where district cooling infrastructure remains absent. SASO quality mark certification creates compliant access corridors for Indian exporters targeting Gulf Cooperation Council procurement channels. The Eastern Province's Dammam industrial zone adopts indirect cooling configurations for humidity-buffered coastal environments.
United Arab Emirates
Dubai's Jebel Ali Free Zone deploys high-capacity industrial units for ambient temperature control in high-bay logistics facilities. ESMA efficiency regulations parallel India's BIS standards, creating dual compliance requirements for equipment suppliers. Abu Dhabi's commercial construction pipeline specifies rooftop ducted systems for new retail and hospitality developments.
United States
Southwestern states including Arizona and New Mexico deploy portable evaporative units for residential cooling in low-humidity desert climates. EPA water-efficiency guidelines influence pump and recirculation system specifications for municipal procurement. Phoenix metropolitan area contractors source replacement pads through direct-to-installer digital platforms with same-day delivery capabilities.
Australia
Western Australia's mining camps and remote communities rely on off-grid solar-evaporative hybrid systems where grid reliability remains intermittent. The country's national energy regulator mandates minimum performance standards for cooling equipment in commercial buildings. Perth's outer metropolitan development corridors specify permanent window-mount units for new residential construction.
Desert Air Cooler Market Competitive Environment
Listed leaders compete with private specialists across distribution channel access and manufacturing scale. The vendor base fragments across three tiers: integrated appliance conglomerates with captive component production, specialist evaporative cooling manufacturers with regional brand recognition, and contract fabricators serving private-label retailers. Strategic archetypes include backward-integrated sheet-metal producers, brand-anchored electrical goods distributors, and polymer pad technology licensors. Dominant competitive moves encompass M&A-driven distribution network consolidation and capacity expansion into BIS-certified testing laboratory partnerships.
Among India-based electrical goods conglomerates, Symphony Limited, Voltas, and Bajaj Electricals occupy positions across distinct competitive vectors. Symphony exemplifies brand-anchored distribution dominance through organized retail channel control in western Indian states. Voltas represents backward-integrated manufacturing scale through in-house production of sheet-metal enclosures and fan-motor assemblies. Bajaj Electricals sits within the tier-2 and tier-3 city penetration archetype, where replacement cycle volume and brand recognition drive specification decisions among contractor networks.
| Leading Market Players |
|---|
| Kenstar |
| Yika |
| Symphony Limited |
| Daikin |
| Panasonic |
| Bajaj Electricals |
| Midea |
| Champion Cooler |
| Voltas |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts between Rajasthan-based sheet-metal fabricators and Gujarat enclosure manufacturers lock in supply access and price visibility through seasonal demand cycles. These arrangements insulate procurement costs from petrochemical feedstock volatility while locking working capital into pre-monsoon inventory builds.
Pricing Analysis
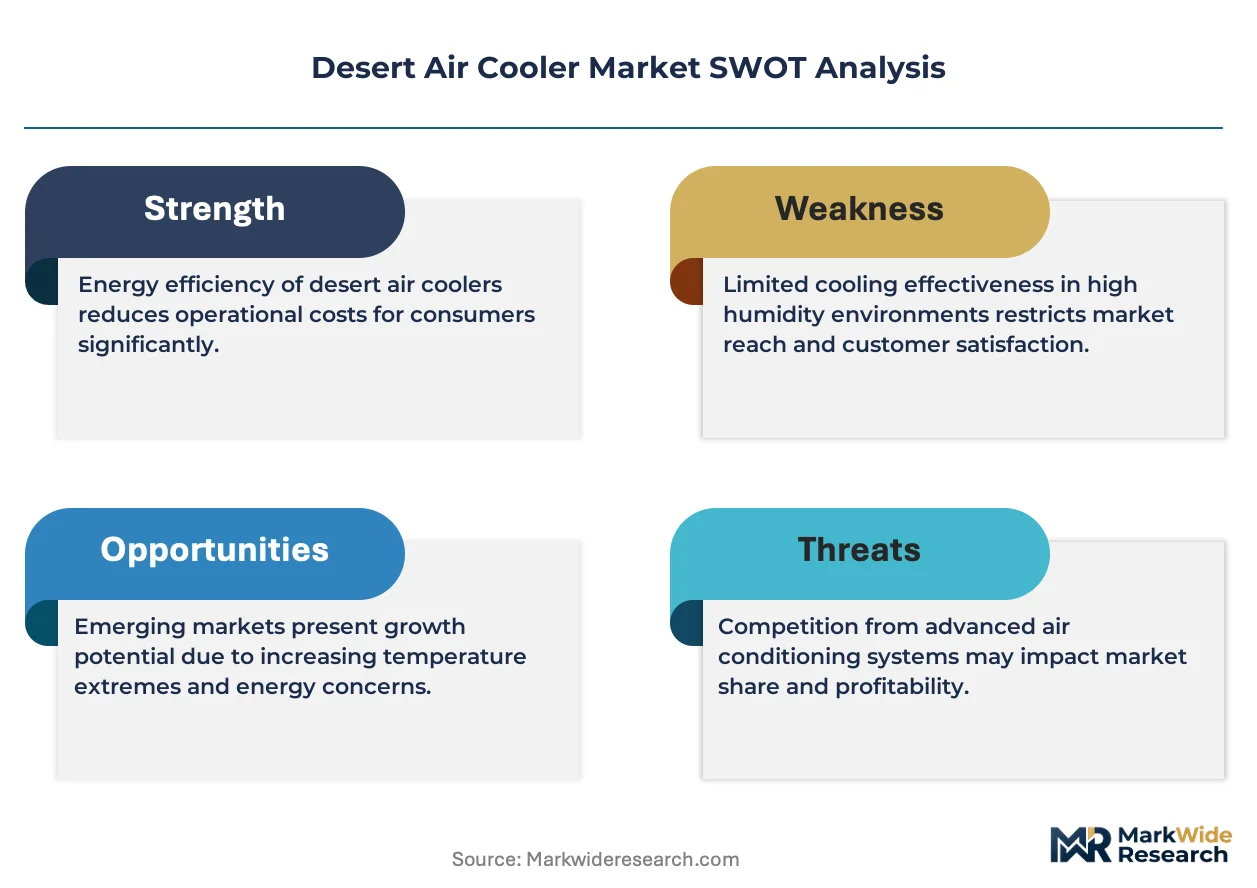
Volume-discount tiering structures separate industrial procurement above 500 units from residential replacement purchases below 50 units. BEE star-rating certification creates price differentiation between compliant and non-compliant equipment. Cost compression in the portable segment is intensifying as e-commerce platforms displace traditional distributor margins. Contractor networks in tier-2 cities exhibit highest price sensitivity, while Saudi industrial buyers prioritize total-cost-of-own calculations.
Supply Chain Analysis
India and China anchor global production of honeycomb cellulose pads and ABS plastic resin for cooler enclosures. Fan-motor assemblies draw from domestic PLI-incentivized facilities above 60 percent value thresholds. Single-source vulnerability concentrates in engineered polymer pad imports for continuous-duty applications. Distribution runs through Jebel Ali Port for Gulf Cooperation Council re-export corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized evaporative pad calibration expertise represents the binding constraint on service network expansion, with vocational certification programs failing to match deployment scale in tier-3 Indian cities.
For Market Incumbents: Compound backward integration into sheet-metal stamping and fan-motor production to defend margin stability against ABS resin price volatility. Secure BIS testing laboratory partnerships to compress certification timelines ahead of seasonal demand peaks. Channel control through captive distribution networks in western Indian states remains the critical defensive lever against e-commerce platform erosion. For New Entrants and Emerging Players: Lead with solar-evaporative hybrid configurations targeting rural Maharashtra where grid reliability gaps persist. The institutional procurement segment across Saudi Arabia and UAE warehouse operators offers lowest competitive density. Specification engineering partnerships with district cooling infrastructure gaps unlock direct sales access without distributor margin stacking. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among IoT-enabled predictive maintenance platforms for commercial estate deployments. Long-term viability hinges on polymer pad technology licensors with continuous-duty validation in hard-water conditions. Watch for inflection signals in SASO quality mark penetration rates among Indian exporters targeting Gulf procurement channels.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sheet-Metal Production | Voltas sustains margin stability through captive enclosure fabrication in Gujarat manufacturing corridors. |
| BIS Testing Laboratory Partnership | Symphony Limited compresses certification cycles to capture pre-monsoon seasonal demand peaks. |
| SASO Quality Mark Certification | Indian exporters unlock compliant access to Saudi Arabia's Riyadh and Jeddah industrial procurement channels. |
| IoT-Enabled Predictive Maintenance Platform | Sensor-embedded coolers generate subscription revenue streams from UAE commercial estate operators. |
| Polymer Evaporative Pad Technology Licensing | Engineered materials extend service intervals for Saudi continuous-duty warehouse applications. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of BIS certification registries, PLI scheme disbursement records, and Gulf Cooperation Council trade manifests. Interviews with plant engineers at Maharashtra manufacturing corridors, procurement leads at UAE logistics hubs, and aftermarket service heads in Rajasthan tier-3 cities informed demand calibration. Secondary validation drew from customs export data, ESMA efficiency compliance filings, and Saudi SASO quality mark databases. Bottom-up unit shipment estimates triangulated against top-down value projections.
Segmentation dimensions modeled span product architecture, cooling technology type, end-user application, and distribution channel across the analysis window. CAGRs derived from regression analysis of historical shipment trajectories and elasticity-adjusted demand curves. Industry-specific forecast inputs include evaporative pad replacement cycle frequencies and municipal water supply restriction schedules in western Indian states.
The analysis sits within stated boundaries; outcomes outside sustained arid climate conditions and PLI incentive continuity would require recalibration. Forecasts reflect assumptions on polymer pad adoption rates and BIS energy-efficiency threshold tightening. Recalibration cycles align with material shifts in petrochemical feedstock pricing and Gulf Cooperation Council procurement regulation amendments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Middle East and Africa Commercial HVAC Market
HVAC Equipment
United States HVAC Equipment Market
HVAC Equipment
Latin America Heat Exchanger Market
HVAC Equipment
Kitchen Hood System Market
HVAC Equipment
Fabric Ducting Market
HVAC Equipment
Global Fan Coil Unit Market
HVAC Equipment
Variable Refrigerant Flow (VRF) System Market
HVAC Equipment
Positive Displacement Blowers Market
HVAC Equipment
Hydro Chillers Market
HVAC Equipment
Commercial Refrigeration Equipment Market
HVAC Equipment
Fabric Air Ducts Market
HVAC Equipment
United States HVAC Equipment and Services Market
HVAC Equipment
High Pressure Heat Exchanger Market
HVAC Equipment
Automatic Ducting Machine Market
HVAC Equipment
Refrigerant Compressors Market
HVAC Equipment
Underfloor Heating Market