
 Industrial Refrigeration Equipment Market | 2026-2036
Industrial Refrigeration Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Refrigeration Equipment Market Outlook
Multi-source procurement for compressors and condensers is pivoting toward vertically integrated suppliers with captive component manufacturing. Johnson Controls leverages its controls technology leadership to bundle hardware with building automation software. Emerson Electric Co. sustains engineering intensity in vapor compression systems for cold storage facilities. GEA Group Aktiengesellschaft anchors European process cooling installations through specialized heat exchanger design.
Industrial refrigeration equipment comprises engineered systems that extract heat from commercial and industrial processes using refrigerants circulated through compressors, condensers, and evaporators operating at specified pressure-temperature envelopes, typically maintaining spaces or fluids between -40°C and 15°C for preservation, processing, or safety purposes. Compressors and condensers command the largest installed base due to their centrality in vapor compression architectures, while controls represent the fastest-upgrading segment as facilities retrofit for predictive maintenance and energy optimization. Cold storage applications absorb the majority of capital expenditure, though blast freezing commands premium pricing for rapid temperature pull-down requirements in seafood and prepared meal processing.
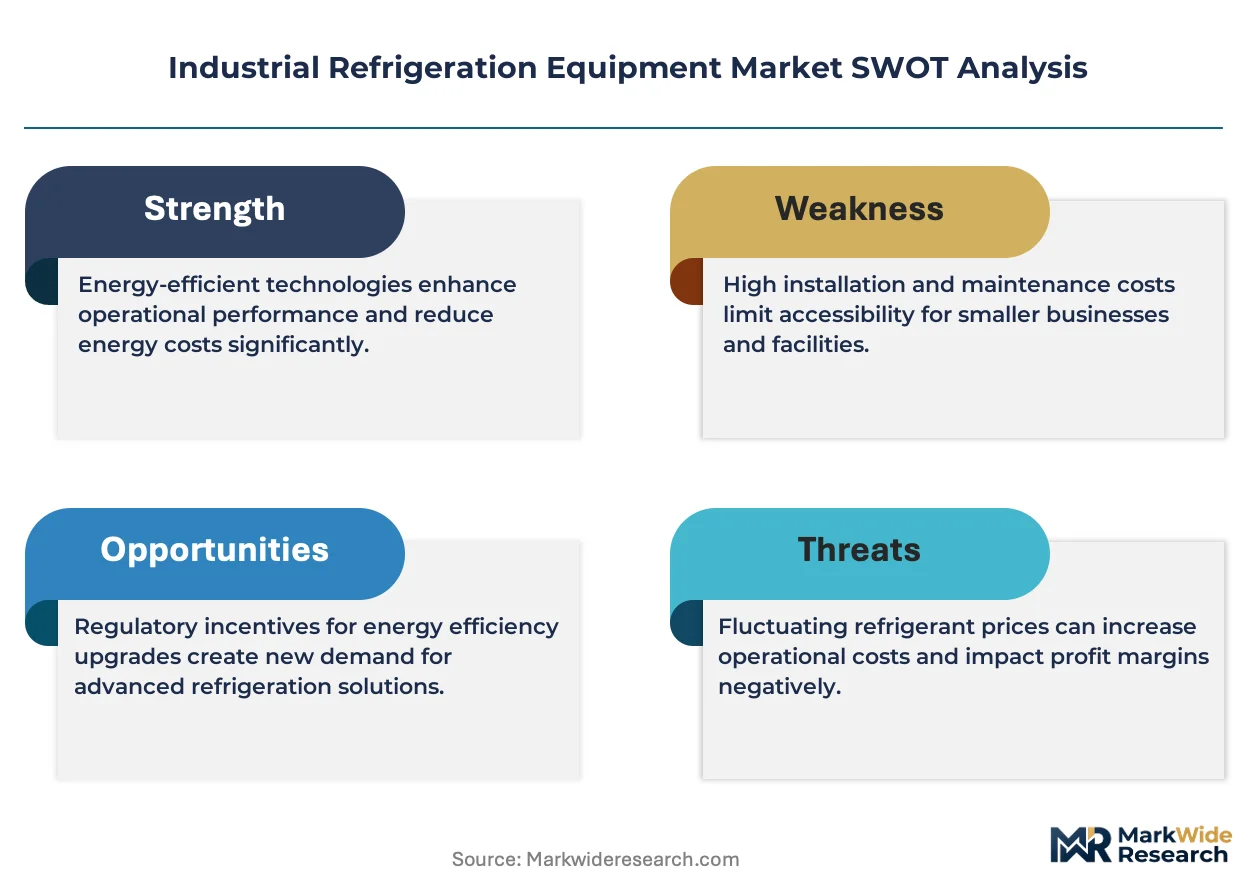
The EPA's AIM Act refrigerant phasedown and the EU F-Gas Regulation are tightening allowable global warming potential thresholds, forcing OEMs to redesign systems for lower-GWP alternatives and driving replacement demand across installed bases. ISO 5149 and ASHRAE safety standards govern machinery room design and refrigerant charge limits, shaping product configurations and installation economics. Stakeholders must monitor refrigerant chemistry transitions and energy efficiency benchmarking to time capital deployment and avoid stranded asset risk in cooling infrastructure.
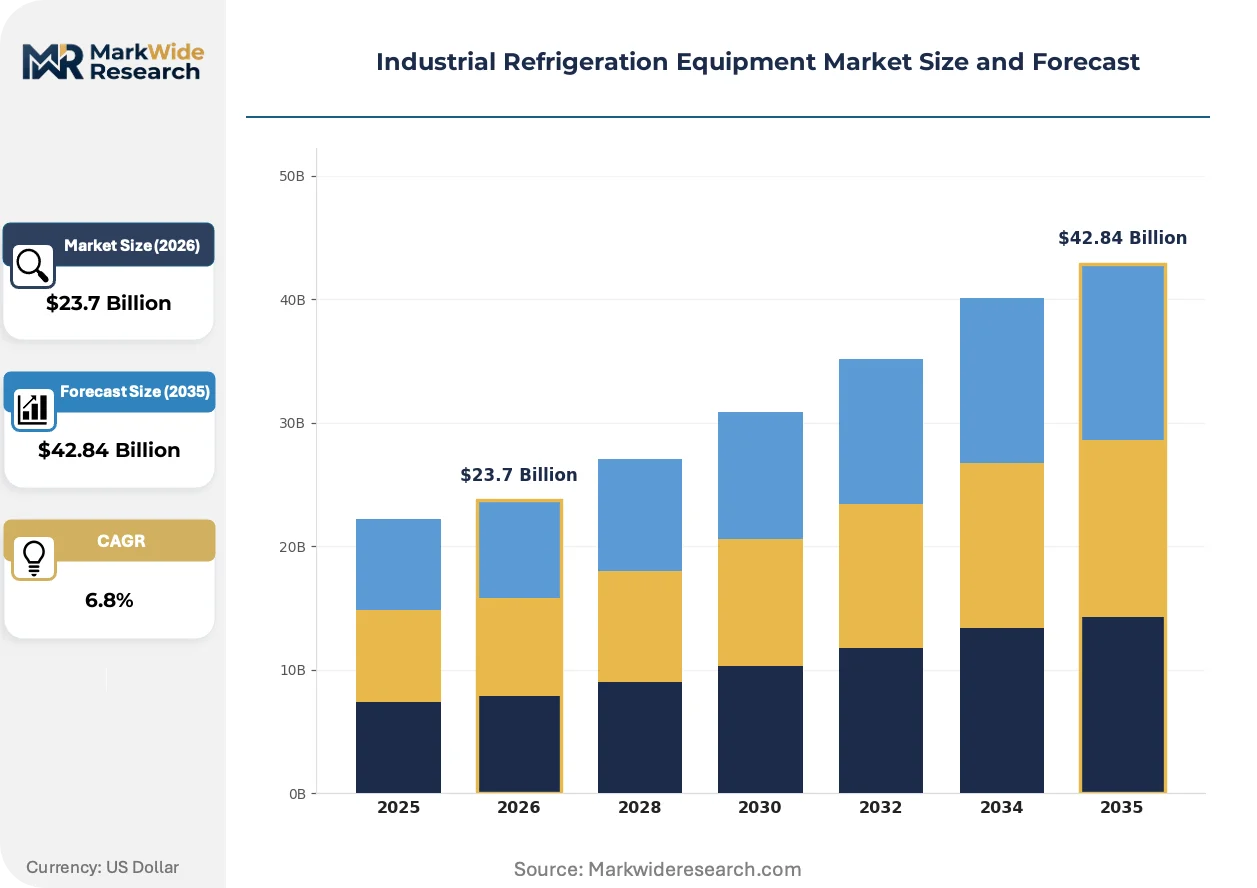
Market Dynamics
The EPA's phasedown of hydrofluorocarbon refrigerants under the AIM Act is compressing replacement cycles and forcing OEMs to redesign compressor and condenser architectures for lower-GWP alternatives, fundamentally restructuring procurement priorities across cold storage and food processing facilities.
Growth Catalysts
- Cold chain logistics expansion:Temperature-sensitive pharmaceutical distribution and perishable food networks are driving compressor and condenser demand in automated warehouse facilities.
- EU F-Gas Regulation:The tightening of allowable global warming potential thresholds across European process cooling installations is accelerating equipment replacement and retrofit activity.
- CO2 transcritical systems:Adoption of natural refrigerant architectures in supermarket and industrial cold storage applications is displacing conventional HFC-based vapor compression equipment.
Market Restraints
- Copper and aluminum input volatility:Compressor and heat exchanger manufacturing faces margin pressure from base metal price swings and concentrated smelter supply.
- Refrigerant chemistry transition costs:OEMs must absorb R&D and retooling expenses for A2L and A3 safety-class alternatives without immediate volume recovery.
- Skilled ammonia refrigeration technicians:The talent pool for industrial ammonia system installation and maintenance remains geographically concentrated in the Upper Midwest and Gulf Coast regions.
Strategic Opportunities
- India cold storage infrastructure:The country's PLI scheme for food processing and FSSAI-mandated cold chain expansion creates greenfield demand for blast freezing and controlled atmosphere systems.
- Predictive maintenance software bundling:Controls vendors can capture recurring revenue by integrating IoT sensors with compressor performance analytics for energy optimization.
- Heat recovery integration:Industrial refrigeration waste heat capture for district heating and process hot water represents an underdeveloped application in Nordic and Canadian installations.
Industry Challenges
- Ammonia safety certification timelines:ASHRAE and ISO 5149 compliance for machinery room design and refrigerant charge limits extends project commissioning schedules.
- Legacy control system integration:Retrofitting predictive maintenance capabilities onto existing PLC architectures in decades-old cold storage facilities demands specialized protocol bridging.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Refrigeration Equipment Market |
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $42.84 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compressors, Condensers, Evaporators, Controls End User: Food & Beverage, Pharmaceutical, Chemical, Manufacturing Technology: Vapor Compression, Absorption, Thermoelectric, Cascade Application: Cold Storage, Process Cooling, Transport Refrigeration, Blast Freezing |
| Companies Covered | Johnson Controls, Emerson Electric Co., GEA Group Aktiengesellschaft, Danfoss, MAY EKAWA MFG. Co., Ltd., EVAPCO Inc., BITZER Kühlmaschinenbau GmbH, Ingersoll Rand, Carrier Global Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Refrigeration Equipment Market Strategic Shifts
Equipment architectures are pivoting from standalone mechanical systems to integrated platforms where hardware, controls, and energy management converge, compressing the traditional supplier-buyer relationship into continuous performance partnerships.
Magnetic bearing centrifugal compressors are eliminating oil management complexity and reducing maintenance intervals in large-tonnage industrial applications. Cold storage operators in the United States and Germany are specifying these units for their part-load efficiency advantages. The technology is converging with variable speed drives and cloud-based performance monitoring to enable demand-response participation in grid balancing markets.
The EPA's AIM Act refrigerant phasedown is mandating transition timelines that compress OEM product development cycles and accelerate obsolescence of high-GWP equipment. Cold storage facilities face stranded asset risk if they install R-404A or R-507A systems before the 2024-2028 production caps take full effect. Equipment buyers in California and Massachusetts are responding by front-loading capital expenditure to secure grandfathered refrigerant supplies or specifying A2L-ready architectures.
Food processors and third-party logistics providers are consolidating vendor relationships and demanding outcome-based performance guarantees rather than discrete equipment procurement. Compressor uptime commitments and energy-per-ton guarantees are displacing traditional warranty terms in contract negotiations. This consolidation is most visible in the United States, where national cold storage operators like Lineage Logistics and Americold are standardizing fleet specifications across multi-site portfolios.
Industrial Refrigeration Equipment Market Segmentation
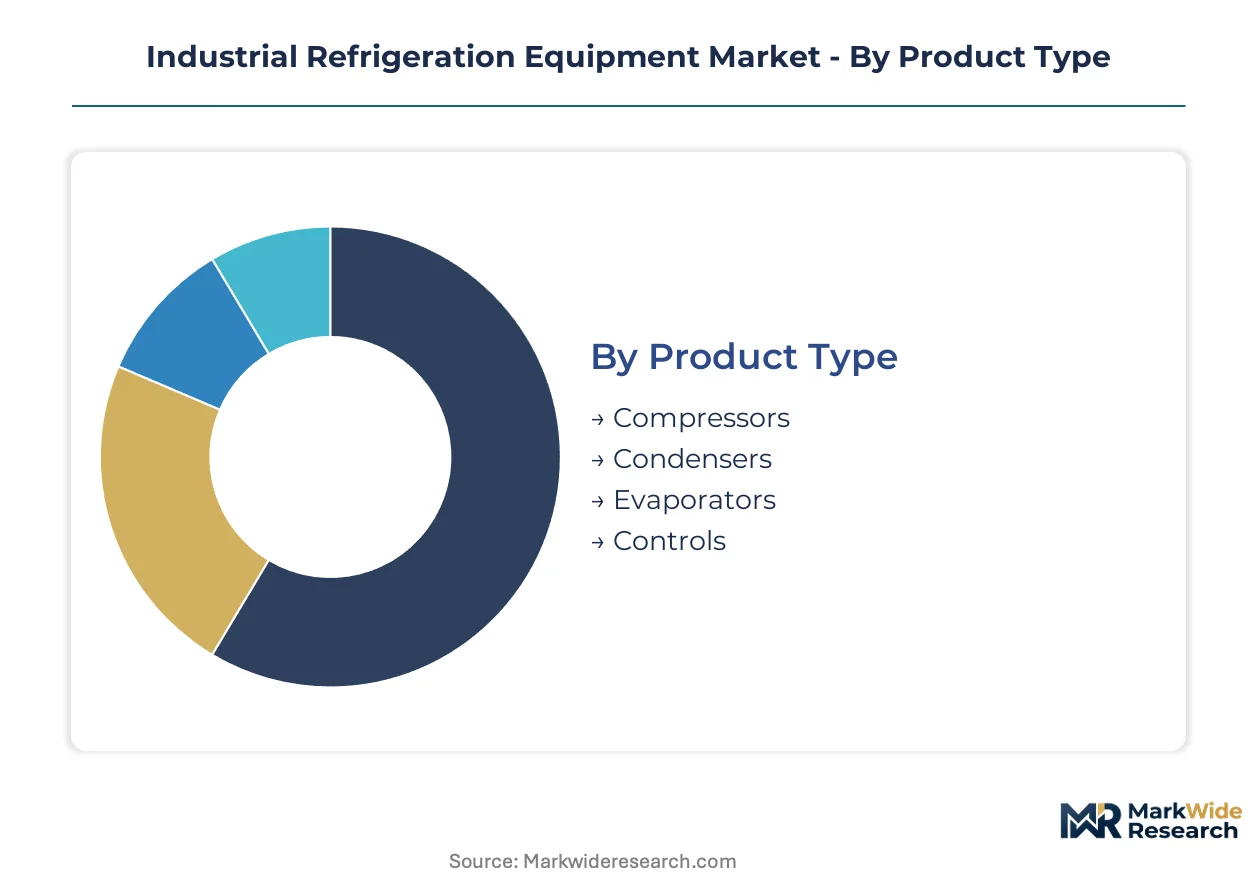
Segmentation in industrial refrigeration reveals how capital deployment concentrates around compressor architectures and cold storage infrastructure, while regulatory pressure on refrigerant chemistry reshapes technology procurement priorities across end-use verticals.
Product Type:
Capital intensity varies sharply across mechanical components, with rotating machinery requiring the heaviest upfront engineering investment.
- Compressors:Centrifugal and screw compressors dominate large-tonnage installations through variable speed drives and magnetic bearing technology. Cold storage operators in the United States specify these units for part-load efficiency in automated warehouse facilities.
- Condensers:Air-cooled and evaporative condenser designs determine system charge limits and machinery room footprint under ASHRAE safety standards. European process cooling installations favor adiabatic condensers for water-scarce regions under EU F-Gas Regulation compliance timelines.
- Evaporators:Unit coolers and air handlers for low-temperature spaces.
- Controls:Building automation systems with predictive maintenance software integration.
Compressors absorb the bulk of installed capacity; controls are expanding most quickly through IoT retrofit demand.
End User:
Application-specific temperature envelopes and regulatory compliance burdens create distinct procurement patterns across verticals.
- Food & Beverage:Cold chain logistics operators and food processors drive compressor demand for blast freezing and controlled atmosphere storage. India's PLI scheme for food processing and FSSAI-mandated cold chain expansion is accelerating greenfield facility construction.
- Pharmaceutical:Temperature-sensitive biologics distribution requires validated cold storage with continuous monitoring.
- Chemical:Process cooling for exothermic reactions and solvent recovery systems.
- Manufacturing:Industrial process cooling for metal treatment and plastics processing.
Food & Beverage commands the majority of capital expenditure; Pharmaceutical is climbing the fastest on biologics distribution requirements.
Technology:
Refrigerant chemistry transitions are forcing architecture shifts that favor natural refrigerants in new installations.
- Vapor Compression:Dominant architecture using reciprocating, scroll, screw, and centrifugal compressors. The EPA's AIM Act phasedown of hydrofluorocarbon refrigerants is accelerating replacement cycles for R-404A and R-507A systems in United States cold storage facilities.
- Absorption:Heat-activated cooling using ammonia-water or lithium bromide pairs.
- Thermoelectric:Solid-state cooling for precise temperature control in small-scale applications.
- Cascade:Dual-refrigerant systems for ultra-low temperature requirements.
Vapor Compression retains the deepest installed base; Cascade systems are gaining share fastest on ultra-low temperature pharmaceutical demand.
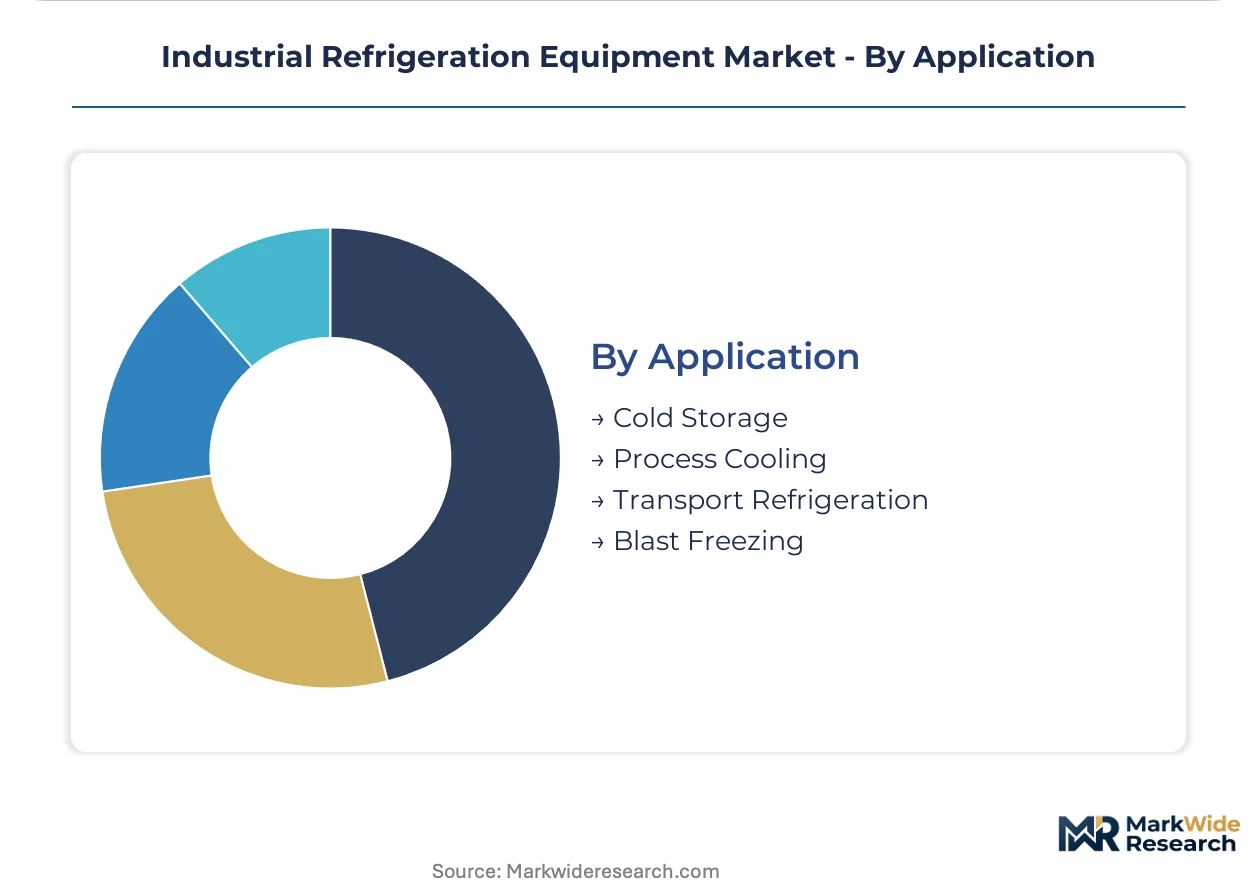
Application:
Facility scale and temperature pull-down speed requirements segment procurement between steady-state and transient cooling loads.
- Cold Storage:Warehouse refrigeration for perishable inventory holding between -40°C and 15°C. Automated facilities in Germany and the United States specify magnetic bearing centrifugal compressors for demand-response grid participation.
- Blast Freezing:Rapid temperature pull-down for seafood and prepared meal processing commands premium pricing. Nordic installations are integrating waste heat recovery for district heating.
- Process Cooling:Continuous heat removal for industrial manufacturing lines.
- Transport Refrigeration:Mobile cooling for refrigerated trucks and containers.
Cold Storage holds the largest equipment base; Blast Freezing shows the steepest expansion trajectory on prepared meal processing growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Copper smelting capacity in Chile and Peru supplies the Americas with refined cathodes for compressor motor windings and heat exchanger tubing, anchoring regional manufacturing economics for rotating machinery and condenser fabrication.
United States
Warehouse automation and food processing plant expansion drive compressor procurement in the Midwest and Southeast. The EPA's AIM Act refrigerant phasedown accelerates replacement cycles for R-404A systems in California and Massachusetts cold storage facilities. Dallas-Fort Worth and Chicago anchor national distribution networks for third-party logistics operators consolidating fleet specifications.
Germany
Process cooling demand from chemical and automotive manufacturing sustains centrifugal compressor installations in the Rhine-Ruhr and Bavarian industrial corridors. EU F-Gas Regulation compliance timelines favor adiabatic condenser designs in water-scarce southern regions. The Eindhoven-Frankfurt logistics cluster integrates magnetic bearing technology for demand-response grid participation.
India
FSSAI-mandated cold chain expansion and PLI scheme incentives for food processing generate greenfield demand for blast freezing systems in Maharashtra and Gujarat. BIS energy efficiency standards reshape equipment specifications for domestic manufacturers. The Delhi-Mumbai Industrial Corridor anchors controlled atmosphere storage investments for horticultural exports.
China
Dual carbon goals and GB standards for industrial energy consumption drive retrofit demand in Yangtze River Delta cold storage facilities. MIIT refrigerant transition guidelines accelerate CO2 transcritical system adoption in supermarket distribution centers. Shandong Province concentrates ammonia refrigeration manufacturing for domestic and Southeast Asian export markets.
Japan
Precision temperature control requirements for biologics distribution sustain cascade system demand in the Kanto pharmaceutical corridor. METI energy conservation standards mandate predictive maintenance integration in legacy cold storage facilities. Osaka-Kobe industrial ports anchor seafood blast freezing capacity serving premium export markets.
Industrial Refrigeration Equipment Market Competitive Environment
Global majors compete with regional champions across refrigerant technology transition timelines and cold storage automation integration depth. The vendor base stratifies into three tiers: full-system integrators with controls software capabilities, component specialists with captive compressor manufacturing, and regional fabricators serving single-country installation markets. Dominant competitive moves include backward integration into heat exchanger production and strategic partnerships with cold chain logistics operators for fleet standardization contracts.
Among diversified industrial conglomerates, Johnson Controls and Emerson Electric Co. exemplify the controls-integrated archetype, while GEA Group Aktiengesellschaft occupies a position within European process cooling specialization. MAY EKAWA MFG. Co., Ltd. represents the Asia-Pacific regional champion model. BITZER Kühlmaschinenbau GmbH anchors the German Mittelstand engineering-intensive tier.
| Leading Market Players |
|---|
| Johnson Controls |
| Emerson Electric Co. |
| GEA Group Aktiengesellschaft |
| Danfoss |
| MAY EKAWA MFG. Co., Ltd. |
| EVAPCO Inc. |
| BITZER Kühlmaschinenbau GmbH |
| Ingersoll Rand |
| Carrier Global Corporation |
| Others |
Value Chain & Pricing Dynamics
Magnetic bearing centrifugal compressor adoption is simultaneously compressing maintenance cost structures and concentrating procurement power among controls-integrated OEMs with captive manufacturing. The technology transition favors suppliers bundling predictive software with hardware, reshaping how cold storage operators evaluate total cost of ownership against upfront capital expenditure.
Pricing Analysis
Warranty and service bundling separates premium-tier suppliers offering uptime guarantees from unbundled component vendors competing on transactional compressor and condenser pricing. Three-tier pricing structure across premium, standard, and economy levels reflects ASHRAE certification tiers, magnetic bearing technology inclusion, and geographic delivery logistics. Cost compression in standard-tier equipment is intensifying because copper and aluminum input volatility squeezes heat exchanger margins. National cold storage operators like Lineage Logistics demonstrate lowest price sensitivity through fleet standardization contracts, while regional food processors remain most responsive to unbundled equipment quotes.
Supply Chain Analysis
ISO 5149 and ASHRAE machinery room certification requirements gate supplier qualification for ammonia refrigeration systems, filtering regional fabricators from national project bids. Manufacturing concentrates in the United States, Germany, and China for compressor motor windings and heat exchanger tubing. Production draws from Chilean and Peruvian copper cathode supplies, Chinese rare earth magnets for variable speed drives, and domestic steel fabrication. Single-source vulnerability in magnetic bearing subcomponents from specialized German and Japanese suppliers poses concentration risk. Distribution runs through OEM-direct channels for large-tonnage installations and regional distributor networks for aftermarket parts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The industrial refrigeration equipment market sits in a refrigerant chemistry transition phase where CO2 transcritical systems are displacing conventional HFC-based vapor compression architectures. This technology replacement cycle compresses product development timelines and rewards suppliers with fastest certification pathways.
For Market Incumbents: Cement controls software leadership by integrating IoT predictive maintenance with magnetic bearing compressor portfolios, defending against emerging entrants with pure-hardware offerings. Prioritize backward integration into heat exchanger production to capture margin from copper price volatility. Lock fleet standardization contracts with national cold storage operators before refrigerant transition deadlines accelerate procurement decisions. For New Entrants and Emerging Players: Launch via blast freezing specialization targeting India's FSSAI-mandated cold chain expansion in Maharashtra and Gujarat, where greenfield demand outpaces established supplier coverage. Target predictive maintenance software retrofit for decades-old PLC architectures in Midwest cold storage facilities, where legacy control system integration demands specialized protocol bridging. Partner with regional ammonia refrigeration technician training programs to overcome talent pool concentration barriers. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified industrial conglomerates seeking cold chain automation capabilities. Five-to-ten year viability hinges on refrigerant chemistry transition execution and controls software recurring revenue attachment rates. Target acquisition archetype: mid-tier compressor specialists with ASHRAE certification depth and regional installation relationships. Watch EPA AIM Act enforcement acceleration and EU F-Gas Regulation tightening as inflection signals for replacement demand timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Heat Exchanger Manufacturing | Captures margin from copper volatility and secures ASHRAE-compliant machinery room configurations. |
| Predictive Maintenance Software Bundling | Transforms transactional compressor sales into recurring revenue through IoT sensor integration. |
| CO2 Transcritical System Certification Investment | Positions OEMs ahead of EPA AIM Act production caps on R-404A and R-507A refrigerants. |
| Fleet Standardization Partnerships | Locks multi-site procurement commitments from Lineage Logistics and Americold through performance guarantees. |
| Ammonia Refrigeration Technician Training Programs | Addresses geographic talent concentration in Upper Midwest and Gulf Coast to accelerate project commissioning. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this industrial refrigeration equipment analysis. Primary interviews with maintenance directors at cold storage facilities, plant engineers at food processing operations, OEM procurement teams, and aftermarket service heads combined with secondary validation from EPA enforcement databases, EU ECHA refrigerant registry filings, and copper cathode import records. Bottom-up equipment shipment triangulation against top-down capital expenditure surveys from cold chain logistics operators ensured cross-verification.
Data-stream reconciliation across compressor unit volumes, condenser installation permits, and controls software licensing records established the analytical framework. Segmentation dimensions modeled include refrigerant technology architecture, compressor type, application temperature envelope, and regional regulatory cluster. CAGRs derived from equipment replacement cycle analysis and refrigerant phasedown timeline compliance requirements. Industry-specific forecast inputs incorporated FSSAI cold chain mandate implementation pace and PLI scheme disbursement trajectories for Indian food processing infrastructure.
EPA enforcement acceleration, EU F-Gas Regulation amendment timing, and copper price volatility spikes are the dominant revision risks to modeled equipment demand. Forecasts reflect assumptions on refrigerant transition compliance rates and cold storage automation adoption curves. A model refresh is warranted upon material change in AIM Act implementation schedules or breakthrough adoption of solid-state cooling alternatives.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
United Kingdom Commercial HVAC Market
HVAC Equipment
Commercial Refrigeration Equipment Market
HVAC Equipment
Industrial Insulation Testers Market
HVAC Equipment
Global Snow Making System Market
HVAC Equipment
GCC Portable Air Conditioners Market
HVAC Equipment
Commercial Refrigeration Compressor Market
HVAC Equipment
Europe Ventilation Equipment Market
HVAC Equipment
Middle East and Africa Commercial HVAC Market
HVAC Equipment
Hot Water Circulator Pump Market
HVAC Equipment
HVAC Services Market
HVAC Equipment
Blowers Market
HVAC Equipment
Industrial Air Heaters Market
HVAC Equipment
Variable Air Volume Box Market
HVAC Equipment
Global Fan Coil Unit Market
HVAC Equipment
Recirculating Chillers Market
HVAC Equipment
Equipment Fan Filter Unit (EFU) Market