
 Foamer Pump Market | 2026-2036
Foamer Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Foamer Pump Market Analysis
EU REACH substance restrictions is consolidating material sourcing standards across European foamer pump supply chains. AptarGroup, Inc. leverages its dispensing technology leadership to sustain premium positioning in personal care applications. Silgan Dispensing Systems anchors industrial cleaning segments through manufacturing scale in North American facilities. Rieke Corporation competes across foodservice and household categories with broad product specialization.
A foamer pump is a mechanical dispensing device that aerates liquid formulations through a specialized mesh or screen system to produce stable foam output, typically operating at pressures between 0.2 and 0.5 bar depending on viscosity and orifice design. The device serves primary commercial purposes in personal care, cleaning, and foodservice applications where controlled foam delivery improves user experience and reduces chemical consumption. Manual foamer pumps occupy the largest volume share due to cost efficiency and battery-free reliability across household and hospitality end users. Electric foamer pumps represent the fastest-expanding category as commercial kitchens and industrial cleaning operations automate dispensing workflows. Foodservice applications concentrate margin pools where NSF-certified pumps command pricing premiums from institutional buyers.
EMA cosmetic ingredient oversight, EU REACH chemical restrictions, and CE marking requirements collectively shape material selection, migration testing protocols, and market access conditions for foamer pump manufacturers serving European buyers. FDA regulations govern pump contact materials and extractables testing for products entering United States personal care and foodservice channels. Stakeholders must monitor evolving PFAS restrictions and single-use packaging directives across multiple jurisdictions to anticipate formulation and design compliance obligations.
Market Dynamics
REACH substance restrictions and EU Green Deal packaging mandates are consolidating material sourcing standards across European foamer pump supply chains, forcing suppliers to validate alternative polymers and accelerate migration testing protocols.
Growth Catalysts
- Refillable Skincare Formats:Personal care brands across Germany, France, and the Netherlands are expanding foamer pump procurement for reusable packaging systems that comply with extended producer responsibility frameworks.
- NSF Certification Premiums:Foodservice institutional buyers in the United States are specifying NSF-certified pumps for commercial kitchen automation, creating margin pools above commodity dispensing hardware.
- Dual Carbon Goals:China's MIIT efficiency standards and provincial low-carbon manufacturing mandates are accelerating electric foamer pump adoption in industrial cleaning operations.
Market Restraints
- Polymer Feedstock Volatility:Engineering-grade polypropylene and specialized elastomer prices fluctuate with crude oil derivatives, compressing margin predictability for injection-molded pump components.
- Mesh Screen Supply Concentration:Precision stainless steel and nylon mesh manufacturing concentrates in Zhejiang Province and Baden-Württemberg, creating single-source vulnerability for specialized foamer elements.
- PFAS Regulatory Friction:ECHA restriction proposals and US EPA action pathways on perfluorinated compounds threaten fluoropolymer seal compatibility in high-viscosity formulations.
Strategic Opportunities
- Latin American Foodservice Expansion:Brazil's ANVISA regulatory harmonization with FDA standards is opening institutional procurement channels for NSF-certified pump systems in São Paulo and Rio de Janeiro hospitality clusters.
- Battery-Free Electric Convergence:Piezoelectric actuation and kinetic energy harvesting are converging with miniaturized motor design to enable cordless foamer pumps without lithium cell dependency.
- Reverse Logistics Integration:German VerpackG packaging law mandates are creating distributor-led take-back channels that reward pump designs optimized for disassembly and material recovery.
Industry Challenges
- Migration Testing Talent Scarcity:Qualified analytical chemists capable of executing EU 10/2011 food contact and REACH SVHC screening protocols command premium compensation in Hamburg and Rotterdam testing hubs.
- Multi-Jurisdiction Certification Timelines:Simultaneous FDA, CE marking, and EMA cosmetic ingredient compliance creates 14-18 month product launch cycles that delay revenue recognition.
- Legacy System Integration Complexity:Foodservice automation buyers require OPC-UA and Modbus communication protocols that many established pump electronics architectures do not natively support.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Foamer Pump Market |
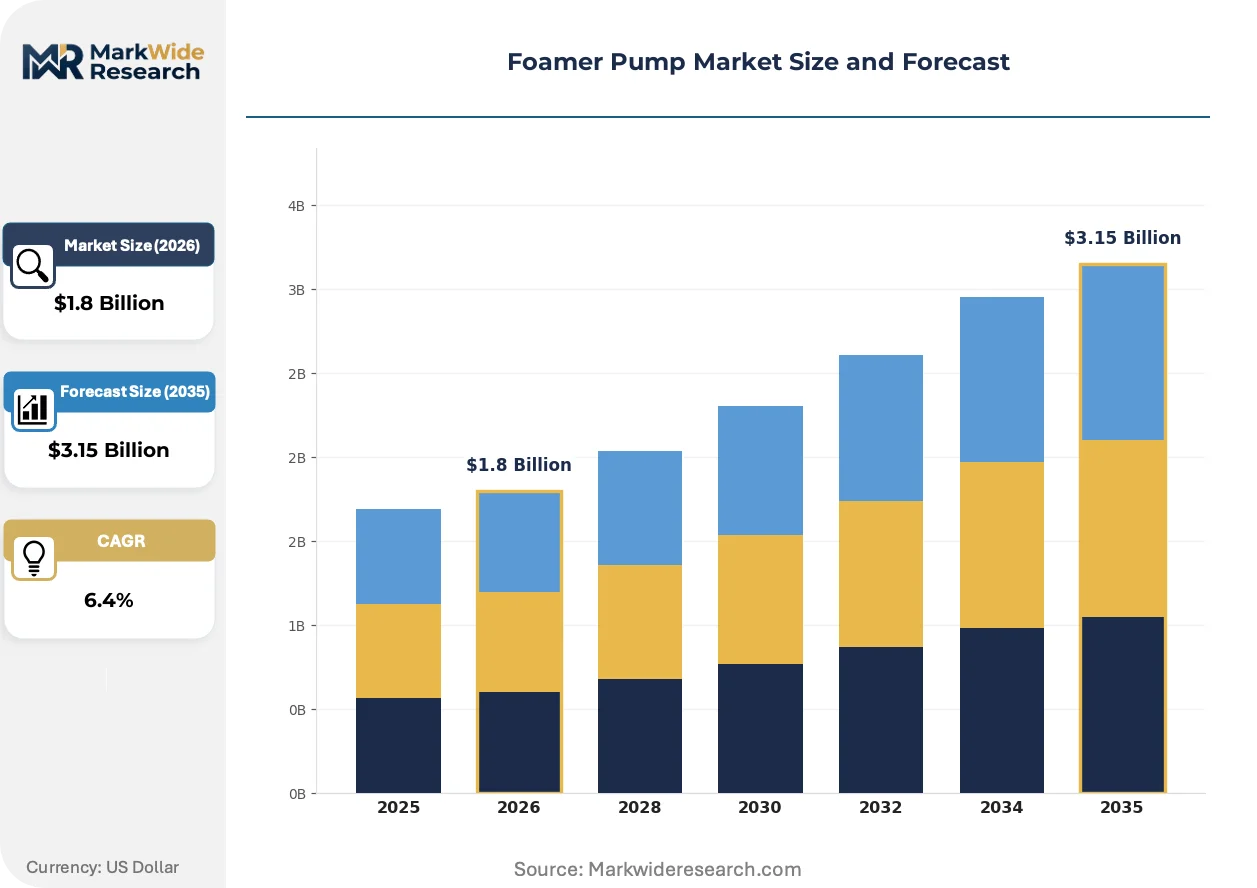
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual, Electric, Battery-operated, Pneumatic Application: Household, Industrial Cleaning, Personal Care, Foodservice End User: Retailers, Manufacturers, Hospitality, Healthcare Functionality: Mixing, Dispensing, Foaming, Pressurizing |
| Companies Covered | Rieke Corporation, APackaging Group, AptarGroup, Inc., Raepak Ltd., Frapack Packaging B.V., Silgan Dispensing Systems, Sun-Rain Sprayer Co., Ltd., Ningbo Sepshion Commodity Co., Ltd., Albéa S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Foamer Pump Market Emerging Trajectories
Active aeration control and connected dispensing systems are transforming foamer pump architecture from passive mechanical devices to precision-dosed, data-generating endpoints within automated workflows.
Electric foamer pumps with integrated pressure sensors and microprocessor-controlled motor modulation are automating foam density consistency in commercial kitchen and industrial cleaning environments. Quick-service restaurant chains and contract foodservice operators in the United States are deploying these systems at pilot scale before broader rollout. This automation is compressing operator training requirements and reducing chemical over-dispense waste by maintaining target expansion ratios regardless of formulation viscosity variation.
EU REACH Annex XVII substance restrictions and the forthcoming Packaging and Packaging Waste Regulation are mandating recycled content thresholds and restricting specific plasticizers in pump components. Industrial consequences include accelerated validation of post-consumer recycled polypropylene and bio-based elastomer alternatives for seal applications. Personal care pump manufacturers serving European buyers are responding by locking multi-year supply agreements with EFSA-registered compounders capable of lot-traceable migration documentation.
Refill station networks and bulk dispensing models are displacing unit-packaged foamer bottles in European personal care retail. Dm-drogerie markt and Douglas are piloting in-store aeration systems that charge reusable vessels with fresh foam on demand. This behavior shift concentrates most visibly in German urban centers where municipal packaging ordinances and consumer deposit-return familiarity accelerate adoption beyond Mediterranean markets.
Foamer Pump Market Segmentation
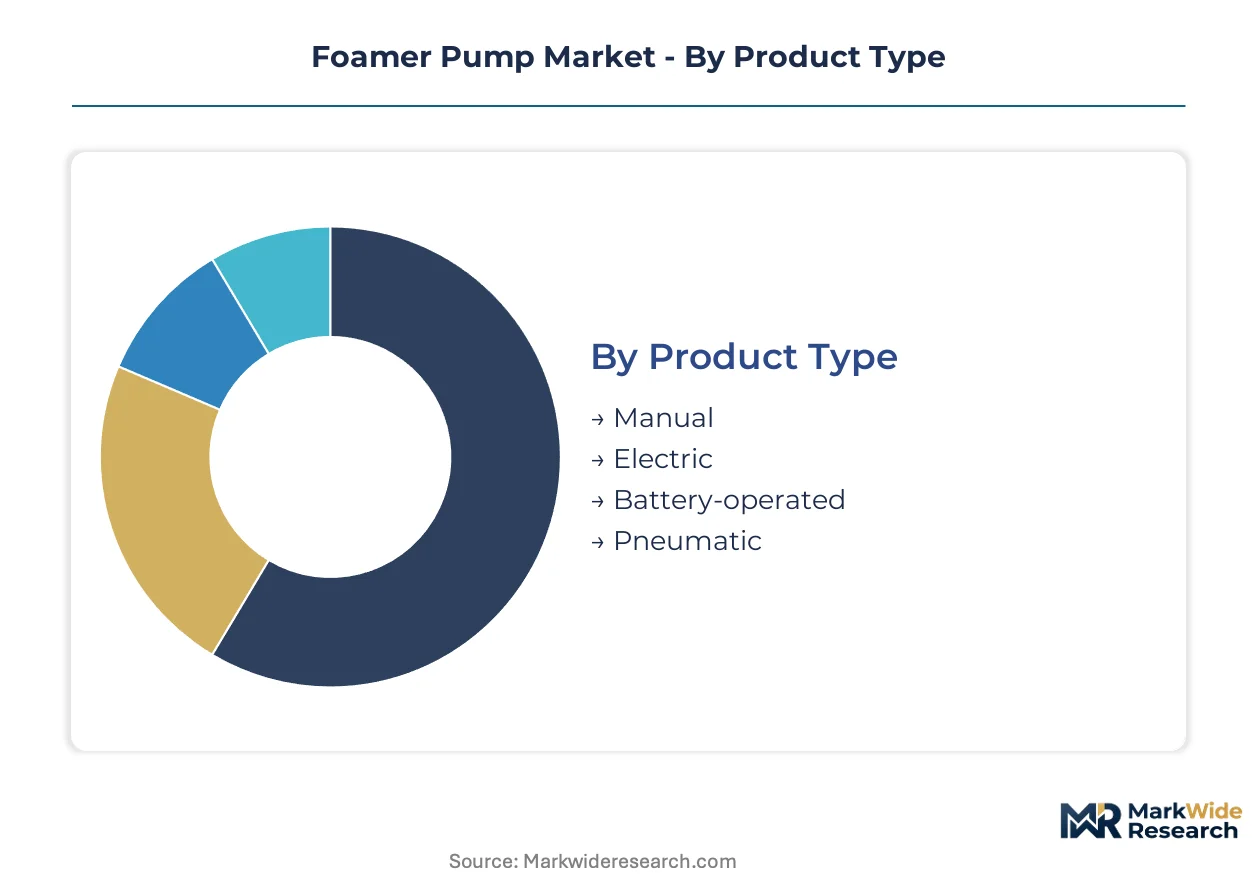
Foamer pump procurement patterns diverge sharply across technical specifications and commercial contexts. Buyers prioritize different performance attributes depending on whether they serve mass retail, institutional foodservice, or precision industrial applications.
Product Type:
Cost tier separates buyers most decisively in this category, from commodity household hardware to precision-engineered commercial systems.
- Manual:Hand-actuated piston mechanisms generate foam through mechanical compression without electrical components. Demand concentrates in German and French household sectors where extended producer responsibility laws reward battery-free reliability and end-of-life material recovery. REACH-compliant polypropylene housings dominate procurement specifications.
- Electric:Microprocessor-controlled motor systems modulate pressure and aeration ratios for consistent foam density. Foodservice automation buyers in the United States specify these for commercial kitchen integration, paying NSF certification premiums that commodity pumps cannot capture.
- Battery-operated:Portable lithium-cell units serve mobile cleaning crews and field hospitality applications where mains power is unavailable. German VerpackG take-back mandates are complicating end-of-life logistics.
- Pneumatic:Compressed-air-driven systems handle high-viscosity industrial formulations in continuous-duty manufacturing environments. MIIT efficiency standards in China are accelerating adoption over electric alternatives in carbon-intensive production zones.
Volume sits with Manual pumps across European retail channels; growth tilts toward Electric systems as commercial kitchen automation expands.
Application:
Margin structure varies dramatically by application, from thin-margin household commodity sales to premium-priced institutional certifications.
- Household:Standardized polypropylene pumps serve mass-market dish soap and hand wash formulations. German discounters dm-drogerie markt and Aldi dominate procurement volume, squeezing supplier margins through consolidated tender processes.
- Industrial Cleaning:Chemical-resistant elastomer seals and stainless steel mesh screens withstand caustic formulations. Demand clusters in China's Guangdong and Jiangsu provinces where provincial low-carbon mandates favor electric foamer integration.
- Personal Care:Aesthetic housing designs and precise dosing mechanisms support premium skincare positioning. Refillable format adoption in Hamburg and Düsseldorf cosmetic manufacturing corridors is reshaping pump specification toward disassembly-friendly architectures.
- Foodservice:NSF-certified pumps with migration-tested contact materials command pricing premiums from institutional buyers. Quick-service restaurant chains in the United States pilot connected dispensing systems before broader rollout.
Revenue concentrates in Personal Care applications; Foodservice delivers the steepest expansion trajectory as commercial kitchen automation accelerates.
End User:
Procurement sophistication separates this category, from price-driven retail sourcing to specification-heavy institutional contracting.
- Retailers:Consolidated purchasing through central European buying offices demands REACH documentation and recycled content verification. Douglas and Sephora specify lot-traceable migration testing for private-label personal care launches.
- Manufacturers:Cosmetic and cleaning compounders integrate foamer pumps into finished product packaging. Hamburg-area premium skincare manufacturers cluster procurement decisions, creating geographic demand concentration.
- Hospitality:Contract foodservice operators and hotel chains specify NSF-certified electric systems for back-of-house automation. São Paulo and Rio de Janeiro hospitality clusters are opening to ANVISA-harmonized FDA standards.
- Healthcare:Antimicrobial formulation compatibility and precise dosing accuracy dominate hospital and long-term care procurement. EMA cosmetic ingredient oversight shapes seal material validation protocols.
Procurement volume aggregates with Retailers; specification complexity climbs fastest among Healthcare buyers.
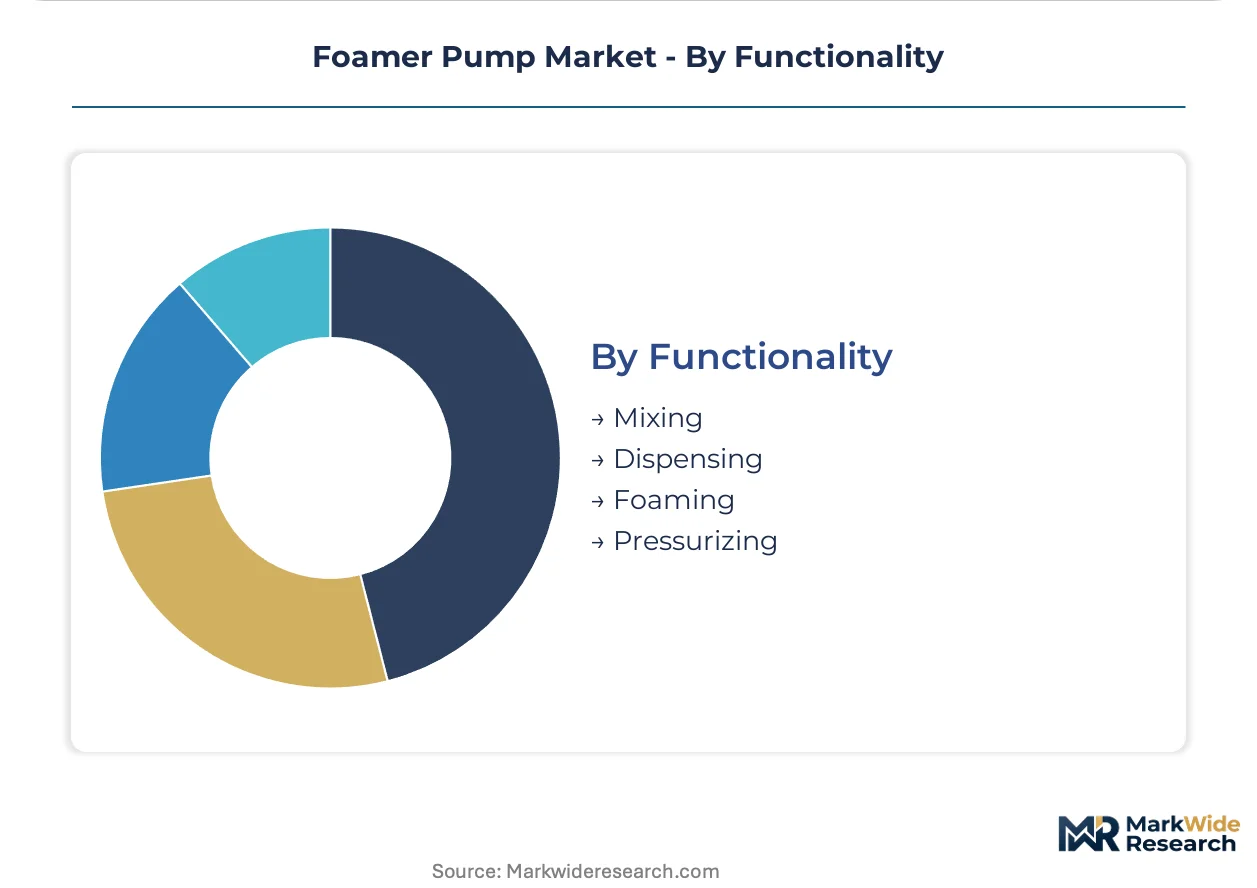
Functionality:
Technical integration depth distinguishes buyer requirements, from simple mechanical dispensing to multi-stage process control.
- Mixing:Inline blending chambers combine concentrate with diluent water at point of dispensing. Industrial cleaning operations in China's coastal manufacturing zones specify these for chemical inventory reduction.
- Dispensing:Controlled volume delivery without aeration serves gel and liquid formulations requiring precise metering. Personal care manufacturers in the Netherlands specify dual-function pumps switching between foam and liquid output.
- Foaming:Mesh or screen aeration systems generate stable foam through mechanical shearing. This core function dominates household and personal care applications where user experience drives repeat purchase.
- Pressurizing:Accumulator or continuous-pressure systems maintain consistent output across viscosity and temperature variation. Foodservice automation buyers require this for integration with PLC-controlled production lines.
Unit volume flows through Foaming functionality; Pressurizing capabilities are gaining share fastest as industrial automation requirements harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in Chinese injection-molding corridors while consumption gravitates toward European personal care and North American foodservice end markets. This geographic split shapes trade flows and regulatory compliance burdens across the value chain.
United States
Foodservice automation drives electric foamer pump specification, with quick-service restaurant chains deploying NSF-certified systems for commercial kitchen integration. FDA contact material regulations govern extractables testing protocols for pumps entering personal care and foodservice channels. Procurement clusters around Chicago and Dallas-Fort Worth distribution hubs serving national hospitality networks.
Germany
Premium cosmetic manufacturers around Hamburg and Düsseldorf are expanding refillable format procurement, creating demand for disassembly-friendly pump architectures. VerpackG packaging law mandates distributor-led take-back channels that reward designs optimized for material recovery. REACH substance restrictions tighten specifications for plastic pump components serving European buyers.
China
Guangdong and Jiangsu provinces host precision mesh manufacturing and injection-molded pump component fabrication at industrial scale. MIIT efficiency standards and provincial low-carbon manufacturing mandates accelerate electric foamer adoption in industrial cleaning operations. Zhejiang Province concentrates specialized stainless steel and nylon mesh production for foamer elements.
Brazil
São Paulo and Rio de Janeiro hospitality clusters are opening to institutional procurement as ANVISA regulatory harmonization with FDA standards progresses. Contract foodservice operators specify imported NSF-certified systems for back-of-house automation. Urban retail expansion creates secondary demand for household foamer pumps through national grocery chains.
Japan
Personal care manufacturers specify high-precision dosing mechanisms for premium skincare positioning in domestic and export markets. METI industrial standards shape material validation protocols for pump contact surfaces. Manufacturing activity concentrates in the Kansai region around Osaka-based packaging equipment suppliers.
Foamer Pump Market Vendor Landscape
The competitive structure tilts toward diversified dispensing technology conglomerates with cross-sector material science capabilities. Tiered specialization separates premium personal care positioning from commodity household hardware. Three archetypes dominate: integrated dispensing systems multinationals, regional injection-molding specialists, and precision mesh component fabricators. Capacity expansion and strategic partnerships represent the dominant competitive moves as players secure qualified polymer supply and migration testing capabilities.
Among North American-diversified conglomerates, AptarGroup, Inc. and Silgan Dispensing Systems occupy positions spanning personal care and industrial segments. Rieke Corporation exemplifies the broad-product-specialist archetype competing across foodservice and household categories. Chinese fabricators including Sun-Rain Sprayer Co., Ltd. and Ningbo Sepshion Commodity Co., Ltd. represent regional scale players serving export markets through cost-efficient manufacturing. European specialists such as Albéa S.A. and Frapack Packaging B.V. anchor premium-tier positioning through proximity to cosmetic manufacturing clusters in France and the Netherlands.
| Leading Market Players |
|---|
| Rieke Corporation |
| APackaging Group |
| AptarGroup, Inc. |
| Raepak Ltd. |
| Frapack Packaging B.V. |
| Silgan Dispensing Systems |
| Sun-Rain Sprayer Co., Ltd. |
| Ningbo Sepshion Commodity Co., Ltd. |
| Albéa S.A. |
| Others |
Supply Flow & Price Mechanics
EU Green Deal packaging mandates and recycled content thresholds gate qualified polymer supply and premium-tier pricing access for foamer pump manufacturers, forcing buyers to pay certification premiums for REACH-compliant, migration-documented components while excluding uncertified suppliers from institutional procurement channels.
Pricing Analysis
NSF certification serves as the dominant value-based pricing anchor, with foodservice institutional buyers paying substantial premiums for pumps validated to contact-material and extractables standards that commodity hardware cannot meet. Three-tier pricing structure across premium, standard, and economy levels separates NSF-certified electric systems from REACH-compliant manual pumps and undifferentiated household commodity units. Cost compression in the economy tier is intensifying because German discounters consolidate tender processes and squeeze supplier margins. Retail procurement offices show highest price sensitivity; healthcare and foodservice automation buyers demonstrate lowest sensitivity due to compliance-driven specification requirements.
Supply Chain Analysis
German VerpackG take-back mandates and China's MIIT efficiency standards are reshaping sourcing patterns toward localized component recovery and low-carbon manufacturing verification. Injection-molded pump housings and precision mesh elements concentrate manufacturing in China, Germany, and the United States. Supply chains draw from engineering-grade polypropylene, specialized elastomer seals, and stainless steel or nylon mesh screens. Single-source vulnerability in Zhejiang Province and Baden-Württemberg for precision mesh fabrication creates concentrated supply risk. Distribution runs through distributor-led take-back channels in Germany and national hospitality distribution hubs in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market has become a vertical-integration race as players pursue captive control over migration testing capabilities and qualified polymer compounding to secure institutional buyer access and defend margin pools.
For Market Incumbents: Deepen backward integration into EFSA-registered polymer compounding and lot-traceable migration documentation to lock out competitors from European personal care procurement channels threatened by REACH substance restriction expansions. Add certified testing capacity in Hamburg and Rotterdam hubs to reduce dependency on scarce analytical chemistry talent and accelerate multi-jurisdiction certification timelines. For New Entrants and Emerging Players: Enter via Brazil's ANVISA-harmonized institutional foodservice procurement channels in São Paulo and Rio de Janeiro hospitality clusters, where regulatory convergence with FDA standards is opening import specifications previously closed to uncertified suppliers. Target battery-free electric foamer architectures using piezoelectric actuation to bypass lithium cell supply constraints and German end-of-life logistics complications. For Investors and Strategic Acquirers: ANVISA regulatory harmonization completion in Brazil is the leading indicator that Latin American foodservice automation demand will inflect toward NSF-certified system adoption, creating acquisition timing for precision dispensing technology assets before valuation expansion. Target mid-cap specialists with existing FDA submissions and CE marking pathways to compress 14-18 month product launch cycles through inherited regulatory dossiers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Secures REACH-compliant material supply with lot-traceable migration documentation for European buyers. |
| Migration Testing Capacity Expansion | Captures scarce analytical chemistry talent in Hamburg and Rotterdam to accelerate certification timelines. |
| ANVISA-Harmonized Product Line Launch | Opens institutional procurement channels in São Paulo and Rio de Janeiro hospitality clusters. |
| Battery-Free Electric Architecture Development | Eliminates lithium cell dependency and German VerpackG take-back compliance burdens. |
| Refill Station Network Partnership | Aligns with dm-drogerie markt and Douglas pilot programs for reusable packaging format demand. |
Methodological Framework
Multi-period observation of REACH substance restriction proposals, ANVISA regulatory harmonization milestones, and MIIT efficiency standard implementations anchored the trend analysis, supplemented by interviews with cosmetic packaging procurement directors, foodservice automation engineers, polymer compounding technical leads, and migration testing laboratory managers. Secondary validation drew from ECHA restriction proposal databases, FDA extractables guidance documents, EU Packaging and Packaging Waste Regulation drafts, and customs trade flow records. Bottom-up segment sizing triangulated against top-down market envelope estimates.
Segment-weighting across product type, application, end user, and functionality dimensions drove volume and value allocation throughout the forecast period. CAGRs derived from elasticity-adjusted demand curves incorporating substitution effects between manual and electric architectures, regulatory compliance cost pass-through coefficients, and refillable format adoption curves. Industry-specific inputs included NSF certification penetration rates in U.S. foodservice and VerpackG take-back channel development in German retail.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated PFAS restriction timelines or polymer feedstock volatility spikes. Assumptions include stable REACH substance restriction implementation schedules and continued ANVISA-FDA harmonization progress. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Global HVAC Packaged Unit Market
HVAC Equipment
Global Commercial Heat Pump Water Heater Market
HVAC Equipment
Germany Commercial HVAC Market
HVAC Equipment
Screw Compressor Market
HVAC Equipment
Water Chiller Market
HVAC Equipment
Global Portable Evaporative Air Cooler Market
HVAC Equipment
Industrial Ventilation Equipment Market
HVAC Equipment
Compressor Controllers Market
HVAC Equipment
Combustion Controls, Equipments and Systems Market
HVAC Equipment
Brazed Plate Heat Exchangers Market
HVAC Equipment
Steam Heat Exchanger Market
HVAC Equipment
Asia-Pacific Compressor Market
HVAC Equipment
Reciprocating Chiller Market
HVAC Equipment
Heavy Duty Heat Pump Market
HVAC Equipment
Global Industrial Air Chiller Market
HVAC Equipment
Strip Warmer Market