
 Global Air Conditioner Market | 2026-2036
Global Air Conditioner Market Size, Share, and Industry Trends Forecast 2026-2036
Global Air Conditioner Market Analysis
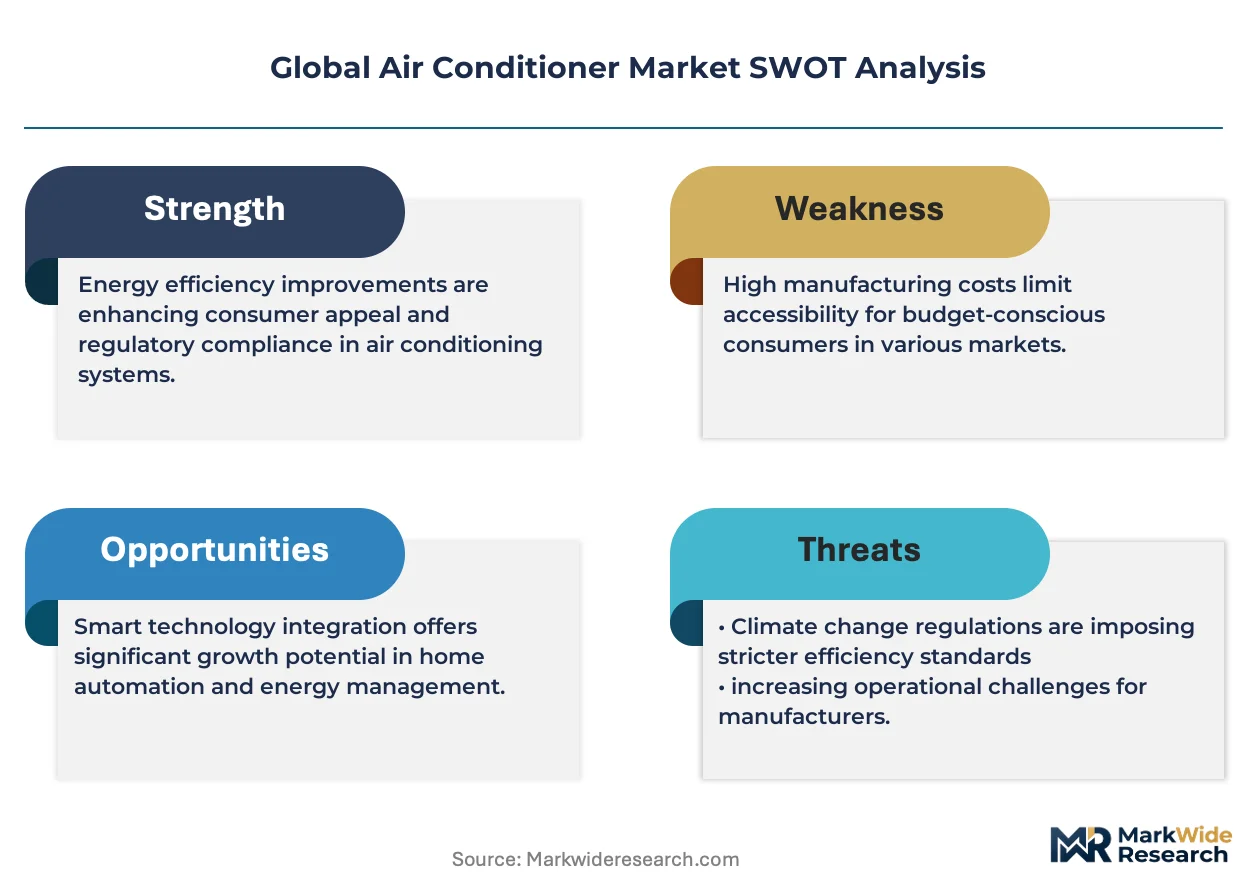
Project finance and green leasing structures for building retrofits is fragmenting competitive access across the Global Air Conditioner Market. Daikin Industries leverages captive compressor production to sustain margin control in premium VRF systems. Gree Electric Appliances anchors its position through backward integration into rare-earth magnet supply for inverter motors. LG Electronics differentiates via smart-home ecosystem integration that extends software recurring revenue alongside hardware sales.
An air conditioner is a vapor-compression refrigeration apparatus designed to extract heat from an enclosed space and discharge it to an external environment, typically operating with refrigerants at evaporator temperatures between 4°C and 10°C and employing rotary or scroll compressors driven by AC or DC inverter motors. Its primary commercial purpose is to maintain thermally controlled environments for human occupancy, process cooling, and equipment protection across buildings, vehicles, and industrial facilities. Split systems dominate installed base value due to retrofit flexibility and multi-zone scalability, while inverter technology captures expanding share as electricity tariff structures penalize peak-demand consumption. Smart-connected units represent the fastest-growing technology segment as building management systems integrate predictive maintenance protocols and utility demand-response signaling.
F-Gas Regulation in Europe mandates stepped HFC refrigerant phase-downs that force R-410A replacement with lower-GWP alternatives such as R-32 and R-454B, reshaping compressor redesign cycles and service technician certification requirements. China's MEE enforces GB energy-efficiency standards that disqualify non-inverter units from subsidy eligibility, while India's BIS labeling program creates market-access barriers for uncertified imports. Stakeholders must monitor refrigerant patent cliffs and regional service-network density as these determine which manufacturers can convert regulatory pressure into installed-base lock-in.
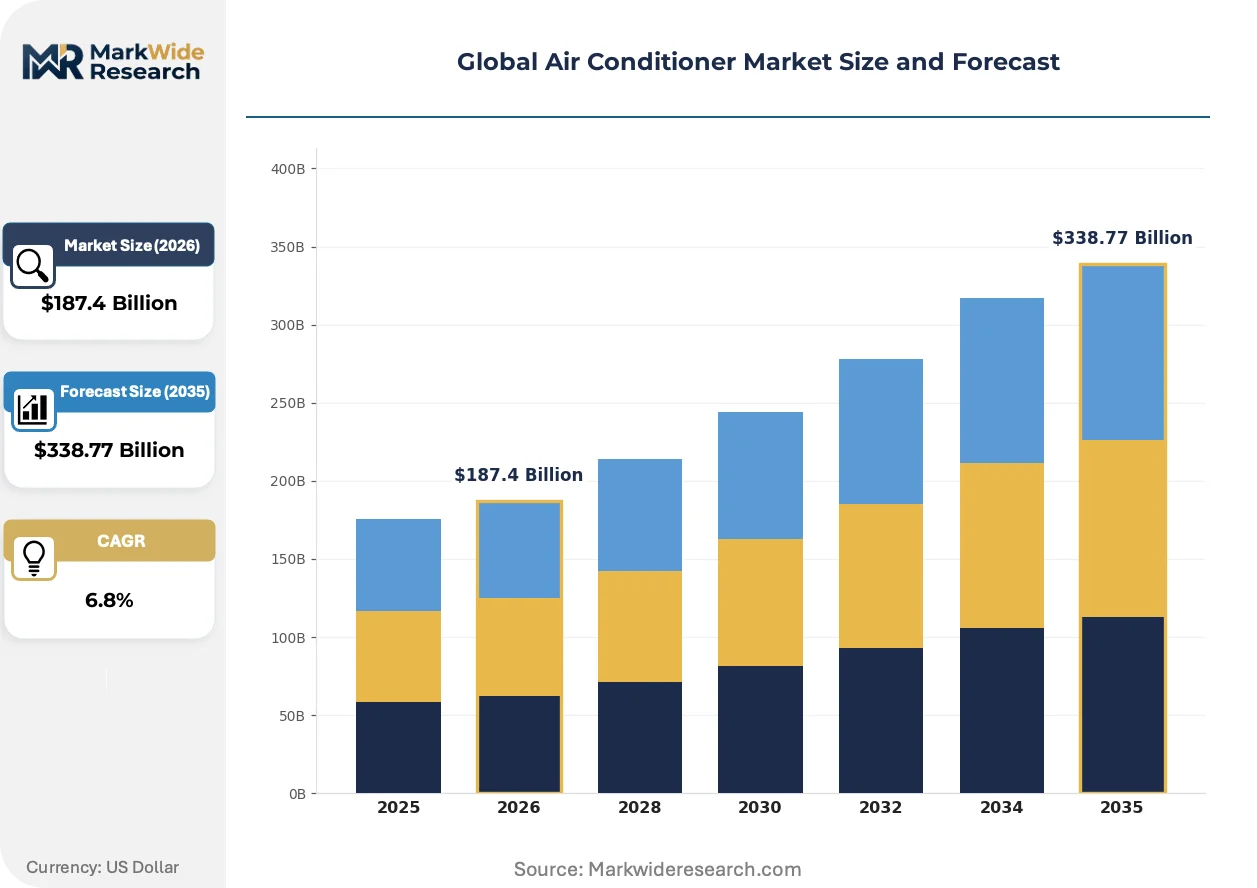
Market Dynamics
Refrigerant chemistry transitions under the F-Gas Regulation are forcing simultaneous compressor redesign, technician retraining, and supply chain reconfiguration across the Global Air Conditioner Market. Manufacturers must synchronize hardware refresh cycles with regional phase-down timelines or risk stranded inventory in key distribution channels.
Growth Catalysts
- India's PLI scheme for component manufacturing:Subsidies for compressor and heat exchanger production are pulling assembly capacity into Gujarat and Tamil Nadu, reducing import dependency for inverter systems.
- Commercial real estate climate mandates:Southeast Asian developers in Bangkok, Jakarta, and Ho Chi Minh City are specifying VRF systems as green building certifications tighten thermal performance requirements.
- R-32 refrigerant adoption:Lower-GWP chemistry is accelerating equipment replacement cycles in Europe and East Asia as service networks phase out R-410A handling capabilities.
Market Restraints
- Rare-earth magnet supply concentration:Neodymium and dysprosium refining capacity clusters in China's Jiangxi and Inner Mongolia, exposing inverter motor manufacturers to export quota volatility.
- Copper and aluminum price volatility:Coil and finstock input costs swing with London Metal Exchange pricing, compressing margins on fixed-price construction contracts.
- Technician certification gaps:F-Gas Regulation mandates for handling A2L mildly flammable refrigerants are narrowing the qualified installer pool in Germany, France, and Italy.
Strategic Opportunities
- Tier-two Indian cities:BIS energy-labeling enforcement and DISCOM peak-load management programs are creating first-time inverter demand in Lucknow, Indore, and Coimbatore.
- Smart-home ecosystem integration:HVAC units connecting to building management systems and utility demand-response networks open recurring software revenue streams alongside hardware sales.
- Retrofit financing structures:Green leasing and energy service company models are unlocking building upgrade cycles in Singapore and Australian commercial property markets.
Industry Challenges
- Refrigerant patent cliff navigation:Manufacturers must time R-454B and R-1234yf adoption to avoid licensing fees while maintaining service network compatibility.
- Legacy system integration complexity:Predictive maintenance sensors and IoT gateways must interface with decades-old building automation protocols in European and North American installed bases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Air Conditioner Market |
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $338.77 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Window, Split, Portable, Central Technology: Inverter, Non-Inverter, Smart, Hybrid End User: Residential, Commercial, Industrial, Automotive Distribution Channel: Online, Offline, Direct, Retail |
| Companies Covered | Carrier Global, LG Electronics, Daikin Industries, Haier Group, Mitsubishi Electric, Gree Electric Appliances, Trane Technologies, Panasonic, Midea Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Air Conditioner Market Emerging Trajectories
Digitalization of thermal management is collapsing traditional boundaries between HVAC hardware, energy software, and grid-interactive services. Three interconnected developments are compressing product lifecycles and rewiring value capture mechanisms.
Variable refrigerant flow systems paired with AI-driven load prediction algorithms are collapsing the performance gap between centralized chillers and distributed split architectures. Large commercial developers in Singapore and Dubai are specifying these hybrid configurations to optimize part-load efficiency across fluctuating occupancy patterns. The technology is compressing the addressable market for conventional rooftop units in mid-rise commercial construction.
Europe's F-Gas Regulation mandates an 80% HFC phase-down by 2030, forcing compressor manufacturers to redesign platforms for A2L refrigerant chemistry at accelerated timelines. The industrial consequence is a bifurcation of service networks between R-32-capable technicians and legacy R-410A operations. Southern European markets including Spain and Portugal face the steepest retraining curves due to fragmented contractor structures.
Building owners are unbundling after-sales service from initial equipment procurement, compressing manufacturer margins on long-term maintenance contracts. Third-party facility management firms in Japan and South Korea are consolidating service purchasing across multi-site portfolios, displacing traditional dealer-captive service models. This procurement compression is most visible in Tokyo's commercial office sector where REITs centralize HVAC asset management.
Global Air Conditioner Market Segmentation
Segmentation in the Global Air Conditioner Market determines service network density requirements and refrigerant handling certification investments. Product architecture and technology tier dictate margin profiles and replacement cycle timing across divergent climate zones and electricity tariff structures.
Product Type:
After-sales service intensity varies sharply across product architectures, with multi-zone systems demanding specialized technician deployment and refrigerant management protocols.
- Split:Wall-mounted and ducted indoor units paired with outdoor condensing modules dominate retrofit installations across Southeast Asian high-rise construction. Demand concentrates in Bangkok, Jakarta, and Ho Chi Minh City where commercial developers specify VRF variants for green building certification compliance.
- Central:Chiller-based systems with air-handling distribution networks anchor large-format commercial and institutional cooling loads. India's pharmaceutical manufacturing clusters in Hyderabad and Ahmedabad drive specification of precision humidity-controlled central plants.
- Window:Self-contained through-wall units serve price-sensitive residential replacement cycles in North American and European legacy housing stock. Compact form factor limits refrigerant charge volumes and simplifies installation labor.
- Portable:Mobile units with exhaust hose configurations address temporary cooling needs in European rental markets and Japanese compact dwellings. Seasonal demand spikes correlate with heat wave frequency in Germany, France, and the UK.
By volume, Split leads. By growth pace, Central is ahead.
Technology:
Cost tier stratification separates premium inverter platforms from entry-level fixed-speed alternatives, with smart connectivity emerging as a distinct value-added layer.
- Inverter:Variable-frequency compressor drives modulate cooling output to match thermal load, cutting electricity consumption during part-load operation. China's GB energy-efficiency standards and India's BIS labeling mandates disqualify non-inverter units from subsidy eligibility, accelerating adoption in tier-two Indian cities.
- Smart:WiFi-enabled units with predictive maintenance algorithms and utility demand-response interfaces command software recurring revenue alongside hardware sales. Singapore's building management system integration requirements and South Korean apartment automation standards drive specification in premium residential segments.
- Non-Inverter:Fixed-speed compressors cycling on/off at full capacity serve price-sensitive markets with stable occupancy patterns. Residual demand persists in Middle Eastern labor accommodation and African informal construction where electricity subsidies blunt operating cost sensitivity.
- Hybrid:Dual-source systems combining vapor-compression with evaporative or solar thermal assist target markets with water availability and high renewable penetration. Pilot deployments concentrate in Australian commercial retrofits and Dubai's sustainable city developments.
By installed base value, Inverter dominates. By expansion trajectory, Smart is climbing the fastest.
End User:
Application-driven specification standards create divergent procurement channels, with commercial and industrial segments unbundling equipment from long-term service contracts.
- Commercial:Office, retail, and hospitality installations prioritize part-load efficiency and zoned temperature control. Southeast Asian REITs in Singapore and Bangkok centralize HVAC asset management across multi-site portfolios, displacing dealer-captive service models.
- Residential:Single-family and multi-family dwellings drive volume through replacement cycles and first-time penetration in emerging markets. India's DISCOM peak-load management programs create inverter demand in Lucknow, Indore, and Coimbatore as tier-two cities electrify.
- Industrial:Process cooling and equipment protection applications demand precision temperature and humidity control. Data center construction in Frankfurt, Amsterdam, and Singapore drives specification of redundant chiller configurations with glycol-based secondary loops.
- Automotive:Electric vehicle thermal management systems integrate cabin comfort with battery pack conditioning. South Korean and Japanese automakers specify heat pump architectures to preserve driving range in cold climate operation.
By unit shipments, Residential leads. By contract value per installation, Industrial is ahead.
Distribution Channel:
Customer type and purchase urgency dictate channel selection, with emergency replacement favoring retail immediacy and planned construction enabling direct procurement negotiation.
- Offline:Bricks-and-mortar dealer networks provide installation coordination and warranty service fulfillment. European F-Gas Regulation certification requirements narrow qualified installer pools in Germany, France, and Italy, reinforcing dealer technical gatekeeping.
- Online:E-commerce platforms with logistics integration capture standard split-system sales in price-transparent markets. China's Alibaba and JD.com ecosystems dominate domestic replacement cycles with next-day delivery and contractor matching services.
- Direct:Manufacturer-to-developer relationships secure large-project specifications with customized engineering support. VRF system procurement for Bangkok, Jakarta, and Ho Chi Minh City commercial towers bypasses wholesale distribution entirely.
- Retail:Big-box and specialty electronics chains serve emergency replacement and seasonal peak demand in North American and European markets. Summer heat wave spikes strain inventory positioning in France, Spain, and the US Southwest.
By transaction volume, Offline leads. By share gain rate, Online is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows concentrate compressor manufacturing in East Asian industrial clusters while European markets absorb premium VRF systems through project finance structures. India's component assembly expansion under PLI subsidies is reducing import dependency for inverter platforms. Southeast Asian commercial construction absorbs Japanese and Korean system exports as green building certifications tighten.
China
Domestic inverter production scales through GB energy-efficiency mandates that disqualify fixed-speed units from subsidy eligibility. MEE enforcement accelerates refrigerant phase-down timelines for industrial cooling applications. Jiangxi and Inner Mongolia host rare-earth magnet refining clusters that supply compressor motor manufacturers with neodymium and dysprosium.
India
PLI scheme subsidies pull compressor and heat exchanger assembly into Gujarat and Tamil Nadu manufacturing zones. BIS energy-labeling enforcement creates market-access barriers for uncertified imports from Southeast Asian trading partners. Lucknow, Indore, and Coimbatore drive first-time inverter penetration as DISCOM peak-load programs electrify tier-two urban corridors.
Germany
F-Gas Regulation mandates compress HFC phase-downs to 80% by 2030, forcing R-410A replacement with A2L refrigerant platforms. Technician certification gaps narrow the qualified installer pool for mildly flammable refrigerant handling. Frankfurt data center construction specifies redundant chiller configurations with glycol-based secondary loops for precision thermal control.
United States
EPA refrigerant management rules under AIM Act provisions accelerate R-454B transition timelines for residential and commercial equipment. Copper and aluminum price volatility on London Metal Exchange compresses margins for fixed-price construction contracts. Southwest summer heat waves strain retail inventory positioning across big-box distribution networks.
Japan
METI building energy codes drive smart-home ecosystem integration for apartment automation standards in premium residential segments. Third-party facility management firms consolidate service purchasing across multi-site commercial portfolios in Tokyo's REIT-dominated office sector. Kansai and Chubu industrial corridors anchor precision compressor manufacturing for export markets.
Global Air Conditioner Market Vendor Landscape
On the supply side, the industry is consolidating around captive component production and backward integration into critical material supply. Tiered competitive positioning separates premium VRF specialists from scale-driven residential manufacturers. Three archetypes dominate: integrated compressor producers, rare-earth magnet controllers, and smart-home ecosystem platforms. Capacity expansion in Indian PLI zones and refrigerant chemistry transitions in Europe constitute the dominant competitive moves reshaping manufacturing footprints.
Among integrated Japanese manufacturers, Daikin Industries and Mitsubishi Electric exemplify the captive-production archetype through in-house compressor platforms and refrigerant technology control. LG Electronics anchors the Korean smart-home vector with ecosystem integration extending software recurring revenue. Gree Electric Appliances represents Chinese scale-driven positioning through upstream control over magnet supply chains for inverter motor production.
| Leading Market Players |
|---|
| Carrier Global |
| LG Electronics |
| Daikin Industries |
| Haier Group |
| Mitsubishi Electric |
| Gree Electric Appliances |
| Trane Technologies |
| Panasonic |
| Midea Group |
| Others |
Supply Flow & Price Mechanics
Compressor overcapacity in China's Jiangsu and Zhejiang provinces is pressuring OEMs to absorb rare-earth magnet cost spikes rather than pass through to buyers, compressing margins on fixed-price construction contracts while forcing tier-two assemblers toward spot aluminum coil purchases.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium VRF, standard inverter split, and economy fixed-speed tiers. Price differentiation separates CE-certified A2L refrigerant platforms from legacy R-410A inventory and uncertified imports. Pricing pressure intensifies as European F-Gas Regulation phase-down timelines accelerate equipment replacement cycles and strand non-compliant inventory. Residential replacement buyers in India's tier-two cities exhibit highest price sensitivity, while Frankfurt and Singapore data center developers accept premium positioning for redundant chiller configurations.
Supply Chain Analysis
Extended payment terms from Japanese trading houses are financing rare-earth magnet stockpiles for inverter motor manufacturers facing Jiangxi export quota volatility. Manufacturing concentrates in China, Thailand, and India, with component assembly pulling toward Gujarat and Tamil Nadu under PLI subsidies. Coil and finstock draw from London Metal Exchange-priced copper and aluminum, exposing margins to commodity swings. Single-source vulnerability clusters in dysprosium refining capacity. Distribution runs through dealer-captive networks in Europe and direct manufacturer-developer relationships for Southeast Asian commercial towers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Air Conditioner Market is entering a cyclical recovery phase as post-pandemic commercial construction backlog clears and refrigerant chemistry transitions force replacement cycles. Replacement demand concentrates in Europe and India where regulatory phase-downs disqualify legacy equipment.
For Market Incumbents: Build captive compressor production moats to defend margin control against rare-earth magnet supply volatility. Secure A2L refrigerant handling certification across service networks before F-Gas Regulation technician gaps widen in Germany, France, and Italy. Anchor installed-base lock-in through predictive maintenance software subscriptions that interface with building management systems. For New Entrants and Emerging Players: Establish a beachhead in India's tier-two inverter retrofit segment where BIS energy-labeling enforcement creates first-time certification demand in Lucknow, Indore, and Coimbatore. Target green leasing structures for Singapore and Australian commercial property retrofits where project finance unbundles equipment from service procurement. Deploy utility demand-response integration as a differentiated software revenue layer. For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale compressor manufacturers with backward integration into rare-earth magnet supply and established service network density in European A2L transition markets. Long-term viability hinges on refrigerant patent cliff navigation and IoT platform recurring revenue attachment. Watch R-454B adoption timelines as inflection signal for stranded R-410A inventory risk.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Compressor Manufacturing | Daikin and Mitsubishi Electric sustain margin control through in-house production platforms. |
| Rare-Earth Magnet Supply Integration | Gree Electric Appliances anchors cost position through upstream control of neodymium sourcing. |
| Smart-Home Ecosystem Integration | LG Electronics extends software recurring revenue alongside hardware through building automation interfaces. |
| A2L Refrigerant Service Certification | European F-Gas Regulation mandates retrain technician pools in Germany, France, and Italy. |
| Green Leasing Structure Deployment | Singapore REITs unlock retrofit cycles through project finance unbundling equipment from maintenance. |
Methodological Framework
The analysis maps inverter technology tiers, refrigerant chemistry transitions, and smart connectivity segments, each validated through plant engineers at compressor manufacturers, procurement leads at commercial real estate developers, service network heads at dealer operations, and regulatory affairs specialists at OEMs. Primary interview findings triangulate against secondary sources including MEE enforcement bulletins, BIS certification registries, F-Gas Regulation implementation guidance, and customs trade data for compressor and heat exchanger flows. Bottom-up unit economics and top-down market sizing converge through cross-validation against DISCOM peak-load program disclosures and green building certification databases.
Assumptions hold fixed current GB energy-efficiency tier structures, F-Gas Regulation phase-down timelines, and PLI subsidy eligibility criteria while varying copper and aluminum price trajectories, rare-earth export quota stringency, and technician certification completion rates across the projection horizon. Segmentation models disaggregate by product architecture, compressor drive technology, refrigerant chemistry, end-use application, and regional regulatory cluster. CAGRs derive from fitted growth curves against historical replacement cycle data and electrification penetration rates in tier-two Indian cities.
Sensitivities concentrate around refrigerant patent cliff timing, A2L service network density achievement, and DISCOM peak-load program expansion. Forecasts reflect documented assumptions regarding subsidy continuity and regulatory enforcement intensity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Ventilation Fan Market
HVAC Equipment
Thermo Ventilators Market
HVAC Equipment
HVAC Air Handling Units Market
HVAC Equipment
Canada Outdoor Air Source Heat Pump Market
HVAC Equipment
Air Conditioner Quilt Market
HVAC Equipment
Industrial Air Heaters Market
HVAC Equipment
Global Industrial Fans and Blowers Market
HVAC Equipment
Variable Refrigerant Flow (VRF) System Market
HVAC Equipment
Industrial Blowers Market
HVAC Equipment
US Residential HVAC Systems Market
HVAC Equipment
Global Large-Scale Natural Refrigerant Heat Pump Market
HVAC Equipment
Swing Compressor Market
HVAC Equipment
Industrial Insulation Testers Market
HVAC Equipment
Global HVAC Linesets Market
HVAC Equipment
Europe Dehumidifier Market
HVAC Equipment
Industrial Air Blower Market