
 3D Printing Building Construction Market | 2026-2036
3D Printing Building Construction Market Size, Share, and Industry Trends Forecast 2026-2036
3D Printing Building Construction Market Analysis
Aftermarket service revenue from printer maintenance and material supply logistics is rewriting how construction technology vendors capture lifetime value. COBOD International A/S anchors the European equipment landscape through its BOD2 gantry systems. ICON Technology Inc. dominates North American project execution with its Vulcan printer fleet deployed across Texas and Mexico. Yingchuang Building Technique controls Asian volume through proprietary cementitious mixtures optimized for high-speed extrusion.
3D printing building construction deploys layer-by-layer additive manufacturing to fabricate structural and non-structural building elements directly from digital models, typically extruding concrete or geopolymers through computer-controlled nozzles at deposition rates exceeding one meter per second for walls and foundations. The process eliminates traditional formwork, reduces material waste by precise dosage control, and enables complex geometries impractical with conventional casting. Material extrusion technology leads current installations due to its compatibility with standard concrete formulations and lower capital thresholds. Infrastructure applications represent the fastest-expanding segment as transportation agencies evaluate printed bridge components and culverts. Onsite construction deployment still captures the dominant share of project value, though offsite manufacturing gains traction for repetitive modular units in residential programs.
The EU Construction Products Regulation and associated CE marking requirements shape market access by demanding declared performance characteristics for printed concrete durability and fire resistance. The US EPA oversees emissions from cement production feeding printer operations, while OSHA addresses silica exposure during material handling and post-processing. Stakeholders must monitor evolving national building codes that alternately accelerate or stall permitting for habitable printed structures.
Market Dynamics
Material extrusion technology is compressing project timelines while the EU Construction Products Regulation mandates performance declarations that filter subscale equipment vendors from commercial viability.
Growth Catalysts
- Affordable housing procurement:Sovereign developers in Gulf Cooperation Council states fund large-scale demonstration projects that validate printed structural units for residential deployment.
- CE marking pathways:The EU Construction Products Regulation creates transparent compliance routes for novel concrete durability certifications, accelerating market access for qualified systems.
- Geopolymer formulation advances:Proprietary cementitious mixtures optimized for high-speed extrusion are expanding the addressable material set beyond conventional concrete.
Market Restraints
- Silica exposure compliance:OSHA workplace standards elevate material handling costs during post-processing operations, particularly for small contractors lacking industrial hygiene infrastructure.
- Equipment supply concentration:Gantry system manufacturing clusters in Northern Europe create lead time vulnerability for non-European project developers.
- Cast-in-place substitution economics:Traditional formwork contractors in mature construction markets underbid printed alternatives on simple geometries.
Strategic Opportunities
- Transportation infrastructure white space:Bridge components and culverts represent underpenetrated applications where transportation agencies evaluate additive manufacturing for complex geometries.
- Offsite manufacturing channels:Repetitive modular residential programs are shifting volume to factory-controlled environments that decouple production from weather and site logistics.
- EPA emissions frameworks:Cement production oversight creates competitive differentiation for low-carbon binder formulations that align with federal environmental compliance trajectories.
Industry Challenges
- Building code integration timelines:Municipal permitting offices lack standardized evaluation protocols for habitable printed structures, stretching project approval cycles.
- Digital fabrication skill scarcity:Construction labor pools require retraining in CAD-to-fabrication workflows, nozzle calibration, and layer adhesion quality control.
- Capex intensity for gantry deployment:Site preparation and printer mobilization demand upfront capital commitments that strain contractor balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D Printing Building Construction Market |
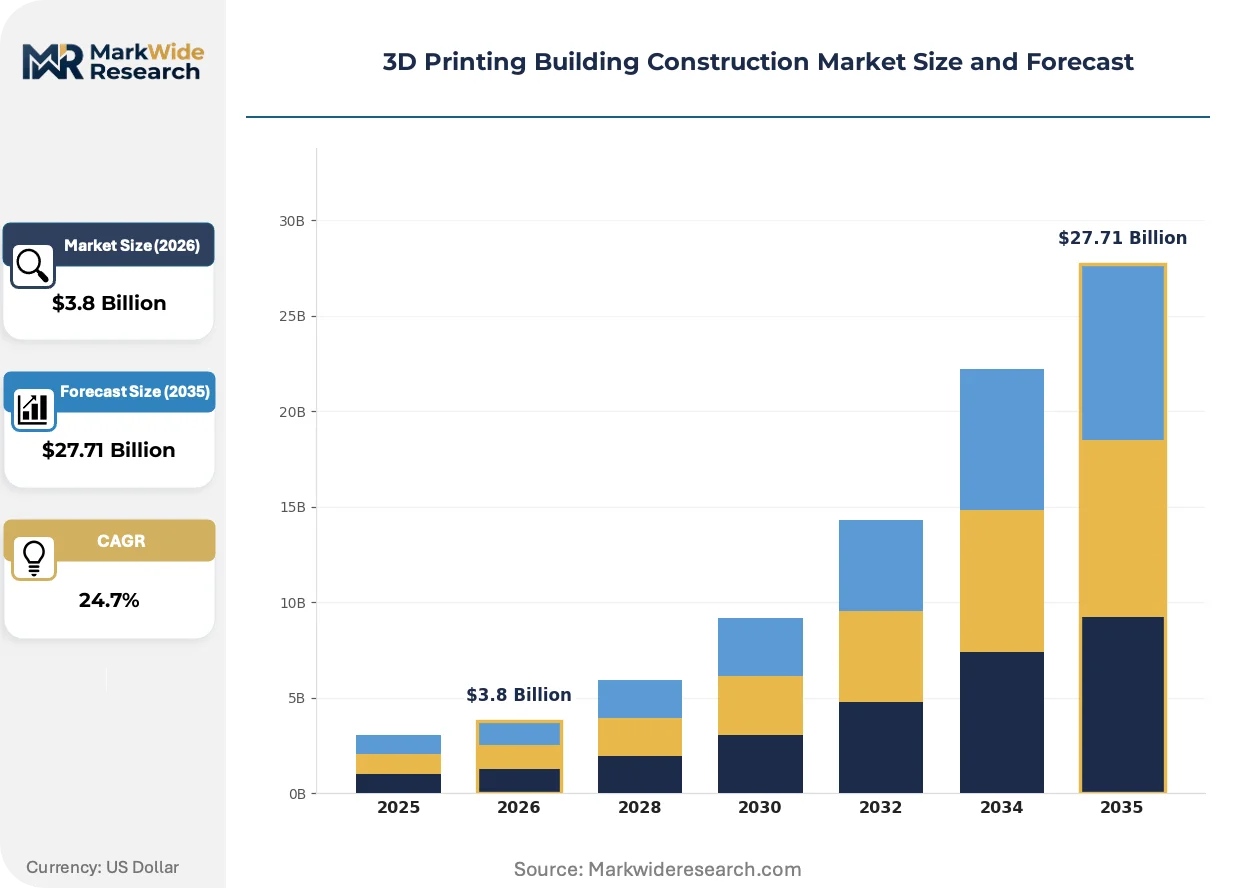
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $27.71 Billion |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Fused Deposition Modeling, Binder Jetting, Material Extrusion, Selective Laser Sintering Application: Residential Structures, Commercial Buildings, Infrastructure Projects, Decorative Elements Material: Concrete, Plastics, Metals, Composite Materials Deployment: Onsite Construction, Offsite Manufacturing, Hybrid Approaches, Remote Locations |
| Companies Covered | Apis Cor, COBOD International A/S, ICON Technology Inc., Yingchuang Building Technique, XtreeE, CyBe Construction, Mighty Buildings, Contour Crafting Corporation, Alquist 3D, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D Printing Building Construction Market Emerging Trajectories
Construction additive manufacturing is converging with automation and materials science to redefine how structural elements move from digital models to physical installation.
Multi-material extrusion systems is hybridizing concrete deposition with integrated insulation and reinforcement placement. Infrastructure contractors in transportation agencies are piloting these configurations for bridge deck segments. The technology is compressing the traditional sequence of structural, thermal, and finishing trades into continuous fabrication cycles.
REACH chemical registration requirements are extending scrutiny to novel geopolymer activators and admixtures used in printable mixtures. Industrial consequence includes reformulation costs for material suppliers seeking European market access. Printed concrete durability testing protocols are most affected, with certification laboratories expanding accelerated aging capacity to meet declared performance timelines.
Buyer aggregation through sovereign wealth funds and affordable housing agencies is consolidating project pipelines into multi-year equipment procurement agreements. Traditional equipment leasing channels face displacement from direct manufacturer-funder relationships. Texas and Mexico project clusters demonstrate this pattern most visibly, with developers securing dedicated printer capacity through volume commitments rather than spot rentals.
3D Printing Building Construction Market Segmentation
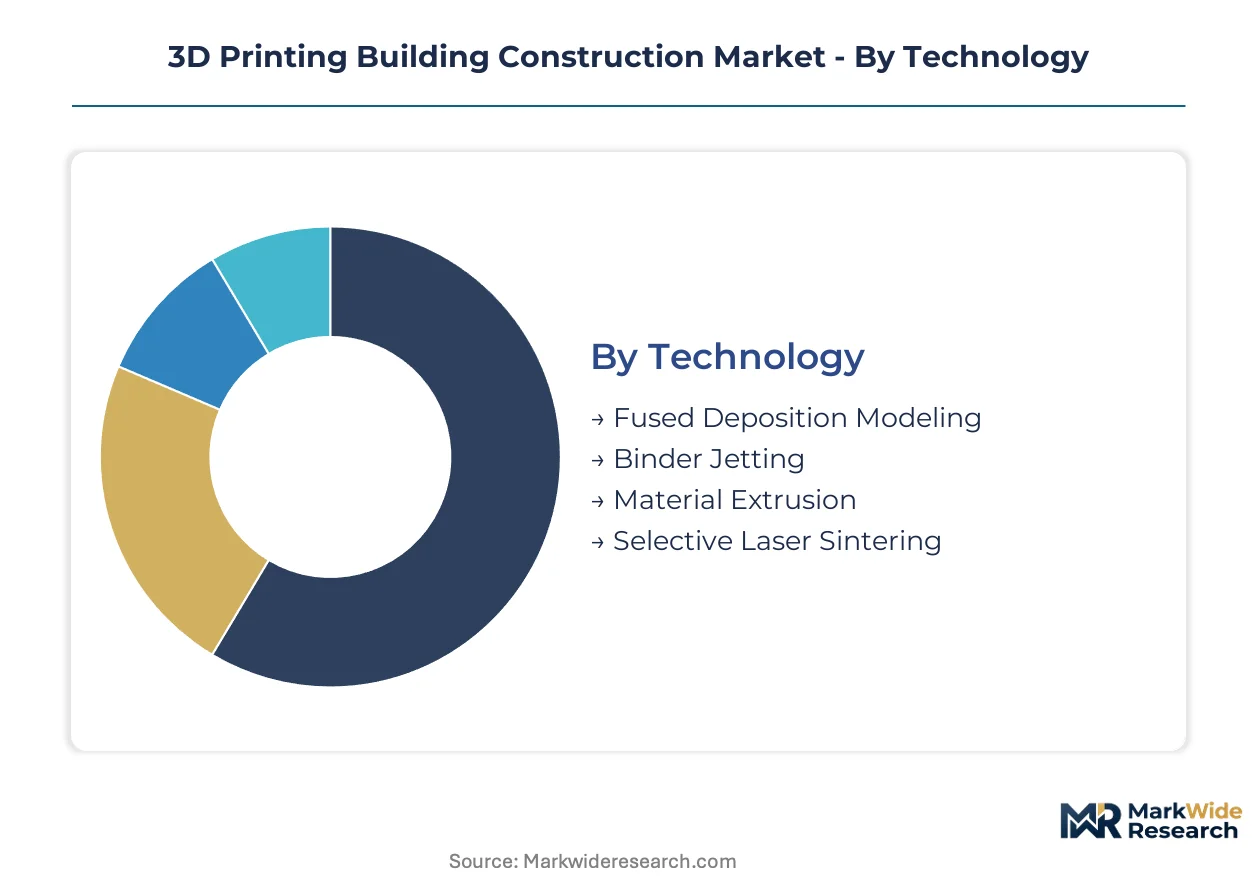
Construction additive manufacturing segments by technology readiness, material compatibility, and project logistics. Equipment depreciation cycles and material formulation patents create divergent margin profiles across categories. Procurement patterns cluster around gantry system availability and regional cement supply chains.
Technology:
Material extrusion compresses wall assembly from weeks to days, while binder jetting and laser-based methods face longer validation timelines for structural certification.
- Material Extrusion:Computer-controlled nozzles deposit concrete or geopolymers layer-by-layer at deposition rates exceeding one meter per second. The Gulf Cooperation Council states concentrate procurement here as sovereign developers validate printed structural units for residential deployment under accelerated project schedules.
- Binder Jetting:Liquid binding agents selectively join powder bed layers to form complex geometries without thermal stress. Infrastructure applications in bridge components and culverts drive evaluation, though transportation agencies await durability testing protocols before commercial scale-up.
- Fused Deposition Modeling:Thermoplastic filament extrusion adapted for construction-scale polymer forms and architectural mock-ups.
- Selective Laser Sintering:Powder fusion systems limited to specialized metal connectors and small-format hardware production.
Material extrusion dominates installed base. Binder jetting is where expansion concentrates for transportation infrastructure applications.
Application:
Residential programs generate recurring volume through affordable housing agencies, while infrastructure projects demand higher performance certification but offer larger per-contract value.
- Infrastructure Projects:Bridge deck segments, culverts, and transportation agency pilot programs evaluate additive manufacturing for geometries impractical with conventional casting. The EU Construction Products Regulation mandates performance declarations for printed concrete durability that filter subscale vendors from commercial viability in this segment.
- Residential Structures:Single-family and multi-unit housing programs deploy printed walls and foundations with reduced formwork costs. Texas and Mexico project clusters demonstrate volume commitment patterns where developers secure dedicated printer capacity through multi-year procurement agreements rather than spot rentals.
- Commercial Buildings:Office and retail structures requiring fire resistance certification under extended code review timelines.
- Decorative Elements:Facade panels and architectural features prioritizing aesthetic complexity over structural load-bearing.
Residential structures anchor current revenue. Infrastructure projects are climbing the fastest as transportation agencies advance from pilot to procurement.
Material:
Standard concrete formulations minimize supply chain reconfiguration, while geopolymers and composites command premium positioning through carbon reduction claims.
- Concrete:Ordinary Portland cement blends optimized for pumpability and layer adhesion dominate current installations. The US EPA oversees emissions from cement production feeding printer operations, creating competitive differentiation for low-carbon binder formulations that align with federal environmental compliance trajectories.
- Composite Materials:Fiber-reinforced and hybrid matrices enable thinner structural sections with enhanced tensile performance. Proprietary cementitious mixtures optimized for high-speed extrusion are expanding the addressable material set beyond conventional concrete in Asian volume deployment.
- Plastics:Recycled polymer feedstocks for non-structural forms and temporary works.
- Metals:Specialized alloys for connection hardware and reinforcement elements requiring post-print machining.
Concrete commands the dominant material share. Composite materials represent the steepest expansion trajectory as durability certification protocols mature.
Deployment:
Onsite mobilization eliminates transportation logistics for large elements, while offsite manufacturing decouples production from weather and site access constraints.
- Onsite Construction:Gantry systems positioned directly at building sites fabricate walls and foundations without module transport. Site preparation and printer mobilization demand upfront capital commitments that strain contractor balance sheets, particularly for small operators lacking industrial hygiene infrastructure for silica exposure compliance.
- Offsite Manufacturing:Factory-controlled environments produce repetitive modular residential units with standardized quality protocols. Repetitive modular residential programs are shifting volume to environments that decouple production from weather and site logistics, accelerating throughput for affordable housing agencies.
- Hybrid Approaches:Partial pre-assembly with final joining operations conducted at destination sites.
- Remote Locations:Deployable printer configurations for mining camps, military installations, and disaster response with limited supply chain access.
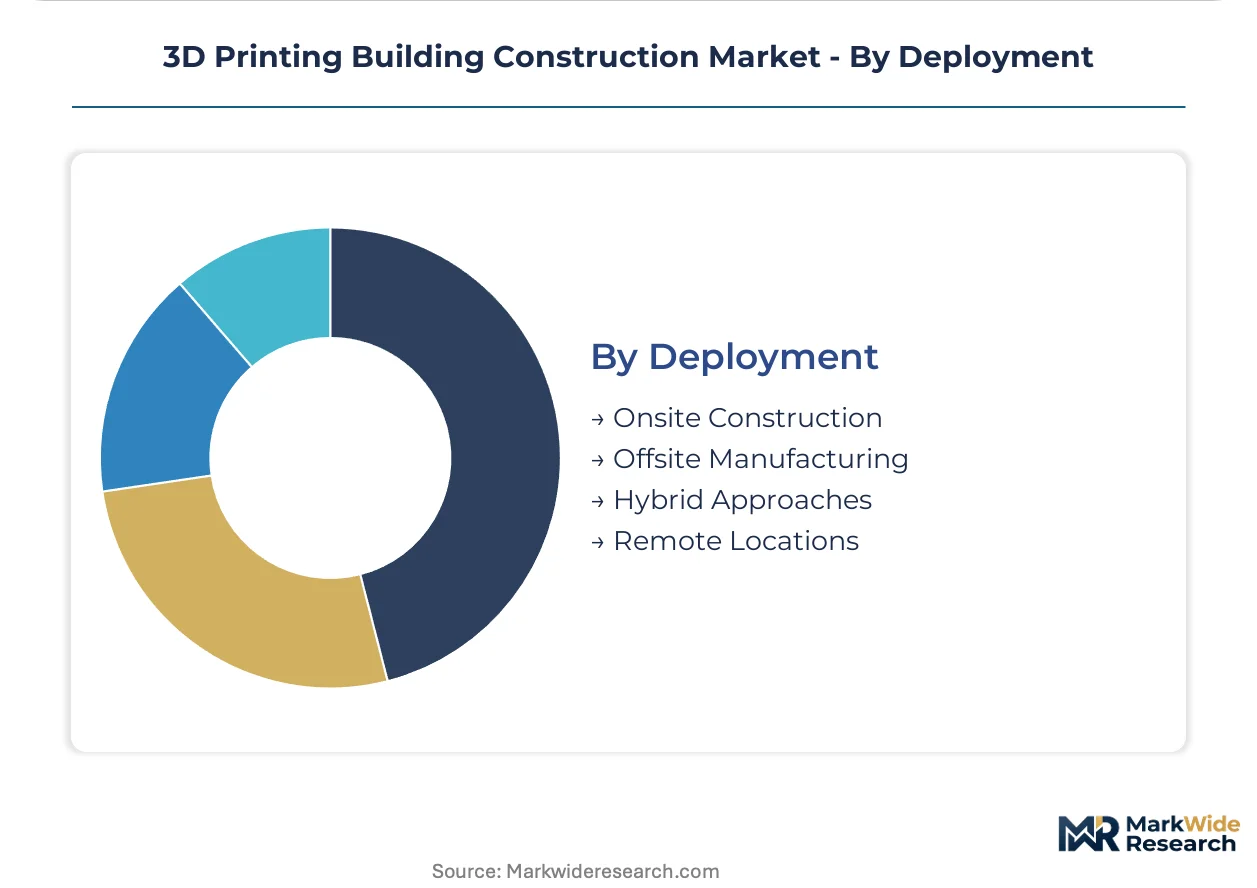
Onsite construction retains the dominant project value share. Offsite manufacturing is gaining share fastest as factory certification pathways streamline permitting cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gantry system manufacturing clusters in Northern Europe and sovereign-funded demonstration projects in the Gulf Cooperation Council states concentrate supply-side capacity. National building codes and environmental regulations fragment market access across jurisdictions. Project pipelines cluster around affordable housing agencies and transportation infrastructure authorities with dedicated procurement budgets.
United States
Texas and Mexico project clusters demonstrate volume commitment patterns where developers secure dedicated printer capacity through multi-year procurement agreements. OSHA workplace standards elevate material handling costs during post-processing operations, particularly for small contractors lacking industrial hygiene infrastructure. Austin and surrounding metros anchor North American project execution with sovereign wealth fund participation in residential demonstration programs.
Germany
Industrial equipment fabricators in Northern Europe supply gantry systems to non-European project developers facing lead time vulnerability. The EU Construction Products Regulation and associated CE marking requirements demand declared performance characteristics for printed concrete durability and fire resistance. Bavaria and Baden-Württemberg concentrate equipment engineering talent and certification laboratory capacity for accelerated aging protocols.
United Arab Emirates
Sovereign developers fund large-scale demonstration projects that validate printed structural units for residential deployment across Gulf Cooperation Council states. MOHAP building safety frameworks intersect with federal environmental compliance for cement production emissions. Dubai and Abu Dhabi anchor demonstration project pipelines with affordable housing agencies expanding procurement of printed structural units.
China
Proprietary cementitious mixtures optimized for high-speed extrusion expand the addressable material set beyond conventional concrete in Asian volume deployment. MIIT industrial standards and GB construction codes govern equipment certification and material performance declarations. Yangtze River Delta manufacturing bases concentrate material formulation R&D and printer component supply chains.
Saudi Arabia
NEOM and giga-project construction schedules compress timelines for printed foundation and wall assembly validation. SFDA building material safety registration and SASO quality conformity programs shape import and domestic production requirements. Riyadh and Eastern Province development authorities integrate printed structural units into sovereign-funded residential and infrastructure programs.
3D Printing Building Construction Market Vendor Landscape
Equipment manufacturers and project execution specialists split the market between capital-intensive gantry system supply and operational deployment capabilities. The vendor base concentrates around Northern European engineering heritage and North American project finance access. Two strategic archetypes dominate: integrated equipment-and-materials platforms and pure-play construction operators. Competitive moves center on multi-year procurement agreements with sovereign developers and factory certification pathways that streamline permitting cycles.
Among European equipment fabricators, COBOD International A/S anchors the capital goods tier with Danish engineering pedigree. ICON Technology Inc. and Yingchuang Building Technique represent the integrated platform model across North American and Asian markets respectively. Apis Cor and Mighty Buildings occupy positions within the project execution specialist archetype, with the former reflecting Russian-origin equipment heritage and the latter exemplifying California-based operational focus. XtreeE and CyBe Construction sit within the European mid-market equipment supply segment, while Contour Crafting Corporation and Alquist 3D represent North American construction operators with distinct geographic concentration patterns.
| Leading Market Players |
|---|
| Apis Cor |
| COBOD International A/S |
| ICON Technology Inc. |
| Yingchuang Building Technique |
| XtreeE |
| CyBe Construction |
| Mighty Buildings |
| Contour Crafting Corporation |
| Alquist 3D |
| Others |
Supply Flow & Price Mechanics
Rotterdam-Dubai maritime corridors carry gantry system components and specialized cementitious mixtures that concentrate supply-side leverage in Northern European fabricators, compressing margins for non-European project developers while enabling tiered pricing across CE-marked premium systems and uncertified economy alternatives.
Pricing Analysis
The EU Construction Products Regulation dictates the pricing tier structure across the market, separating CE-marked premium systems with validated durability declarations from uncertified economy alternatives lacking fire resistance documentation. Price differentiation hinges on certification grade and geographic delivery cost, with Gulf Cooperation Council sovereign developers absorbing premium positioning for accelerated project schedules. Cost compression in the economy tier is intensifying as traditional formwork contractors underbid printed alternatives on simple geometries. Small contractors lacking industrial hygiene infrastructure exhibit the highest price sensitivity, while sovereign wealth funds demonstrate the least.
Supply Chain Analysis
Tariff exposure between Germany and non-European project developers dominates supply chain risk planning for gantry system procurement. Manufacturing concentrates in Denmark, Germany, and China, with the Yangtze River Delta anchoring material formulation R&D and printer component fabrication. Raw material dependencies center on Ordinary Portland cement, proprietary geopolymer activators, and fiber reinforcement additives. Single-source vulnerability persists for gantry system manufacturing clusters in Northern Europe. Distribution runs through direct manufacturer-funder relationships displacing traditional equipment leasing channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aftermarket service revenue from printer maintenance and material supply logistics is expanding faster than hardware sales, repositioning vendor economics around lifetime value capture rather than transactional equipment placement.
For Market Incumbents: Harden defensive positioning through backward integration into proprietary cementitious mixture supply, securing captive feedstock for high-speed extrusion systems. Expand certification laboratory capacity in Bavaria and Baden-Württemberg to accelerate CE marking timelines and filter subscale competitors from commercial viability. Threat substitution from traditional formwork contractors demands margin protection through multi-year procurement agreements with sovereign developers.
For New Entrants and Emerging Players: Pursue transportation infrastructure white space in bridge components and culverts where durability testing protocols remain underdeveloped and incumbent certification advantages are weakest. Target North American project execution through OSHA-compliant material handling infrastructure partnerships that elevate small contractor operational barriers. Go-to-market positioning should emphasize factory-controlled offsite manufacturing channels that decouple production from weather and site logistics constraints.
For Investors and Strategic Acquirers: Regional project execution specialists with demonstrated permitting navigation capabilities in Texas and Mexico represent the most compelling acquisition archetype for platform consolidation. Long-term viability across the analysis window rests on demonstrated ability to secure dedicated printer capacity through volume commitments rather than spot rental economics. The signal to watch is municipal building code integration timelines—accelerated standardization protocols for habitable printed structures would mark inflection toward mainstream procurement.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Year Procurement Agreements | Sovereign developers in Gulf Cooperation Council states secure dedicated printer capacity through volume commitments rather than spot rentals. |
| CE Marking Pathway Investment | Certification laboratory expansion in Bavaria accelerates declared performance timelines for printed concrete durability under EU Construction Products Regulation. |
| Geopolymer Formulation R&D | Proprietary cementitious mixtures optimized for high-speed extrusion expand addressable material sets beyond conventional concrete in Asian volume deployment. |
| Offsite Manufacturing Scale-Up | Factory-controlled environments for repetitive modular residential programs decouple production from weather and site logistics constraints. |
| Aftermarket Service Infrastructure | Printer maintenance and material supply logistics networks capture lifetime value exceeding transactional equipment placement economics. |
Methodological Framework
Initial hypotheses were tested against primary input from equipment engineering directors, sovereign developer procurement leads, certification laboratory technical managers, and aftermarket service heads, then refined through secondary validation against SEC filings from construction technology vendors, EU Construction Products Regulation documentation, EPA emissions oversight records, and customs data for gantry system trade flows. Bottom-up project pipeline enumeration triangulated against top-down equipment manufacturer shipment records.
Demand-supply balance modeling across the projection horizon segmented by technology readiness, material compatibility, application type, and deployment mode, with CAGRs derived from equipment depreciation cycles and material formulation patent expiration timelines. Forecast inputs incorporated municipal building code integration timelines and affordable housing agency procurement budget trajectories.
Macroeconomic conditions sit as an overlay; deviation in sovereign wealth fund allocation priorities, cement production emissions enforcement intensity, or construction labor retraining program funding would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory pathway maturation and equipment certification standardization. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Construction
Pre-Engineered Building Market
Building Construction
Spain Construction Market
Building Construction
ASEAN Prefab Wood Buildings Market
Building Construction
Italy Construction Market
Building Construction
North America Prefabricated Buildings Market
Building Construction
UAE Prefab Wood Buildings Market
Building Construction
Dominican Republic Construction Market
Building Construction
Honduras Construction Market
Building Construction
Brazil Construction Market
Building Construction
Russia Prefabricated Buildings Market
Building Construction
United Kingdom Data Center Construction Market
Building Construction
Latin America Construction Market
Building Construction
Saudi Arabia Prefab Wood Buildings Market
Building Construction
US Modular Construction Market
Building Construction
Egypt Construction Market
Building Construction
Middle East Data Center Construction Market