
 South Korea Transportation Infrastructure Construction Market | 2026-2036
South Korea Transportation Infrastructure Construction Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Transportation Infrastructure Construction Market Analytics
Grade-separated expressway specifications is rotating toward higher seismic resilience ratings and extended design-life thresholds. Samsung C&T leverages its integrated engineering-procurement-construction capability to secure complex interchange contracts. Hyundai E&C anchors the railway segment through dedicated trackwork subsidiaries and tunnel-boring expertise.
South Korea transportation infrastructure construction encompasses the civil engineering, materials deployment, and systems integration required to build and rehabilitate road, rail, bridge, and airport assets with design loads typically calibrated for 100-year service life and peak ground acceleration thresholds exceeding 0.3g. The primary purpose is sustaining national logistics velocity while hardening networks against geohazard exposure. Railway and bridge project types command premium engineering margins due to specialized substructure requirements and limited domestic contractor pools. Concrete and steel material categories dominate procurement volumes, though composite reinforcement is gaining share in coastal corrosion zones where lifecycle cost calculations favor fiber-reinforced polymer applications.
MFDS safety standards for construction material certification, KOSHA occupational exposure limits, and MOTIE energy-efficiency benchmarks for transport facilities collectively shape contractor qualification requirements and project bidding parameters. The Korea Land & Geospatial Informatix Corporation's digital twin mandates for major corridor projects are tightening data interoperability requirements across design and construction phases. Stakeholders must calibrate technology roadmaps against evolving smart infrastructure procurement criteria before the next national plan revision cycle locks in technical specifications.
Market Dynamics
Urban rail expansion in the Seoul metropolitan corridor is compressing procurement cycles and forcing domestic contractors to accelerate design-build integration. The Korea Expressway Corporation's digital tolling mandates are simultaneously reshaping project specifications across the national expressway network.
Growth Catalysts
- Seoul Metropolitan Rail Procurement:The Ministry of Land, Infrastructure and Transport's five-year capital allocation for urban rail corridors is pulling forward contract awards for tunnel-boring and trackwork specialists.
- MFDS Material Certification Standards:Enhanced safety protocols for construction material testing are creating qualified supplier premiums that reward domestic producers with certified production lines.
- Busan Port-Rail Intermodal Upgrades:Container throughput expansion at Korea's largest maritime gateway is driving dedicated freight corridor investments linking the port to inland distribution centers.
Market Restraints
- Steel Price Volatility:Rebar and structural steel input costs fluctuate with global scrap and billet indices, compressing fixed-price contract margins for bridge and viaduct projects.
- Specialized Contractor Concentration:Tunnel-boring machine operation and segment manufacturing capabilities cluster among three domestic equipment lessors, creating bottleneck risk for concurrent rail projects.
- KOSHA Occupational Exposure Compliance:Silica dust and vibration monitoring requirements extend site preparation timelines and inflate temporary works budgets.
Strategic Opportunities
- Gwangju Metropolitan Rail Extension:The Honam region's underserved urban transit network presents greenfield corridor development potential for integrated design-build consortia.
- Fiber-Reinforced Polymer Convergence:Composite reinforcement hybridization with conventional rebar is opening coastal bridge maintenance contracts where lifecycle cost calculations override first-cost preferences.
- Korea Land & Geospatial Informatix Digital Twin Mandates:BIM-to-asset-management data interoperability requirements are creating first-mover advantages for contractors with proprietary 4D modeling platforms.
Industry Challenges
- Tunnel-Boring Specialist Scarcity:Licensed TBM operators and segment erection crews command wage premiums that distort project labor cost forecasts.
- Legacy Highway Tolling Integration:Expressway Corporation's mixed fleet of RFID and video-tolling infrastructure requires hybrid system architecture that complicates smart mobility retrofits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Transportation Infrastructure Construction Market |
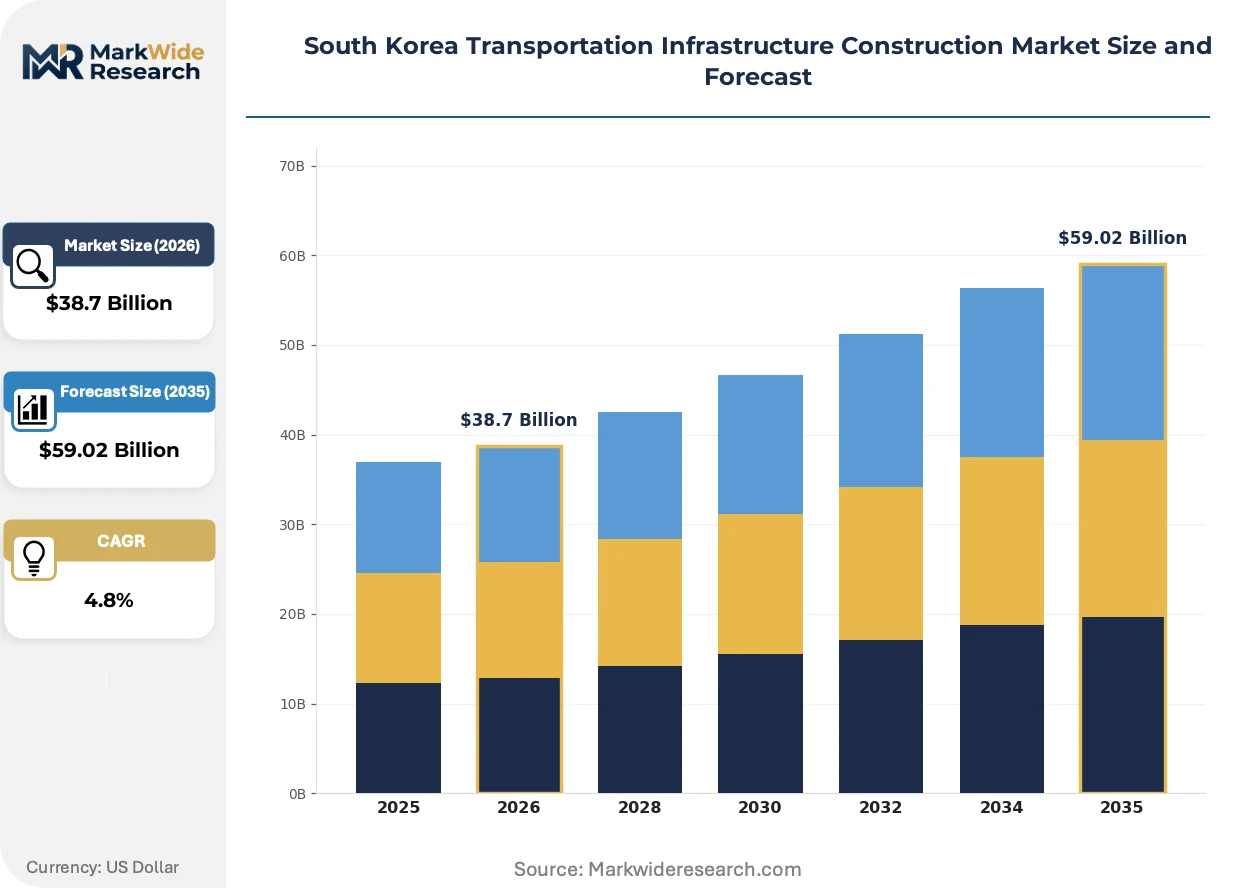
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $59.02 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Project Type: Roads, Bridges, Railways, Airports Material Type: Concrete, Steel, Asphalt, Composites Construction Method: Traditional, Modular, Precast, In situ Funding Source: Public Sector, Private Investment, PPP, International Loans |
| Companies Covered | GS E&C, POSCO E&C, Samsung C&T, Hoban Construction, Lotte E&C, Hyundai E&C, Daewoo E&C, Hanwha Engineering & Construction, Daelim Industrial, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Transportation Infrastructure Construction Market Evolving Landscape
Digital construction methodologies are decomposing traditional design-bid-build sequences across South Korea's major transportation corridors. Contractors now face compressed delivery timelines that reward real-time data interoperability over document-based handoffs.
Ultra-high-performance concrete is decomposing conventional precast segment specifications for immersed tube tunnels and cable-stayed bridge decks. Korea Expressway Corporation specifications now permit UHPC for expansion joint repairs and deck overlays on high-traffic corridors. The material's superior compressive strength and chloride resistance is compressing maintenance cycle frequencies in coastal exposure zones.
MOTIE energy-efficiency benchmarks for transport facilities are mandating LED tunnel lighting, regenerative braking systems, and solar-integrated noise barriers on new alignments. Project developers must demonstrate lifecycle carbon calculations to qualify for green financing windows. The railway segment bears the heaviest compliance burden, with station HVAC and traction power systems subject to real-time monitoring requirements.
Public-sector procurement is consolidating contract packaging across the Seoul metropolitan rail program. The Ministry of Land, Infrastructure and Transport now favors single-source responsibility for civil works, systems integration, and preliminary operations rather than segmented bidding. This bundling is most visible on the GTX corridors, where design-build-operate contracts span 30-year concession periods.
South Korea Transportation Infrastructure Construction Market Segmentation
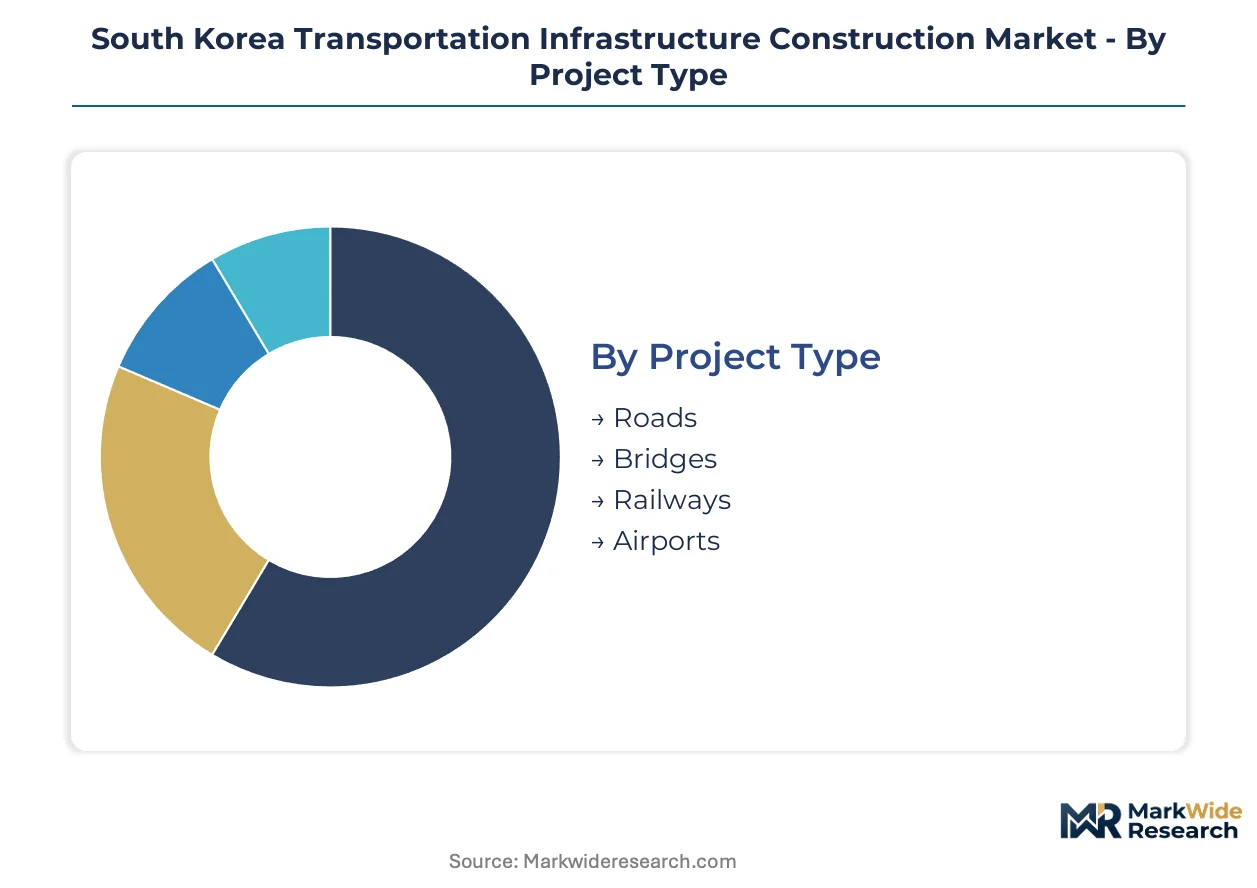
Transportation infrastructure construction in South Korea fragments across project specifications, material procurement, and delivery methodologies. Each segmentation dimension carries distinct margin profiles and regulatory compliance burdens that shape contractor bidding strategies. Understanding these divisions reveals where capital allocation concentrates and where technical differentiation creates competitive moats.
Project Type:
Railway and bridge contracts flow through MOTIE's consolidated procurement channels, while road and airport projects distribute across Korea Expressway Corporation and regional airport authority tender processes.
- Railways:Tunnel-boring and trackwork specialization commands premium engineering margins due to limited domestic contractor pools and MOTIE's 100-year design-life mandates. Demand concentrates in the Seoul metropolitan corridor where GTX corridor awards are compressing procurement cycles and forcing accelerated design-build integration.
- Bridges:Cable-stayed and immersed-tube specifications require seismic resilience ratings exceeding 0.3g peak ground acceleration with extended service-life thresholds. The Greater Busan region absorbs significant capital allocation for port-rail intermodal viaducts where geohazard exposure drives substructure investment.
- Roads:Expressway widening and urban arterial upgrades dominate public-sector tender volumes.
- Airports:Runway rehabilitation and terminal expansion projects concentrate at Incheon and Gimhae gateways.
Railways dominate installed base value. Bridges represent where expansion concentrates most steeply.
Material Type:
Cost tier stratification separates commodity bulk procurement from certified specialty grades that qualify for MFDS safety protocols and coastal corrosion zones.
- Concrete:Ultra-high-performance formulations are decomposing conventional precast segment specifications for immersed tube tunnels and cable-stayed bridge decks. Korea Expressway Corporation specifications now permit UHPC for expansion joint repairs on high-traffic corridors where chloride resistance compresses maintenance frequencies.
- Steel:Rebar and structural sections face margin compression from global scrap and billet price volatility. Fixed-price contract exposure for bridge and viaduct projects intensifies procurement risk management requirements.
- Asphalt:Wearing course and binder specifications vary by traffic load classification and climate zone.
- Composites:Fiber-reinforced polymer hybridization with conventional rebar is opening coastal bridge maintenance contracts where lifecycle cost calculations override first-cost preferences in Busan and Ulsan exposure zones.
Concrete anchors procurement volumes. Composites represent the steepest expansion trajectory as lifecycle accounting penetrates maintenance specifications.
Construction Method:
Volume distribution favors traditional and in situ techniques for legacy asset rehabilitation, while modular and precast adoption accelerates on greenfield corridors where schedule compression rewards factory-controlled quality.
- Traditional:Cast-in-place substructure work retains dominance for foundation and subgrade applications where site-specific geotechnical conditions defy standardization.
- Modular:Prefabricated superstructure elements reduce on-site labor exposure and KOSHA occupational compliance burdens for silica dust and vibration monitoring.
- Precast:Segmental box girder and tunnel lining manufacturing clusters among three domestic equipment lessors, creating bottleneck risk for concurrent rail projects.
- In situ:Remains prevalent for retrofit and widening contracts where existing alignment constraints prohibit modular substitution.
Traditional methods dominate installed base. Precast is where expansion concentrates as digital twin mandates tighten dimensional tolerance requirements.
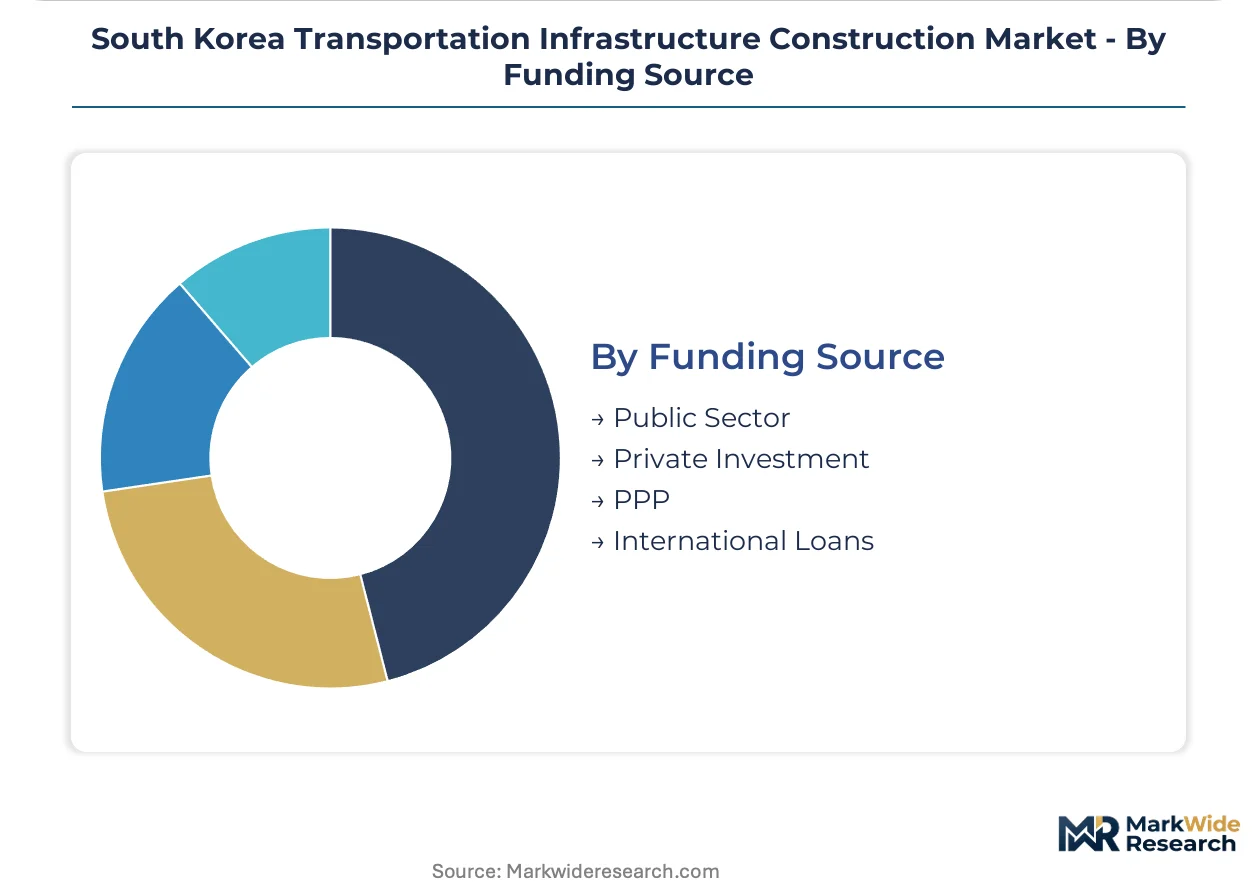
Funding Source:
Customer type segmentation separates sovereign-guaranteed public procurement from risk-bearing private structures where concession periods and revenue-sharing terms reshape project finance architecture.
- Public Sector:Ministry of Land, Infrastructure and Transport capital allocations pull forward contract awards through consolidated design-build-operate packaging on GTX corridors with 30-year concession periods.
- Private Investment:Institutional capital participation concentrates in revenue-tolled expressway segments where traffic volume forecasts support availability-payment structures.
- PPP:Hybrid risk allocation models are expanding across metropolitan rail extensions where construction completion guarantees intersect with ridership-based operating subsidies.
- International Loans:Multilateral development bank participation remains limited to strategic corridor upgrades with cross-border connectivity implications.
Public sector funding dominates installed base. PPP structures represent where expansion concentrates as procurement bundling deepens across the Seoul metropolitan program.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea's transportation infrastructure construction market exhibits pronounced regional specialization, with capital flows concentrating in metropolitan corridors where export-import logistics intersect with domestic mobility demands. The Seoul Capital Area dominates procurement volumes, while southeastern port zones absorb intermodal upgrade investments.
Seoul Capital Area
GTX corridor awards are compressing procurement cycles for tunnel-boring and trackwork specialists across the metropolitan rail program. MOTIE's consolidated design-build-operate packaging spans 30-year concession periods that reshape contractor qualification requirements. The Ministry of Land, Infrastructure and Transport's digital twin mandates for major corridor projects are tightening data interoperability requirements across design and construction phases in the capital region.
Busan-Ulsan
Container throughput expansion at Korea's largest maritime gateway is driving dedicated freight corridor investments linking the port to inland distribution centers. Port-rail intermodal upgrades are absorbing significant capital allocation where geohazard exposure drives substructure investment. The Korea Expressway Corporation's specifications for coastal corrosion zones favor fiber-reinforced polymer applications in viaduct maintenance contracts across the southeastern exposure belt.
Daegu-Gyeongbuk
Honam region rail extensions present greenfield corridor development potential for integrated design-build consortia seeking untapped metropolitan transit networks. MOTIE energy-efficiency benchmarks for transport facilities mandate LED tunnel lighting and regenerative braking systems on new alignments. Daegu metropolitan rail procurement is pulling forward contract awards as the city anchors logistics velocity for the inland manufacturing belt.
Daejeon-Sejong
Administrative capital relocation has concentrated government facility construction, with transportation linkages receiving parallel upgrade investments. The Korea Land & Geospatial Informatix Corporation's digital twin mandates are creating first-mover advantages for contractors with proprietary 4D modeling platforms in this central corridor. Sejong's planned urban rail network represents emerging demand for precast segment manufacturing capabilities.
Gwangju-Honam
The underserved urban transit network in Korea's southwestern quadrant presents procurement opportunities as national rail modernization extends beyond the Seoul-Busan axis. MFDS safety standards for construction material certification create qualified supplier premiums that reward domestic producers with certified production lines. Gwangju metropolitan rail extension planning is accelerating as the Honam region seeks parity with southeastern logistics infrastructure.
South Korea Transportation Infrastructure Construction Market Competitive Landscape
Listed leaders compete with private specialists across integrated engineering-procurement-construction capability, creating a tiered structure where scale-driven conglomerates anchor premium corridor contracts while regional specialists capture maintenance and retrofit niches. The market concentrates around three strategic archetypes: diversified construction conglomerates with captive equipment fleets, dedicated engineering subsidiaries of industrial groups, and specialized tunneling consortia. Competitive dynamics center on design-build-operate bundling and proprietary digital twin platform development as primary differentiation vectors.
Within the diversified conglomerate tier, Samsung C&T, Hyundai E&C, and GS E&C exemplify integrated capability spanning civil works, systems integration, and preliminary operations. These entities occupy positions where consolidated procurement packaging rewards single-source responsibility over segmented bidding. Samsung C&T anchors complex interchange contracts through engineering-procurement-construction integration, while Hyundai E&C sits within railway specialization via dedicated trackwork subsidiaries. GS E&C represents the scale-driven archetype competing across expressway, rail, and airport verticals where public-sector tender volumes concentrate procurement risk.
| Leading Market Players |
|---|
| GS E&C |
| POSCO E&C |
| Samsung C&T |
| Hoban Construction |
| Lotte E&C |
| Hyundai E&C |
| Daewoo E&C |
| Hanwha Engineering & Construction |
| Daelim Industrial |
| Others |
Value Network & Pricing Analysis
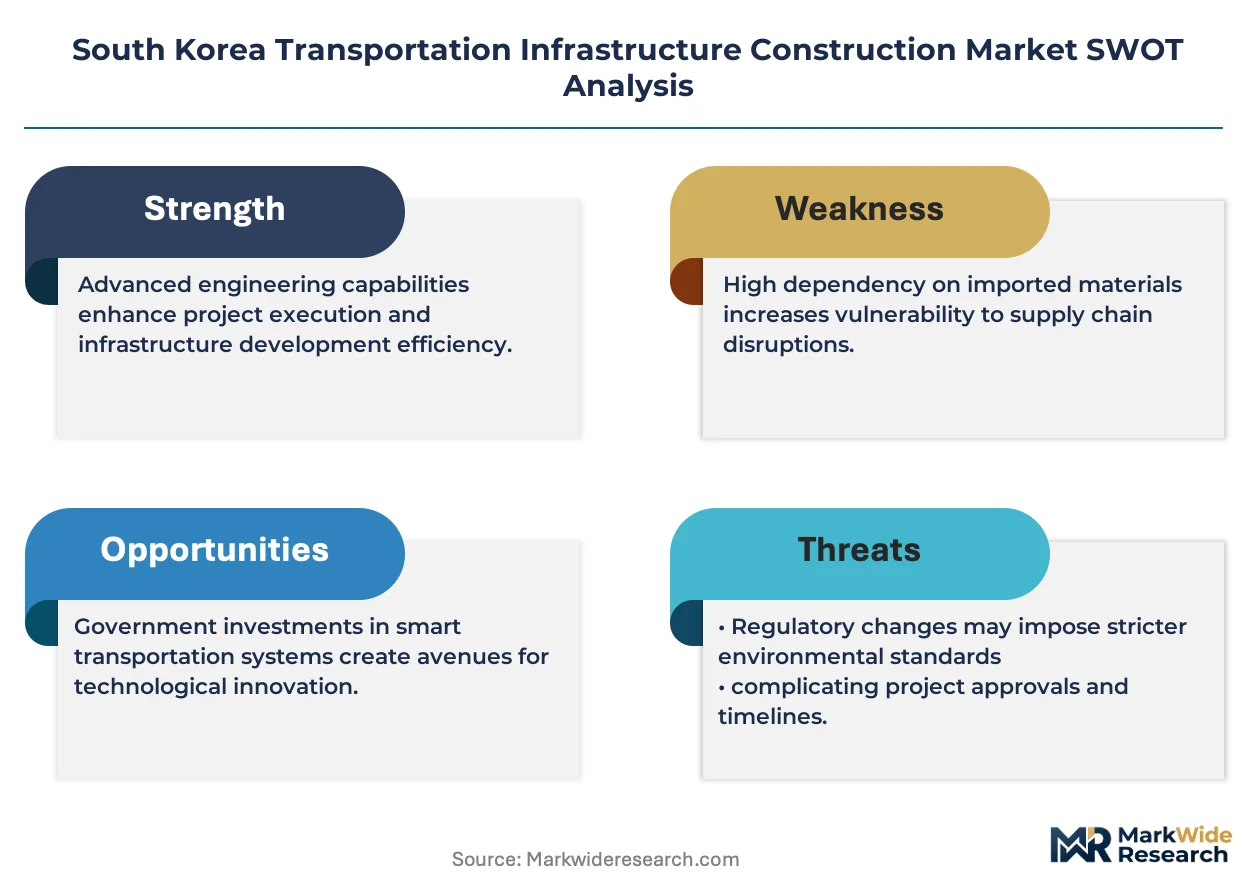
MFDS safety standards for construction material certification simultaneously gate supplier qualification and create price stratification across certified versus uncertified production tiers. Domestic contractors absorb qualified supplier premiums while global steel volatility compresses fixed-price contract margins.
Pricing Analysis
Public-sector procurement officers anchor pricing structures through consolidated design-build-operate packaging on GTX corridors. Three-tier pricing structure across premium certified-grade, standard domestic-grade, and economy import-grade materials segments the market by MFDS compliance tier. Pricing pressure stems from global scrap and billet indices compressing bridge project margins. Municipal buyers exhibit highest price sensitivity due to fixed capital allocations, while Korea Expressway Corporation concessions demonstrate lowest sensitivity through availability-payment structures.
Supply Chain Analysis
South Korea and China anchor structural steel and cement production for domestic transportation infrastructure. Rebar, precast concrete segments, and tunnel-boring machine components constitute critical input dependencies. Single-source vulnerability concentrates in TBM operation capabilities among three domestic equipment lessors. Distribution runs through Korea Expressway Corporation and Ministry of Land, Infrastructure and Transport procurement channels with consolidated tender packaging.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sustains defensive moats through regulatory entrenchment. MFDS certification requirements and MOTIE design-life mandates create switching costs that lock qualified suppliers into long-term contractor relationships.
For Market Incumbents: Shield market position through captive TBM fleet expansion and proprietary 4D modeling platform development. Tunnel-boring specialist scarcity threatens project delivery timelines. Backward integration into segment manufacturing reduces bottleneck exposure. Certification investment in MFDS-compliant production lines deepens supplier lock-in. For New Entrants and Emerging Players: Anchor in Gwangju-Honam rail extensions where incumbent concentration remains lowest. The Honam region's underserved metropolitan transit network offers greenfield corridor development potential. Fiber-reinforced polymer hybridization for coastal bridge maintenance contracts provides entry wedge through lifecycle cost differentiation rather than first-cost competition. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across digital twin-enabled design-build-operate concessions. Five-to-ten-year viability favors contractors with integrated civil works and systems integration capabilities. Acquisition targets should demonstrate proprietary BIM-to-asset-management data interoperability. The signal to watch is MOTIE procurement bundling depth across subsequent national plan revision cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Design-Build-Operate Bundling | Consolidated 30-year GTX concessions reward single-source responsibility over segmented bidding. |
| Digital Twin Platform Development | Korea Land & Geospatial Informatix mandates create first-mover advantages for 4D modeling capabilities. |
| TBM Fleet Captive Supply | Specialized contractor concentration in segment manufacturing reduces concurrent project bottleneck risk. |
| UHPC Material Certification | Korea Expressway Corporation specifications for ultra-high-performance concrete open premium maintenance contracts. |
| Coastal Corrosion Zone Specialization | Busan-Ulsan fiber-reinforced polymer applications override first-cost preferences through lifecycle accounting. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with tunnel-boring specialists, trackwork subcontractors, Korea Expressway Corporation procurement officers, and MOTIE planning directors. Secondary validation drew from MOTIE capital allocation disclosures, Korea Land & Geospatial Informatix digital twin specifications, MFDS certification registries, and contractor SEC filings. Bottom-up project pipeline aggregation and top-down national infrastructure budget triangulation anchored volume estimates.
Across the analysis window, forecasts model project type segmentation by railway, bridge, road, and airport verticals alongside material tier stratification and delivery methodology. CAGRs derive from contracted award schedules and procurement cycle compression patterns. Inputs include MOTIE five-year capital allocation trajectories, GTX corridor concession timelines, and Busan port throughput expansion commitments.
Decision-makers should treat outputs as directional under assumptions of sustained public-sector capital commitment and stable steel input costs; material deviation would warrant model refresh. Specific risks include KOSHA compliance timeline extensions, TBM operator wage inflation, and legacy tolling integration complexity. Recalibration cycles align with material shifts in national plan revision schedules and expressway corporation procurement bundling depth.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infrastructure Construction
Asia-Pacific Transportation Infrastructure Construction Market
Infrastructure Construction
Rebar Tier Market
Infrastructure Construction
Bahrain Construction Market
Infrastructure Construction
Sweden Transportation Infrastructure Construction Market
Infrastructure Construction
Heavy Movable Bridges Market
Infrastructure Construction
Brazil Infrastructure Sector Market
Infrastructure Construction
Global Port Infrastructure Market
Infrastructure Construction
Thailand Data Center Construction Market
Infrastructure Construction
North America Transportation Infrastructure Construction Market
Infrastructure Construction
Utility System Construction Market
Infrastructure Construction
Australia Transportation Infrastructure Construction Market
Infrastructure Construction
Global Rail Infrastructure Market
Infrastructure Construction
United States Transportation Infrastructure Construction Market
Infrastructure Construction
Global Manhole Covers Market
Infrastructure Construction
Pipeline Network Market
Infrastructure Construction
Transmission and Distribution Infrastructure Market