
 North America Commercial HVAC Market | 2026-2036
North America Commercial HVAC Market Size, Share, and Industry Trends Forecast 2026-2036
North America Commercial HVAC Market Insights
Equipment-as-a-service leasing and performance-contracting finance is reconfiguring capital deployment across the North America commercial HVAC landscape. Carrier Global Corp leverages captive financing arms to anchor multi-year service agreements in institutional accounts. Trane Technologies Plc sustains technology leadership through deep R&D investment in electrified heat pump architectures. Daikin Industries Ltd competes on manufacturing scale, operating some of the largest variable refrigerant flow production capacity serving North American distributors.
North America commercial HVAC encompasses climate control systems engineered to regulate temperature, humidity, and air quality across non-residential built environments, typically operating at capacities from five tons to thousands of tons with coefficient of performance ratings dictating energy consumption thresholds. These systems serve the fundamental commercial purpose of maintaining occupant productivity, protecting sensitive equipment, and ensuring code-compliant indoor air circulation across diverse building typologies. Chillers retain the largest installed base among product categories, though heat pump technology is capturing the fastest expansion as electrification mandates intensify across jurisdictions. Variable Refrigerant Flow systems concentrate margin pools in premium commercial retrofit applications where zoning flexibility commands pricing power against conventional hydronic alternatives.
The US Department of Energy enforces minimum efficiency standards under federal appliance regulations, while EPA oversees phasedown schedules for hydrofluorocarbon refrigerants under the AIM Act, and state-level stretch codes in California and New York impose requirements exceeding federal baselines. These layered standards are forcing equipment turnover cycles shorter than historical replacement patterns, compressing manufacturer development timelines and reshaping distributor inventory profiles. Stakeholders must monitor refrigerant transition readiness across their installed bases and assess which state-level efficiency trajectories will dictate next-generation product platform investments.
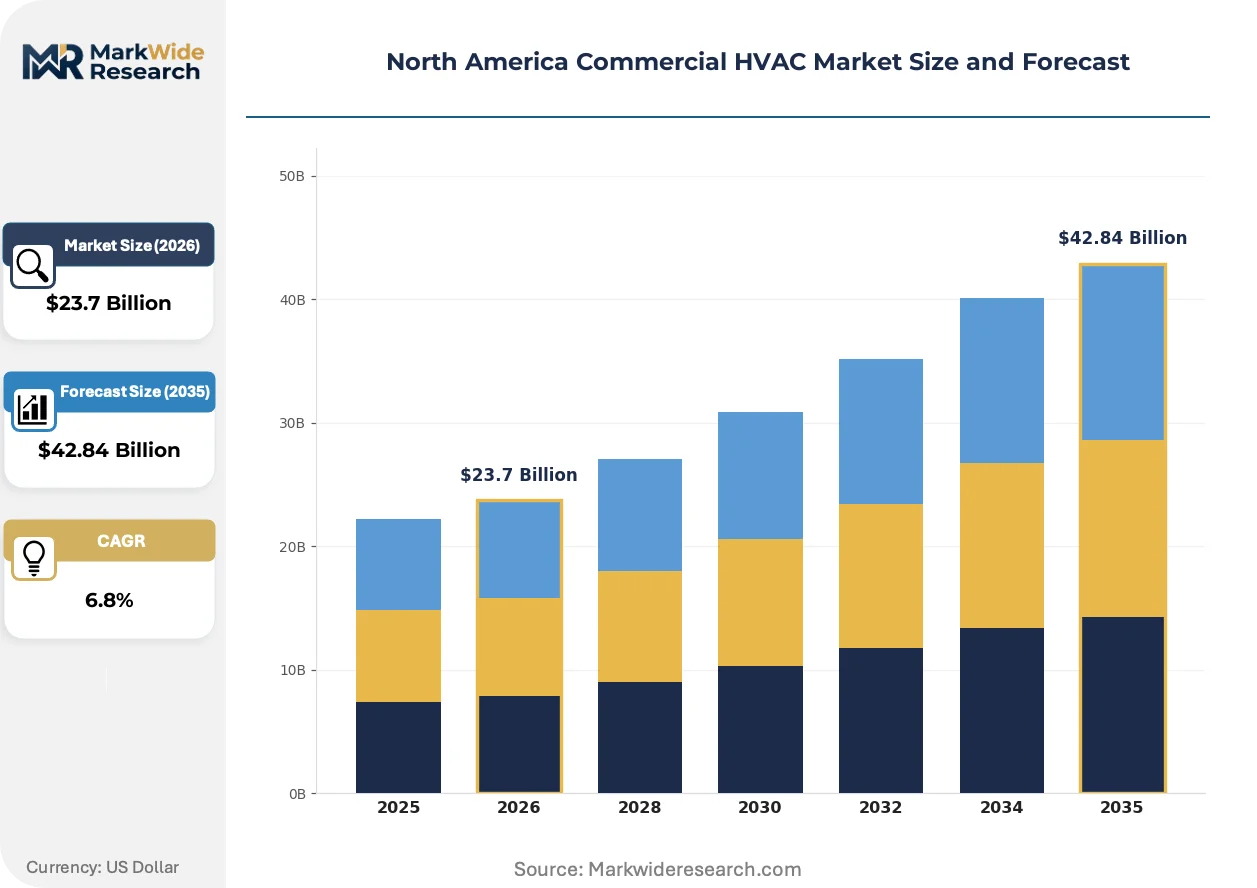
Market Dynamics
Electrification mandates and refrigerant phase-down schedules are compressing equipment replacement cycles across the North America commercial HVAC landscape, forcing building operators and contractors into accelerated capital planning.
Growth Catalysts
- AIM Act HFC Phase-Down:The EPA's refrigerant management rules under the American Innovation and Manufacturing Act are mandating lower-GWP alternatives, stimulating equipment turnover across the installed base.
- Data Center Expansion:Hyperscale computing facilities in Texas, Arizona, and Virginia are driving specialized precision cooling demand with 24/7 operational requirements.
- Heat Pump Technology Maturation:Cold-climate heat pump performance improvements are extending viable deployment zones into northern US states and Canadian provinces previously dependent on fossil heating.
Market Restraints
- Copper and Aluminum Input Volatility:Raw material price swings for coil and heat exchanger manufacturing are compressing OEM margins and complicating project bidding.
- Specialized Refrigerant Supply Concentration:Limited domestic production capacity for next-generation low-GWP refrigerants creates import dependency and allocation risk during peak construction seasons.
- Electrical Infrastructure Bottlenecks:Utility interconnection delays and transformer shortages in high-growth corridors are extending project timelines beyond equipment delivery schedules.
Strategic Opportunities
- Canadian Federal Greener Homes Initiative:Commercial building retrofit incentives are opening underpenetrated markets in Ontario and British Columbia for high-efficiency system upgrades.
- Predictive Maintenance Convergence:Integration of IoT sensor networks with machine learning diagnostics is creating recurring revenue streams beyond traditional service contracts.
- Performance Contracting Expansion:Energy Service Companies in California and New York are bundling HVAC upgrades with guaranteed savings structures, reducing upfront capital barriers for institutional buyers.
Industry Challenges
- Refrigerant Handling Certification Bottlenecks:EPA Section 608 technician credentialing requirements are constraining field workforce availability during peak installation seasons.
- Legacy BAS Integration Complexity:Building automation protocol fragmentation between proprietary and open standards is extending commissioning timelines and escalating project risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Commercial HVAC Market |
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $42.84 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chillers, Boilers, Air Handlers, Rooftop Units Technology: Variable Refrigerant Flow, Heat Pumps, Hydronic Systems, Ductless Systems End User: Commercial Buildings, Educational Institutions, Healthcare Facilities, Retail Spaces Installation: New Construction, Renovation, Retrofit, Replacement |
| Companies Covered | Carrier Global Corp, Trane Technologies Plc, Lennox International Inc, Johnson Controls International Plc, Daikin Industries Ltd, AAON Inc, Danfoss AS, Schneider Electric SE, Honeywell International Inc, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Commercial HVAC Market Trends and Innovations
Digitalization of asset management and thermal energy storage are converging to transform how commercial buildings procure, operate, and finance climate control infrastructure across North America.
Magnetic-bearing chiller compressors are eliminating oil-lubricated mechanical systems from large-tonnage applications. Hospital and university campuses with continuous cooling loads are specifying these units for part-load efficiency advantages. The technology is rendering obsolete traditional centrifugal compressor maintenance schedules and oil management protocols.
The EPA's Technology Transitions rule under the AIM Act is restricting high-GWP refrigerants in new equipment categories annually through 2028. Manufacturers are accelerating R-454B and R-513A platform rollouts ahead of compliance deadlines. Rooftop unit replacements in California and Washington state are experiencing the most acute supply chain and pricing adjustments.
Facility managers are unbundling long-term service agreements from initial equipment procurement, creating competitive tension between OEM-affiliated service arms and independent contractors. Third-party maintenance providers in Texas and Florida are capturing aftermarket revenue through specialized refrigerant management and controls expertise. This disintermediation is most pronounced in Class A office portfolios with centralized procurement functions.
North America Commercial HVAC Market Segmentation
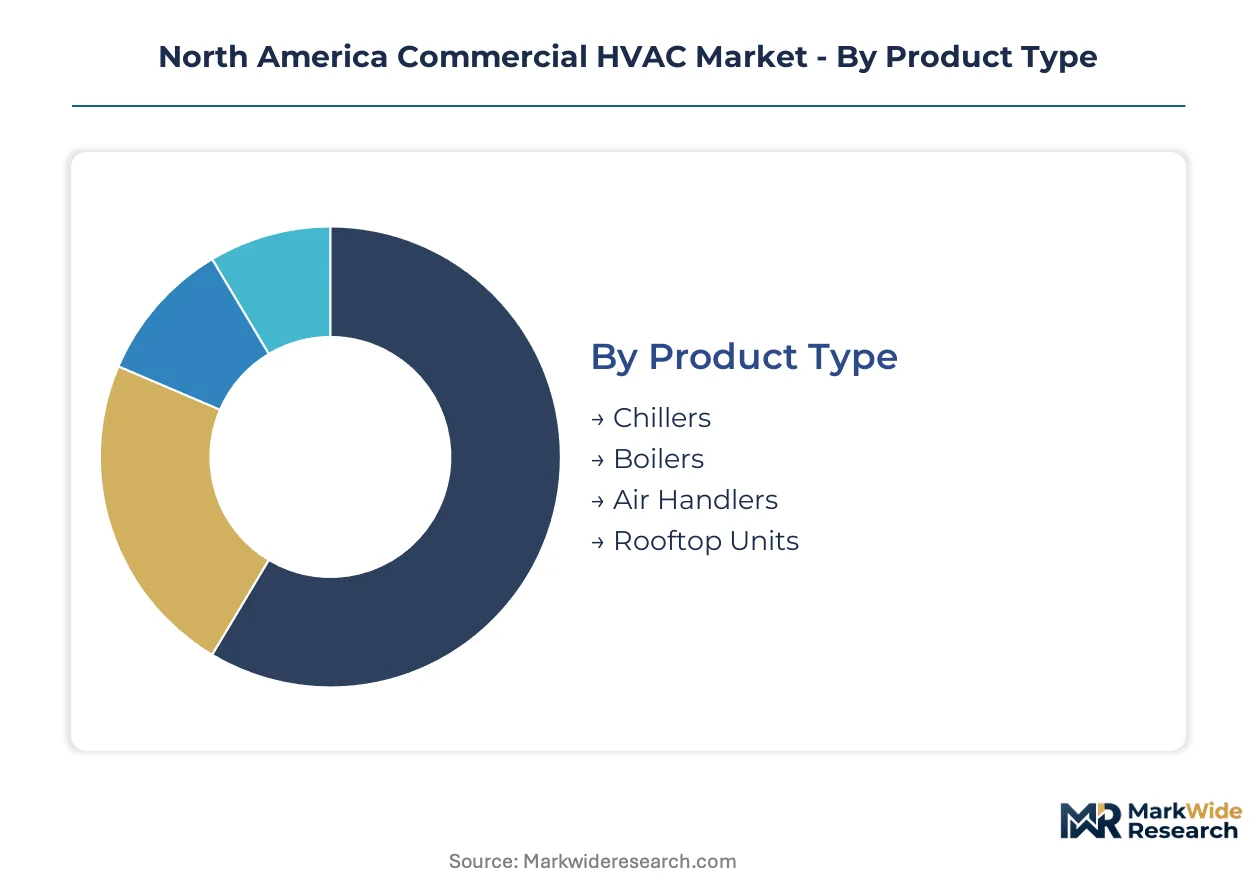
Commercial HVAC procurement patterns diverge sharply across building life cycles, thermal load profiles, and regulatory exposure zones. Equipment specifications and financing structures must align with these segment boundaries to capture margin pools effectively.
Product Type:
Mature centrifugal and absorption technologies anchor the installed base, while emerging magnetic-bearing and modular configurations are displacing legacy architectures in premium applications.
- Chillers:Centrifugal and absorption systems dominate large-tonnage cooling loads above 500 tons, with magnetic-bearing compressors eliminating oil management protocols in hospital and university campuses. Texas and California data center corridors are driving demand for high-efficiency centrifugal units with integrated thermal storage.
- Air Handlers:Custom-fabricated and standardized modular configurations serve distinct project scales, with premium units specifying MERV-16 filtration and UV-C disinfection for healthcare and bioscience facilities. Demand concentrates in Northeast corridor hospital renovations and Southeast life science expansions.
- Boilers:Condensing and non-condensing designs split along efficiency mandates, with Canadian federal Greener Homes incentives accelerating high-efficiency condensing deployments in Ontario commercial retrofits.
- Rooftop Units:Packaged gas-electric and heat pump configurations dominate single-story retail and light commercial, with California Title 24 and Washington state stretch codes forcing accelerated R-454B refrigerant platform transitions.
Chillers retain volume leadership; air handlers hold the steepest expansion curve.
Technology:
Cost tier stratification separates premium electrified architectures from conventional fossil-dependent systems, with mid-market hybrid configurations capturing renovation budgets.
- Heat Pumps:Cold-climate variable-speed compressors with enhanced vapor injection are extending viable deployment into Minnesota, Wisconsin, and Canadian provinces previously dependent on fossil heating. DOE efficiency mandates and IRA commercial credits are compressing payback periods in institutional applications.
- Variable Refrigerant Flow:Multi-zone refrigerant distribution systems command pricing power in Class A office retrofits and historic building renovations where ductwork constraints prohibit conventional hydronic alternatives. Margin pools concentrate in premium commercial corridors of Manhattan, Boston, and San Francisco.
- Hydronic Systems:Boiler-chiller paired architectures with four-pipe distribution maintain dominance in large-format healthcare and educational campuses with simultaneous heating and cooling requirements.
- Ductless Systems:Mini-split and multi-split configurations serve boutique retail, restaurant, and small-office applications with minimal spatial intrusion and rapid installation timelines.
Hydronic systems anchor the revenue base; heat pumps are climbing the fastest.
End User:
Application-driven specification standards create divergent procurement patterns, with mission-critical loads commanding premium engineering and 24/7 service commitments.
- Healthcare Facilities:Infection control protocols mandate HEPA filtration, pressure cascade management, and redundant mechanical systems with 99.999% uptime requirements. Joint Commission accreditation drives replacement cycles shorter than typical equipment lifespans.
- Commercial Buildings:Class A office portfolios with centralized procurement functions are unbundling service agreements from equipment procurement, creating competitive tension between OEM-affiliated and independent service providers.
- Educational Institutions:K-12 and university capital planning cycles align with bond issuance schedules, with performance contracting structures reducing upfront barriers for energy efficiency retrofits.
- Retail Spaces:Big-box and strip-mall configurations prioritize rapid deployment and standardized maintenance protocols, with national rollouts specifying uniform equipment platforms across distributed footprints.
Commercial buildings generate the largest equipment volume; healthcare facilities command the highest specification intensity.
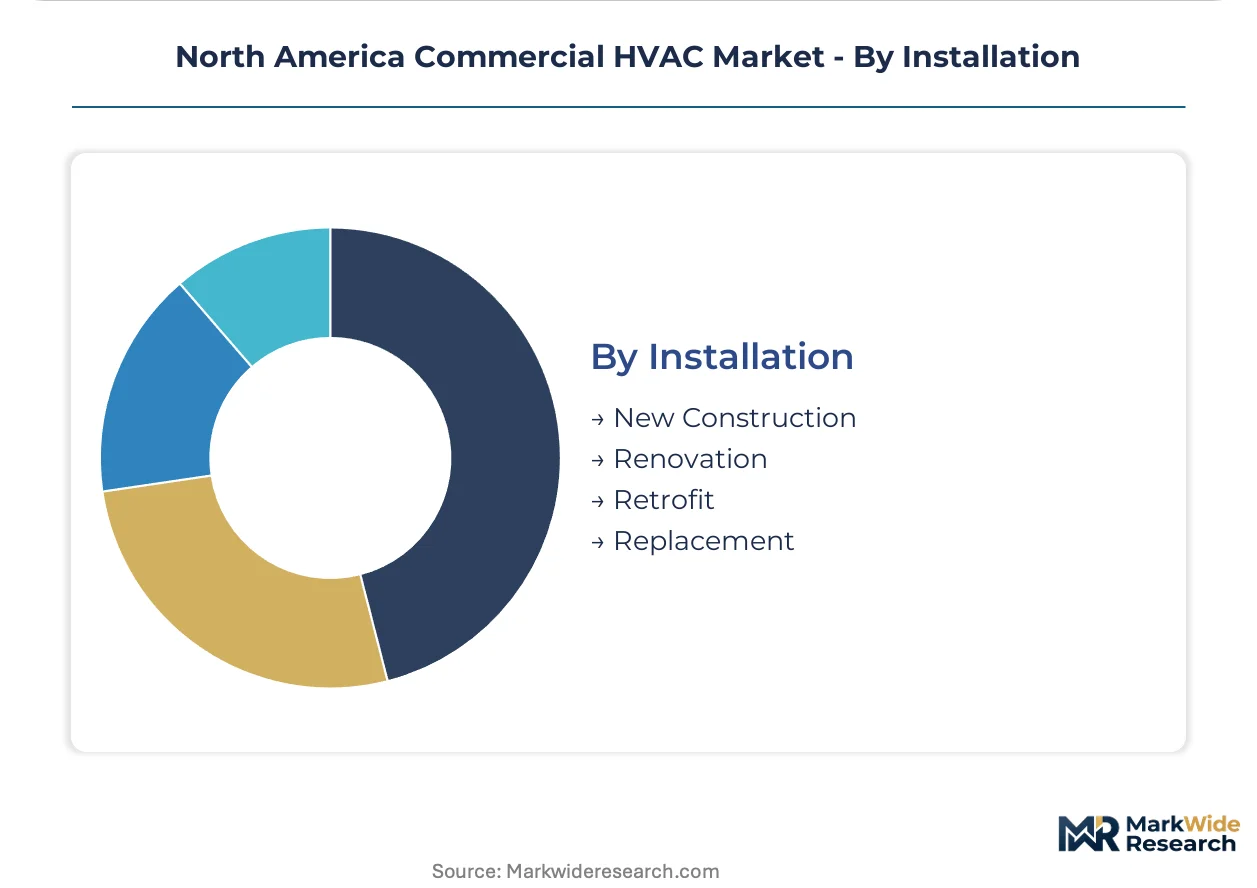
Installation:
Customer type segmentation separates owner-occupied long-term hold strategies from developer-driven speculative construction with minimal first-cost emphasis.
- Retrofit:Existing building system replacements must navigate spatial constraints, asbestos abatement, and phased occupancy requirements, with refrigerant recovery and equipment staging extending project timelines. AIM Act phase-down schedules are accelerating retrofit activity ahead of R-22 and R-410A service restrictions.
- New Construction:Ground-up projects allow integrated design optimization, with early mechanical contractor involvement enabling thermal storage and heat recovery configurations impractical in renovation contexts.
- Renovation:Partial system upgrades within occupied buildings balance disruption minimization against efficiency gains, often specifying modular or temporary cooling during construction phases.
- Replacement:Like-for-like emergency substitutions dominate distressed asset scenarios, with expedited procurement prioritizing availability over optimization.
New construction captures the largest absolute spend; retrofit is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment import flows into North America concentrate from Asian manufacturing hubs, while Canadian and Mexican facilities increasingly serve continental distribution networks. Cross-border supply chain integration shapes procurement patterns across the region's three national markets.
United States
Data center construction in Texas, Arizona, and Virginia drives precision cooling demand with 24/7 operational requirements. EPA refrigerant phase-down schedules under the AIM Act accelerate equipment turnover cycles ahead of compliance deadlines. California Title 24 stretch codes and Washington state efficiency mandates are forcing R-454B platform transitions in rooftop unit replacements.
Canada
Federal Greener Homes Initiative incentives accelerate high-efficiency commercial retrofits in Ontario and British Columbia. Natural Resources Canada efficiency standards exceed federal baselines in select provinces, compressing payback periods for institutional buyers. Cold-climate heat pump deployments extend into Prairie Provinces previously dependent on fossil heating infrastructure.
Mexico
Nearshoring manufacturing expansion in Nuevo León and Baja California generates commercial building stock requiring climate control systems. Mexican federal energy efficiency standards under CONUEE create regulatory alignment with US EPA frameworks. Mexico City Metro corridor experiences concentrated demand from Class A office and hospitality developments.
North America Commercial HVAC Market Competitive Landscape
On the supply side, the industry is consolidated around integrated HVAC conglomerates with captive distribution networks and multi-decade service infrastructures. Three strategic archetypes dominate: full-system OEMs with financing arms, component specialists with controls expertise, and regional fabricators with retrofit customization capabilities. Competitive intensity manifests through strategic partnerships for refrigerant platform transitions and geographic expansion into underpenetrated Canadian markets.
Among North American-integrated conglomerates, Carrier Global Corp and Trane Technologies Plc exemplify the full-system OEM archetype with captive financing capabilities. Daikin Industries Ltd occupies a position representing Asian-origin manufacturing scale serving continental distribution networks. These three anchors illustrate how supply-side concentration around integrated players shapes competitive dynamics across equipment procurement and long-term service contracting.
| Leading Market Players |
|---|
| Carrier Global Corp |
| Trane Technologies Plc |
| Lennox International Inc |
| Johnson Controls International Plc |
| Daikin Industries Ltd |
| AAON Inc |
| Danfoss AS |
| Schneider Electric SE |
| Honeywell International Inc |
| Others |
Pricing and Supply Chain Analysis
Copper and aluminum commodity volatility determines both pricing tier spreads and supply chain shape across the North America commercial HVAC landscape. Raw material input swings compress OEM margins while forcing distributors into inventory hedging strategies that widen price differentials between standard and premium equipment tiers.
Pricing Analysis
Industrial OEM buyers anchor a project-based pricing structure across equipment categories. Pricing stratifies across premium, standard, and economy tiers based on efficiency certification levels and after-sales service bundling. Cost compression in mid-tier rooftop units is intensifying because California Title 24 and Washington state stretch codes mandate R-454B refrigerant platform transitions. Institutional buyers with performance contracting structures exhibit lowest price sensitivity, while independent contractors in distressed replacement scenarios face acute budget constraints.
Supply Chain Analysis
Export-control restrictions on semiconductor components for variable-speed compressor controls limit equipment flow flexibility from Asian manufacturing hubs. Production concentrates in China, Mexico, and the United States for coil and heat exchanger fabrication. Supply chains draw from Chilean copper concentrates and domestic aluminum smelting for raw material feedstocks. Single-source vulnerability in next-generation low-GWP refrigerant production creates allocation risk during peak construction seasons. Distribution runs through captive OEM-affiliated networks and independent wholesale distributors serving contractor installation bases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
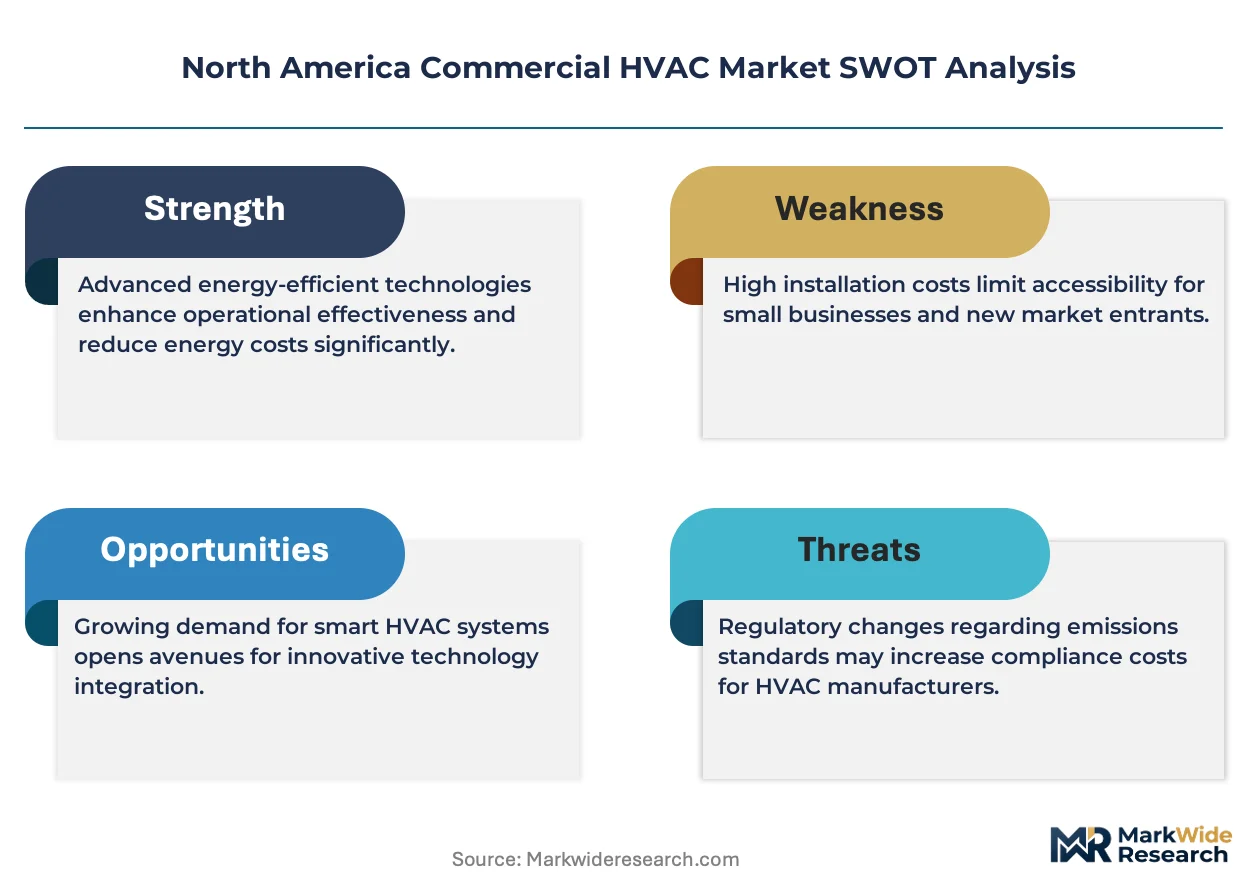
The North America commercial HVAC market represents an early-cycle expansion story. Electrification mandates and refrigerant phase-down schedules under the AIM Act accelerate equipment turnover ahead of historical replacement patterns.
For Market Incumbents: Pre-empt margin erosion by securing captive refrigerant supply agreements before allocation constraints tighten. Expand backward integration into compressor manufacturing to reduce dependency on semiconductor-controlled variable-speed components. Deepen service infrastructure in Texas and California data center corridors where 24/7 uptime requirements command premium pricing. For New Entrants and Emerging Players: Canadian Prairie Provinces present underpenetrated white space for cold-climate heat pump deployment where fossil heating infrastructure dominates. Target Ontario commercial retrofit incentives under the federal Greener Homes Initiative for fastest market entry. Pursue specialized refrigerant handling certification programs to differentiate against incumbent service arms constrained by EPA Section 608 technician shortages. For Investors and Strategic Acquirers: EPA Technology Transitions rule implementation reshapes the acquisition landscape by mandating annual high-GWP refrigerant restrictions through 2028. Long-term viability centers on platforms with R-454B and R-513A readiness across the projection horizon. Target mid-scale regional fabricators with retrofit customization capabilities in underpenetrated Canadian markets. Monitor state-level stretch code adoption velocity as the signal for next-generation product platform investment intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Platform Transition | EPA AIM Act compliance deadlines force R-454B and R-513A manufacturing line conversions ahead of restrictions. |
| Cold-Climate Heat Pump Scale-Up | DOE efficiency mandates and IRA commercial credits compress payback periods in Minnesota and Canadian provinces. |
| Predictive Maintenance Integration | IoT sensor networks with machine learning diagnostics create recurring revenue beyond traditional service contracts. |
| Performance Contracting Expansion | Energy Service Companies in California bundle HVAC upgrades with guaranteed savings structures reducing capital barriers. |
| Canadian Market Geographic Expansion | Federal Greener Homes Initiative incentives open underpenetrated Ontario and British Columbia retrofit markets. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EPA regulatory filings, DOE efficiency standard databases, and equipment manufacturer SEC disclosures. Interviews with HVAC contractor operations managers, facilities engineering directors at institutional accounts, distributor procurement leads, and OEM product strategy heads inform demand-side dynamics. Trade data from customs records and industry association shipment reports provide supply-side validation. Bottom-up equipment unit analysis triangulates against top-down construction spending and building stock estimates.
Forecast inputs include electrification mandate adoption curves, refrigerant phase-down compliance schedules, and data center construction permitting data across the analysis window. Segmentation models incorporate product type, technology architecture, end-use application, installation context, and regional regulatory cluster. CAGRs derive from equipment replacement cycle compression and efficiency standard trajectory modeling. Cold-climate heat pump performance improvements and utility interconnection capacity constraints factor into geographic deployment assumptions.
Practitioners should monitor EPA rulemaking timelines, state stretch code adoption velocity, and copper futures price movements for early signals of forecast deviation. Material shifts in federal appliance efficiency standard stringency or refrigerant supply allocation mechanisms would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Shell and Tube Heat Exchangers Market
HVAC Equipment
North America Heat Exchanger Market
HVAC Equipment
North America Industrial Air Chiller Market
HVAC Equipment
Global Home Ventilation System Market
HVAC Equipment
Variable Refrigerant Flow (VRF) System Market
HVAC Equipment
Heat Moisture Exchanger Market
HVAC Equipment
Heavy Duty Heat Pump Market
HVAC Equipment
Steam Boiler Systems Market
HVAC Equipment
Japan Commercial HVAC Market
HVAC Equipment
Europe Heating Radiator Market
HVAC Equipment
HVAC Air Handling Units Market
HVAC Equipment
United States HVAC Equipment Market
HVAC Equipment
Field-Erected Cooling Tower Market
HVAC Equipment
Utility and Industrial Boilers Market
HVAC Equipment
Global Modular Chillers Market
HVAC Equipment
Hydro Chillers Market